
 Medical Clothing Market | 2026-2036
Medical Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Clothing Market Intelligence
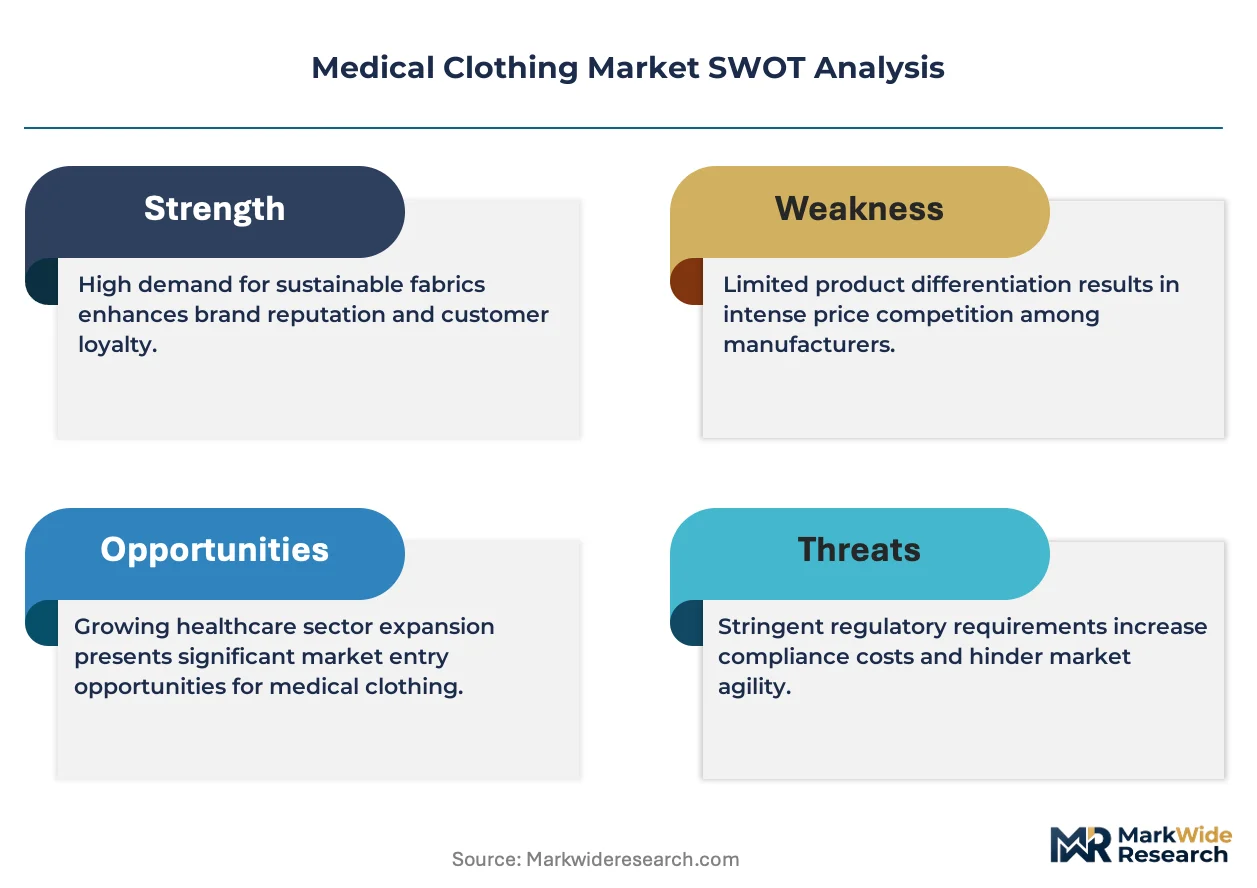
A divergence in material science capabilities and manufacturing scale is unwinding the market's competitive structure. Large-scale providers like Medline Industries leverage extensive distribution networks to serve hospital systems. In contrast, 3M Company differentiates through proprietary non-woven fabric technologies that enhance barrier protection. Ansell Ltd. specializes in high-performance surgical gloves and protective suits, occupying a premium niche.
Medical clothing encompasses disposable and reusable garments designed to create a barrier against pathogens, fluids, and particulate matter. These products, often made from polypropylene SMS fabric or polyester-cotton blends, must meet specific fluid resistance and breathability standards. Surgical gowns and isolation gowns represent high-margin categories due to stringent regulatory testing. The scrubs segment, while larger in volume, faces greater price competition, with demand growing from hospitals and diagnostic centers.
Regulatory frameworks are critical in defining product performance and market access. The US FDA classifies surgical apparel into four levels of barrier protection, while the EU's Medical Device Regulation (MDR) governs CE marking. Conformance with ISO 13485 quality management standards is also essential for manufacturers. Navigating these varied international standards is a primary challenge for market participants seeking broad geographic reach.
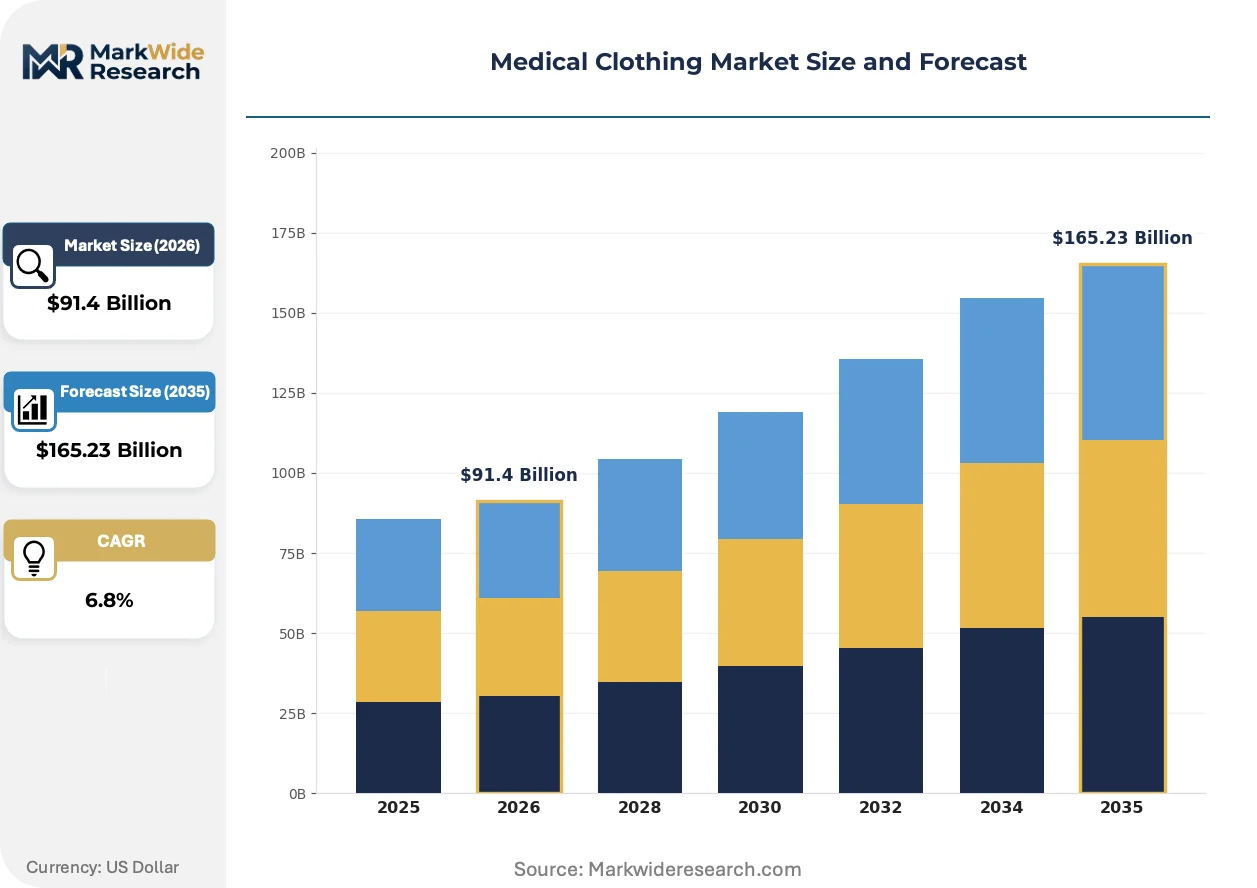
Market Dynamics
Intensifying regulatory scrutiny over infection control is the central force shaping the medical clothing market. Mandates from bodies like the US FDA and the EU's MDR are compelling innovations in material science and barrier performance standards.
Growth Catalysts
- Strict Regulations:The EU's Medical Device Regulation (MDR) elevates performance requirements, forcing an upgrade cycle toward higher-grade, certified materials.
- Ambulatory Surgical Centers:The expansion of outpatient surgery centers creates new demand for specialized, single-use surgical gowns and procedural drapes.
- Healthcare Modernization:Developing economies in Southeast Asia are investing in healthcare infrastructure, adopting stricter infection control protocols that require standards-compliant medical apparel.
Market Restraints
- Raw Material Volatility:The market is sensitive to price fluctuations in petroleum-derived polypropylene, the primary input for non-woven SMS fabrics.
- Regulatory Compliance Burden:Navigating disparate standards, such as the FDA's four-level barrier system and the EU's CE marking process, increases costs and time-to-market.
- Reusable vs. Disposable Trade-offs:The operational complexities and high upfront costs associated with laundering and sterilizing reusable garments limit their adoption in some facilities.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Latin America and the Middle East present growth opportunities as healthcare spending and quality standards rise.
- Smart Textiles:Integrating sensors into garments for monitoring patient vitals or detecting fluid breaches offers a path to high-margin, differentiated products.
- Specialized Apparel:There is an unmet need for garments designed for specific high-risk procedures, such as chemotherapy handling or orthopedic surgery.
Industry Challenges
- Supply Chain Complexity:Managing the sterilization, tracking, and logistics for reusable garment programs presents significant operational hurdles for healthcare providers.
- Global Quality Assurance:Ensuring consistent adherence to quality management standards like ISO 13485 across a fragmented global manufacturing footprint is a major challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Clothing Market |
| Market Size in 2026 | $91.4 Billion |
| Market Size in 2035 | $165.23 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gowns, Scrubs, Lab Coats, Patient Apparel, Isolation Gowns Material: Cotton, Polyester, Polypropylene, Polyester-Cotton Blend, SMS Fabric Application: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Dental Clinics End User: Surgeons, Nurses, Technicians, Medical Assistants, Caregivers |
| Companies Covered | Medline Industries, Cardinal Health, 3M Company, Ansell Ltd, Barco Uniforms, Halyard Health, Semperit AG Holding, Superior Uniform Group, Owens & Minor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Clothing Market Strategic Shifts & Innovations
A fundamental re-evaluation of material science is underway, driven by the twin demands for higher barrier protection and greater environmental sustainability. This shift impacts everything from raw material selection to end-of-life product management and manufacturing processes.
Smart textiles integrate conductive fibers to create garments that can monitor patient vitals or detect pathogen presence. Specialized hospital units, such as ICUs and infectious disease wards, are early adopters of this technology. The integration of these functions into the fabric itself is miniaturizing diagnostic equipment, moving it from the bedside directly onto the patient.
European Union directives targeting single-use plastics are creating long-term pressure on the disposable garments segment. This regulatory climate compels manufacturers to explore bio-based polymers and advanced recycling processes for materials like polypropylene. The disposable surgical gown and drape categories are most exposed, requiring new designs to ensure future compliance and market access.
Consolidated purchasing by Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs) alters the procurement landscape. This model centralizes buying decisions, often favoring large-scale suppliers who can offer bundled contracts and standardized pricing across an entire health system. The influence of GPOs is particularly significant in the United States, impacting market access for smaller, specialized apparel producers.
Medical Clothing Market Segmentation
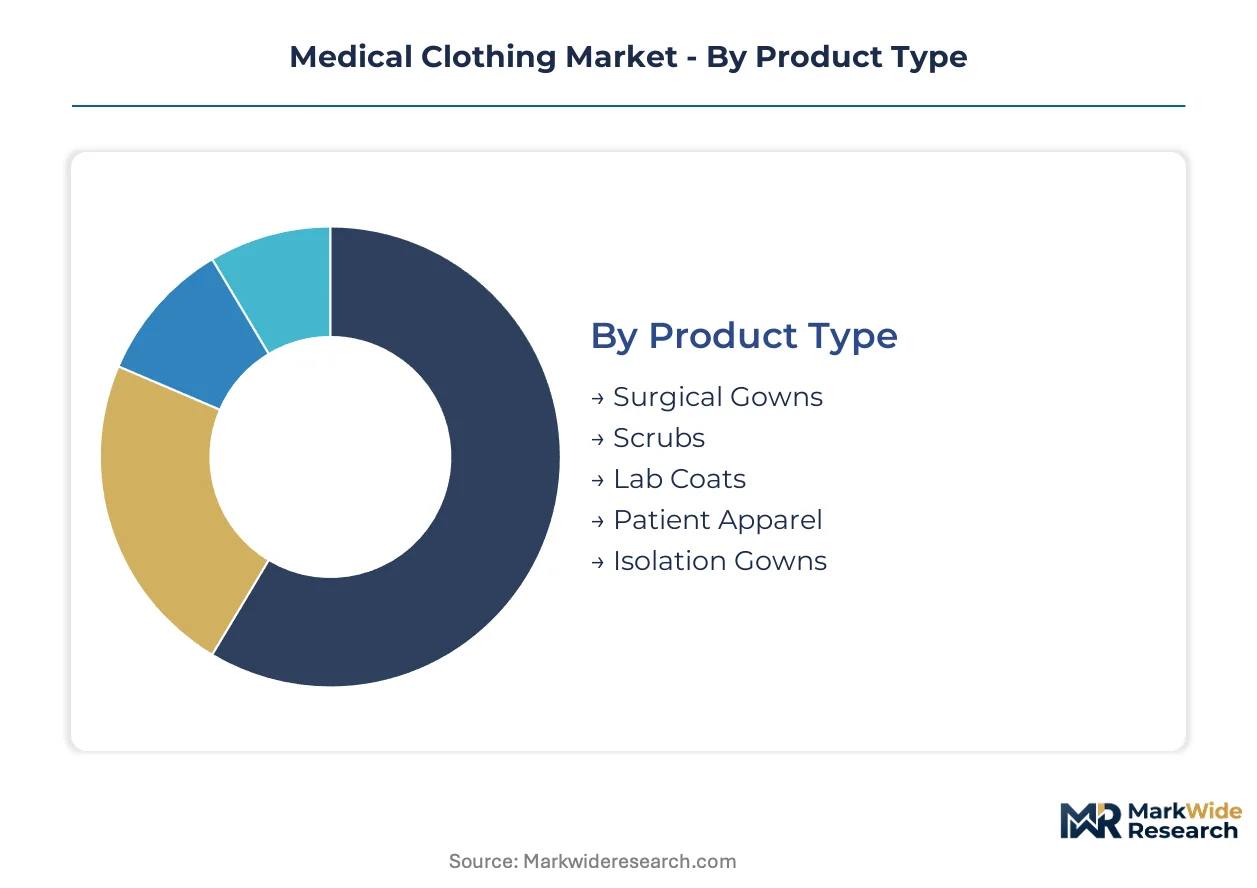
The medical clothing market segmentation reflects the diverse functional demands, regulatory imperatives, and material innovations shaping the industry. Understanding these segments is crucial for manufacturers to align product development with specific end-user needs and compliance standards.
Product Type:
The medical clothing market experiences varying substitution pressures across its product types, driven by performance requirements and cost considerations.
- Surgical Gowns:Barrier protection against fluids and pathogens is critical for these sterile garments. Demand concentrates in operating rooms across Germany and the United States, driven by strict FDA barrier standards.
- Isolation Gowns:These garments create a protective barrier in contaminated environments, preventing cross-contamination. Their use is expanding in ambulatory surgical centers, responding to increased outpatient procedures and infection control protocols.
- Scrubs:These everyday garments provide comfort and basic protection for healthcare professionals.
- Lab Coats:Lab coats offer general protection against spills and contamination in clinical and laboratory settings.
- Patient Apparel:Designed for patient comfort and modesty, these garments are used across various healthcare settings.
Scrubs anchor the volume base while Isolation Gowns gain share at the steepest rate.
Material:
Material selection significantly differentiates medical clothing products, influencing both performance attributes and manufacturing costs.
- Polypropylene:This thermoplastic polymer forms the base for many disposable non-woven medical garments. Its demand is strongly influenced by petroleum price fluctuations, impacting overall production costs.
- SMS Fabric:Comprising Spunbond-Meltblown-Spunbond layers, this non-woven material offers superior barrier protection and breathability. It is critical for high-performance surgical gowns, meeting stringent EU MDR requirements.
- Cotton:Natural fiber primarily used in reusable garments due to its comfort and absorbency.
- Polyester:Synthetic fiber offering durability and moisture resistance, often blended for medical textiles.
- Polyester-Cotton Blend:This blend combines the comfort of cotton with the durability of polyester for reusable medical apparel.
Demand for Polyester-Cotton Blend is driven by the need for reusable options, while SMS Fabric expands due to increasing barrier protection mandates.
Application:
The application landscape dictates specific regulatory compliance levels and volume requirements for medical clothing.
- Hospitals:These facilities represent the largest consumption segment for medical clothing, requiring a full spectrum of products from scrubs to high-barrier surgical gowns. Procurement often occurs through consolidated purchasing by Group Purchasing Organizations.
- Ambulatory Surgical Centers:Focused on outpatient procedures, these centers drive demand for single-use surgical gowns and procedural drapes. Their expansion creates new requirements for specialized, cost-effective apparel solutions.
- Diagnostic Centers:These centers utilize medical clothing for basic protection and hygiene during patient examinations and testing.
- Dental Clinics:Dental clinics require specific protective apparel, including gowns and masks, for both practitioners and patients.
The largest segment, Hospitals, faces pressure from Ambulatory Surgical Centers due to the increasing shift towards outpatient care models.
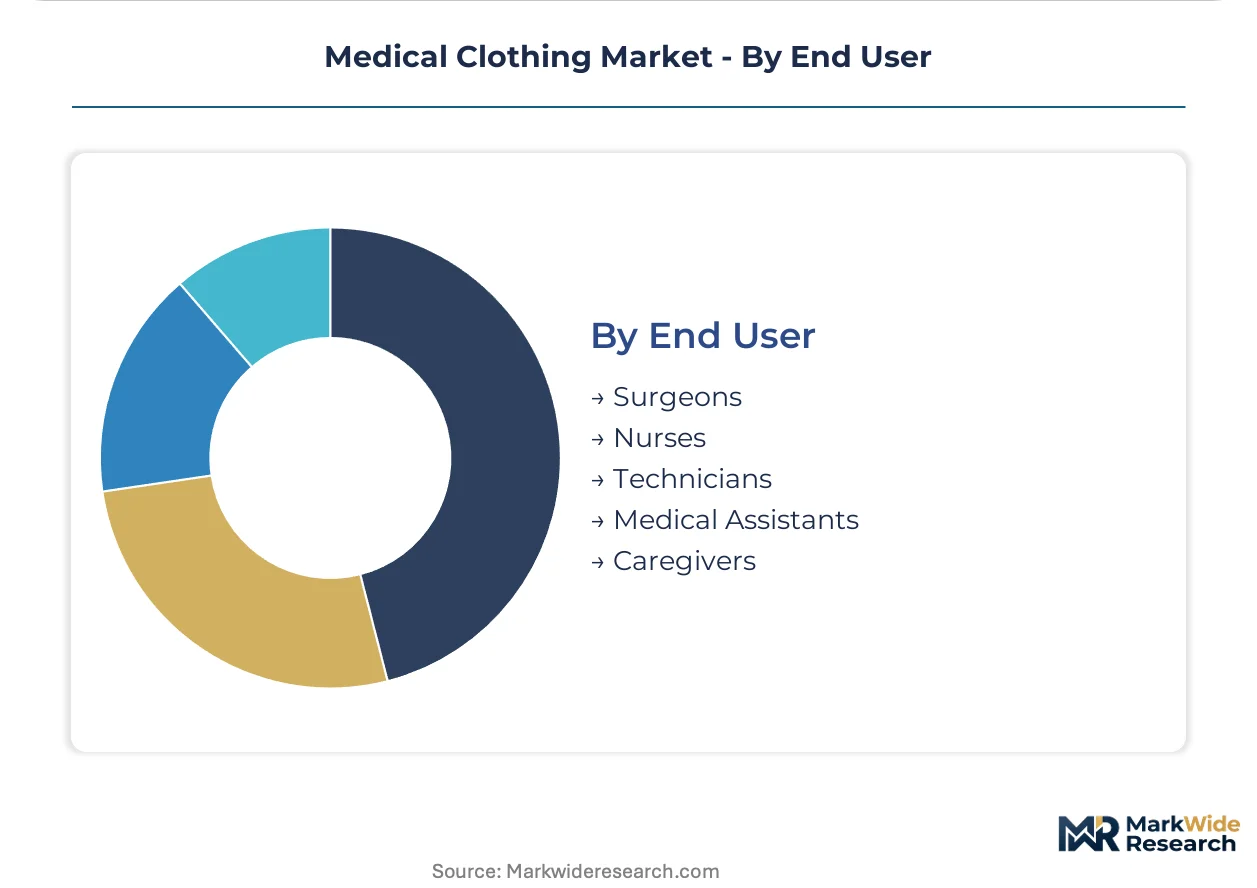
End User:
End-user roles within healthcare dictate specialized garment features, ranging from barrier protection to ergonomic design.
- Surgeons:This group requires the highest level of barrier protection, demanding sterile surgical gowns and gloves for invasive procedures. Garments must meet stringent performance standards, like FDA Level 4.
- Nurses:Nurses utilize a broad range of medical clothing, from scrubs to isolation gowns, emphasizing comfort, durability, and ease of movement during patient care. Their demand is substantial across all healthcare settings.
- Technicians:Technicians wear specialized apparel for protection in laboratory, diagnostic imaging, or sterile processing environments.
- Medical Assistants:Medical assistants require comfortable and functional scrubs or lab coats for daily patient interaction and administrative tasks.
- Caregivers:Caregivers use protective apparel to maintain hygiene and prevent cross-contamination in various care settings.
While Surgeons represent the most stringent demands, Nurses drive consistent volume for general medical apparel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced medical clothing products varies significantly across regions. Developed markets like the United States command premium pricing due to stringent regulatory demands, while cost-sensitive developing economies in Latin America face different market dynamics. This asymmetry influences investment and product development strategies.
United States
Demand for high-barrier surgical gowns is strong, driven by a high volume of procedures and strict infection control protocols. The US FDA's four-level barrier system mandates specific performance standards for medical apparel. Major medical device clusters in California and Massachusetts focus on innovation in protective fabrics.
Germany
Healthcare modernization initiatives and a focus on advanced medical technologies fuel demand for high-quality, certified medical clothing. The EU's Medical Device Regulation (MDR) elevates performance requirements, necessitating an upgrade cycle. R&D hubs in cities like Munich and Berlin drive innovation in smart textiles.
China
Significant investment in healthcare infrastructure creates substantial demand for both disposable and reusable medical garments. The country's national health authorities are progressively adopting stricter infection control protocols, influencing procurement. Industrial zones in Guangdong and Jiangsu provinces are major manufacturing centers for medical textiles.
India
Expanding healthcare access and increasing awareness of hygiene standards are driving consistent volume demand for essential medical clothing. The national pharmaceutical regulator's guidelines for medical devices are tightening, pushing for better quality control. Major textile and medical device clusters in Maharashtra and Gujarat are scaling up local manufacturing.
Brazil
Modernization of public and private healthcare facilities generates new demand for specialized medical apparel, particularly in urban centers. The national health surveillance agency, ANVISA, sets performance and safety standards for medical devices. São Paulo and Rio de Janeiro serve as key distribution and manufacturing hubs for medical textile producers.
Medical Clothing Market Key Industry Players
Concentration sits with large-scale generalist providers leveraging extensive distribution networks for a broad product portfolio across diverse healthcare systems. The market structure also includes technology-driven innovators focusing on advanced material science for enhanced barrier protection and specialized manufacturers serving premium niche segments. Competitive moves often involve strategic partnerships to expand geographic reach, capacity expansion to meet rising regulatory-driven demand, and portfolio diversification.
At the scale-driven end, Medline Industries exemplifies providers leveraging vast distribution networks to serve hospital systems with a wide array of medical apparel. 3M Company occupies a position among technology differentiators, focusing on proprietary non-woven fabric technologies that enhance barrier protection. Ansell Ltd., a specialist in high-performance surgical gloves and protective suits, represents the premium niche segment. These entities collectively shape the market's competitive dynamics through their distinct operational models and product differentiation strategies.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| 3M Company |
| Ansell Ltd |
| Barco Uniforms |
| Halyard Health |
| Semperit AG Holding |
| Superior Uniform Group |
| Owens & Minor |
| Others |
Cost & Logistics Intelligence
The shift towards bio-based polymers, replacing traditional petroleum-derived polypropylene, simultaneously reshapes manufacturing geography and alters pricing economics for medical textiles. This substitution introduces new cost structures and supply dependencies.
Pricing Analysis
Configured-to-order pricing for specialized surgical apparel commands a premium over standardized, high-volume scrubs. The dominant pricing model for large hospital systems and Group Purchasing Organizations involves contract-based long-term offtake agreements. Price differentiation stems from stringent certification levels, such as FDA barrier standards, and the volume scale of procurement. Pricing pressure stems from consolidated purchasing by GPOs, particularly impacting high-volume segments like scrubs, while surgical gowns exhibit lower price sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies face challenges due to raw material volatility, prompting some facilities to consider strategic stockpiles for critical medical clothing. Global supply concentrates manufacturing in China, India, and Southeast Asia, primarily drawing from petroleum-derived polypropylene and specialized non-woven fabrics. Commodity price volatility for polypropylene represents a structural supply chain risk. Distribution runs through large-scale logistics providers and consolidated purchasing by Group Purchasing Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical clothing market presents a significant fragmentation opportunity, driven by the expansion of ambulatory surgical centers. This demand-side shift creates distinct niches for specialized, single-use procedural drapes and gowns.
For Market Incumbents: Secure long-term contracts with Group Purchasing Organizations to maintain volume stability against price competition. Incumbents should invest in proprietary material technologies to meet evolving barrier protection standards. Expanding global certification pathways, particularly for EU MDR compliance, defends market access. This strategy mitigates risks from intensifying regulatory scrutiny over single-use plastics directives.
For New Entrants and Emerging Players: Certification fast-tracks, such as those for niche applications, enable new entrants to penetrate the medical clothing market. Target specialized apparel for high-risk procedures like chemotherapy handling, addressing unmet needs. The most penetrable segment lies within rapidly expanding ambulatory surgical centers. A go-to-market angle involves value-added partnerships with smaller, independent healthcare networks.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-driven innovators specializing in advanced barrier protection and sustainable materials. The market exhibits a long-term growth trajectory over the next decade, driven by escalating infection control mandates. Acquisition targets include vertically integrated specialists with proprietary material science capabilities. The signal to watch is the adoption rate of smart textiles in critical care units, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Polymer R&D | Addresses EU single-use plastics directives and secures future market access. |
| Expand Global Certification Capabilities | Ensures compliance with diverse regulatory frameworks like FDA and EU MDR. |
| Form Partnerships with Ambulatory Surgical Centers | Captures demand for specialized, single-use apparel in a high-growth segment. |
| Develop Smart Textile Prototypes | Creates high-margin, differentiated products for patient monitoring and pathogen detection. |
| Consolidate Regional Manufacturing Hubs | Optimizes supply chain efficiency and reduces logistics costs for key markets. |
Research Approach
The analysis maps medical clothing sub-sectors, each validated through primary interviews with hospital purchasing committees, biomedical engineers, and material scientists. Secondary research synthesized data from FDA filings, EU MDR guidelines, and ISO standards. This approach combined bottom-up market sizing with top-down validation against industry reports. Triangulation across these diverse data points ensured robust market insights.
Output consistency was validated against external benchmarks and peer-reviewed studies across the analysis window. The analytical framework modeled segmentation by product type, material, application, end user, and barrier protection level. Compound Annual Growth Rates were derived from historical data projections and regression analysis. Forecast inputs included healthcare expenditure growth and infection control mandate intensity.
Decision-makers should treat outputs as directional under current healthcare spending and regulatory stability assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, acknowledging potential impacts from raw material price volatility or major regulatory shifts. Revision becomes warranted when infection control mandates or healthcare infrastructure investments cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Swab Cups Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Smear Mask Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Global Surgical Kits Market