
 Global Lancets Market | 2026-2036
Global Lancets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lancets Market Foresight
Hospital pharmacy procurement is narrowing as online retailers and direct-to-consumer channels capture chronic disease management spending. Becton, Dickinson and Company leverages its institutional contracts to sustain shelf presence in acute care settings, while Abbott Laboratories anchors the home monitoring ecosystem through integrated glucose-lancet systems. Roche Diagnostics differentiates via automated platform compatibility, and Ypsomed competes on pen-needle crossover technology for insulin-dependent users.
A lancet is a small, sharp instrument designed to puncture skin capillaries for blood sampling, typically manufactured from surgical-grade stainless steel or high-carbon steel with precision-ground triangular or beveled tips calibrated to penetration depths between 0.8 mm and 3.0 mm. Its primary commercial purpose is enabling minimally invasive blood extraction for point-of-care diagnostics, laboratory assays, and patient self-monitoring of metabolic and hematologic parameters. Safety lancets command the dominant revenue share due to needlestick prevention mandates in clinical environments, while retractable mechanisms represent the fastest-expanding engineering category as manufacturers engineer integrated trigger systems that eliminate exposed sharps. Home care providers constitute the most concentrated end-user growth vector, though diagnostic laboratories retain the deepest volume contracts and margin pools through centralized purchasing agreements.
The FDA enforces 510(k) premarket notification requirements for lancet devices, while the EU MDR imposes strengthened clinical evidence standards and post-market surveillance obligations on manufacturers seeking CE marking. ISO 11607-1 and ISO 13485 govern sterilization validation and quality management systems, respectively, creating compliance cost barriers that favor scaled producers over regional entrants. Stakeholders must monitor evolving sharps disposal regulations and reimbursement coding shifts for home-use devices as payors recalibrate chronic disease management incentives.
Market Dynamics
The FDA's sharpened single-use safety mandates are compressing product redesign cycles and forcing manufacturers to prioritize retractable trigger mechanisms over conventional fixed-blade formats.
Growth Catalysts
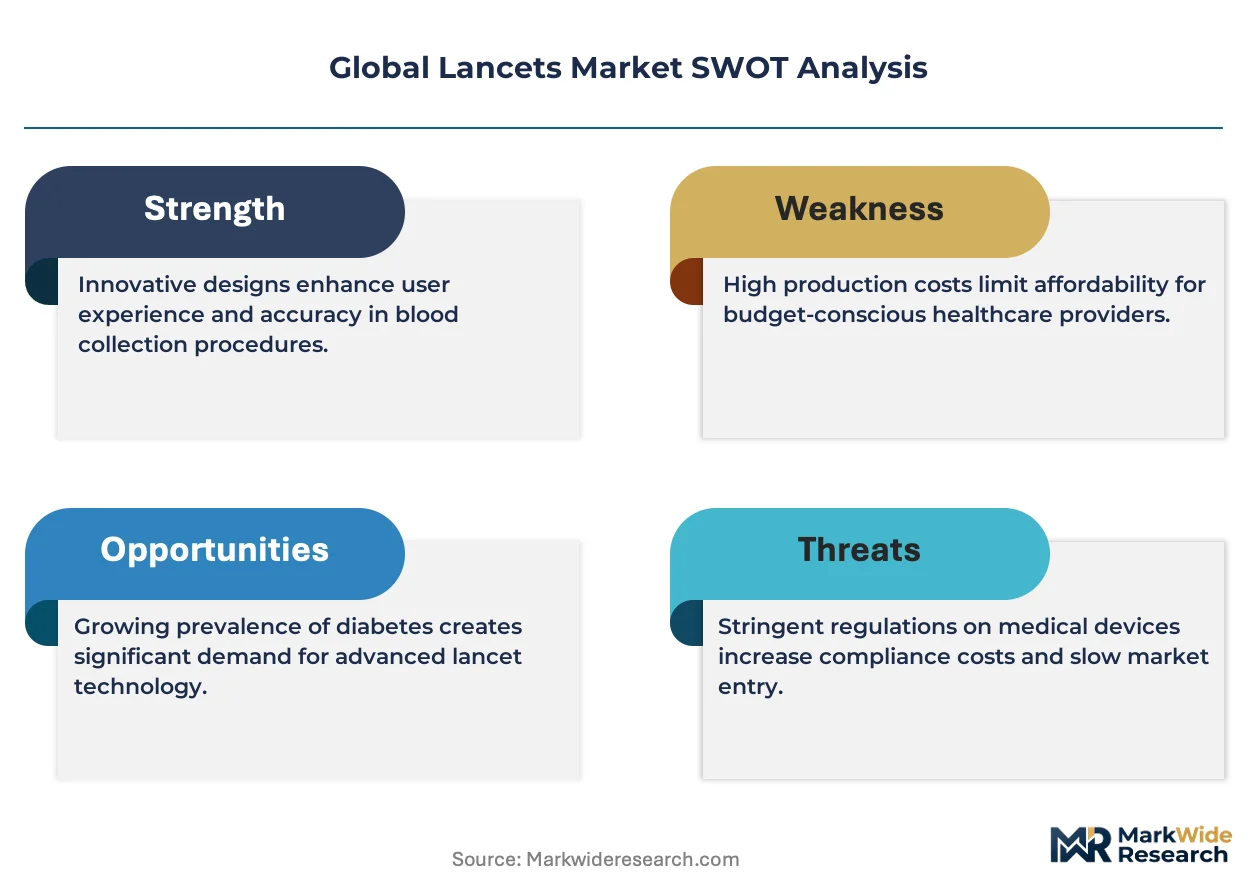
- Home-based diabetes monitoring:Patients managing chronic conditions outside clinical settings create sustained pull for integrated glucose-lancet systems.
- EU MDR clinical evidence standards:Strengthened post-market surveillance obligations elevate barrier-to-entry, protecting compliant incumbents from low-cost regional competition.
- Needlestick prevention mandates:Occupational safety regulations in acute care environments lock in demand for safety-engineered lancet designs.
Market Restraints
- Surgical-grade stainless steel input volatility:Raw material price swings compress margin predictability for precision-ground tip manufacturers.
- 510(k) premarket notification timelines:FDA clearance durations extend commercialization lead times for novel mechanism designs.
- Centralized laboratory purchasing concentration:Diagnostic lab volume contracts limit pricing autonomy for suppliers outside preferred vendor networks.
Strategic Opportunities
- India's expanding chronic disease infrastructure:Underpenetrated home monitoring penetration in tier-2 cities offers whitespace for localized distribution partnerships.
- Pen-needle crossover convergence:Insulin delivery device compatibility creates bundled attach opportunities for lancet manufacturers with diabetes platform expertise.
- Direct-to-consumer channel emergence:Online retail bypass of hospital pharmacy procurement unlocks margin capture for brands with digital fulfillment capabilities.
Industry Challenges
- ISO 13485 quality management system audits:Certification maintenance demands dedicated compliance personnel that strain mid-tier manufacturer overhead structures.
- Sharps disposal regulation fragmentation:Inconsistent state-level biohazard handling rules complicate national distribution logistics for home-use device suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lancets Market |
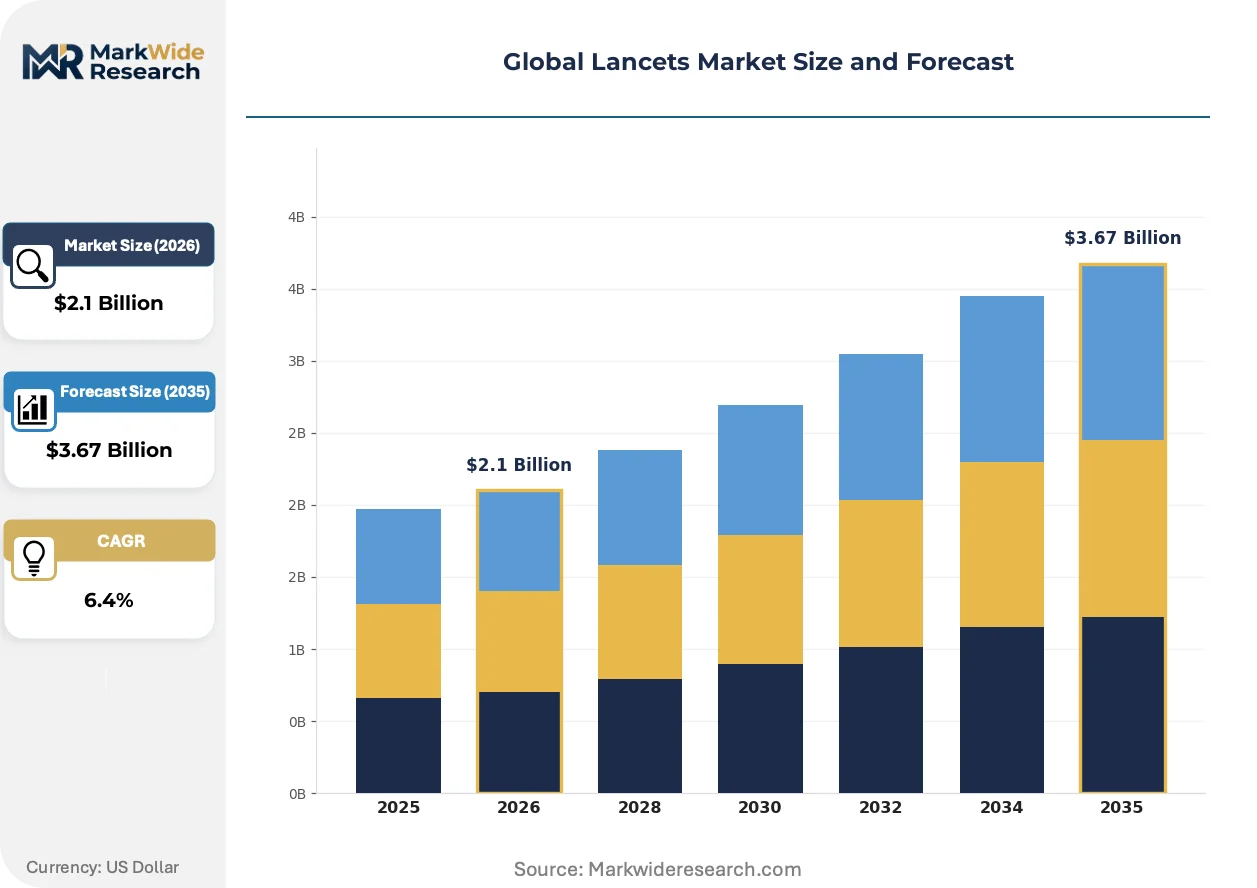
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Lancets, Safety Lancets, Retractable Lancets, Spring-Activated Lancets, Reusable Lancets Application: Diabetes Monitoring, Hematology Testing, Allergy Testing, Hormone Testing, Coagulation Testing End User: Diagnostic Laboratories, Blood Donation Centers, Clinical Research Organizations, Home Care Providers, Phlebotomy Clinics Distribution Channel: Hospital Pharmacies, Online Retailers, Medical Supply Wholesalers, Specialty Stores, Direct Sales |
| Companies Covered | Becton, Dickinson and Company, Roche Diagnostics, B. Braun SE, Abbott Laboratories, Terumo Corporation, Ypsomed, HTL-Strefa, Medline Industries, Owen Mumford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lancets Market Shifts & Advancements
Engineering priorities across the lancet category are pivoting toward integrated safety mechanisms and connectivity-ready form factors that align with decentralized diagnostic workflows.
Retractable trigger systems are migrating from premium acute-care SKUs toward mid-tier home monitoring configurations. Hospital procurement committees now specify exposed-needle elimination as a baseline requirement. This mechanism diffusion is compressing the price premium historically commanded by safety-engineered devices.
EU MDR post-market surveillance obligations are extending clinical evidence requirements beyond initial CE marking. Manufacturers must maintain active safety databases and periodic performance reviews. High-volume contract holders in Germany and France are absorbing these compliance costs through centralized quality infrastructure.
Self-monitoring patients are consolidating purchasing through integrated glucose meter subscription programs. Retail pharmacy shelf space for standalone lancet SKUs is contracting as device bundling captures recurring revenue streams. This channel compression is most pronounced in United States Medicare reimbursement corridors where payors incentivize chronic disease management platform adherence.
Global Lancets Market Segmentation
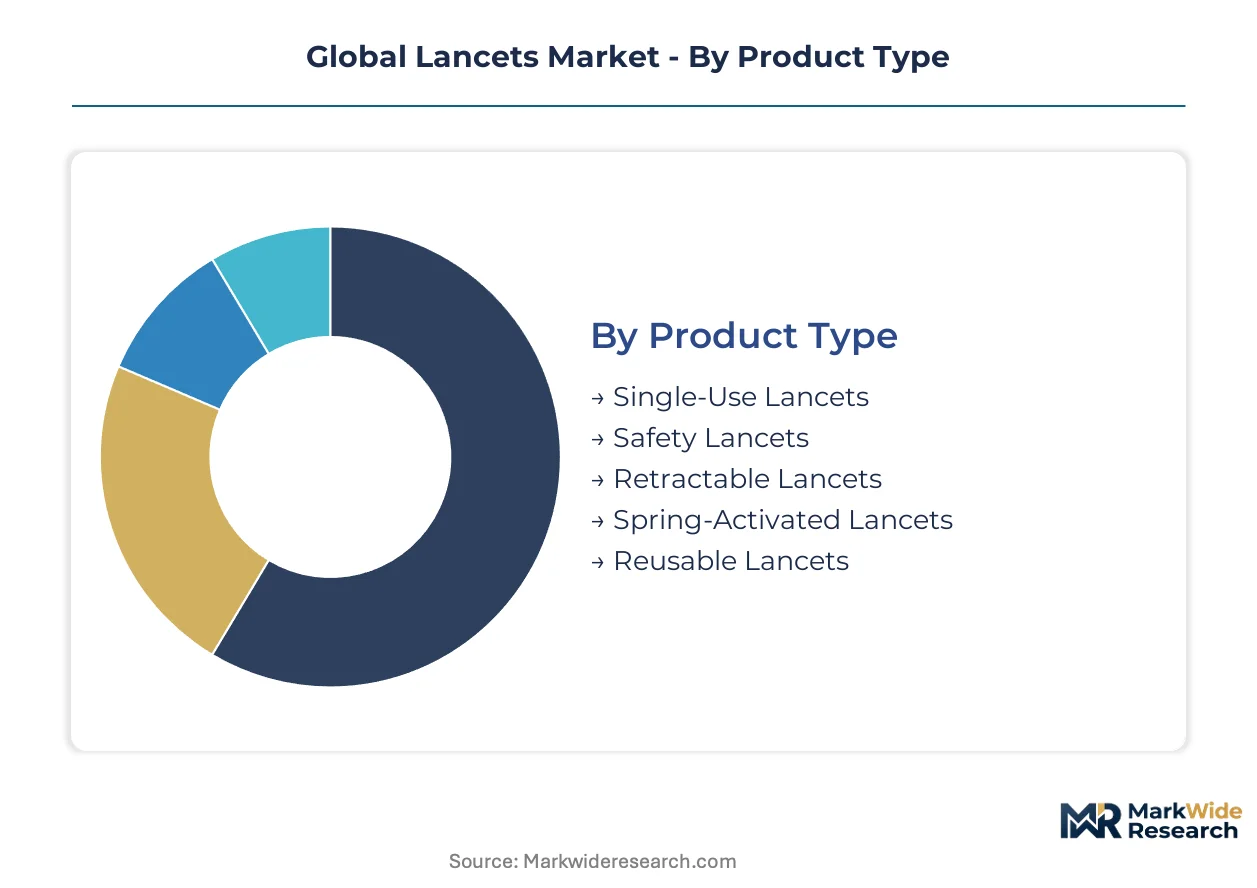
Lancet purchasing patterns fragment sharply across clinical and consumer channels, with product lifecycle velocity varying from single-use disposables to multi-year reusable platforms. Understanding segment turnover dynamics enables manufacturers to align inventory models with actual consumption cadence rather than aggregate demand assumptions.
Product Type:
Cycle times compress toward the safety-engineered end of the spectrum, where regulatory refresh mandates accelerate replacement schedules, while reusable platforms sustain decade-long amortization horizons in cost-constrained settings.
- Safety Lancets:These devices incorporate fixed-depth penetration with integrated needle shields that activate upon withdrawal, eliminating exposed sharps. Demand concentrates in United States hospital systems where OSHA needlestick prevention rules mandate engineered controls, though EU MDR post-market surveillance obligations now extend compliance documentation burdens across the product lifecycle.
- Retractable Lancets:Trigger-activated mechanisms draw the blade into a sealed housing post-puncture, representing the dominant engineering trajectory for new product development. Germany's centralized hospital procurement networks specify exposed-needle elimination as baseline tender criteria, compressing price premiums for safety features as mechanism diffusion accelerates.
- Single-Use Lancets:Conventional fixed-blade disposables dominate volume in emerging markets where cost sensitivity overrides safety mandates.
- Spring-Activated Lancets:Pre-cocked mechanical systems standardize penetration force for patient self-collection.
- Reusable Lancets:Metal-bodied devices with replaceable blade cartridges persist in veterinary and industrial screening applications.
Safety lancets dominate installed base. Retractable mechanisms are where expansion concentrates.
Application:
Testing frequency creates divergent margin profiles, with daily self-monitoring applications sustaining recurring revenue streams against episodic clinical diagnostics that concentrate volume in quarterly purchasing windows.
- Diabetes Monitoring:Finger-prick glucose calibration demands precision-ground triangular tips calibrated to 1.0-1.5mm depths for capillary flow optimization. United States Medicare reimbursement corridors incentivize platform adherence through integrated meter-lancet subscription bundles, shifting purchasing from retail pharmacy shelves toward direct fulfillment channels.
- Hematology Testing:Microhematocrit and hemoglobin screening require deeper 2.5-3.0mm penetration for venous blood equivalent volumes. Diagnostic laboratories in France and Germany retain deepest margin pools through centralized purchasing agreements that lock in multi-year supply contracts with ISO 13485-certified manufacturers.
- Allergy Testing:Multi-site puncture protocols favor disposable arrays over individual lancets.
- Hormone Testing:Point-of-care fertility and cortisol assays drive demand for ultra-sharp beveled tips.
- Coagulation Testing:INR monitoring for anticoagulant therapy requires consistent penetration depth to minimize tissue trauma variability.
Diabetes monitoring commands recurring revenue density. Hematology testing anchors institutional contract value.
End User:
Procurement sophistication separates centralized laboratory tender processes from fragmented home-care purchasing, with blood donation centers occupying an intermediate tier of scheduled volume commitments.
- Home Care Providers:Patient-directed chronic disease management creates the steepest expansion trajectory for integrated glucose-lancet systems. India's tier-2 city distribution networks remain underpenetrated, offering whitespace for localized partnerships that bypass hospital pharmacy intermediaries.
- Diagnostic Laboratories:High-throughput central facilities in the United States and Germany consolidate purchasing through preferred vendor networks that demand sterilization validation per ISO 11607-1. These contracts limit pricing autonomy for suppliers outside established quality infrastructure.
- Blood Donation Centers:Scheduled screening programs generate predictable volume with standardized safety specifications.
- Clinical Research Organizations:Trial protocols drive demand for calibrated penetration consistency across multi-site studies.
- Phlebotomy Clinics:Capillary collection specialists balance throughput efficiency against patient comfort metrics.
Diagnostic laboratories dominate contract value concentration. Home care providers are climbing the fastest.
Distribution Channel:
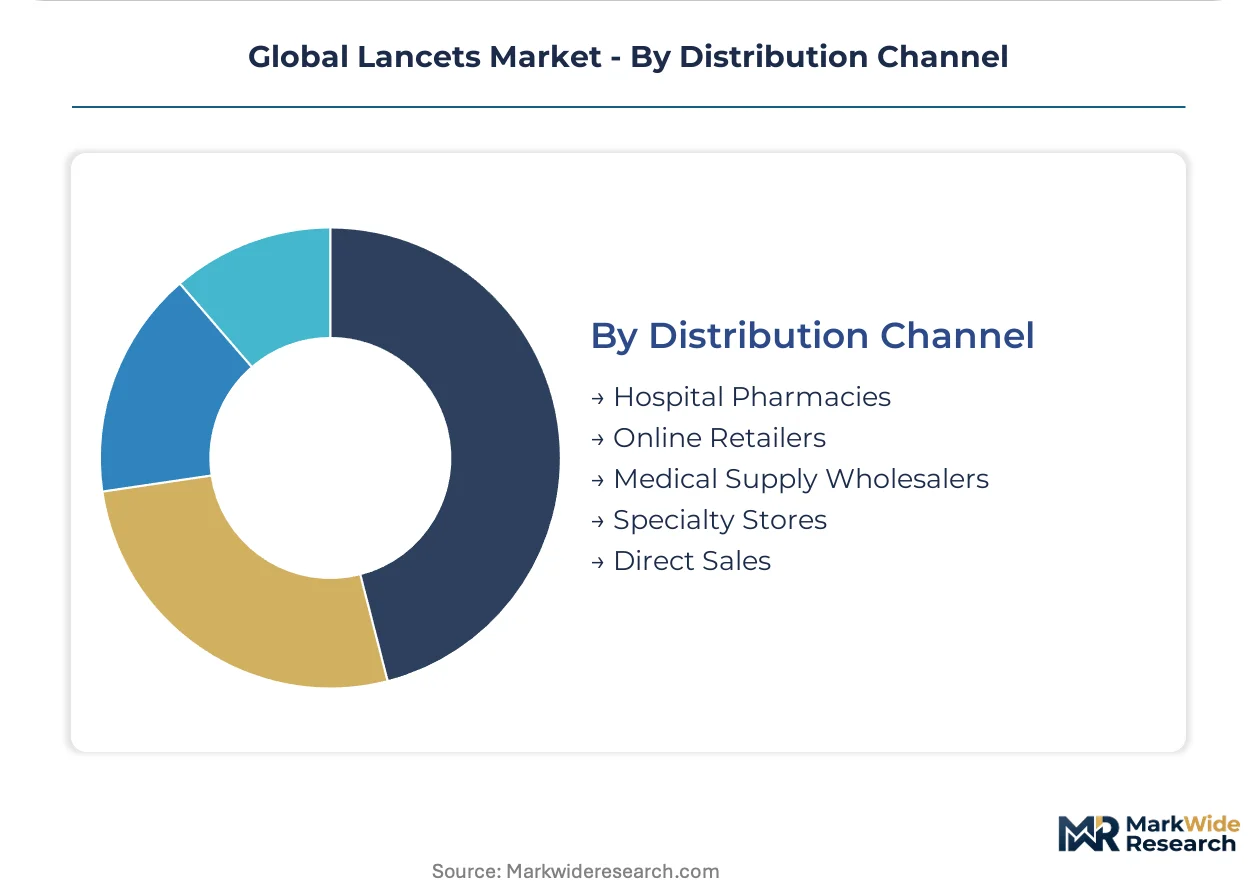
Channel economics diverge between high-touch institutional sales requiring field clinical support and automated digital fulfillment that captures margin through inventory disintermediation.
- Online Retailers:Direct-to-consumer platforms bypass hospital pharmacy procurement committees, enabling brands with digital fulfillment capabilities to capture recurring subscription revenue. United States patients managing chronic conditions outside clinical settings increasingly consolidate purchasing through integrated glucose meter programs.
- Hospital Pharmacies:Institutional procurement is narrowing as formulary committees prioritize bundled device contracts over standalone lancet SKUs. Becton, Dickinson and Company leverages existing institutional relationships to sustain shelf presence in acute care settings.
- Medical Supply Wholesalers:Regional distributors retain relevance in markets with fragmented provider landscapes.
- Specialty Stores:Diabetes-focused retail channels offer patient education touchpoints for new product adoption.
- Direct Sales:Manufacturer field forces serve high-volume laboratory accounts with custom logistics integration.
Hospital pharmacies dominate legacy volume. Online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States and German procurement corridors where safety mandates and reimbursement depth sustain premium mechanisms, while cost-sensitive markets in India and Brazil compress margins toward single-use commodity formats.
United States
Medicare reimbursement corridors incentivize integrated glucose-lancet subscription bundles that shift purchasing toward direct fulfillment channels. FDA 510(k) premarket notification requirements extend commercialization timelines for novel retractable designs. Hospital procurement committees in the Northeast Corridor increasingly specify exposed-needle elimination as baseline tender criteria.
Germany
Centralized hospital procurement networks specify safety-engineered designs as mandatory tender prerequisites, compressing price premiums for retractable mechanisms. EU MDR post-market surveillance obligations extend clinical evidence requirements beyond initial CE marking. Baden-Württemberg's medical device manufacturing cluster hosts quality infrastructure investments that absorb compliance cost burdens.
India
Tier-2 city distribution networks remain underpenetrated for home monitoring systems, creating whitespace for localized partnerships that bypass hospital pharmacy intermediaries. CDSCO medical device regulations are tightening sterilization validation standards for imported lancet devices. Maharashtra's chronic disease management infrastructure is expanding through public-private diagnostic partnerships in Mumbai and Pune.
Japan
Aging demographics sustain demand for patient-friendly self-collection devices with standardized penetration force calibration. PMDA quality management system audits enforce ISO 13485 compliance rigor that favors scaled producers over regional entrants. The Kansai region's Osaka-based medical supply distribution networks concentrate volume contracts for hematology screening applications.
Brazil
Public health system procurement for diabetes screening programs drives volume demand for cost-optimized single-use formats. ANVISA medical device registration requirements are aligning with international sterilization validation standards. São Paulo's diagnostic laboratory networks are consolidating purchasing through preferred vendor agreements that limit pricing autonomy for non-certified suppliers.
Global Lancets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-ground tips and retractable housings to branded device assemblers. The vendor base stratifies across three tiers: multinational health conglomerates with institutional contract depth, mid-scale regional manufacturers serving emerging market price points, and specialized safety-engineering firms focused on needlestick prevention mechanisms. Dominant competitive moves include backward integration into surgical-grade steel supply chains and strategic partnerships with glucose meter manufacturers for bundled subscription offerings.
Among diversified health technology conglomerates, Becton, Dickinson and Company and Abbott Laboratories occupy positions anchoring the acute care and home monitoring vectors respectively. Roche Diagnostics exemplifies the automated platform compatibility archetype, while Terumo Corporation and Ypsomed represent specialized engineering origins with crossover expertise from insulin delivery device categories.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Roche Diagnostics |
| B. Braun SE |
| Abbott Laboratories |
| Terumo Corporation |
| Ypsomed |
| HTL-Strefa |
| Medline Industries |
| Owen Mumford |
| Others |
Supply & Pricing Matrix
Surgical-grade stainless steel supply concentrates in German and Japanese specialty mills, anchoring margin capture downstream with ISO 13485-certified device assemblers who command premium positioning in hospital procurement corridors.
Pricing Analysis
Configured-to-order pricing for retractable trigger mechanisms commands spreads against standard fixed-blade formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Pricing pressure stems from mechanism diffusion as safety features become baseline requirements. Diagnostic laboratories exhibit lowest price sensitivity due to centralized contract lock-in, while emerging market distributors face acute cost compression.
Supply Chain Analysis
Tariff exposure between United States and Chinese component suppliers dominates supply chain risk planning for retractable housing manufacturers. Precision-ground tip production draws from German, Swiss, and Japanese machining centers. Raw material dependencies span surgical-grade stainless steel, high-carbon steel feedstock, and medical-grade polymer housings. Single-source vulnerability persists in spring-actuator subassemblies. Distribution runs through medical supply wholesalers serving hospital systems and direct-to-consumer platforms bypassing pharmacy intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lancet category faces high-growth disruption as FDA single-use safety mandates and EU MDR post-market surveillance obligations simultaneously elevate compliance barriers and compress product redesign cycles.
For Market Incumbents: Insulate market position by deepening backward integration into surgical-grade steel supply chains and accelerating ISO 13485 certification investments ahead of EU MDR enforcement waves. Retractable mechanism commoditization threatens premium tier margins; counter through exclusive hospital system partnerships that lock in formulary placement. For New Entrants and Emerging Players: India's tier-2 city distribution networks offer whitespace for localized partnerships bypassing hospital pharmacy intermediaries. Target direct-to-consumer subscription models for integrated glucose-lancet systems where Medicare reimbursement incentives consolidate purchasing. Pen-needle crossover compatibility with insulin delivery platforms provides the most penetrable entry angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale safety-engineering specialists holding needlestick prevention patents. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch for CDSCO regulatory tightening in India as the signal indicating acquisition timing for localized distribution platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Retractable Mechanism Patent Portfolio | OSHA needlestick mandates in United States hospitals lock in demand for engineered safety controls. |
| ISO 13485 Certification Investment | EU MDR post-market surveillance obligations extend compliance burdens across product lifecycles. |
| Direct-to-Consumer Channel Buildout | Medicare reimbursement corridors shift chronic disease purchasing toward integrated subscription fulfillment. |
| Pen-Needle Crossover Technology | Insulin delivery device compatibility creates bundled attach opportunities for diabetes platform players. |
| Localized India Distribution Partnership | Tier-2 city underpenetration offers whitespace bypassing hospital pharmacy procurement concentration. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and diabetes care coordinators provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up volume modeling triangulated with top-down market sizing across safety-engineered and conventional product categories.
Scenario-bracketing anchored projections across the analysis window, with segmentation modeling spanning product mechanism type, application specificity, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to calibrated baseline estimates, incorporating diabetes prevalence trajectories, safety mandate adoption curves, and channel shift elasticities as category-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by low-cost regional assemblers or accelerated FDA mechanism mandates would shift outcomes. Material shifts in EU MDR enforcement intensity or Indian CDSCO sterilization standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Global Needles Market
Medical Supplies
Surgical Amniotics Market