
 Serum Separating Tubes Market | 2026-2036
Serum Separating Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Serum Separating Tubes Market Analysis
Phlebotomy technician shortages across developed healthcare systems is reorganizing how laboratories procure pre-analytical consumables. Becton Dickinson and Company dominates North American institutional contracts through backward integration into resin molding and sterilization infrastructure. Greiner Bio-One International GmbH competes in European diagnostics networks with specialized Vacutainer lines optimized for high-throughput analyzers. Sarstedt AG & Co. KG anchors German-speaking markets through direct distribution to mid-sized hospital labs.
Serum separating tubes are evacuated blood collection vessels incorporating thixotropic gel barriers that partition serum from cellular components post-centrifugation, typically manufactured from polyethylene terephthalate or polypropylene with interior silicone coatings to control clot activation and hemolysis rates. Gel tubes command premium positioning in clinical chemistry and immunoassay workflows where sample integrity directly determines diagnostic accuracy. Plastic materials displace glass in most high-volume settings due to breakage reduction and lighter freight costs, though glass persists in specific research facilities requiring thermal stability. Blood banks represent a concentrated demand pocket with distinct volume specifications and regulatory documentation requirements.
The FDA enforces Class II medical device controls over tube sterility and additive concentration tolerances, while the EU MDR mandates updated technical documentation and post-market surveillance for CE-marked collection systems. ISO 6710 standards govern dimensional interchangeability across analyzer platforms, constraining proprietary design divergence. Laboratories and procurement consortia must monitor evolving biocompatibility testing protocols and polymer supply chain certifications as regulatory scrutiny intensifies for materials contacting human biological specimens.
Market Dynamics
Automated pre-analytical processing lines in diagnostic laboratories are compressing turnaround times and forcing tube manufacturers to standardize dimensional tolerances for robotic handling systems.
Growth Catalysts
- EU MDR compliance mandates:Updated technical documentation requirements for CE-marked collection systems are accelerating replacement cycles in European diagnostics networks.
- Thixotropic gel barrier chemistry:Advanced silicone-based separators are improving serum yield purity for immunoassay workflows in high-throughput clinical chemistry labs.
- Polyethylene terephthalate displacement:United States reference laboratories are converting glass tube inventories to plastic formats to reduce breakage-related specimen loss.
Market Restraints
- Petrochemical resin volatility:Polypropylene and PET feedstock prices fluctuate with crude oil benchmarks, compressing margin predictability for molded tube producers.
- Single-source sterilization infrastructure:Gamma irradiation capacity concentrates in Germany and the United States, creating geographic chokepoints for terminal sterilization.
- Glass persistence in research:Thermal stability requirements in academic medical centers sustain demand for borosilicate formats that plastic cannot replicate.
Strategic Opportunities
- Point-of-care expansion:Ambulatory surgical centers in Japan are adopting compact centrifuge-tube combinations for intraoperative chemistry panels.
- Blood bank documentation automation:Serialized tube labeling integrated with laboratory information systems streamlines regulatory traceability for transfusion services.
- ISO 6710 harmonization:Dimensional standardization across analyzer platforms enables private-label tube sourcing for procurement consortia.
Industry Challenges
- Phlebotomy technician scarcity:Workforce gaps in the United States and Germany are extending specimen collection windows and degrading sample quality.
- Additive concentration validation:FDA Class II controls require lot-to-lot testing of clot activator and gel barrier chemistries, extending release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum Separating Tubes Market |
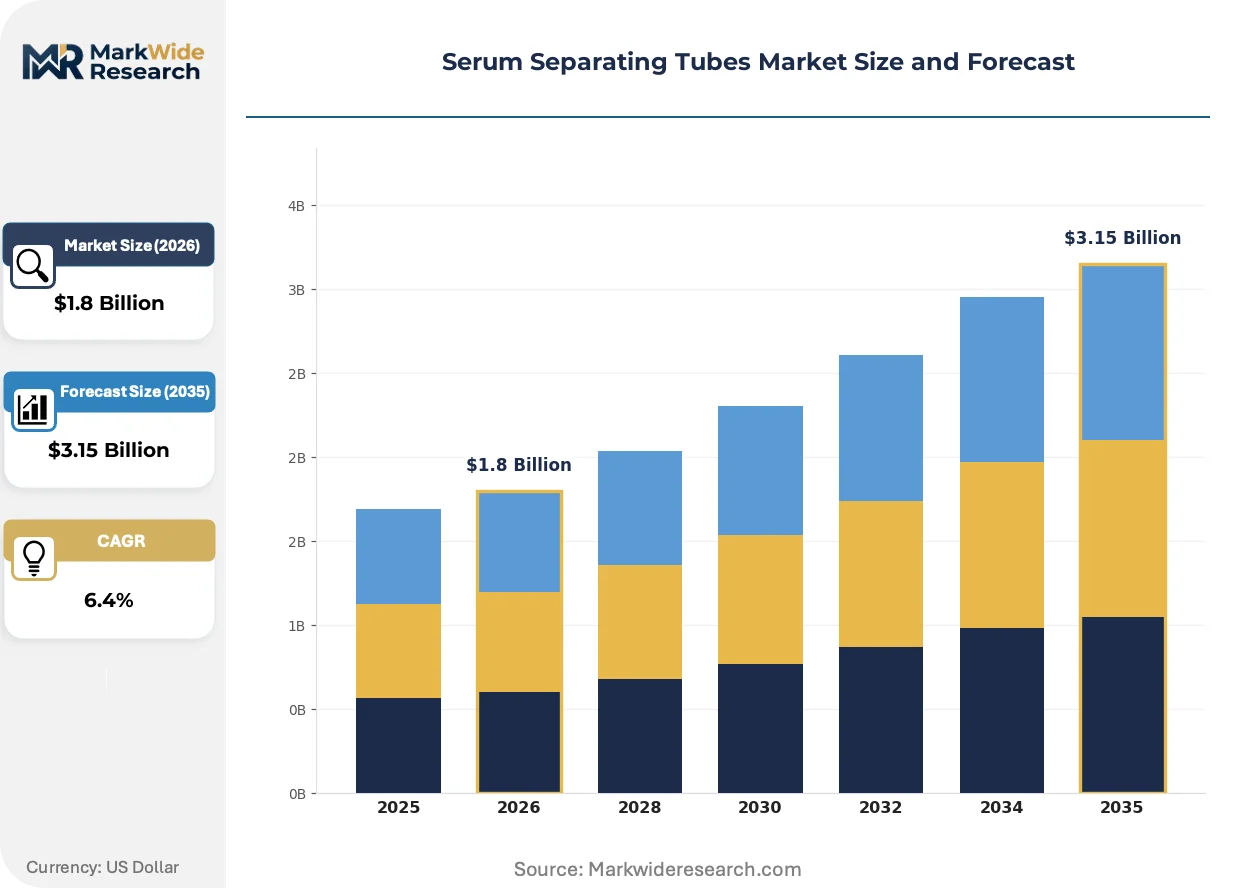
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacutainer, Blood Collection Set, Micro Tube, Gel Tube Material: Plastic, Glass, Polymer, Silicone Application: Clinical Labs, Blood Banks, Research Facilities, Hospitals End User: Laboratories, Healthcare Providers, Research Institutions, Diagnostic Centers |
| Companies Covered | Sarstedt AG & Co. KG, Danaher Corporation, Becton Dickinson and Company, Sekisui Diagnostics LLC, Corning Incorporated, Greiner Bio-One International GmbH, Thermo Fisher Scientific Inc., Terumo Corporation, Cardinal Health Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum Separating Tubes Market Emerging Trajectories
Pre-analytical automation is compressing specimen processing windows and forcing convergence between tube engineering and laboratory robotics architecture.
Micro-volume serum separating tubes is miniaturizing blood draw requirements for pediatric and geriatric populations. Neonatal intensive care units in Japan and Germany are adopting 0.5 mL draw formats to reduce iatrogenic anemia risk. This downsizing is compressing reagent consumption per test and enabling multiplexed analyzer configurations previously uneconomical at standard volumes.
REACH substance restrictions on phthalate plasticizers are forcing reformulation of tube cap and stopper elastomers across European manufacturing. Compounders must certify alternative plasticizer systems for biocompatibility under EU MDR Annex I requirements. Blood collection device manufacturers serving EEA markets are consolidating supplier audits to document compliance chain-of-custody for notified body review.
Consolidated procurement by multi-hospital health systems is displacing fragmented distributor relationships in the United States. Integrated delivery networks in Texas and California are negotiating direct contracts with tube manufacturers for standardized SKU rationalization. This concentration is compressing regional distributor margins and favoring suppliers with captive molding capacity and validated sterilization infrastructure.
Serum Separating Tubes Market Segmentation
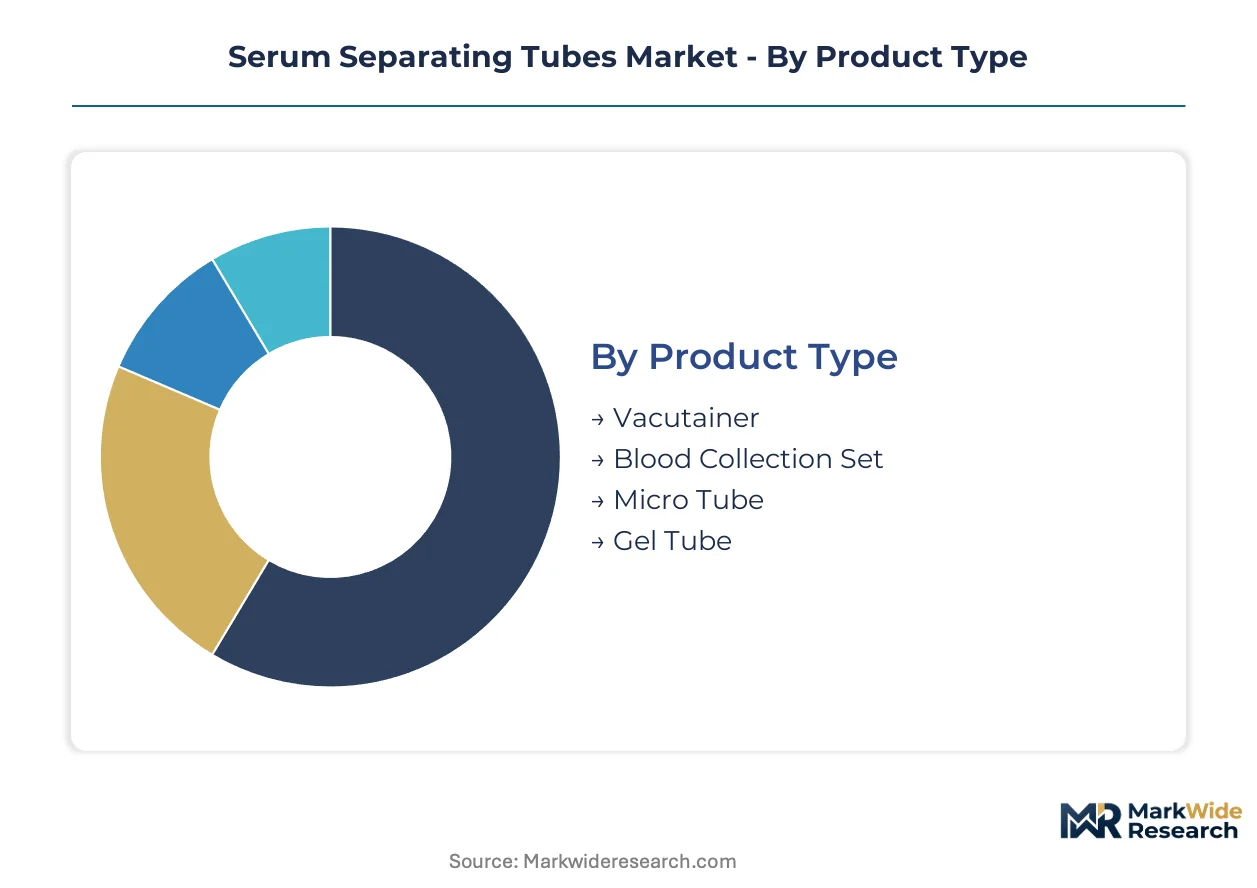
Serum separating tube procurement patterns diverge sharply across clinical settings, with automated high-throughput labs demanding dimensional precision while point-of-care sites prioritize draw-volume flexibility. Material selection and tube format choices directly determine compatibility with centrifugation protocols and analyzer interfaces.
Product Type:
Vacutainer formats face intensifying substitution pressure from micro tube alternatives in pediatric and geriatric care settings where blood volume conservation dominates clinical decision-making.
- Vacutainer:Evacuated blood collection vessels with standardized interior vacuum pressure enabling precise fill volumes. Demand concentrates in United States reference laboratories where BD's institutional contracts lock in high-volume procurement for chemistry and immunoassay workflows.
- Gel Tube:Thixotropic separator tubes incorporating silicone-based barriers that partition serum from clot post-centrifugation. German hospital networks favor these formats for STAT testing due to reduced aliquot transfer steps and faster turnaround times.
- Blood Collection Set:Integrated needle-tube combinations designed for single-draw efficiency. These configurations serve ambulatory surgical centers in Japan seeking to minimize phlebotomy steps.
- Micro Tube:Reduced-volume formats typically below 1.0 mL draw capacity. Neonatal intensive care units in Germany and Japan adopt these to limit iatrogenic anemia in low-birth-weight infants.
Vacutainer anchors the volume base while micro tube gains share at the steepest rate.
Material:
Cost tier stratification separates premium polymer formulations from commodity plastics, with glass persisting only where thermal stability justifies handling risk.
- Plastic:Polyethylene terephthalate and polypropylene tubes dominating high-volume clinical chemistry. United States laboratories converted glass inventories to plastic formats to reduce breakage-related specimen loss and lower freight costs per unit.
- Polymer:Advanced copolymer formulations engineered for dimensional stability under centrifugation stress. Japanese diagnostic manufacturers specify these materials for robotic handling systems requiring tight tolerance consistency.
- Glass:Borosilicate formats retaining niche demand in academic medical centers. Research facilities in Germany specify glass for thermal cycling applications where plastic deformation would compromise sample integrity.
- Silicone:Interior coating materials controlling clot activation kinetics and hemolysis rates. Blood banks in the United States specify silicone-coated surfaces to preserve coagulation factor activity in donor samples.
Plastic anchors the volume base while polymer gains share at the steepest rate.
Application:
Customer type concentration varies by throughput intensity, with blood banks representing a distinct procurement segment governed by transfusion service documentation requirements.
- Clinical Labs:High-throughput diagnostic facilities processing thousands of specimens daily. Automated pre-analytical lines in United States health systems force dimensional standardization for robotic tube handling.
- Blood Banks:Transfusion services requiring serialized traceability and specialized volume specifications. German Red Cross facilities mandate lot-level documentation linking each tube to donor identification systems.
- Hospitals:Acute care settings with mixed STAT and routine testing demands. Mid-sized German hospital labs source through direct distribution relationships emphasizing just-in-time replenishment.
- Research Facilities:Academic medical centers with protocol-specific material requirements. Thermal stability needs in some molecular biology workflows sustain borosilicate glass demand that clinical sites have abandoned.
Clinical labs anchors the volume base while blood banks gains share at the steepest rate.
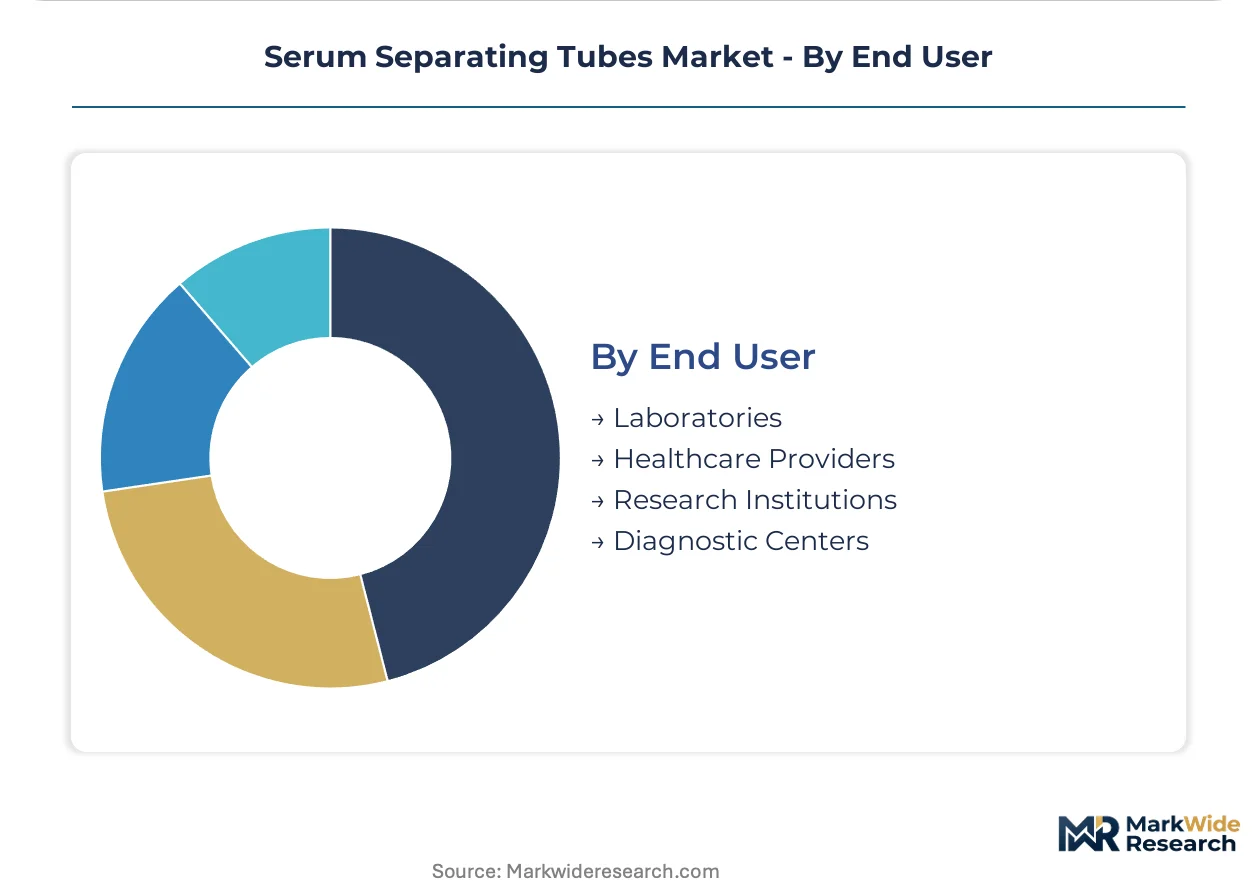
End User:
Procurement authority is consolidating as integrated delivery networks displace fragmented distributor relationships, compressing regional margin structures.
- Laboratories:Independent and hospital-affiliated diagnostic facilities with high-volume consumable throughput. Texas and California health systems negotiate direct manufacturer contracts for SKU rationalization across network sites.
- Diagnostic Centers:Outpatient facilities specializing in routine chemistry and immunoassay panels. Japanese ambulatory networks specify compact centrifuge-tube combinations for same-day result delivery.
- Healthcare Providers:Physician offices and clinics with lower throughput but diverse test menus. These sites prioritize draw-volume flexibility over processing speed.
- Research Institutions:Academic and commercial research organizations with protocol-specific requirements. German university hospitals maintain separate procurement streams for clinical versus research-grade materials.
Laboratories anchors the volume base while diagnostic centers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major healthcare systems. United States laboratories prioritize plastic formats for automated handling, German facilities emphasize gel separator chemistry for STAT workflows, and Japanese networks drive micro-volume innovation for pediatric applications.
United States
Reference laboratories and integrated delivery networks dominate procurement volume. FDA Class II medical device controls enforce sterility and additive concentration tolerances for all marketed collection systems. Texas and California health systems negotiate direct manufacturer contracts, bypassing traditional distributor channels for standardized SKU rationalization across network sites.
Germany
Mid-sized hospital labs and blood bank facilities anchor demand through direct distribution relationships. EU MDR mandates updated technical documentation and intensified post-market surveillance for CE-marked collection systems. The Nümbrecht region hosts specialized manufacturers supplying German-speaking diagnostics networks with Vacutainer-optimized formats for high-throughput analyzers.
Japan
Ambulatory surgical centers and neonatal intensive care units drive adoption of compact centrifuge-tube combinations and 0.5 mL micro formats. PMDA biocompatibility standards govern materials contacting biological specimens. Tokyo and Osaka metropolitan clusters concentrate procurement authority for centralized hospital networks specifying robotic handling compatibility.
United Kingdom
National Health Service procurement frameworks consolidate purchasing for chemistry and immunoassay workflows. MHRA regulations align with EU MDR transitional provisions for post-Brexit device certification. London and Southeast England reference laboratories standardize dimensional tolerances for automated pre-analytical processing lines.
China
Domestic diagnostic manufacturers expand molded tube capacity to serve tier-one hospital networks. NMPA medical device registration requirements intensify for polymer-based collection systems. Yangtze River Delta industrial clusters concentrate resin compounding and gamma sterilization infrastructure for regional supply security.
Serum Separating Tubes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in captive resin molding and terminal sterilization infrastructure. The upper tier commands institutional contracts through validated supply chains, while mid-cap competitors defend position through regional distribution density and application-specific format development. Strategic moves center on backward integration into polymer feedstock and consolidation of gamma irradiation capacity. Procurement consolidation by multi-hospital systems is compressing distributor margins and favoring manufacturers with in-house production capabilities.
Among Germany-based specialists, Sarstedt AG & Co. KG and Greiner Bio-One International GmbH occupy positions anchored in European diagnostics networks, with the former exemplifying direct distribution models to mid-sized hospital labs and the latter representing Vacutainer line optimization for automated analyzers. Becton Dickinson and Company, identifiable by its corporate suffix, represents the integrated archetype with institutional contract penetration across North American reference laboratories. These three entities collectively illustrate the geographic segmentation of procurement authority and the competitive premium placed on validated sterilization infrastructure.
| Leading Market Players |
|---|
| Sarstedt AG & Co. KG |
| Danaher Corporation |
| Becton Dickinson and Company |
| Sekisui Diagnostics LLC |
| Corning Incorporated |
| Greiner Bio-One International GmbH |
| Thermo Fisher Scientific Inc. |
| Terumo Corporation |
| Cardinal Health Inc. |
| Others |
Supply Flow & Price Mechanics
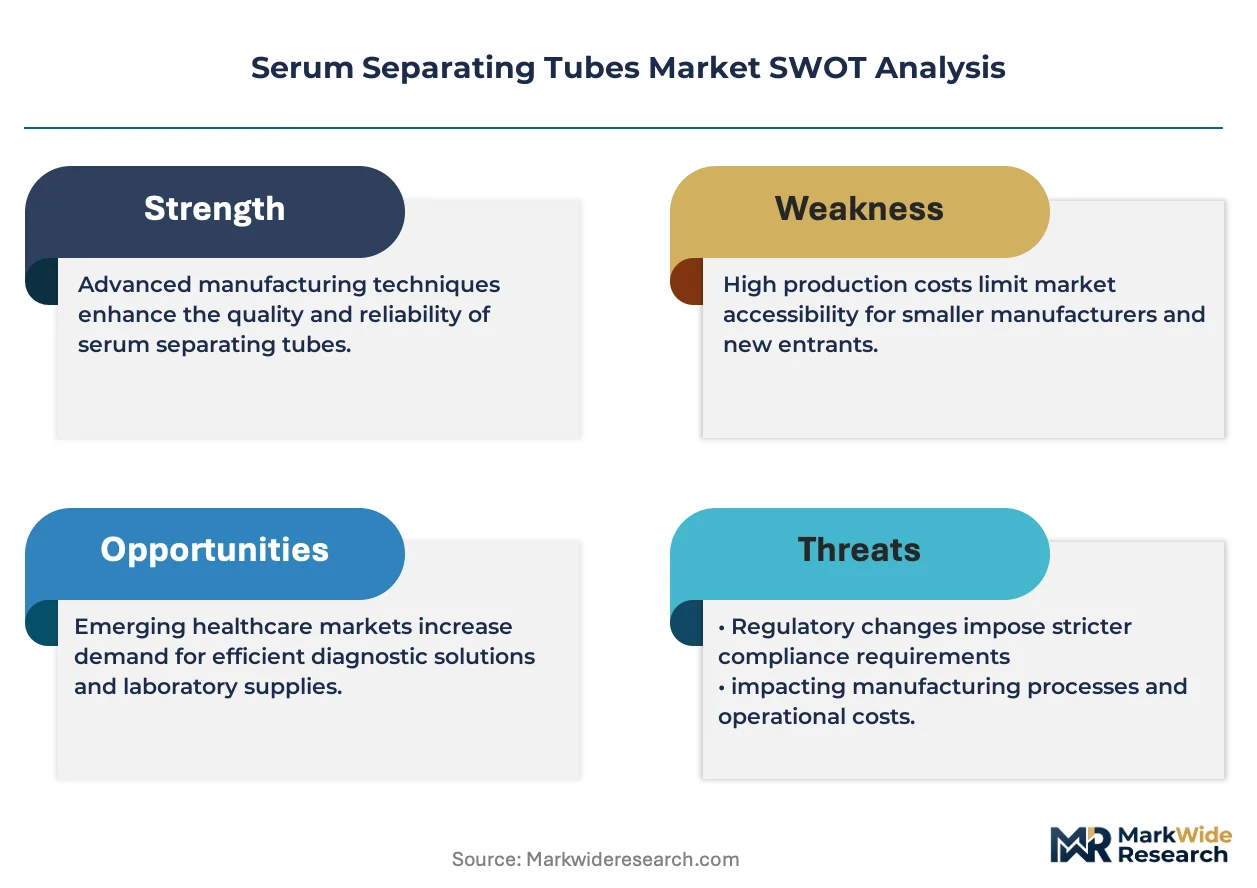
FDA Class II medical device controls and EU MDR Annex I biocompatibility requirements simultaneously gate supplier qualification and stratify price tiers across the serum separating tubes market, forcing manufacturers to absorb certification costs into premium positioning while commodity-grade alternatives face margin compression from procurement consolidation.
Pricing Analysis
Long-term institutional offtake agreements dominate procurement between United States integrated delivery networks and manufacturers with validated sterilization infrastructure, while spot purchasing persists for research-grade borosilicate formats. Three-tier pricing structure across premium, standard, and economy levels separates gel separator tubes with advanced thixotropic chemistry from basic plastic Vacutainers and uncoated commodity alternatives. Cost compression in standard-tier PET tubes is intensifying because Texas and California health systems negotiate direct manufacturer contracts, bypassing distributor markups. Blood banks and neonatal intensive care units exhibit lowest price sensitivity due to protocol-locked specifications, while ambulatory surgical centers in Japan drive hardest bargain on compact centrifuge-tube combinations.
Supply Chain Analysis
Just-in-time replenishment preferences among German mid-sized hospital labs contrast with strategic stockpiling of gamma-sterilized inventories by United States reference laboratories anticipating single-source sterilization bottlenecks. Resin compounding concentrates in Germany, the United States, and China, with PET and polypropylene feedstock drawing from petrochemical complexes tethered to crude oil benchmarks. Single-source gamma irradiation vulnerability concentrates terminal sterilization in Nümbrecht-region facilities and select United States sites. Distribution runs through direct manufacturer relationships for institutional contracts, while regional distributors serve fragmented healthcare provider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-analytical automation and micro-volume format innovation are disrupting procurement patterns, with EU MDR compliance timelines compressing supplier replacement cycles and opening windows for repositioning.
For Market Incumbents: Consolidate backward integration into resin molding and captive gamma sterilization infrastructure to defend against phlebotomy technician scarcity degrading sample quality and triggering demand volatility. Lock in multi-year institutional contracts with Texas and California integrated delivery networks before SKU rationalization waves eliminate distributor buffer relationships. Prioritize ISO 6710 dimensional certification investments to maintain robotic handling compatibility as automated pre-analytical lines proliferate. For New Entrants and Emerging Players: Differentiate on micro-volume gel separator chemistry optimized for 0.5 mL neonatal draws in Japan and Germany, where iatrogenic anemia protocols create protocol-locked demand pockets. Target blood bank documentation automation as the most penetrable segment, with serialized tube labeling integrated to laboratory information systems representing unserved need beneath incumbent radar. Pursue private-label sourcing partnerships with procurement consortia leveraging ISO 6710 harmonization to bypass brand loyalty barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across polymer formulation and sterilization infrastructure, favoring acquisition of mid-cap European manufacturers with EU MDR technical documentation already filed. Five-to-ten year viability hinges on positioning ahead of REACH substance restriction enforcement on phthalate plasticizers forcing stopper reformulation. Watch gamma irradiation capacity utilization rates as the signal for sterilization chokepoint severity and pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Molding | Captive PET supply secures margin control against petrochemical volatility and FDA additive tolerance requirements. |
| EU MDR Technical Documentation Filing | Accelerated CE marking pathway captures replacement cycle demand as European diagnostics networks retool. |
| Micro-Volume Format Development | 0.5 mL gel tubes penetrate Japan NICU protocols and German pediatric networks with protocol-locked specifications. |
| Serialized Labeling System Integration | Blood bank traceability automation aligns with German Red Cross lot-level documentation mandates. |
| Gamma Sterilization Capacity Expansion | Terminal sterilization infrastructure alleviates geographic chokepoints in Germany and United States supply nodes. |
Methodological Framework
A spread of perspectives from hospital procurement managers, GPO contracts directors, biomedical engineers, and phlebotomy supervisors converged on the working assumptions, validated against FDA 510(k) filings, EU MDR notified body documentation, ISO 6710 certification records, and hospital supply chain databases. Bottom-up unit demand estimates from clinical chemistry and immunoassay workflow counts were triangulated with top-down polymer consumption data from resin compounding disclosures.
Segmentation dimensions modeled include product format, material chemistry, application setting, and end-user procurement authority across the projection horizon. CAGRs were derived from installed base expansion of automated pre-analytical lines and blood draw volume trends in reference laboratory networks. Forecast inputs incorporated phlebotomy workforce projections and EU MDR transition timelines for technical documentation updates.
Forecasts assume regulatory continuity in FDA Class II controls and EU MDR Annex I requirements; material policy shifts would require re-modeling. Revision becomes warranted when gamma sterilization capacity utilization or petrochemical feedstock volatility crosses thresholds disrupting supply security assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Suture Wire Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Amniotic Products Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
NPWT Canisters Market