
 Global Medical Elastomers Market | 2026-2036
Global Medical Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Elastomers Market Foresight
China is tilting toward expanded thermoplastic elastomer capacity for medical-grade applications. Dow Inc. leverages integrated silicone supply chains across North America and Europe. BASF SE sustains R&D intensity in high-purity styrenic block copolymers for drug delivery devices. Trelleborg AB anchors its position through specialized cleanroom manufacturing for seals and gaskets.
Medical elastomers comprise polymeric materials exhibiting reversible elastic deformation under stress, including silicones, thermoplastic elastomers, and fluoroelastomers formulated to meet USP Class VI and ISO 10993 biocompatibility standards for repeated sterilization cycles. These materials serve critical functions in fluid containment, barrier protection, and flexible mechanical interfaces within invasive and non-invasive medical devices. Silicone elastomers command the largest value share due to established clinical acceptance and broad regulatory clearances across implantable and non-implantable applications. Thermoplastic elastomers represent the fastest-expanding product category, displacing conventional vulcanized rubbers in disposable diagnostic components where cost-efficient injection molding and recycling compatibility matter. Drug delivery devices concentrate margin pools as manufacturers demand elastomeric formulations with precise permeation control and extractables profiles.
FDA enforces biocompatibility and sterilization validation protocols under 21 CFR Part 820 quality system regulations, while the EU MDR mandates enhanced clinical evidence and post-market surveillance for elastomeric components in Class IIa and higher devices. ISO 10993 series standards govern biological evaluation, with ISO 13485 certification becoming a baseline procurement filter for OEM supply agreements. Stakeholders must monitor evolving extractables and leachables testing requirements as regulatory bodies tighten scrutiny on additive packages and processing aids in long-dwell medical applications.
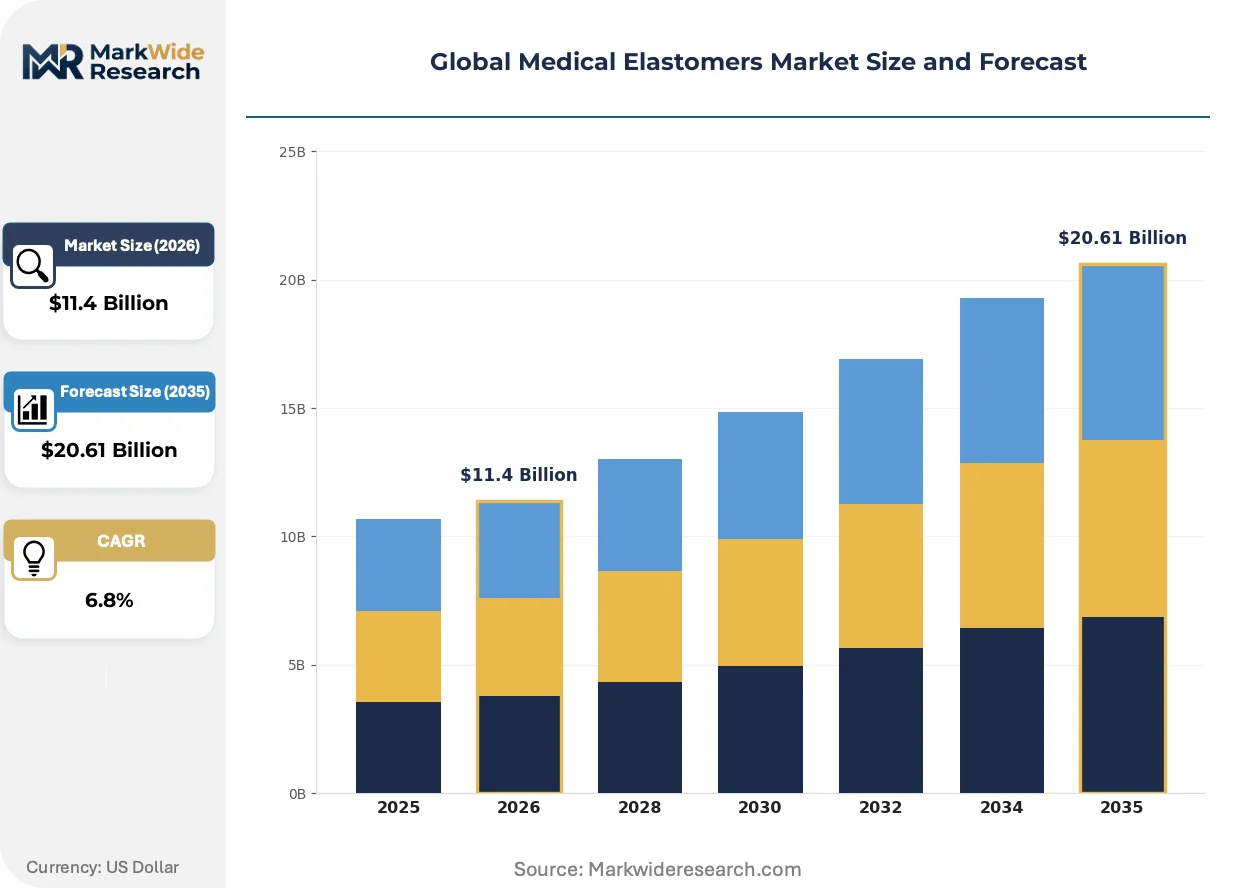
Market Dynamics
Regulatory tightening around extractables and leachables testing is forcing medical device manufacturers to requalify entire elastomer portfolios, compressing supplier switching costs while elevating biocompatibility documentation to a primary procurement filter.
Growth Catalysts
- EU MDR clinical evidence mandates:Class IIa and higher devices require enhanced post-market surveillance, driving demand for pre-validated elastomer grades with established biological evaluation dossiers.
- Thermoplastic elastomer process economics:Injection molding cycle times and recycling compatibility are displacing conventional vulcanized rubbers in high-volume disposable diagnostic components.
- Drug delivery precision requirements:Manufacturers seek elastomeric formulations with controlled permeation profiles for implantable pumps and auto-injectors, concentrating margin pools in specialized compounding capabilities.
Market Restraints
- Silicone feedstock concentration:Organosilicon precursor supply clusters in China and Germany expose compounders to geopolitical disruption and freight cost volatility.
- ISO 10993-18 extractables testing burden:Analytical chemistry requirements for additive packages and processing aids extend qualification timelines by 12-18 months for new material introductions.
- Fluoroelastomer substitution pressure:Perfluorinated chemistry faces scrutiny under EU REACH restriction proposals, prompting OEMs to evaluate hydrogenated nitrile alternatives for seal applications.
Strategic Opportunities
- India medical device manufacturing:PLI scheme incentives and CDSCO regulatory harmonization efforts are attracting catheter and tubing investments to Ahmedabad and Chennai clusters.
- Continuous manufacturing integration:Twin-screw extrusion and direct compounding lines enable real-time viscosity control for drug-eluting elastomeric reservoirs.
- Cleanroom-as-a-service models:Specialized toll compounding with ISO 13485 certification reduces capital barriers for mid-size device innovators entering implantable segments.
Industry Challenges
- Biocompatibility toxicologist scarcity:ISO 10993-1 interpretation expertise concentrates at contract research organizations, creating bottlenecks for small-volume OEM qualification programs.
- Legacy sterilization validation gaps:Gamma and electron-beam dose mapping studies for novel elastomer grades require redundant testing across multiple device configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Elastomers Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SIS, Silicone, Natural Rubber, Fluoroelastomers, Thermoplastic Elastomers Application: Catheters, Seals & Gaskets, Surgical Instruments, Wound Care, Drug Delivery Devices End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Pharmaceutical Manufacturers Delivery Mode: Injection Molding, Extrusion, Compression Molding, Transfer Molding, Blow Molding |
| Companies Covered | BASF SE, Dow Inc., Celanese Corporation, Eastman Chemical Company, Solvay, DuPont, Kuraray Co. Ltd., Teknor Apex, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Elastomers Market Shifts & Advancements
Digitalization of material qualification workflows and convergence of additive manufacturing with elastomer processing are compressing development cycles while fragmenting traditional batch-release economics.
Liquid silicone rubber (LSR) injection molding with in-mold monitoring sensors is rendering obsolete conventional compression molding for complex catheter hub geometries. Cardiovascular device manufacturers in Minnesota and Massachusetts are adopting LSR-cell integrations that cut cycle times by half. The technology is compressing minimum viable volume thresholds and enabling same-day design iterations that thermoset alternatives cannot match.
FDA's updated guidance on ISO 10993-1 biological evaluation requires chemical characterization for all new elastomer formulations regardless of prior predicate device history. The policy elevates extractables profiling to a gatekeeping step in 510(k) submissions. Implantable device segments in the United States are responding by pre-qualifying supplier compounds through master file arrangements.
Hospital procurement consortia are consolidating elastomeric component sourcing through single-source framework agreements with tier-one compounders. Group purchasing organizations in Germany and the United States are displacing spot-market purchasing for standard-grade tubing and seals. Device OEMs in these markets now face margin compression unless they demonstrate unique formulation IP or dedicated cleanroom capacity.
Global Medical Elastomers Market Segmentation
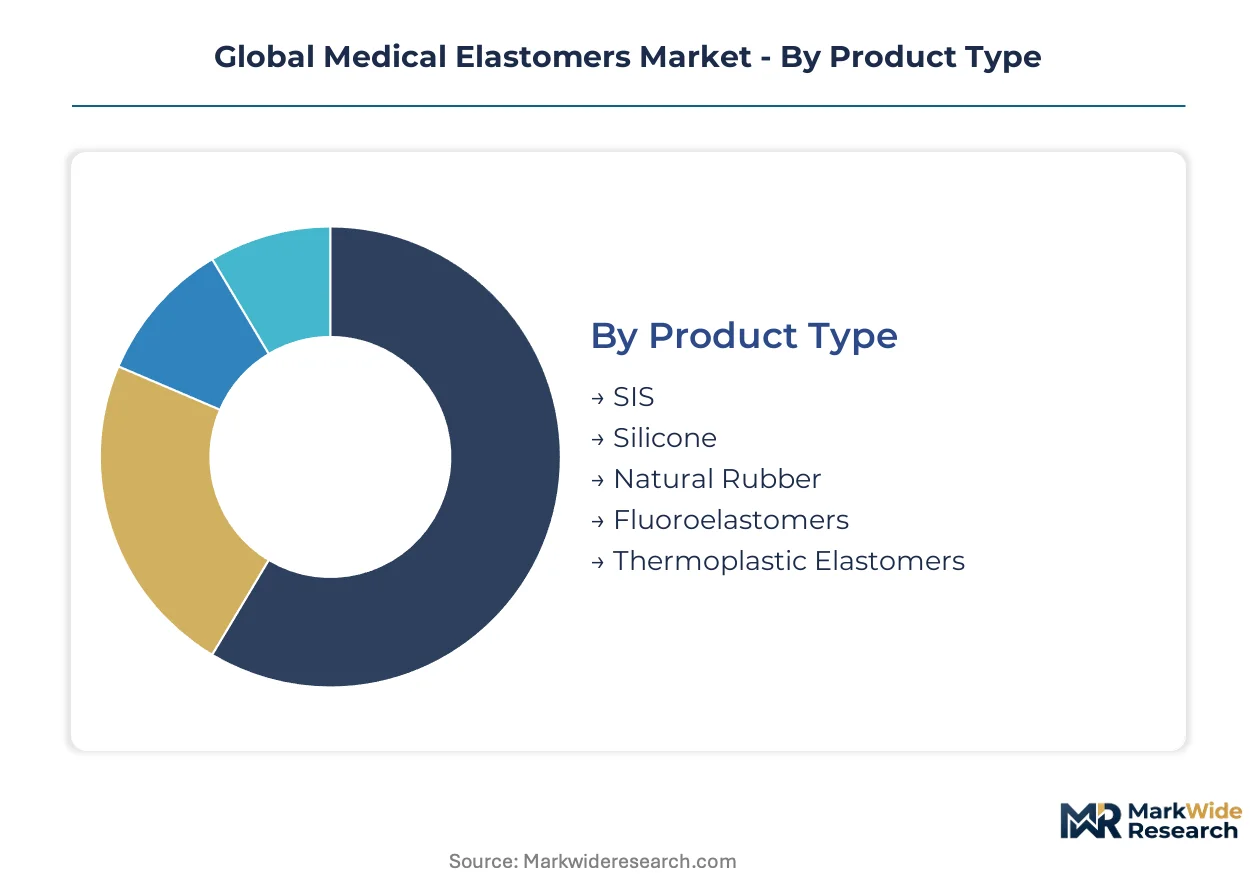
Medical elastomer segmentation reveals divergent performance requirements across implantable, interventional, and diagnostic applications. Material selection cascades through sterilization compatibility, extractables profiles, and processing economics that reshape supplier positioning.
Product Type:
Silicone elastomers anchor chronic implant applications while thermoplastic alternatives penetrate high-throughput disposables.
- Silicone:Cross-linked polydimethylsiloxane networks withstand gamma and autoclave sterilization without property degradation. Demand concentrates in implantable pumps and long-dwell catheters where USP Class VI compliance and decades of clinical precedent reduce regulatory risk for device OEMs.
- Thermoplastic Elastomers:Styrenic block copolymers and polyolefin blends enable overmolding and recycling compatibility absent in thermoset alternatives. Germany and China are expanding compounding capacity for diagnostic consumables where injection molding cycle economics outweigh material cost premiums.
- Fluoroelastomers:Perfluorinated chemistry delivers chemical resistance for aggressive drug formulations and surgical sealants.
- SIS:Styrene-isoprene-styrene block copolymers serve pressure-sensitive adhesive layers in wound care and transdermal patches.
- Natural Rubber:Latex-based formulations persist in surgical gloves and elastic bandages despite protein allergen concerns.
The dominant share belongs to Silicone, while Thermoplastic Elastomers is closing the gap fastest.
Application:
Functional demands fragment across fluid containment, barrier protection, and mechanical actuation roles.
- Catheters:Multi-lumen tubing and hub assemblies require kink resistance, torque transmission, and bondability to rigid polymers. Minnesota and Massachusetts device clusters drive specification tightening for cardiovascular and urological access devices.
- Drug Delivery Devices:Auto-injector plungers, pump reservoirs, and septa demand precise compression set and extractables control. FDA's ISO 10993-18 emphasis is elongating qualification timelines for novel formulations in this high-margin segment.
- Seals & Gaskets:Static and dynamic sealing in surgical instruments and diagnostic equipment prioritizes compression set resistance and broad chemical compatibility.
- Surgical Instruments:Grips, handles, and insulating layers balance sterilization durability with tactile feedback requirements.
- Wound Care:Adhesive dressings and negative pressure therapy seals emphasize moisture vapor transmission and gentle skin adhesion.
Catheters command the largest volume position, though Drug Delivery Devices generates the steepest margin expansion.
End User:
Procurement sophistication varies from centralized hospital consortia to specialized pharmaceutical manufacturing.
- Hospitals:Group purchasing organizations in the United States and Germany consolidate tubing and seal sourcing through multi-year framework agreements. Standard-grade silicone components face price compression unless suppliers demonstrate dedicated cleanroom capacity or formulation IP.
- Pharmaceutical Manufacturers:Combination product regulations impose extractables validation burdens that favor pre-qualified elastomer compounds with master file arrangements. Injectable drug containment drives demand for platinum-cured silicone and specialized halobutyl formulations.
- Ambulatory Surgical Centers:Cost-sensitive procurement favors thermoplastic elastomer disposables over reusable silicone alternatives.
- Diagnostic Laboratories:High-throughput consumable consumption prioritizes injection molding efficiency and lot-to-lot consistency.
Hospitals absorb the greatest tonnage, yet Pharmaceutical Manufacturers concentrate the most stringent material qualification requirements.
Delivery Mode:
Processing technology selection locks in cost structures and design freedom for device geometries.
- Injection Molding:Liquid silicone rubber and thermoplastic elastomer injection enable complex geometries with tight dimensional tolerances. LSR-cell integrations with in-mold monitoring are displacing compression molding for catheter hubs in United States cardiovascular device manufacturing.
- Extrusion:Continuous profile generation dominates multi-lumen tubing production where concentricity and wall uniformity determine device performance. China and Germany host the most advanced medical tubing extrusion lines.
- Compression Molding:Thermoset silicone curing persists for large-section seals and gaskets where tooling simplicity outweighs cycle time penalties.
- Transfer Molding:Intermediate complexity components balance tooling cost with geometric capability for medium-volume surgical instrument parts.
- Blow Molding:Hollow elastomeric reservoirs and bellows applications remain niche due to limited material compatibility.
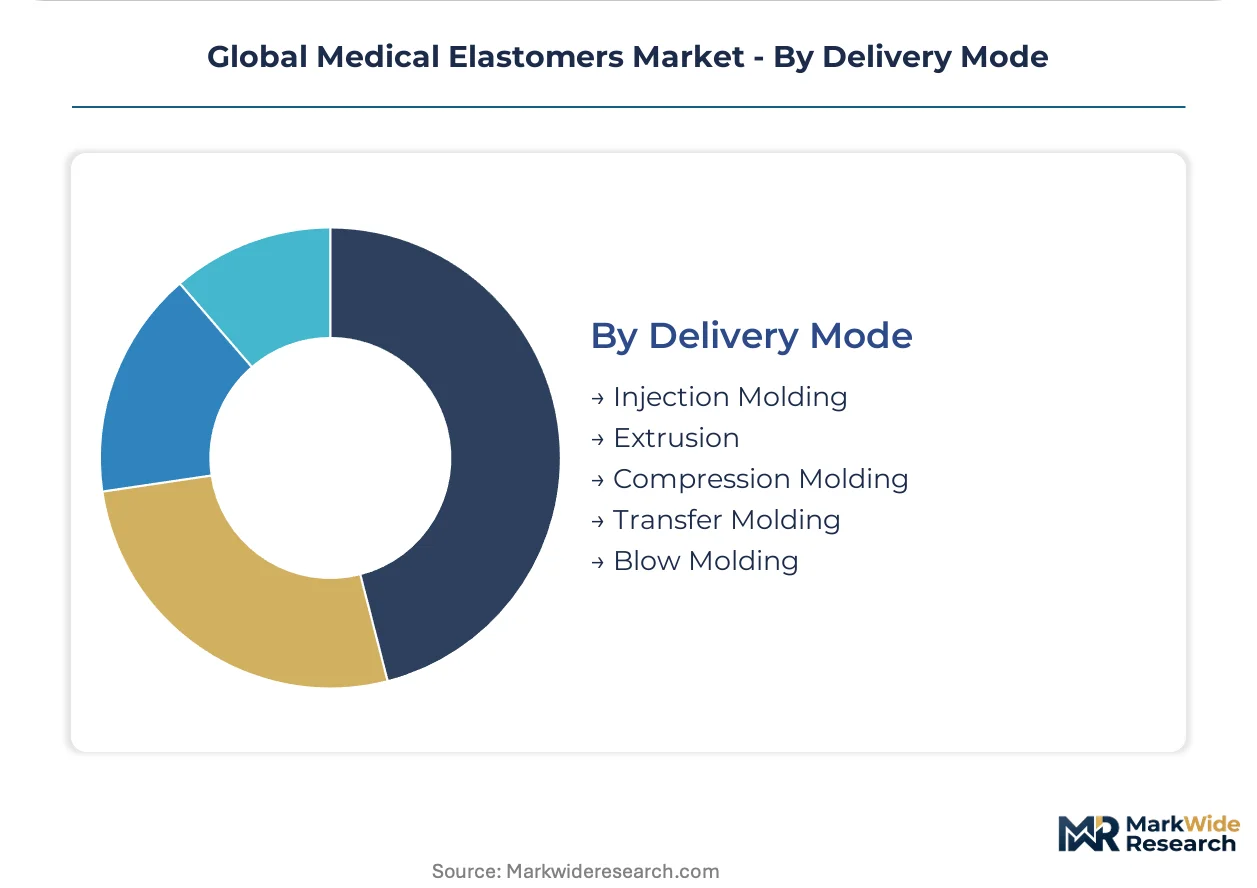
Injection Molding and Extrusion together process the overwhelming majority of medical elastomer volume, with Compression Molding retreating to legacy seal applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes implant-grade silicone for long-dwell devices, while China and Germany concentrate on high-throughput thermoplastic elastomer disposables where injection molding economics dominate procurement decisions.
United States
FDA's ISO 10993-18 extractables mandates and 21 CFR Part 820 quality system regulations drive demand for pre-qualified elastomer compounds with established biological evaluation dossiers. The cardiovascular device clusters in Minnesota and Massachusetts are adopting liquid silicone rubber injection molding with in-mold monitoring sensors for catheter hub geometries. Hospital procurement consortia are consolidating tubing and seal sourcing through multi-year framework agreements.
Germany
EU MDR clinical evidence requirements for Class IIa and higher devices elevate biocompatibility documentation to a primary procurement filter for elastomer suppliers. BASF SE sustains R&D intensity in high-purity styrenic block copolymers for drug delivery devices from its Ludwigshafen operations. The country's medical device manufacturing base is expanding compounding capacity for diagnostic consumables.
China
Organosilicon precursor supply concentration exposes compounders to freight cost volatility, yet domestic demand for thermoplastic elastomer capacity continues expanding. NMPA regulatory harmonization efforts and dual carbon goals are reshaping material qualification timelines. Medical-grade elastomer production is tilting toward expanded thermoplastic capacity in key manufacturing zones.
India
PLI scheme incentives and CDSCO regulatory alignment are attracting catheter and tubing investments to Ahmedabad and Chennai clusters. Cost-sensitive procurement at ambulatory surgical centers favors thermoplastic elastomer disposables over reusable silicone alternatives. Domestic compounding capabilities remain underdeveloped for implant-grade applications.
Japan
PMDA biocompatibility standards and METI industrial policy support precision elastomeric components for combination products and auto-injector systems. The country's pharmaceutical manufacturers impose stringent extractables validation burdens that favor pre-qualified compounds with master file arrangements. Medical device innovation concentrates in the Kanto and Kansai industrial corridors.
Global Medical Elastomers Market Competitive Landscape
Capability concentration sits with specialized cleanroom compounders holding ISO 13485 certification and established biological evaluation dossiers; scale advantage sits with integrated chemical producers commanding organosilicon precursor supply chains. The market structures around three tiers: multinational diversified chemical conglomerates, mid-cap elastomer specialists with dedicated medical divisions, and regional toll compounders offering cleanroom-as-a-service models. Dominant competitive moves include backward integration into silicone feedstock production and strategic partnerships with device OEMs for co-developed drug-eluting formulations.
Among integrated chemical producers, Dow Inc. and BASF SE exemplify the scale-driven tier with captive supply chain control over medical-grade silicone and styrenic block copolymer precursors. Trelleborg AB occupies a position within the specialist tier, anchoring its market presence through dedicated cleanroom manufacturing infrastructure for seals and gaskets. These three companies represent the archetypal competitive positions: upstream-integrated feedstock dominance, formulation R&D leadership, and manufacturing specialization with regulatory certification depth.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Celanese Corporation |
| Eastman Chemical Company |
| Solvay |
| DuPont |
| Kuraray Co. Ltd. |
| Teknor Apex |
| Trelleborg AB |
| Others |
Supply & Pricing Matrix
Ludwigshafen's styrenic block copolymer capacity expansions are compressing spot-market premiums for thermoplastic elastomer grades, forcing compounders in China and the United States to defend contract renewals through dedicated cleanroom certifications rather than volume discounts.
Pricing Analysis
Long-term offtake agreements with tier-one device OEMs dominate procurement for implant-grade silicone, insulating suppliers from spot-price volatility in organosilicon feedstocks. Three-tier pricing structure across platinum-cured, peroxide-cured, and industrial-grade silicone levels reflects ISO 10993-18 testing burden and master file availability. Pricing pressure stems from hospital GPO consolidation in Germany and the United States, where standard-grade tubing faces cost compression unless suppliers demonstrate formulation IP. Ambulatory surgical centers exhibit highest price sensitivity, favoring thermoplastic elastomer disposables; pharmaceutical manufacturers show lowest sensitivity due to extractables validation requirements.
Supply Chain Analysis
EU REACH restriction proposals on perfluorinated chemistry are constraining fluoroelastomer flows to medical seal applications, accelerating OEM qualification of hydrogenated nitrile alternatives. Organosilicon precursor production clusters in China, Germany, and the United States; styrenic block copolymers draw from BASF's Ludwigshafen complex and expanding Chinese compounding capacity. Single-source vulnerability concentrates in platinum-catalyzed silicone for drug-eluting reservoirs. Distribution runs through ISO 13485-certified toll compounders serving Minnesota and Massachusetts device clusters with just-in-time hub deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate hydrogenated nitrile substitution pressure as fluoroelastomers face regulatory headwinds, requiring rapid requalification of seal portfolios to defend contracted positions in surgical instrument supply chains.
For Market Incumbents: Insulate contracted revenue by accelerating backward integration into medical-grade silicone feedstock production in Germany or the United States, reducing exposure to Chinese organosilicon freight volatility. Secure ISO 10993-18 pre-validation dossiers for core compound grades to compress OEM switching timelines when EU MDR surveillance requirements tighten. Master file arrangements with FDA represent the critical defensive lever against emerging cleanroom-as-a-service competitors. For New Entrants and Emerging Players: Mid-tier diagnostic consumable manufacturers in India represent the most penetrable entry point, where PLI scheme incentives and CDSCO harmonization reduce regulatory friction for thermoplastic elastomer tubing suppliers. Toll compounding partnerships with ISO 13485-certified facilities in Ahmedabad bypass capital-intensive cleanroom construction. Direct sales to ambulatory surgical centers, bypassing consolidated hospital GPOs, offers the clearest go-to-market angle for cost-positioned entrants. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cleanroom compounders with established biological evaluation dossiers over commodity silicone producers. Long-term viability rests on regulatory certification depth rather than scale economics. Acquisition targets should demonstrate FDA master file arrangements and EU MDR technical documentation capabilities. The signal to watch is CDSCO regulatory alignment progress in India, which would validate capital deployment into Ahmedabad and Chennai manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstock | Captive organosilicon supply reduces exposure to Chinese freight volatility and German precursor pricing. |
| ISO 10993-18 Pre-Validation Investment | Established extractables dossiers compress OEM qualification timelines by 12-18 months under FDA guidance. |
| Cleanroom-as-a-Service Expansion | Toll compounding models lower capital barriers for mid-size innovators entering implantable device segments. |
| EU MDR Technical Documentation Buildout | Enhanced clinical evidence capabilities secure Class IIa and higher device supply contracts. |
| Hydrogenated Nitrile Qualification Programs | Fluoroelastomer substitution readiness addresses REACH restriction risks in surgical seal applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers at Minnesota and Massachusetts device clusters, procurement managers at German hospital GPOs, regulatory affairs leads at compounders holding FDA master files, and technical directors at ISO 13485-certified toll manufacturers. Secondary validation drew from FDA 510(k) submission databases, EU MDR technical documentation repositories, CDSCO registration filings, and customs trade data on organosilicon precursor flows. Bottom-up segmentation modeling across product type, application, and delivery mode was cross-checked against top-down chemical industry capacity assessments.
Calibration against historical qualification timeline data and sterilization validation cost structures anchored the analytical framework across the analysis window. Segmentation dimensions included elastomer chemistry type, device application class, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated EU MDR implementation pacing and NMPA harmonization milestones in China.
Macroeconomic conditions sit as an overlay; deviation in freight rates for organosilicon precursors or euro-dollar exchange volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timelines and sterilization technology adoption curves. Material shifts in EU REACH restriction scope or FDA ISO 10993-1 guidance updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Filter Needles Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Face Mask Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Endoscope Protective Barrier Covers Market