
 Global Automated Blood Tube Labeler and Specimen Transport Box Market | 2026-2036
Global Automated Blood Tube Labeler and Specimen Transport Box Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Blood Tube Labeler and Specimen Transport Box Market Intelligence
Market Context
Germany's precision manufacturing base is reshaping supply dynamics for automated blood tube labelers across European diagnostic networks. Siemens Healthineers leverages its embedded automation portfolio to dominate integrated lab workflow contracts. BD Becton Dickinson and Company anchors North American hospital procurement through its extensive specimen management ecosystem. Thermo Fisher Scientific competes on R&D intensity, extending its informatics-linked labeling platforms into biobanking applications.
Technical Definition and Segment Structure
Automated blood tube labelers and specimen transport boxes comprise electromechanical systems that apply patient-specific identifiers to evacuated collection tubes and engineered containers that maintain chain-of-custody integrity during clinical logistics. These systems integrate thermal transfer or laser printing modules with barcode verification sensors to eliminate manual transcription errors in high-throughput phlebotomy and laboratory receiving workflows. Automated labeling machines command the largest installed base among product types, though RFID-enabled transport boxes capture premium pricing through real-time temperature and location telemetry. Clinical laboratories represent the most mature application segment, while biotechnology firms emerge as the fastest-growing end user category driven by cell therapy manufacturing traceability requirements.
Regulatory Framework and Outlook
FDA Unique Device Identification rules, EU MDR CE marking requirements, and Japan's PMDA quality management standards collectively mandate machine-readable label durability and audit trail documentation across the product lifecycle. These frameworks elevate compliance costs for entry-level equipment while creating specification advantages for vendors with pre-validated software stacks. Stakeholders must monitor evolving harmonization between FDA barcode label standards and EU FMD serialization protocols to anticipate cross-border procurement specifications.
Market Dynamics
Pre-analytical error reduction mandates are forcing hospital laboratories to consolidate specimen handling workflows around integrated automation platforms, compressing procurement cycles from multi-vendor evaluations to single-source integrated contracts.
Growth Catalysts
- FDA Unique Device Identification:The FDA's UDI requirements mandate machine-readable label durability across the product lifecycle, creating specification pull for vendors with pre-validated software stacks in US hospital networks.
- Cell therapy manufacturing:Biotechnology firms expanding cell therapy production require specimen transport boxes with real-time chain-of-custody telemetry, opening premium-priced demand beyond clinical laboratory applications.
- Germany:Siemens Healthineers leverages its embedded automation portfolio to dominate integrated lab workflow contracts across German diagnostic networks, concentrating procurement authority among capital-rich integrated delivery networks.
Market Restraints
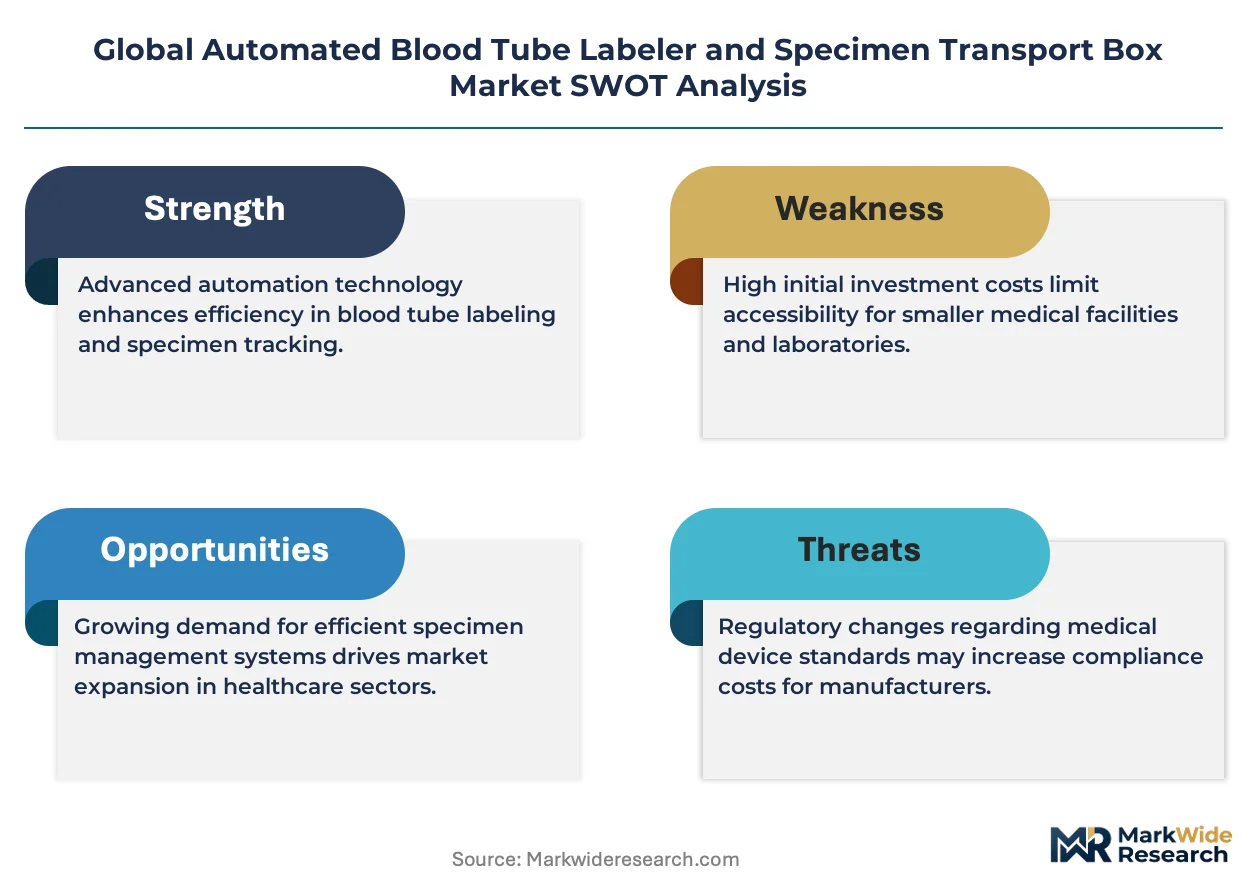
- EU MDR compliance costs:CE marking requirements for automated labeling systems elevate validation expenses, creating specification advantages for incumbent vendors while raising barriers for entry-level equipment manufacturers.
- Precision component supply:Thermal transfer printheads and RFID sensor modules concentrate among Japanese and German component suppliers, exposing lead time vulnerabilities for non-integrated labeler assemblers.
- Laser marking substitution:Direct tube laser etching technologies threaten thermal transfer label demand in high-volume reference laboratories seeking permanent identifier durability.
Strategic Opportunities
- Japan biobanking expansion:METI-funded precision medicine initiatives are driving specimen repository construction, creating demand for RFID-enabled transport boxes with cryogenic temperature telemetry in Tokyo and Osaka research clusters.
- EU FMD serialization harmonization:Evolving alignment between FDA barcode standards and EU pharmaceutical serialization protocols creates cross-border procurement specification advantages for vendors with dual-validated platforms.
- Cloud-native middleware:Convergence of laboratory information systems with IoT-enabled transport box telemetry is collapsing integration timelines for distributed diagnostic networks seeking centralized specimen tracking.
Industry Challenges
- Mechatronics engineering scarcity:Design of electromechanical labeling modules with barcode verification sensors requires specialized motion control and optical engineering talent concentrated among German and Japanese industrial automation firms.
- Legacy LIS integration:Hospital laboratories operate heterogeneous middleware environments, forcing transport box vendors to maintain multiple API certification pathways and extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Blood Tube Labeler and Specimen Transport Box Market |
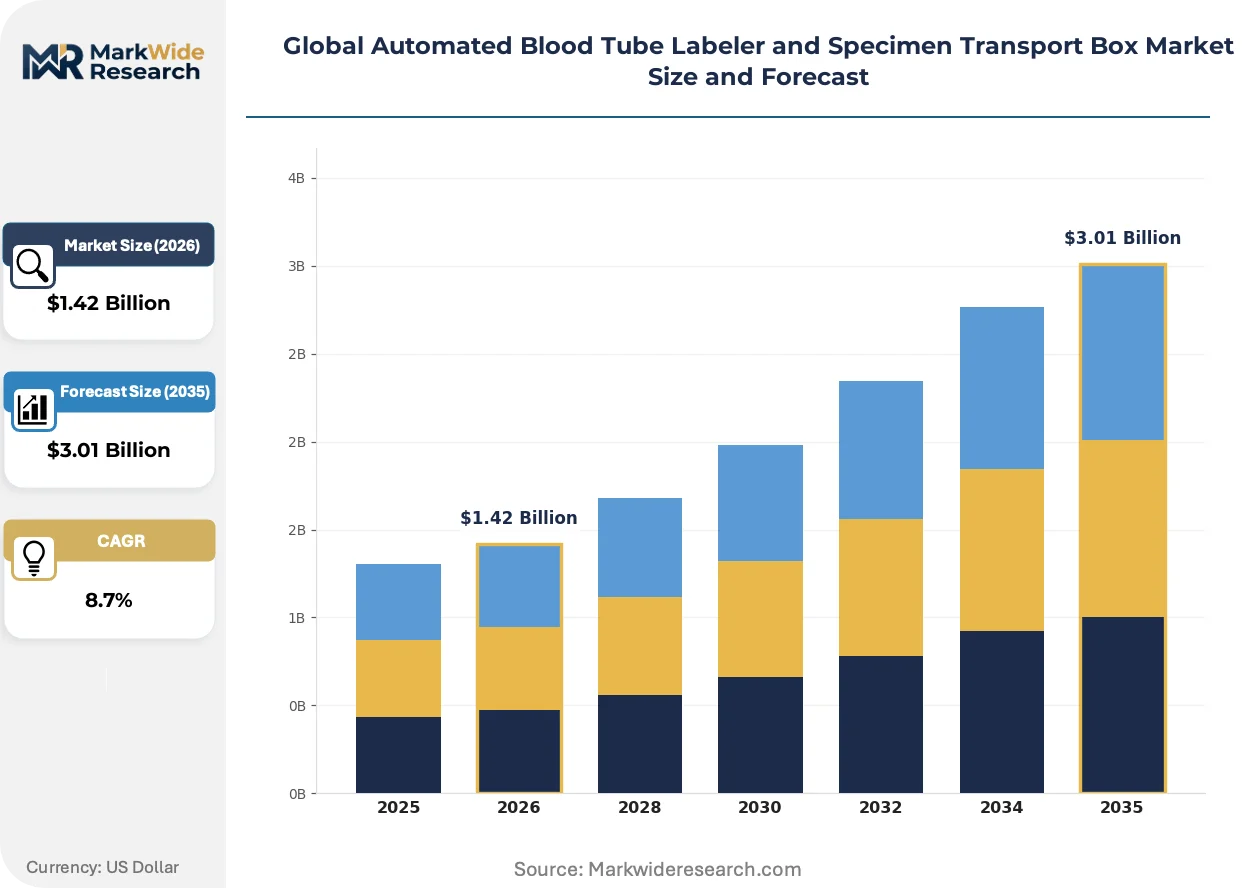
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Labeling Machines, Specimen Transport Boxes, Barcode Scanners, Adhesive Labels Technology: RFID, QR Code, 2D Barcode, Infrared Tracking, NFC Application: Clinical Laboratories, Diagnostic Centers, Research Institutes, Blood Banks, Pharmacies End User: Hospital Labs, Independent Testing Facilities, Academic Research Labs, Biotechnology Firms |
| Companies Covered | Siemens Healthineers, Inpeco, BD Becton Dickinson and Company, Kobayashi Create, Sonoco Products Company, Abbott Laboratories, Techno Medica, Greiner Holding, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Blood Tube Labeler and Specimen Transport Box Market Strategic Shifts & Innovations
Specimen handling automation is converging around three vectors: hardware miniaturization for point-of-care deployment, regulatory-driven label durability specifications, and procurement consolidation favoring integrated workflow vendors over point solution providers.
RFID-enabled transport boxes with embedded temperature and location sensors are collapsing the distinction between passive shipping containers and active monitoring systems. Cell therapy manufacturers and biobanking operations in the United States and Germany are adopting these platforms at accelerated procurement cycles. The structural consequence is compressing pricing power for conventional passive transport box suppliers unable to offer real-time telemetry integration.
EU MDR CE marking requirements for automated labeling systems mandate audit trail documentation and software lifecycle validation that exceeds prior medical device directive standards. This regulatory elevation disproportionately affects mid-tier equipment vendors lacking dedicated regulatory affairs functions. German and Swiss manufacturers with established quality management systems are capturing specification advantages in European diagnostic network tenders.
Hospital procurement committees are consolidating vendor relationships around single-source integrated contracts spanning labelers, transport boxes, and middleware connectivity. This behavioral shift displaces point solution purchasing that characterized 2010s laboratory capital allocation. The pattern is most visible in United States health system consolidation, where centralized supply chain functions negotiate multi-site automation rollouts with preferred vendors.
Global Automated Blood Tube Labeler and Specimen Transport Box Market Segmentation
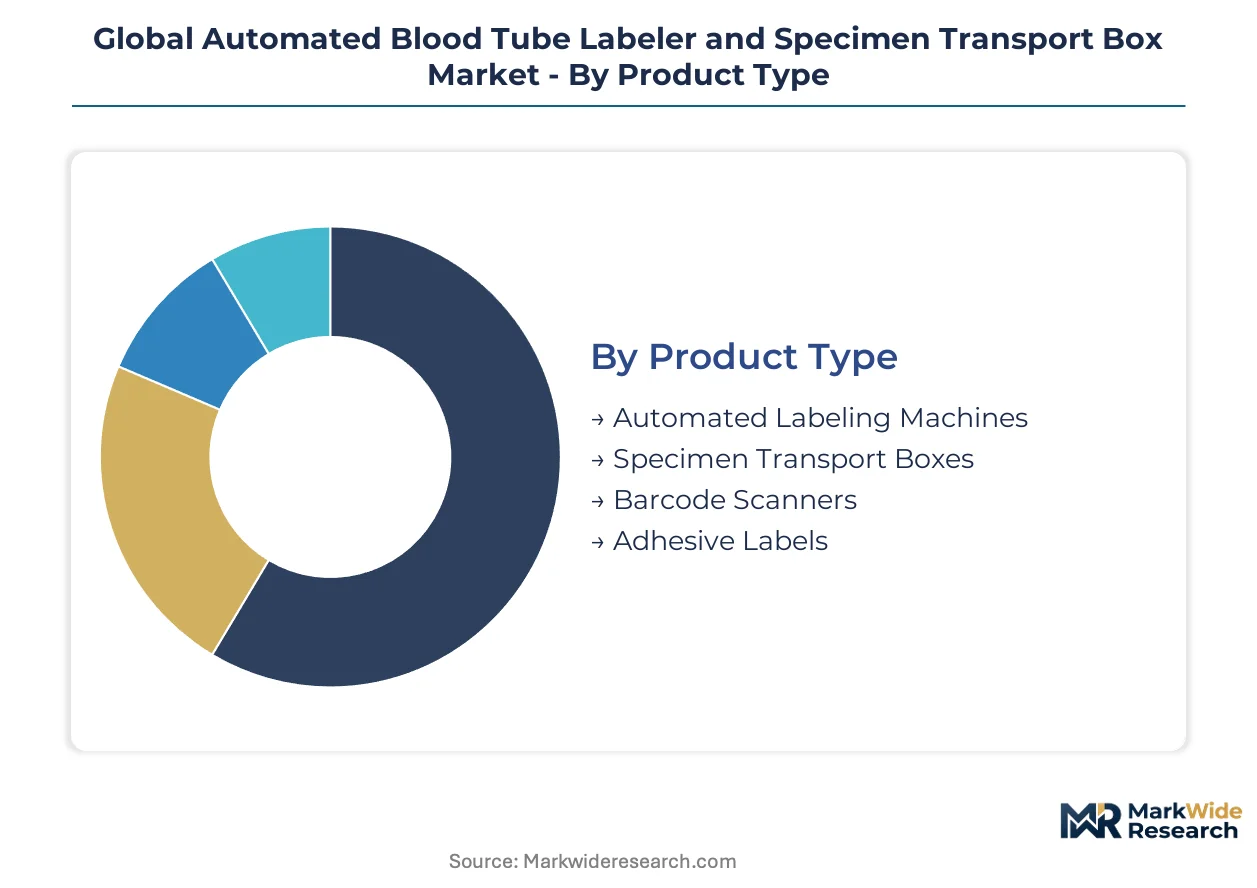
Segmentation in automated blood tube labeling and specimen transport reveals distinct procurement rhythms across product categories. Equipment with embedded software validation cycles moves through hospital capital committees slower than consumables with standardized specifications.
Product Type:
Replacement cycles stretch from months for adhesive labels to years for electromechanical labelers, creating divergent revenue recognition patterns across vendor portfolios.
- Automated Labeling Machines:Electromechanical systems integrate thermal transfer or laser printing modules with barcode verification sensors. Hospital laboratories in the United States and Germany are consolidating procurement around these capital-intensive units to satisfy FDA UDI and EU MDR traceability mandates.
- Specimen Transport Boxes:Engineered containers maintain chain-of-custody integrity through temperature-stable materials and tamper-evident seals. Biotechnology firms expanding cell therapy manufacturing in Germany and Japan are driving premium demand for RFID-enabled variants with real-time telemetry.
- Barcode Scanners:Handheld and fixed-mount optical readers verify label integrity at collection and receiving points.
- Adhesive Labels:Thermal transfer substrates with machine-readable symbologies represent the highest-turnover segment with recurring revenue profiles.
Automated labeling machines dominate installed base. Specimen transport boxes with embedded sensors are where expansion concentrates.
Technology:
Implementation complexity separates technologies requiring infrastructure investment from those deployable through software updates alone.
- RFID:Passive and active radio-frequency identification enables non-line-of-sight tracking with encrypted data payloads. Biobanking operations in Tokyo and Osaka research clusters are adopting cryogenic-tolerant RFID tags under METI-funded precision medicine initiatives.
- QR Code:Two-dimensional matrix symbologies store larger data payloads than linear barcodes. Diagnostic networks in Germany favor QR implementations for their compatibility with existing smartphone-based verification workflows.
- 2D Barcode:Data Matrix and PDF417 formats support FDA UDI and EU FMD serialization requirements with compact footprint.
- Infrared Tracking:Optical beacon systems provide short-range location verification within laboratory facilities.
- NFC:Near-field communication supports tap-to-verify authentication at point-of-care settings.
2D barcode maintains broadest compatibility across legacy infrastructure. RFID is climbing the fastest as real-time telemetry becomes standard in cell therapy logistics.
Application:
Regulatory stringency varies sharply across settings, with GMP-manufacturing environments imposing validation burdens absent in routine diagnostic workflows.
- Clinical Laboratories:High-throughput hospital and reference labs process thousands of specimens daily with zero-tolerance for pre-analytical errors. Siemens Healthineers dominates integrated workflow contracts across German diagnostic networks through embedded automation portfolios.
- Diagnostic Centers:Outpatient and community-based testing facilities prioritize compact footprint and rapid implementation timelines.
- Research Institutes:Academic and government laboratories emphasize flexibility for protocol variation over standardization.
- Blood Banks:Donor traceability requirements mandate permanent identifier durability through temperature extremes and processing steps.
- Pharmacies:Retail and hospital pharmacy settings apply labeling automation to medication compounding and clinical trial specimen collection.
Clinical laboratories anchor volume demand. Biotechnology applications are gaining share fastest as cell therapy manufacturing scales.
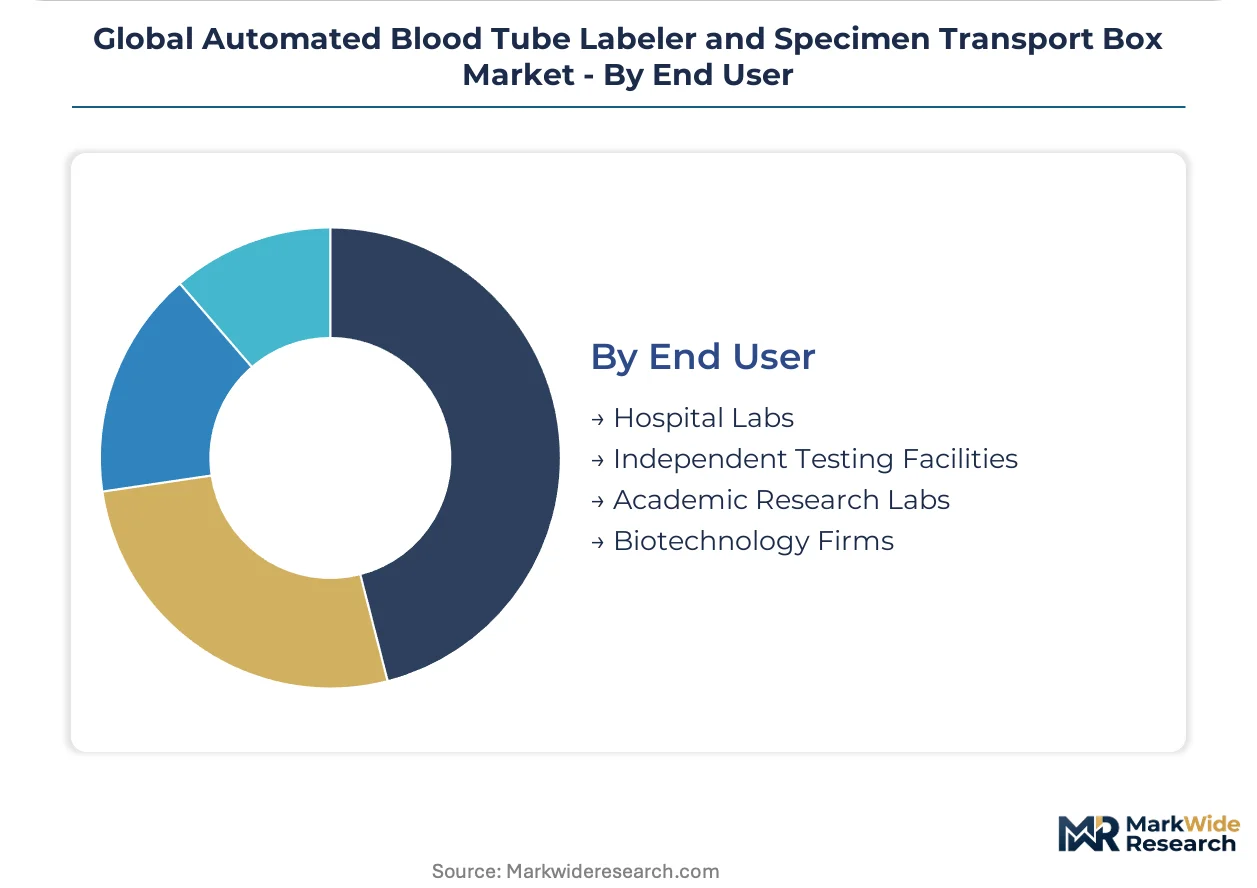
End User:
Capital availability and procurement authority concentration determine whether sales cycles run through centralized supply chain functions or individual laboratory managers.
- Hospital Labs:Integrated delivery networks in the United States negotiate multi-site automation rollouts with preferred vendors, compressing point-solution purchasing. BD Becton Dickinson anchors North American procurement through extensive specimen management ecosystems.
- Independent Testing Facilities:Commercial reference laboratories balance automation investment against throughput guarantees from health system contracts.
- Academic Research Labs:Grant-funded operations face capital constraints that favor modular, upgradeable platforms over integrated systems.
- Biotechnology Firms:Cell therapy and gene therapy manufacturers require specimen transport boxes with audit trail documentation exceeding clinical laboratory standards. Thermo Fisher Scientific extends informatics-linked labeling platforms into these biobanking applications.
Hospital labs command largest capital allocation. Biotechnology firms show steepest expansion trajectory as advanced therapy manufacturing infrastructure builds out.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Unique Device Identification rules anchor United States procurement specifications, while EU MDR compliance costs and Japan's PMDA quality mandates shape investment patterns across diagnostic networks. Siemens Healthineers leverages its embedded automation portfolio to dominate integrated lab workflow contracts.
United States
Hospital laboratories consolidate specimen handling workflows around integrated automation platforms to satisfy FDA UDI traceability mandates. The FDA's barcode label standards require machine-readable durability across product lifecycles. BD Becton Dickinson anchors North American procurement through extensive specimen management ecosystems concentrated in New Jersey and North Carolina research corridors.
Germany
Centralized lab networks drive capital investment in specimen handling infrastructure across Bavarian and Baden-Württemberg diagnostic clusters. EU MDR CE marking requirements elevate validation expenses for automated labeling systems. Siemens Healthineers dominates integrated workflow contracts through precision manufacturing capabilities embedded in Erlangen and Munich automation portfolios.
Japan
METI-funded precision medicine initiatives accelerate specimen repository construction in Tokyo and Osaka research clusters. PMDA quality management standards mandate audit trail documentation for automated blood tube labelers. Kobayashi Create and Techno Medica occupy positions within domestic supply chains serving Kanto and Kansai biobanking operations.
China
NMPA medical device registration requirements tighten traceability specifications for imported automated labeling equipment. Domestic diagnostic networks expand automation procurement to reduce pre-analytical errors in high-throughput hospital laboratories. Yangtze River Delta and Pearl River Delta manufacturing bases concentrate electromechanical component assembly for regional labeler vendors.
Switzerland
Swissmedic quality management systems create specification advantages for manufacturers with pre-validated software stacks in European tenders. Precision component engineering capabilities concentrate around Basel and Zurich industrial automation clusters. Greiner Holding exemplifies the mid-tier equipment segment serving diagnostic networks with established regulatory affairs functions.
Global Automated Blood Tube Labeler and Specimen Transport Box Market Key Industry Players
Capability concentration sits with integrated workflow vendors; scale advantage sits with diversified life science conglomerates. The vendor base organizes around three strategic archetypes: embedded automation specialists, specimen management ecosystem providers, and informatics-linked platform developers. Siemens Healthineers and BD Becton Dickinson exemplify the first two archetypes respectively. Dominant competitive moves include strategic partnerships with laboratory information system vendors and portfolio diversification into biobanking applications.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying R&D intensity and informatics-linked labeling platform extension. Abbott Laboratories represents the diagnostics-anchored archetype with embedded automation capabilities. Specialized mid-tier vendors including Inpeco and Techno Medica sit within regional procurement networks where compliance validation and localized service support determine contract awards. Sonoco Products Company exemplifies the packaging-centric archetype expanding into temperature-telemetry transport box solutions.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Inpeco |
| BD Becton Dickinson and Company |
| Kobayashi Create |
| Sonoco Products Company |
| Abbott Laboratories |
| Techno Medica |
| Greiner Holding |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Japanese thermal transfer printhead manufacturers determines both three-tier pricing spreads across premium RFID-enabled and economy thermal-transfer equipment and supply chain vulnerability to lead time disruptions in German and US diagnostic network procurement.
Pricing Analysis
German hospital systems command 15-25% premiums over US independent labs for equivalent automated labeling machines due to bundled EU MDR validation services. Pricing stratifies across premium, standard, and economy tiers driven by software validation depth and after-sales service bundling. Cost compression in mid-tier thermal transfer equipment is intensifying as Chinese labeler vendors enter European tenders without pre-validated quality management systems. Independent testing facilities exhibit highest price sensitivity; biotechnology firms show lowest sensitivity due to GMP compliance requirements.
Supply Chain Analysis
Foxconn and Jabil hold contract manufacturing capacity for electromechanical labeler assembly serving Siemens Healthineers and BD Becton Dickinson. Precision component engineering concentrates in Japan, Germany, and Switzerland for RFID sensor modules and optical verification systems. Raw material dependencies span rare-earth magnets for motor assemblies, specialized thermal transfer ribbons, and cryogenic-grade polymers for transport box insulation. Single-source vulnerability in Japanese printhead supply exposes non-integrated assemblers to allocation risk during demand surges. Distribution runs through GPO contracts in US hospital networks and direct OEM relationships in German diagnostic clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as cell therapy manufacturing demands outpace standardized clinical laboratory equipment, opening niches for specialized vendors with GMP-validated platforms.
For Market Incumbents: Build regulatory validation moats through pre-certified software stacks that compress competitor implementation timelines. Deepen backward integration into thermal transfer printhead supply through captive production partnerships with Japanese component specialists. Defend against laser marking substitution by embedding permanent-identifier durability guarantees into service contracts. Prioritize R&D in cryogenic-tolerant RFID telemetry for biobanking applications. For New Entrants and Emerging Players: Pursue white-space positioning in cloud-native middleware for distributed diagnostic networks lacking centralized LIS integration. Target Japan's METI-funded biobanking construction with RFID-enabled transport boxes featuring temperature telemetry. Penetrate academic research labs through modular upgradeable platforms that bypass capital committee procurement cycles. Lead go-to-market with API-first connectivity that collapses legacy system integration timelines. For Investors and Strategic Acquirers: Mid-tier European equipment vendors with established CE marking pathways and embedded quality management systems represent attractive consolidation targets. Long-term viability rests on exposure to cell therapy manufacturing infrastructure buildout rather than mature clinical laboratory replacement cycles. Monitor FDA-EU FMD serialization harmonization progress as inflection signal for cross-border procurement specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Pre-validated software stacks accelerate hospital procurement cycles in EU MDR-regulated tenders. |
| RFID Telemetry Platform Launch | Real-time chain-of-custody documentation captures premium pricing from cell therapy manufacturers. |
| Hospital System Partnership | Integrated workflow contracts with US health systems displace point-solution vendors. |
| Software Companion Development | Cloud-native middleware collapses LIS integration timelines for distributed diagnostic networks. |
| Backward Integration into Printheads | Captive supply of Japanese thermal transfer components insulates against allocation risk. |
Research Approach
Cross-validation between primary interviews with hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists and secondary sources including FDA 510(k) filings, EU MDR notified body databases, and hospital procurement records anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across product type, technology, application, and end user dimensions.
Calibration against historical capital expenditure patterns in US, German, and Japanese diagnostic networks shapes the analytical framework across the projection horizon. Segmentation modeling spans automated labeling machines, specimen transport boxes, barcode scanners, and adhesive labels by technology tier, regulatory validation depth, and geographic adoption pattern. CAGRs derive from equipment replacement cycle analysis and biotechnology infrastructure buildout trajectories. Industry-specific inputs include pre-analytical error reduction mandates and cell therapy manufacturing traceability requirements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese labeler vendors with price-disruptive thermal transfer equipment would shift outcomes. Quarterly review of FDA-EU serialization harmonization progress, METI biobanking funding allocations, and thermal transfer printhead supplier allocation policies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Suture Tapes Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Medical Bags Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market