
 US Dental Splint Market | 2026-2036
US Dental Splint Market Size, Share, and Industry Trends Forecast 2026-2036
US Dental Splint Market Intelligence
Oral surgery practices is expanding utilization of dental splints for post-operative jaw stabilization and temporomandibular joint recovery protocols. Danaher Corporation leverages its diagnostic-imaging-to-consumables portfolio to anchor dental workflow integration. Dentsply Sirona sustains broad channel control across chairside and laboratory splint fabrication systems. Henry Schein, Inc. competes through distribution scale that reaches independent dental clinics in secondary US markets.
A dental splint is a removable or fixed intraoral device fabricated from thermoplastic, acrylic, or elastomeric materials that mechanically stabilizes dentition, redistributes occlusal forces, or maintains jaw positioning. These devices typically range from 1.5 mm to 5 mm in thickness and are produced through vacuum forming, pressure molding, or CAD/CAM milling processes to achieve patient-specific fit. Thermoplastic splints lead product type demand due to chairside adaptability and lower laboratory turnaround, while soft splints capture growth in chronic pain management applications where patient compliance depends on wear comfort. Occlusal splints for teeth grinding occupy the largest application segment by volume, though temporomandibular joint disorder applications command premium pricing due to specialist involvement and custom fabrication requirements.
FDA Center for Devices and Radiological Health classifies dental splints as Class II medical devices requiring 510(k) premarket notification, while OSHA bloodborne pathogen standards govern in-office fabrication protocols. State dental boards in California, New York, and Texas impose continuing education requirements for splint-fitting procedures that filter practitioner participation. Stakeholders must monitor evolving digital dentistry reimbursement codes and state-level scope-of-practice debates that could shift splint provision between dentists, orthodontists, and emerging teledental platforms.
Market Dynamics
Digital dentistry workflows are compressing fabrication timelines and redistributing value from dental laboratories toward chairside production, fundamentally restructuring how splints reach patients.
Growth Catalysts
- Post-operative oral surgery protocols:Oral surgery practices across California, Texas, and Florida are expanding splint utilization for jaw stabilization following temporomandibular joint procedures.
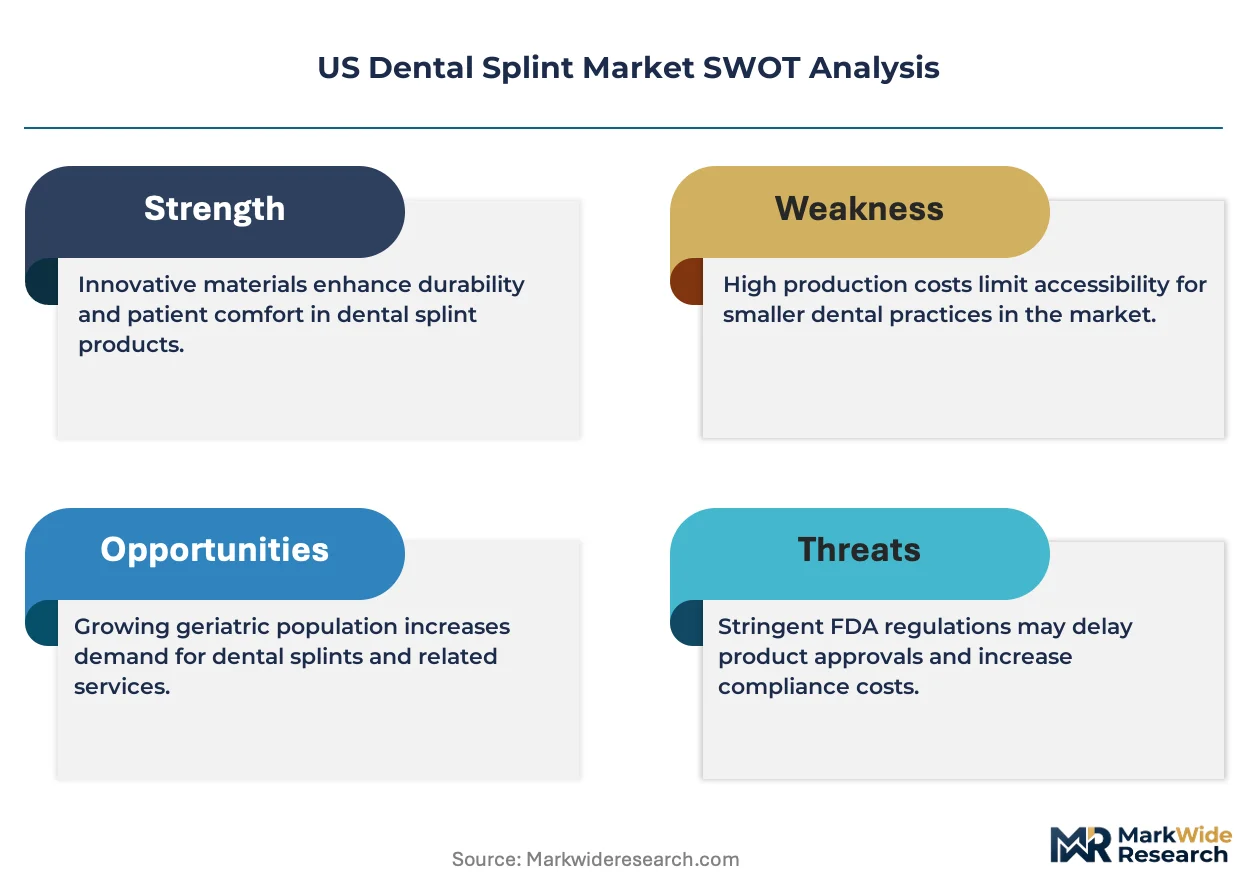
- FDA 510(k) pathway clarity:The FDA Center for Devices and Radiological Health maintains predictable Class II medical device classification that reduces premarket notification uncertainty for manufacturers.
- Thermoplastic chairside adaptability:Vacuum forming and pressure molding technologies enable same-day splint delivery that eliminates laboratory turnaround delays.
Market Restraints
- Acrylic resin cost volatility:Petroleum-derived monomer feedstock prices fluctuate with crude oil markets, squeezing margins on traditional splint materials.
- Laboratory concentration in coastal states:CAD/CAM milling capacity clusters in California and New York, creating geographic supply bottlenecks for interior practices.
- OSHA bloodborne pathogen compliance:In-office fabrication protocols impose sterilization infrastructure requirements that limit small clinic participation.
Strategic Opportunities
- Teledental platform integration:Remote impression capture and digital prescription workflows are opening splint provision to patients in rural Texas and Florida counties with limited TMJ specialist access.
- Soft elastomeric chronic pain applications:Medicare Advantage plans in select states are piloting reimbursement for medically necessary TMJ splints, expanding addressable demand beyond cosmetic grinding guards.
- State-level scope-of-practice expansion:Dental board deliberations in emerging markets may authorize hygienist-fitted provisional splints, broadening the practitioner base.
Industry Challenges
- CAD/CAM technician certification timelines:State dental boards in California, New York, and Texas mandate continuing education hours for digital splint-fitting that constrain workforce scaling.
- Legacy practice management system integration:Older electronic health record platforms lack digital dentistry reimbursement code compatibility, forcing manual claims processing.
- Reimbursement code fragmentation:Divergent CDT code interpretation across commercial payers creates administrative burden and payment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dental Splint Market |
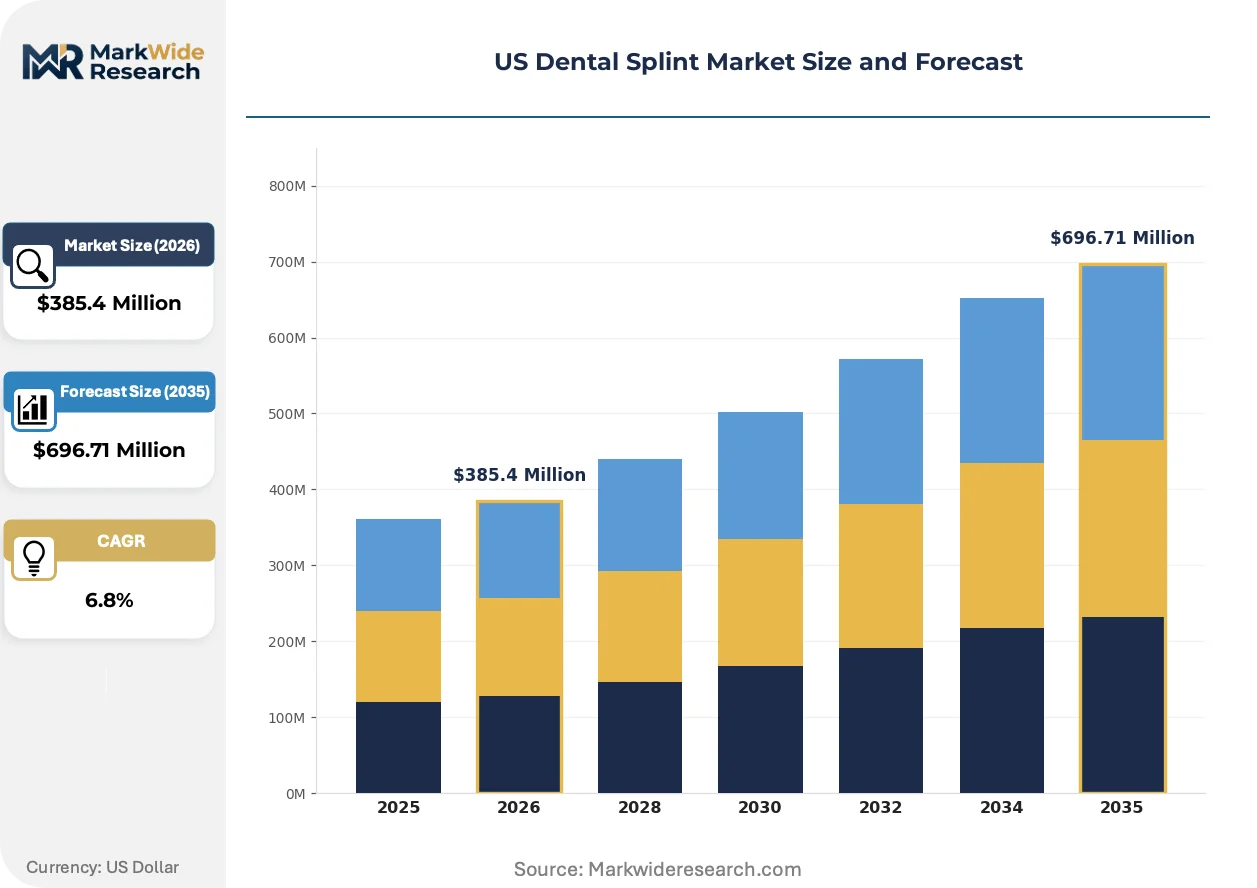
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Splints, Hard Acrylic Splints, Soft Splints, Occlusal Splints End User: Dentists, Orthodontists, Oral Surgeons, Dental Clinics Application: Teeth Grinding, Temporomandibular Joint Disorders, Post-Surgical Recovery, Chronic Pain Management Material: Polycarbonate, Acrylic, Polyurethane, Thermoplastic Elastomers |
| Companies Covered | Danaher Corporation, Dentsply Sirona, Ultradent Products Inc., Septodont Holding, Henry Schein, Inc., Benco Dental Supply Company, Brasseler USA, 3D Systems, Inc., Aqualizer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dental Splint Market Strategic Shifts & Innovations
Workflow digitization is collapsing the traditional laboratory-dentist-patient chain into integrated chairside production systems that compress delivery from weeks to hours.
Intraoral scanning hardware paired with chairside milling units is modularizing the splint production process. General dentistry practices in high-volume Texas markets are adopting these systems at accelerating rates to capture laboratory margin. This technology stack is modularizing the value chain by enabling practices to internalize design, fabrication, and fitting within a single appointment.
FDA digital dentistry guidance documents are clarifying software-as-a-medical-device boundaries for CAD/CAM design tools. Manufacturers must now validate algorithm-generated occlusal surfaces through clinical performance data rather than predicate device equivalence. Splint-specific 510(k) submissions are most affected in California and Florida where digital adoption rates outpace regulatory template updates.
Patient-driven aesthetic preferences are compressing switching cycles for occlusal guards. Consumers in Florida's retiree corridors and California's metropolitan markets are replacing thermoplastic devices annually rather than biennially, prioritizing clarity and stain resistance over durability. This pattern is most visible in cash-pay cosmetic applications where insurance reimbursement constraints do not apply.
US Dental Splint Market Segmentation
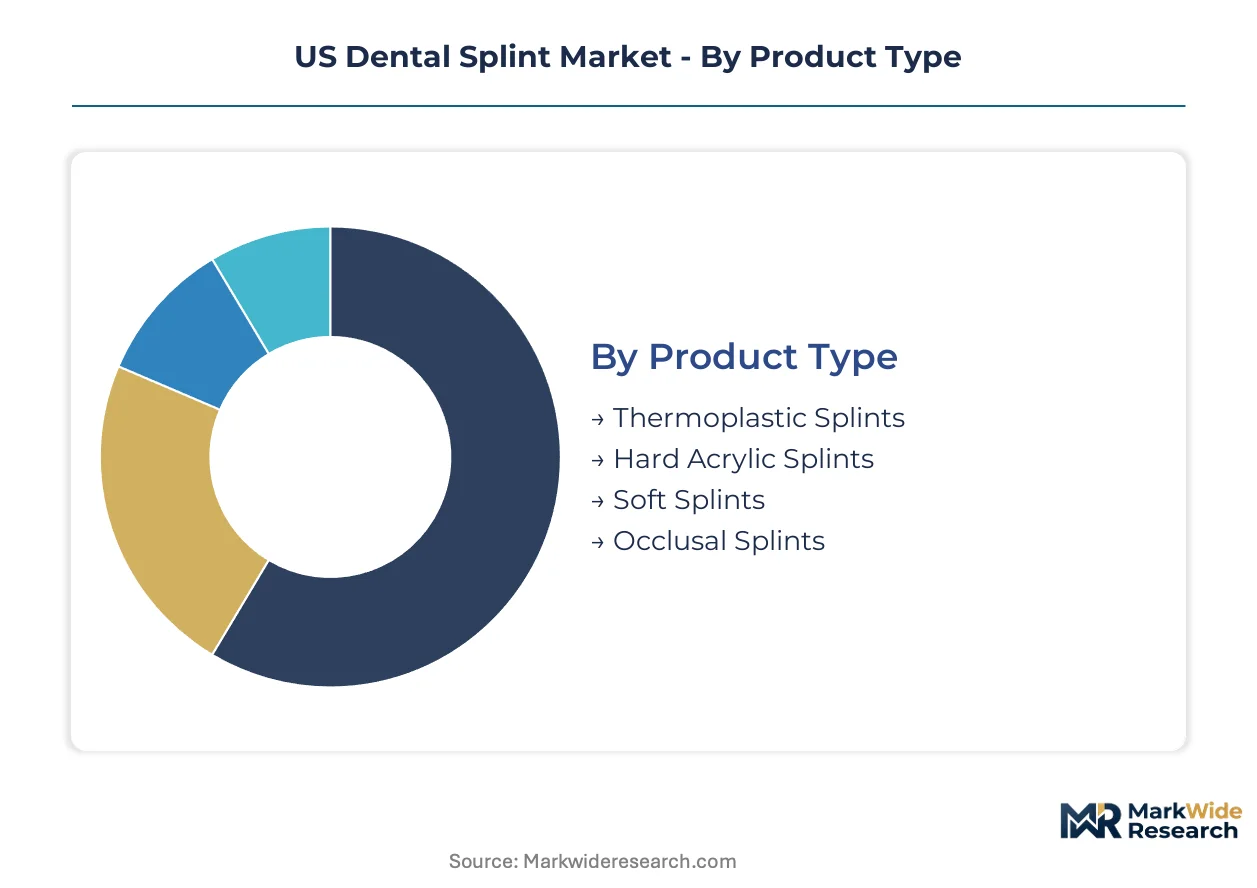
Dental splint procurement decisions hinge on material certification pathways, practitioner scope-of-practice boundaries, and reimbursement code eligibility. Segmentation reveals how FDA Class II device requirements and state dental board regulations filter market access across product categories and end-user channels.
Product Type:
FDA 510(k) premarket notification requirements vary by material rigidity and intended therapeutic claim, with thermoplastic devices facing streamlined review compared to custom-fabricated occlusal appliances.
- Thermoplastic Splints:Vacuum-formed or pressure-molded devices fabricated from ethylene-vinyl acetate copolymers achieve 1.5-3 mm thickness with chairside adaptability. Demand concentrates in high-volume Texas dental clinics where same-day delivery eliminates laboratory coordination costs and patient return visits.
- Occlusal Splints:Precision-milled or hand-articulated appliances designed to redistribute masticatory forces across full dental arches require predicate device equivalence demonstrations in 510(k) submissions. California TMJ specialists command premium pricing for these custom fabrications due to specialist credentialing requirements and extended fitting protocols.
- Hard Acrylic Splints:Methyl methacrylate-based devices fabricated through cold-cure or heat-cure polymerization offer durability for extended wear cycles.
- Soft Splints:Elastomeric formulations prioritize patient compliance in chronic pain applications where tissue tolerance exceeds mechanical precision requirements.
Thermoplastic Splints sits at the top of the volume ranking, with Soft Splints climbing the fastest.
End User:
State scope-of-practice regulations determine which practitioners may prescribe, fit, and adjust splint devices, creating channel-specific demand patterns across the US.
- Dentists:General practitioners in Florida's retiree corridors generate substantial volume for grinding guard applications, with cash-pay cosmetic demand driving annual replacement cycles independent of insurance reimbursement constraints.
- Oral Surgeons:Post-operative stabilization protocols following temporomandibular joint arthroscopy or orthognathic procedures require rigid fixation splints with documented occlusal relationships. Texas and California academic medical centers anchor demand for these specialized fabrications.
- Orthodontists:Retention-phase appliances and deprogramming splints integrate with comprehensive treatment planning.
- Dental Clinics:Federally qualified health centers and community health clinics in rural Florida counties access splint provision through teledental referral networks.
Dentists captures the largest prescription volume, while Oral Surgeons deliver the highest revenue per procedure.
Application:
Medicare Advantage pilot programs and commercial payer policy variations segment addressable demand by medical necessity determination criteria.
- Teeth Grinding:Bruxism appliances represent the highest-volume application segment, with over-the-counter alternatives competing at the economy tier while dentist-dispensed devices capture compliance-monitored segments.
- Temporomandibular Joint Disorders:Medically necessary splint therapy for internal derangement or myofascial pain dysfunction commands prior authorization requirements and specialist referral protocols that constrain volume but expand per-unit pricing.
- Post-Surgical Recovery:Maxillofacial surgery practices utilize rigid splint fixation following orthognathic procedures or condylar fracture repair.
- Chronic Pain Management:Multidisciplinary pain clinics in California integrate splint therapy with physical medicine modalities for refractory orofacial pain syndromes.
Teeth Grinding dominates unit shipments, with Temporomandibular Joint Disorders expanding most quickly.
Material:
Feedstock cost volatility and biocompatibility testing requirements differentiate margin profiles across polymer categories.
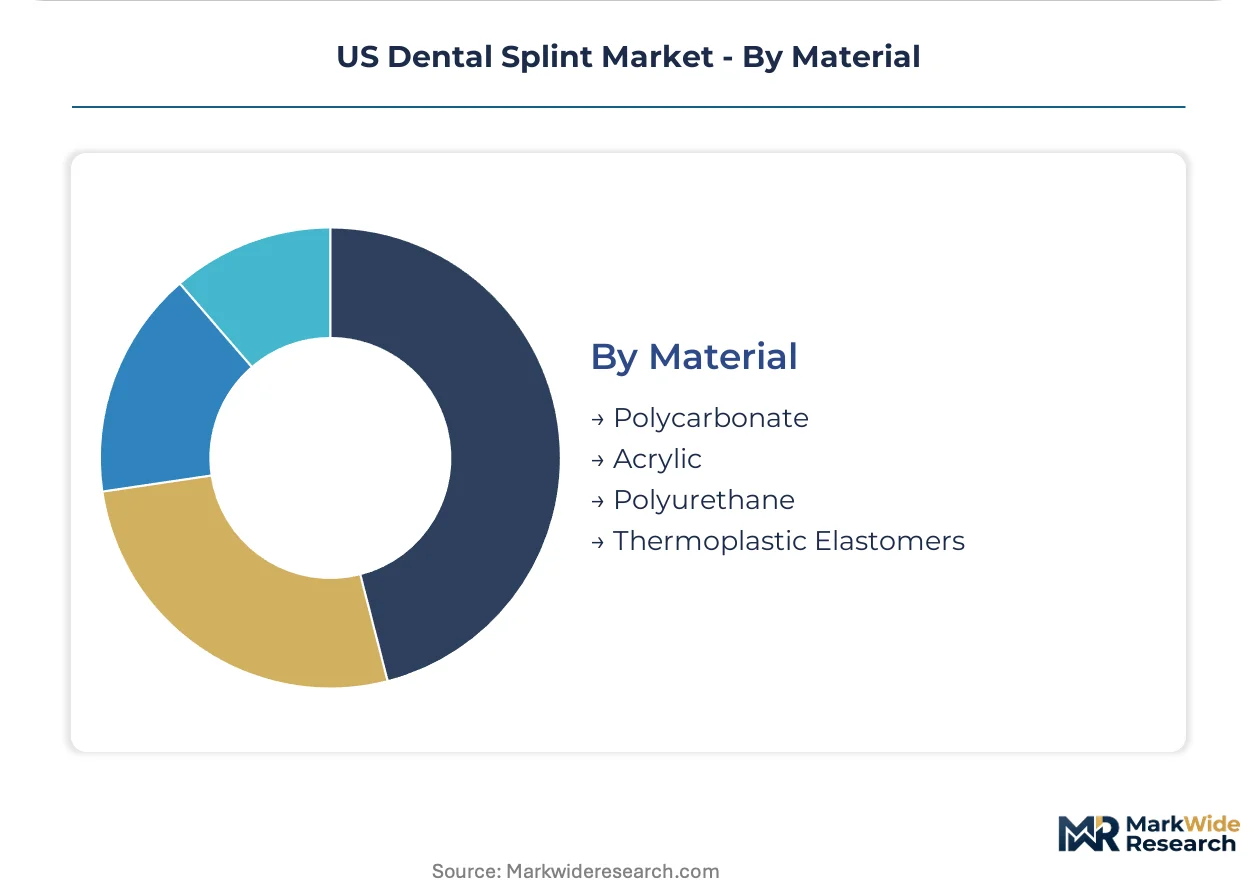
- Acrylic:Methyl methacrylate homopolymers and copolymers provide rigidity for long-term occlusal stability, though petroleum-derived monomer costs fluctuate with crude oil benchmarks.
- Polycarbonate:Bisphenol A-free formulations address patient sensitivity concerns while maintaining optical clarity for aesthetic applications in California metropolitan markets.
- Polyurethane:Thermoset elastomers offer tailored hardness grades for dual-layer splint constructions.
- Thermoplastic Elastomers:Styrenic block copolymers and polyolefin blends enable overmolding and multi-material fabrication techniques.
Acrylic retains the largest installed base, with Thermoplastic Elastomers gaining share fastest in soft splint applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redistributing dental splint production capacity toward states with streamlined laboratory licensing, while patient demand concentrates in metropolitan corridors with TMJ specialist density.
California
Los Angeles and San Francisco anchor the nation's largest cluster of CAD/CAM milling laboratories serving custom occlusal splint fabrication. The California Dental Board mandates continuing education hours for digital splint-fitting that filter practitioner participation. Academic medical centers in San Diego and Stanford drive post-surgical stabilization protocol innovation.
Texas
Dallas-Fort Worth and Houston dental clinics generate the highest thermoplastic splint volume through chairside vacuum forming systems. The Texas State Board of Dental Examiners maintains scope-of-practice boundaries that limit hygienist-fitted provisional splints. Rural counties in West Texas access splint provision through emerging teledental referral networks.
Florida
Retiree corridors in Miami-Dade and Palm Beach counties drive annual replacement cycles for aesthetic occlusal guards. The Florida Board of Dentistry regulates in-office fabrication protocols under OSHA bloodborne pathogen standards. Tampa Bay academic medical centers specialize in temporomandibular joint disorder applications commanding premium pricing.
New York
Manhattan and Long Island dental laboratories concentrate precision-milled hard acrylic splint capacity for the Northeast corridor. The New York State Education Department's Office of the Professions oversees dental laboratory technician certification timelines. Buffalo and Rochester community health clinics pilot Medicare Advantage reimbursement for medically necessary TMJ splints.
Illinois
Chicago metropolitan practices balance laboratory outsourcing with emerging chairside milling adoption for same-day delivery. The Illinois Department of Financial and Professional Regulation governs dental device fabrication facility licensure. Peoria and Springfield oral surgery practices expand splint utilization for post-orthognathic procedure stabilization.
US Dental Splint Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbents extend from diagnostic imaging into consumable workflows. The market structures around three tiers: diversified dental conglomerates with end-to-end workflow control, specialized splint fabricators with regional laboratory density, and emerging digital platform players compressing delivery timelines. Strategic archetypes include workflow integrators capturing laboratory margin through chairside systems, distribution-scale intermediaries reaching independent clinics, and material-science specialists differentiating through biocompatibility certification. M&A activity and technology licensing agreements represent the dominant competitive moves.
Among diversified dental conglomerates, Danaher Corporation and Dentsply Sirona exemplify the workflow integration archetype, anchoring positions across imaging-to-consumables value chains. Henry Schein, Inc. occupies the distribution-scale tier, reaching independent dental clinics in secondary markets through logistics infrastructure. These three entities represent contrasting strategic positions without implying specific market share claims.
| Leading Market Players |
|---|
| Danaher Corporation |
| Dentsply Sirona |
| Ultradent Products Inc. |
| Septodont Holding |
| Henry Schein, Inc. |
| Benco Dental Supply Company |
| Brasseler USA |
| 3D Systems, Inc. |
| Aqualizer |
| Others |
Cost & Logistics Intelligence
Acrylic resin monomer costs fluctuate with crude oil benchmarks, flowing from petroleum feedstock through methyl methacrylate polymerization into three distinct pricing tiers: economy thermoplastic guards, standard chairside-fabricated devices, and premium custom-milled occlusal appliances. Henry Schein's distribution scale captures mid-tier volume, while California laboratory clusters command premium positioning through FDA 510(k) predicate device specialization and extended fitting protocols.
Pricing Analysis
Distributor margin compression defines the mid-market layer, with Henry Schein and Benco Dental Supply Company extracting 15-25 points on laboratory-sourced devices versus 40-50 points on proprietary chairside systems. Pricing stratifies across premium, standard, and economy tiers: premium custom occlusal splints from California CAD/CAM laboratories carry specialist credentialing premiums; standard thermoplastic devices compete on laboratory turnaround speed; economy boil-and-bite alternatives face direct-to-consumer pressure. Pricing pressure stems from petroleum-derived monomer volatility squeezing acrylic splint margins. Cash-pay cosmetic buyers in Florida retiree corridors show lowest price sensitivity, while rural Texas clinics accessing teledental referral networks prioritize cost minimization.
Supply Chain Analysis
CAD/CAM technician certification bottlenecks in California, New York, and Texas constrain milling capacity expansion despite rising chairside demand. Raw material dependencies center on Saudi Arabian and Korean petroleum feedstock for methyl methacrylate monomers, German and Japanese precision milling hardware, and Chinese thermoplastic elastomer sheet stock. Single-source vulnerability concentrates in coastal laboratory clusters where California and New York facilities serve interior practices through extended logistics corridors. Distribution runs through three channels: direct manufacturer-to-clinic for chairside systems, dental distributor intermediaries for laboratory-sourced devices, and emerging teledental platforms connecting rural patients with urban specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US dental splint market rewards geographic arbitrage between high-regulation coastal states with premium pricing power and lower-compliance interior markets with volume scalability. Texas and Florida offer cost-advantaged entry points where state dental board continuing education requirements remain less stringent than California's digital splint-fitting mandates.
For Market Incumbents: Cement laboratory margin defense by acquiring chairside milling technology specialists before digital workflows fully disintermediate traditional fabrication. Danaher Corporation and Dentsply Sirona should prioritize backward integration into thermoplastic elastomer sheet manufacturing to offset petroleum feedstock volatility. Lock in exclusive distribution with Florida retiree corridor clinic chains where annual replacement cycles generate predictable recurring revenue.
For New Entrants and Emerging Players: Enter via teledental platform partnerships targeting rural Texas and Florida counties with limited TMJ specialist density. White-space opportunity concentrates in Medicare Advantage reimbursement navigation for medically necessary TMJ splints, where prior authorization complexity deters generalist competitors. Position through soft elastomeric chronic pain applications where patient compliance requirements favor comfort-focused formulations over precision-milled alternatives.
For Investors and Strategic Acquirers: Consolidation pressure builds where state scope-of-practice expansion authorizes hygienist-fitted provisional splints, compressing the addressable market for traditional dentist-dispensed devices. Long-term viability favors targets with digital workflow integration capabilities spanning intraoral scanning through chairside fabrication. Watch FDA software-as-a-medical-device guidance evolution as the inflection signal: algorithm-validated occlusal surface design tools will separate acquirable technology platforms from stranded laboratory assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Chairside Milling Technology Acquisition | Captures laboratory margin by internalizing splint fabrication within general dentistry practices. |
| Teledental Platform Integration | Extends splint provision to rural Texas and Florida counties lacking TMJ specialist access. |
| Soft Elastomeric Formulation Development | Addresses Medicare Advantage pilot reimbursement for medically necessary chronic pain applications. |
| FDA 510(k) Software Validation Investment | Secures predicate device equivalence for algorithm-generated occlusal surface design tools. |
| State Scope-of-Practice Regulatory Engagement | Positions for hygienist-fitted provisional splint authorization in emerging markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental laboratory technicians, TMJ specialists, oral surgeons, GPO contracts managers, and state dental board administrators with secondary validation against FDA 510(k) premarket notification databases, OSHA bloodborne pathogen compliance records, CDT code interpretation guidelines, and dental distributor financial disclosures. Bottom-up demand modeling from clinic-level procedure volumes triangulated against top-down market sizing from material consumption data.
Segment-weighting approaches distributed value across product type, end user, application, and material dimensions, with particular attention to thermoplastic versus hard acrylic margin profiles and dentist versus oral surgeon prescription patterns. CAGRs derived from procedure volume trends, reimbursement code expansion trajectories, and digital adoption curve penetration rates across the analysis window. Industry-specific inputs included petroleum-derived monomer price indices, state dental board continuing education hour requirements, and CAD/CAM milling capacity utilization surveys.
The model holds under stable FDA Class II device classification and predictable state scope-of-practice boundaries; deviation in Medicare Advantage reimbursement expansion rates or teledental platform regulatory authorization would shift volume projections between laboratory and chairside channels. Material substitution toward bioresorbable polymers or algorithm-validated design tool regulatory reclassification represent additional forecast sensitivities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Aligners Market
Dental Devices
Dental Impression System Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Malocclusion Market
Dental Devices
Global Dental Turbine Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
China Dental Implants Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Lights for Dental Healthcare Market