
 Cork Stoppers Market | 2026-2036
Cork Stoppers Market Size, Share, and Industry Trends Forecast 2026-2036
Cork Stoppers Market Analysis
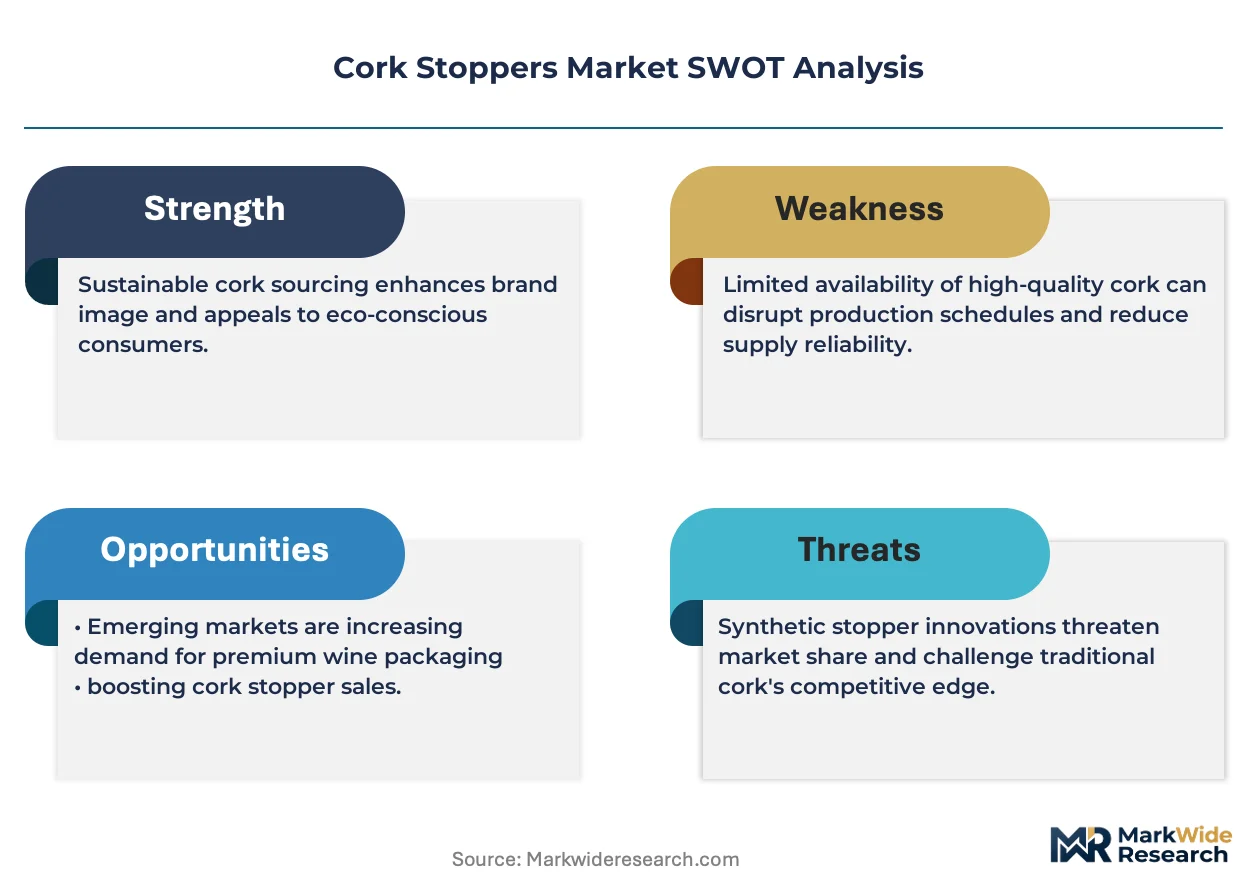
The capital-intensity divergence between automated cork processing lines and traditional hand-finished operations is rotating competitive advantage toward scaled manufacturers. Corticeira Amorim leverages vertical integration from Portuguese cork oak forests through finished stopper production to dominate supply security. Nomacorc anchors its position with synthetic cork technology leadership, competing aggressively on consistency and taint elimination for volume wine segments.
Cork stoppers are cylindrical closure devices machined from the bark of Quercus suber, the cork oak tree, with natural cork segments exhibiting cellular structures containing approximately 40 million air-filled cells per cubic centimeter that provide elastic compression and gas-seal recovery. The primary commercial purpose centers on hermetic sealing of glass containers, particularly wine bottles, where controlled oxygen transmission rates influence product aging and sensory development. Natural cork retains primacy in premium wine bottling applications where closure provenance and ritual extraction sustain brand positioning, while synthetic cork segments capture value in commercial wine tiers prioritizing supply predictability and elimination of 2,4,6-trichloroanisole contamination risk. Composite and agglomerated categories occupy intermediate positions, with agglomerated cork leveraging granulated material recovery to serve fortified wine and spirits segments where cost discipline outweighs natural grain aesthetics.
EU REACH regulations and the F-Gas framework indirectly shape cork stopper demand by constraining synthetic closure alternatives dependent on petroleum-derived feedstocks, while Portuguese forest certification under Forest Stewardship Council protocols governs raw material market access for premium positioning. FDA food-contact substance notifications and EU EFSA migration limits structure compliance requirements for pharmaceutical and beverage packaging applications. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and synthetic material substitution economics to calibrate portfolio allocation between natural and technical cork solutions.
Market Dynamics
EU deforestation-free supply chain regulations are forcing wine closure suppliers to document Portuguese cork oak provenance, compressing procurement timelines and elevating certified forest management from marketing claim to market access requirement.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:The framework accelerates certified cork procurement as wineries face Scope 3 emissions disclosure obligations. Premium bottlers now specify FSC-certified closures to satisfy ESG-linked financing covenants.
- 2,4,6-trichloroanisole elimination demand:Sensory quality failures in high-value wine segments drive investment in gas chromatography screening and alternative oxygen management technologies. Producers reject batch variability that risks brand equity damage.
- Mediterranean wine export concentration:France, Italy, and Spain account for dominant cork stopper offtake as Old World producers defend appellation authenticity against New World synthetic closure competition. Regional bottling traditions embed natural cork as a terroir signal.
Market Restraints
- Cork oak bark supply concentration:Portugal and Spain control over 80% of harvestable Quercus suber forests, creating geopolitical exposure and price volatility during drought cycles that reduce bark yield quality.
- Petroleum-derived synthetic substitution:Injection-molded closures from polyethylene and thermoplastic elastomers compete on unit cost consistency and taint elimination, pressuring natural cork in commercial wine tiers below 10 euro retail.
- REACH chemical compliance burden:ECHA substance restrictions on processing aids and surface treatments increase formulation testing costs for agglomerated and colmated cork categories, disadvantaging smaller processors.
Strategic Opportunities
- Sparkling wine and spirits expansion:Champagne-method producers and premium whiskey distillers represent underpenetrated cork categories where technical agglomerates can displace plastic and metal closures with heritage positioning.
- Pharmaceutical packaging migration:FDA food-contact substance notifications for chlorinated phenol-free cork grades open vial and container sealing applications where elastomeric alternatives face extractables scrutiny.
- Carbon-negative certification monetization:Portuguese forest stewardship standards enable verified carbon credit stacking on cork oak management, creating pricing premiums for climate-neutral closure claims in environmentally segmented retail channels.
Industry Challenges
- Artisan craftsmanship attrition:Hand-finishing expertise for premium natural cork grades is concentrating in aging workforces without structured apprenticeship pipelines, threatening quality consistency at the top of the product pyramid.
- Automated optical sorting capex barriers:Machine vision systems for cellular structure grading require 2-3 million euro capital commitments that fragment competitive capacity between scaled integrated producers and traditional cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cork Stoppers Market |
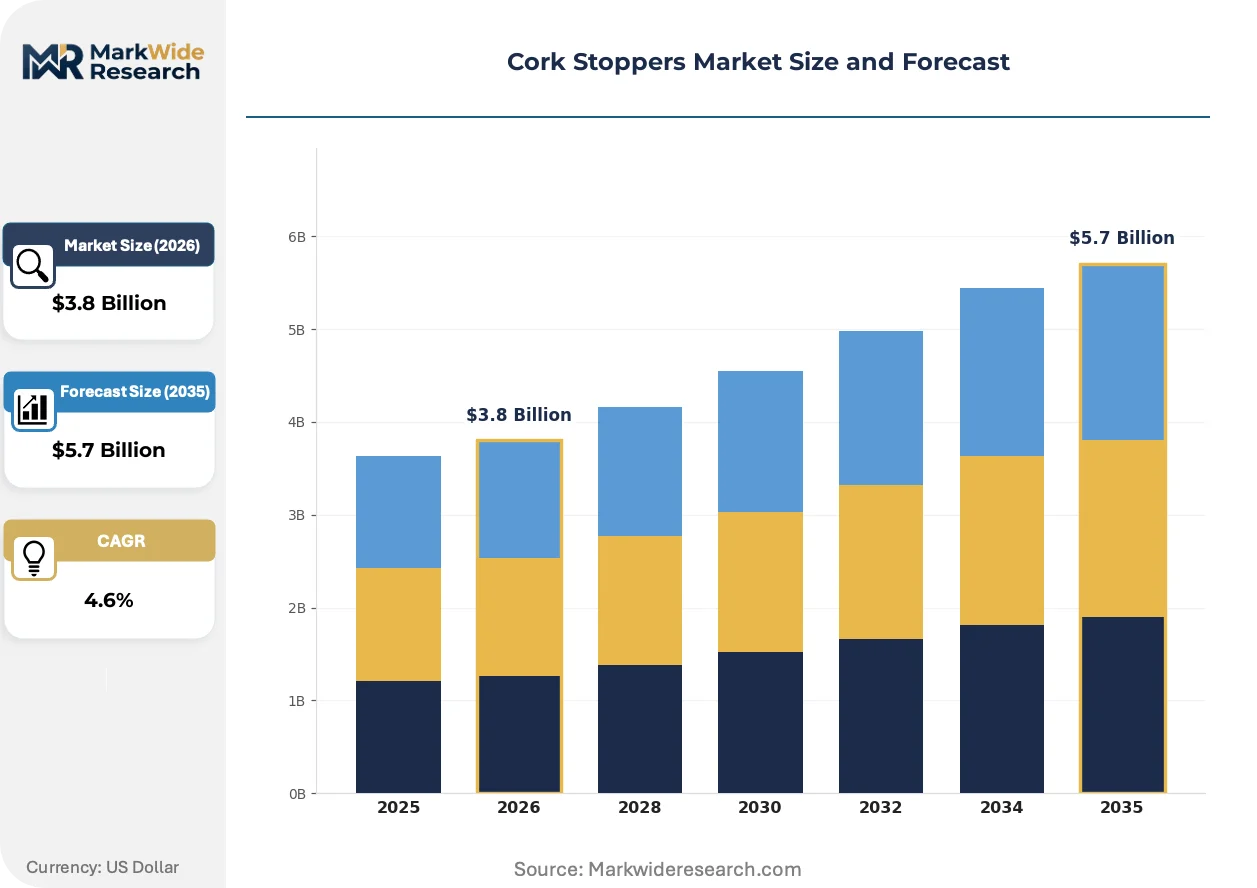
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cork, Composite Cork, Synthetic Cork, Agglomerated Cork End User: Wine Industry, Beverage Industry, Food Industry, Pharmaceutical Sector Application: Wine Bottling, Olive Oil Packaging, Pharmaceutical Packaging, Carbonated Beverage Sealing Size: Standard Size, Custom Size, Miniature Size, Oversized |
| Companies Covered | M.A. Silva, Nomacorc, Corticeira Amorim, Jelinek Cork Group, Oeneo Group, Vinventions, DIAM Bouchage, Portocork America, Cork Supply, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cork Stoppers Market Emerging Trajectories
Digital traceability infrastructure and advanced surface engineering are redefining how cork stoppers demonstrate quality assurance and functional performance to risk-averse wine producers.
Laser-based micro-perforation technology is decomposing the historical trade-off between oxygen transmission rate precision and natural material authenticity. Champagne houses and premium red wine producers are adopting these engineered corks to achieve bottle-aging predictability without sacrificing ritual extraction ceremony. The technology compresses synthetic closure advantages while preserving cork's sensory provenance signaling.
EU F-Gas Regulation constraints on hydrofluorocarbon propellants used in synthetic closure manufacturing are indirectly elevating natural cork's relative competitiveness. The framework increases production cost volatility for petroleum-based alternatives while Portuguese forest certification schemes gain regulatory recognition under the EU Green Deal's biodiversity objectives. Wine producers in Germany and the Netherlands are responding with explicit cork-preferred procurement policies.
Direct-to-winery contracting is consolidating procurement relationships away from traditional distributor intermediaries. Large cooperative cellars in Bordeaux and Rioja are negotiating multi-year supply agreements with vertically integrated Portuguese processors, displacing spot-market purchasing. This channel shift is most visible in appellation-controlled segments where supply security outweighs price optimization in supplier selection criteria.
Cork Stoppers Market Segmentation
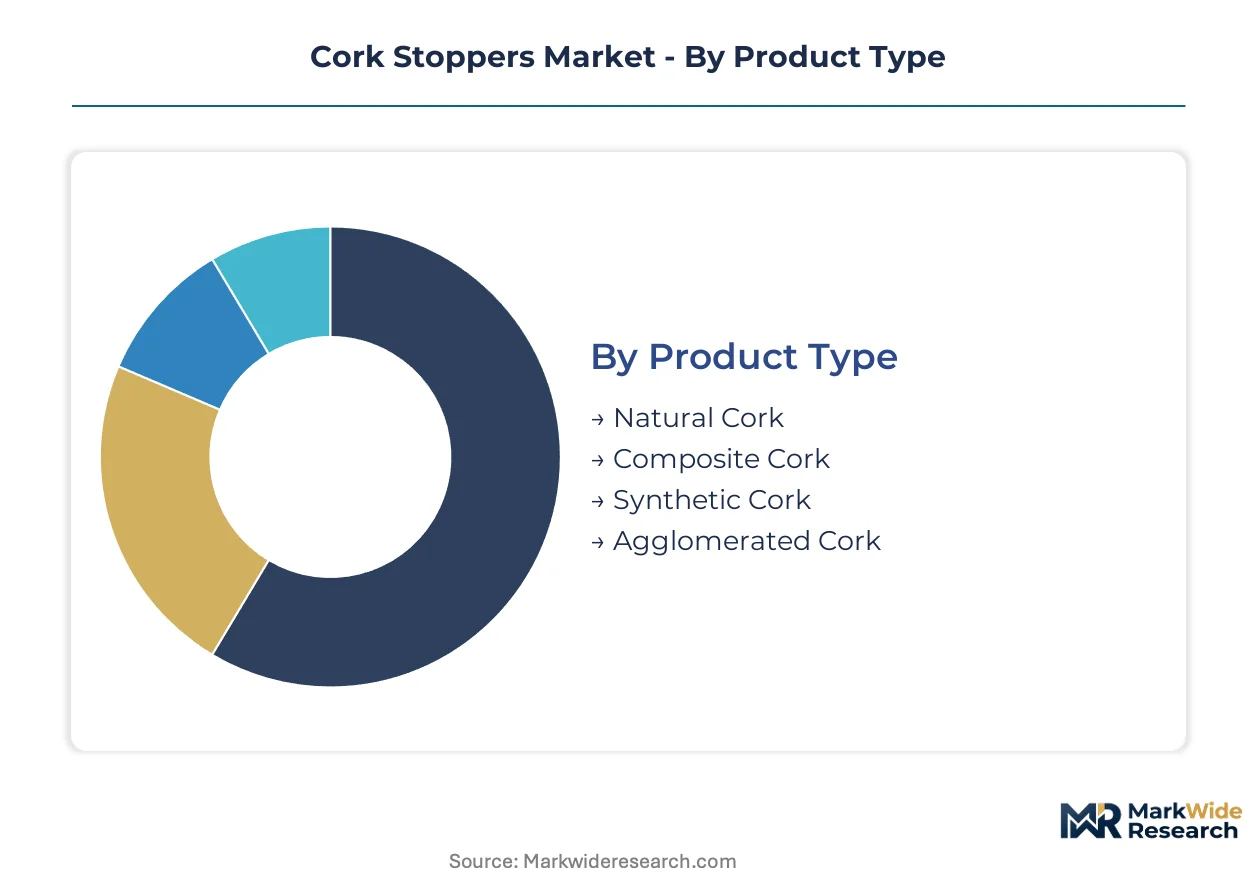
Cork stopper procurement strategies diverge sharply across product grades and end-use specifications, with regulatory compliance thresholds determining viable supplier pools for each segment. Wine producers, pharmaceutical packagers, and food manufacturers impose distinct performance criteria that reshape manufacturing priorities and certification investments.
Product Type:
EU REACH substance restrictions and FDA food-contact notifications create divergent compliance burdens across material categories, with natural cork facing chlorinated phenol screening while synthetic alternatives navigate petroleum-derived feedstock constraints.
- Natural Cork:Machined from Quercus suber bark with approximately 40 million air-filled cells per cubic centimeter, delivering elastic compression and gas-seal recovery. Premium wine bottling in France, Italy, and Spain concentrates demand here, driven by appellation authenticity requirements and ritual extraction ceremony. FSC-certified Portuguese forest sourcing now constitutes a market access prerequisite under EU Green Deal procurement mandates.
- Synthetic Cork:Injection-molded from polyethylene and thermoplastic elastomers, engineered for oxygen transmission consistency and complete 2,4,6-trichloroanisole elimination. Commercial wine tiers below 10 euro retail price points anchor volume, with producers prioritizing supply predictability over provenance signaling. EU F-Gas Regulation constraints on hydrofluorocarbon propellants elevate relative production cost volatility against natural alternatives.
- Composite Cork:Hybrid constructions combining natural cork granules with synthetic binding agents, occupying intermediate positioning on cost and performance spectra.
- Agglomerated Cork:Granulated material recovery products serving fortified wine and spirits segments where cost discipline outweighs natural grain aesthetics.
Natural cork handles the majority of throughput; synthetic cork is the fastest mover on share.
End User:
Customer procurement sophistication varies dramatically, with wine industry buyers negotiating multi-year direct contracts while pharmaceutical and food sectors impose extractables testing regimes that disqualify informal suppliers.
- Wine Industry:Dominant demand concentration spanning Champagne-method producers, Bordeaux cooperative cellars, and Rioja bottling facilities. ESG-linked financing covenants now mandate FSC-certified closure sourcing, compressing supplier eligibility to vertically integrated Portuguese processors with documented forest stewardship.
- Pharmaceutical Sector:Vial and container sealing applications where elastomeric alternatives face heightened extractables scrutiny under FDA guidance. Chlorinated phenol-free cork grades with complete substance notifications capture migration-sensitive applications.
- Beverage Industry:Carbonated and still beverage bottling outside wine, spanning premium water and craft spirits where closure differentiation supports brand positioning.
- Food Industry:Olive oil and specialty food packaging requiring hermetic sealing with neutral sensory impact, typically specifying agglomerated or composite grades for cost containment.
Wine industry procurement absorbs the dominant volume share; pharmaceutical sector qualifications are expanding most quickly.
Application:
Functional performance requirements stratify by oxygen transmission precision needs, with bottle-aging predictability commanding premium positioning against immediate-consumption packaging.
- Wine Bottling:Controlled oxygen transmission rates influence sensory development trajectory, with laser-microperforated engineered corks decomposing historical trade-offs between precision and authenticity. Champagne houses and premium red wine producers drive adoption of surface-engineered grades.
- Pharmaceutical Packaging:Container sealing applications where USP Class VI and FDA food-contact compliance structure supplier qualification timelines. Sterile vial applications favor chlorinated phenol-free natural cork over elastomeric alternatives facing extractables scrutiny.
- Olive Oil Packaging:UV protection and oxidation prevention requirements favor dark glass with cork closure, particularly in Italian and Spanish export markets defending appellation authenticity.
- Carbonated Beverage Sealing:Pressure retention specifications exceeding still wine requirements, historically served by technical agglomerates and composite constructions.
Wine bottling commands the dominant application share; pharmaceutical packaging is climbing the fastest on qualification momentum.
Size:
Dimensional standardization versus customization reflects channel concentration, with direct-to-winery contracting enabling bespoke specifications that distributor-mediated spot purchasing cannot accommodate.
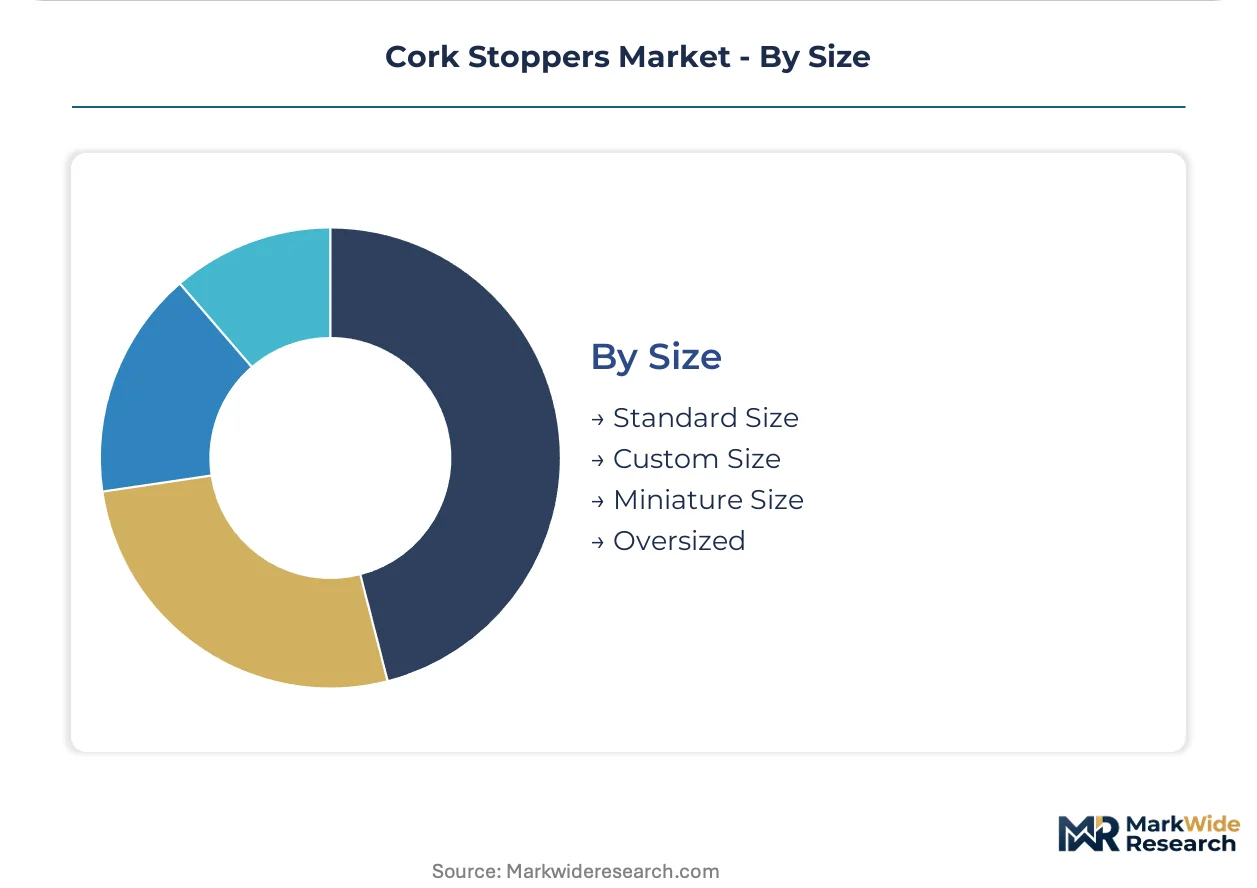
- Standard Size:750ml wine bottle compatibility dominates volume throughput, with Bordeaux and Burgundy neck finish specifications constituting procurement defaults for scaled production.
- Custom Size:Magnum, Jeroboam, and proprietary formats for luxury positioning, negotiated through multi-year supply agreements with vertically integrated processors.
- Miniature Size:Single-serve and airline hospitality formats, typically specifying agglomerated grades for cost discipline at reduced material volumes.
- Oversized:Specialty spirits and commemorative packaging, commanding premium pricing for hand-finished natural cork grades.
Standard size absorbs the majority of throughput; custom size is gaining share fastest on premiumization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Portuguese forest-origin stoppers while Italian and Spanish bottlers absorb premium differentials for appellation-authenticated closures. Mediterranean wine export concentration creates demand asymmetry between cork-producing and cork-consuming geographies.
Portugal
Portuguese Quercus suber forests supply over half of global raw cork bark, with Alentejo and Algarve regions hosting vertically integrated processing clusters. EU Green Deal sustainable sourcing mandates require Forest Stewardship Council certification for market access, compressing informal harvesters from supply chains. Corticeira Amorim anchors production gravity in Santa Maria da Feira with captive forest-to-finished-stopper operations.
France
Champagne houses and Bordeaux cooperative cellars drive premium natural cork offtake, prioritizing oxygen management precision for bottle-aging predictability. ANSM pharmaceutical packaging regulations structure compliance requirements for chlorinated phenol-free grades in sterile vial applications. The Champagne-Ardenne cluster is adopting laser-microperforated engineered corks to decompose historical trade-offs between authenticity and performance consistency.
Italy
Italian wine producers in Tuscany and Piedmont defend appellation authenticity through natural cork procurement, embedding closure provenance as terroir signaling. EFSA migration limits govern food-contact substance notifications for olive oil and specialty food packaging applications. The Prosecco-producing Veneto region is expanding technical agglomerate adoption for pressure-retention specifications in sparkling formats.
Spain
Rioja and Ribera del Duero bottling facilities negotiate multi-year direct contracts with Portuguese processors, displacing distributor-mediated spot purchasing. Spanish forest stewardship standards under EU deforestation-free supply chain regulations compress procurement timelines for documented provenance. Catalonia's cava producers represent underpenetrated technical cork categories where heritage positioning can displace plastic closures.
United States
California's Napa and Sonoma premium wine producers specify FSC-certified closures to satisfy ESG-linked financing covenants, importing Portuguese natural cork despite synthetic alternatives. FDA food-contact substance notifications structure compliance for pharmaceutical vial sealing applications where elastomeric alternatives face extractables scrutiny. Pacific Northwest distillers are emerging as specialty spirits closure demand centers for commemorative packaging formats.
Cork Stoppers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with natural cork specialists competing against synthetic closure engineers on divergent value vectors. The vendor base stratifies across three tiers: vertically integrated Portuguese forest-origin processors, petroleum-derived synthetic manufacturers, and hybrid composite specialists. Strategic moves concentrate on backward integration into raw material security, automated optical sorting capacity expansion, and direct-to-winery contracting channel shifts.
Among Portuguese-origin integrated processors, Corticeira Amorim exemplifies forest-to-finished-product control, while M.A. Silva occupies a position within the premium natural cork tier. Nomacorc anchors the synthetic technology vector with polyethylene and thermoplastic elastomer expertise. These three represent the dominant competitive archetypes shaping procurement relationships across Mediterranean wine-producing regions.
| Leading Market Players |
|---|
| M.A. Silva |
| Nomacorc |
| Corticeira Amorim |
| Jelinek Cork Group |
| Oeneo Group |
| Vinventions |
| DIAM Bouchage |
| Portocork America |
| Cork Supply |
| Others |
Supply Flow & Price Mechanics
Automated optical sorting capacity utilization above 80% at Portuguese integrated processors compresses unit costs for premium natural cork grades while elevating price floors for hand-finished artisan segments. Scale economies in machine vision grading systems tether supply concentration to pricing power, with FSC-certified forest access commanding 15-25% premiums over uncertified alternatives.
Pricing Analysis
Configured-to-order pricing for laser-microperforated engineered corks spans 3-4x multiples against standard agglomerated grades, with Champagne houses absorbing premiums for oxygen transmission precision. Three-tier pricing structure across premium natural, technical agglomerated, and economy synthetic levels anchors the market, with differentiation driven by FSC certification tier and cellular structure density grading. Cost compression in commercial wine tiers below 10 euro retail intensifies as polyethylene closure consistency improves. Volume wine producers exhibit highest price sensitivity; appellation-controlled estates prioritize supply security over unit cost optimization.
Supply Chain Analysis
Strategic stockpiling of certified cork bark dominates procurement strategy among vertically integrated Portuguese processors, insulating against Alentejo drought cycles that compress harvest yields. Raw material supply draws from Portugal, Spain, and limited Moroccan Quercus suber forests, with granulated recovery feedstock resting on cooperage byproduct streams and post-industrial collection networks. Single-source vulnerability concentrates in Alentejo-Algarve processing clusters exposed to EU deforestation-free documentation requirements. Distribution runs through direct-to-winery contracting channels that displace traditional distributor intermediaries in Bordeaux and Rioja procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent cork stopper producers face sustained substitution pressure from injection-molded polyethylene closures advancing on taint elimination and oxygen consistency performance vectors.
For Market Incumbents: Consolidate captive supply of FSC-certified Portuguese cork oak bark through multi-year forest management agreements, locking out synthetic competitors from ESG-linked financing channels. Deepen backward integration into automated optical sorting capacity to compress unit costs against artisan cooperative rivals. Prioritize laser-microperforation R&D investment to decompose the authenticity-performance trade-off that currently favors synthetic alternatives in commercial tiers. For New Entrants and Emerging Players: Digital traceability platform deployment represents a service-layer gap where incumbent Portuguese processors under-serve smaller appellation producers seeking documented provenance for export compliance. Target pharmaceutical vial sealing qualifications where FDA food-contact notification timelines disadvantage established wine-focused suppliers. Pursue chlorinated phenol-free grade certification as the primary go-to-market wedge against elastomeric incumbent suppliers facing extractables scrutiny. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated processors with demonstrated FSC certification compliance and automated grading capacity over synthetic technology pure-plays facing EU F-Gas Regulation cost volatility. Long-term viability hinges on carbon-negative certification monetization potential across Portuguese forest stewardship standards. Acquisition focus should center on processors with documented EU deforestation-free supply chain infrastructure. The signal to watch is German and Dutch wine producer procurement policy shifts toward explicit cork-preferred specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Forest Holdings | FSC-certified Portuguese cork oak access secures ESG-linked financing channel eligibility for premium positioning. |
| Automated Optical Sorting Capacity Expansion | Machine vision systems for cellular structure grading compress unit costs against artisan cooperative competitors. |
| Laser-Microperforation Technology Deployment | Engineered cork precision decomposes historical authenticity-performance trade-offs favoring synthetic substitutes. |
| Direct-to-Winery Contracting Channel Shift | Multi-year supply agreements with Bordeaux and Rioja cellars displace spot-market purchasing relationships. |
| Pharmaceutical Vial Sealing Qualification | FDA food-contact substance notifications open migration-sensitive applications beyond wine industry concentration. |
Methodological Framework
The analysis maps natural cork, synthetic cork, composite, and agglomerated product categories, each validated through primary interviews with Portuguese forest management officers, Champagne house procurement directors, Bordeaux cooperative cellar managers, and pharmaceutical packaging compliance leads. Secondary validation draws from EU EFSA migration limit documentation, FDA food-contact substance notification databases, Forest Stewardship Council certification registries, and Portuguese agricultural ministry harvest statistics. Bottom-up segmentation modeling triangulates against top-down macroeconomic demand indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled dimensions spanning material grade tier, end-use industry vertical, oxygen transmission specification, and regional regulatory cluster. CAGRs derive from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific forecast inputs include EU Green Deal procurement mandate implementation timelines and synthetic closure petroleum feedstock cost volatility indices.
Material uncertainties — Portuguese drought cycle severity, EU deforestation-free regulation enforcement intensity, synthetic closure technological advancement rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding FSC certification adoption curves and direct-to-winery channel migration velocity. Revision becomes warranted when synthetic closure oxygen transmission consistency crosses thresholds that eliminate natural cork's performance differentiation in premium wine segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Dispensing Spouts Market
Caps and Closures
Box Latch Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
PVC-Free Cap Liners Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Drop Sealers Market