
 Crimp-On Spouts Market | 2026-2036
Crimp-On Spouts Market Size, Share, and Industry Trends Forecast 2026-2036
Crimp-On Spouts Market Analytics
The capital-intensity divergence between large-format extrusion molders and precision metal-forming specialists is rotating competitive investment toward automated crimp-sealing lines. Berry Global leverages captive resin compounding to control raw material pass-through costs. AptarGroup sustains technical leadership in multi-layer barrier spout architectures. Silgan Holdings anchors North American beverage packaging through long-term supply agreements with carbonated soft drink bottlers.
Crimp-on spouts are mechanically attached dispensing closures that form a hermetic seal through radial compression of a metal or polymer band around a container neck finish, typically achieving pull-off forces of 15-50 Newtons depending on band gauge and substrate compatibility. These devices enable controlled product dispensing while maintaining shelf stability for liquid and semi-viscous contents across food, chemical, and pharmaceutical applications. Plastic spouts lead volume due to cost scalability in high-speed injection molding, though metal variants command premium positioning in chemical storage where thermal resistance and mechanical durability outweigh unit economics. The pharmaceutical application segment shows the fastest structural expansion as single-use dosing compliance drives tamper-evident closure mandates. Factory assembly installation dominates throughput, yet automated crimping systems represent the emerging margin pool as OEMs integrate vision-guided placement robotics.
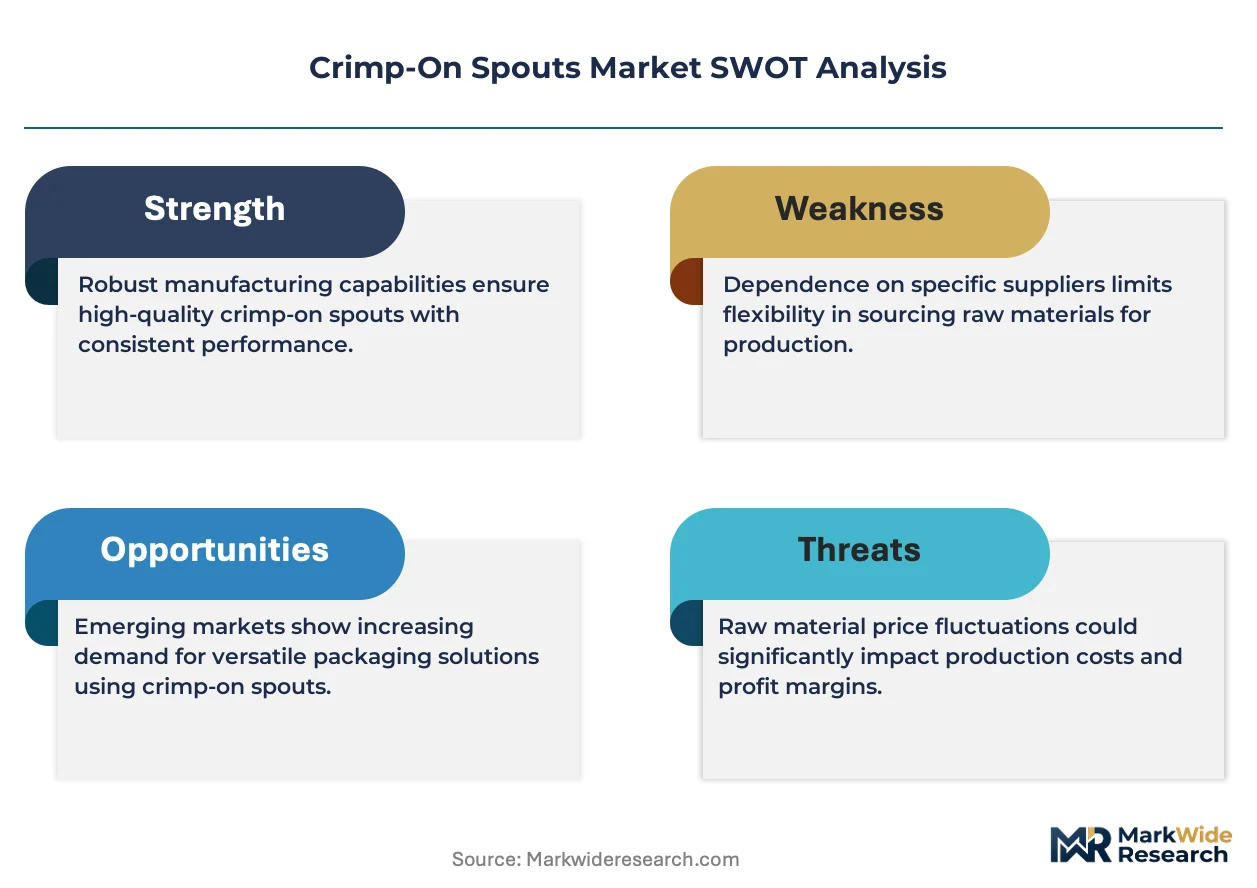
FDA 21 CFR Part 177 governs indirect food additive compliance for polymer spout materials in U.S. distribution, while EU REACH restricts candidate substance migration from metal-plated band components into consumable contents. The EU Packaging and Packaging Waste Regulation further mandates recyclability design standards that reshape material selection across composite spout constructions. Stakeholders must monitor evolving extended producer responsibility schemes and decide between reformulating for mono-material recyclability or accepting compliance premiums for proven multi-layer barrier performance.
Market Dynamics
Automated crimp-sealing lines are compressing unit economics for mid-tier molders while concentrating margin capture among precision metal-forming specialists with captive robotics integration. This capital divergence is forcing portfolio repositioning across the supplier base.
Growth Catalysts
- Tamper-evident mandates:EU Packaging and Packaging Waste Regulation compliance requirements are accelerating pharmaceutical and beverage container retrofits across Germany and France. Single-use dosing protocols drive closure replacement cycles.
- Barrier polymer advances:Multi-layer EVOH coextrusion architectures are extending shelf stability for sensitive liquid contents. Food manufacturers in the Benelux corridor are specifying these configurations for ambient distribution.
- Industrial packaging corridor concentration:Germany's Rhine-Ruhr manufacturing belt generates sustained demand for chemical-resistant metal spout variants. Regional logistics infrastructure supports just-in-time delivery for high-volume contract fillers.
Market Restraints
- Resin cost volatility:Polypropylene and polyethylene feedstock pass-through clauses compress fixed-margin contracts for injection molders. Berry Global's captive compounding provides insulation unavailable to smaller competitors.
- REACH substance restrictions:Candidate list updates for metal-plated band components force reformulation cycles. Compliance premiums for proven multi-layer constructions exceed mono-material alternatives by substantial margins.
- Substitution by snap-fit alternatives:Threadless closure systems are capturing low-viscosity liquid segments where hermetic integrity requirements are less stringent. Cost-sensitive private-label beverage brands are piloting these designs.
Strategic Opportunities
- Vision-guided placement robotics:OEM integration of automated crimping systems creates service revenue pools beyond hardware sales. System integrators in Stuttgart and Munich are developing turnkey modules for retrofit installation.
- Extended producer responsibility schemes:France's Citeo eco-modulation bonuses reward mono-material spout designs with reduced environmental contributions. Early compliance positions suppliers for preferential listing with national retail chains.
- Pharmaceutical compliance specialization:FDA 21 CFR Part 177 documentation services represent high-margin advisory revenue. Contract manufacturers serving US export markets require validated material traceability systems.
Industry Challenges
- Multi-standard certification timelines:Simultaneous FDA, EMA, and ANVISA submissions for pharmaceutical spout variants extend product launch windows. Documentation burden disproportionately affects mid-cap specialists without dedicated regulatory affairs functions.
- Legacy crimping equipment retrofit complexity:Mechanical band-feed systems lack compatibility with vision-guided placement modules. Plant engineering teams face extended downtime during automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crimp-On Spouts Market |
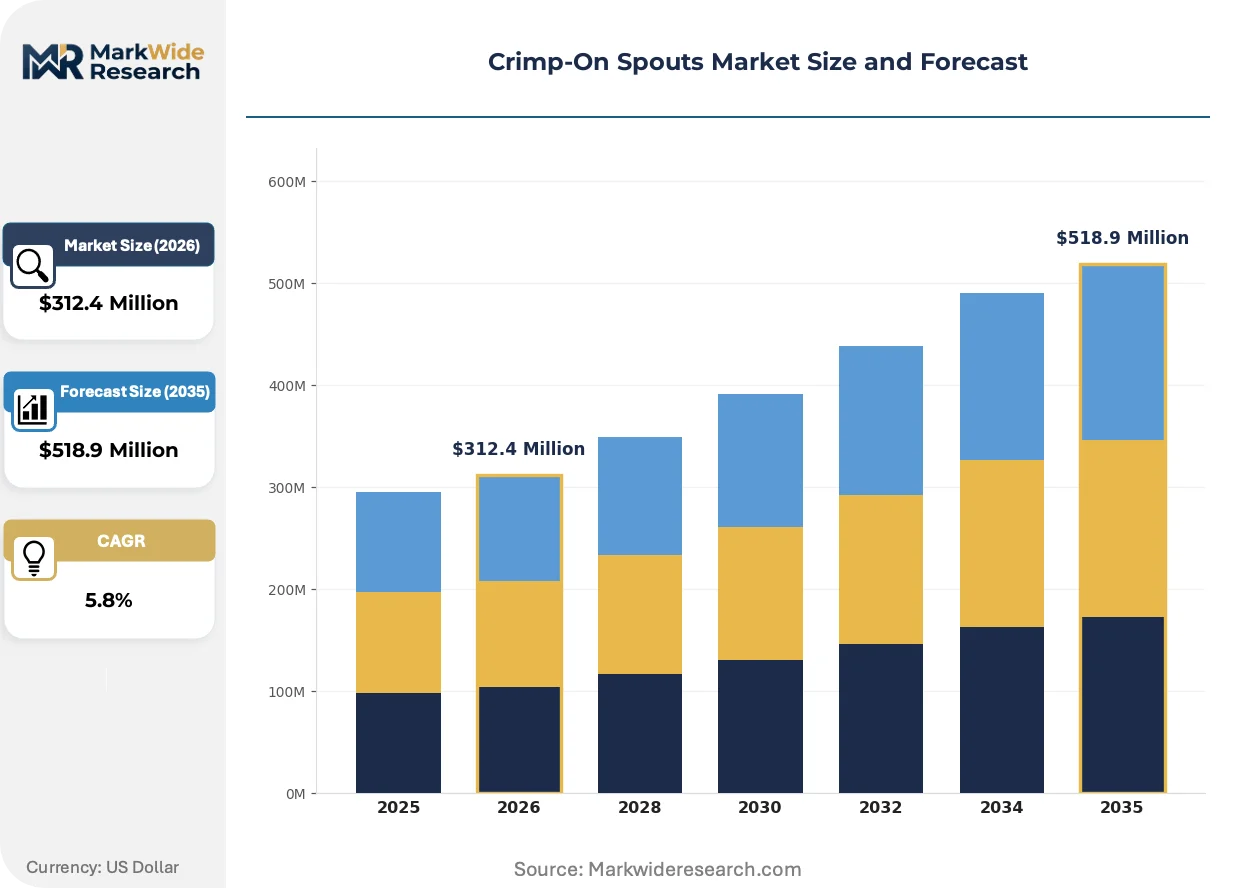
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Rubber Application: Food Packaging, Beverage Containers, Chemical Storage, Pharmaceutical End User: Manufacturers, Retailers, Distributors, Wholesalers Installation: On-Site, Factory Assembly, DIY, Automated |
| Companies Covered | Berry Global, AptarGroup, WestRock, Amcor, Silgan Holdings, Ball Corporation, Crown Holdings, Consolidated Container Company, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crimp-On Spouts Market Evolving Landscape
Material science convergence with automation architecture is redrawing competitive boundaries between polymer specialists and metal-forming incumbents. Technical leadership now requires simultaneous command of barrier-layer chemistry and precision assembly robotics.
Multi-layer coextrusion blow molding is decomposing the traditional separation between spout body production and downstream barrier treatment. Pharmaceutical contract manufacturers in Basel and Lyon are specifying integrated EVOH-nylon-PP constructions that eliminate secondary lamination steps. This consolidation is compressing the supplier tier by internalizing what previously required specialized converter relationships.
EU REACH candidate list expansion is forcing systematic substance screening across metal-plated band supply chains. Industrial chemical packaging producers are migrating to stainless-steel band alternatives despite unit cost premiums. German KBA transport safety guidelines for hazardous materials are reinforcing this specification shift through tightened mechanical durability testing protocols.
Consolidated procurement by pan-European beverage bottlers is compressing supplier negotiation cycles and unbundling technical service components. Purchasing departments at major carbonated soft drink groups are separating tooling investment from unit pricing in multi-year agreements. This disaggregation is most visible in the Netherlands, where contract packaging concentration enables standardized specification across multiple brand portfolios.
Crimp-On Spouts Market Segmentation
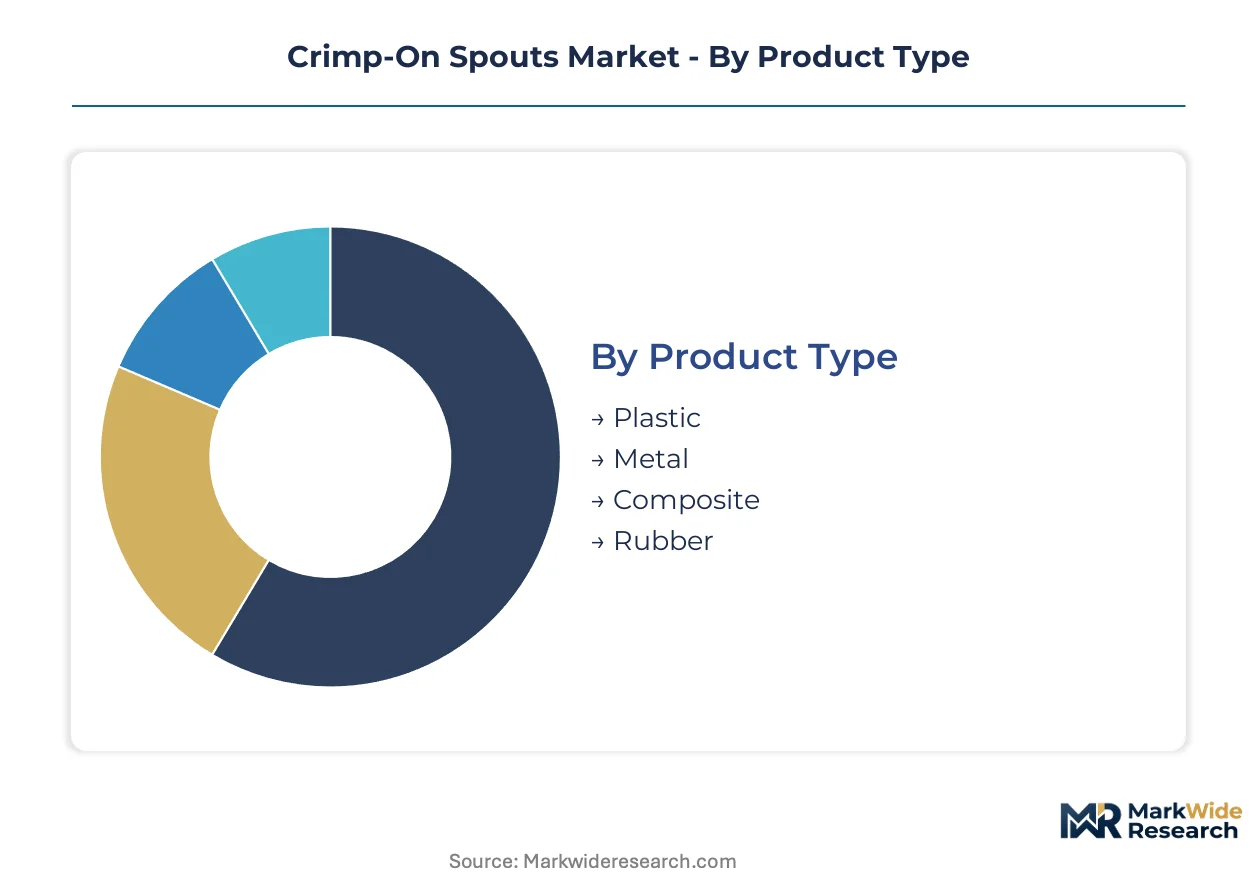
Crimp-on spout segmentation reveals divergent vulnerability to snap-fit substitution across material classes, while installation method differentiation increasingly determines margin capture. Understanding these fault lines enables targeted positioning against automated crimp-sealing line investments and regulatory compliance specialization.
Product Type:
Substitution pressure from threadless closure systems concentrates most intensely on cost-driven plastic variants, while metal and composite constructions defend position through performance-critical specifications.
- Plastic:Polypropylene and polyethylene injection-molded bodies dominate unit economics through high-speed production scalability. Beverage container manufacturers in Germany specify these for carbonated soft drink distribution where cost minimization outweighs thermal resistance requirements.
- Metal:Stainless-steel and aluminum band constructions achieve 15-50 Newton pull-off forces for chemical storage applications. Germany's KBA transport safety guidelines for hazardous materials reinforce specification migration from plated alternatives amid REACH candidate list expansion.
- Composite:Multi-layer polymer-metal laminates balance barrier performance with mechanical durability for sensitive pharmaceutical contents.
- Rubber:Elastomeric sealing elements provide compression-set recovery for temperature-cycling applications in industrial chemical containment.
Plastic anchors the volume base while composite gains share at the steepest rate.
Application:
Margin concentration follows regulatory stringency gradients, with pharmaceutical and food packaging commanding compliance premiums unavailable to commoditized beverage segments.
- Food Packaging:EVOH coextrusion architectures extend shelf stability for ambient distribution of sensitive liquid contents. Benelux manufacturers specify multi-layer barrier configurations for aseptic filling operations.
- Beverage Containers:Tamper-evident closure mandates under EU Packaging and Packaging Waste Regulation drive retrofit demand across Germany and France. Carbonated soft drink bottlers consolidate procurement through separated tooling and unit pricing agreements.
- Chemical Storage:Metal-spout dominance persists where thermal resistance and mechanical durability outweigh unit economics. Rhine-Ruhr industrial corridor generates sustained demand for hazardous material containment.
- Pharmaceutical:Single-use dosing compliance protocols accelerate closure replacement cycles. FDA 21 CFR Part 177 documentation requirements create high-margin advisory revenue for validated material traceability systems.
Beverage containers anchor the volume base while pharmaceutical climbs the fastest.
End User:
Procurement authority concentration among manufacturers reshapes channel economics, compressing distributor margins while rewarding direct technical service relationships.
- Manufacturers:Beverage and pharmaceutical contract fillers specify crimp-on spouts at source for integrated filling-line compatibility. Automated crimp-sealing line investments concentrate decision authority at this tier.
- Retailers:Private-label beverage brands pilot threadless alternatives where hermetic integrity requirements permit cost reduction.
- Distributors:Chemical packaging intermediaries stock metal-spout variants for just-in-time delivery to Rhine-Ruhr manufacturing clusters.
- Wholesalers:Bulk procurement of standardized plastic spouts serves regional beverage bottlers with limited specification customization.
Manufacturers anchor the volume base while retailers expand specification influence most rapidly.
Installation:
Automation intensity divides competitive returns, with vision-guided placement systems capturing service revenue pools beyond hardware margins.
- Factory Assembly:High-throughput integration dominates volume production for major beverage bottlers. Long-term supply agreements with carbonated soft drink groups anchor North American capacity utilization.
- Automated:Vision-guided placement robotics create emerging margin pools as OEMs integrate crimping modules. System integrators in Stuttgart and Munich develop turnkey retrofit installations.
- On-Site:Field crimping serves remote chemical storage facilities with specialized hazardous material handling requirements.
- DIY:Manual installation persists in low-volume specialty chemical and artisanal food segments where capital investment is prohibitive.
Factory assembly anchors the volume base while automated installation expands at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial packaging corridor while French beverage manufacturers absorb compliance premiums under tightened EU regulations. This asymmetry reflects divergent supply chain configurations and regulatory exposure across Western European markets.
Germany
Rhine-Ruhr manufacturing clusters drive sustained demand for chemical-resistant metal spout variants in hazardous material containment. KBA transport safety guidelines reinforce specification migration from plated metal alternatives toward stainless-steel band constructions. Stuttgart-based system integrators develop vision-guided placement robotics for automated crimp-sealing line retrofits.
France
Beverage container manufacturers accelerate tamper-evident closure retrofits under EU Packaging and Packaging Waste Regulation mandates. Citeo eco-modulation bonuses reward mono-material spout designs with reduced environmental contribution fees. Lyon pharmaceutical contract manufacturers specify integrated EVOH-nylon-PP barrier architectures for single-use dosing compliance.
United States
Carbonated soft drink bottlers consolidate procurement through separated tooling and unit pricing agreements in multi-year supply arrangements. FDA 21 CFR Part 177 governs indirect food additive compliance for polymer spout materials in interstate distribution. Midwestern contract packaging hubs anchor North American capacity utilization for factory-assembled installations.
Netherlands
Benelux food manufacturers specify multi-layer EVOH coextrusion configurations for aseptic filling operations and ambient distribution of sensitive liquid contents. Consolidated procurement by pan-European beverage groups compresses supplier negotiation cycles in the Rotterdam-Antwerp logistics corridor. Private-label brands pilot threadless closure alternatives where hermetic integrity requirements permit cost reduction.
Switzerland
Basel pharmaceutical clusters demand validated material traceability systems for FDA 21 CFR Part 177 documentation services. Swissmedic regulatory alignment with EMA standards streamlines multi-jurisdiction certification timelines for barrier spout exports. Precision metal-forming specialists in the Swiss Mittelland region supply stainless-steel band components for chemical storage applications.
Crimp-On Spouts Market Competitive Landscape
Concentration sits with diversified packaging conglomerates that leverage captive resin compounding and long-term beverage supply agreements to defend margin positions. Mid-tier injection molders face compression from automated crimp-sealing line investments that reward scale and robotics integration. Two strategic archetypes dominate: precision metal-forming specialists with hazardous material certification, and polymer barrier-layer technologists serving pharmaceutical compliance mandates. Competitive moves center on M&A for regional filling-line integration and capacity expansion in automated crimping module production.
Within the diversified packaging tier, Berry Global, AptarGroup, and Silgan Holdings represent contrasting strategic postures. Berry Global exemplifies vertical integration through captive resin compounding that insulates against polypropylene feedstock volatility. AptarGroup occupies a position in multi-layer barrier spout architecture development for pharmaceutical and food applications. Silgan Holdings anchors North American beverage packaging relationships through long-term supply agreements with carbonated soft drink bottlers. These three entities collectively illustrate how scale, material control, and customer lock-in differentiate competitive returns in automated crimp-sealing line markets.
| Leading Market Players |
|---|
| Berry Global |
| AptarGroup |
| WestRock |
| Amcor |
| Silgan Holdings |
| Ball Corporation |
| Crown Holdings |
| Consolidated Container Company |
| Berlin Packaging |
| Others |
Value Network & Pricing Analysis
Stainless-steel band migration from plated metal alternatives simultaneously redistributes supply geography toward German precision metal-forming clusters and compresses pricing premiums for REACH-compliant chemical storage specifications. This substitution dynamic tightens cost pass-through mechanics for mid-tier injection molders while rewarding captive resin compounders with insulation against polypropylene feedstock volatility.
Pricing Analysis
The customization-premium spread widens between configured-to-order multi-layer barrier spouts and standard polypropylene injection-molded variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale thresholds. Cost compression in standard plastic tiers intensifies because snap-fit substitution threats squeeze fixed-margin contracts. Private-label beverage brands exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb compliance premiums for validated material traceability systems.
Supply Chain Analysis
Just-in-time inventory strategies dominate Rhine-Ruhr chemical packaging corridors, while strategic stockpiling of EVOH barrier resins buffers Benelux food manufacturers against coextrusion supply interruptions. Geographic supply concentration centers on Germany, France, and the Netherlands for precision metal-forming and automated crimping module production. Raw material dependencies draw from polypropylene feedstocks, stainless-steel band coils, and multi-layer polymer films. Single-source vulnerability in vision-guided robotics components threatens automated crimp-sealing line retrofits. Distribution runs through direct technical service relationships with contract fillers rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated crimp-sealing line integration functions as a platform-economics inflection where OEM interoperability standards determine ecosystem capture. Vision-guided placement robotics interoperability protocols are consolidating supplier tiers around turnkey module providers.
For Market Incumbents: Shield margin positions by deepening captive resin compounding capabilities and securing long-term supply agreements with carbonated soft drink bottlers. Snap-fit substitution threats in low-viscosity beverage segments demand defensive certification investments in tamper-evident closure mandates. Automated crimping module production capacity in Stuttgart and Munich anchors technical service revenue pools beyond hardware sales.
For New Entrants and Emerging Players: Differentiate on pharmaceutical compliance specialization where FDA 21 CFR Part 177 documentation services command advisory premiums. White-space targets include vision-guided placement robotics system integration for legacy equipment retrofits and mono-material spout designs qualifying for France's Citeo eco-modulation bonuses. Field crimping services for remote chemical storage facilities offer the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation implementation reshapes the acquisition landscape toward mono-material recyclability capabilities and validated pharmaceutical traceability systems. Long-term viability over the coming decade hinges on positioning against extended producer responsibility scheme evolution. Precision metal-forming specialists with KBA hazardous material certification represent the priority acquisition archetype. The signal to monitor is Citeo eco-modulation bonus schedule revisions favoring mono-material designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Crimping Module Production | Stuttgart system integrators capture service revenue beyond hardware margins through vision-guided robotics. |
| Mono-Material Spout Design Reformulation | Citeo eco-modulation bonuses in France reward recyclability compliance with reduced environmental contribution fees. |
| Captive Resin Compounding Expansion | Backward integration into polypropylene feedstock insulates against volatility compressing fixed-margin contracts. |
| Pharmaceutical Compliance Documentation Services | FDA 21 CFR Part 177 validation creates high-margin advisory revenue for material traceability systems. |
| Stainless-Steel Band Supply Agreement | German KBA transport safety guidelines reinforce specification migration from REACH-restricted plated alternatives. |
Research Methodology
Cross-validation between primary interviews with filling-line engineers, procurement leads at beverage contract manufacturers, regulatory affairs specialists, and aftermarket service heads anchors the qualitative findings. Secondary sources draw from EU Packaging and Packaging Waste Regulation compliance databases, FDA 21 CFR Part 177 submission records, KBA hazardous material transport guidelines, and customs trade data for polymer and metal band imports. Bottom-up volume modeling triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around resin cost volatility scenarios and regulatory timeline acceleration tests forecast robustness. Segmentation dimensions span material class, application vertical, installation method, and regional regulatory cluster. CAGRs derive from unit economics modeling of automated crimp-sealing line adoption curves and pharmaceutical compliance retrofit cycles. Industry-specific inputs include EVOH coextrusion capacity expansion announcements and vision-guided robotics integration rates at OEM facilities.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated snap-fit substitution would require recalibration. Forecasts reflect documented assumptions regarding REACH candidate list expansion pace and extended producer responsibility scheme implementation timelines. Practitioners should keep alternative scenarios live as automation interoperability standards and mono-material recyclability thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
PCR Closures Market
Caps and Closures
Disc Top Caps Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
IBC Caps Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market