
 Reverse Cap Bottles Market | 2026-2036
Reverse Cap Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Cap Bottles Market Analytics
Asset-light leasing models for injection-molding equipment is tilting competitive dynamics toward mid-tier converters who previously faced capital barriers. Amcor leverages its global film and closure network to sustain multi-regional supply contracts for pharmaceutical clients. Berry Global anchors North American capacity through dedicated healthcare packaging facilities with cleanroom certification. Silgan Holdings competes via in-house metal closure production integrated with bottle manufacturing lines.
Reverse cap bottles employ threaded or lug-style closures engineered to seal via counter-clockwise or specialized torque patterns, typically manufactured through injection molding of polypropylene or polyethylene with precision thread tolerances of 0.05 mm to prevent leakage and enable child-resistant functionality. Their primary purpose centers on securing liquid and semi-liquid contents across regulated industries where tamper evidence and user safety are mandatory. Plastic closures dominate volume due to cost scalability, though composite segments capturing glass-and-polymer hybrids are expanding fastest in cosmetics where aesthetic differentiation commands premium positioning. Flip-top configurations lead in pharmaceutical dispensing convenience, while screw cap variants retain margin pools in food and beverage applications requiring hermetic sealing.
FDA 21 CFR Part 211 mandates container-closure integrity testing for pharmaceutical applications, while EMA's Annex 1 guidelines impose particulate and sterility standards that elevate barrier specification requirements. REACH and EU Packaging Waste Directive frameworks restrict certain plasticizers and mandate recyclability thresholds, reshaping material selection across European supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based polymer certifications that will determine qualified supplier status in regulated end-use sectors.
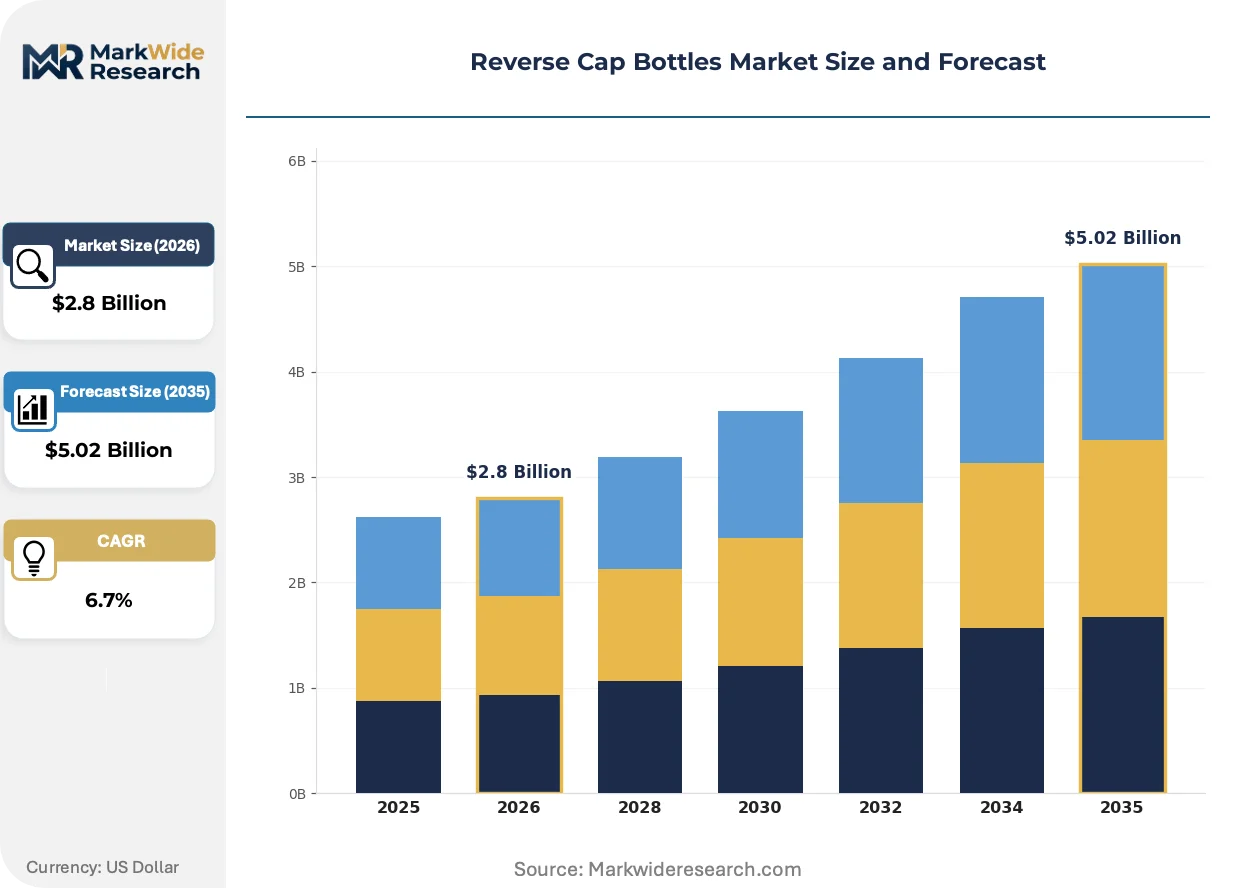
Market Dynamics
Asset-light leasing for injection-molding equipment is dismantling capital barriers that historically protected large converters, enabling mid-tier suppliers to capture pharmaceutical contracts previously locked by cleanroom-certified incumbents.
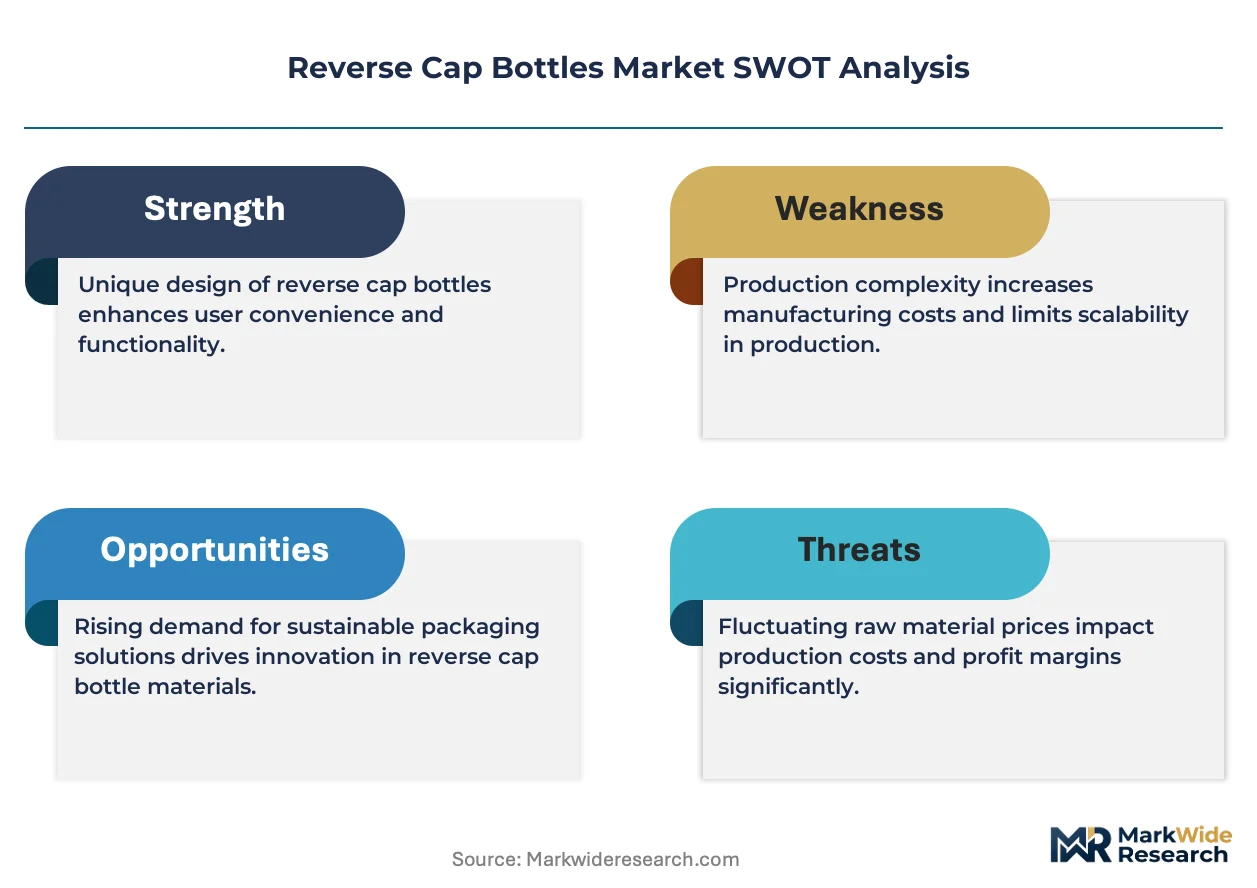
Growth Catalysts
- FDA 21 CFR Part 211:Container-closure integrity testing mandates for pharmaceutical packaging elevate demand for precision-threaded reverse cap systems with documented torque tolerance certification.
- Child-resistant closure mechanisms:Regulatory mandates across pediatric pharmaceutical and household chemical sectors standardize counter-clockwise torque patterns as the dominant safety engineering protocol.
- Flip-top dispensing configurations:Convenience-driven adoption in liquid medication packaging accelerates conversion from conventional screw caps in United States and German healthcare supply chains.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings tied to naphtha cracking economics compress converter margins and destabilize long-term contract pricing.
- Cleanroom certification concentration:North American and Western European healthcare packaging capacity remains concentrated among facilities with ISO 14644 Class 7 or better certification, limiting qualified supplier pools.
- Glass-polymer hybrid substitution:Premium cosmetics brands in France and Switzerland migrate toward glass primary containers with polymer overcaps, displacing all-plastic reverse cap bottles in high-margin fragrance segments.
Strategic Opportunities
- Brazilian pharmaceutical packaging:ANVISA's tightening traceability requirements for serialized closures create first-mover advantage for converters with integrated tamper-evident and authentication features.
- Bio-based polypropylene certification:ISCC PLUS and RSB chain-of-custody standards unlock qualified supplier status for European pharmaceutical procurement tenders with mandated renewable content thresholds.
- Direct-to-pharmacy distribution:Bypassing traditional wholesale channels through hospital system consignment models reduces inventory carrying costs and accelerates specification feedback loops for custom closure designs.
Industry Challenges
- Precision thread machining expertise:Tolerance requirements of 0.05 mm for pharmaceutical-grade seals exceed capabilities of generalist injection molders, creating acute scarcity of qualified tooling engineers.
- EMA Annex 1 particulate compliance:Sterility barrier validation timelines extend 18-24 months for new closure formats, compressing product development windows and straining R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Cap Bottles Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Composite Closure Type: Screw Cap, Snap-on Cap, Flip Top, Push-pull Cap End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale |
| Companies Covered | AptarGroup, Mondi Group, Amcor, Bericap, Berry Global, Silgan Holdings, Green Rush Packaging, Closure Systems International, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Cap Bottles Market Evolving Landscape
Digital thread verification and connected packaging layers are converging with material science advances to redefine how closure integrity is authenticated across regulated supply chains.
Embedded NFC and QR-coded tamper-evident bands are digitizing supply chain traceability for pharmaceutical reverse cap bottles. European and North American contract manufacturers are piloting these systems at scale for high-value biologics. This convergence is digitizing authentication workflows and compressing the window for counterfeit product infiltration.
REACH restrictions on phthalate plasticizers and the EU Packaging Waste Directive's recyclability thresholds are forcing polypropylene formulation changes across European converter networks. Material suppliers are accelerating non-phthalate catalyst systems and post-consumer recycled content qualification. German and French pharmaceutical packagers are absorbing the highest compliance costs as they retrofit existing tooling for modified melt-flow resins.
Hospital system consolidation in the United States is concentrating procurement authority among integrated delivery networks with standardized formularies. These buyers are unbundling closure specifications from bottle supply agreements, awarding separate contracts to specialized converters with dedicated healthcare certification. This disintermediation is visible most acutely in the Northeast and Midwest, where three IDNs control the majority of inpatient pharmaceutical packaging decisions.
Reverse Cap Bottles Market Segmentation
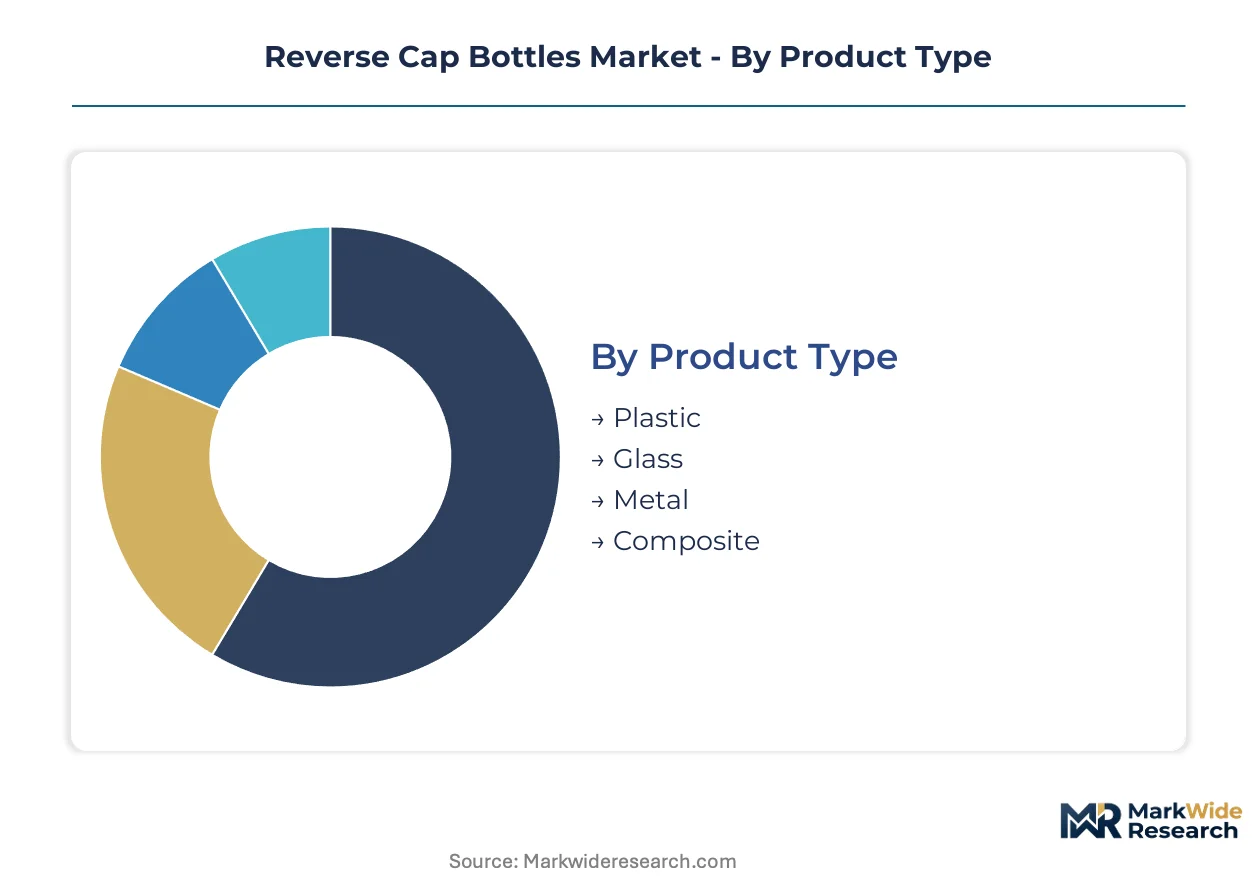
Segmentation in reverse cap bottles determines specification intensity, certification burden, and margin architecture across divergent end-use requirements. Material selection and closure engineering separate pharmaceutical-grade precision from commodity food packaging, while channel strategy dictates inventory velocity and customer intimacy models.
Product Type:
Mature commodity resins dominate volume, yet emerging hybrid formats are capturing specification-driven niches through barrier performance and aesthetic differentiation.
- Plastic:Polypropylene and polyethylene injection-molded bottles constitute the baseline volume platform, with thread tolerances engineered to 0.05 mm for pharmaceutical-grade hermetic sealing. Demand concentrates in United States generic drug packaging, where FDA 21 CFR Part 211 compliance mandates documented torque certification and child-resistant functionality.
- Glass:Borosilicate and soda-lime containers deliver inert barrier properties for parenteral and high-value liquid formulations. German pharmaceutical packagers specify glass reverse cap systems for biologics requiring absolute oxygen and moisture exclusion, absorbing premium positioning despite higher logistics costs.
- Metal:Aluminum and tinplate closures serve specialized chemical and industrial applications requiring electromagnetic shielding or extreme temperature resistance.
- Composite:Glass-polymer hybrid constructions pair primary glass barriers with precision-molded polymer overcaps for cosmetic fragrance segments in France and Switzerland.
Plastic retains volume leadership; composite holds the steepest expansion curve.
Closure Type:
Cost tier stratification separates precision-engineered dispensing systems from basic sealing solutions, with premium configurations commanding 3-4x unit economics over commodity screw caps.
- Screw Cap:Threaded closures with standardized torque patterns remain the default for food and beverage hermetic sealing, manufactured through high-cavitation injection molding for cost scalability. United States condiment and sauce packagers specify screw cap reverse bottles for hot-fill compatibility and shelf stability.
- Flip Top:Hinged dispensing closures integrate child-resistant mechanisms with single-handed operation for liquid medication compliance. German hospital system procurement concentrates demand for flip-top pharmaceutical bottles, driven by nursing efficiency and pediatric safety mandates.
- Snap-on Cap:Lug-style closures enable rapid capping line speeds for high-volume beverage applications with moderate barrier requirements.
- Push-pull Cap:Sports and personal care dispensing formats prioritize user convenience over tamper-evident rigor.
Screw cap commands the broadest installed base; flip top generates the highest specification premiums.
End User:
Application-driven certification requirements fragment the competitive landscape, with pharmaceutical and cosmetics segments imposing qualification barriers that exclude generalist converters.
- Pharmaceuticals:Container-closure integrity testing, child-resistant certification, and EMA Annex 1 particulate compliance define the most stringent specification tier. Cleanroom-certified converters in Germany and the United States capture these contracts through 18-24 month validation timelines that generalist molders cannot replicate.
- Cosmetics:Aesthetic differentiation and tactile closure engineering command premium positioning in French and Swiss fragrance markets. Glass-polymer hybrid reverse cap bottles displace all-plastic alternatives where brand equity justifies unit cost multiples.
- Food & Beverage:Hermetic sealing and hot-fill compatibility drive screw cap dominance in condiment and ready-to-drink segments.
- Household Products:Chemical resistance and child-resistant mandates standardize counter-clockwise torque patterns for cleaning and automotive fluids.
Pharmaceuticals anchor margin pools; cosmetics delivers the fastest share gains in premium positioning.
Distribution Channel:
Customer type determines service intensity, with direct and wholesale channels diverging sharply on technical support requirements and inventory commitment depth.
- Direct Sales:Hospital system consignment and pharmaceutical contract manufacturing relationships demand embedded engineering support and rapid specification iteration. United States integrated delivery networks in the Northeast and Midwest unbundle closure procurement from bottle supply, awarding separate contracts to healthcare-certified specialists.
- Wholesale:Distributor-mediated volume moves through pharmaceutical and cosmetics wholesale networks in Germany and France, aggregating fragmented brand owner demand.
- Retail:Mass-market food and beverage packaging flows through retail-centric supply chains with standardized specifications and price-driven procurement.
- E-commerce:Direct-to-consumer cosmetic and specialty pharmaceutical brands experiment with customized closure formats and subscription fulfillment models.
Direct sales captures the highest value per unit; e-commerce shows the most rapid channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands a 15-20% premium over United States contract rates for pharmaceutical-grade reverse cap bottles, reflecting EMA Annex 1 compliance costs and cleanroom certification scarcity. This asymmetry reshapes converter location decisions and cross-border supply chain configurations.
United States
Integrated delivery networks in the Northeast and Midwest concentrate procurement authority for pharmaceutical packaging, unbundling closure specifications from bottle supply agreements. FDA 21 CFR Part 211 mandates container-closure integrity testing with documented torque tolerance certification. Boston and Minneapolis anchor cleanroom-certified converter capacity serving hospital system consignment models.
Germany
Pharmaceutical packagers specify glass reverse cap systems for biologics requiring absolute oxygen and moisture exclusion, absorbing premium positioning despite higher logistics costs. EMA Annex 1 guidelines impose particulate and sterility standards that elevate barrier specification requirements. The Rhine-Main cluster around Frankfurt hosts specialized converters with ISO 14644 Class 7 certification for parenteral packaging.
Brazil
ANVISA's tightening traceability requirements for serialized closures create first-mover advantage for converters with integrated tamper-evident and authentication features. Generic drug manufacturers in São Paulo and Rio de Janeiro drive volume demand for cost-optimized plastic reverse cap bottles. Local converters are retrofitting lines to meet serialization mandates ahead of regulatory deadlines.
France
Premium cosmetics brands in the Île-de-France region migrate toward glass primary containers with polymer overcaps, displacing all-plastic reverse cap bottles in high-margin fragrance segments. REACH restrictions on phthalate plasticizers force polypropylene formulation changes across converter networks. Paris-based luxury houses command unit cost multiples through aesthetic differentiation and tactile closure engineering.
Switzerland
Swissmedic regulations for pharmaceutical packaging align with EMA standards while imposing additional quality system requirements for exported products. Basel and Zurich host precision molders serving both domestic pharmaceutical manufacturers and cross-border supply into German and French markets. These converters specialize in composite glass-polymer hybrid constructions for high-value liquid formulations.
Reverse Cap Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower tooling portfolios. The market structures around three tiers: global converters with multi-regional healthcare certification, regional specialists with single-market regulatory depth, and commodity molders serving food and beverage applications. Strategic archetypes include cleanroom-certified pharmaceutical specialists, asset-light mid-tier suppliers leveraging equipment leasing, and vertically integrated film-to-closure platforms. Competitive moves concentrate on M&A for regulatory certification portfolios and capacity expansion in Brazilian and Southeast Asian pharmaceutical corridors.
Among diversified packaging platforms, Amcor leverages its global film and closure network to sustain multi-regional supply contracts, while Berry Global anchors North American capacity through dedicated healthcare packaging facilities. Silgan Holdings occupies a position within metal closure integrated manufacturing, competing via in-house production lines synchronized with bottle forming operations. These three exemplify distinct strategic postures: Amcor represents network breadth, Berry Global exemplifies regional healthcare depth, and Silgan Holdings anchors materials-integrated verticality.
| Leading Market Players |
|---|
| AptarGroup |
| Mondi Group |
| Amcor |
| Bericap |
| Berry Global |
| Silgan Holdings |
| Green Rush Packaging |
| Closure Systems International |
| Ball Corporation |
| Others |
Value Network & Pricing Analysis
Cleanroom-certified capacity scarcity in Germany and the United States drives supplier pricing power while forcing buyers into long-term offtake commitments. This utilization asymmetry rewards incumbents with ISO 14644 Class 7 certification and compresses margins for generalist converters locked out of pharmaceutical-grade contracts.
Pricing Analysis
Configured-to-order pricing for EMA Annex 1-compliant reverse cap systems commands substantial premiums over standard screw cap configurations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates converters by certification investment and thread precision capability. Cost compression in commodity plastic bottles is intensifying because polypropylene feedstock volatility destabilizes contract pricing. Generic drug packagers exhibit highest price sensitivity, while biologics manufacturers absorb premium positioning for glass-polymer hybrid systems.
Supply Chain Analysis
Contract manufacturing concentration among cleanroom-certified converters in Germany, the United States, and Switzerland governs pharmaceutical-grade supply availability. Propylene monomer, precision tooling steel, and medical-grade colorants constitute critical input dependencies. Single-source vulnerability around ISO 14644 Class 7 certified facilities in the Rhine-Main cluster creates acute supply risk for European biologics packagers. Distribution runs through hospital system consignment models in the Northeast and Midwest United States, bypassing traditional wholesale channels for high-specification closures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse cap bottles represent a service-attach opportunity where embedded engineering support and rapid specification iteration generate recurring revenue streams expanding faster than unit hardware sales. Hospital system consignment models and direct-to-pharmacy distribution layers are capturing margin pools that commodity converters cannot access.
For Market Incumbents:Insulate pharmaceutical-grade positioning by acquiring cleanroom-certified capacity in Brazil ahead of ANVISA serialization mandates. Backward integration into precision thread tooling production reduces dependency on scarce qualified engineers and defends against asset-light mid-tier suppliers leasing injection-molding equipment.
For New Entrants and Emerging Players:Pursue Brazilian generic drug packaging contracts where local converters lag in integrated tamper-evident and authentication feature capabilities. ANVISA's tightening traceability requirements create white-space for first-movers with serialized closure systems. Direct sales to São Paulo-based manufacturers bypasses established wholesale relationships.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting downward across asset-light mid-tier suppliers leveraging equipment leasing models, compressing returns for traditional cleanroom-heavy investments. Target acquisition archetype: regional specialists with single-market regulatory depth and existing healthcare certification portfolios. Monitor propylene monomer price volatility as inflection indicator for converter margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Acquisition | ISO 14644 Class 7 status unlocks pharmaceutical contracts with 18-24 month validation barriers. |
| Bio-based Polypropylene Qualification | ISCC PLUS certification secures qualified supplier status for European renewable content mandates. |
| Direct-to-Pharmacy Distribution | Hospital system consignment models reduce inventory carrying costs and accelerate specification feedback. |
| Embedded NFC Integration | Connected packaging layers digitize authentication workflows for high-value biologics supply chains. |
| Precision Tooling Capability Buildout | In-house thread machining expertise addresses acute scarcity of 0.05 mm tolerance engineers. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging engineers, cleanroom facility managers, hospital procurement directors, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 21 CFR Part 211 guidance documents, EMA Annex 1 guidelines, ANVISA serialization mandates, and customs trade data for polypropylene resin flows. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across material, closure, and end-use segments.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside cases reflecting regulatory enforcement intensity and feedstock price trajectories. Segmentation dimensions modeled include material grade tier, closure engineering complexity, end-use certification requirements, and regional regulatory cluster. CAGRs derived from installed base expansion rates and replacement demand cycles, incorporating pharmaceutical pipeline data and cosmetics brand launch calendars as industry-specific inputs.
Sensitivities concentrate around ANVISA enforcement timelines, REACH plasticizer restriction scope expansion, and propylene monomer price volatility. Forecasts reflect documented assumptions on cleanroom certification adoption curves and serialization technology penetration rates. Quarterly review of hospital system procurement consolidation indicators and bio-based polymer certification uptake is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Canada Plastic Caps and Closures Market
Caps and Closures
Overcaps Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Cap Seals Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Plastic Tamper Evident Closures Market