
 Snap-On Closures Market | 2026-2036
Snap-On Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Snap-On Closures Market Outlook
Subscription-based closure auditing and predictive maintenance software is restructuring how converters monetize their installed base. Silgan Holdings Inc anchors North American beverage packaging through captive blow-molding and closure manufacturing. Bericap GmbH & Co. KG dominates European dairy and water segments with high-cavitation HDPE molding lines. AptarGroup Inc differentiates in pharmaceutical dispensing through elastomeric liner technology and child-resistant certification depth.
Snap-on closures are mechanical fastening devices that engage a container finish through radial interference fit, typically requiring 15-30 Newtons of disengagement force and incorporating tamper-evident bands or induction seals for product integrity. They serve primary containment functions across liquid, semi-solid, and dry goods distribution chains. Flip top formats lead in personal care and on-the-go beverage applications where single-handed operation commands shelf preference. Plastic resins—particularly polypropylene and HDPE—sustain the largest material share though metal overcaps retain premium positioning in spirits and cosmetic gift sets. Pharmaceutical vials represent the fastest-growing application vector as biologic drugs multiply and regulatory serialization requirements harden packaging specifications.
FDA 21 CFR regulations on child-resistant packaging and EU MDR traceability mandates compel closure manufacturers to validate torque-release profiles and integrate serialization-ready geometries. REACH restrictions on phthalate plasticizers and emerging PFAS limits under EPA TSCA Section 5 are forcing resin reformulation roadmaps across European and American supply bases. Stakeholders must monitor how California SB 54 extended producer responsibility rules and EU Packaging and Packaging Waste Regulation revisions cascade into minimum recycled content thresholds that reshape material economics and tooling investments.
Market Dynamics
Pharmaceutical serialization mandates and biologic drug proliferation are compressing closure specification cycles, forcing molders to retool for smaller lot sizes and integrated tamper-evident features.
Growth Catalysts
- EU MDR traceability mandates:Medical device packaging must now embed unique device identifiers directly into closure geometries, driving replacement demand across European pharma contract manufacturers.
- Biologic drug expansion:Temperature-sensitive protein therapies require elastomeric-lined closures with validated gas barrier properties, creating specification premiums for qualified suppliers.
- Precision molding clusters in Germany:Concentrated tooling expertise around Stuttgart and Munich enables rapid prototype-to-production cycles for cosmetic and pharma packers seeking customization.
Market Restraints
- HDPE resin price volatility:Feedstock linkage to natural gas liquids exposes margin structures to petrochemical cycle swings, particularly affecting high-cavitation dairy closure producers.
- PFAS regulatory limits:EPA TSCA Section 5 notification requirements and emerging state-level prohibitions are forcing fluoropolymer liner reformulations with uncertain performance validation timelines.
- Substitution by pump dispensers:Personal care brands are migrating viscous formulations from snap-on jars to airless pump systems, compressing addressable volume in skincare segments.
Strategic Opportunities
- Underpenetrated Indian pharma packaging:CDSCO's alignment with ICH Q1 stability guidelines is accelerating domestic biologic manufacturing, creating demand for imported closure validation expertise.
- Subscription-based auditing software:Converters can monetize installed base relationships through predictive maintenance platforms that reduce unplanned downtime for beverage bottlers.
- California SB 54 compliance services:Extended producer responsibility rules mandate post-consumer recycled content thresholds, positioning early adopters to capture premium pricing from brands seeking regulatory safe harbor.
Industry Challenges
- Multi-cavity mold validation timelines:FDA 21 CFR child-resistant certification requires torque-release testing across production variance, extending qualification periods for new pharmaceutical closure designs.
- Legacy ERP integration with serialization:Track-and-trace data exchange between closure molding cells and downstream packaging lines demands middleware investment that mid-tier converters struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap-On Closures Market |
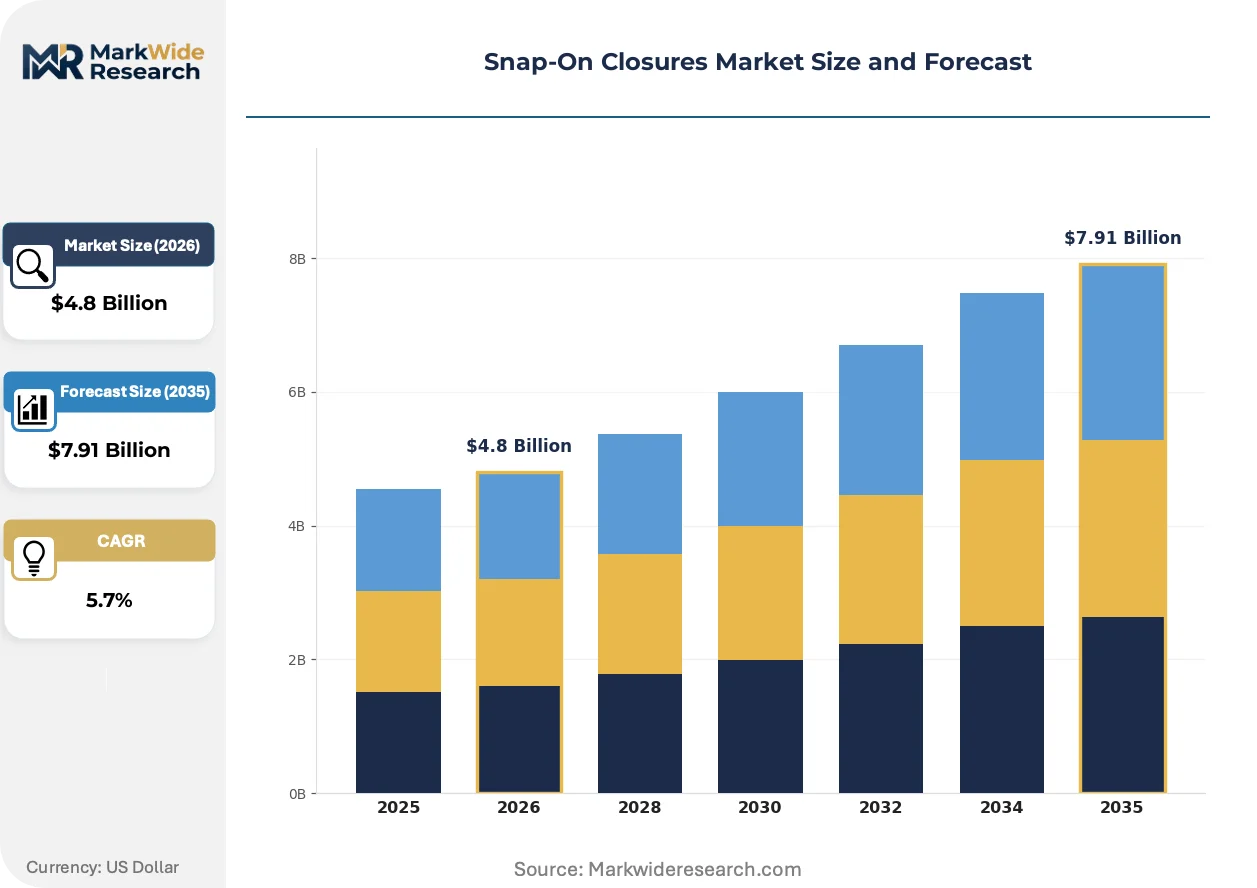
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Screw Cap, Snap Cap, Push-Pull Cap Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Application: Beverage Packaging, Cosmetic Containers, Pharmaceutical Vials, Household Cleaners |
| Companies Covered | Berry Global Inc, Silgan Holdings Inc, AptarGroup Inc, Amcor plc, Closure Systems International Inc, Bericap GmbH & Co. KG, Mold-Rite Plastics LLC, Weener Plastics Group BV, O.Berk Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap-On Closures Market Strategic Shifts
Digital thread technologies and regulatory serialization requirements are converging to transform how closure manufacturers validate quality and manage post-market traceability obligations.
High-cavitation electric molding is automating changeover sequences and cavity-specific process control, enabling pharmaceutical converters to run smaller validated batches without manual intervention. Medical device packers in Germany and Switzerland are adopting these cells to satisfy EU MDR lot-size flexibility requirements. The technology is automating compliance documentation generation, compressing audit preparation cycles from weeks to hours.
REACH restrictions on phthalate plasticizers are compelling resin suppliers to commercialize bio-based alternative formulations with equivalent elastomeric performance. Compounders must revalidate gas permeation coefficients and compression set properties under accelerated aging protocols. Pharmaceutical vial applications face the steepest reformulation burden, as EMA guidelines require demonstration of extractables profiles across the product shelf life.
Direct-to-brand procurement models are disintermediating traditional distribution channels for specialty cosmetic closures, with contract packers in France and Italy establishing preferred supplier agreements that bypass regional distributors. These arrangements consolidate specification authority with brand technical teams and compress commercial negotiation cycles. Personal care segments exhibit the most pronounced channel consolidation, driven by sustainability scorecard requirements that demand direct supplier accountability.
Snap-On Closures Market Segmentation
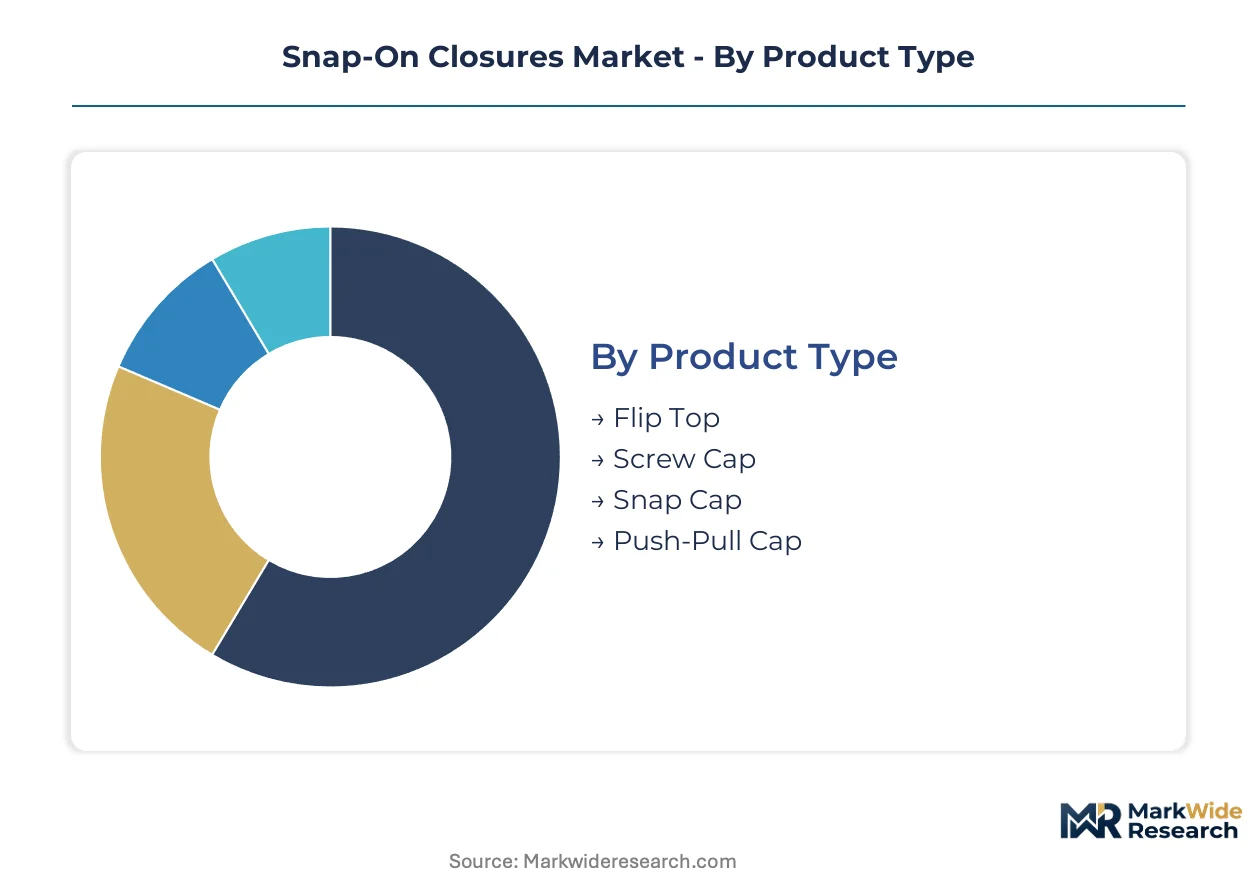
Snap-on closure procurement hinges on torque-release profiles, barrier properties, and regulatory serialization readiness. Specification cycles compress as pharmaceutical and cosmetic brands demand validated geometries for biologic containment and tamper-evident compliance. Segmentation reveals how material selection and format design diverge across containment-critical versus convenience-driven applications.
Product Type:
Single-handed operation requirements and child-resistant mandates dominate buyer specification priorities.
- Flip Top:Hinged lid designs integrate living-hinge polypropylene construction with 180-degree articulation cycles exceeding 10,000 repetitions. Demand concentrates in on-the-go beverage and personal care segments across Germany and France, where single-handed dispensing commands shelf placement premiums.
- Screw Cap:Continuous thread formats with induction-seal compatibility dominate wine and spirits containment. Italian and Spanish bottlers specify aluminum-laminate liners for oxygen barrier performance in premium olive oil and vinegar distribution.
- Snap Cap:Radial interference-fit designs with audible engagement feedback serve dairy and water segments. High-cavitation molding lines in Bavaria supply European contract packers with sub-0.5-second cycle times.
- Push-Pull Cap:Bimodal actuation mechanisms combine child-resistant locking with adult-accessible dispensing. Sports nutrition and isotonic beverage brands in Switzerland specify these formats for gym-channel distribution.
Volume sits with Screw Cap; growth tilts toward Flip Top.
Material:
REACH compliance timelines and recycled content thresholds reshape resin procurement strategies.
- Plastic:Polypropylene and HDPE sustain the largest specification share through chemical resistance and induction-seal compatibility. German automotive-adjacent compounders supply pharma-grade resins with validated extractables profiles for EMA submission.
- Metal:Aluminum and tinplate overcaps retain premium positioning in spirits gift sets and cosmetic limited editions. French perfume houses specify brushed-finish closures with embossed brand cresting.
- Glass:Ground-glass stopper formats persist in laboratory reagent and high-purity solvent containment. Swiss specialty chemical distributors specify borosilicate closures for thermal shock resistance.
- Composite:Multi-material laminates combine plastic structural bodies with metal decorative overwraps. Italian cosmetic packers source these for sustainability scorecard compliance without sacrificing premium aesthetics.
Plastic captures current volume; composite formulations gain share fastest.
End User:
Regulatory stringency and lot-size flexibility requirements segment buyer technical sophistication.
- Food & Beverage:Extended shelf-life dairy and aseptic juice applications specify oxygen-scavenging liners and tamper-evident bands. Bavarian dairy cooperatives validate closure torque profiles across high-speed filling lines exceeding 60,000 units hourly.
- Pharmaceuticals:Biologic drug proliferation demands elastomeric-lined closures with validated gas barrier and extractables documentation. CDSCO-aligned Indian manufacturers import European validation expertise for domestic insulin and monoclonal antibody packaging.
- Personal Care:Viscous formulation compatibility and airless pump substitution pressure define specification trade-offs. French skincare brands migrate premium serums from snap-on jars to pump dispensers, compressing closure addressable volume.
- Household Products:Chemical resistance and child-resistant certification dominate bleach and ammonia containment. UK contract packers specify HDPE closures with induction seals for e-commerce leakage liability mitigation.
Food & Beverage holds installed volume; pharmaceuticals show steepest expansion trajectory.
Application:
Distribution channel integrity requirements and consumption occasion patterns dictate format selection.
- Beverage Packaging:Carbonation retention and pasteurization compatibility specifications span water, dairy, and alcoholic segments. Italian prosecco producers specify mushroom-shaped closures with wire cages for pressure containment.
- Cosmetic Containers:Premium unboxing experience and refill compatibility drive decoration and reclosure engineering. German sustainable beauty brands specify mono-material PP closures for recyclability certification.
- Pharmaceutical Vials:Lyophilization compatibility and autoclave sterilization resistance qualify closure elastomers. Swiss injectable drug manufacturers validate silicone oil migration profiles across freeze-thaw cycles.
- Household Cleaners:Trigger spray and snap-cap formats compete for surface disinfectant and laundry additive containment. Spanish retail chains specify closures with flow-control orifices for dosing precision.
Beverage Packaging anchors current volume; pharmaceutical vials climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision molding clusters across Germany and Switzerland, while consumption spreads across pharmaceutical contract manufacturers in India and beverage bottlers in Italy. This geographic split shapes trade flows and regulatory compliance burdens differently across supply chain nodes.
Germany
Stuttgart and Munich host dense networks of high-cavitation molders serving cosmetic and pharma contract packers with rapid prototype-to-production cycles. EMA guidelines on extractables documentation compel resin suppliers to validate bio-based plasticizer alternatives. Bavarian dairy cooperatives operate filling lines exceeding 60,000 units hourly, validating closure torque profiles under EU food contact regulations.
United States
FDA 21 CFR child-resistant certification requirements extend qualification timelines for new pharmaceutical closure designs. California SB 54 extended producer responsibility rules mandate post-consumer recycled content thresholds, forcing resin reformulation roadmaps. Midwest beverage bottlers specify induction-seal compatibility for extended shelf-life dairy and aseptic juice applications.
India
CDSCO alignment with ICH Q1 stability guidelines accelerates domestic biologic manufacturing, creating demand for imported closure validation expertise. Maharashtra and Gujarat-based pharma contract manufacturers seek elastomeric-lined closures for insulin and monoclonal antibody packaging. Central government PLI scheme incentives support packaging material localization efforts.
Switzerland
Swissmedic regulations govern injectable drug packaging validation, including silicone oil migration profiling across freeze-thaw cycles. Basel-area biologic drug manufacturers specify lyophilization-compatible closures with autoclave sterilization resistance. Precision molding expertise in the Lake Geneva region serves temperature-sensitive protein therapy containment requirements.
Italy
Prosecco producers in Veneto specify mushroom-shaped closures with wire cages for pressure containment under Italian wine consortium standards. Cosmetic packers in Milan and Florence establish direct procurement agreements with specialty closure fabricators, bypassing traditional distribution channels. Emilia-Romagna-based olive oil bottlers specify aluminum-laminate liners for oxygen barrier performance.
Snap-On Closures Market Competitive Environment
Top-tier vendors anchor pharmaceutical and beverage segments through captive molding capacity and regulatory certification depth, while mid-tier specialists occupy customization-intensive cosmetic and personal care niches. The vendor base stratifies across three archetypes: integrated packaging conglomerates with blow-molding and closure manufacturing, precision molding specialists serving pharma validation requirements, and regional fabricators focused on high-speed dairy and water applications. Competitive moves center on M&A to secure molding technology portfolios and capacity expansion in high-cavitation electric molding cells.
Among integrated packaging conglomerates, Berry Global Inc and Amcor plc exemplify scale-driven positions spanning multiple containment formats and geographic markets. Silgan Holdings Inc occupies a North American anchor role through beverage packaging integration. Within European precision molding, Bericap GmbH & Co. KG and Weener Plastics Group BV represent high-cavitation specialists serving dairy and water segments. AptarGroup Inc sits within the pharmaceutical certification tier, differentiated through elastomeric liner technology and child-resistant validation depth. Closure Systems International Inc and Mold-Rite Plastics LLC illustrate mid-cap positions across beverage and household product applications.
| Leading Market Players |
|---|
| Berry Global Inc |
| Silgan Holdings Inc |
| AptarGroup Inc |
| Amcor plc |
| Closure Systems International Inc |
| Bericap GmbH & Co. KG |
| Mold-Rite Plastics LLC |
| Weener Plastics Group BV |
| O.Berk Company LLC |
| Others |
Value Chain & Pricing Dynamics
California SB 54 extended producer responsibility mandates gate qualified supply access and premium-tier pricing power, as converters demonstrating recycled-content compliance capture preferential procurement from brands seeking regulatory safe harbor while non-compliant suppliers face volume exclusion from major beverage and personal care accounts.
Pricing Analysis
Margin tightening in pharmaceutical-grade closures reflects multi-cavity mold validation timelines extending FDA 21 CFR child-resistant certification periods. Three-tier pricing structure across premium, standard, and economy levels separates elastomeric-lined biologic containment from dairy snap-caps and commodity water closures. Cost-down pressure on standard-tier HDPE formats accelerates because resin price volatility linked to natural gas liquids exposes high-cavitation producers to petrochemical cycle swings. Dairy cooperatives in Bavaria exhibit highest price sensitivity; Swiss injectable drug manufacturers show least sensitivity due to validation switching costs.
Supply Chain Analysis
Dual-sourcing requirements from European pharma contract manufacturers mandate qualified backup suppliers for elastomeric-lined closures, compressing single-source dependency risk. Supply concentrates in Germany, Switzerland, and Italy, with Stuttgart precision molding clusters and Basel-area biologic containment specialists anchoring qualified capacity. Raw material dependencies center on pharmaceutical-grade polypropylene resins, bromobutyl elastomer liners, and induction-seal aluminum laminates. Tariff exposure on European-sourced validation expertise threatens Indian CDSCO-aligned manufacturers building domestic biologic packaging capability. Distribution runs through direct-to-brand procurement channels disintermediating traditional regional distributors in French and Italian cosmetic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified molding capacity for pharmaceutical validation represents the binding constraint propping pricing premiums, as EU MDR traceability mandates and FDA child-resistant certification timelines extend qualification periods beyond mid-tier converter resource thresholds.
For Market Incumbents: Extend high-cavitation electric molding cell deployment in German precision clusters to capture EU MDR-driven replacement demand, while deepening elastomeric liner technology portfolios to defend against pump dispenser substitution in personal care segments. Backward integration into pharmaceutical-grade resin compounding secures extractables documentation control for EMA submission requirements. For New Entrants and Emerging Players: Capture underpenetrated Indian pharma packaging demand by importing European closure validation expertise for CDSCO-aligned biologic manufacturers in Maharashtra and Gujarat. White-space concentration sits with domestic insulin and monoclonal antibody containment. Go-to-market leverage rests on regulatory consulting bundled with hardware supply. For Investors and Strategic Acquirers: FDA 21 CFR certification backlogs extending beyond 18 months is the leading indicator that pharmaceutical-grade molding capacity scarcity will persist, supporting premium valuation multiples for qualified assets. Target precision molding specialists with validated elastomeric liner portfolios and existing pharma customer relationships. Watch for CDSCO accelerated biologic approval timelines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| High-Cavitation Electric Molding Deployment | Automates EU MDR compliance documentation generation for pharmaceutical contract manufacturers in Stuttgart clusters. |
| Elastomeric Liner Technology Acquisition | Consolidates gas barrier validation capabilities for temperature-sensitive protein therapy containment requirements. |
| Direct-to-Brand Procurement Channel Development | Bypasses distributor intermediation in French and Italian cosmetic segments where sustainability scorecards demand supplier accountability. |
| Recycled Content Compliance Service Launch | Captures California SB 54 premium pricing from beverage brands seeking extended producer responsibility safe harbor. |
| Indian Regulatory Consulting Integration | Positions imported validation expertise for CDSCO-aligned biologic manufacturers domesticating insulin packaging. |
Study Parameters
Document review covered FDA 21 CFR guidance documents, EMA extractables guidelines, EU MDR technical documentation requirements, and California SB 54 regulatory texts, complemented by interviews with pharmaceutical packaging engineers, cosmetic brand technical sourcing managers, dairy cooperative procurement leads, and high-cavitation molding cell operators. Secondary validation drew from SEC filings of integrated packaging conglomerates, customs trade data on resin imports, and EU food contact regulatory databases. Bottom-up demand modeling across torque-release specification tiers triangulated against top-down macroeconomic drivers.
Segment-level value outputs trace to disaggregated modeling across product type, material grade, end-use regulatory stringency, and geographic production cluster dimensions throughout the forecast period. CAGRs derive from regression analysis of historical specification cycle compression and regulatory mandate implementation timelines. Industry-specific forecast inputs include EU MDR lot-size flexibility requirements and CDSCO biologic manufacturing localization incentives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS regulatory limit expansion under EPA TSCA Section 5 and REACH bio-based plasticizer commercialization timelines. Model outputs reflect assumptions on resin price volatility persistence and pharmaceutical serialization middleware adoption rates. A model refresh is warranted upon material change in FDA child-resistant certification timeline guidance or California SB 54 recycled content threshold enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
IBC Caps Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Cover Caps Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
PET Dome Lids Market