
 Smooth Hinge Caps and Closure Market | 2026-2036
Smooth Hinge Caps and Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Smooth Hinge Caps and Closure Market Outlook
European injection molding capacity is shifting toward high-cavitation tooling for polypropylene hinge closures. Berry Global Inc. leverages backward integration into resin compounding to secure margin control across pharmaceutical and food-grade closure lines. Silgan Holdings Inc. anchors North American supply through dedicated manufacturing platforms serving beverage and personal care brands. AptarGroup Inc. differentiates via precision dosing closure technology that extends into smooth hinge formats for over-the-counter applications.
Smooth hinge caps and closures are mechanical fastening devices manufactured from polypropylene, aluminum, or composite substrates, featuring an integral living hinge that permits repeated opening and closing without material fatigue; they function to secure contents while enabling single-handed access in consumer and industrial environments. Plastic caps dominate volume production due to cost-efficient injection molding scalability, though composite closures are gaining traction where metal barrier properties must combine with polymer flexibility. Magnetic closure technology commands premium positioning in furniture and consumer electronics segments, while snap-fit mechanisms sustain cost-driven demand across automotive interior panels.
FDA regulations govern child-resistant packaging standards that directly shape hinge closure design specifications for pharmaceutical and household chemical applications. EPA guidelines on recycled content thresholds are pressuring converters to certify post-consumer polypropylene streams in closure production. EMA stability testing requirements for drug packaging further tighten material compatibility protocols across European supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks that will recalibrate material selection criteria and recycling infrastructure investments.
Market Dynamics
REACH compliance in the European Union is tightening material certification requirements for plastic closure components, forcing converters to recalibrate resin sourcing and testing protocols across pharmaceutical and food-grade supply chains.
Growth Catalysts
- Child-Resistant Mandates:FDA regulations governing pharmaceutical packaging standards are expanding specification requirements for smooth hinge closures with integrated safety mechanisms, pulling demand from generic alternatives.
- Appliance Premiumization:Chinese domestic manufacturers are specifying magnetic push-to-open closures for refrigerator door systems, creating a new performance tier in consumer durables.
- High-Cavitation Tooling:European injection molding capacity is shifting toward multi-cavity molds for polypropylene hinge closures, compressing unit economics and accelerating throughput.
Market Restraints
- Resin Price Volatility:Polypropylene feedstock costs fluctuate with propylene monomer availability, squeezing margin predictability for converters without backward integration into resin compounding.
- Certification Backlogs:EMA stability testing requirements for drug packaging create extended validation timelines, delaying new product commercialization by quarters.
- Aluminum Substitution Pressure:Metal barrier closures retain niche positioning in oxygen-sensitive applications, limiting plastic penetration in wine and pharmaceutical segments.
Strategic Opportunities
- Extended Producer Responsibility:Evolving EU frameworks will recalibrate material selection criteria, rewarding early movers with certified post-consumer polypropylene streams and recycling infrastructure partnerships.
- Precision Dosing Convergence:Integration of metered-dispense mechanisms with smooth hinge formats opens over-the-counter pharmaceutical applications previously served by separate components.
- India Appliance Assembly:Underpenetrated penetration of premium refrigerator specifications in Indian manufacturing creates whitespace for magnetic closure technology transfer.
Industry Challenges
- Living Hinge Fatigue Expertise:Engineering talent capable of optimizing integral hinge geometry for million-cycle durability remains concentrated among specialized mold designers.
- Multi-Regulatory Parallel Certification:Simultaneous FDA, EMA, and national pharmaceutical authority approvals fragment compliance resources and extend development cycles.
- Legacy Equipment Retrofit Costs:Converting existing injection lines for high-cavitation tooling demands capital outlays that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smooth Hinge Caps and Closure Market |
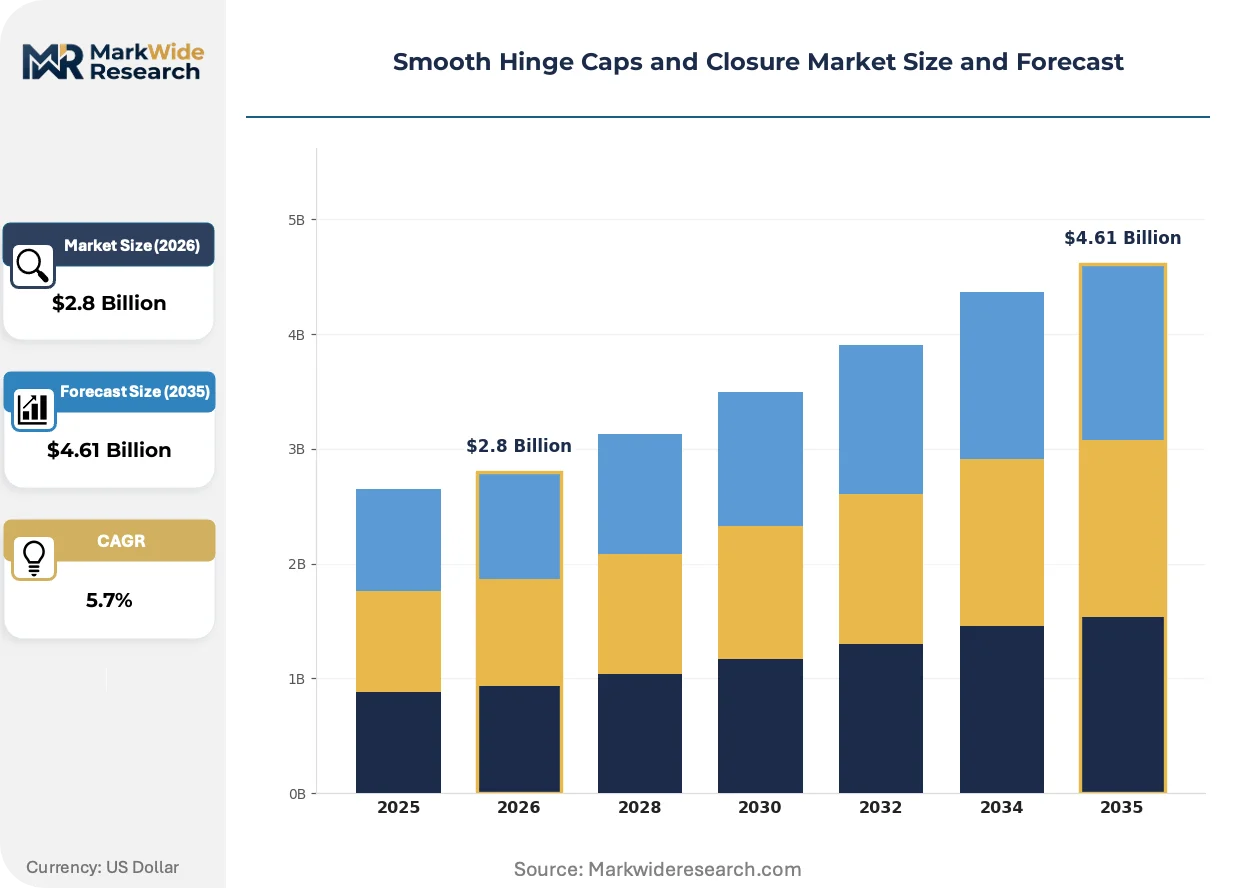
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Metal Caps, Rubber Seals, Composite Closures End User: Consumer Electronics, Automotive, Furniture, Industrial Equipment Closure Technology: Screw-On, Snap-Fit, Magnetic, Push-To-Open Material: Polypropylene, Aluminum, Steel, Silicone |
| Companies Covered | Berry Global Inc., Closure Systems International Inc., Nippon Closures Co Ltd., Interpac International Corporation, B&C Plastics Ltd., Silgan Holdings Inc., AptarGroup Inc., Amcor PLC, Bericap GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smooth Hinge Caps and Closure Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape competitive positioning in closure manufacturing, with sustainability credentials and functional integration emerging as primary differentiation vectors.
Living hinge design software paired with simulation-driven mold flow analysis is overtaking traditional empirical prototyping in closure development cycles. Pharmaceutical packaging engineers in Germany and Switzerland are adopting these tools to compress validation timelines. The structural consequence is a compression of development-to-production intervals from months to weeks for qualified converters.
REACH substance restrictions on phthalates and heavy metal stabilizers in polypropylene compounding are tightening material certification requirements. Converters serving European pharmaceutical and food-grade markets must document supply chain transparency through SCIP database submissions. The segments most affected are child-resistant closures, where alternative stabilizer packages require reformulation and requalification.
Appliance manufacturers are consolidating supplier bases around vertically integrated closure specialists capable of delivering magnetic push-to-open mechanisms with embedded sensor compatibility. Procurement teams at Chinese refrigerator OEMs are awarding multi-year contracts to converters with in-house magnet assembly and electronics integration capabilities. This concentration is most visible in Qingdao and Hefei manufacturing clusters, where premium model specifications now mandate smart closure functionality.
Smooth Hinge Caps and Closure Market Segmentation
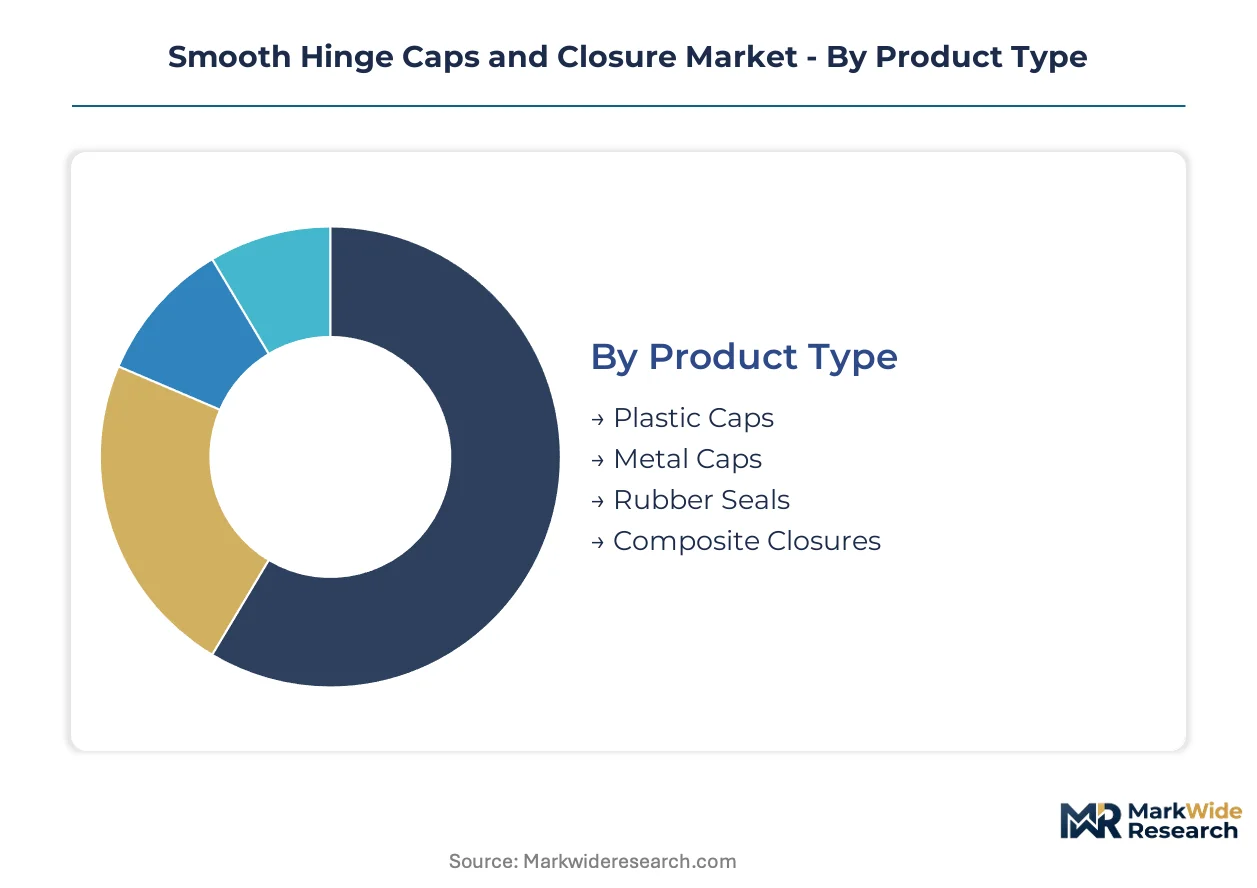
Smooth hinge caps and closures serve divergent performance requirements across pharmaceutical, appliance, and industrial end-uses, making material selection and mechanism design critical commercial variables. Segmentation reveals where converter investments in tooling and certification concentrate, and where emerging specifications are rewriting procurement criteria.
Product Type:
Injection molding capacity for hinge closures clusters around converters with multi-cavity tooling expertise and resin compounding integration.
- Plastic Caps:Polypropylene living hinges dominate volume production through cost-efficient injection molding scalability. Pharmaceutical packaging lines in Germany and household chemical brands in the United States specify child-resistant smooth hinge formats, pulling demand from metal alternatives where barrier properties are secondary.
- Composite Closures:Multi-layer substrates combine metal barrier properties with polymer flexibility for oxygen-sensitive applications. Wine and pharmaceutical segments in France and Italy specify these for extended shelf-life requirements where aluminum alone lacks hinge durability.
- Metal Caps:Aluminum screw-hinge hybrids retain niche positioning in high-barrier pharmaceutical and beverage segments.
- Rubber Seals:Silicone compression elements integrate into hinged assemblies for thermal cycling resistance in automotive and appliance applications.
Plastic caps absorb the bulk of installed capacity; composite closures are expanding most quickly as barrier-plus-flex specifications proliferate.
End User:
Application-driven specification divergence separates premium-tier appliance procurement from cost-optimized automotive interior sourcing.
- Consumer Electronics:Magnetic push-to-open mechanisms with embedded sensor compatibility command premium positioning. Chinese refrigerator OEMs in Qingdao and Hefei manufacturing clusters award multi-year contracts to converters with in-house magnet assembly and electronics integration capabilities.
- Automotive:Snap-fit smooth hinge formats sustain cost-driven demand across interior panel assemblies. Tier-1 suppliers in Germany and Mexico specify polypropylene hinge closures for glove compartment and center console applications where million-cycle durability testing is mandatory.
- Furniture:Concealed hinge closures with soft-close damping specify higher-grade polymer formulations for residential and office cabinetry.
- Industrial Equipment:Metal-reinforced hinge closures serve chemical resistance and impact loading requirements in factory environments.
Consumer electronics claims the steepest expansion trajectory; automotive maintains the largest volume base.
Closure Technology:
Mechanism selection tracks end-use accessibility requirements and regulatory safety mandates across pharmaceutical and appliance segments.
- Magnetic:Push-to-open actuation with embedded neodymium assemblies enables single-handed operation in premium refrigerator and furniture applications. Procurement teams in China and South Korea specify these for smart-home integration where sensor feedback loops are required.
- Push-To-Open:Spring-loaded hinge mechanisms without magnetic components serve mid-tier appliance specifications where cost compression dominates.
- Screw-On:Threaded hinge closures retain pharmaceutical and chemical packaging share where tamper-evidence and child-resistance are regulated.
- Snap-Fit:Integral living hinge geometries enable rapid assembly in automotive and consumer goods where reclosability is secondary to manufacturing throughput.
Screw-on mechanisms retain the largest installed base; magnetic configurations are gaining share fastest in premium appliance tiers.
Material:
Resin sourcing and metal procurement strategies diverge based on REACH compliance burdens and recycled content certification requirements.
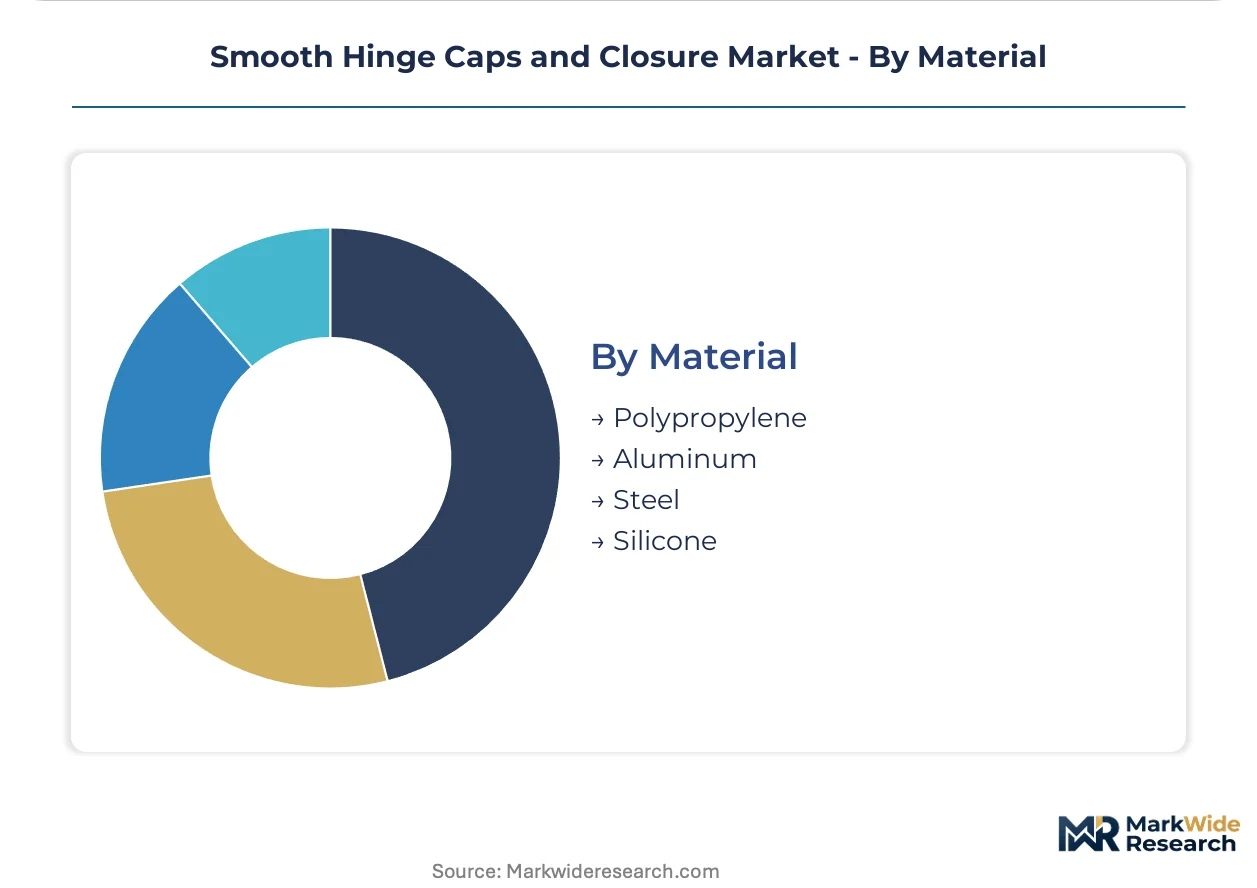
- Polypropylene:Homopolymer and copolymer grades with alternative stabilizer packages dominate living hinge applications. EMA stability testing requirements and REACH substance restrictions on phthalates and heavy metal stabilizers force reformulation and requalification cycles for European pharmaceutical supply chains.
- Aluminum:Barrier-grade alloys with anodized or coated surfaces serve oxygen-sensitive pharmaceutical and wine closures where metal flexibility is engineered through reduced-gauge geometries.
- Steel:Tinplate and chrome-plated substrates retain industrial and select beverage packaging applications.
- Silicone:High-consistency rubber compounds integrate as secondary seals within hinged assemblies for thermal and chemical resistance.
Polypropylene commands the dominant share of material throughput; aluminum maintains defensive positioning in barrier-critical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene monomer availability along the US Gulf Coast anchors North American resin supply for hinge closure converters. German chemical clusters feed European pharmaceutical packaging lines with certified polypropylene compounds. Chinese appliance manufacturing corridors in Shandong and Anhui provinces specify magnetic closure assemblies for premium refrigerator exports.
Germany
Pharmaceutical packaging engineers in Stuttgart and Heidelberg are expanding orders for child-resistant smooth hinge closures with integrated safety mechanisms. REACH compliance through ECHA is tightening material certification requirements for plastic closure components, forcing converters to recalibrate resin sourcing protocols. The Rhine-Main manufacturing cluster hosts specialized mold designers optimizing living hinge geometry for million-cycle durability in medical applications.
United States
FDA regulations governing child-resistant packaging standards are pulling demand toward smooth hinge closures with integrated safety mechanisms across pharmaceutical and household chemical segments. EPA guidelines on recycled content thresholds are pressuring converters to certify post-consumer polypropylene streams in closure production. Berry Global Inc. leverages backward integration into resin compounding to secure margin control across pharmaceutical and food-grade closure lines from its Evansville operations.
China
Domestic appliance manufacturers in Qingdao and Hefei are specifying magnetic push-to-open closures for premium refrigerator door systems with embedded sensor compatibility. SAMR quality certification requirements are tightening for smart-home integrated closure components entering commercial distribution. The Yangtze River Delta manufacturing corridor concentrates injection molding capacity serving both export markets and domestic premium appliance brands.
Japan
Precision dosing closure technology from Osaka and Nagoya engineering centers extends into smooth hinge formats for over-the-counter pharmaceutical applications. METI industrial standards are accelerating validation timelines for pharmaceutical packaging materials with enhanced barrier properties. The Kanto region hosts converters developing composite closures combining metal barrier properties with polymer flexibility for oxygen-sensitive drug packaging.
India
Underpenetrated premium refrigerator specifications in Indian manufacturing create whitespace for magnetic closure technology transfer from established East Asian suppliers. CDSCO pharmaceutical packaging regulations are aligning with international stability testing protocols for drug-contact materials. The Pune-Nashik industrial corridor is emerging as an assembly hub for domestic appliance brands seeking localized closure sourcing.
Smooth Hinge Caps and Closure Market Competitive Environment
Global majors compete with regional champions across pharmaceutical certification and appliance integration capabilities. The vendor base clusters around three strategic tiers: vertically integrated resin compounders with captive molding capacity, specialized closure converters with pharmaceutical regulatory expertise, and appliance-focused assemblers with magnet integration capabilities. Strategic moves concentrate on high-cavitation tooling investments and backward integration into resin compounding to defend margin position.
Within the integrated compounder-molder tier, Berry Global Inc. and Silgan Holdings Inc. exemplify scale-driven positioning through captive resin supply and dedicated manufacturing platforms. AptarGroup Inc. occupies a precision-dosing specialization anchor, representing the technology-convergence archetype where metered-dispense mechanisms integrate with smooth hinge formats. Among Asia-Pacific fabricators, Nippon Closures Co Ltd. and Closure Systems International Inc. sit within the regional champion category, serving domestic appliance OEMs with localized certification and logistics advantages.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Closure Systems International Inc. |
| Nippon Closures Co Ltd. |
| Interpac International Corporation |
| B&C Plastics Ltd. |
| Silgan Holdings Inc. |
| AptarGroup Inc. |
| Amcor PLC |
| Bericap GmbH |
| Others |
Value Chain & Pricing Dynamics
Backward integration into resin compounding anchors pricing power for converters serving pharmaceutical and food-grade closure lines, locking in margin control against propylene monomer volatility while externalizing cost pressure onto non-integrated competitors. This structural divide separates Berry Global's captive supply model from mid-tier converters exposed to spot resin markets.
Pricing Analysis
Service-bundling separates pharmaceutical-grade closures with EMA stability documentation and FDA child-resistant certification from unbundled commodity formats lacking regulatory support. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and volume scale, with premium magnetic push-to-open assemblies commanding substantial premiums over snap-fit automotive interior formats. Cost compression in standard-tier polypropylene hinge closures is intensifying because European REACH compliance forces reformulation cycles. Tier-1 appliance manufacturers in China exhibit lowest price sensitivity; generic household chemical brands sustain highest sensitivity.
Supply Chain Analysis
Regional distribution centers along the US Gulf Coast, Rhine-Main corridor, and Yangtze River Delta concentrate polypropylene resin staging for just-in-time molding operations. Manufacturing draws from propylene feedstock in the United States, Germany, and China, with neodymium magnet assemblies sourcing primarily from Chinese rare earth processors. Single-source vulnerability concentrates in specialized living hinge mold designers concentrated in Stuttgart and Osaka. Distribution runs through converter-direct models for pharmaceutical OEMs and tiered distributor networks for appliance assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is a vertical-integration race where control over resin compounding and high-cavitation tooling capacity determines survival. Players are pursuing upstream resin supply and downstream appliance integration as dual levers.
For Market Incumbents: Lock in multi-year resin supply agreements and expand high-cavitation tooling capacity in Qingdao and Evansville to outpace emerging Asian fabricators. Threat from magnetic closure technology transfer to Indian appliance assembly demands defensive certification investments in CDSCO-aligned stability protocols. Backward integration into magnet assembly capabilities protects premium positioning. For New Entrants and Emerging Players: Begin with underpenetrated precision dosing convergence opportunities in over-the-counter pharmaceutical applications, where AptarGroup's technology leadership has not fully extended. Indian appliance manufacturing corridors around Pune-Nashik offer the most penetrable geography for magnetic closure technology transfer. Go-to-market through partnership with established East Asian magnet suppliers accelerates SAMR qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging conglomerates seeking pharmaceutical regulatory expertise and appliance magnet integration capabilities. Long-term viability hinges on converters with demonstrated EMA/FDA dual certification and living hinge fatigue engineering depth. Watch for REACH substance restriction expansions forcing consolidation among non-compliant mid-tier compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive polypropylene supply secures margin control against monomer volatility. |
| High-Cavitation Tooling Investment | European mold designers compress unit economics for million-cycle pharmaceutical closures. |
| Magnet Assembly Capability Buildout | Chinese refrigerator OEMs award multi-year contracts to converters with in-house neodymium integration. |
| EMA/FDA Dual Certification Investment | Parallel regulatory approval capacity opens pharmaceutical supply chains across Atlantic markets. |
| Smart Closure Electronics Integration | Sensor-compatible push-to-open mechanisms capture premium appliance specifications in Qingdao. |
Study Parameters
Independent corroboration across closure converter executives, pharmaceutical packaging engineers, appliance procurement managers, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EMA stability testing protocols, FDA 510(k) filings, SAMR certification databases, and customs trade records for polypropylene closure components. Bottom-up modeling of injection molding capacity and top-down triangulation against pharmaceutical packaging expenditure flows anchored volume estimates.
Comparable-period anchoring to historical REACH compliance cycles and FDA child-resistant packaging mandate implementations structured the projection horizon. Segmentation dimensions span material substrate, closure technology mechanism, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating appliance premiumization rates and pharmaceutical packaging line expansion. Forecast inputs include propylene monomer supply trajectories and EMA stability testing backlog durations.
Underlying measurement precision varies by segment; pharmaceutical-grade closures with documented regulatory submissions carry tighter precision than speculative appliance smart-closure adoption curves. Forecasts reflect assumptions on REACH substance restriction timelines and rare earth magnet supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
Metal Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Vented Caps Market
Caps and Closures
Crimp Top Cap Market