
 Crimp Top Cap Market | 2026-2036
Crimp Top Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Crimp Top Cap Market Outlook
Pharmaceutical packaging is expanding as the dominant demand vector for crimp top caps, displacing slower-growth food canning segments in investment priority. Silgan Holdings Inc. leverages its metal-forming infrastructure to anchor supply relationships with parenteral drug manufacturers. Crown Holdings Inc. competes through aluminum specialization and tight-tolerance forming capabilities for high-barrier applications. Berry Global Inc. differentiates via composite material science that bridges metal strength with polymer sealing flexibility.
A crimp top cap is a mechanically affixed closure formed by radial compression of a metal skirt around a container neck finish, typically manufactured through deep-drawn aluminum stamping or injection-molded polymer insert assembly, creating a hermetic seal critical for oxygen-sensitive and sterile contents. Metal caps dominate current volume owing to established pharmaceutical validation protocols and inert gas flush compatibility, while composite caps represent the fastest-growing structural category as manufacturers seek to reduce aluminum gauge without sacrificing seal integrity. Plastic caps occupy mature positions in non-sterile chemical and cosmetic bottling where permeation tolerance is wider.
The FDA enforces container closure system integrity standards under 21 CFR 211.94, directly shaping aluminum thickness and elastomer liner specifications for drug applications. The EU MDR and REACH constrain PVC and certain plasticizer chemistries in medical-contact components, redirecting formulation toward polyethylene and steel-reinforced alternatives. Stakeholders must monitor evolving pharmacopeial chapters on extractables and leachables, as these will determine which material segments retain market access across regulated jurisdictions.
Market Dynamics
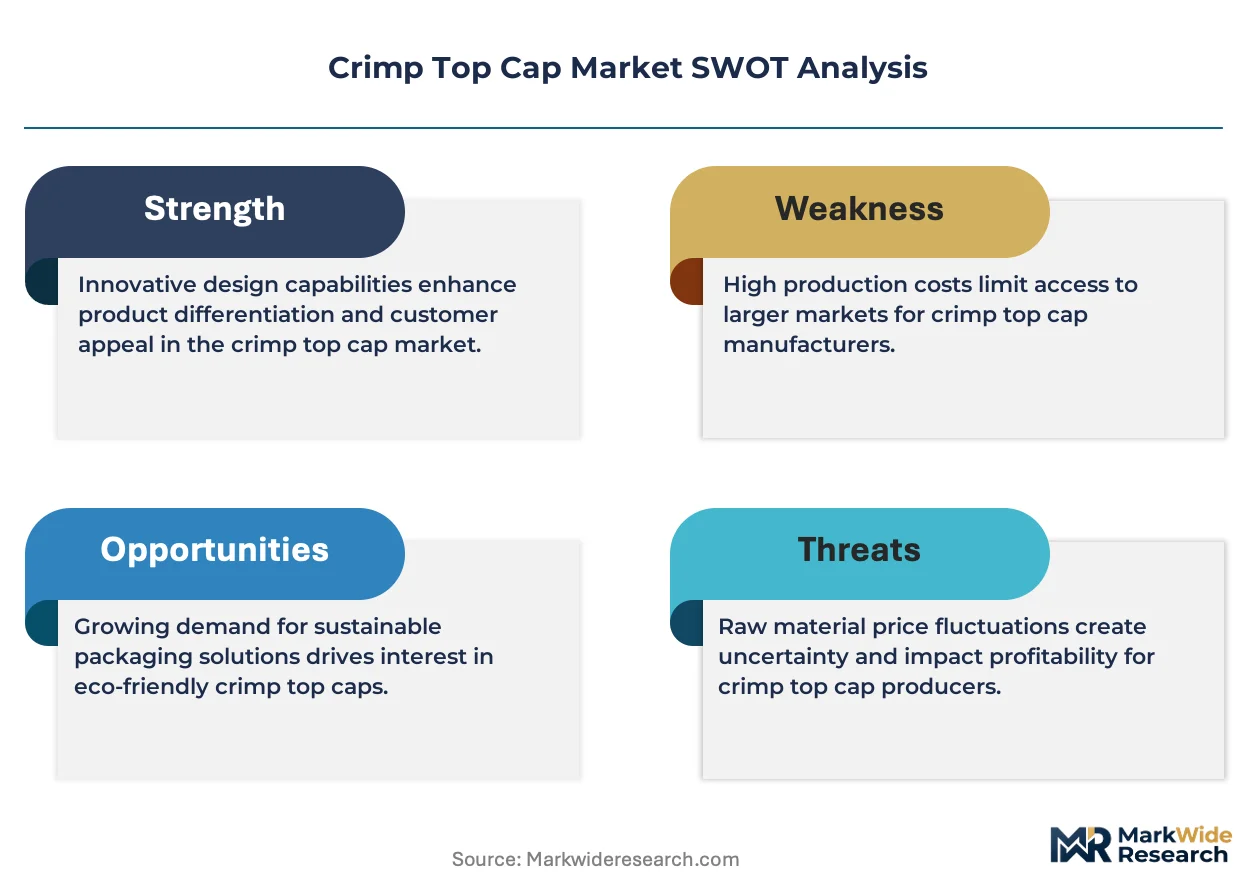
Pharmaceutical container closure integrity standards under 21 CFR 211.94 and EU MDR extractables testing are forcing aluminum gauge reductions and composite material validation cycles across the supply base.
Growth Catalysts
- Biologics fill-finish expansion:Parenteral drug manufacturers in Germany and the United States are scaling sterile vial lines that require validated crimp-cap systems for oxygen-sensitive formulations.
- EU MDR stability mandates:The regulation's container closure integrity requirements are accelerating replacement of legacy PVC-lined caps with polyethylene and elastomer alternatives in European packaging facilities.
- India's contract manufacturing surge:Generic drug production clusters in Hyderabad and Ahmedabad are consuming aluminum crimp caps at volumes that justify dedicated stamping capacity investments.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations compress forming margins and complicate long-term supply agreements for deep-drawn cap manufacturers.
- Specialty elastomer concentration:Bromobutyl and chlorobutyl liner supply concentrates among three global chemical suppliers, creating single-source vulnerability for high-barrier pharmaceutical applications.
- Validation timeline rigidity:FDA stability testing protocols for container closure systems extend new material qualification cycles to 24-36 months, freezing design iterations.
Strategic Opportunities
- Prefilled syringe-to-vial conversion:Biologics manufacturers are revisiting vial formats for high-viscosity formulations, opening crimp-cap demand in fill-finish lines previously dedicated to syringe assemblies.
- REACH-compliant composite platforms:The EU's chemical restrictions are creating first-mover advantage for cap suppliers with validated steel-reinforced polymer constructions that bypass PVC limitations.
- Cold chain distribution expansion:mRNA vaccine logistics requirements in the United States and Europe are prioritizing hermetic seal performance at ultra-low temperatures, favoring aluminum-composite hybrid designs.
Industry Challenges
- Extractables chemist scarcity:Pharmaceutical manufacturers face 18-month recruitment cycles for analytical chemists capable of executing USP Chapter 1664 leachables studies on novel elastomer formulations.
- Legacy line retrofit costs:Converting 20mm and 13mm crimp stations to accommodate reduced-gauge aluminum without jam rates demands capital outlays that mid-tier generic producers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crimp Top Cap Market |
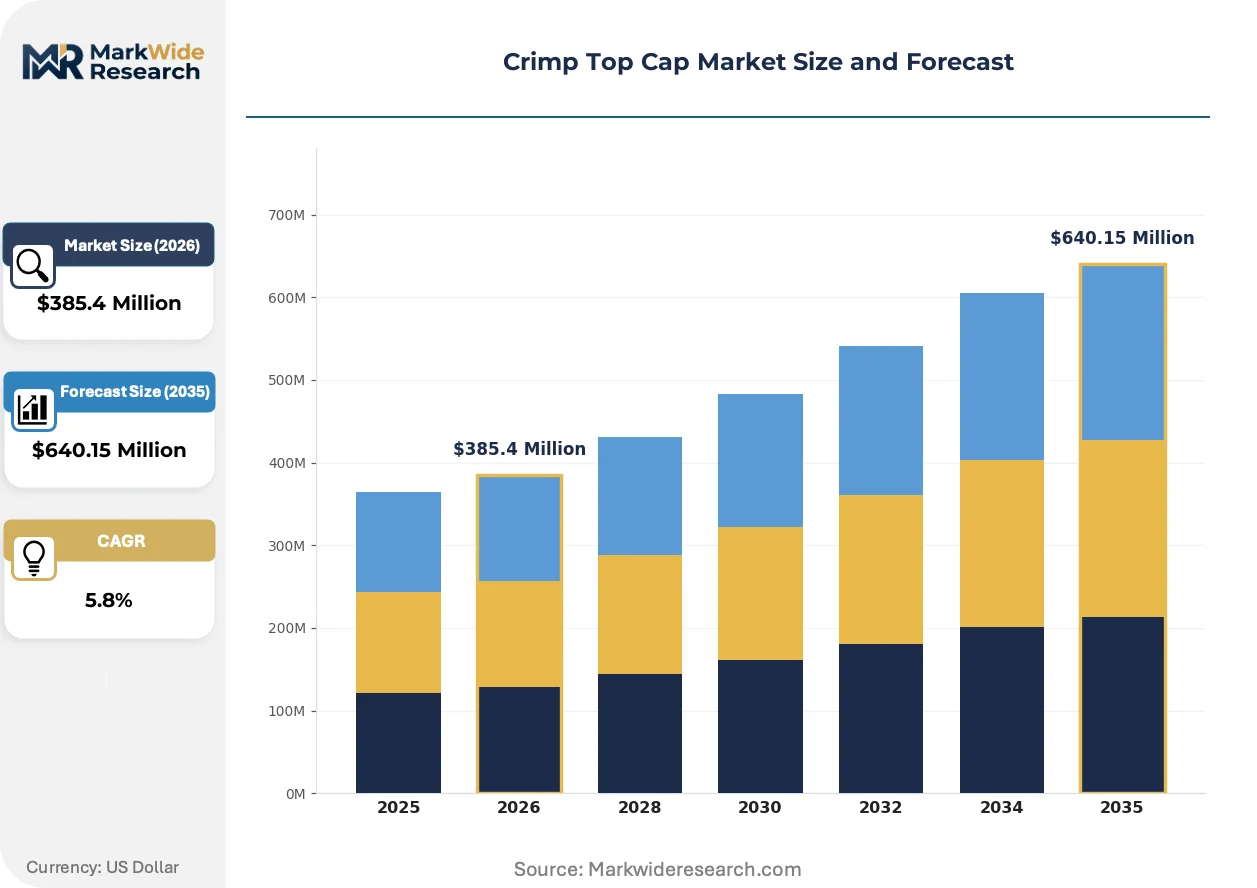
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Metal Caps, Composite Caps, Biodegradable Caps End User: Food and Beverage, Pharmaceuticals, Cosmetics, Chemicals Application: Canning, Bottling, Packaging, Sealing Material: Polyethylene, Aluminum, Steel, PVC |
| Companies Covered | Silgan Holdings Inc., Crown Holdings Inc., Berry Global Inc., Amcor Limited, Specialty Silicone Products, Sigma-Aldrich Co Ltd., Jinan Youlyy Industrial Co., EMA Pharmaceuticals, Closure Systems International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crimp Top Cap Market Strategic Shifts
Material science convergence with regulatory chemistry requirements is compressing traditional aluminum-dominated supply relationships while elevating composite validation capabilities as a competitive differentiator.
Multi-layer co-injection molding for cap inserts is overtaking separate metal-over-polymer assembly in high-volume parenteral applications. German and Swiss fill-finish contractors are adopting these unified constructions to eliminate liner delamination risks during steam sterilization. The technology is overtaking conventional two-piece designs by reducing particle generation and simplifying component traceability.
REACH Annex XVII restrictions on phthalate plasticizers are redirecting liner formulation toward hydrogenated styrenic block copolymers and thermoplastic elastomer alternatives. The European Chemicals Agency's substance evaluation roadmap is forcing compounders to resubmit drug master files for legacy PVC-containing constructions. Pharmaceutical packagers in France and Italy are responding by dual-sourcing elastomer specifications to preempt supply interruption.
Consolidated procurement by global biologics CDMOs is compressing supplier qualification lists and extending master service agreement durations. Tier-one fill-finish operators in Massachusetts and North Carolina are bundling cap, vial, and seal purchasing under single-source technical agreements that lock out smaller metal stampers. This concentration is most visible in United States oncology drug packaging, where three contract manufacturers control a majority of sterile vial throughput.
Crimp Top Cap Market Segmentation
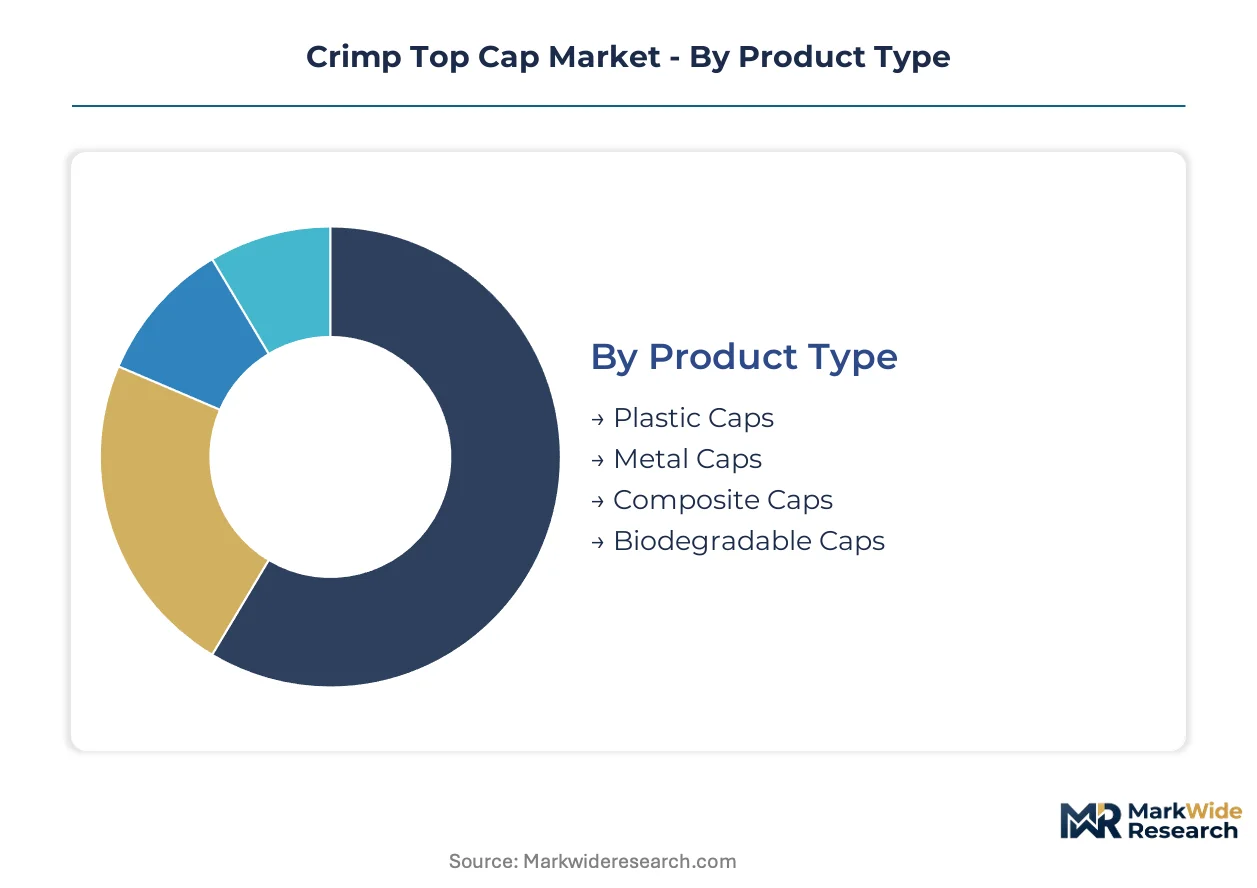
Crimp top cap segmentation reveals divergent technical requirements across pharmaceutical validation protocols, food safety standards, and chemical resistance specifications. Material selection and forming precision determine which suppliers capture volume in regulated versus commodity end-uses.
Product Type:
Standalone metal caps dominate pharmaceutical lines requiring validated hermetic seals, while composite and biodegradable constructions embed polymer science for sustainability-driven conversions.
- Metal Caps:Deep-drawn aluminum or steel stampings with elastomer liners form the benchmark for oxygen-sensitive parenteral drugs. FDA 21 CFR 211.94 validation protocols and inert gas flush compatibility anchor demand in German and United States fill-finish facilities.
- Composite Caps:Steel-reinforced polymer or aluminum-polymer hybrids bridge metal strength with liner flexibility. REACH Annex XVII phthalate restrictions are accelerating polyethylene-based composite adoption across French and Italian packaging lines.
- Plastic Caps:Injection-molded polyethylene or polypropylene constructions serve non-sterile chemical and cosmetic bottling where permeation tolerance permits polymer-only seals.
- Biodegradable Caps:PLA and starch-based alternatives target single-use food canning applications with limited shelf-life requirements.
Metal caps lead volumes today; composite caps are gaining share fastest.
End User:
Cost tier stratification separates validated pharmaceutical systems from commodity food and chemical closures, with cosmetics occupying a mid-tier precision position.
- Pharmaceuticals:Sterile vial and ampoule sealing for biologics, vaccines, and parenteral drugs demands aluminum or composite caps with documented container closure integrity. EMA stability mandates and USP Chapter 1664 extractables testing concentrate procurement among qualified suppliers in Massachusetts and North Carolina contract manufacturing clusters.
- Food and Beverage:Acidic and low-acid canning applications utilize tinplate or aluminum caps with compound liners for hermetic preservation. FDA low-acid canned food regulations govern thermal processing compatibility.
- Chemicals:Solvent-resistant aluminum or steel caps with fluoropolymer liners seal agrochemical and industrial reagent containers. Chemical resistance specifications vary by UN dangerous goods classification.
- Cosmetics:Premium fragrance and skincare bottling employs aluminum caps with decorative finishes and controlled torque specifications for pump dispenser integration.
Pharmaceuticals command premium pricing tiers; food and beverage generates the highest unit volumes.
Application:
Application maturity varies from century-old canning processes to precision bottling automation requiring micron-level forming tolerance.
- Canning:Double-seam and roll-on capping for preserved foods utilizes formed metal caps with plastisol or rubber-based sealing compounds. Thermal processing cycles dictate liner compound selection.
- Bottling:Vial, bottle, and jar sealing across pharmaceutical, cosmetic, and chemical sectors requires crimp-head compatibility with 13mm, 20mm, and 28mm neck finishes.
- Packaging:Secondary and tertiary containment applications include overcap and transit protection functions with reduced seal integrity requirements.
- Sealing:Specialized hermetic and tamper-evident closures for diagnostic reagents and reference standards prioritize oxygen and moisture barrier performance.
Bottling leads volumes today; canning is expanding most slowly amid container format shifts.
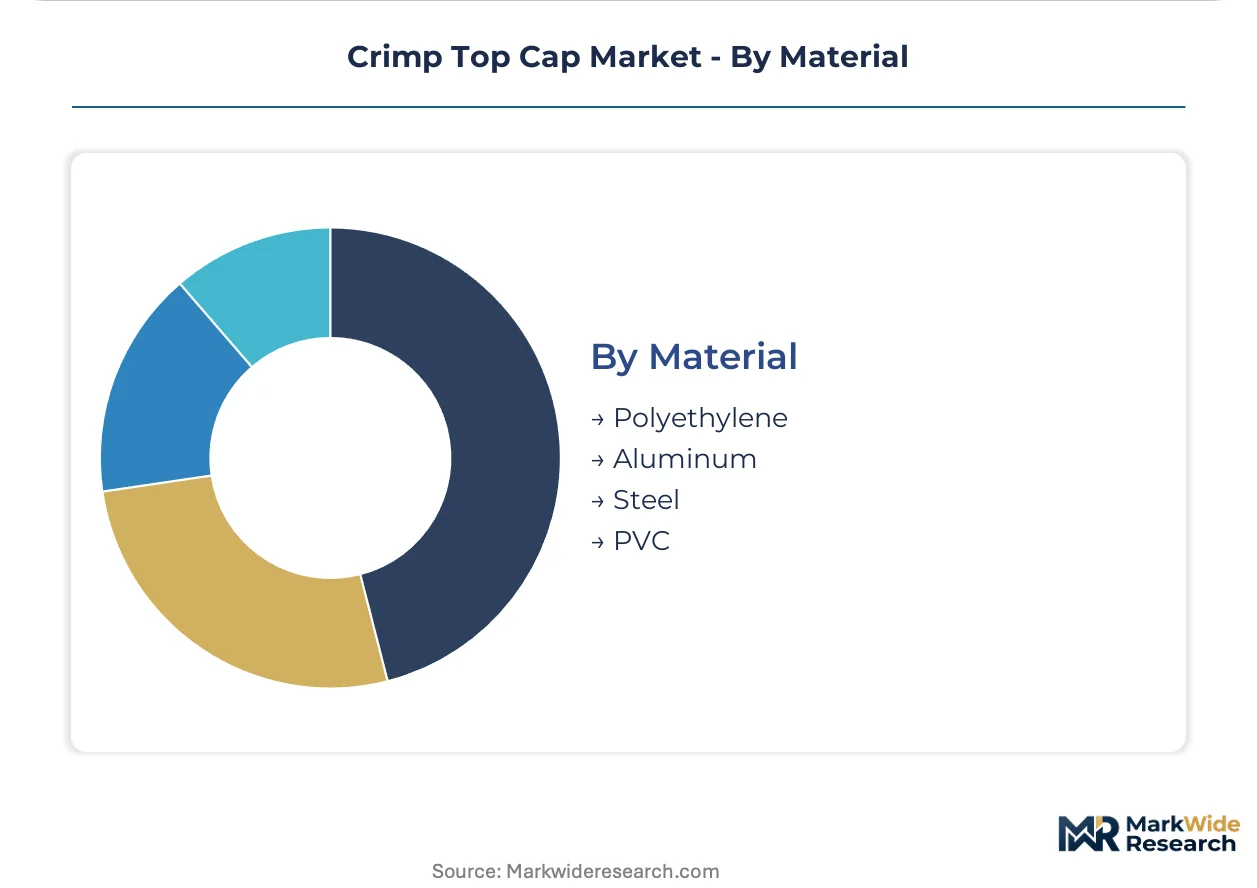
Material:
Supply concentration and price volatility differentiate aluminum from polymer alternatives, with PVC facing regulatory displacement.
- Aluminum:Deep-drawn 1050 and 3003 alloy stampings provide lightweight, corrosion-resistant shells for pharmaceutical and food applications. LME price volatility compresses forming margins and complicates long-term supply agreements.
- Polyethylene:High-density and linear low-density polyethylene liners and cap bodies substitute for PVC in REACH-compliant constructions. Hydrogenated styrenic block copolymers are displacing legacy plasticizer formulations.
- Steel:Tinplate and chrome-plated steel caps serve high-temperature canning applications where aluminum softening limits performance. European tinplate supply concentrates among integrated steel producers.
- PVC:Plasticized polyvinyl chloride liners face ECHA substance evaluation and EU MDR restrictions, redirecting formulation toward polyethylene and thermoplastic elastomer alternatives.
Aluminum leads volumes today; polyethylene is climbing the fastest on regulatory substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting crimp-cap manufacturing toward jurisdictions with streamlined pharmaceutical validation pathways. The United States and Germany absorb premium-tier volumes through CDMO concentration, while India and China capture scale-driven contract manufacturing.
United States
FDA 21 CFR 211.94 container closure standards and biologics fill-finish expansion drive demand. Massachusetts and North Carolina oncology drug packaging clusters concentrate sterile vial throughput among three dominant contract manufacturers. CDMO procurement bundling is compressing supplier qualification lists.
Germany
EMA stability mandates and EU MDR extractables testing accelerate aluminum-gauge reduction programs. Baden-Württemberg and Bavaria host precision metal-forming facilities serving parenteral drug manufacturers. Multi-layer co-injection molding adoption is overtaking conventional two-piece designs.
India
Generic drug export growth and CDSCO manufacturing license expansion scale aluminum crimp-cap consumption. Hyderabad and Ahmedabad production clusters justify dedicated stamping capacity investments. Contract manufacturing surge concentrates demand among export-oriented packaging facilities.
China
NMPA pharmaceutical packaging material registration requirements and domestic biologics capacity expansion reshape supply relationships. Yangtze River Delta metal-forming infrastructure serves both domestic and export fill-finish operations. REACH-compliant composite platform development is accelerating.
Switzerland
Swissmedic inspection intensity and high-value biologics packaging standards sustain premium-tier demand. Basel-region fill-finish contractors specify tight-tolerance aluminum-composite hybrids for oxygen-sensitive formulations. Cold chain distribution requirements favor hermetic seal performance at ultra-low temperatures.
Crimp Top Cap Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical validation capabilities determining tier placement. The supplier base concentrates among metal-forming conglomerates with pharmaceutical-grade certification and composite material science specialists. Three archetypes dominate: integrated metal-packaging conglomerates, polymer science specialists, and regional stamping operations serving generic drug producers. Capacity expansion and regulatory compliance investments constitute the primary competitive moves.
Within the integrated conglomerate tier, Silgan Holdings Inc. and Crown Holdings Inc. occupy positions defined by deep-drawn aluminum infrastructure and established pharmaceutical customer relationships. Berry Global Inc. exemplifies the polymer-composite archetype, bridging metal strength with liner flexibility. Regional fabricators including Jinan Youlyy Industrial Co. anchor contract manufacturing supply into Indian and Chinese generic drug packaging clusters.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Crown Holdings Inc. |
| Berry Global Inc. |
| Amcor Limited |
| Specialty Silicone Products |
| Sigma-Aldrich Co Ltd. |
| Jinan Youlyy Industrial Co. |
| EMA Pharmaceuticals |
| Closure Systems International Inc. |
| Others |
Value Chain & Pricing Dynamics
CDMO procurement bundling in Massachusetts and North Carolina oncology packaging clusters is compressing supplier margins and forcing metal stampers to absorb aluminum volatility through long-term master service agreements.
Pricing Analysis
Distributor margins on validated pharmaceutical-grade caps run 12-18 points above commodity food canning equivalents. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated aluminum systems from REACH-compliant composites and generic tinplate constructions. Cost compression in standard-tier composites is intensifying because polyethylene liner compounders face dual-sourcing mandates. Generic drug manufacturers in India exhibit highest price sensitivity; Swiss biologics packagers show least.
Supply Chain Analysis
India's domestic-content thresholds for pharmaceutical packaging under CDSCO manufacturing license rules are redirecting stamping capacity toward Hyderabad and Ahmedabad production clusters. Deep-drawn aluminum coil feeds from Germany, China, and the United States anchor shell production. Bromobutyl and chlorobutyl liner supply rests on three global chemical suppliers, creating single-source vulnerability for high-barrier applications. Distribution runs through fill-finish contractors and packaging distributors to drug manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Crimp Top Cap Market compounds steadily as biologics fill-finish expansion sustains validated closure demand across regulated jurisdictions.
For Market Incumbents: Lock in master service agreement extensions with tier-one CDMOs before composite validation cycles complete. Backward integration into elastomer compounding secures liner supply against chemical supplier concentration. Crown capacity additions in Baden-Württemberg and Silgan's pharmaceutical-grade certification depth defend against regional stampers in India. For New Entrants and Emerging Players: The premium-to-economy price gap in European REACH-compliant composites opens white-space for validated steel-reinforced polymer platforms. Target mid-tier generic producers in India facing legacy line retrofit costs with reduced-gauge aluminum-plus-polymer hybrid offerings. Pursue direct technical qualification with fill-finish contractors bypassing distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with composite material science specialists bridging metal-forming and polymer chemistry capabilities. Five-to-ten year viability hinges on extractables testing capacity expansion ahead of pharmacopeial chapter revisions. Watch EMA substance evaluation roadmaps for PVC liner disqualification signals.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Platform Validation | REACH Annex XVII compliance secures European market access against PVC displacement. |
| Elastomer Compounding Backward Integration | Captive bromobutyl supply insulates against three-supplier concentration risk. |
| Reduced-Gauge Aluminum Capacity Expansion | Baden-Württemberg stamping investments serve EMA stability mandate compliance. |
| Multi-Layer Co-Injection Molding Adoption | German fill-finish contractors specify unified constructions eliminating delamination. |
| CDMO Technical Agreement Bundling | Massachusetts oncology packaging clusters compress supplier lists to three qualified sources. |
Study Parameters
Direct dialogue with pharmaceutical packaging procurement managers, fill-finish operations directors, elastomer compounders, and regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FDA 21 CFR filings, EMA marketing authorization databases, USP Chapter 1664 guidance documents, and CDSCO manufacturing license records. Bottom-up volume builds across aluminum gauge tiers, liner chemistries, and neck finish specifications triangulated against top-down pharmaceutical packaging expenditure estimates.
Segment-level outputs across metal, composite, plastic, and biodegradable cap types, plus pharmaceutical, food, chemical, and cosmetic end-uses, fed into the analytical framework. CAGRs derived from elasticity-adjusted demand projections tied to biologics fill-finish line expansion and generic drug export growth trajectories. Aluminum LME price scenarios and elastomer supply concentration factors shaped sensitivity bounds.
Caveats apply where FDA stability testing protocol revisions or EMA extractables threshold changes could materially shift the outlook. Forecasts embed assumptions on CDMO procurement concentration and REACH enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Tube Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Bag Closures Market
Caps and Closures
Dauber Caps Market
Caps and Closures
Case Closures and Sealers Market