
 Thailand Plastic Caps and Closures Market | 2026-2036
Thailand Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Plastic Caps and Closures Market Insights
Artisanal bottled-water startups and regional juice processors is collapsing as the dominant buyer archetype, displacing legacy mass-market carbonated soft drink bottlers that long dictated volume contracts. Crown Seal Public Company Limited anchors domestic production through its integrated metal-and-plastic closure campus in Pathum Thani. Berry Global Inc. competes via specialized dispensing cap lines serving personal care multinationals with Thai manufacturing footprints. Aptar Group Inc. differentiates through precision-molded flip-top and pump closures for pharmaceutical and cosmetic applications.
Plastic caps and closures are injection- or compression-molded thermoplastic components engineered to seal containers against contamination, leakage, and oxidation, with thread pitch, torque release, and oxygen transmission rate as critical performance parameters. Screw caps dominate unit volume across Thailand's bottled water and cooking oil sectors due to cost efficiency and resealability. Dispensing caps represent the fastest-expanding material category as household care and personal care brands adopt controlled-flow formats for convenience positioning. Polypropylene commands widening preference over polyethylene in hot-fill and retort applications where thermal stability determines seal integrity.
Thai FDA food-contact notifications and Industrial Product Standards (TISI) certifications govern migration limits and material traceability for closures touching consumable goods. The Pollution Control Department's escalating restrictions on single-use plastics and microplastic leakage are forcing reformulation toward bio-based polypropylene and thinner-wall designs. Stakeholders must monitor how ASEAN harmonization of packaging Extended Producer Responsibility frameworks reshapes material qualification timelines and recycling infrastructure investments.
Market Dynamics
Thai FDA migration from PVC to polypropylene food-contact standards is compressing material qualification timelines and forcing reformulation investments across domestic molding operations.
Growth Catalysts
- Hot-fill polypropylene adoption:Thermal stability requirements in retort cooking oil packaging are accelerating polypropylene displacement of polyethylene. Thai bottlers in Pathum Thani industrial zones are qualifying thinner-wall designs for oxygen transmission rate compliance.
- ASEAN Extended Producer Responsibility harmonization:Draft frameworks for packaging waste accountability are creating material traceability mandates. Closure producers are investing in blockchain-linked resin sourcing to preempt compliance deadlines.
- Tamper-evident dispensing formats:Personal care multinationals with Thai manufacturing footprints are specifying precision-molded flip-top closures for controlled-flow positioning in household care segments.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and regional refinery maintenance cycles inject margin uncertainty into polypropylene pellet contracts.
- Pathum Thani production concentration:Crown Seal's integrated campus anchors domestic screw cap supply, creating single-source vulnerability for mass-market bottled water contracts.
- Recycling infrastructure gap:Thailand's mechanical recycling capacity for polypropylene closures lags behind bio-based resin pilot volumes, limiting circularity claims.
Strategic Opportunities
- Rayong industrial zone expansion:Bottling operations serving ASEAN export markets are underserved for pharmaceutical-grade child-resistant closures, creating white space for precision molders.
- Pollution Control Department bio-based mandates:Escalating single-use plastic restrictions are creating procurement preferences for bio-polypropylene closures in municipal water contracts.
- Smart closure integration:Near-field communication tags and freshness indicators are converging with injection-molding processes for premium beverage authentication.
Industry Challenges
- TISI certification timeline compression:Industrial Product Standards food-contact testing queues are extending material qualification cycles, delaying product launches for reformulated resins.
- Hot-runner mold capex intensity:Thin-wall polypropylene designs for oxygen barrier performance require precision hot-runner systems, straining mid-tier molder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Plastic Caps and Closures Market |
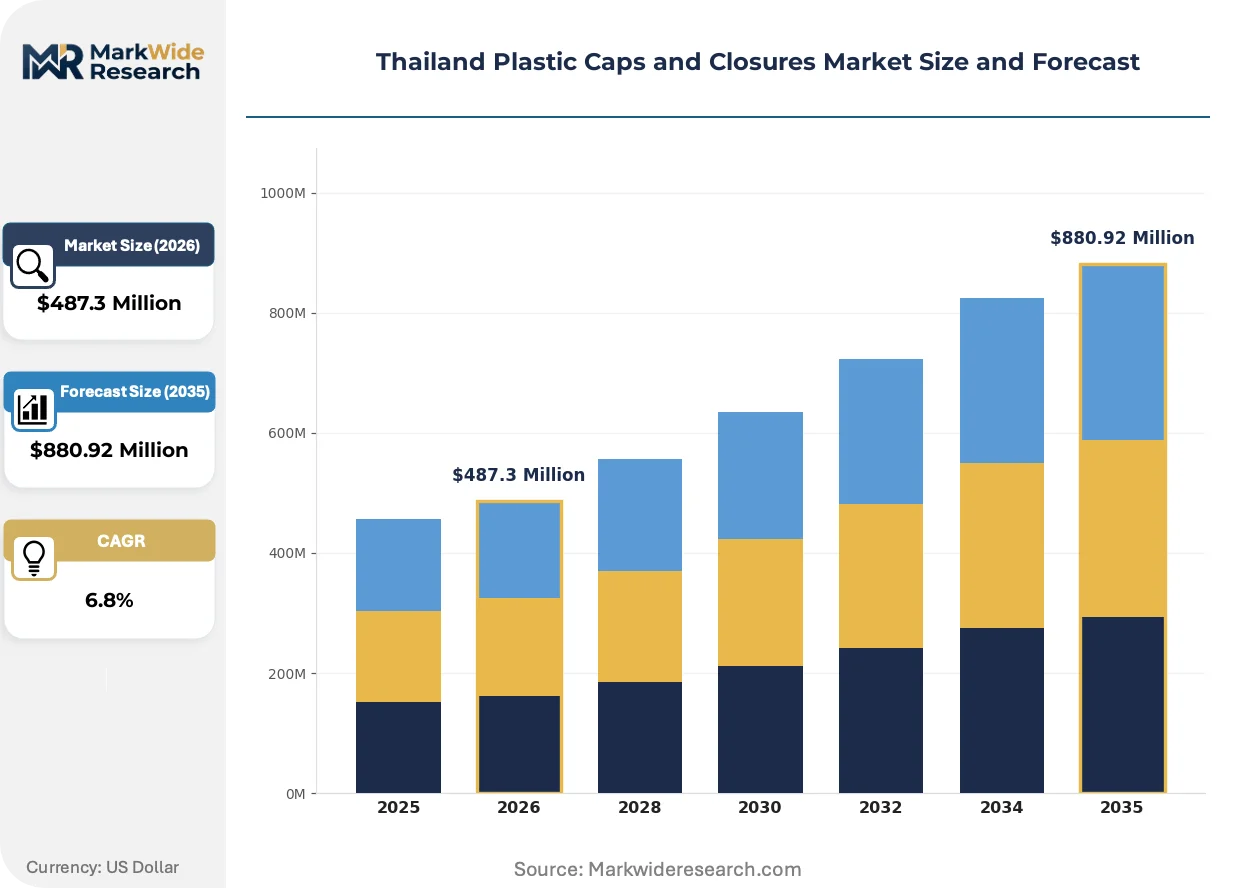
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
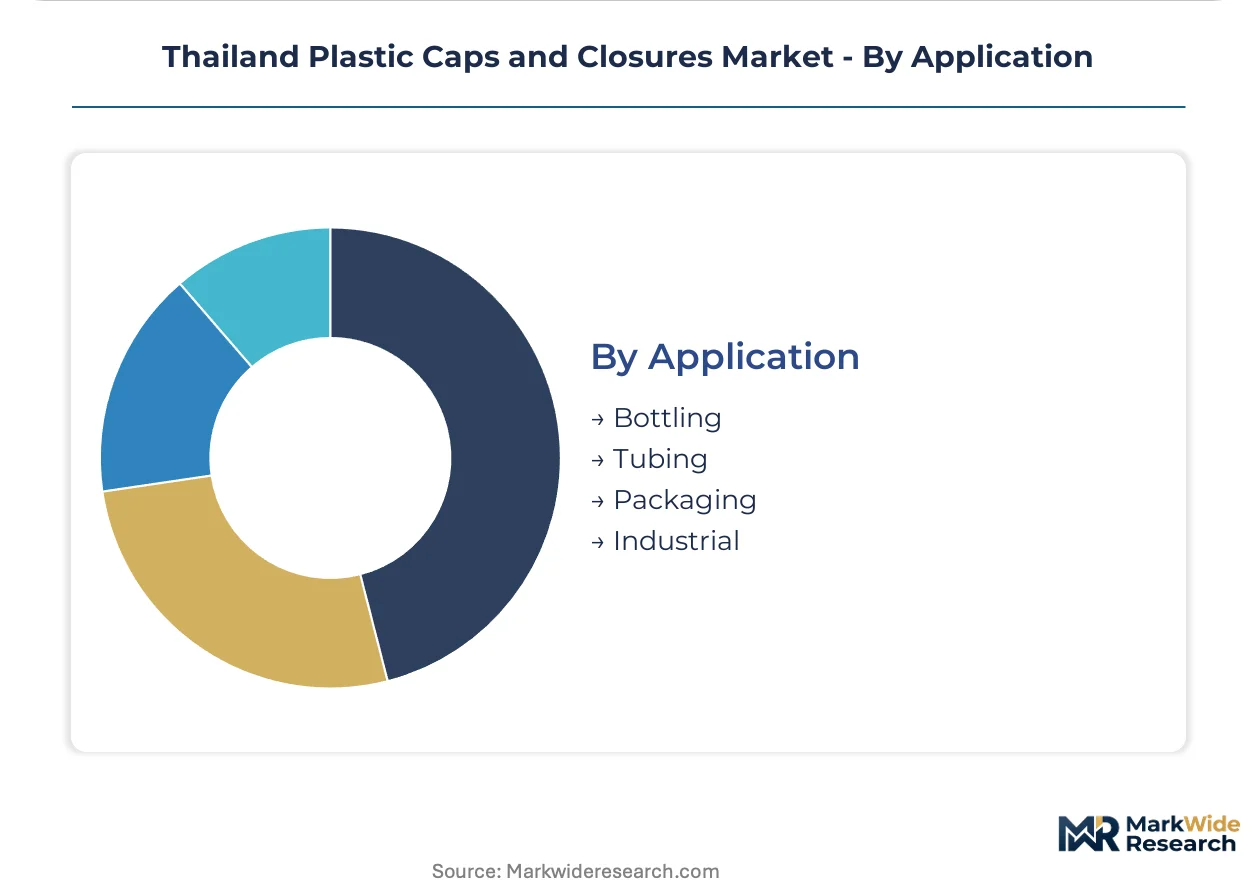
| Segmentation | Product Type: Screw Caps, Snap Caps, Dispensing Caps, Tamper Evident Caps Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Healthcare, Personal Care, Household Care Application: Bottling, Tubing, Packaging, Industrial |
| Companies Covered | Crown Seal Public Company Limited, Berry Global Inc., Aptar Group Inc., Tetra Pak International SA, Precision Plastic Co. Ltd., Amcor Group GmbH, Berli Dynaplast Co. Ltd., Weener Plastics Group B.V., Silgan Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Plastic Caps and Closures Market Trends and Innovations
Material science advances and regulatory tightening are compressing closure geometries while expanding functional integration, reshaping competitive advantage around precision molding rather than volume scale.
Thin-wall polypropylene technology is miniaturizing closure geometries without sacrificing torque release performance. Artisanal bottled-water startups in Bangkok are adopting sub-1.5 gram screw caps for lightweighting claims. The technology is miniaturizing material throughput per unit, compressing resin cost structures for premium positioning.
Thai FDA food-contact notification requirements are tightening migration limit documentation for polypropylene alternatives. Closure producers must now submit resin batch traceability records for hot-fill applications. Pharmaceutical and cosmetic segments are responding by qualifying dedicated medical-grade molding cells to segregate compliance risk.
Buyer concentration among regional juice processors is collapsing contract structures that long favored mass-market carbonated soft drink bottlers. Direct procurement relationships with co-manufacturers are displacing distributor-mediated volume agreements. This pattern is most visible in Chiang Mai, where craft beverage brands specify custom tamper-evident formats through direct mold-development contracts.
Thailand Plastic Caps and Closures Market Segmentation

Segmentation in Thailand's plastic caps and closures market reveals how procurement channels fragment across performance tiers and compliance requirements. Channel mix varies sharply by end-use sophistication, with pharmaceutical and premium beverage buyers demanding dedicated supply chains distinct from mass-market bottled water procurement.
Product Type:
Channel distribution splits between direct mold-development contracts for custom formats and distributor-mediated bulk procurement for standardized designs.
- Screw Caps:Threaded thermoplastic closures engineered for torque release and resealability, typically injection-molded in polypropylene or polyethylene. Mass-market bottled water bottlers in Pathum Thani industrial zones source these through high-volume annual contracts, though thin-wall lightweighting is compressing per-unit resin costs.
- Dispensing Caps:Controlled-flow closures incorporating flip-top hinges, pump mechanisms, or directional spouts for measured product release. Personal care multinationals with Thai manufacturing footprints specify precision-molded variants through direct technical partnerships, bypassing traditional distribution layers.
- Snap Caps:Press-fit closures relying on interference fit rather than thread engagement, common in single-serve dairy and condiment applications.
- Tamper Evident Caps:Integral break-ring or shrink-band designs providing visible post-manufacture breach indication, mandatory for pharmaceutical and premium beverage segments.
By volume, Screw Caps leads. By growth pace, Dispensing Caps is expanding most quickly.
Material:
Cost tier stratification separates commodity resins from performance grades requiring specialized thermal stability or migration compliance documentation.
- Polypropylene:Semi-crystalline thermoplastic with superior hot-fill tolerance and oxygen barrier performance versus polyethylene. Thai FDA food-contact notifications are accelerating displacement of PVC alternatives, with Pathum Thani molders qualifying thinner-wall designs for retort cooking oil packaging.
- Polyethylene:Lower-density alternative dominating cold-fill applications where thermal stress is absent. Mass-market bottled water contracts favor this grade for cost efficiency, though hot-fill migration is eroding share in premium segments.
- Polyvinyl Chloride:Legacy food-contact material facing accelerated phase-out under Thai FDA tightening of migration limit standards.
- Polystyrene:Rigid amorphous polymer limited to non-food applications and cosmetic jars where clarity and dimensional stability outweigh impact resistance requirements.
Polypropylene commands premium positioning. Polyethylene retains volume dominance in commodity segments.
End User:
Customer type determines specification intensity, with pharmaceutical and food-contact buyers imposing traceability mandates absent in industrial applications.
- Food & Beverage:Dominant demand concentration spanning bottled water, cooking oil, and regional juice processing. Bangkok and Chiang Mai craft beverage brands are collapsing legacy distributor relationships in favor of direct mold-development contracts for custom tamper-evident formats.
- Healthcare:Pharmaceutical-grade requirements including child-resistant and senior-friendly closure mechanisms. Rayong industrial zone bottling operations serving ASEAN export markets remain underserved for this specification tier.
- Personal Care:Precision dispensing and aesthetic surface finish requirements drive specification toward specialized molding cells.
- Household Care:Chemical resistance and controlled-flow functionality for cleaning product applications.
Food & Beverage generates the highest unit volumes. Healthcare shows the steepest specification escalation.
Application:
Geographic concentration within Thailand aligns application mix with industrial zone capabilities and export corridor access.
- Bottling:Container sealing for liquid and semi-liquid products across beverage, pharmaceutical, and personal care segments. Central Plains corridor operations cluster around Rayong and Pathum Thani for domestic consumption and ASEAN export fulfillment.
- Packaging:Secondary containment and portion-control formats beyond conventional bottle sealing, including pouch fitments and flexible package closures.
- Tubing:Squeeze-tube dispensing closures for cosmetic and pharmaceutical cream applications.
- Industrial:Non-food-contact chemical and lubricant container sealing with reduced regulatory documentation burdens.
Bottling anchors production scale. Packaging applications are gaining share fastest through flexible format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's plastic caps and closures production flows primarily toward ASEAN export corridors, with Vietnamese and Indonesian bottlers absorbing substantial volumes from Rayong and Pathum Thani manufacturing clusters.
Central Plains Corridor
Pathum Thani industrial zones concentrate domestic screw cap fabrication for mass-market bottled water contracts. Thai FDA food-contact notifications are accelerating PVC-to-polypropylene migration timelines for cooking oil retort packaging. Crown Seal's integrated campus anchors regional supply security for carbonated soft drink bottlers.
Eastern Economic Corridor
Rayong province hosts expanding pharmaceutical-grade closure demand from ASEAN export-oriented bottling operations. Pollution Control Department bio-based procurement mandates are reshaping municipal water contract specifications. Precision molders are qualifying child-resistant formats for underserved healthcare segments.
Bangkok Metropolitan Area
Craft beverage brands in Bangkok and Chiang Mai are collapsing legacy distributor relationships for direct mold-development contracts. Artisanal bottled-water startups specify custom tamper-evident formats through technical partnerships. Thin-wall lightweighting claims are compressing per-unit resin costs below 1.5 grams.
Northern Region
Chiang Mai juice processors are displacing mass-market carbonated soft drink bottlers as dominant buyer archetypes. Regional craft brands demand precision-molded flip-top closures for controlled-flow positioning. Direct procurement relationships with co-manufacturers are eliminating traditional volume contract structures.
Thailand Plastic Caps and Closures Market Competitive Landscape
Player mix skews toward integrated domestic fabricators with metal-and-plastic closure capabilities alongside multinational specialists in precision dispensing formats. Market structure concentrates around Crown Seal's Pathum Thani campus for commodity screw caps while fragmenting across specialized molders for pharmaceutical and personal care applications. Two strategic archetypes dominate: integrated domestic producers with captive resin sourcing and multinational precision specialists with dedicated medical-grade molding cells. Competitive moves center on hot-runner mold capacity expansion and blockchain-linked resin traceability investments for ASEAN Extended Producer Responsibility compliance.
Among Thailand-based integrated producers, Crown Seal Public Company Limited anchors domestic supply security through its Pathum Thani campus. Multinational precision specialists include Berry Global Inc. and Aptar Group Inc., which occupy positions serving personal care and pharmaceutical segments respectively. These three entities exemplify the bifurcation between scale-driven commodity fabrication and specification-intensive custom molding.
| Leading Market Players |
|---|
| Crown Seal Public Company Limited |
| Berry Global Inc. |
| Aptar Group Inc. |
| Tetra Pak International SA |
| Precision Plastic Co. Ltd. |
| Amcor Group GmbH |
| Berli Dynaplast Co. Ltd. |
| Weener Plastics Group B.V. |
| Silgan Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for polypropylene resin lock in supply access for Pathum Thani molders while capping price visibility against propylene feedstock swings. Thai FDA migration timelines compress material qualification cycles, forcing buyers to pre-commit volumes before reformulation costs stabilize.
Pricing Analysis
Thin-wall polypropylene technology commands a 15-20% premium over conventional screw cap designs due to hot-runner mold complexity and oxygen barrier certification. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade child-resistant closures from mass-market bottled water caps and industrial chemical seals. Pricing pressure stems from naphtha-cracking margin volatility eroding pellet contract stability. Mass-market bottled water bottlers exhibit highest price sensitivity, while pharmaceutical and cosmetic segments absorb premiums for traceability documentation.
Supply Chain Analysis
Thailand and South Korea anchor regional polypropylene resin supply for closure fabrication, with Singapore and Japan providing specialty additive packages for hot-fill thermal stability. Domestic molding operations draw from ASEAN naphtha crackers and Middle Eastern propylene imports, with carbon black and UV stabilizers sourced from China and Taiwan. Single-source vulnerability concentrates in Crown Seal's Pathum Thani campus for commodity screw caps. Distribution runs through direct technical partnerships for pharmaceutical and personal care segments, while mass-market bottled water relies on distributor-mediated bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision hot-runner mold capacity represents the critical scarcity asset in this market, separating specification-intensive suppliers from commodity fabricators. Players lacking medical-grade molding cells or blockchain-linked resin traceability systems face disqualification from pharmaceutical and ASEAN EPR-compliant contracts.
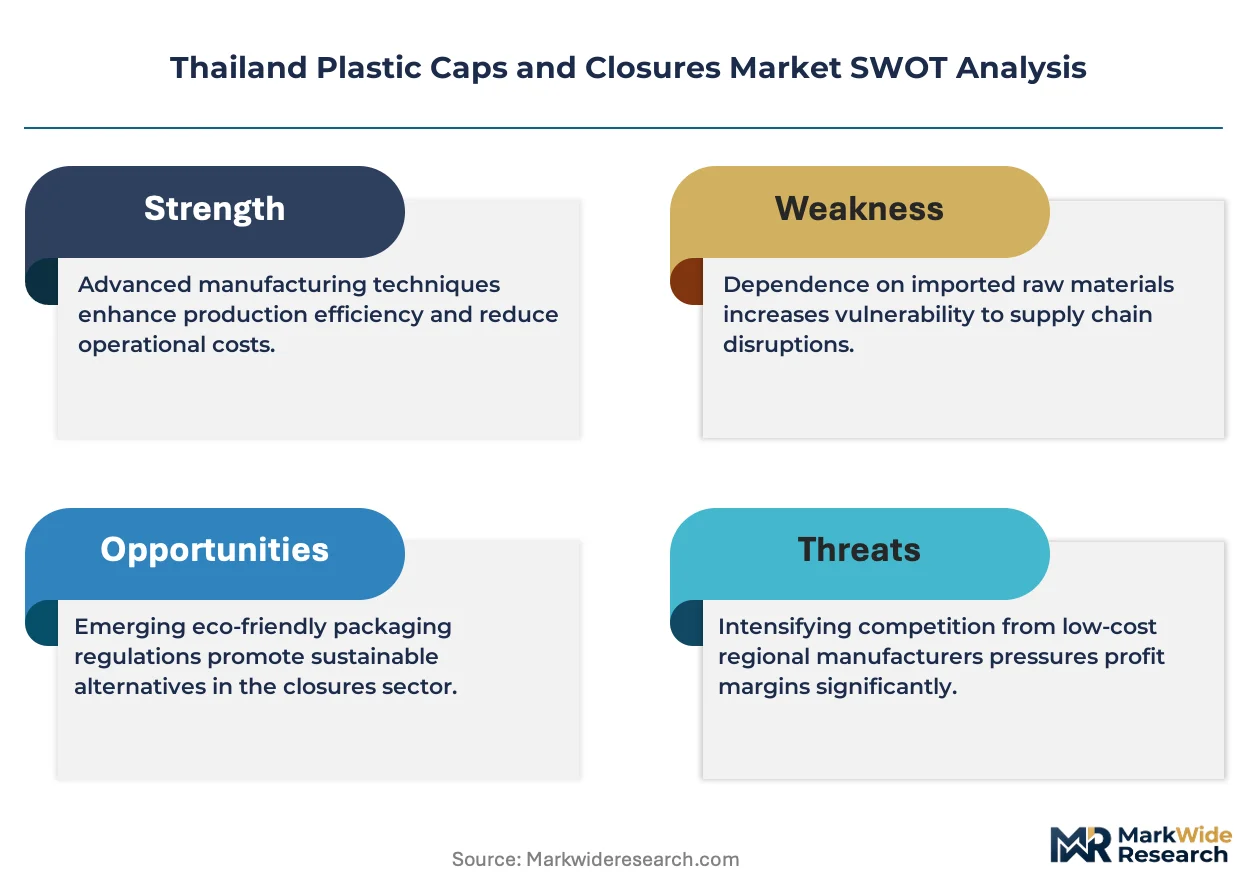
For Market Incumbents: Shield mass-market bottled water contracts through backward integration into polypropylene compounding, preempting feedstock volatility exposure. Accelerate hot-runner mold capacity expansion in Rayong to capture underserved pharmaceutical-grade demand before precision specialists establish presence. Thai FDA timeline compression for food-contact notifications threatens qualification backlogs for reformulated resins. For New Entrants and Emerging Players: Lead with child-resistant closure qualification for Rayong pharmaceutical export bottlers, where incumbent coverage gaps create immediate white space. Target direct mold-development relationships with Chiang Mai craft beverage brands displacing legacy distributor structures. Position through medical-grade molding cell investment and Thai FDA notification expertise rather than volume scale. For Investors and Strategic Acquirers: Precision molders with dedicated pharmaceutical cells and blockchain resin traceability systems offer the strongest acquisition profile for ASEAN EPR compliance exposure. Long-term viability hinges on regulatory technology integration rather than commodity molding scale. Watch Thai FDA enforcement intensity on migration limit documentation as the inflection signal for material qualification cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Runner Mold Capacity Expansion | Enables thin-wall polypropylene qualification for oxygen barrier compliance in retort cooking oil packaging. |
| Blockchain-Linked Resin Traceability | Preempts ASEAN Extended Producer Responsibility mandates for packaging waste accountability documentation. |
| Medical-Grade Molding Cell Segregation | Isolates pharmaceutical and cosmetic production from food-contact contamination risk per Thai FDA requirements. |
| Direct Mold-Development Partnerships | Bypasses distributor layers for Chiang Mai craft beverage brands specifying custom tamper-evident formats. |
| Bio-Polypropylene Reformulation Investment | Aligns with Pollution Control Department procurement preferences for municipal water contract eligibility. |
Research Methodology
Desk research of Thai FDA food-contact notification databases, Industrial Product Standards certification records, and ASEAN trade flow statistics preceded structured interviews with plant managers at Pathum Thani molding operations, procurement leads at regional juice processors, and regulatory affairs specialists at personal care multinationals. Secondary validation drew from customs export data, resin producer pricing disclosures, and Pollution Control Department policy drafts. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand aggregation by end-use segment.
Variance decomposition across product type, material grade, end-use sophistication, and geographic production cluster shaped the analytical framework. CAGRs derived from segment-level growth rate distributions weighted by base-year revenue contribution. Industry-specific forecast inputs included naphtha-cracking margin cycles, Thai FDA enforcement trajectory, and ASEAN EPR implementation timelines.
Forecasts assume regulatory continuity in Thai FDA food-contact standards and Pollution Control Department plastic restriction regimes; material policy shifts would require re-modeling. Propylene feedstock volatility and mechanical recycling infrastructure gaps represent specific revision risks. Recalibration cycles align with material shifts in ASEAN harmonization frameworks and bio-based resin commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Cap Liner Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Child Resistant Dropper Caps Market
Caps and Closures
Brush Caps Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
End Cap Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Colombia Plastic Caps and Closures Market