
 APAC Plastic Caps and Closures Market | 2026-2036
APAC Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Plastic Caps and Closures Market Outlook
Bulk procurement channels serving multinational beverage bottlers is reconfiguring supplier qualification criteria across the APAC Plastic Caps and Closures Market. Amcor leverages integrated resin-to-closure manufacturing to secure long-term supply contracts with carbonated soft drink producers. Closure Systems International anchors its regional footprint through high-speed compression molding lines optimized for lightweight polyethylene closures. Nippon Closures dominates precision dispensing cap segments for soy sauce and condiment brands across Japan and Taiwan.
Plastic caps and closures are threaded or snap-fit sealing devices manufactured from thermoplastic resins through injection, compression, or blow molding processes, typically achieving torque removal forces between 10 and 25 inch-pounds depending on liner configuration and neck finish specification. Their primary purpose is to preserve product integrity, enable controlled dispensing, and support tamper-evident compliance across liquid and semi-solid consumer goods. Screw caps retain the largest volume share in beverage and edible oil applications where resealability and oxygen barrier performance command premium positioning. Polypropylene formulations are displacing polyethylene in hot-fill and retort applications due to superior thermal stability and dimensional recovery after steam sterilization cycles.
Japan's METI enforces container and packaging recycling targets that mandate minimum recycled content thresholds, while China's SAMR implements GB standards governing food-contact plastic migration limits that directly shape resin selection and additive formulations for export-bound closures. India's BIS certification requirements for food-grade plastics create compliance barriers that favor suppliers with in-house testing laboratories and documented traceability systems. Stakeholders must monitor evolving extended producer responsibility frameworks across Indonesia, Thailand, and the Philippines, where draft regulations will impose post-consumer collection obligations on imported and domestically produced closures alike.
Market Dynamics
Automated capping line investments across Southeast Asian beverage corridors are compressing supplier qualification cycles and forcing resin-to-closure integration decisions.
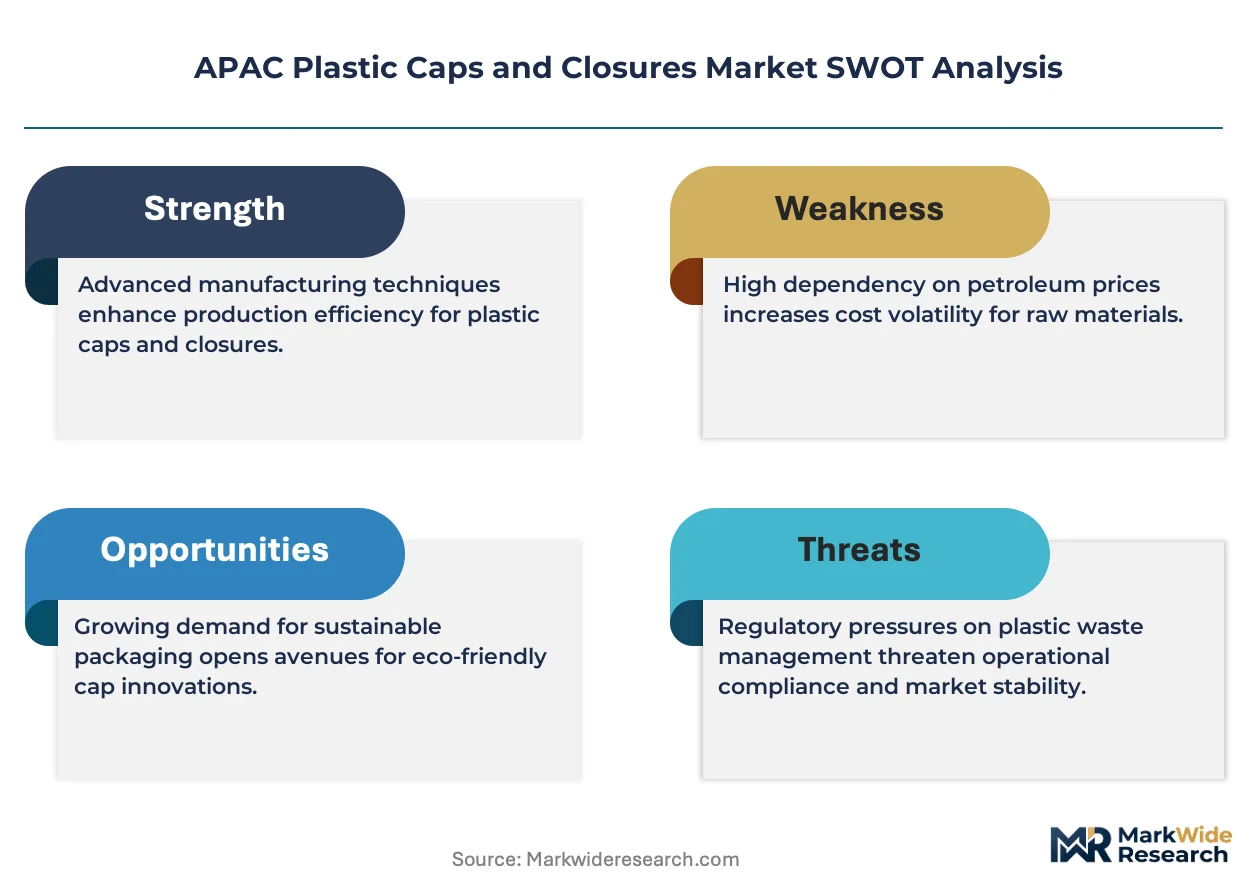
Growth Catalysts
- India's BIS certification mandates:Food-contact plastic testing protocols are tightening material traceability requirements, favoring suppliers with captive laboratory infrastructure.
- Hot-fill polypropylene adoption:Superior thermal stability in retort applications is displacing polyethylene in soy sauce and edible oil packaging across Japan and Taiwan.
- Vietnam's export manufacturing corridors:Concentrated demand near Ho Chi Minh City and Binh Duong province is anchoring regional production scale.
Market Restraints
- Recycled content thresholds:Japan's METI container recycling targets mandate minimum post-consumer resin incorporation, limiting virgin polypropylene availability for high-clarity applications.
- Migration limit compliance:China's SAMR GB standards for food-contact plastics impose additive formulation constraints that extend qualification timelines for export-bound closures.
- Biopolymer substitution pressure:Extended producer responsibility drafts across Indonesia, Thailand, and the Philippines are elevating collection cost exposure for conventional thermoplastic closures.
Strategic Opportunities
- Precision dispensing segments:Soy sauce and condiment brands across Japan and Taiwan are upgrading to controlled-flow cap designs with oxygen barrier liners.
- Extended producer responsibility tailwinds:Draft post-consumer collection obligations in Indonesia, Thailand, and the Philippines will reward suppliers with closed-loop resin recovery systems.
- Lightweight compression molding convergence:High-speed polyethylene closure production is hybridizing with in-mold labeling for premium beverage positioning.
Industry Challenges
- Compression molding capex intensity:High-speed line investments for lightweight closures require dedicated tooling programs that strain mid-tier supplier balance sheets.
- BIS certification timeline compression:India's food-grade plastic documentation requirements are extending supplier onboarding cycles beyond typical beverage contract windows.
- Resin formulation IP fragmentation:Proprietary additive packages for hot-fill polypropylene are creating licensing complexity across Japan-Taiwan supply corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Plastic Caps and Closures Market |
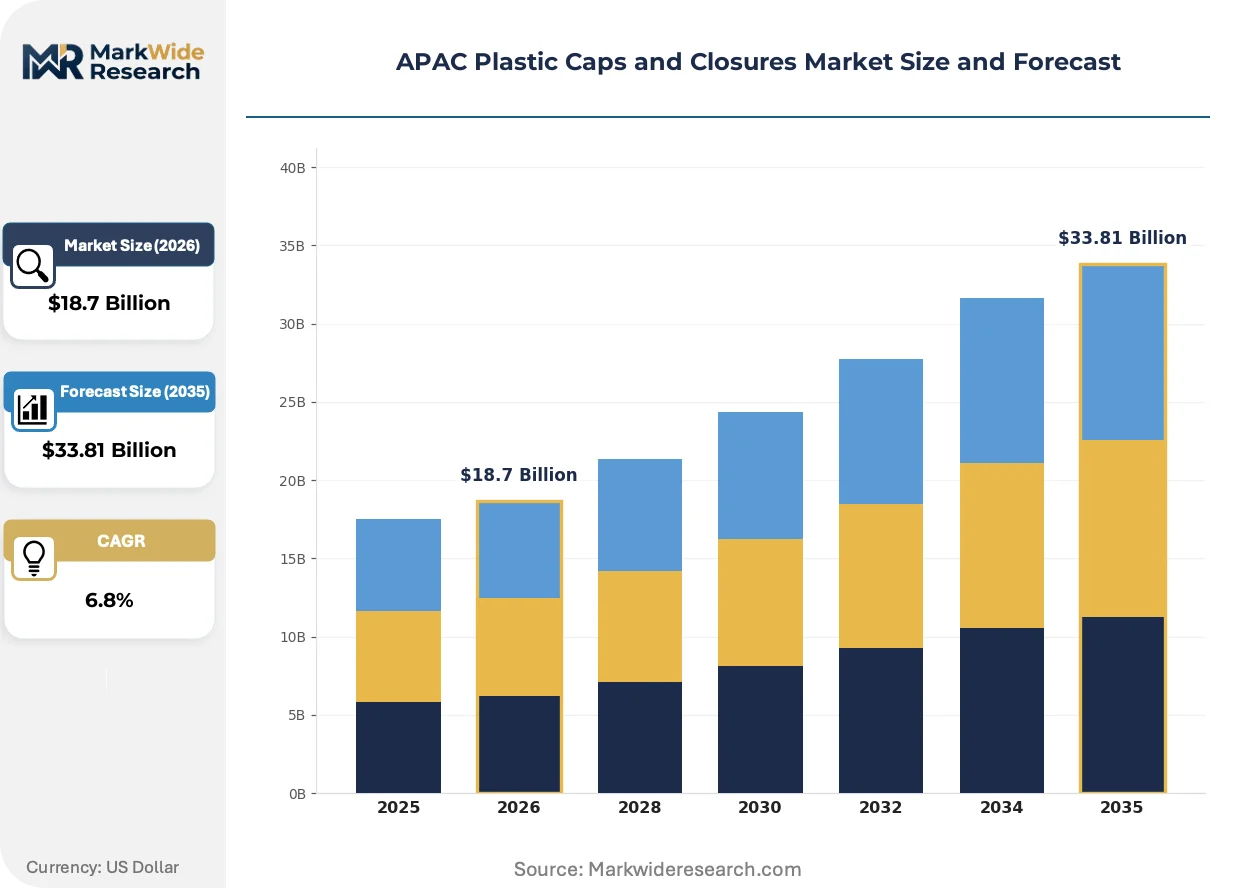
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Corks Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverage, Personal Care, Healthcare, Household Products Technology: Injection Molding, Blow Molding, Compression Molding, Thermoforming |
| Companies Covered | Berry Global, Closure Systems International, Amcor, Nippon Closures, BERICAP, AptarGroup, Silgan Holdings, Albéa Services, Crown, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Plastic Caps and Closures Market Strategic Shifts
Material science advances and regulatory compliance architectures are converging to redefine competitive advantage in precision sealing applications across the region.
Polypropylene formulations engineered for dimensional recovery after steam sterilization cycles are hybridizing with oxygen scavenger liner technologies. Hot-fill beverage producers in Vietnam and Thailand are adopting these hybrid systems at accelerated qualification paces. The structural consequence is compression of supplier tiers into resin-compounder-closure integrators capable of guaranteeing migration compliance.
China's SAMR is enforcing GB standards governing food-contact plastic migration limits with expanded testing scope for volatile organic compounds. Industrial consequence includes mandatory reformulation of antioxidant and slip additive packages in export-bound closures. High-barrier edible oil segments serving European and North American buyers are most affected, with suppliers accelerating third-party laboratory certification renewals.
Bulk procurement contracts serving multinational beverage bottlers are consolidating supplier bases around integrated resin-to-closure manufacturers. Direct sourcing agreements are displacing distributor intermediaries in carbonated soft drink and bottled water channels. This channel compression is most visible in Vietnam's Binh Duong province, where bottler technical audits now precede volume commitments.
APAC Plastic Caps and Closures Market Segmentation
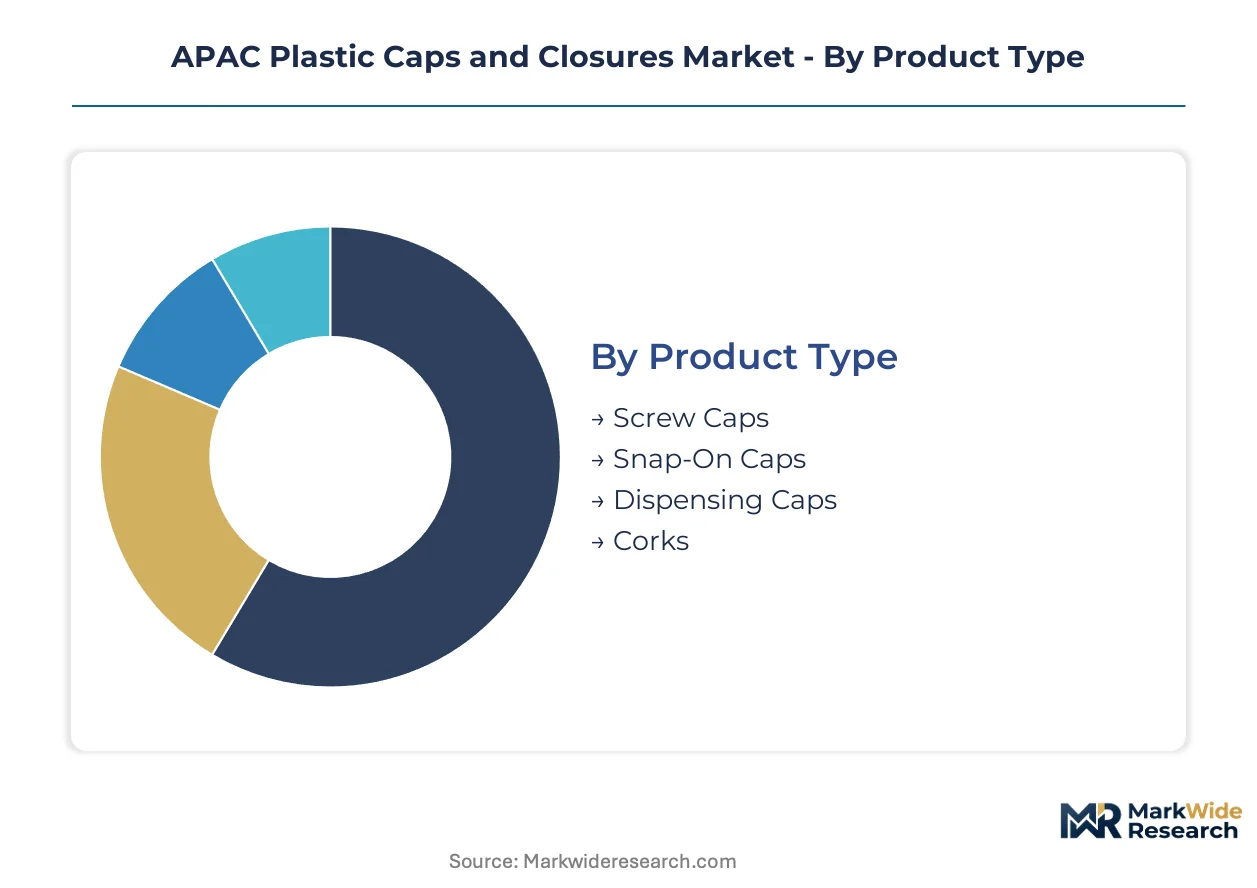
Segmentation in the APAC Plastic Caps and Closures Market reveals how resin selection, molding technology, and end-use specifications create distinct competitive arenas. Suppliers must match material properties to thermal stability requirements while navigating divergent regulatory compliance burdens across food-contact and healthcare applications.
Product Type:
Mature formats dominate beverage volumes while emerging designs capture premium positioning in condiment and personal care channels.
- Screw Caps:Threaded closure systems achieve torque removal forces between 10 and 25 inch-pounds through liner configuration and neck finish optimization. Carbonated soft drink producers across Vietnam's Binh Duong province specify these for oxygen barrier performance and resealability compliance. India's BIS certification mandates are tightening material traceability requirements for food-contact screw cap suppliers.
- Dispensing Caps:Precision flow-control mechanisms integrate oxygen scavenger liner technologies for soy sauce and condiment brands across Japan and Taiwan. Hot-fill polypropylene formulations engineered for dimensional recovery after steam sterilization cycles are displacing polyethylene in these applications. METI recycling targets are mandating minimum post-consumer resin incorporation that limits virgin material availability for high-clarity dispensing formats.
- Snap-On Caps:Friction-fit sealing devices serve single-serve beverage and household product applications where resealability is secondary to tamper evidence.
- Corks:Synthetic and natural stopper alternatives retain niche positioning in premium alcoholic beverage segments across Australia's wine export corridors.
Screw caps retain volume leadership; dispensing caps hold the steepest expansion curve.
Material:
Cost tiers stratify around thermal performance requirements and regulatory migration compliance burdens.
- Polypropylene:Thermoplastic resin formulations deliver superior thermal stability and dimensional recovery after retort sterilization cycles. Hot-fill beverage producers in Vietnam and Thailand are accelerating qualification paces for these materials. China's SAMR GB standards for food-contact plastic migration limits are forcing additive package reformulations in export-bound polypropylene closures.
- Polyethylene:Lightweight resin systems dominate high-speed compression molding lines optimized for carbonated soft drink and bottled water volumes. Closure Systems International anchors regional production through dedicated polyethylene closure programs. Japan's METI container recycling targets mandate post-consumer resin thresholds that constrain virgin polyethylene availability.
- PVC:Chlorinated thermoplastic retains limited pharmaceutical and chemical-resistant applications where barrier properties outweigh sustainability scrutiny.
- PET:Polyester resin closures serve specialized pharmaceutical and high-clarity cosmetic segments requiring dimensional stability and chemical resistance.
Polyethylene commands the largest production scale; polypropylene is climbing the fastest on hot-fill adoption.
End User:
Application requirements dictate oxygen barrier specifications, tamper-evident compliance, and dispensing precision.
- Food & Beverage:Packaging lines across Southeast Asian beverage corridors are scaling automated capping systems to meet throughput targets. Bulk procurement contracts serving multinational bottlers are consolidating supplier bases around integrated resin-to-closure manufacturers. BIS certification requirements in India are extending supplier onboarding cycles beyond typical contract windows.
- Healthcare:Pharmaceutical closure systems require child-resistant and senior-friendly compliance architectures with documented traceability systems. Migration limit testing under China's SAMR protocols shapes additive selection for export-bound healthcare closures.
- Personal Care:Dispensing precision and aesthetic finish requirements drive specification differentiation in premium shampoo and cosmetic packaging.
- Household Products:Chemical resistance and cost optimization dominate specification criteria for cleaning product closures.
Food & Beverage anchors regional demand; Healthcare holds the steepest expansion trajectory on regulatory compliance premiums.
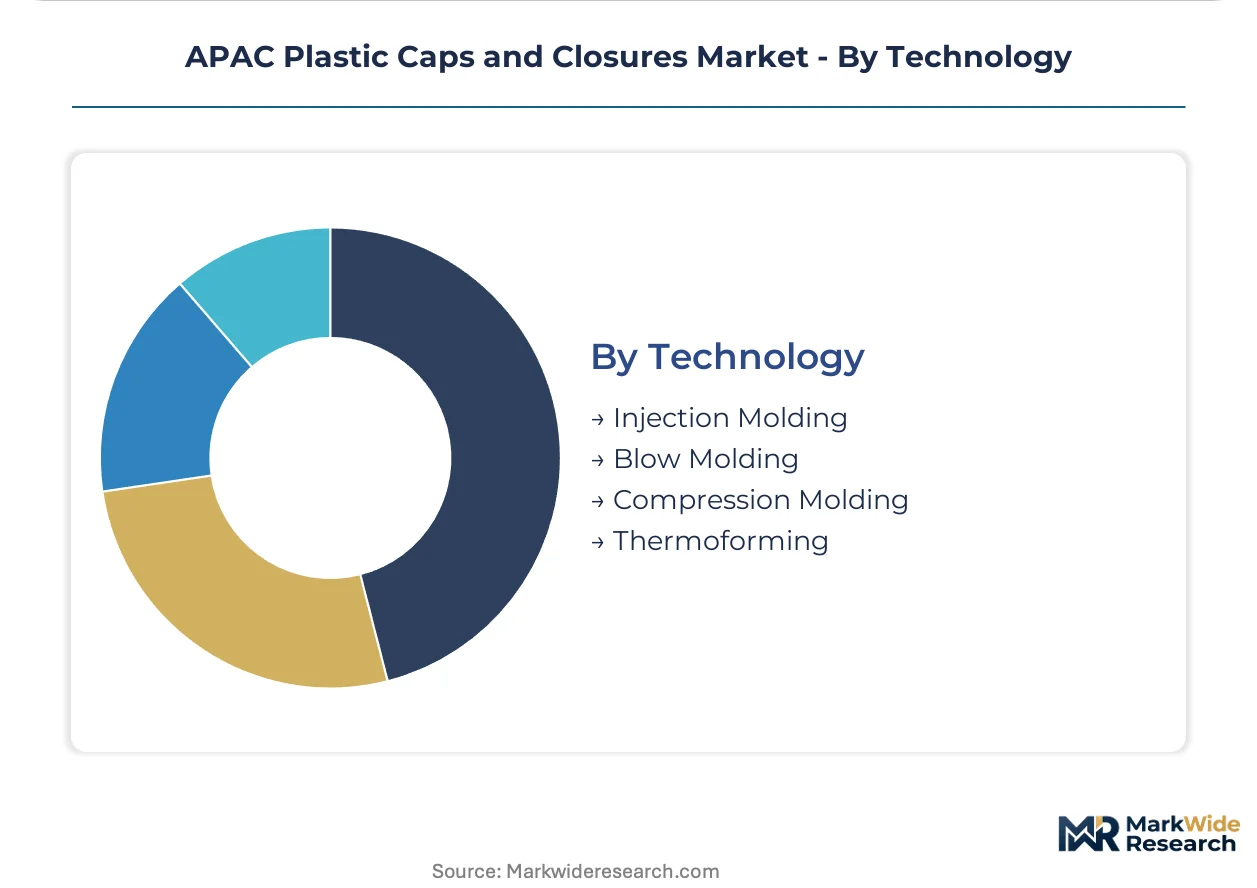
Technology:
Volume scale and capital intensity separate molding process competitive positions.
- Compression Molding:High-speed line investments for lightweight polyethylene closures require dedicated tooling programs that strain mid-tier supplier balance sheets. Closure Systems International anchors its regional footprint through optimized compression systems. Capex intensity is compressing supplier tiers into resin-compounder-closure integrators.
- Injection Molding:Precision tool engineering enables complex thread geometries and multi-component dispensing cap production. Nippon Closures dominates precision segments through injection-molded systems for soy sauce brands.
- Blow Molding:Hollow-forming processes serve specialized container-integrated closure applications in personal care and household segments.
- Thermoforming:Sheet-based forming retains niche positioning in thin-walled, single-serve packaging formats with limited resealability requirements.
Compression molding retains volume leadership; injection molding holds the steepest expansion curve on precision dispensing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang deep-sea port complex anchors Thailand's position as a regional distribution hub for closure systems serving Mekong basin beverage corridors.
China
Carbonated soft drink bottlers in Guangdong province are scaling automated capping lines to meet export contract volumes. SAMR enforces GB standards governing food-contact plastic migration limits with expanded volatile organic compound testing scope. Dongguan and Shenzhen manufacturing clusters concentrate compression molding capacity for lightweight polyethylene closures bound for North American buyers.
India
Edible oil packagers in Maharashtra and Gujarat are retrofitting hot-fill lines to accommodate polypropylene closure systems. BIS certification mandates for food-grade plastics extend supplier qualification timelines beyond typical procurement windows. The Bhiwandi-Nashik industrial corridor near Mumbai anchors domestic resin-to-closure integration investments.
Japan
Precision dispensing cap demand from soy sauce and condiment brands drives specification upgrades across Kansai and Chubu regions. METI container recycling targets mandate minimum post-consumer resin thresholds that constrain virgin polypropylene availability. Nagoya-based manufacturing clusters specialize in oxygen scavenger liner technologies for premium food packaging.
Vietnam
Export-oriented beverage bottlers near Ho Chi Minh City are consolidating supplier bases around integrated manufacturers. Binh Duong province hosts the densest concentration of high-speed compression molding lines serving ASEAN carbonated soft drink markets. Technical audits now precede volume commitments from multinational bottlers operating through Cat Lai port logistics.
Indonesia
Draft extended producer responsibility regulations are elevating post-consumer collection cost exposure for closure importers and domestic producers alike. Java-based beverage corridors are piloting closed-loop resin recovery systems to preempt compliance burdens. Surabaya manufacturing zones concentrate injection molding capacity for dispensing cap formats serving domestic condiment brands.
APAC Plastic Caps and Closures Market Competitive Environment
On the supply side, the industry is consolidating around integrated resin-compounder-closure manufacturers capable of guaranteeing migration compliance across divergent regulatory regimes. Tier compression is eliminating distributor intermediaries in favor of direct sourcing agreements with multinational bottlers. Three archetypes dominate: global packaging conglomerates with captive resin operations, regional specialists in precision dispensing formats, and scale-driven compression molding contractors. Competitive intensity centers on backward integration into polymer compounding and geographic expansion through technical audit relationships.
Among integrated packaging conglomerates, Amcor and Berry Global exemplify the resin-to-closure model that secures long-term beverage supply contracts. Closure Systems International occupies a position within the scale-driven tier, anchoring regional production through dedicated high-speed line investments. Nippon Closures represents the precision specialist archetype, with expertise concentrated in controlled-flow dispensing systems for condiment applications across Japan and Taiwan markets.
| Leading Market Players |
|---|
| Berry Global |
| Closure Systems International |
| Amcor |
| Nippon Closures |
| BERICAP |
| AptarGroup |
| Silgan Holdings |
| Albéa Services |
| Crown |
| Others |
Value Chain & Pricing Dynamics
The Laem Chabang deep-sea port complex channels freight cost dynamics through Southeast Asian beverage corridors, concentrating supply power among resin-integrated manufacturers while forcing three-tier price differentiation across premium hot-fill, standard carbonated, and economy bottled water segments.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts serving multinational beverage bottlers, with pricing stratifying across premium hot-fill polypropylene, standard polyethylene screw caps, and economy snap-fit formats. Price differentiation rests on BIS certification grade and captive laboratory infrastructure in India, plus oxygen barrier liner performance in Japan-Taiwan condiment channels. Cost compression in standard polyethylene tiers is intensifying because high-speed compression molding capex demands are squeezing mid-tier suppliers. Economy bottled water bottlers exhibit highest price sensitivity; premium soy sauce brands in Kansai region show lowest.
Supply Chain Analysis
Upstream polypropylene and polyethylene resin feedstock supplies draw from Saudi Arabia, South Korea, and Singapore refining hubs, with additive packages compounding in China's Guangdong province and Thailand's Eastern Economic Corridor. Raw material dependencies center on propylene monomer, antioxidant stabilizers, and oxygen scavenger liner substrates. Single-source vulnerability concentrates in Japanese METI-certified post-consumer resin streams for high-clarity dispensing caps. Distribution runs through direct technical audit relationships with multinational bottlers, displacing traditional distributor intermediaries in Vietnam's Binh Duong province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification timeline compression and Japan's METI recycled content mandates constitute a dual regulatory inflection that will eliminate non-integrated suppliers across the analysis window.
For Market Incumbents: Entrench through backward integration into polymer compounding and captive laboratory certification infrastructure. Amcor and Berry Global models demonstrate how resin-to-closure control defends against hot-fill polypropylene formulation IP fragmentation. Accelerate high-speed compression molding capacity in Vietnam's Binh Duong province to capture ASEAN carbonated soft drink contract renewals. For New Entrants and Emerging Players: Precision dispensing cap shortages for Taiwan condiment brands represent the most penetrable entry point, followed by India's BIS-certified food-grade screw cap gaps. Target technical partnership structures with Nagoya-based oxygen scavenger liner specialists rather than greenfield compression molding investments. Direct sourcing qualification through Japanese soy sauce brand technical audits offers faster revenue traction than distributor channel builds. For Investors and Strategic Acquirers: Regional resin-compounder-closure integrators with documented METI recycling compliance and BIS laboratory infrastructure represent the highest-conviction acquisition archetype. Long-term viability hinges on closed-loop post-consumer collection systems ahead of Indonesia, Thailand, and Philippines extended producer responsibility enforcement. Monitor draft EPR implementation timelines as the primary inflection signal for conventional thermoplastic closure asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply secures BIS and SAMR migration compliance documentation for Indian and Chinese export contracts. |
| High-Speed Compression Molding Capacity Expansion | Dedicated lightweight polyethylene lines in Vietnam's Binh Duong province anchor ASEAN beverage bottler technical audit relationships. |
| Closed-Loop Post-Consumer Collection Systems | Preemptive EPR compliance infrastructure in Indonesia, Thailand, and Philippines insulates against collection cost exposure. |
| Precision Dispensing Cap R&D Partnerships | Oxygen scavenger liner technology alliances with Nagoya specialists capture Japan-Taiwan condiment brand upgrade cycles. |
| Captive Laboratory Certification Investment | In-house BIS testing capabilities compress supplier onboarding timelines for Indian edible oil and beverage packaging contracts. |
Study Parameters
A standing panel of beverage packaging procurement directors, resin compounding technical managers, regulatory compliance officers at BIS and SAMR, and high-speed molding line engineers provided ongoing calibration across the study period. Primary interview findings triangulated against secondary sources including Indian customs import data for food-grade plastic closures, Japanese METI container recycling reports, Vietnam industrial zone investment disclosures, and ASEAN beverage production statistics. Bottom-up volume modeling from individual plant capacities converged with top-down demand estimates from end-use consumption patterns.
Scenario-bracketing anchored projections across regulatory acceleration, resin price volatility, and EPR implementation delay assumptions throughout the forecast period. Segmentation modeling incorporated product type, material formulation, end-use application, molding technology, and country-level regulatory cluster dimensions. CAGRs derived from slope-intercept analysis of historical trajectory alignment with structural driver intensity, with specific weighting applied to hot-fill polypropylene adoption curves and compression molding automation penetration rates.
Practitioners should monitor BIS certification backlog lengths, METI recycled content threshold adjustments, and Indonesia EPR draft finalization for early signals of forecast revision necessity. Cross-checking against beverage bottler capex announcements and resin producer margin disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Bag Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Cap Seals Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Vented Caps Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
United States Plastic Caps and Closure Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market