
 Buttress Closures Market | 2026-2036
Buttress Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Buttress Closures Market Outlook
REACH compliance is shifting the cost-of-entry calculus for European suppliers of buttress closures. Berry Global Inc. leverages vertical integration across resin compounding and molding operations to absorb regulatory testing costs. Silgan Holdings Inc. anchors its position through metal closure expertise that satisfies dual food-contact and pharmaceutical standards. Amcor Limited differentiates via R&D intensity in lightweight composite structures that maintain thread integrity under torque stress.
Buttress closures are threaded dispensing and sealing devices featuring steep, asymmetric thread profiles that engage container necks with fewer rotations than continuous threads, typically manufactured through injection molding or compression forming of polypropylene or polyethylene resins. Their primary purpose is to secure liquid and semi-solid contents in pharmaceutical syrups, industrial chemicals, and food condiments while enabling rapid opening and reliable resealability. Standard closures dominate volume production for mass-market food applications where cost efficiency outweighs customization needs, while specialty closures capture margin pools in pharmaceutical and agrochemical segments requiring child-resistant and tamper-evident certifications. Automated closures represent the fastest-growing product type as filling lines integrate capping equipment with vision systems that verify thread engagement torque.
The FDA enforces 21 CFR requirements for pharmaceutical container closures, including extractables and leachables testing that shapes material selection and validation timelines for U.S.-market suppliers. EMA's MDR and EU Packaging and Packaging Waste Regulation compel European manufacturers to document recyclability pathways and reduce heavy metal content in closure pigments. China's NMPA and GB standards for food-contact plastics create parallel compliance tracks for exporters serving Asia-Pacific distribution. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or region-specific formulation strategies minimize compliance burden.
Market Dynamics
Pharmaceutical filling lines are accelerating adoption of vision-verified capping systems that demand thread precision tolerances below 0.1 millimeters, forcing closure manufacturers to retool molding operations for automated compatibility.
Growth Catalysts
- REACH compliance deadlines:ECHA's phased restrictions on persistent organic pollutants in polymer additives are redirecting European pharmaceutical packagers toward certified food-grade polypropylene closures with documented recyclability pathways.
- Agrochemical dispensing:Precision agriculture equipment manufacturers specify buttress-threaded containers for herbicide concentrates, prioritizing rapid reseal integrity after field exposure to dust and vibration.
- Injection molding automation:Servo-electric mold technologies with real-time cavity pressure monitoring are compressing cycle times for high-volume food condiment closures without sacrificing thread profile accuracy.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins in Asian petrochemical hubs transmit directly to resin contract pricing, squeezing margin stability for mid-volume European molders without captive olefin supply.
- Single-source tooling dependency:Precision buttress thread inserts for multi-cavity molds are manufactured by a concentrated German and Swiss supplier base, creating bottleneck risk for capacity expansion timelines.
- Metal closure substitution:Steel lug closures with compound gaskets retain share in high-acid food segments where oxygen ingress sensitivity outweighs convenience benefits of plastic threading.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO's alignment with ICH Q3D elemental impurity guidelines is opening specification windows for compliant polypropylene closures serving contract manufacturing organizations in Hyderabad and Ahmedabad.
- Dual-carbon policy convergence:China's MEE mandates for post-consumer recycled content in packaging are creating first-mover advantage for closure suppliers with validated mechanical recycling feedstock streams.
- Connected packaging integration:Near-field communication tags embedded in closure tops are converging with pharmaceutical track-and-trace mandates, enabling authentication and dosing-reminder functionality.
Industry Challenges
- Validation protocol compression:FDA 21 CFR extractables studies with 24-month stability timelines are colliding with pharmaceutical customers' 18-month product launch windows, forcing parallel rather than sequential testing strategies.
- Multi-material separation:Closure liners with ethylene-vinyl acetate gaskets bonded to polypropylene shells complicate mechanical recycling streams, requiring redesign investment ahead of extended producer responsibility enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buttress Closures Market |
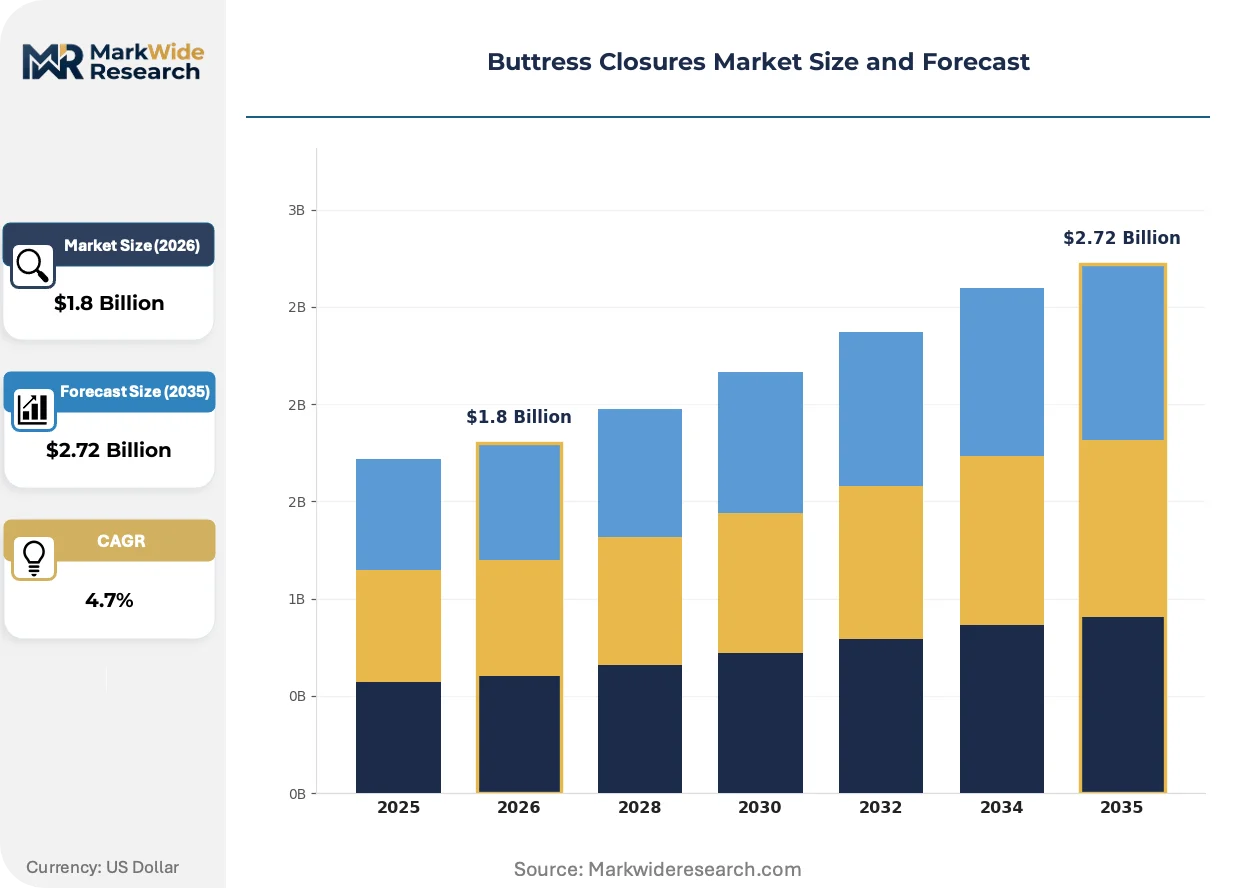
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Closures, Specialty Closures, Custom Closures, Automated Closures Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Pharmaceutical, Cosmetics, Personal Care Distribution Channel: Online Retail, Brick-and-Mortar, Direct Sales, Distributors |
| Companies Covered | Berry Global Inc., Amcor Limited, Silgan Holdings Inc., AptarGroup, Guala Closures S.p.A., O.Berk Company, Closure Systems International (CSI), Huhtamaki Group, RPC Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buttress Closures Market Strategic Shifts
Active pharmaceutical ingredient manufacturers are rewriting packaging specifications to accommodate cold-chain distribution, reshaping closure performance requirements around thermal cycling resistance and low-temperature torque consistency.
Biobased polypropylene derived from renewable naphtha pathways is integrating into pharmaceutical-grade closure formulations, with early adopters in Nordic markets demanding mass-balance certification from resin suppliers. The material maintains identical mechanical properties to fossil-derived equivalents while satisfying corporate Scope 3 reduction targets. This integration is compressing the premium pricing window for conventional petroleum-based alternatives as supply scales.
EMA's MDR Annex I general safety and performance requirements are tightening documentation burdens for closure-to-container seal integrity in Class III medical devices, forcing manufacturers to maintain design dossiers with fatigue-testing data across temperature ranges. The regulation's industrial consequence is a bifurcation between suppliers with in-house metrology capabilities and those dependent on third-party testing houses. Pharmaceutical contract packagers in Ireland and Belgium are consolidating supplier panels to entities with notified body relationships.
Consolidation among North American generic drug manufacturers is concentrating procurement authority at headquarters level, displacing decentralized plant-level sourcing that previously accommodated regional molders. The new model favors national distribution agreements with tiered pricing structures tied to annual volume commitments. This concentration is most visible in New Jersey and Pennsylvania corridor operations serving the largest contract manufacturing organizations.
Buttress Closures Market Segmentation
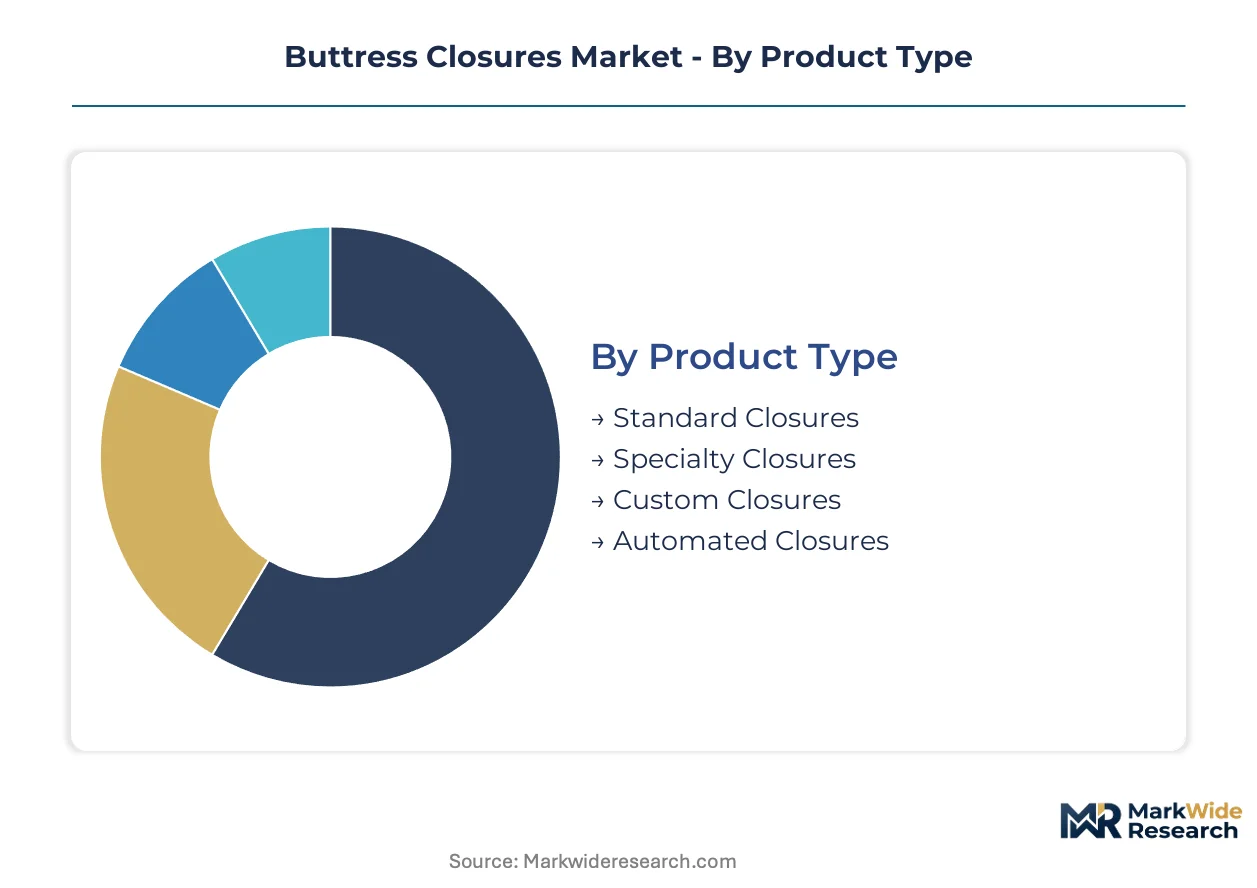
Buttress closures serve divergent performance requirements across pharmaceutical cold-chain logistics, industrial chemical dispensing, and food condiment packaging. Segmentation reveals where molding precision premiums command pricing power versus where resin cost efficiency dominates procurement decisions.
Product Type:
Mold-making capacity concentrates in German and Swiss tooling houses, creating supply bottlenecks for high-cavity precision inserts.
- Standard Closures:Mass-produced polypropylene and polyethylene caps for food condiments and household chemicals. Demand clusters with high-volume sauce and oil packagers in Germany's Ruhr industrial corridor, where automated filling lines prioritize thread consistency over customization.
- Specialty Closures:Child-resistant and tamper-evident designs with multi-component liners meeting FDA 21 CFR extractables requirements. Pharmaceutical contract manufacturers in Ireland and Belgium specify these for pediatric syrup packaging, absorbing validation costs through premium pricing.
- Custom Closures:Application-specific thread profiles and dispensing orifices engineered for agrochemical concentrates.
- Automated Closures:Vision-system-compatible designs with torque-verification features for high-speed capping lines.
Standard closures absorb the bulk of installed capacity; automated closures are expanding most quickly.
Material:
Resin formulation strategies diverge between REACH-compliant European supply and cost-optimized Asian production.
- Plastic:Polypropylene dominates through injection molding efficiency and chemical resistance. Food-grade certified grades with documented recyclability pathways are displacing legacy formulations in EMA-regulated pharmaceutical packaging.
- Metal:Steel lug closures with compound gaskets retain position in high-acid food segments and oxygen-sensitive pharmaceutical applications where barrier properties outweigh plastic convenience.
- Glass:Limited to premium cosmetic and diagnostic reagent applications requiring inert contact surfaces.
- Composite:Lightweight hybrid structures combining polymer shells with barrier-coated liners for cold-chain pharmaceutical distribution.
Plastic commands the greatest molding capacity; composite formulations are gaining share fastest.
End User:
Regulatory intensity varies sharply across customer segments, reshaping supplier qualification requirements.
- Food & Beverage:High-volume condiment and cooking oil packaging where cost efficiency and thread reliability outweigh advanced features. German food processors drive standardization through centralized procurement.
- Pharmaceutical:The most demanding segment for extractables documentation, child-resistance certification, and cold-chain torque consistency. EMA MDR Annex I requirements are consolidating supplier panels to entities with notified body relationships.
- Cosmetics:Aesthetic and dispensing-function differentiation for premium skincare and fragrance applications.
- Personal Care:Flip-top and disc-top buttress variants for shampoo and lotion bottles with one-handed operation requirements.
Food & Beverage generates the highest unit volumes; pharmaceutical applications carry the steepest expansion trajectory.
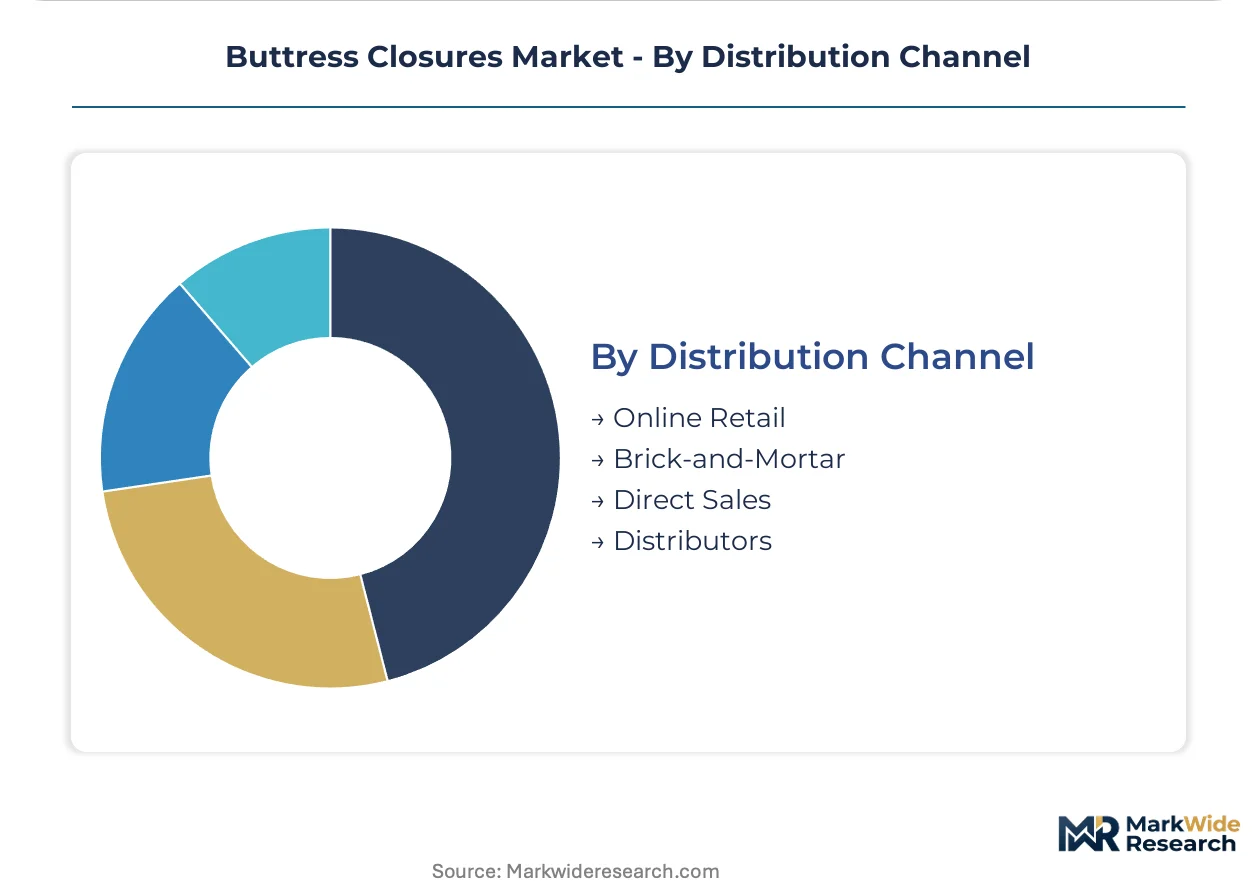
Distribution Channel:
Channel selection reflects customer scale and specification complexity rather than geography alone.
- Direct Sales:National distribution agreements with tiered pricing tied to annual volume commitments. North American generic drug manufacturer consolidation has concentrated procurement authority at headquarters level, displacing plant-level sourcing.
- Distributors:Regional inventory holding for mid-volume pharmaceutical and food packagers requiring technical support and rapid replenishment.
- Online Retail:Catalog-based procurement for standard closure specifications with predictable lead times.
- Brick-and-Mortar:Limited to emergency replacement and small-lot specialty orders.
Direct sales capture the largest contract values; distributor relationships are deepening fastest among mid-tier pharmaceutical packagers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturing clusters in Germany and India generate concentrated demand for precision-molded buttress closures, while food processing corridors in the United States and Brazil sustain high-volume standard closure consumption. Regulatory divergence across FDA, EMA, and CDSCO jurisdictions is fragmenting supplier qualification requirements by geography.
Germany
Precision engineering clusters in Baden-Württemberg and North Rhine-Westphalia serve domestic pharmaceutical exporters and Central European food processors with high-cavity molding capacity. REACH compliance deadlines from ECHA are redirecting pharmaceutical packagers toward certified food-grade polypropylene closures with documented recyclability pathways. The Ruhr industrial corridor hosts automated filling lines for condiment and cooking oil applications where thread consistency commands procurement priority.
United States
Generic drug manufacturer consolidation in New Jersey and Pennsylvania corridors has concentrated procurement authority at headquarters level, displacing plant-level sourcing. FDA 21 CFR extractables and leachables testing requirements shape material selection and validation timelines for domestic suppliers. National distribution agreements with tiered pricing structures now dominate contract structures for pharmaceutical closure supply.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines is opening specification windows for compliant polypropylene closures serving contract manufacturing organizations. Hyderabad and Ahmedabad pharmaceutical export corridors are expanding validation-capable supplier relationships. Domestic molders are investing in metrology capabilities to meet international pharmaceutical customer audit requirements.
China
MEE mandates for post-consumer recycled content in packaging are creating first-mover advantage for closure suppliers with validated mechanical recycling feedstock streams. NMPA and GB standards for food-contact plastics create parallel compliance tracks for exporters serving Asia-Pacific distribution. Yangtze River Delta molding operations are retooling for pharmaceutical-grade precision to capture export market share.
Brazil
ANVISA pharmaceutical packaging regulations are tightening documentation requirements for imported closures, favoring suppliers with established Brazilian distribution partnerships. São Paulo state food processing clusters sustain demand for standard polypropylene closures in condiment and edible oil applications. Local molders face margin pressure from Asian resin cost advantages and European technical specification premiums.
Buttress Closures Market Competitive Environment
German and Swiss producers anchor the precision-tooling tier; North American and Asian molders hold scale-driven positions in standard closure supply. The market structures around three tiers: multinational packaging conglomerates with captive resin compounding, mid-volume regional specialists with notified body relationships, and commodity molders serving cost-sensitive food applications. Strategic moves concentrate on backward integration into resin supply and consolidation of pharmaceutical customer panels through validation protocol alignment.
Among packaging conglomerates, Berry Global Inc. and Amcor Limited exemplify the multinational tier with integrated resin and molding operations spanning multiple regulatory jurisdictions. Silgan Holdings Inc. occupies a distinct position through metal closure expertise that satisfies dual food-contact and pharmaceutical standards. These three entities represent the competitive archetypes: resin-integrated polymer specialists, diversified packaging platforms, and metal-to-plastic hybrid manufacturers.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor Limited |
| Silgan Holdings Inc. |
| AptarGroup |
| Guala Closures S.p.A. |
| O.Berk Company |
| Closure Systems International (CSI) |
| Huhtamaki Group |
| RPC Group Plc |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between pharmaceutical-grade and food-grade closures creates parallel pricing architectures and divergent supply chain configurations. Pharmaceutical buyers absorb validation premiums for EMA-notified body relationships while food processors prioritize resin cost efficiency through centralized procurement in Germany's Ruhr corridor.
Pricing Analysis
Volume-driven standard closures trade on thin margins against specialty pharmaceutical designs capturing validation premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, cavity precision, and resin grade differentiation. Cost compression in commodity polypropylene segments is intensifying because Asian naphtha-cracking margins transmit directly to European molders without captive olefin supply. Food processors exhibit highest price sensitivity; pharmaceutical contract manufacturers prioritize compliance documentation over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical contract packagers mandate qualified secondary suppliers for thread precision inserts. Manufacturing concentrates in Germany, Switzerland, and China, with German and Swiss houses dominating high-cavity precision tooling. Raw material flows draw from Saudi and Korean polypropylene feedstock, German tool steel, and Italian liner compounds. Single-source dependency on Swiss-German mold insert suppliers creates bottleneck risk for capacity expansion. Distribution runs through direct national agreements with tiered volume commitments for pharmaceutical giants, regional distributors for mid-tier food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The buttress closures market sits in an automation-transition phase as vision-verified capping systems displace mechanical torque verification. Servo-electric mold technologies with real-time cavity pressure monitoring are compressing cycle times while demanding thread precision below 0.1 millimeters.
For Market Incumbents: Hedge against metal closure substitution in high-acid food segments by accelerating composite barrier development for oxygen-sensitive applications. Backward integration into certified food-grade resin compounding absorbs REACH testing costs that commodity competitors cannot shoulder. Prioritize notified body relationship maintenance as EMA MDR Annex I documentation burdens consolidate supplier panels. For New Entrants and Emerging Players: Enter via CDSCO-aligned validation corridors serving Hyderabad and Ahmedabad pharmaceutical export clusters where international compliance capabilities remain scarce. Target mid-volume pharmaceutical contract packagers in Ireland and Belgium displaced by headquarters-level procurement consolidation. Lead with metrology investment and third-party testing house partnerships to bypass multi-year qualification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing notified body relationships given EMA MDR Annex I enforcement tightening documentation requirements for Class III medical device closures. Five-to-ten year viability favors molders with in-house metrology capabilities over those dependent on external testing houses. Watch for inflection in pharmaceutical customer audit failure rates as a signal of supplier panel consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive food-grade polypropylene supply absorbs ECHA REACH testing costs that erode commodity competitor margins. |
| Metrology Capability Buildout | In-house cavity pressure monitoring and thread verification accelerates pharmaceutical customer qualification timelines. |
| Notified Body Relationship Establishment | EMA MDR Annex I compliance documentation becomes deliverable differentiator for Class III medical device closures. |
| Servo-Electric Mold Technology Adoption | Real-time process control achieves sub-0.1 millimeter thread precision for vision-verified capping system compatibility. |
| Post-Consumer Recycled Feedstock Validation | China MEE mandates for packaging recycled content create first-mover advantage in Asia-Pacific export corridors. |
Study Parameters
Trade databases, ECHA regulatory filings, and pharmaceutical packaging customs records formed the secondary backbone for demand quantification. Primary interviews with injection molding plant managers, pharmaceutical procurement leads at contract manufacturing organizations, notified body auditors, and food processor category buyers combined with bottom-up capacity modeling and top-down spend analysis. Triangulation across primary field contacts and secondary validation ensured segment-level accuracy for standard, specialty, and automated closure categories.
Historical trendline analysis of resin pricing volatility, tooling capacity utilization, and pharmaceutical filing volumes established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type precision tier, material certification grade, end-use regulatory intensity, and distribution channel concentration. CAGRs derived from weighted average of demand-side pharmaceutical pipeline expansion, supply-side molding capacity additions, and regulatory compliance timeline compression. Cold-chain torque consistency requirements and extractables documentation burdens served as pharmaceutical-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene feedstock disruption or accelerated ECHA restriction timelines. Model outputs reflect assumptions around REACH compliance deadline adherence, CDSCO-ICH Q3D alignment pace, and MEE recycled content mandate enforcement. A model refresh is warranted upon material change in pharmaceutical customer consolidation patterns or German-Swiss tooling capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
Dropper Caps Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
Bag Closures Market
Caps and Closures
Foamed End Caps Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market
Caps and Closures
IBC Caps Market
Caps and Closures
End Cap Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Lug Caps Market
Caps and Closures
Flapper Caps Market
Caps and Closures
Global Aluminum Caps and Closures Market