
 Flat Valve Caps and Closures Market | 2026-2036
Flat Valve Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Valve Caps and Closures Market Foresight
Asset-light leasing models for injection-molding equipment is tilting competitive dynamics toward mid-tier converters with limited capex budgets. Guala Closures Group leverages its European tooling network to sustain high-volume contracts for beverage valve closures. Aptar Group differentiates through precision-molded dispensing systems that dominate personal care and chemical applications. Amcor anchors its position with integrated resin-to-closure supply chains serving multinational paint brands.
Flat valve caps and closures are threaded sealing devices incorporating a one-way or pressure-equalization valve, typically injection-molded from polypropylene or polyethylene with silicone or elastomer valve inserts, designed to control gas exchange, prevent leakage, and maintain container integrity during storage and transport. Plastic caps command the largest volume share across paint containers and chemical drums due to cost efficiency and chemical resistance, while composite caps are gaining traction in food storage applications where oxygen barrier performance justifies premium positioning. Polypropylene dominates material selection for solvent-contact applications, with stainless steel variants occupying niche demand from oil refineries requiring flame-resistant closure systems.
REACH and the EU Green Deal are tightening restrictions on volatile organic compound emissions from paint and coating containers, directly shaping valve closure material specifications and recycling mandates in Europe. EPA regulations under the National Emission Standards for Hazardous Air Pollutants impose comparable containment requirements on U.S. chemical drum packaging, while China's GB standards for hazardous material transport containers influence export-oriented closure manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which material formats retain cost-competitive compliance access across major industrial markets.
Market Dynamics
REACH compliance in Europe is compressing material choices for chemical-contact closures, forcing converters to abandon legacy rubber formulations and validate silicone alternatives through accelerated aging protocols. Paint manufacturers in Germany's Ludwigshafen and Leverkusen clusters now specify tamper-evident valve closures as standard procurement terms, shifting competitive advantage toward suppliers with ECHA-registered polymer grades.
Growth Catalysts
- Solvent-based coating demand:Industrial paint production in Germany's chemical corridor is expanding procurement of tamper-evident valve closures to meet container integrity standards for volatile formulations.
- REACH material specifications:ECHA's tightening restrictions on volatile organic compound emissions are mandating silicone valve inserts over nitrile rubber in chemical-contact applications.
- Polypropylene process innovation:Injection-molding advancements in thin-wall valve seat geometry are reducing unit weight while maintaining pressure-equalization performance across solvent containers.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with propylene monomer supply from European crackers, compressing converter margins on fixed-price annual contracts.
- Tooling concentration:High-cavity injection molds for precision valve inserts concentrate among specialized toolmakers in southern Germany, creating supply bottlenecks for new market entrants.
- Stainless steel substitution:Oil refineries specify flame-resistant metal closures for drum applications, displacing plastic alternatives in niche but high-value segments.
Strategic Opportunities
- Food storage oxygen barriers:Composite cap structures combining polypropylene shells with ethylene vinyl alcohol interlayers are penetrating premium vacuum-sealed container markets.
- Extended producer responsibility frameworks:EU Green Deal recycling mandates favor mono-material polypropylene designs over multi-component assemblies, rewarding converters with in-house regrind capabilities.
- Asset-light equipment leasing:Mid-tier converters are accessing high-tonnage injection presses through operating leases, eroding the capital barrier that historically protected volume leaders.
Industry Challenges
- Silicone validation timelines:ECHA substance dossier requirements for novel valve insert elastomers extend certification cycles to 18-24 months, delaying product launches.
- Legacy system integration:Automated capping lines in established paint plants require mechanical retrofits to accommodate new tamper-evident closure geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Valve Caps and Closures Market |
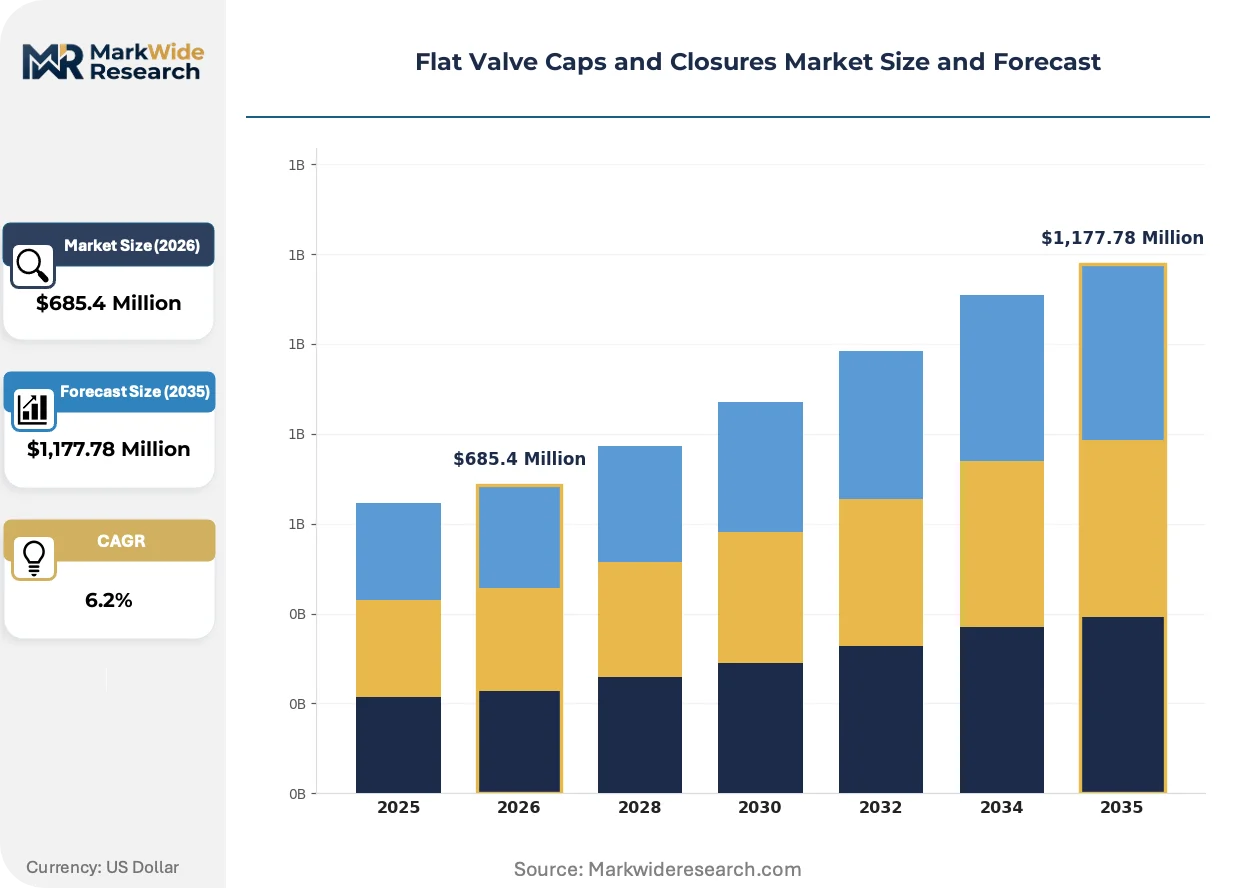
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Caps, Metal Caps, Composite Caps, Aluminum Caps, Brass Caps Material: Polypropylene, Polyethylene, Stainless Steel, Nylon, Copper Application: Paint Containers, Chemical Drums, Food Storage, Beverage Bottles, Lubricant Containers End User: Chemical Manufacturers, Food Processors, Beverage Producers, Paint Companies, Oil Refineries |
| Companies Covered | Guala Closures Group, Aptar Group, Amcor, Closure Systems International, UNITED CAPS, Crown Holdings, BERICAP Holdings, Berry Global, Silgan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Valve Caps and Closures Market Shifts & Advancements
Valve closure engineering is converging with sustainability mandates and precision dispensing requirements, compressing development cycles while expanding functional specifications. Material scientists and mold designers are collaborating on next-generation structures that satisfy both chemical resistance and circular economy targets.
Multi-layer co-injection technology is hybridizing polypropylene outer shells with thermoplastic elastomer valve seats in single-cycle production. Specialty chemical packagers in the Netherlands are qualifying these structures for solvent-based coating containers. The process is hybridizing cost structures by eliminating secondary assembly operations while enabling material separation at end-of-life for mechanical recycling streams.
EPA's National Emission Standards for Hazardous Air Pollutants are tightening containment specifications for chemical drum packaging in the United States. Closure manufacturers must now validate permeation resistance through standardized acetone exposure protocols. Drum reconditioners in Texas and Louisiana are retrofitting inventory with EPA-compliant valve caps ahead of enforcement phase-ins.
Direct procurement relationships between paint multinationals and specialized closure converters are displacing distributor intermediaries in high-volume solvent coating segments. Technical service teams from converter operations now embed directly at customer formulation labs to co-develop valve specifications. This pattern is most pronounced in Germany, where BASF and AkzoNobel facilities maintain resident engineer programs with preferred suppliers.
Flat Valve Caps and Closures Market Segmentation
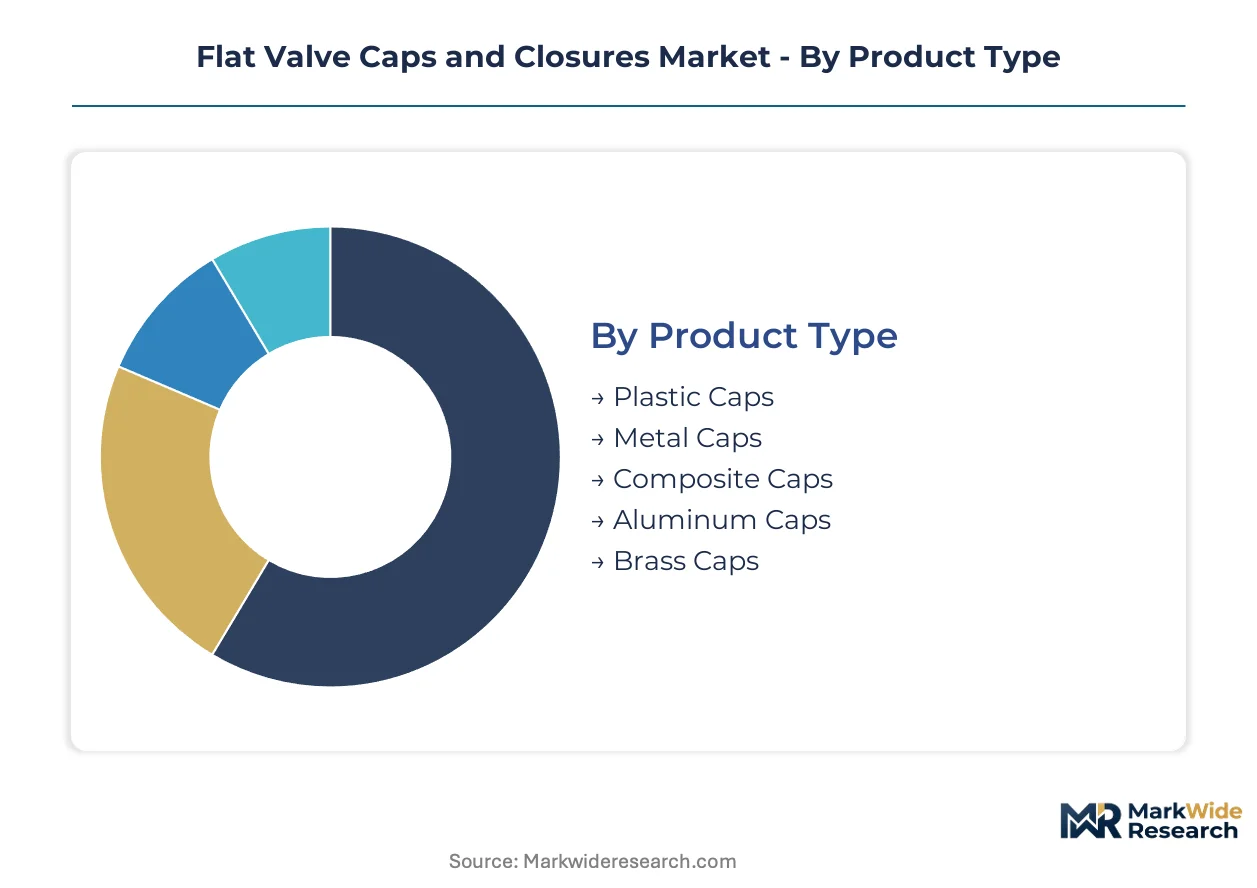
Segmentation in flat valve caps and closures reflects divergent technical requirements across chemical containment, food preservation, and industrial fluid management. Material compatibility with aggressive solvents, pressure-equalization performance, and regulatory compliance thresholds create distinct procurement patterns by end-use sector.
Product Type:
After-sales service intensity varies sharply across product categories, with composite and metal caps demanding specialized technical support for seal integrity validation and replacement protocols.
- Plastic Caps:Injection-molded polypropylene or polyethylene structures with integrated elastomer valve seats dominate solvent-based coating containers. German paint manufacturers in Ludwigshafen and Leverkusen specify these as standard for volatile formulation containment under REACH protocols.
- Metal Caps:Stainless steel, aluminum, and brass variants deliver flame-resistant sealing for oil refinery drum applications. Copper-threaded designs from specialized European toolmakers command premium positioning in high-temperature chemical processing environments.
- Composite Caps:Multi-layer structures combining polymer shells with oxygen barrier interlayers penetrate premium food storage segments.
- Aluminum Caps:Lightweight corrosion-resistant threading suits beverage carbonation pressure management.
- Brass Caps:Machined precision threading serves lubricant container specifications requiring thermal cycling durability.
Plastic caps hold the largest share; momentum sits with composite caps as oxygen barrier specifications tighten in food packaging.
Material:
Cost tier differentiation separates commodity polymer grades from engineered metal alloys, with validation timelines and ECHA registration requirements widening the procurement gap.
- Polypropylene:Dominates chemical-contact applications through solvent resistance and thin-wall injection-molding compatibility. REACH compliance mandates are accelerating silicone valve insert adoption over legacy nitrile rubber in German industrial coating clusters.
- Polyethylene:Lower-density alternative for non-aggressive fluid containers where permeation resistance requirements moderate.
- Stainless Steel:Flame-resistant specifications from oil refineries displace polymer alternatives in niche high-value drum sealing segments.
- Nylon:Engineering-grade polymer for high-torque capping line compatibility.
- Copper:Antimicrobial surface properties serve specialized food-contact valve applications.
Polypropylene commands volume leadership; stainless steel is climbing the fastest on safety-critical refinery procurement.
Application:
Volume concentration tracks industrial production clustering, with paint and chemical processing corridors driving procurement scale.
- Paint Containers:Tamper-evident valve closures are expanding as standard procurement terms for solvent-based coatings. EPA National Emission Standards for Hazardous Air Pollutants and REACH protocols mandate validated permeation resistance through standardized acetone exposure testing.
- Chemical Drums:Pressure-equalization valves prevent container deformation during transport of volatile formulations. Drum reconditioners in Texas and Louisiana are retrofitting inventory ahead of enforcement phase-ins.
- Food Storage:Vacuum-sealed container specifications favor composite cap structures with ethylene vinyl alcohol interlayers.
- Beverage Bottles:Carbonation retention drives precision-molded dispensing system requirements.
- Lubricant Containers:Thermal cycling durability specifications favor engineered polymer or metal threading.
Paint containers hold the largest share; food storage is gaining share fastest on premium oxygen barrier positioning.
End User:
Customer type determines technical service embedding depth, with chemical and paint multinationals demanding resident engineer programs for specification co-development.
- Chemical Manufacturers:Container integrity standards for hazardous material transport mandate validated valve closure systems. Direct procurement relationships are displacing distributor intermediaries in high-volume segments.
- Paint Companies:BASF and AkzoNobel facilities in Germany maintain embedded technical service teams with preferred closure suppliers for formulation lab collaboration.
- Food Processors:Extended producer responsibility frameworks under EU Green Deal favor mono-material designs for mechanical recycling compatibility.
- Beverage Producers:Precision dispensing requirements drive specification toward specialized converter networks.
- Oil Refineries:Flame-resistant metal closure specifications create insulated demand segments.
Chemical manufacturers hold the largest share; paint companies show steepest expansion trajectory on tamper-evident standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented closure manufacturers in Germany and the Netherlands supply precision-molded valve systems to chemical processors across North America and Asia-Pacific. Import dependency for silicone valve insert raw materials concentrates sourcing relationships with Asian polymer compounders.
Germany
Industrial paint production clusters in Ludwigshafen and Leverkusen drive concentrated procurement of tamper-evident valve closures for solvent-based coatings. ECHA's REACH protocols mandate silicone valve inserts over legacy nitrile rubber formulations, compressing material validation timelines to 18-24 months. BASF and AkzoNobel facilities maintain embedded technical service teams with preferred closure suppliers for specification co-development.
United States
EPA's National Emission Standards for Hazardous Air Pollutants are tightening containment specifications for chemical drum packaging ahead of enforcement phase-ins. Drum reconditioners in Texas and Louisiana are retrofitting inventory with compliant valve caps. Direct procurement relationships between paint multinationals and specialized converters are displacing distributor intermediaries in high-volume segments.
China
GB standards for hazardous material transport containers influence export-oriented closure manufacturers serving European and North American markets. Domestic chemical processors in the Yangtze River Delta are upgrading container integrity systems to meet international shipping requirements. Injection-molding equipment lessors are expanding asset-light access for mid-tier converters in Jiangsu and Zhejiang provinces.
Netherlands
Specialty chemical packagers are qualifying multi-layer co-injection valve closures for solvent-based coating containers. EU Green Deal recycling mandates favor mono-material polypropylene designs over multi-component assemblies. Rotterdam-area converters are investing in in-house regrind capabilities to maintain cost-competitive compliance access.
India
Domestic paint manufacturers are expanding procurement of valve closures for water-based and solvent-based formulations alike. BIS certification requirements for chemical-contact packaging materials are tightening quality thresholds for imported closure systems. Industrial coating production in Maharashtra and Gujarat is concentrating demand for pressure-equalization valve specifications.
Flat Valve Caps and Closures Market Competitive Landscape
On the supply side, the industry is consolidating around converters with ECHA-registered polymer grades and validated silicone valve insert formulations. Tiered competitive positioning separates integrated resin-to-closure suppliers from specialized precision-molding operations. Strategic archetypes include multinational packaging conglomerates with captive resin supply, European tooling networks sustaining high-volume beverage contracts, and asset-light mid-tier converters accessing leased injection capacity. Dominant competitive moves center on direct technical service embedding at customer formulation labs and backward integration into resin compounding.
Among European-anchored packaging specialists, Guala Closures Group and BERICAP Holdings occupy positions within the precision-tooling tier, while Aptar Group represents the dispensing systems specialization archetype. These companies exemplify contrasting strategic postures: tooling-network leverage versus precision-molded differentiation. Amcor anchors the integrated supply chain archetype with resin-to-closure capabilities serving multinational chemical brands. The competitive terrain rewards converters who combine ECHA-registered material portfolios with resident engineer programs at industrial coating clusters.
| Leading Market Players |
|---|
| Guala Closures Group |
| Aptar Group |
| Amcor |
| Closure Systems International |
| UNITED CAPS |
| Crown Holdings |
| BERICAP Holdings |
| Berry Global |
| Silgan Holdings |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese injection-molding equipment leasing is compressing converter margins across European solvent-container markets while simultaneously enabling mid-tier German and Dutch players to sustain price-competitive silicone valve insert offerings under REACH mandates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across paint and chemical drum segments. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered silicone formulations from legacy nitrile rubber and unvalidated imports. Cost compression in standard-tier polypropylene closures is intensifying because propylene monomer supply volatility from European crackers feeds directly into converter pricing. Mid-tier asset-light converters show highest price sensitivity, while integrated resin-to-closure suppliers at BASF and AkzoNobel procurement desks demonstrate lowest.
Supply Chain Analysis
Propylene monomer supply concentrates in Germany, the Netherlands, and Belgium, with silicone valve insert compounding anchored in South Korean and Japanese specialty polymer operations. Raw material dependencies span propylene feedstock, high-purity silicone elastomers, and precision mold tooling from southern German toolmakers. Single-source vulnerability around high-cavity injection molds for thin-wall valve seat geometry creates supply bottlenecks for new market entrants. Distribution runs through direct procurement relationships between paint multinationals and specialized converters, displacing distributor intermediaries in high-volume solvent coating segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ECHA-registered polymer grades and 18-24 month silicone validation timelines constructs a formidable defensive moat for incumbent converters with established certification dossiers.
For Market Incumbents: Insulate market position by deepening backward integration into resin compounding for REACH-compliant polypropylene grades and embedding resident engineer programs at Ludwigshafen and Leverkusen coating clusters. Asset-light leasing models from emerging Jiangsu and Zhejiang converters threaten volume leadership in standard-tier segments. For New Entrants and Emerging Players: Pursue white-space opportunities in food storage oxygen barrier applications where composite cap structures with ethylene vinyl alcohol interlayers command premium positioning. The Netherlands specialty chemical packaging corridor offers the most penetrable geography for multi-layer co-injection qualification. A technical service embedding strategy at customer formulation labs accelerates specification co-development timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with captive ECHA-registered material portfolios and long-term direct procurement contracts with paint multinationals. Long-term viability across the analysis window favors acquisition targets combining in-house regrind capabilities with mono-material polypropylene design expertise. Monitor EPA enforcement phase-ins for National Emission Standards for Hazardous Air Pollutants as the signal for North American retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | ECHA-registered polymer grades secure REACH compliance access for German paint cluster procurement. |
| Multi-layer Co-injection Technology Deployment | Netherlands specialty packagers qualify hybrid structures for solvent-based coating container applications. |
| In-house Regrind Capability Investment | EU Green Deal recycling mandates reward mono-material polypropylene designs with mechanical recycling compatibility. |
| Resident Engineer Program Expansion | BASF and AkzoNobel facilities embed technical service teams for specification co-development. |
| Asset-light Equipment Leasing Access | Mid-tier converters in Jiangsu and Zhejiang erode capital barriers protecting volume leaders. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at German industrial coating facilities, procurement leads at paint multinationals, distribution channel partners in the Netherlands, and technical R&D directors at silicone valve insert compounders; and secondary validation through ECHA substance dossier records, customs and trade data for polypropylene resin flows, Cefic chemical industry reports, and SEC filings from packaging conglomerates. Bottom-up and top-down triangulation cross-checked regional production cluster outputs against end-use demand aggregation.
Forecast inputs considered material substitution dynamics, regulatory enforcement timelines, and capacity utilization across injection-molding networks. Segmentation dimensions modeled include product type tier, end-use application, material grade, and regional production hub clustering. CAGRs were derived through iterative reconciliation of supply-side capacity expansion against demand-pull from solvent-based coating production corridors. Industry-specific forecast inputs encompass REACH compliance cost pass-through rates and EPA enforcement phase-in schedules for chemical drum packaging.
Sensitivities concentrate around propylene monomer price volatility, ECHA validation timeline extensions for novel elastomer formulations, and substitution acceleration toward stainless steel in oil refinery applications. Cross-checking against Cefic chemical production indices and ECHA registration database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Cap Seals Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Box Latch Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Non-Aerosol Overcaps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Gable Top Cap and Closures Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market