
 Global Aluminum Caps and Closures Market | 2026-2036
Global Aluminum Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Caps and Closures Market Foresight
Aftermarket refurbishment of crimping and capping equipment is reshaping margin pools across the value chain. Guala Closures leverages its Italian manufacturing heritage to dominate premium spirits closure design. Closure Systems International anchors North American beverage supply through high-speed rotary capping lines. Crown Holdings, Inc. extends its metal packaging empire into aluminum closures with integrated sheet-to-cap production.
Aluminum caps and closures are threaded or press-fit sealing devices manufactured from 3000-series or 8000-series aluminum alloy sheet, typically 0.20–0.35 mm thick, formed through deep drawing, knurling, and liner insertion to create hermetic seals for bottles and containers. Their primary purpose is to preserve product integrity, enable tamper evidence, and support repeated opening cycles across liquid and semi-solid packaged goods. Screw caps occupy the largest volume position in beverages, where standardization around ROPP (Roll-On Pilfer-Proof) neck finishes drives procurement consolidation. Pharmaceutical grade material commands the tightest specification band and carries the highest per-unit margin, as CDSCO, FDA, and EMA all mandate extractables testing and batch traceability for drug-contact closures. Child-resistant caps represent the fastest-growing product type, propelled by poison-prevention regulations in household chemicals and over-the-counter medications.
FDA enforces 21 CFR 177.1390 for indirect food additives in closure liners, while EMA's MDR and REACH compliance requirements shape aluminum sourcing and coating chemistry for European pharmaceutical and cosmetic applications. China's NMPA and GB standards impose additional sterility validation layers on imported closure systems for injectable drugs. Stakeholders must monitor divergence between regional recyclability mandates and alloy purity specifications, as closed-loop collection infrastructure matures at uneven speeds across major consumption clusters.
Market Dynamics
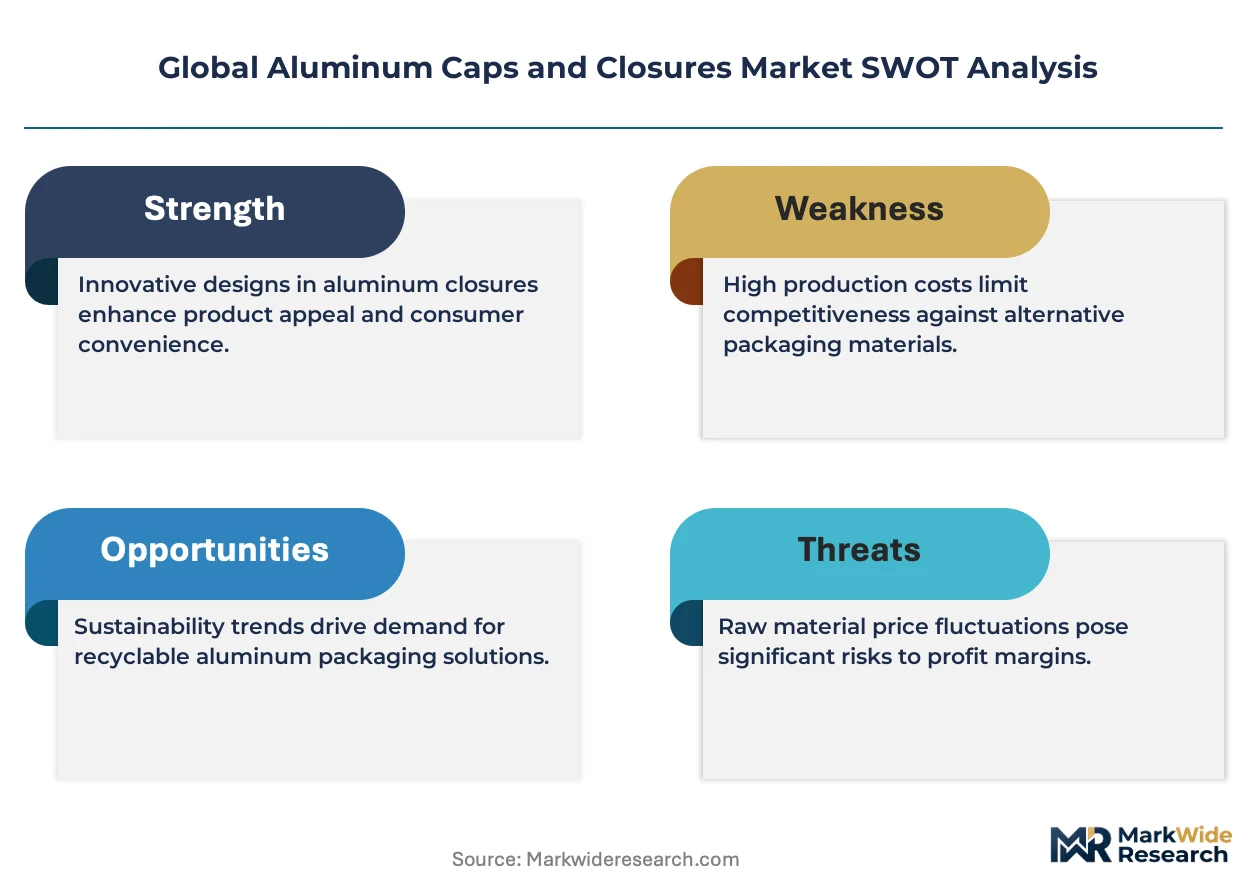
EU Packaging and Packaging Waste Regulation mandates are compressing multi-material closure designs toward mono-material aluminum formats, forcing converters to retool liner chemistry and knurling specifications across European beverage and pharmaceutical supply chains.
Growth Catalysts
- REACH compliance evolution:ECHA's tightening extractables thresholds for indirect food contact are disqualifying polymer-lined closures, redirecting spirits and wine bottlers toward unlined or food-grade lacquered aluminum alternatives that simplify compliance documentation.
- Pharmaceutical serialization:CDSCO and FDA track-and-trace mandates for sterile barrier systems are elevating aluminum's batch traceability advantage over plastic alternatives in parenteral drug packaging corridors.
- Child-resistant mechanism standardization:Poison Prevention Packaging Act requirements in household chemicals and OTC medications are driving tooling investments for push-and-turn aluminum designs that integrate tamper evidence with senior-friendly ergonomics.
Market Restraints
- LME aluminum volatility:Primary ingot price swings transmit directly to 3000-series sheet costs, compressing converter margins on fixed-price annual contracts with beverage bottlers.
- Deep-drawing equipment concentration:High-speed press and liner insertion machinery supply concentrates among German and Italian original equipment manufacturers, creating 18-24 month lead time bottlenecks for capacity expansion.
- Polymer substitution in low-value beverages:Polypropylene screw caps retain cost advantage in carbonated soft drinks and bulk water segments where oxygen ingress tolerance permits material downgrade.
Strategic Opportunities
- India pharmaceutical corridor:Domestic injectable drug manufacturers scaling under PLI scheme incentives are importing sterile aluminum closures at premium specifications, creating localization opportunities for alloy slitting and liner insertion operations.
- Digital printing convergence:Direct-to-metal inkjet systems are hybridizing with traditional offset decoration, enabling lot-size-one customization for craft spirits brands without cylinder changeover costs.
- Closed-loop collection infrastructure:EU Green Deal circular economy action plan subsidies for aluminum beverage can and closure co-collection are improving scrap purity streams that feed secondary alloy production.
Industry Challenges
- Extractables validation timelines:USP Class VI and ISO 10993 biocompatibility testing for pharmaceutical-grade lacquers extends new product qualification to 14-18 months, delaying revenue recognition on customized closure programs.
- ROPP neck finish standardization gaps:Divergent thread specifications between European EN and American GPI standards force converters to maintain dual tooling inventories, inflating working capital requirements for global beverage accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Caps and Closures Market |
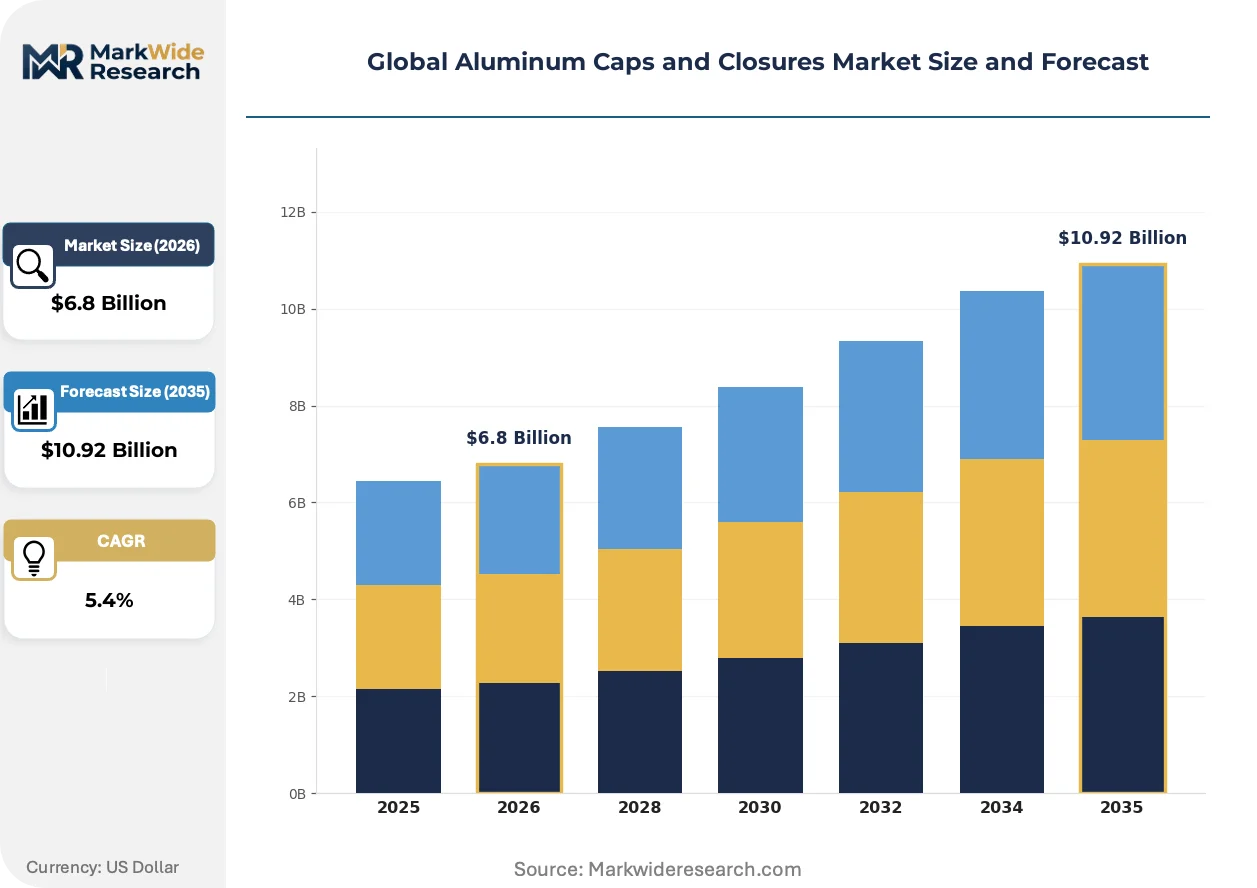
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Press-On Caps, Flip-Top Caps, Dispensing Caps, Child-Resistant Caps Material Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade, Beverage Grade Application: Beverages, Pharmaceuticals, Cosmetics, Chemicals, Household Products Customer Type: Beverage Manufacturers, Pharmaceutical Companies, Personal Care Brands, Chemical Producers, Packaging Firms |
| Companies Covered | Guala Closures, Closure Systems International, Crown Holdings, Inc., Herti JSC, Nippon Closures Co. Ltd., Silgan Holdings, Inc., Pelliconi & C. SpA, Federfin Tech S.R.L, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Caps and Closures Market Shifts & Advancements
Active material science and regulatory chemistry revisions are compressing traditional closure design cycles, while digital manufacturing tools embed customization capabilities that previously required dedicated production lines.
Smart closure technologies incorporating NFC tags and tamper-evident sensors are hybridizing with conventional aluminum shell structures. Premium spirits brands in France and Germany are piloting these connected formats for authentication and consumer engagement programs. The structural consequence is a bifurcation between commodity screw caps and value-added intelligent closure platforms that command 3-4x unit premiums.
EMA's Medical Device Regulation reclassification of certain drug-contact closures as Class IIa devices is imposing quality management system audits on previously exempt converters. European pharmaceutical packaging suppliers are responding by segregating production lines and dedicating cleanroom capacity to MDR-compliant operations. This regulatory friction is accelerating consolidation among mid-tier European closure manufacturers lacking certification resources.
Brand owners in wine and spirits are compressing supplier rosters from multi-source regional procurement to single-source global framework agreements with tier-one converters. This concentration behavior is most visible in Germany's premium Riesling and sparkling wine sectors, where Guala Closures and similar integrated suppliers capture multi-year exclusivity through design-to-cost engineering partnerships that lock out smaller competitors.
Global Aluminum Caps and Closures Market Segmentation
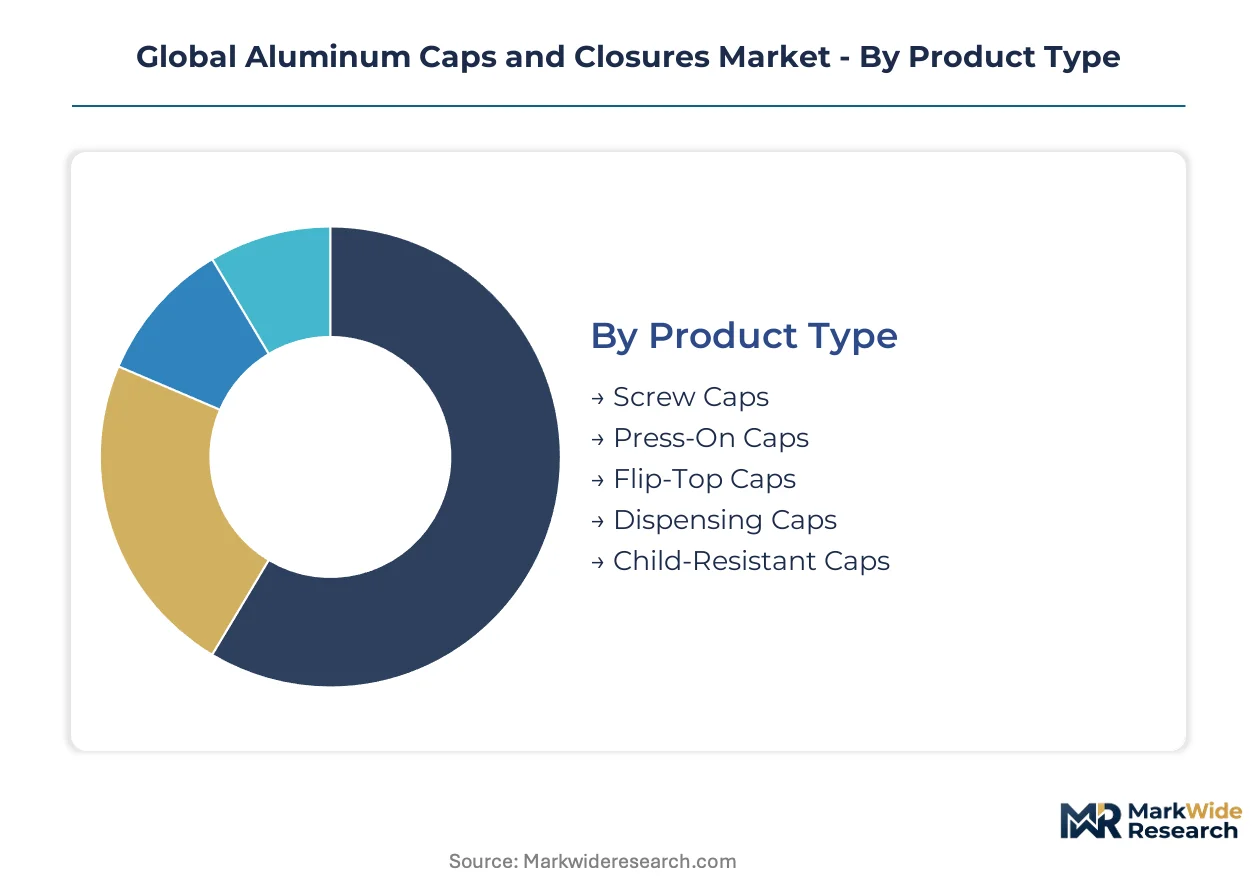
Segmentation in aluminum caps and closures reflects divergent specification bands across regulatory environments. Material grade purity thresholds and application-specific barrier requirements create distinct procurement clusters with non-overlapping supplier qualifications.
Product Type:
Closure mechanism determines sealing performance, tamper evidence capability, and line speed compatibility across filling operations.
- Screw Caps:Threaded ROPP designs dominate wine and spirits bottling through standardized neck finishes. German premium Riesling producers are converting from cork to aluminum screw caps under ECHA extractables compliance pressure.
- Child-Resistant Caps:Push-and-turn mechanisms integrate senior-friendly ergonomics with poison-prevention mandates. FDA Poison Prevention Packaging Act enforcement is elevating demand from US OTC pharmaceutical and household chemical bottlers.
- Press-On Caps:Crimped designs for aerosol and tube applications.
- Flip-Top Caps:Hinged dispensing formats for personal care and condiments.
- Dispensing Caps:Orifice-control designs for viscous products and controlled dosing.
Screw caps hold installed capacity. Child-resistant caps are rotating up the share rankings.
Material Grade:
Purity specifications cascade from extractables testing requirements through alloy sourcing and coating chemistry decisions.
- Pharmaceutical Grade:USP Class VI and ISO 10993 biocompatibility validation mandates 14-18 month qualification timelines. CDSCO track-and-trace requirements for sterile barrier systems favor aluminum's batch traceability in India's injectable drug corridor.
- Food Grade:FDA 21 CFR 177.1390 compliance for indirect food additives in closure liners. REACH extractables thresholds are disqualifying polymer-lined alternatives across European spirits bottling.
- Beverage Grade:Oxygen ingress specifications for carbonated and still drinks.
- Cosmetic Grade:EMA MDR reclassification pressures for certain drug-contact closures.
- Industrial Grade:Lower specification band for non-consumable chemical containment.
Pharmaceutical grade commands margin premiums. Food grade is climbing the fastest on regulatory substitution effects.
Application:
End-use sectors impose distinct barrier, sterility, and child-safety requirements that filter supplier eligibility.
- Beverages:Wine, spirits, and premium water segments drive ROPP standardization. France and Germany lead cork-to-aluminum conversion for premium still and sparkling wines under EU Packaging and Packaging Waste Regulation recyclability mandates.
- Pharmaceuticals:Sterile barrier systems for parenteral drugs command tightest specification bands. China's NMPA imposes additional sterility validation layers on imported closure systems for injectable drugs.
- Cosmetics:Dispensing and airless pump integration requirements.
- Chemicals:Corrosion resistance for aggressive formulations.
- Household Products:Child-resistant mandates for cleaning and maintenance chemicals.
Beverages anchor volume throughput. Pharmaceuticals is expanding most quickly on serialization and sterility demands.
Customer Type:
Procurement concentration and vertical integration depth vary sharply across buyer categories.
- Pharmaceutical Companies:Serialization mandates and sterile barrier requirements drive long-term supplier relationships. Domestic Indian drug manufacturers scaling under PLI scheme incentives are importing premium-specification closures, creating localization opportunities.
- Beverage Manufacturers:High-speed rotary capping line integration and global framework agreements favor tier-one converters with design-to-cost engineering capabilities.
- Personal Care Brands:Lot-size-one customization demand from craft and premium positioning.
- Chemical Producers:Child-resistant specification compliance for regulated formulations.
- Packaging Firms:Converter and distributor intermediaries serving fragmented regional accounts.
Pharmaceutical companies lock in supplier capacity. Beverage manufacturers are gaining share fastest on procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed press and liner insertion machinery supply concentrates among German and Italian original equipment manufacturers, creating 18-24 month lead time bottlenecks for capacity expansion across the value chain.
United States
FDA Poison Prevention Packaging Act enforcement elevates demand for push-and-turn aluminum designs from US OTC pharmaceutical and household chemical bottlers. The 21 CFR 177.1390 framework for indirect food additives in closure liners shapes coating chemistry decisions. Closure Systems International anchors North American beverage supply through high-speed rotary capping lines in the Midwest manufacturing corridor.
Germany
Premium Riesling and sparkling wine producers are converting from cork to aluminum screw caps under ECHA extractables compliance pressure. REACH thresholds for indirect food contact disqualify polymer-lined alternatives across spirits bottling. Bavaria's precision engineering cluster supplies deep-drawing equipment and knurling machinery to converters throughout Europe.
France
Champagne houses and premium still wine estates pilot NFC-enabled smart closures for authentication and consumer engagement programs. EMA's Medical Device Regulation reclassification of certain drug-contact closures imposes quality management system audits on previously exempt converters. The Île-de-France packaging innovation cluster hosts pilot programs for digital direct-to-metal inkjet decoration systems.
China
Domestic injectable drug manufacturers scaling sterile barrier systems drive demand in the pharmaceutical packaging corridor. NMPA and GB standards impose additional sterility validation layers on imported closure systems for parenteral drugs. The Yangtze River Delta concentration of alloy slitting and liner insertion operations is expanding to serve localization mandates.
India
Domestic drug manufacturers scaling under PLI scheme incentives import sterile aluminum closures at premium specifications. CDSCO track-and-trace mandates for sterile barrier systems favor aluminum's batch traceability in the injectable drug corridor. Maharashtra's pharmaceutical manufacturing belt is attracting investment in localized alloy slitting and liner insertion capacity.
Global Aluminum Caps and Closures Market Competitive Landscape
Vertically integrated specialists and regional equipment fabricators split the market into distinct capability tiers. Tier-one converters with captive sheet supply and in-house liner chemistry control pricing and design-to-cost partnerships with global beverage accounts. Mid-tier regional players concentrate on pharmaceutical-grade qualification and cleanroom-segregated production lines. Dominant competitive moves include M&A to secure alloy slitting capacity and strategic partnerships for digital printing convergence.
Among Italian heritage manufacturers, Guala Closures and Pelliconi & C. SpA exemplify the design-to-cost engineering archetype that captures multi-year exclusivity in premium spirits. Crown Holdings, Inc. anchors the integrated metal packaging tier with captive sheet-to-cap production capabilities. These three entities represent the consolidation trajectory as brand owners compress supplier rosters from multi-source regional procurement toward single-source global framework agreements.
| Leading Market Players |
|---|
| Guala Closures |
| Closure Systems International |
| Crown Holdings, Inc. |
| Herti JSC |
| Nippon Closures Co. Ltd. |
| Silgan Holdings, Inc. |
| Pelliconi & C. SpA |
| Federfin Tech S.R.L |
| Amcor plc |
| Others |
Supply & Pricing Matrix
Undercapacity in European deep-drawing equipment supply is compressing converter margins while amplifying pricing power for German and Italian machinery suppliers who control 18-24 month order backlogs. This utilization asymmetry forces closure manufacturers to pass alloy volatility through fixed-price beverage contracts or absorb losses, reshaping procurement behavior toward captive sheet supply and long-term equipment partnerships.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European pharmaceutical and spirits applications, separating USP Class VI-validated pharmaceutical grades from food-grade lacquered alternatives and standard beverage specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with batch traceability and extractables documentation commanding substantial premiums over commodity ROPP designs. Cost compression in standard beverage grades is intensifying because LME aluminum volatility transmits directly through 3000-series sheet contracts, while pharmaceutical buyers show lowest price sensitivity due to 14-18 month qualification lock-in effects.
Supply Chain Analysis
Extended payment terms from tier-one beverage bottlers are squeezing working capital across mid-tier converters, forcing reliance on supply-chain finance facilities anchored in German and Italian equipment vendor programs. Raw material flows draw from primary aluminum smelting in China, Russia, and Canada, with 3000-series and 8000-series alloy slitting concentrated in the Yangtze River Delta, Bavaria, and the US Midwest. Single-source vulnerability runs through German and Italian original equipment manufacturers for high-speed press and liner insertion machinery. Distribution runs through direct converter relationships with global beverage frameworks and pharmaceutical sterilization facilities, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket refurbishment and digital printing services are expanding faster than hardware sales, creating recurring-revenue layers that improve lifetime customer value and reduce cyclical exposure to capital equipment cycles.
For Market Incumbents: Harden captive supply positions through backward integration into alloy slitting and liner chemistry formulation, insulating margin structures from LME volatility and REACH compliance cost spikes. Consolidate design-to-cost engineering partnerships with premium spirits bottlers in Germany and France before smaller competitors secure cleanroom-segregated pharmaceutical capacity under EMA MDR reclassification pressures. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical packaging corridor by localizing sterile barrier closure production for domestic injectable drug manufacturers scaling under PLI scheme incentives. Target digital direct-to-metal inkjet decoration services for craft spirits brands seeking lot-size-one customization without cylinder changeover costs, leveraging hybrid equipment partnerships with Italian machinery suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with integrated aftermarket service networks and pharmaceutical-grade certification portfolios that lock in multi-year sterile barrier supply agreements. Long-term viability favors targets with captive alloy slitting, cleanroom-segregated production lines, and established track-and-trace compliance for CDSCO and FDA serialization mandates. Watch for inflection signals in EU Green Deal circular economy subsidy flows that accelerate closed-loop aluminum collection infrastructure and secondary alloy purity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Slitting | Captive 3000-series sheet supply insulates margins from LME volatility and REACH compliance spikes. |
| Cleanroom Production Line Segregation | EMA MDR reclassification mandates quality management system audits for pharmaceutical-grade closures. |
| Digital Direct-to-Metal Inkjet Deployment | Hybrid decoration systems enable lot-size-one customization for craft spirits brands without cylinder costs. |
| Pharmaceutical Serialization Partnership | CDSCO and FDA track-and-trace mandates favor aluminum's batch traceability in sterile barrier systems. |
| Closed-Loop Collection Infrastructure | EU Green Deal subsidies for aluminum beverage can and closure co-collection improve secondary alloy purity streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports, combining structured interviews with closure manufacturing executives, pharmaceutical packaging procurement managers, beverage bottler supply chain directors, and deep-drawing equipment specialists with bottom-up and top-down triangulation. Primary engagement spans tier-one converters, mid-tier regional players, and machinery original equipment manufacturers across Germany, Italy, China, and India. Secondary validation draws from FDA 21 CFR filings, EMA MDR guidance documents, CDSCO track-and-trace notifications, LME aluminum price series, and EU Packaging and Packaging Waste Regulation impact assessments.
Forecast inputs incorporate closure mechanism type, material grade purity band, end-use application sector, and regional regulatory cluster across the projection horizon. Segmentation modeling spans screw caps, child-resistant designs, and press-on formats against pharmaceutical, beverage, cosmetic, and chemical applications. CAGRs derive from installed capacity utilization rates, conversion cost trajectories, and substitution elasticity estimates between aluminum and polymer alternatives. Industry-specific inputs include ECHA extractables threshold evolution, PLI scheme incentive flows in India, and NFC-enabled smart closure adoption curves in premium spirits.
Sensitivities concentrate around LME aluminum price volatility, REACH compliance timeline extensions, and pharmaceutical qualification delay risks. Forecasts reflect documented assumptions on regulatory harmonization, equipment lead time normalization, and closed-loop collection infrastructure maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Saudi Arabia Plastic Caps and Closures Market
Caps and Closures
Ribbed Phenolic Caps Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Thailand Plastic Caps and Closures Market
Caps and Closures
Vietnam Plastic Caps and Closures Market