
 Rubber Membrane Market | 2026-2036
Rubber Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Membrane Market Analysis
Performance-grade EPDM membrane specifications is unwinding legacy commodity positioning across the industry. Carlisle Companies leverages captive polymer sourcing to sustain margin stability in North American roofing channels. Sika AG anchors European specification-grade demand through direct contractor relationships and technical service depth. Firestone Building Products Company competes on installed-system warranties that extend beyond membrane-only coverage.
Rubber membrane denotes a flexible, elastomeric sheet material manufactured from synthetic polymers such as ethylene propylene diene monomer (EPDM), neoprene, or silicone, typically calendered to thicknesses between 0.8 mm and 2.0 mm and engineered to provide impermeable barriers against moisture, gases, or chemicals. EPDM sheets dominate commercial roofing specifications due to decades of ultraviolet resistance validation, while liquid-applied silicone membranes capture fastest growth in complex geometric waterproofing where sheet seams create vulnerability. Sheet and roll forms still occupy the majority of construction procurement volumes, though liquid formats are displacing traditional approaches in renovation contexts where substrate access is constrained.
REACH compliance in Europe and EPA construction-volatile organic compound rules in the United States constrain adhesive and primer chemistries that bond membranes to substrates, pushing reformulation toward water-based systems. The EU F-Gas Regulation and corresponding state-level California Air Resources Board measures restrict blowing agents in insulated membrane assemblies, altering product stack specifications. Stakeholders must monitor regulatory divergence between jurisdictions when configuring multi-region product portfolios.
Market Dynamics
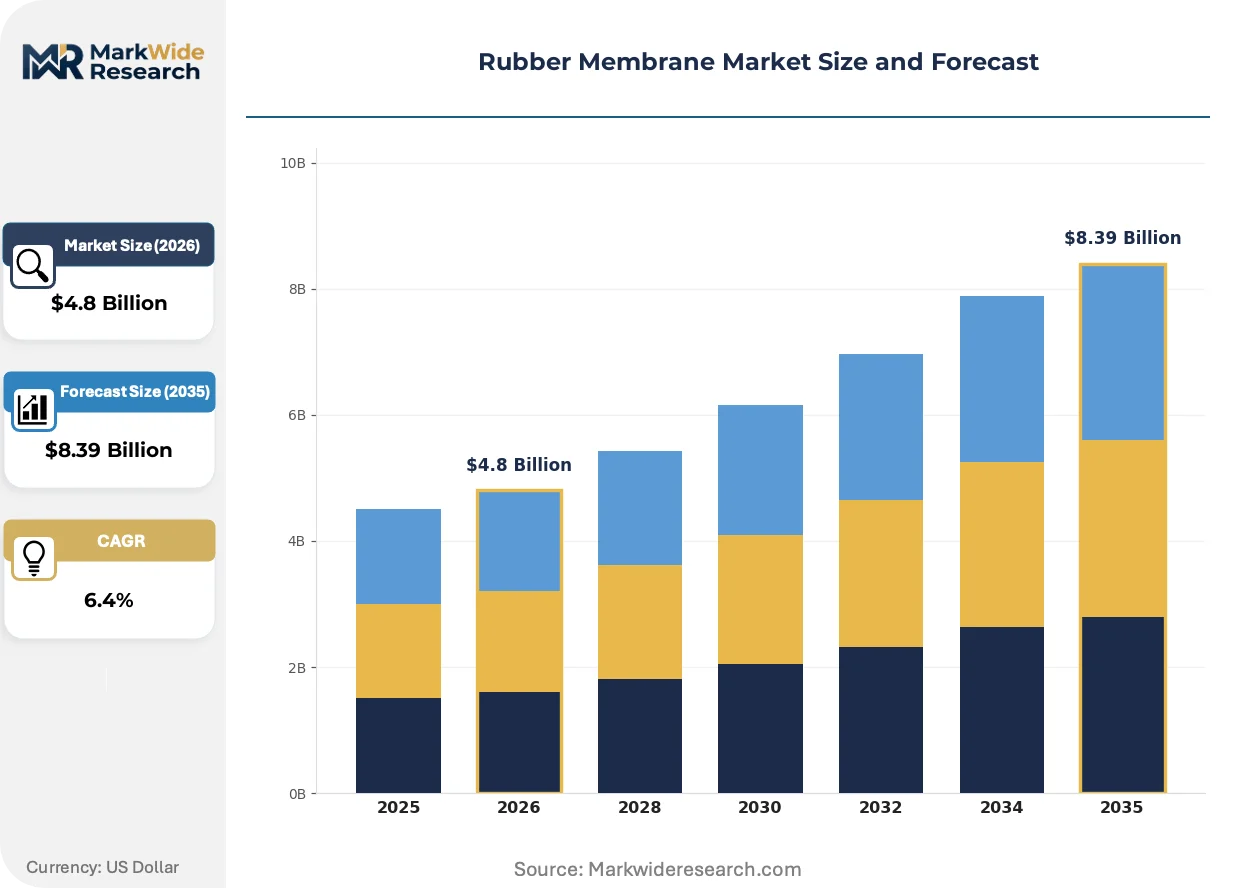
The rubber membrane market is undergoing structural recalibration as regulatory pressure on high-global-warming-potential blowing agents forces reformulation of insulated membrane assemblies, compelling manufacturers to reconfigure supply chains and product specifications across multiple jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of HFC blowing agents is accelerating investment in next-generation foam technologies for insulated roofing systems, creating specification-grade demand for compliant membrane assemblies in German and French commercial construction.
- Energy-efficient building retrofits:Germany's federal funding programs for building envelope upgrades are channeling procurement toward high-performance EPDM systems with validated thermal bridging reduction.
- Liquid-applied silicone membranes:Complex geometric waterproofing in renovation contexts is driving fastest adoption where sheet membrane seams present installation vulnerability.
Market Restraints
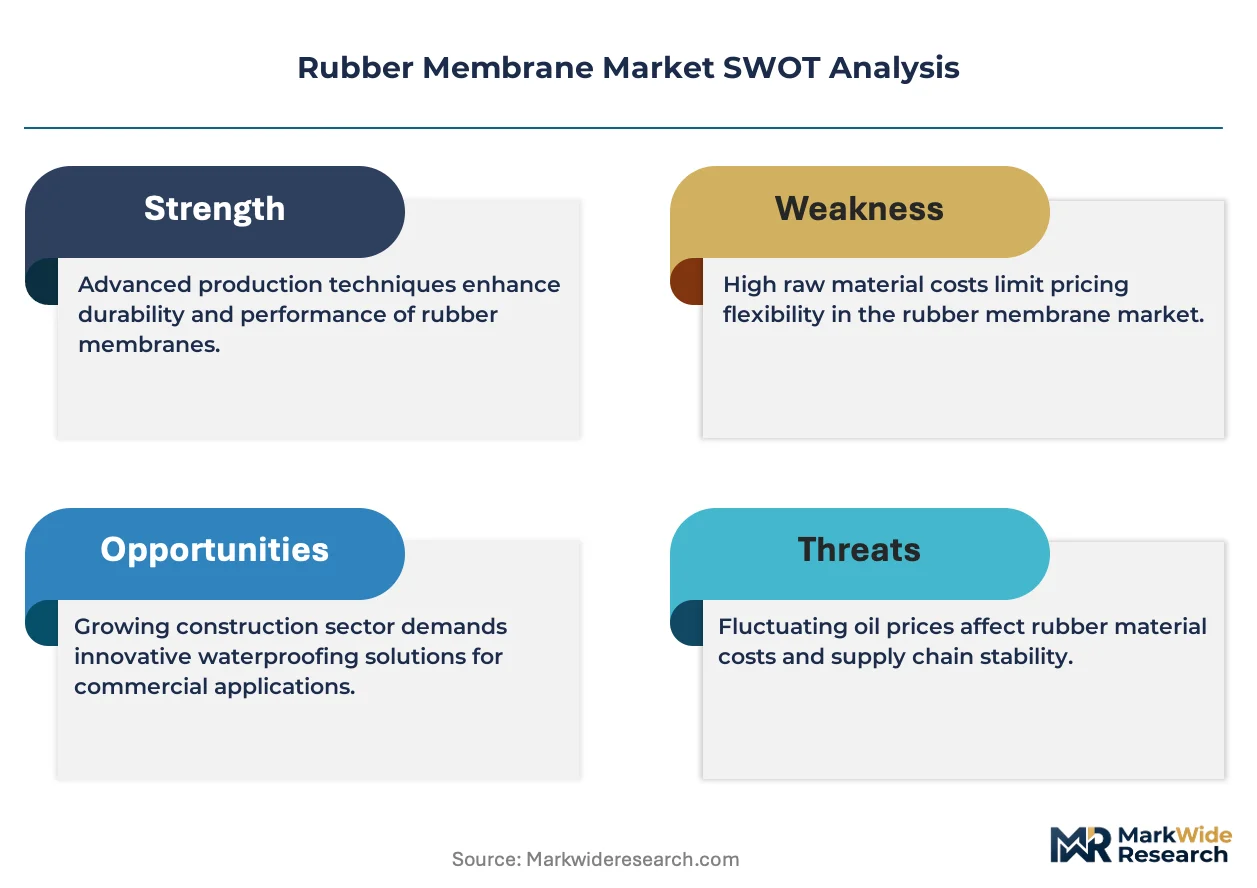
- Petrochemical feedstock volatility:EPDM polymer production depends on ethylene and propylene derivatives, exposing membrane manufacturers to naphtha-cracking margin compression.
- Adhesive chemistry constraints:EPA construction-VOC rules and REACH compliance in Europe are restricting solvent-based bonding systems, forcing costly water-based reformulation.
- Thermoplastic polyolefin substitution:TPO membranes are capturing share in cost-sensitive commercial roofing specifications where reflectivity ratings drive procurement decisions.
Strategic Opportunities
- California Air Resources Board measures:State-level restrictions on high-GWP blowing agents are creating first-mover advantage for membrane suppliers with CARB-compliant product lines.
- Direct contractor relationships:Bypassing traditional distribution through specification-grade technical service models is unlocking margin capture in European roofing channels.
- Installed-system warranties:Extending coverage beyond membrane-only to full assembly performance is differentiating offerings in risk-averse commercial property markets.
Industry Challenges
- Certified installer scarcity:Liquid-applied silicone application requires specialized training and substrate assessment capabilities that outpace current workforce development.
- Multi-jurisdiction portfolio complexity:Divergent regulatory timelines between EU F-Gas phaseout and state-level US measures are fragmenting R&D allocation and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Membrane Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, Neoprene, Silicone, Butyl Application: Waterproofing, Roofing, Flooring, Lining End User: Construction, Automotive, Aerospace, Industrial Form: Sheets, Rolls, Liquid, Granules |
| Companies Covered | SealEco, Soprema Group, Carlisle Companies, Sika AG, Dow, BASF, GAF Materials Corporation, Firestone Building Products Company, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Membrane Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are actively splitting the market between high-performance specification-grade systems and commodity alternatives, with installation methodology and warranty structure becoming primary differentiation vectors.
Reinforced EPDM membrane technology is bifurcating the commercial roofing segment. Polyester-fleece backed sheets deliver dimensional stability for mechanically attached systems in high-wind zones. Specification engineers in US Gulf Coast and Atlantic seaboard markets are specifying these variants at accelerating rates. The technology is bifurcating procurement patterns between wind-uplift-rated assemblies and standard adhered systems.
REACH authorization requirements for diisocyanate-containing adhesives are constraining bonding system availability across European construction markets. Industrial consequence includes accelerated migration toward water-based and moisture-cure polyurethane alternatives with reformulated isocyanate content. German roofing contractors are most affected, with technical service providers scrambling to certify replacement chemistries before 2023 sunset dates.
Building owners are unbundling membrane procurement from installation services, creating direct material sourcing channels that bypass traditional roofing contractor markups. This disintermediation is compressing distributor margins while favoring manufacturers with captive technical service networks. The pattern is most visible in US commercial property management, where portfolio-scale purchasing centralizes specification authority.
Rubber Membrane Market Segmentation
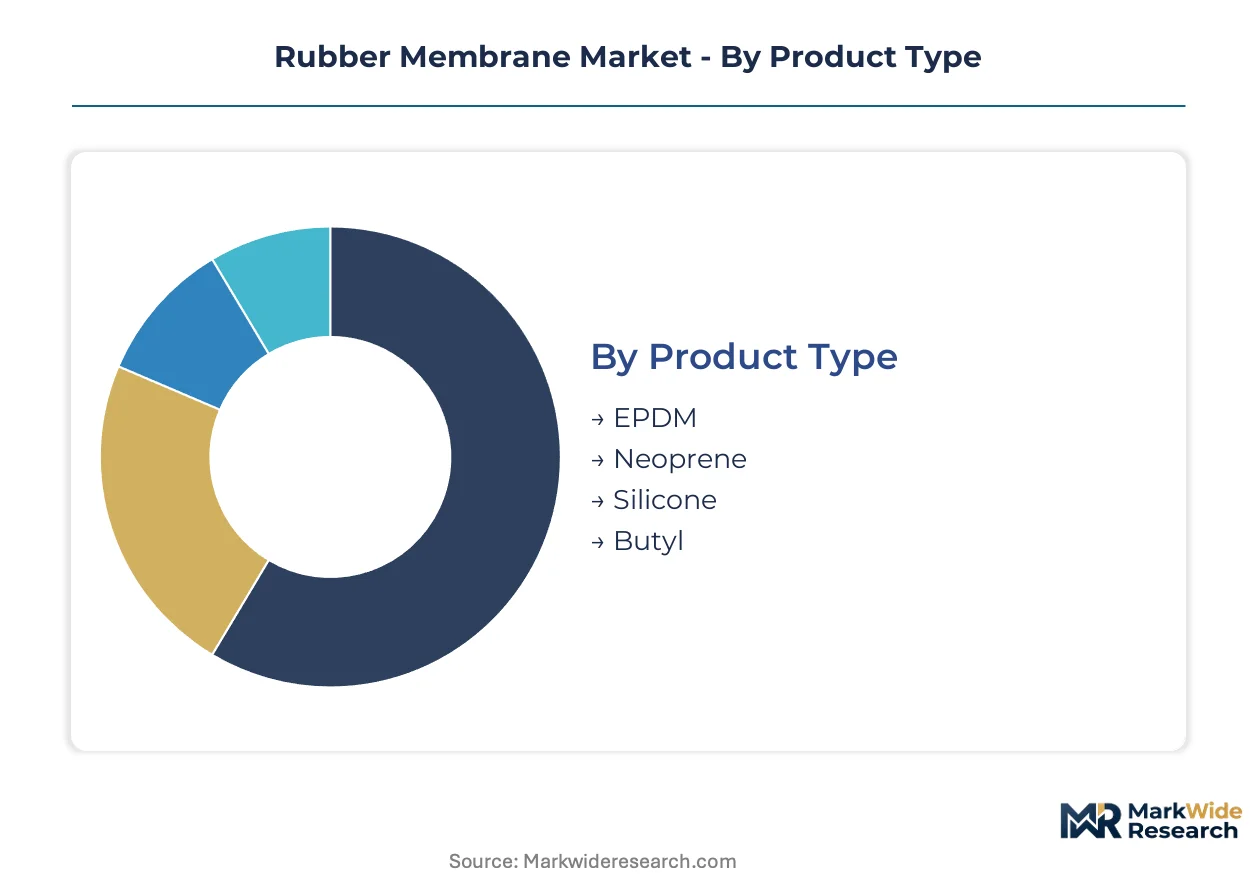
Product heterogeneity in rubber membranes creates divergent substitution economics across polymer chemistries and application formats. Specification engineers trade ultraviolet resistance, seam integrity, and installation labor intensity when selecting between EPDM sheets and liquid-applied alternatives.
Product Type:
EPDM faces intensifying substitution pressure from thermoplastic polyolefin membranes in cost-sensitive commercial roofing, while silicone liquid formulations capture specification share in complex geometries where sheet seams create vulnerability.
- EPDM:Ethylene propylene diene monomer sheets dominate commercial roofing specifications through decades of ultraviolet resistance validation. German energy-efficient building retrofits channel procurement toward high-performance EPDM systems with thermal bridging reduction.
- Silicone:Liquid-applied formulations capture fastest adoption in renovation contexts where substrate access constrains sheet installation. Complex geometric waterproofing in US commercial property management drives specification away from seam-dependent alternatives.
- Neoprene:Chloroprene-based membranes deliver chemical resistance for industrial containment applications.
- Butyl:Isobutylene-isoprene copolymers provide gas-impermeable barriers in HVAC and aerospace sealing.
EPDM anchors the volume base while silicone gains share at the steepest rate.
Application:
Margin structures vary sharply between exposed roofing systems requiring long-duration warranties and concealed waterproofing where membrane replacement costs dominate lifecycle economics.
- Waterproofing:Below-grade and plaza deck applications demand puncture-resistant membranes with validated seam integrity. Liquid-applied silicone displaces sheet alternatives in German renovation markets where substrate access is constrained.
- Roofing:Exposed membrane assemblies specify EPDM or TPO based on reflectivity ratings and wind-uplift requirements. US Gulf Coast and Atlantic seaboard markets accelerate procurement of polyester-fleece-backed EPDM for high-wind zones.
- Flooring:Elastomeric underlayment and athletic surface applications specify recycled rubber granules.
- Lining:Industrial containment and pond applications prioritize chemical resistance over weathering performance.
Roofing commands the largest revenue pool while waterproofing expands most quickly through renovation-driven silicone adoption.
End User:
Customer procurement sophistication spans from centralized portfolio-scale purchasing in commercial property management to fragmented project-level specification in industrial maintenance.
- Construction:Commercial building envelopes concentrate demand for EPDM and liquid silicone membranes. US property management firms unbundle material procurement from installation services, compressing distributor margins.
- Automotive:Sealing and NVH applications specify precision-extruded EPDM profiles.
- Aerospace:Fuel tank and pressure seal applications demand fluorosilicone and specialty butyl compounds.
- Industrial:Tank lining and chemical containment prioritize neoprene and chlorosulfonated polyethylene alternatives.
Construction absorbs the majority of membrane volume while industrial end uses deliver the highest specification premiums.
Form:
Installation methodology determines labor cost structure and warranty risk allocation between membrane manufacturers and applicators.
- Sheets:Factory-calendered EPDM membranes between 0.8 mm and 2.0 mm thickness enable rapid coverage of large roof areas. Mechanically attached and fully adhered systems dominate German and French commercial construction procurement.
- Liquid:Cold-applied silicone eliminates seam vulnerability in complex geometries. California Air Resources Board restrictions on high-GWP blowing agents create first-mover advantage for CARB-compliant liquid membrane suppliers.
- Rolls:Continuous sheet formats reduce field seaming for large-scale roofing contractors.
- Granules:Recycled rubber particles serve athletic surfaces and acoustic underlayment.
Sheet and roll formats retain the volume base while liquid applications climb the fastest through renovation market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane manufacturing concentrates in polymer-producing regions with established construction chemical infrastructure. German industrial clusters dominate European specification-grade supply. North American production serves domestic roofing channels through captive polymer integration.
Germany
Federal funding for building envelope retrofits channels procurement toward high-performance EPDM systems with thermal bridging validation. The EU F-Gas Regulation accelerates investment in next-generation foam technologies for compliant membrane assemblies. Industrial concentration in North Rhine-Westphalia hosts formulation facilities serving French and Benelux export markets.
United States
Commercial property management firms unbundle material procurement from installation services, compressing traditional distributor margins. EPA construction-VOC rules restrict solvent-based bonding systems, forcing water-based adhesive reformulation. Gulf Coast and Atlantic seaboard markets specify polyester-fleece-backed EPDM for wind-uplift-rated assemblies.
France
Specification-grade demand concentrates in commercial construction with direct contractor relationships unlocking margin capture. REACH authorization requirements for diisocyanate-containing adhesives constrain bonding system availability. Roofing contractors in the Île-de-France region scramble to certify replacement chemistries before regulatory sunset dates.
China
Industrial membrane demand for chemical containment applications prioritizes neoprene and chlorosulfonated polyethylene alternatives. NMPA and GB standards govern construction material specifications with increasing alignment to international testing protocols. Yangtze River Delta manufacturing clusters supply both domestic waterproofing projects and export-oriented liquid silicone formulations.
India
Infrastructure investment in commercial building envelopes drives EPDM specification for ultraviolet resistance in tropical climates. BIS certification requirements for construction materials create compliance barriers for imported membrane systems. Maharashtra and Gujarat industrial corridors host emerging domestic calendering capacity for sheet membrane production.
Rubber Membrane Market Vendor Landscape
Concentration sits with diversified construction chemical conglomerates and specialized roofing system suppliers. The vendor base spans three tiers: integrated polymer producers with captive membrane operations, specification-grade system houses with technical service networks, and regional fabricators competing on installed cost. Strategic moves center on backward integration into polymer supply and extension of warranty coverage beyond membrane-only to full assembly performance.
Within the diversified chemical conglomerate tier, Dow and BASF exemplify integrated polymer-to-membrane positioning. Among specialized roofing system suppliers, Carlisle Companies and Sika AG occupy positions anchored by direct contractor relationships and technical service depth. Firestone Building Products Company represents the warranty-differentiation archetype with installed-system coverage extending beyond membrane-only protection.
| Leading Market Players |
|---|
| SealEco |
| Soprema Group |
| Carlisle Companies |
| Sika AG |
| Dow |
| BASF |
| GAF Materials Corporation |
| Firestone Building Products Company |
| Johns Manville |
| Others |
Supply Flow & Price Mechanics
Calendering capacity utilization above 85 percent in German and US manufacturing clusters concentrates pricing power among integrated polymer producers while establishing cost floors that regional fabricators cannot match without captive ethylene sourcing. Scale advantages in membrane production translate directly into specification-grade pricing authority, particularly where EU F-Gas compliance requires reformulated foam backing investments that smaller competitors cannot amortize.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European membrane markets, separating CARB-compliant and REACH-authorized assemblies from legacy formulations facing regulatory sunset. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal performance validation, with specification engineers in German commercial construction least sensitive to price and cost-conscious US property management firms most responsive to unbundled material sourcing. Cost compression in commodity EPDM grades is intensifying because thermoplastic polyolefin substitution erodes volume leverage for non-integrated manufacturers.
Supply Chain Analysis
Germany and the United States anchor membrane calendering and liquid silicone formulation, with Yangtze River Delta clusters supplying export-oriented waterproofing materials. EPDM polymer production draws from ethylene and propylene feedstocks, while silicone resins rest on methyl chloride and silicon metal supply. Single-source vulnerability concentrates in specialty diisocyanate adhesives facing REACH authorization restrictions. Distribution runs through specification-grade technical service networks in European markets and unbundled direct procurement channels in US commercial property management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified liquid-applied silicone applicators remain scarce relative to renovation-driven demand growth, creating a bottleneck that constrains market expansion and rewards early capability investment. This skill gap separates specification-grade system houses from commodity membrane suppliers.
For Market Incumbents: Consolidate specification authority through captive installer certification programs that lock in contractor loyalty before regulatory compliance requirements escalate. Acquire distressed regional fabricators in North Rhine-Westphalia to secure EPDM calendering capacity adjacent to German retrofit funding pipelines. Prioritize backward integration into polymer supply to defend margin stability against naphtha-cracking volatility.
For New Entrants and Emerging Players: Differentiate on CARB-compliant liquid membrane formulations targeting California commercial roofing contractors ahead of state-level blowing agent restrictions. Target waterproofing renovation segments where substrate access constraints favor cold-applied silicone over sheet alternatives. Pursue direct contractor relationships that bypass traditional distribution markups and capture specification-grade pricing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specification-grade system houses with technical service networks over commodity membrane fabricators. Five-to-ten year viability hinges on regulatory compliance capabilities rather than scale alone. Watch diisocyanate adhesive authorization timelines as inflection indicators for European market restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive ethylene sourcing insulates Carlisle Companies and Dow from naphtha margin compression. |
| Installer Certification Programs | Sika AG's technical service depth locks in German roofing contractors before REACH adhesive sunsets. |
| CARB-Compliant Product Line Launch | First-mover liquid silicone suppliers capture California specification share ahead of state restrictions. |
| Installed-System Warranty Extension | Firestone Building Products differentiates beyond membrane-only coverage in risk-averse property markets. |
| Direct Contractor Relationship Building | Bypassing distribution compresses margins but unlocks specification authority in European channels. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with membrane plant managers, roofing contractor procurement leads, EPDM technical R&D directors, and specification engineers at commercial property firms; and secondary validation through customs and trade data, SEC 10-K filings, Cefic construction chemical reports, and EPA construction-VOC regulatory filings. Bottom-up and top-down triangulation cross-checked volume estimates against polymer production disclosures and regional building permit data.
Across the analysis window, the forecasting framework modeled rubber membrane demand by polymer chemistry, application format, installation methodology, end-use industry, and regional regulatory cluster. CAGRs were derived from segment-level growth rate synthesis calibrated to ethylene feedstock cost trajectories and building envelope retrofit funding cycles. Industry-specific inputs included EU F-Gas phasedown timelines and California Air Resources Board measure adoption curves.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and continued German federal retrofit funding; material deviation in naphtha cracking margins or construction stimulus withdrawal would warrant model refresh. Recalibration cycles align with material shifts in blowing agent regulation timelines and certified installer workforce development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Elastomeric Polyolefins Market