
 Middle-East and Africa Thermoplastic Elastomer (TPE) Market | 2026-2036
Middle-East and Africa Thermoplastic Elastomer (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Thermoplastic Elastomer (TPE) Market Foresight
Advanced recycling-compatible TPE formulations is reconfiguring material selection protocols across the region's automotive supply base. SABIC leverages its integrated feedstock position in Jubail to control cost structures for styrenic block copolymer grades. ExxonMobil Corporation anchors its regional presence through specialized thermoplastic polyolefin supply to Tier-1 interior suppliers. Kraton Corporation differentiates via hydrogenated styrenic technology leadership serving medical device compounders in South Africa.
Thermoplastic elastomers combine rubber-like elasticity with thermoplastic processability, typically comprising hard and soft polymer segments phase-separated at the microscale to deliver Shore A hardness values from 30 to 95 without vulcanization. These materials primarily serve industries requiring flexible, recyclable alternatives to conventional cross-linked rubber in sealing, cushioning, and grip applications. Styrenic Block Copolymers occupy the dominant volume position due to established compounding infrastructure and cost efficiency in automotive interior soft-touch surfaces. Thermoplastic Polyurethanes command premium positioning in medical device tubing where biocompatibility and sterilization resistance justify higher formulation costs. Thermoplastic Polyolefins demonstrate the fastest application expansion in consumer goods packaging closures across Nigerian and Kenyan manufacturing hubs.
Saudi Arabia's Standards, Metrology and Quality Organization (SASO) and South Africa's National Regulator for Compulsory Specifications (NRCS) enforce divergent product safety protocols that fragment compliance costs for pan-regional suppliers. REACH-equivalent substance restrictions emerging in Gulf Cooperation Council customs unions are accelerating reformulation investments among petrochemical producers. Stakeholders must monitor how Egypt's industrial chemical registration framework evolves relative to its African Continental Free Trade Area commitments.
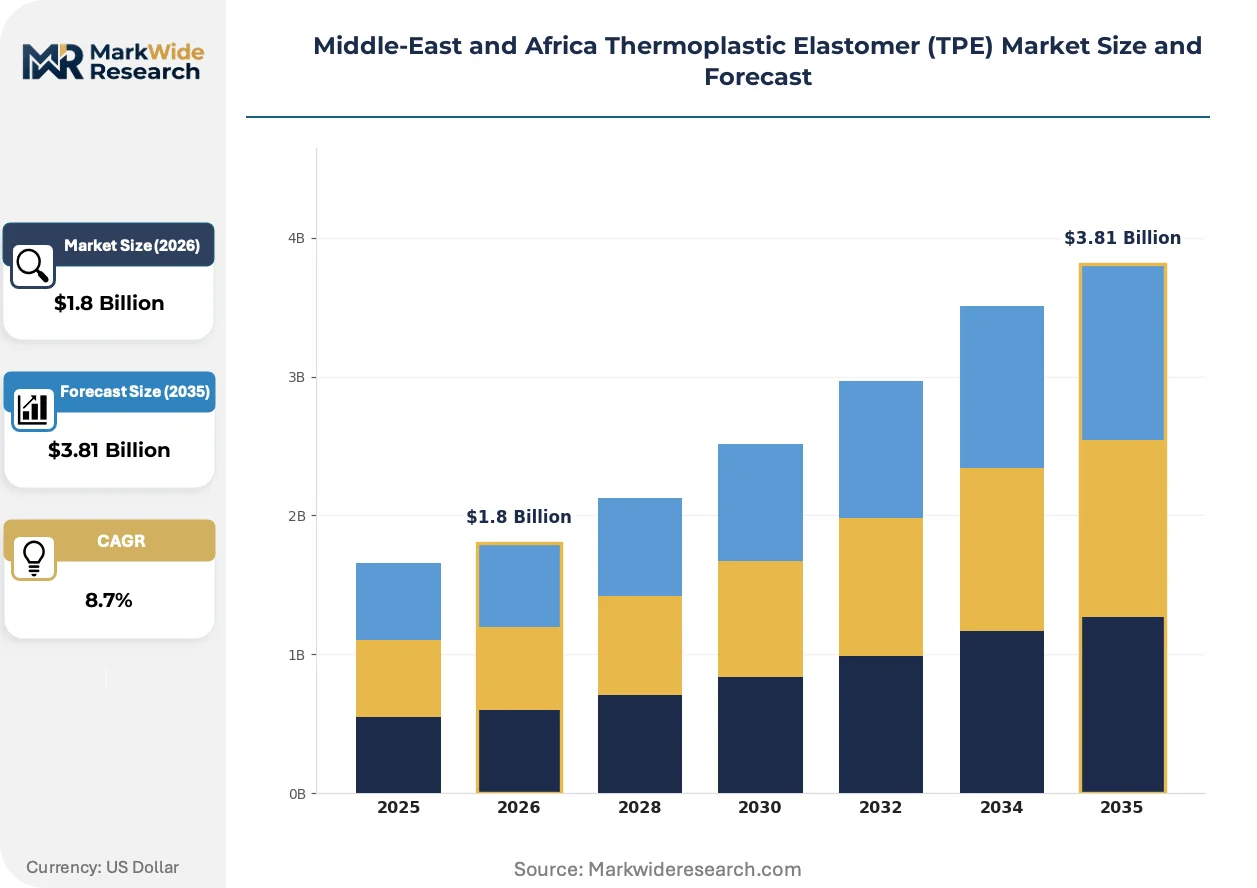
Market Dynamics
The Middle-East and Africa TPE market is being fundamentally restructured by the EU Green Deal's extraterritorial pressure on Gulf petrochemical exporters, forcing reformulation investments across the Jubail-Yanbu corridor before products reach European automotive supply chains.
Growth Catalysts
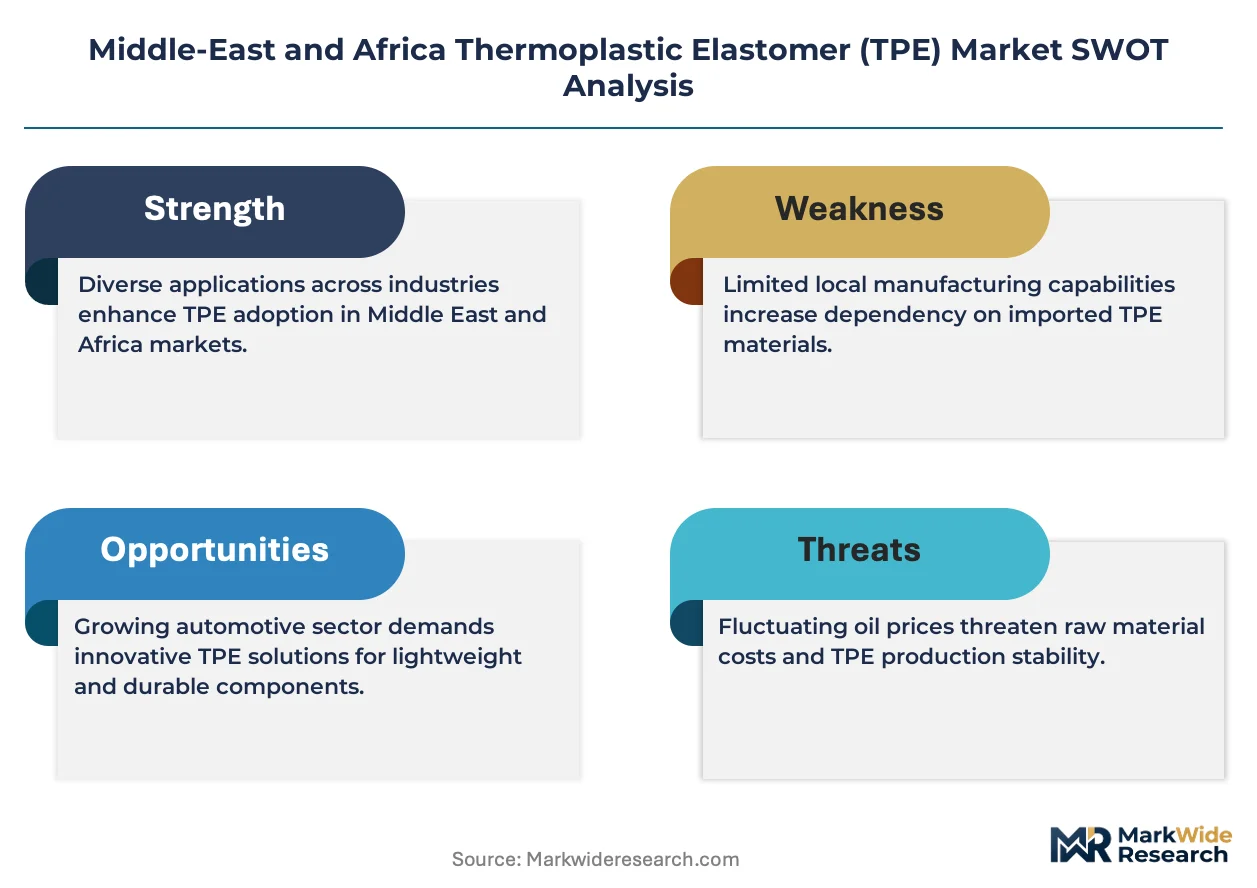
- Automotive lightweighting mandates:Saudi Arabia and UAE manufacturers are substituting TPE for heavier rubber and PVC in interior soft-touch components to meet fleet efficiency targets.
- REACH-equivalent substance restrictions:Emerging Gulf Cooperation Council customs union regulations are accelerating migration toward phthalate-free and recycled-content formulations.
- Medical device tubing demand:South African healthcare infrastructure expansion is pulling hydrogenated styrenic block copolymers for biocompatible fluid handling systems.
Market Restraints
- Crude oil derivative volatility:Styrene and butadiene feedstock costs swing with naphtha cracking economics, compressing margin predictability for regional compounders.
- Supply concentration in Jubail:Over 60% of regional SBC capacity sits within a 50-kilometer radius, creating single-point vulnerability to Saudi industrial action or feedstock disruption.
- Fragmented compliance architecture:SASO technical regulations diverge from NRCS specifications, forcing dual certification runs for pan-regional suppliers.
Strategic Opportunities
- Egyptian industrial chemical registration:Cairo's evolving framework under AfCFTA commitments may create a harmonized entry point for North African market access.
- Consumer goods packaging in Nigeria:Thermoplastic polyolefins are penetrating closure and seal applications in Lagos manufacturing hubs as local bottling capacity expands.
- Advanced recycling compatibility:Mechanical recycling infrastructure investments in Kenya are creating pull for TPE grades that tolerate multi-pass reprocessing without property degradation.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing Shore A hardness with UV stabilization for desert climates command premium wages across the GCC.
- Biocompatibility certification timelines:Medical device compounders face 18-24 month validation cycles with South Africa's health products regulator.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Thermoplastic Elastomer (TPE) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Thermoplastic Polyolefins, Thermoplastic Polyurethanes, Others Application: Automotive Interiors, Medical Devices, Consumer Goods, Industrial Applications End User: Automotive Manufacturers, Healthcare Providers, Electronics Companies, Furniture Manufacturers Form: Granules, Sheets, Films, Blends |
| Companies Covered | SABIC, ExxonMobil Corporation, BASF, LG Chem, Kraton Corporation, Sadara Chemical Company, PetroRabigh, Al-Jubail Petrochemical Company (KEMYA), Covestro AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Thermoplastic Elastomer (TPE) Market Shifts & Advancements
Material science advances and regulatory extraterritoriality are converging to redefine formulation priorities across Middle Eastern petrochemical operations and African conversion industries.
Hydrogenated styrenic block copolymer technology is migrating from conventional automotive interior applications toward medical device and personal care packaging segments. South African compounders serving pharmaceutical tubing manufacturers are adopting saturated mid-block architectures to achieve gamma sterilization resistance. This technology is migrating from commodity automotive grades into premium medical formulations at 15-20% formulation cost premiums that buyers absorb for compliance certainty.
EU Green Deal carbon border adjustment mechanisms are forcing Gulf producers to quantify Scope 3 emissions across TPE value chains. Saudi petrochemical regulators are responding with national low-carbon product certification schemes that mirror EU methodology. Automotive Tier-1 suppliers sourcing from Jubail now require mass-balance certified feedstocks to maintain European OEM qualification status.
Specification-driven procurement is consolidating buyer power among Saudi and UAE automotive assemblers. Tier-1 interior suppliers are being pushed toward single-source TPE formulations with locked Shore A tolerances rather than multi-vendor qualification. This concentration is most visible in Riyadh and Jeddah manufacturing zones where SABIC maintains direct technical service presence at assembler compounds.
Middle-East and Africa Thermoplastic Elastomer (TPE) Market Segmentation
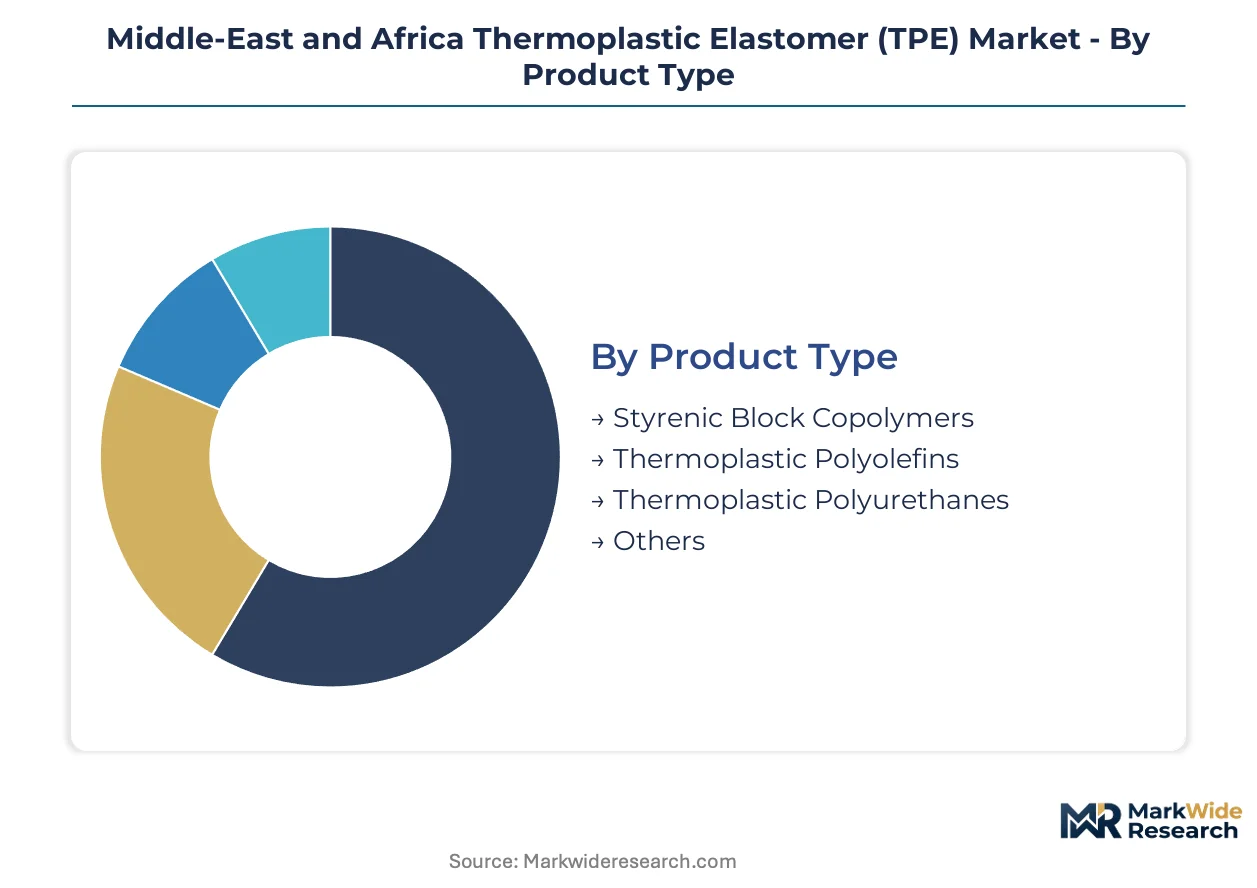
Segmentation reveals how TPE procurement patterns diverge across the Middle-East and Africa. Technical specifications, regulatory compliance requirements, and processing infrastructure shape purchasing decisions differently for each category. Understanding these divides exposes where formulation investments concentrate versus where commoditization pressures dominate.
Product Type:
After-sales technical service intensity varies dramatically across TPE chemistries, with hydrogenated grades demanding sustained formulation support while commodity polyolefins require minimal ongoing intervention.
- Styrenic Block Copolymers:Hard and soft polymer segments phase-separate at the microscale to deliver Shore A hardness from 30 to 95 without vulcanization. SABIC controls regional supply from Jubail, serving Saudi and UAE automotive assemblers with locked Shore A tolerances that Tier-1 interior suppliers now demand.
- Thermoplastic Polyolefins:Demonstrate the fastest application expansion across Nigerian and Kenyan manufacturing hubs where mechanical recycling infrastructure investments create pull for multi-pass reprocessing tolerance. Lagos bottling capacity expansion drives closure and seal adoption.
- Thermoplastic Polyurethanes:Command premium positioning in South African medical device tubing where biocompatibility and sterilization resistance justify formulation cost premiums.
- Others:Include copolyester elastomers and polyamide grades serving niche industrial sealing applications in Egyptian chemical processing zones.
By volume, Styrenic Block Copolymers leads. By growth pace, Thermoplastic Polyolefins is ahead.
Application:
Application segmentation tracks how EU Green Deal extraterritoriality filters through value chains, with European automotive qualification requirements reshaping formulation priorities in non-automotive segments.
- Automotive Interiors:Soft-touch surfaces, sealing systems, and anti-vibration components. Saudi Arabia and UAE manufacturers substitute TPE for heavier rubber and PVC to meet fleet efficiency targets, with mass-balance certified feedstocks now required for European OEM qualification.
- Medical Devices:Pharmaceutical tubing and fluid handling systems. South African compounders face 18-24 month validation cycles with the country's health products regulator, concentrating demand among suppliers with established biocompatibility dossiers.
- Consumer Goods:Packaging closures, grips, and personal care dispensers. Nigerian and Kenyan manufacturing hubs expand local conversion capacity for beverage and cosmetics applications.
- Industrial Applications:Conveyor belts, hoses, and vibration dampening for mining and petrochemical operations. Demand clusters around Jubail and Yanbu industrial cities.
Automotive Interiors commands the largest formulation volumes. Medical Devices generates the steepest margin premiums.
End User:
End user structure reflects procurement consolidation trends, with Saudi and UAE automotive assemblers pushing single-source qualification while healthcare and electronics buyers maintain multi-vendor strategies.
- Automotive Manufacturers:Riyadh and Jeddah assembly compounds drive specification-driven procurement. Direct technical service presence at production sites determines supplier selection more than price.
- Healthcare Providers:South African hospital infrastructure expansion pulls hydrogenated styrenic grades for gamma-sterilizable tubing. Procurement prioritizes regulatory dossier completeness over unit cost.
- Electronics Companies:Cable jacketing and connector sealing applications. Egyptian electronics manufacturing zones under AfCFTA prefer regional compounders with REACH-equivalent documentation.
- Furniture Manufacturers:Castor wheels, armrests, and edge trim. Fragmented demand across North African upholstery workshops limits formulation standardization.
Automotive Manufacturers concentrate purchasing power most intensely. Healthcare Providers impose the longest qualification timelines.
Form:
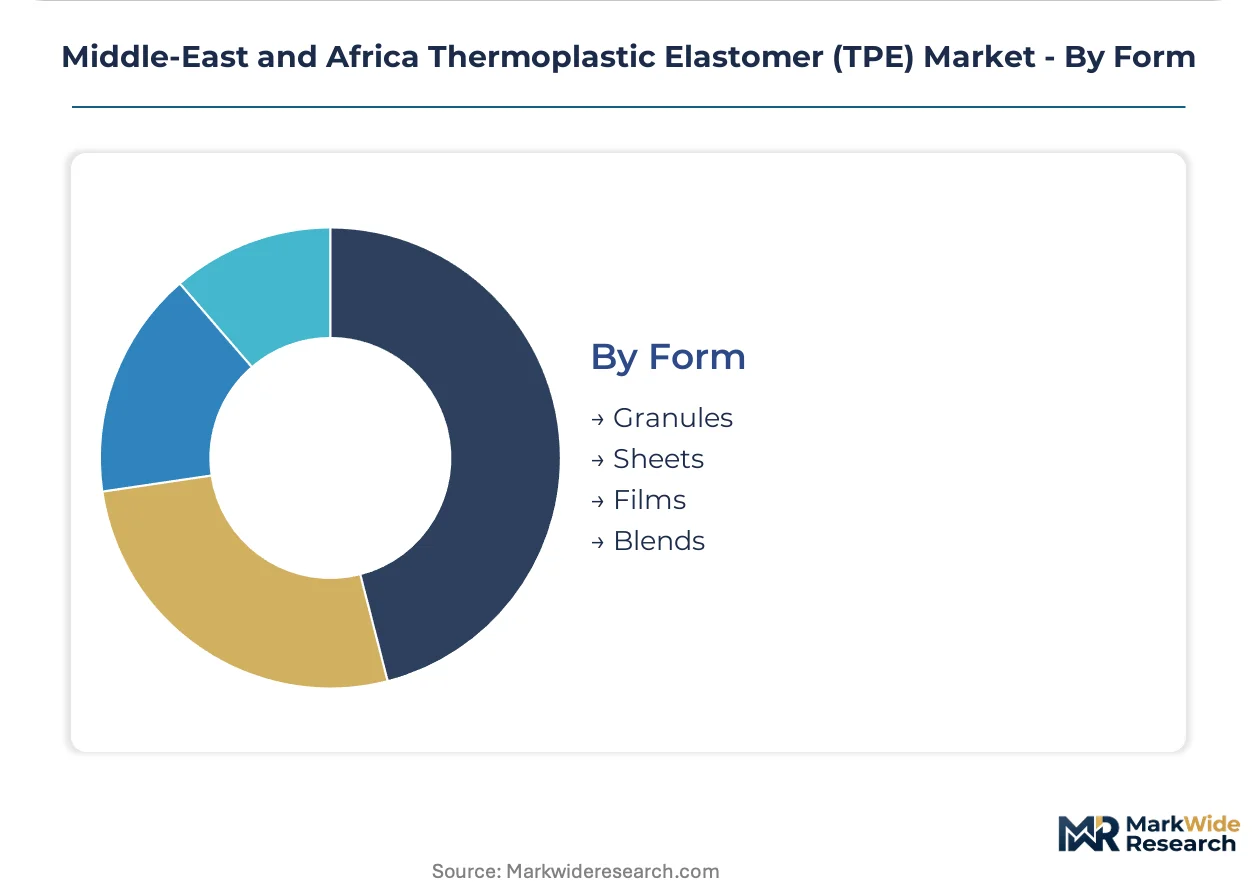
Form segmentation tracks processing infrastructure distribution, with granule supply dominating where compounder networks are dense and film/sheet growth following packaging investment patterns.
- Granules:Standard pellet form for injection molding and extrusion. Jubail petrochemical corridor ships granules across GCC and into East African conversion industries.
- Sheets:Calendered products for thermoforming and die-cutting. South African automotive suppliers source locally for interior trim components.
- Films:Thin-gauge extrusion for lamination and surface protection. Nigerian flexible packaging converters drive demand in Lagos manufacturing zones.
- Blends:Pre-compounded specialty formulations with additives and colorants. Medical device compounders in South Africa specify custom blends to accelerate regulatory submission.
Granules dominates shipment volumes. Films shows the steepest expansion trajectory as packaging investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports TPE formulations through the Jubail-Yanbu corridor to European automotive supply chains, while South African compounders serve domestic medical device manufacturers and Nigerian converters supply West African packaging markets.
Saudi Arabia
SASO enforces REACH-equivalent substance restrictions that accelerate phthalate-free formulation investments. The Jubail industrial city concentrates over sixty percent of regional SBC capacity within a fifty-kilometer radius. SABIC leverages this feedstock integration to control cost structures for styrenic block copolymer grades serving Riyadh and Jeddah automotive assemblers.
United Arab Emirates
MOHAP and the country's national quality regulator drive compliance convergence with EU Green Deal carbon border requirements. Dubai and Abu Dhabi manufacturing zones import granule formulations for injection molding of consumer goods components. Local bottling capacity expansion pulls thermoplastic polyolefins for closure and seal applications.
South Africa
NRCS biocompatibility protocols impose eighteen-to-twenty-four month validation cycles on medical device compounders. The country's national pharmaceutical regulator prioritizes regulatory dossier completeness over unit cost in healthcare procurement. Johannesburg and Cape Town industrial zones concentrate hydrogenated styrenic block copolymer compounding for gamma-sterilizable tubing.
Nigeria
Lagos manufacturing hubs expand local conversion capacity for beverage and cosmetics packaging applications. The country's national standards organization enforces emerging technical regulations on plastic materials. Mechanical recycling infrastructure investments create pull for TPE grades that tolerate multi-pass reprocessing without property degradation.
Egypt
Cairo's evolving industrial chemical registration framework operates under AfCFTA commitments that may harmonize North African market access. The country's national quality regulator enforces divergent product safety protocols from Gulf Cooperation Council customs unions. Alexandria and Suez Canal industrial zones serve as potential entry points for regional TPE distribution.
Middle-East and Africa Thermoplastic Elastomer (TPE) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers. The market structure concentrates around integrated petrochemical producers with captive feedstock positions and independent compounders with technical service capabilities. Three archetypes dominate: integrated petrochemical majors with backward control over styrene and butadiene supply, regional compounders with medical-grade certification expertise, and packaging-focused converters with mechanical recycling partnerships. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure mass-balance certified feedstocks for European OEM qualification.
Among Jubail-anchored petrochemical producers, SABIC and Sadara Chemical Company exemplify the integrated archetype with feedstock control over regional SBC cost structures. Kraton Corporation occupies a position within the specialist tier, representing hydrogenated styrenic technology leadership for medical device applications. These three companies illustrate how competitive positioning separates feedstock-integrated volume players from formulation-specialist margin players across the Middle-East and Africa TPE market.
| Leading Market Players |
|---|
| SABIC |
| ExxonMobil Corporation |
| BASF |
| LG Chem |
| Kraton Corporation |
| Sadara Chemical Company |
| PetroRabigh |
| Al-Jubail Petrochemical Company (KEMYA) |
| Covestro AG |
| Others |
Supply & Pricing Matrix
Overcapacity signals across the Jubail-Yanbu petrochemical corridor are compressing supplier pricing power while simultaneously accelerating consolidation investments among integrated producers. SABIC and Sadara Chemical Company utilize captive feedstock positions to maintain margin buffers that independent compounders cannot replicate.
Pricing Analysis
Current-generation hydrogenated styrenic block copolymers command 15-20% formulation premiums over prior-generation automotive grades, while next-generation recycling-compatible TPEs remain in pilot-scale pricing. Three-tier pricing structure across premium medical-grade, standard automotive-grade, and economy packaging-grade levels dominates procurement. Price differentiation rests on biocompatibility certification tier and volume scale commitments. Cost compression in standard automotive grades is intensifying because Tier-1 suppliers are consolidating to single-source qualification. Consumer goods packaging buyers exhibit highest price sensitivity; medical device compounders show lowest.
Supply Chain Analysis
Contract manufacturing concentration sits with SABIC, Sadara Chemical Company, and PetroRabigh controlling over sixty percent of regional SBC capacity within a fifty-kilometer Jubail radius. Geographic supply concentration centers on Saudi Arabia, South Africa, and Nigeria as primary formulation and conversion nodes. Raw material dependencies draw from naphtha-derived styrene, butadiene from ethylene cracking, and polyolefin feedstocks. Single-source vulnerability represents the dominant structural risk given Jubail corridor concentration. Distribution runs through petrochemical producer-direct technical service teams for automotive accounts and regional distributor networks for packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa TPE market is emerging from a cyclical trough driven by automotive production normalization across Saudi Arabia and the UAE. Feedstock cost volatility and regulatory extraterritoriality are resetting competitive positioning.
For Market Incumbents: Harden feedstock integration advantages through backward control over butadiene supply chains threatened by naphtha cracking economics volatility. Expand hydrogenated styrenic capacity in South Africa to capture medical device tubing demand before Kraton Corporation consolidates regulatory dossier relationships. Prioritize mass-balance certification investments to defend European OEM qualification status against EU Green Deal carbon border exposure. For New Entrants and Emerging Players: Establish a beachhead in Nigerian packaging closure applications where thermoplastic polyolefin demand outpaces local compounding capacity. Target Kenyan mechanical recycling partnerships as entry points for multi-pass reprocessing-tolerant formulations. Leverage AfCFTA harmonization momentum in Egypt to build North African distribution before Cairo's industrial chemical registration framework solidifies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogenated styrenic medical-grade segments due to eighteen-to-twenty-four month biocompatibility validation timelines. Long-term viability favors acquiring regional compounders with established South African health products regulator dossiers over greenfield capacity builds. Monitor Egypt's AfCFTA implementation pace as inflection indicator for North African market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Supply | SABIC's captive feedstock control insulates margin structures from naphtha volatility. |
| Mass-Balance Certification Program | European OEM qualification now requires quantified Scope 3 emissions documentation. |
| Medical-Grade Compounding Scale-Up | Johannesburg hydrogenated SBC capacity addresses South African gamma-sterilization demand. |
| Recycling-Compatible Formulation Launch | Kenyan mechanical infrastructure investments create pull for multi-pass tolerant grades. |
| North African Distribution Partnership | Egyptian AfCFTA positioning offers harmonized entry point before registration framework finalizes. |
Research Methodology
Cross-validation between primary interviews with petrochemical plant managers, automotive Tier-1 procurement leads, medical device compounders, and Kenyan packaging converters anchors the qualitative findings. Secondary validation draws from customs trade data, Gulf Petrochemicals and Chemicals Association reports, SEC 10-K filings, and SASO technical regulation disclosures. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic absorption rates.
Calibration against historical styrenic block copolymer price elasticity and automotive production correlations shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry, Shore A hardness specification band, and regional regulatory cluster. CAGRs derive from feedstock cost trajectory assumptions and substitution elasticity estimates for rubber and PVC displacement.
Stress conditions across naphtha cracking margins, EU Green Deal enforcement intensity, and AfCFTA harmonization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding automotive lightweighting mandate adherence and medical device infrastructure expansion timelines. Quarterly review of Jubail corridor capacity utilization and SASO REACH-equivalent implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market