
 Elastic Films Market | 2026-2036
Elastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Elastic Films Market Foresight
Buyer concentration in food and beverage logistics is expanding as major retail chains consolidate procurement across national distribution networks. Berry Global Group leverages integrated blown film extrusion to serve pan-European grocery retailers with standardized pallet wrap specifications. RKW Group anchors its position through dedicated agriculture film lines that supply contract farming operations in France and the Netherlands. Amcor plc competes by extending its pharmaceutical-grade elastic film portfolio to meet serialization and barrier requirements for European drug manufacturers.
Elastic films are polyolefin-based or elastomer-modified substrates engineered to sustain elongation rates of 50-300% while maintaining tensile recovery, produced primarily through cast or blown extrusion with subsequent orientation. Their primary commercial purpose centers on unitization, surface protection, and controlled-atmosphere containment across industrial and consumer supply chains. Polyethylene formulations dominate volume throughput in packaging applications where cost-per-wrap economics govern procurement decisions. Polyurethane films command premium positioning within medical drapes and surgical incise applications where biocompatibility and vapor transmission rates determine specification compliance. The 20-50 microns thickness band captures the bulk of agricultural silage and bale wrap demand, where puncture resistance must balance against material cost per hectare covered.
The European Chemicals Agency enforces REACH substance restrictions that constrain plasticizer and additive selections for food-contact elastic films, directly elevating reformulation costs for compounders serving the sector. Germany's Federal Environment Agency implements packaging ordinance recycling quotas that pressure producers to incorporate post-industrial regrind without compromising cling performance. The EU Green Deal's target thresholds for recycled content in plastic packaging will force stakeholders to validate mechanical recycling streams or accelerate chemical recycling partnerships before compliance deadlines tighten. Buyers and producers must monitor how rapidly scaling chemical recycling capacity alters virgin resin price spreads and certificate-of-origin traceability requirements.
Market Dynamics
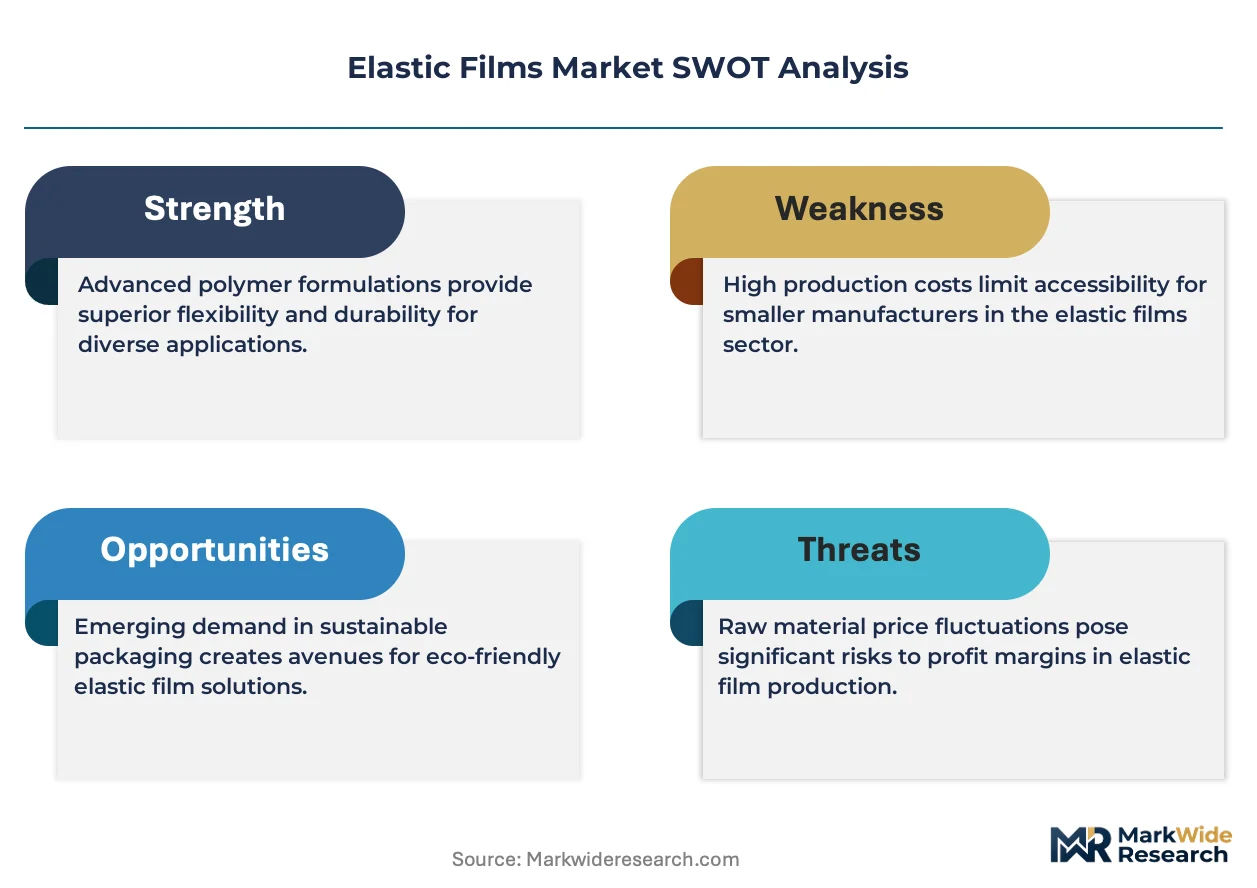
The EU F-Gas Regulation and REACH compliance are forcing compounders to reformulate elastic film additives, compressing margins while creating first-mover advantages for producers with validated recycling streams. This regulatory pressure sits at the center of current market restructuring.
Growth Catalysts
- Modified atmosphere packaging:Food and beverage manufacturers are scaling elastic film usage to extend shelf life and reduce spoilage in centralized distribution networks.
- Chemical recycling partnerships:Producers with validated mechanical or chemical recycling streams gain compliance headroom under EU Green Deal recycled content mandates.
- Central European logistics density:Germany's concentration of extrusion facilities serves pan-European grocery retail chains with standardized pallet wrap procurement.
Market Restraints
- Ethylene feedstock volatility:Polyolefin-based elastic films face margin compression when naphtha and natural gas liquids spike on supply disruptions.
- REACH substance restrictions:ECHA constraints on plasticizers and additives elevate reformulation costs for food-contact film compounders.
- Polyurethane substitution in medical:Biocompatible polyurethane films command premium positioning in surgical drapes, limiting polyethylene penetration in high-margin healthcare.
Strategic Opportunities
- Post-industrial regrind integration:Germany's packaging ordinance recycling quotas create competitive differentiation for producers mastering cling performance with recycled content.
- Pharmaceutical serialization compliance:Barrier-grade elastic films for drug unitization represent underpenetrated volume as serialization mandates expand.
- Agricultural silage optimization:The 20-50 microns thickness band for bale wrap offers white space where puncture resistance improvements justify premium pricing.
Industry Challenges
- Certificate-of-origin traceability:Chemical recycling scaling demands granular documentation systems that most compounders lack.
- Blown film extrusion technician scarcity:Specialized operators for orientation and gauge control command wage premiums that constrain capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastic Films Market |
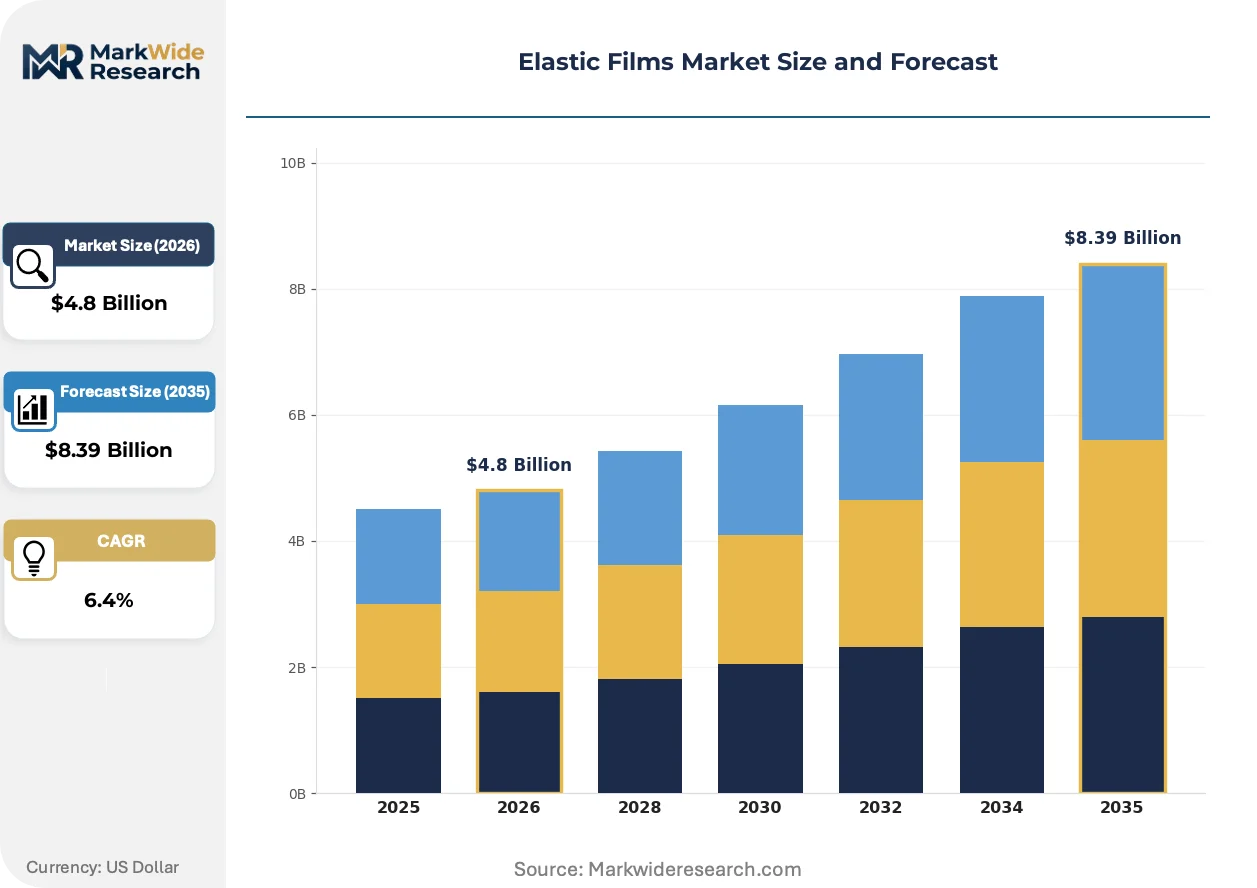
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyurethane, PVDC Application: Packaging, Medical, Agriculture, Automotive End User: Consumer Goods, Pharmaceuticals, Food & Beverage, Electronics Thickness: Below 20 Microns, 20-50 Microns, 50-100 Microns, Above 100 Microns |
| Companies Covered | Berry Global Group, Inc., RKW Group, Coveris Holdings S.A., Fitesa, SWM (Mativ), AEP Industries Inc., Sigma Plastics Group, DUO PLAST AG, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastic Films Market Shifts & Advancements
Active reformulation of elastic film substrates is compressing traditional specification boundaries. Producers now compete on validated circularity credentials rather than virgin resin cost alone.
Multi-layer coextrusion with compatibilized post-consumer regrind is decentralizing supply chain control from petrochemical majors toward integrated compounders with captive recycling partnerships. Agricultural and industrial wrap buyers are piloting these specifications at 15-20% regrind loadings. The technology is decentralizing procurement power toward mid-tier producers with verified mechanical recycling streams.
REACH substance restrictions on phthalate plasticizers and heavy metal catalysts are eliminating legacy additive packages from food-contact specifications. Compounders must validate alternative cling agents and slip additives through EFSA migration testing. Agricultural silage film producers face the steepest reformulation timelines given the sector's historical reliance on cost-optimized additive bundles.
Consolidated retail procurement is compressing supplier rosters as pan-European grocery chains centralize pallet wrap purchasing through single-source framework agreements. Regional distributors lose volume to direct manufacturer relationships. Germany and the Netherlands exhibit the most advanced buyer concentration, with contract farming cooperatives in France following similar consolidation patterns.
Elastic Films Market Segmentation
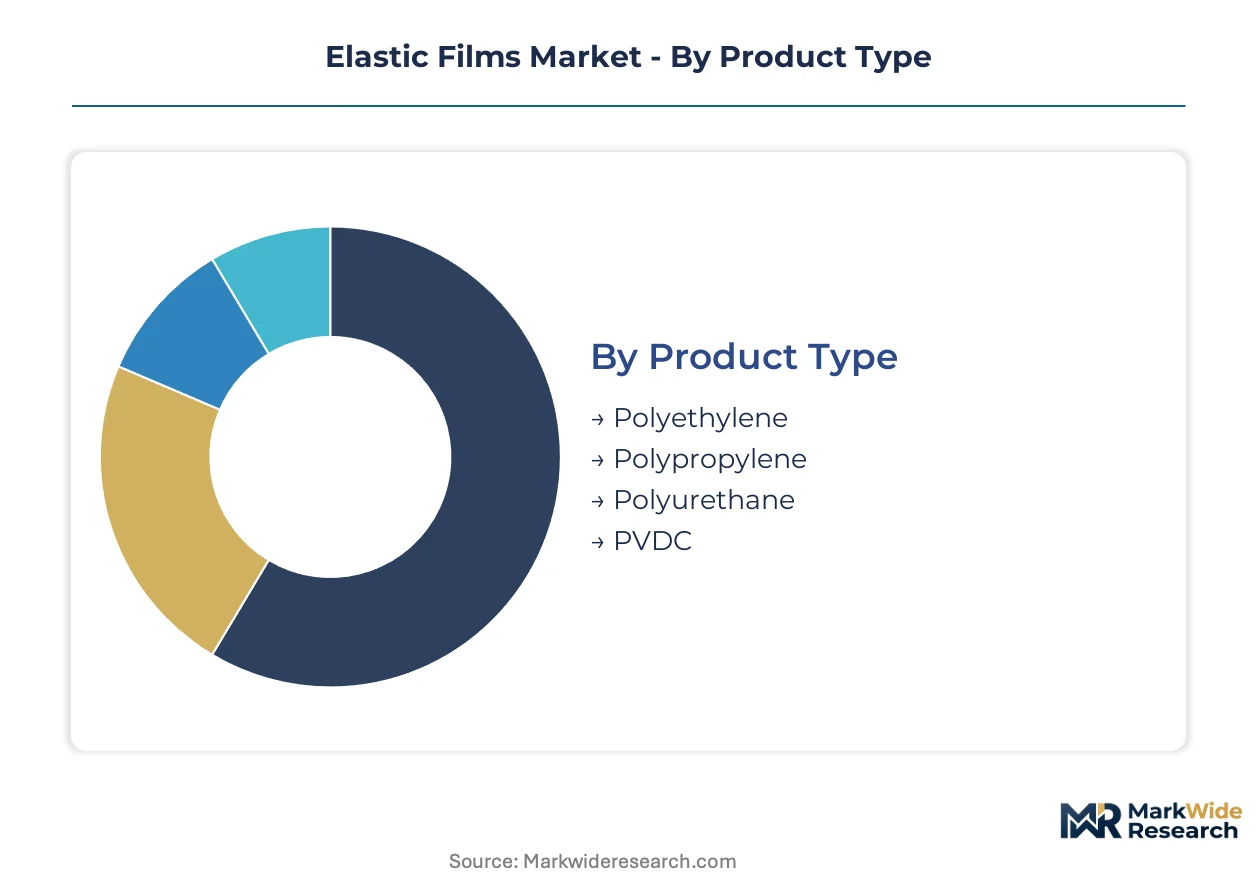
Elastic film procurement patterns diverge sharply across material chemistry, application stress profiles, and regulatory exposure. Buyers select formulations based on elongation recovery requirements, barrier specifications, and compliance burdens rather than commodity resin pricing alone.
Product Type:
Material selection separates buyers by cost tolerance and performance threshold.
- Polyethylene:Blown and cast extrusion of linear low-density and metallocene grades dominates pallet wrap and silage applications. German grocery retailers and French farming cooperatives specify polyethylene for unitization economics where 200-300% stretch ratios must balance against cost-per-meter wrapped.
- Polypropylene:Oriented cast films with higher tensile modulus serve temperature-resistant bundling and retail display overwrap. Demand concentrates in Italian and Spanish consumer goods distribution where clarity and heat-seal response outweigh maximum elongation.
- Polyurethane:Elastomeric films with vapor transmission control command surgical drape and wound dressing specifications. EMA biocompatibility requirements constrain supplier pools to compounders with validated medical device master files.
- PVDC:High-barrier coextrusions with oxygen and moisture resistance target pharmaceutical blister packs and premium food preservation. REACH substance scrutiny on chlorine-containing polymers limits new capacity investment.
Polyethylene leads volumes today; polyurethane is gaining share fastest.
Application:
Stress profiles and regulatory intensity determine formulation investment.
- Packaging:Modified atmosphere and vacuum skin formats drive multi-layer coextrusion with EVOH tie layers. Central European logistics networks specify 15-25 micron hand and machine wrap grades with standardized cling additives.
- Medical:Sterile barrier systems for surgical drapes and incise films require ISO 13485 quality systems and batch-level extractables documentation. German and Swiss device manufacturers source polyurethane and polyethylene blends through qualified supplier audits.
- Agriculture:Silage and bale wrap films face puncture resistance demands against crop stalks and stones. Dutch and Danish dairy cooperatives pilot 30% post-industrial regrind loadings under national packaging ordinance pressures.
- Automotive:Surface protection films during assembly and transport use UV-stabilized polyethylene with clean-removal adhesives. Stuttgart and Wolfsburg production clusters specify low-outgassing formulations for paint shop compatibility.
Packaging commands current revenue concentration; medical applications show the steepest margin expansion trajectory.
End User:
Traceability and migration testing requirements fragment supplier relationships.
- Consumer Goods:Retail display overwrap and bundling films prioritize optical clarity and printability. EFSA migration limits on additives constrain formulation flexibility for food-contact specifications.
- Pharmaceuticals:Serialization mandates and barrier integrity requirements drive qualification of dedicated extrusion lines. German drug manufacturers demand certificate-of-origin documentation for resin lots.
- Food & Beverage:Modified atmosphere packaging for meat, cheese, and produce represents the largest volume outlet. Centralized retail procurement in Germany and the Netherlands compresses supplier rosters toward integrated compounders.
- Electronics:Anti-static and cleanroom-compatible films protect semiconductors and displays during assembly. Swiss and German precision manufacturing clusters specify ionic contamination thresholds below 10 ppm.
Food & beverage anchors procurement volumes; pharmaceuticals is climbing the fastest.
Thickness:
Gauge selection reflects puncture resistance demands against material cost optimization.
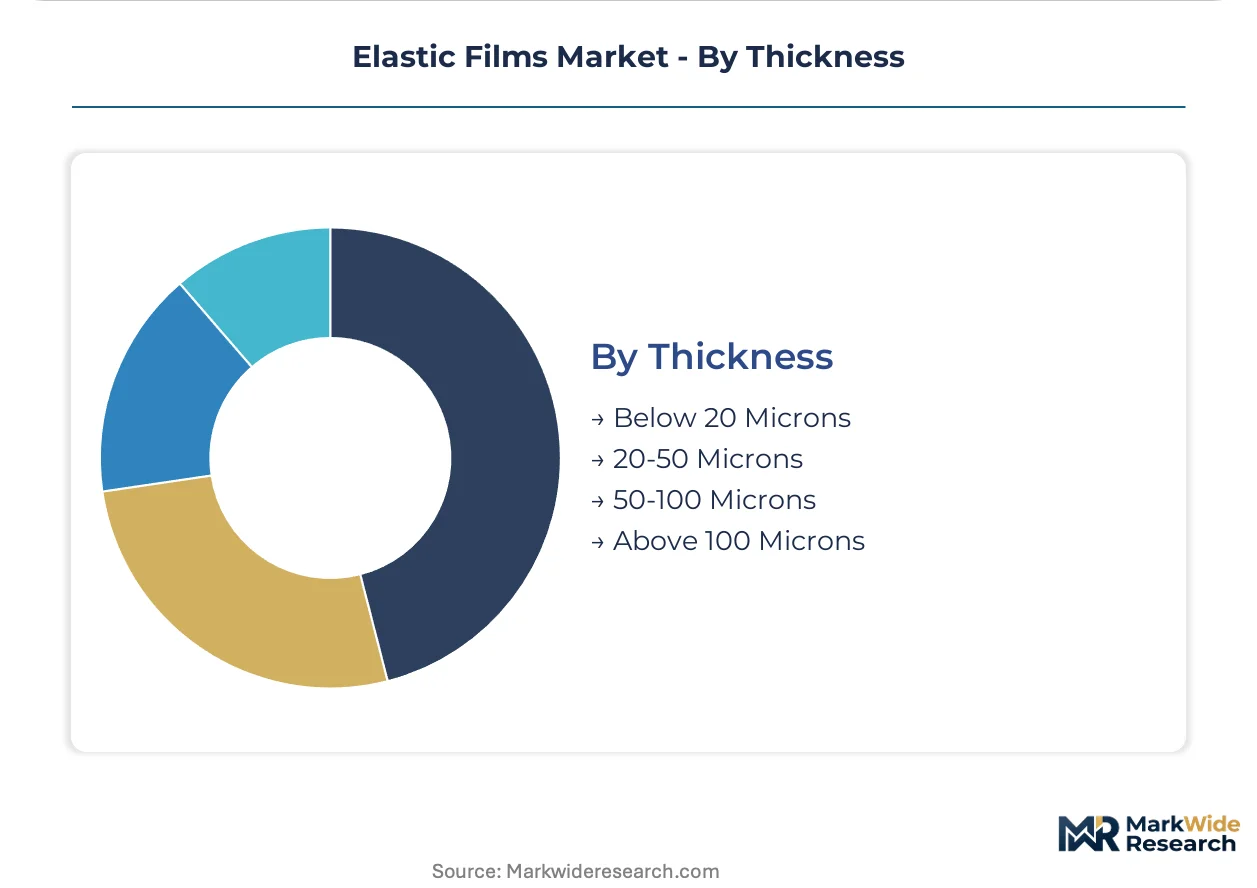
- Below 20 Microns:Hand-wrap and light bundling applications where labor cost exceeds material cost. German discount retailers specify 12-17 micron machine films for high-velocity palletization.
- 20-50 Microns:Agricultural silage wrap and industrial machine stretch films balance puncture resistance with hectare coverage economics. French and Dutch contract farming operations dominate demand.
- 50-100 Microns:Heavy-duty unitization and construction membrane applications. REACH-compliant additive packages for UV stabilization elevate compounder qualification burdens.
- Above 100 Microns:Specialized dunnage and protective masking for automotive and aerospace components. Low-volume, high-margin specifications with dedicated extrusion campaigns.
The 20-50 micron band leads agricultural and industrial volumes; below 20 micron specifications are expanding most quickly in retail logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's concentration of blown film extrusion facilities contrasts with the United States' dispersed logistics packaging demand. Both markets face tightening recycled content mandates, though regulatory mechanisms differ sharply.
Germany
Central European grocery retailers consolidate pallet wrap procurement through direct manufacturer relationships. The Federal Environment Agency enforces packaging ordinance recycling quotas that pressure producers to integrate post-industrial regrind. Berry Global Group and RKW Group operate major extrusion facilities serving pan-European distribution networks from North Rhine-Westphalia and Hesse.
France
Contract farming cooperatives drive agricultural silage film demand with puncture resistance specifications for dairy operations. ANSM migration limits constrain food-contact additive selections for stretch films serving retail meat packaging. The Auvergne-Rhône-Alpes cluster hosts compounders reformulating cling agents to meet EFSA compliance deadlines.
Netherlands
Dutch dairy cooperatives pilot 30% post-industrial regrind loadings in bale wrap applications under national circular economy targets. ECHA REACH substance restrictions eliminate legacy phthalate plasticizers from silage film formulations. Rotterdam logistics hubs specify standardized machine wrap grades for high-velocity container handling.
United States
Discount retailers specify 12-17 micron machine films for automated palletization in distribution centers. FDA food-contact substance regulations govern additive migration limits for meat and produce packaging. Midwest manufacturing clusters in Illinois and Ohio concentrate blown film capacity serving domestic logistics networks.
China
E-commerce fulfillment centers scale machine stretch film consumption for parcel unitization. SAMR national standards on plastic packaging recycling establish recycled content benchmarks for logistics films. Yangtze River Delta manufacturing bases supply cast extrusion capacity for export-oriented consumer goods bundling.
Elastic Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct value chain positions. The vendor base separates into tiered groups: integrated petrochemical-backed producers, mid-scale compounders with captive recycling streams, and regional distributors losing volume to direct relationships. Three archetypes dominate: conglomerates leveraging resin access, specialists mastering circularity credentials, and logistics-focused extruders optimizing gauge control. M&A activity concentrates on recycling technology acquisition, while capacity expansion targets chemical recycling integration ahead of compliance deadlines.
Among diversified packaging conglomerates, Berry Global Group and Amcor plc occupy positions spanning multiple substrate categories. RKW Group exemplifies the focused specialist archetype with dedicated agriculture and industrial film lines. These three anchors illustrate how scale advantages diverge: conglomerates deploy resin purchasing power while specialists capture premium positioning through validated recycling partnerships and application-specific formulation expertise.
| Leading Market Players |
|---|
| Berry Global Group, Inc. |
| RKW Group |
| Coveris Holdings S.A. |
| Fitesa |
| SWM (Mativ) |
| AEP Industries Inc. |
| Sigma Plastics Group |
| DUO PLAST AG |
| Amcor plc |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in European elastic film extrusion have consolidated fragmented regional capacity, tightening pricing discipline while embedding post-industrial regrind economics into contract structures. Their ownership model rewards operational efficiency over volume share, compressing margin tolerance for independent compounders serving German grocery retailers under Federal Environment Agency recycling quotas.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for standard polyethylene pallet wrap grades. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant food-contact specifications from industrial bundling grades. Price differentiation rests on certification grade and volume scale, with centralized retail procurement extracting steepest discounts. Cost compression in standard grades is intensifying because ethylene feedstock volatility and REACH reformulation expenses squeeze compounder margins. Discount retailers exhibit highest price sensitivity; pharmaceutical manufacturers show least sensitivity due to serialization compliance requirements.
Supply Chain Analysis
Freight cost differentials between Rotterdam port access and inland European distribution nodes favor compounders with co-located recycling partnerships over virgin resin importers. Supply concentrates in Germany, France, and the Netherlands, with blown film extrusion drawing from naphtha-derived polyethylene, metallocene catalyst systems, and compatibilized post-industrial regrind. Single-source vulnerability around specialized blown film extrusion technicians constrains capacity expansion. Distribution runs through direct manufacturer relationships with pan-European grocery chains, bypassing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elastic films constitute a late-cycle quality story as food and beverage logistics consolidate procurement toward suppliers with validated circularity credentials and EFSA-compliant additive packages. Modified atmosphere packaging specifications now demand barrier-grade coextrusion that commodity compounders cannot meet.
For Market Incumbents: To counter margin compression from REACH reformulation costs and ethylene feedstock volatility, Berry Global Group and RKW Group should deepen backward integration into chemical recycling partnerships while locking multi-year offtake agreements with Central European retail chains. Capacity expansion in North Rhine-Westphalia preserves logistics advantage for German pallet wrap demand. For New Entrants and Emerging Players: EU F-Gas Regulation and REACH compliance in Germany and France opens a window for mid-scale compounders with validated mechanical recycling streams to capture agricultural silage film share from legacy producers burdened by legacy additive reformulation timelines. Target Dutch dairy cooperatives piloting 30% post-industrial regrind loadings with technical sales emphasizing puncture resistance validation. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors losing volume to direct manufacturer relationships, though acquisition upside requires digital transformation of certificate-of-origin traceability systems. Five-to-ten year viability favors compounders with captive recycling partnerships over pure extrusion plays. Watch chemical recycling capacity scaling in Rotterdam as inflection indicator for virgin resin price spread compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Recycling | Secures compliance headroom under EU Green Deal mandates for German producers. |
| Long-term Supply Agreement with Retail Chains | Locks volume commitments from pan-European grocery consolidators in Netherlands and Germany. |
| Green Manufacturing Transition | Validates post-industrial regrind loadings for EFSA-compliant food-contact specifications. |
| Capacity Expansion | Adds blown film extrusion lines in Hesse to serve Central European logistics density. |
| Joint Venture with Recycling Technology Provider | Accelerates chemical recycling validation ahead of tightening packaging ordinance deadlines. |
Research Methodology
Coverage spans Germany, France, Netherlands, United States, and China, with primary inputs from each region combining interviews with blown film extrusion plant managers, procurement leads at pan-European grocery retailers, distribution channel partners, and technical R&D directors at compounders. Secondary validation drew from ECHA substance restriction filings, EU packaging ordinance compliance databases, SEC 10-K disclosures from diversified packaging conglomerates, and customs trade data on polyethylene resin flows. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Granularity-level framing modeled polyethylene, polypropylene, polyurethane, and PVDC chemistries separately by thickness band and application stress profile across the projection horizon. End-use segmentation captured food and beverage, pharmaceutical, agricultural, and automotive demand with distinct regulatory exposure coefficients. CAGRs derived from elasticity-adjusted substitution curves for modified atmosphere packaging penetration and recycled content mandate compliance timelines. Feedstock price scenarios and REACH reformulation cost curves informed margin trajectory assumptions.
Revisions become necessary when chemical recycling capacity scaling accelerates virgin resin price spread compression or when EFSA migration testing timelines delay alternative additive validation. Forecasts reflect assumptions about regulatory enforcement consistency and retail procurement consolidation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Global Beeswax Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
United States Neoprene Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market