
 UV Stabilized Thermoplastic Elastomer Market | 2026-2036
UV Stabilized Thermoplastic Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
UV Stabilized Thermoplastic Elastomer Market Intelligence
Qualification against standards like ASTM D4329 for UV exposure performance is collapsing the time required for material validation in automotive applications. This accelerated testing cycle benefits established suppliers with proven formulations. BASF SE leverages its extensive chemical expertise to meet stringent OEM requirements for colorfastness and durability. Kraton Corporation specializes in high-performance styrenic block copolymers for demanding outdoor uses. Arkema S.A. competes with its portfolio of advanced copolyester elastomers targeting specialty applications.
UV stabilized thermoplastic elastomers are polymer composites that blend the processing ease of thermoplastics with the flexibility of rubber. These materials incorporate additives such as hindered amine light stabilizers (HALS) to resist degradation from ultraviolet radiation. Their primary purpose is to provide color stability and mechanical integrity in components exposed to long-term sunlight. Styrenic block copolymers and thermoplastic polyurethanes lead in value due to their performance balance, while automotive parts represent the largest application segment.
Material selection is governed by chemical regulations like the EU's REACH framework and the US EPA's Toxic Substances Control Act. Additionally, China's GB standards for automotive materials influence formulation choices by setting limits on volatile organic compounds. These rules dictate allowable additives and finished product compliance. Component suppliers must balance long-term weatherability performance with evolving chemical substance restrictions and cost pressures from OEMs.
Market Dynamics
The market's central dynamic is the tension between automotive OEM demands for lightweight, durable materials and the tightening regulatory landscape governing chemical substances. This dual pressure, exemplified by the EU's End-of-Life Vehicles Directive and REACH, forces continuous reformulation and innovation in TPE compounds.
Growth Catalysts
- Automotive Lightweighting Mandates:Regulations promoting vehicle efficiency and recyclability, such as the EU's End-of-Life Vehicles Directive, drive the substitution of heavier materials with UV stabilized TPEs in exterior trim, seals, and under-hood components.
- Accelerated Material Validation:The adoption of standardized accelerated weathering tests like ASTM D4329 shortens the qualification cycle for new materials, enabling faster integration of proven TPE formulations into automotive production lines.
- Expansion in Building and Construction:Demand for durable, weather-resistant materials for window seals, roofing membranes, and exterior profiles in the construction industry provides a significant growth avenue beyond automotive applications.
Market Restraints
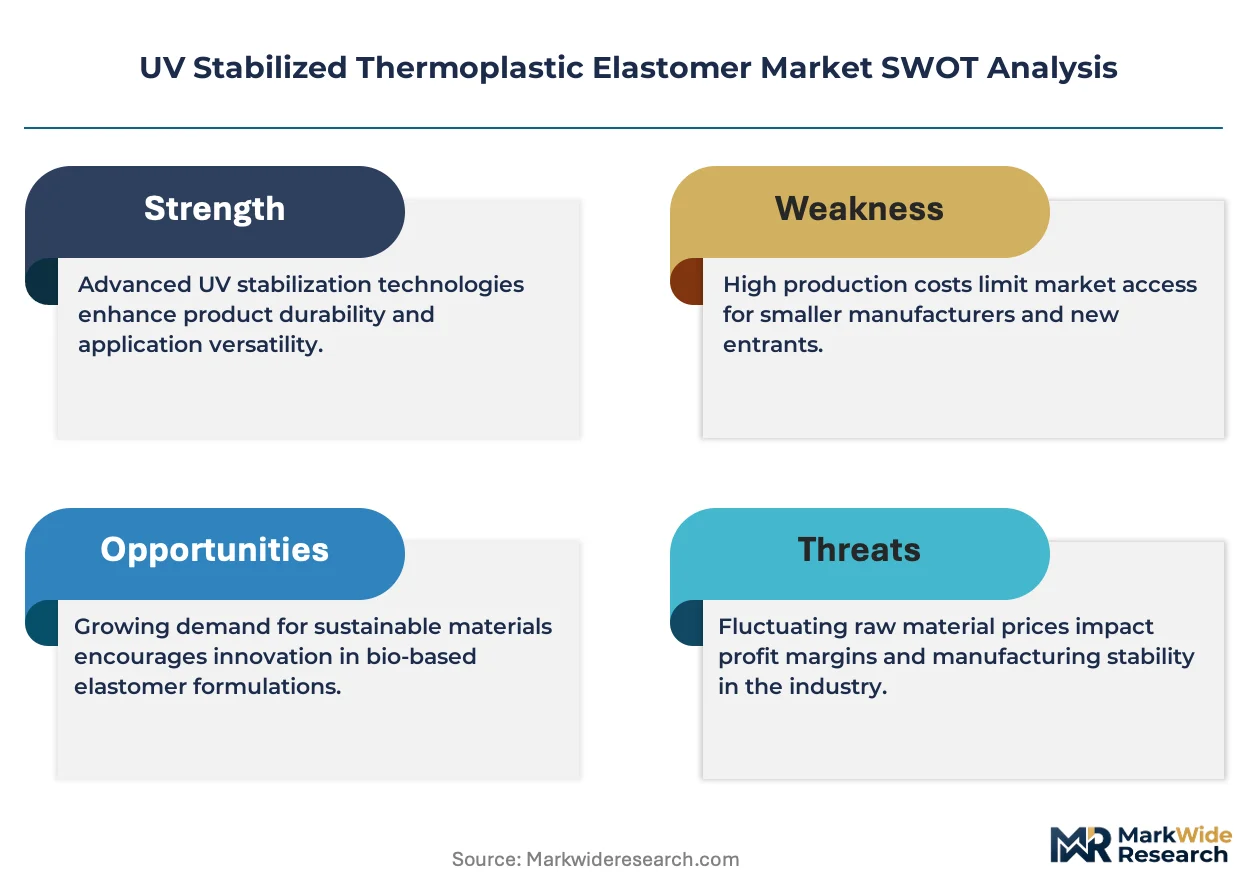
- Petrochemical Feedstock Volatility:The cost of key raw materials, including styrenic block copolymers and polyolefins, is directly tied to volatile petrochemical markets, creating pricing instability and margin pressure for TPE compounders.
- Substitution from Alternative Materials:In certain cost-sensitive applications, UV stabilized TPEs face competition from traditional thermoset rubbers like EPDM and other stabilized thermoplastics that may offer a different cost-performance balance.
- Evolving Chemical Regulations:Constantly changing substance-of-concern lists under frameworks like the EU's REACH and the US EPA's TSCA create compliance burdens and necessitate ongoing investment in reformulation to avoid restricted additives.
Strategic Opportunities
- Bio-Based and Recycled TPEs:Developing UV stabilized thermoplastic elastomers from bio-based feedstocks or with high-recycled content offers a path to meet OEM sustainability targets and appeal to environmentally conscious end-users.
- Penetration in Renewable Energy:The solar energy sector presents an opportunity for specialized TPEs in applications like photovoltaic module frames, junction box seals, and cable insulation that require long-term UV resistance.
- Consumer and Electronics Applications:Untapped demand exists in consumer goods, such as outdoor equipment, wearable electronics, and tool grips, where durability, color stability, and soft-touch feel are valued attributes.
Industry Challenges
- Complex Color Matching and Stability:Achieving precise color matching specified by automotive OEMs and ensuring long-term colorfastness under real-world UV exposure remains a significant technical and operational challenge for compounders.
- End-of-Life Recycling Logistics:Establishing efficient and scalable collection and recycling systems for post-consumer products containing TPEs, particularly from complex assemblies like vehicles, is critical for achieving circular economy goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Stabilized Thermoplastic Elastomer Market |
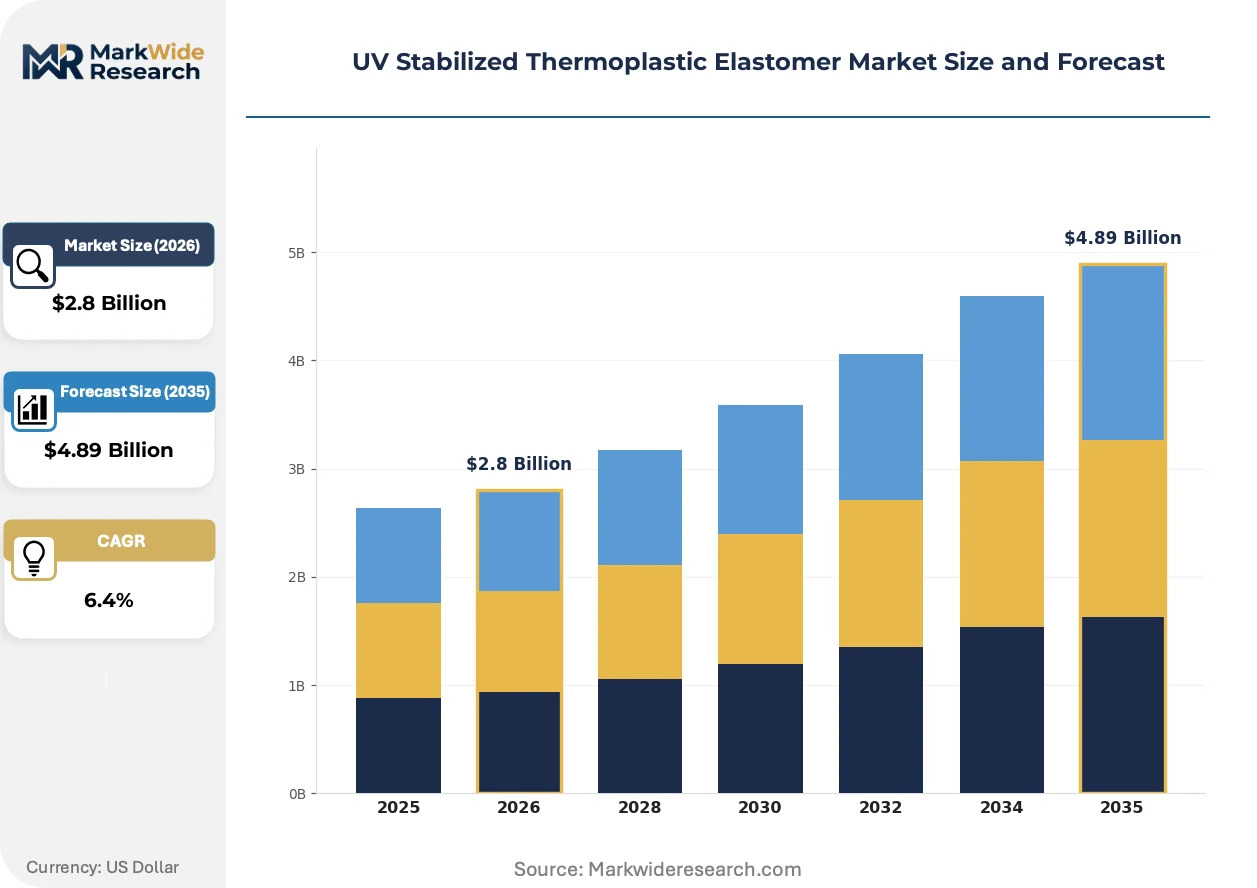
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Thermoplastic Polyurethanes, Thermoplastic Polyolefins, Copolyester Elastomers Application: Automotive Parts, Consumer Goods, Medical Devices, Coatings End User: Manufacturers, Distributors, Retailers, OEMs Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | LG Chem Ltd, Advanced Elastomer Systems L.P., BASF SE, Mitsui Chemicals Inc, Dynasol Elastomers LLC, Arkema S.A., Kraton Corporation, Celanese Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Stabilized Thermoplastic Elastomer Market Strategic Shifts & Innovations
Material science advancements are focused on enhancing long-term performance while navigating a complex web of global environmental and safety regulations. This drives innovation toward specialty polymers and low-impact formulations that meet stringent criteria for both durability and compliance across multiple industries.
High-performance copolyester elastomers (TPE-E) and thermoplastic vulcanizates (TPVs) provide superior chemical and heat resistance. Automotive and industrial equipment manufacturers are adopting these materials for components exposed to harsh under-hood or outdoor environments. This evolution toward specialty polymers is displacing conventional thermoset rubbers and standard TPEs in applications where performance cannot be compromised.
China's GB standards for automotive materials impose strict limits on volatile organic compounds (VOCs) and other hazardous substances in vehicle interiors. This regulatory pressure forces compounders to develop new low-emission TPE formulations for parts like instrument panel skins, door trim, and floor mats. The interior components segment is therefore a center of innovation for compliant, aesthetically pleasing materials.
A shift in material specification protocols is evident as OEMs increasingly rely on accelerated weathering test data to qualify suppliers. This approach compresses validation timelines from years to months, creating an advantage for compounders with pre-certified formulations that meet standards like ASTM D4329. The trend is most visible in the North American and European automotive supply chains, where reducing time-to-market is paramount.
UV Stabilized Thermoplastic Elastomer Market Segmentation
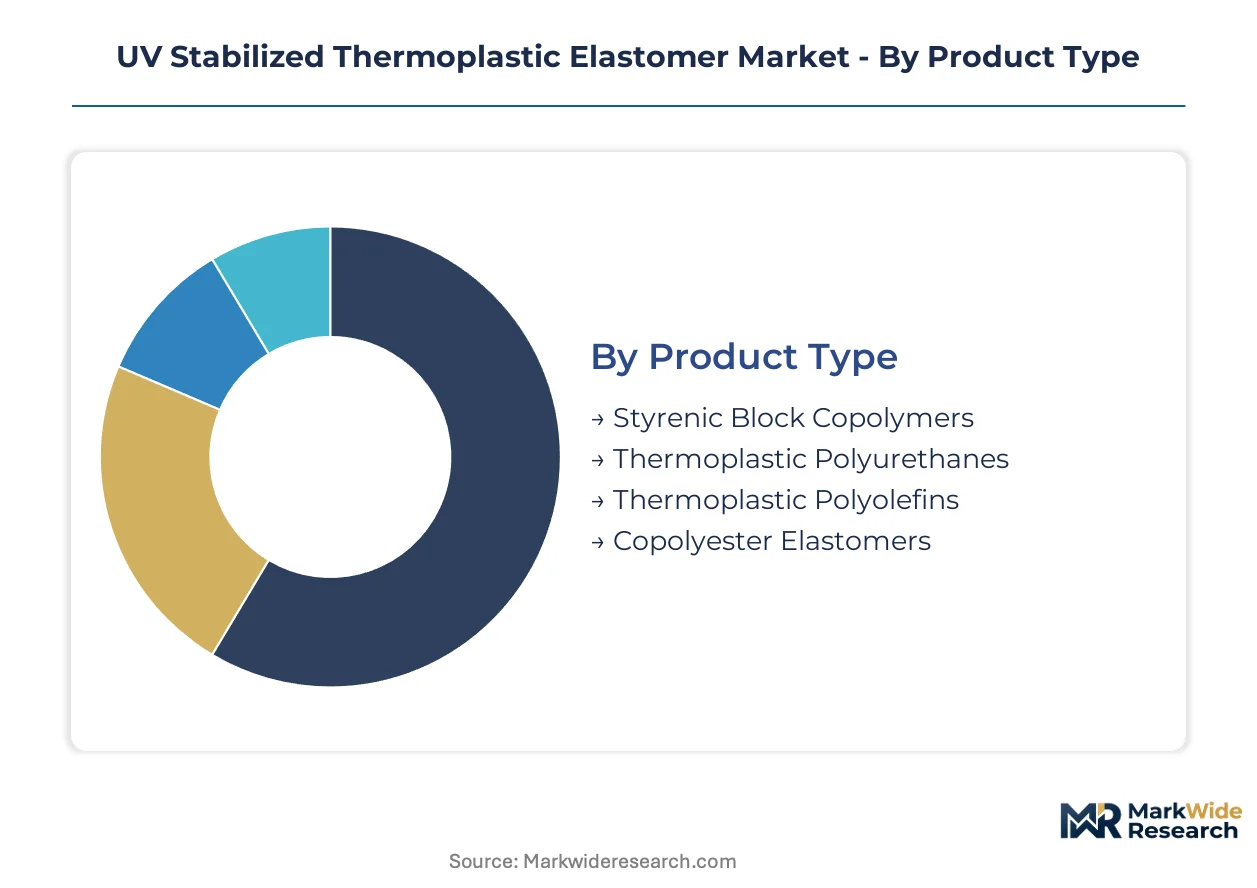
The UV stabilized thermoplastic elastomer market segmentation provides a granular view of material adoption and end-use demand. Understanding these distinct categories helps stakeholders identify specific growth pockets and tailor product development for diverse industry requirements. This detailed breakdown highlights where material innovation and application expansion are most pronounced.
Product Type:
The market for UV stabilized TPEs shows distinct preferences for material types, with certain formulations dominating domestic consumption while others target export-oriented manufacturing hubs.
- Styrenic Block Copolymers:These TPEs, composed of hard polystyrene blocks and soft elastomeric blocks, offer excellent elasticity and processability. Demand concentrates heavily in automotive production centers in Germany and the United States for exterior trim and weather seals, driven by mandates for lightweighting.
- Thermoplastic Polyurethanes:Known for their superior abrasion resistance, chemical resilience, and high tensile strength, TPUs find extensive use in demanding outdoor applications. Growth is significant in China's automotive sector and for specialized industrial components, where durability and performance under harsh UV exposure are critical.
- Thermoplastic Polyolefins:TPOs combine the properties of rubber and plastic, offering good impact strength and chemical resistance for less demanding exterior applications.
- Copolyester Elastomers:TPE-Es provide high-temperature performance and chemical resistance, making them suitable for specialized industrial and under-hood automotive components.
Styrenic Block Copolymers commands the established base. The steepest expansion runs through Thermoplastic Polyurethanes.
Application:
Application segments for UV stabilized TPEs are primarily differentiated by their specific performance requirements and exposure conditions, influencing material selection and additive packages.
- Automotive Parts:This segment includes exterior trim, weather seals, gaskets, and interior components requiring long-term UV stability, colorfastness, and resistance to environmental factors. OEM specifications for durability and aesthetics in vehicles drive material innovation and volume in this sector.
- Consumer Goods:Applications range from outdoor sporting equipment and garden tools to wearable electronics and soft-touch grips, where tactile feel, durability, and UV resistance are essential. Design flexibility and aesthetic appeal are significant factors for material selection in this diverse segment.
- Medical Devices:Specialized UV stabilized TPEs are used in medical tubing, seals, and grips, requiring biocompatibility and resistance to sterilization methods in addition to UV protection.
- Coatings:TPEs are incorporated into protective coatings for enhanced flexibility, weatherability, and impact resistance in architectural and industrial applications.
The Automotive Parts segment generates the largest volume. Consumer Goods are expanding most quickly.
End User:
The end-user landscape for UV stabilized TPEs reflects the varying degrees of material processing and integration required by different industry participants, from raw material conversion to final product assembly.
- Manufacturers:These entities process TPE compounds into intermediate components or finished products for various industries, often requiring specialized molding or extrusion capabilities. Material consistency and technical support from suppliers are paramount for manufacturers.
- OEMs:Original Equipment Manufacturers directly integrate UV stabilized TPEs into their final products, such as vehicles, appliances, or electronic devices. OEMs often dictate stringent performance specifications and material qualifications, influencing compounder R&D.
- Distributors:These companies manage the supply chain, purchasing TPE materials in bulk from producers and reselling them to smaller manufacturers or specialized fabricators. Distributors provide logistical support and regional market access for TPE suppliers.
- Retailers:Retailers primarily sell finished consumer goods containing UV stabilized TPE components, focusing on product aesthetics, functionality, and brand reputation.
Manufacturers represent the largest purchasing group. The fastest growth in demand comes from OEMs.
Distribution Channel:
The distribution channels for UV stabilized TPEs are shaped by the volume requirements, technical support needs, and geographic reach necessary to serve a diverse customer base.
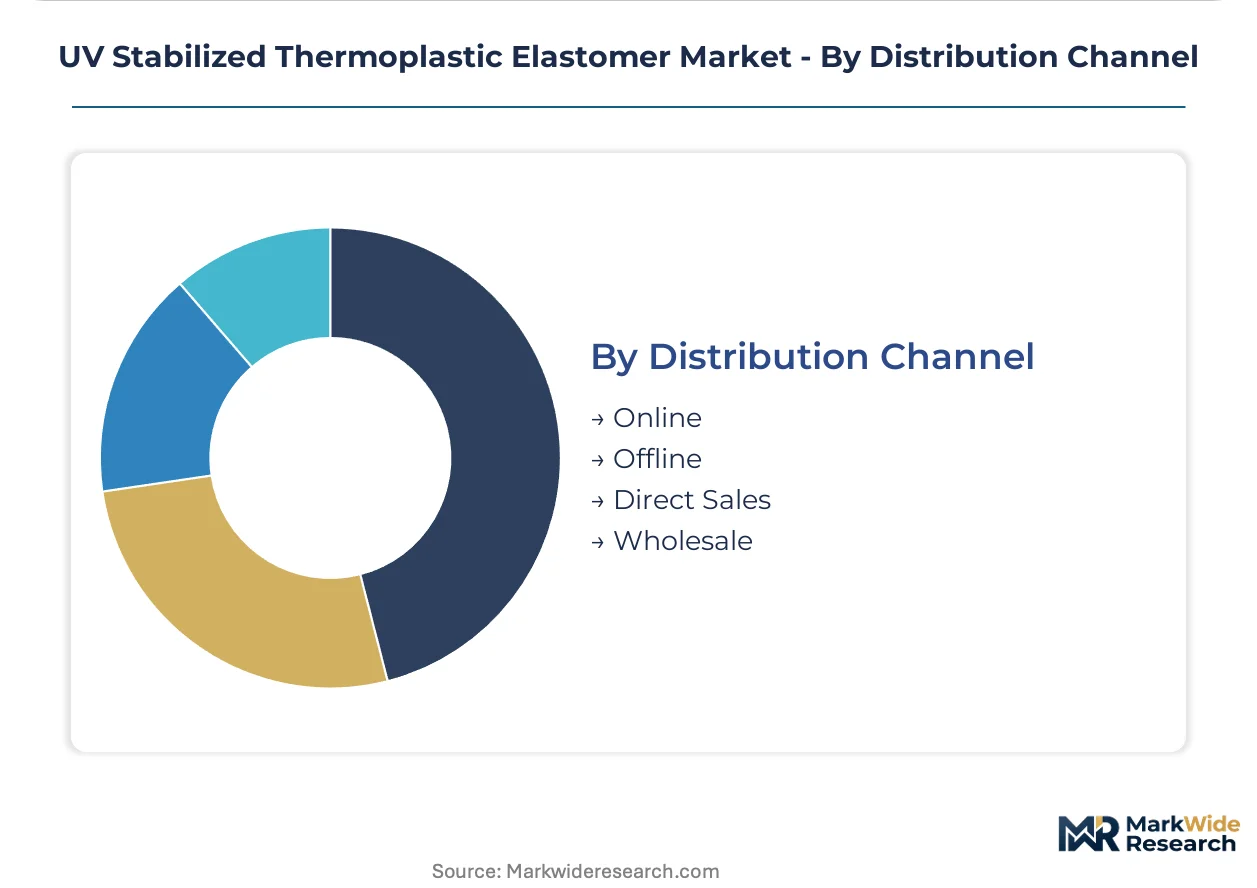
- Offline:This traditional channel involves direct sales, regional warehouses, and physical sales networks, often preferred for large-volume industrial orders and complex technical applications. Established relationships and on-site technical assistance are crucial for offline distribution.
- Direct Sales:Major TPE producers often engage in direct sales to large OEMs and Tier 1 suppliers, facilitating close collaboration on material development and supply chain integration. This channel allows for customized solutions and long-term strategic partnerships.
- Online:E-commerce platforms and digital marketplaces are gaining traction for smaller orders, specialized compounds, and rapid prototyping needs, offering convenience and broader accessibility for a diverse customer base.
- Wholesale:Wholesalers purchase TPE materials in bulk and distribute them to a network of smaller manufacturers and fabricators, providing a cost-effective solution for wider market penetration.
Offline channels maintain the largest volume. Direct Sales are capturing market share most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulations promoting vehicle efficiency and recyclability, such as the EU's End-of-Life Vehicles Directive, drive the substitution of heavier materials with UV stabilized TPEs. This global shift towards lightweighting and durability influences material specification across major automotive production hubs. Demand concentrates in regions with stringent environmental policies and significant manufacturing bases.
China
Demand for UV stabilized TPEs in China stems from its massive automotive production and expanding construction sector. China's GB standards for automotive materials impose strict limits on VOCs, influencing TPE formulation choices. Manufacturing clusters in the Yangtze River Delta are innovating low-emission TPEs for vehicle interiors and exterior components.
Germany
Germany's automotive industry drives significant demand for high-performance UV stabilized TPEs in exterior trim and seals. The EU's REACH framework and End-of-Life Vehicles Directive necessitate advanced, recyclable material solutions. Bavaria and Baden-Württemberg, key automotive manufacturing regions, focus on TPE development for premium vehicle applications.
United States
The United States automotive sector requires UV stabilized TPEs for lightweighting and enhanced durability in components like weather seals. The US EPA's Toxic Substances Control Act (TSCA) influences allowable additives and finished product compliance for TPE compounds. Detroit's automotive hub and surrounding manufacturing states are adopting accelerated material validation for new TPE formulations.
Japan
Japan's electronics and automotive industries are adopting UV stabilized TPEs for their long-term performance and aesthetic appeal. JIS standards for industrial materials guide the selection and qualification of TPEs for outdoor applications. Tokyo and Nagoya-based manufacturers are integrating advanced TPE-E and TPV materials into high-performance industrial equipment.
India
India's rapidly expanding automotive and construction sectors are increasing the need for durable, weather-resistant TPE materials. BIS standards for plastic products ensure quality and performance for TPE applications in infrastructure and consumer goods. Manufacturing centers in Maharashtra and Tamil Nadu are witnessing growth in TPE compounding for local and export markets.
UV Stabilized Thermoplastic Elastomer Market Key Industry Players
Player mix skews toward established chemical conglomerates and specialized elastomer manufacturers, influencing material innovation and supply chain stability. The market exhibits a tiered structure, with global chemical giants commanding significant R&D capabilities and production scale. Mid-sized regional compounders often focus on niche applications or specific geographies, offering tailored solutions. Companies pursue portfolio diversification, geographic expansion, and strategic partnerships to strengthen their market presence and expand material offerings.
Specialists in high-performance styrenic block copolymers, Kraton Corporation exemplifies a focus on demanding outdoor uses, particularly where long-term UV resistance is critical. BASF SE, a German chemical multinational, represents the broad portfolio approach, leveraging extensive chemical expertise to meet stringent OEM requirements for colorfastness and durability. Arkema S.A., a French advanced materials company, occupies a position in specialty copolyester elastomers, targeting specific high-value industrial and automotive applications. These companies anchor innovation in UV stabilization technologies and advanced TPE formulations, driving material advancements across diverse end-use sectors.
| Leading Market Players |
|---|
| LG Chem Ltd |
| Advanced Elastomer Systems L.P. |
| BASF SE |
| Mitsui Chemicals Inc |
| Dynasol Elastomers LLC |
| Arkema S.A. |
| Kraton Corporation |
| Celanese Corporation |
| Evonik Industries AG |
Cost & Logistics Intelligence
Extended OEM qualification lead times for new UV stabilized TPE formulations directly influence pricing power for established suppliers. This supply chain dynamic ensures premium pricing for proven materials that meet stringent automotive standards.
Pricing Analysis
Certification against standards like ASTM D4329 creates the primary spread in UV stabilized TPE pricing. The market operates on a hybrid model, combining contract-based long-term off-take for large automotive OEMs with transactional pricing for smaller specialty applications. Price differentiation stems from material performance balance, such as styrenic block copolymers versus thermoplastic polyolefins, and the level of customization required. Pricing softness reflects volatility in petrochemical feedstock costs, impacting compounder margins, while automotive OEMs are less price-sensitive for critical exterior components.
Supply Chain Analysis
Consistent raw material lead times are crucial for maintaining stable production schedules across the UV stabilized TPE supply chain. Supply concentrates in major automotive production hubs like Germany, the United States, and China. The industry draws from key inputs including styrenic block copolymers, polyolefins, and hindered amine light stabilizers. A structural risk involves commodity price volatility for these petrochemical feedstocks, with distribution running through direct sales channels for large OEMs and offline networks for smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity driven by the demand for specialized, compliant TPE formulations across diverse end-use sectors. Evolving chemical regulations and sustainability targets are creating numerous niche segments.
For Market Incumbents: Secure long-term supply agreements with automotive OEMs to defend against substitution from alternative materials. Incumbents should invest in R&D for bio-based and recycled TPEs, addressing evolving chemical regulations like REACH. Capacity expansion in automotive production centers, such as Germany and China, can reinforce market share. This strategy mitigates the threat of new entrants offering sustainable alternatives.
For New Entrants and Emerging Players: Anchor in niche applications within the renewable energy sector, such as solar module frames and cable insulation. Untapped demand in consumer goods, particularly outdoor equipment and wearable electronics, represents a penetrable segment. Offer specialized TPEs with rapid material validation data, leveraging new testing standards like ASTM D4329. A go-to-market angle could emphasize sustainability through high-recycled content formulations.
For Investors and Strategic Acquirers: Long-term, this sits as a performance materials play because regulatory pressures and OEM demands for lightweighting will continue. Focus on acquiring specialized compounders with proprietary UV stabilization technologies and expertise in bio-based formulations. These mid-sized players often possess unique intellectual property and specific market access. Widespread adoption of bio-based TPEs by major automotive brands signals an inflection point for broader market integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding TPE production in key automotive regions like China supports growing demand for lightweight materials. |
| Green Manufacturing Transition | Developing bio-based TPEs aligns with OEM sustainability targets and evolving chemical regulations like REACH. |
| Long-term Supply Agreement | Securing multi-year contracts with automotive OEMs provides revenue stability and ensures material integration into vehicle platforms. |
| Joint Venture | Partnering to develop advanced UV stabilization technologies enhances material durability and colorfastness under harsh outdoor conditions. |
| Technology Licensing | Licensing specialized copolyester elastomer formulations allows penetration into high-performance industrial and under-hood automotive applications. |
Research Approach
Initial hypotheses were tested against primary input from automotive OEM procurement leads, TPE compounders, and chemical additive suppliers, then refined. This involved combining in-depth interviews with secondary validation from customs data, industry association reports, and company 10-K filings. A bottom-up and top-down triangulation approach ensured data consistency across various market segments.
Variance decomposition was applied to isolate the impact of different market forces across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, distribution channel, and UV exposure performance grade. Compound annual growth rates were derived from historical trends and projected growth drivers. Vehicle production forecasts and construction spending served as key industry-specific forecast inputs.
Material uncertainties — such as geopolitical events, rapid shifts in chemical regulations, or unforeseen technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding raw material price stability and consistent regulatory frameworks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market