
 Asia-Pacific Aluminum Door and Window Market | 2026-2036
Asia-Pacific Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aluminum Door and Window Market Analytics
Thermal break extrusion technology is fragmenting traditional aluminum fabrication across Asia-Pacific. LIXIL Corporation leverages its Japanese R&D base to dominate high-performance frame engineering. YKK AP anchors regional supply through integrated extrusion and finishing networks in Southeast Asia.
Asia-Pacific aluminum doors and windows are fabricated from 6063-T5 or 6061-T6 aluminum alloy extrusions, typically anodized or powder-coated for corrosion resistance, and assembled with polyamide thermal strips to achieve U-values below 2.0 W/m²K for climate-responsive building envelopes. Sliding doors lead residential volume in dense urban markets where space efficiency governs design. Thermal break frames capture expanding margin pools as India's BIS standards and China's GB 50189 energy codes tighten. Commercial buildings application outpaces residential growth in Vietnam and Indonesia where foreign direct investment flows into logistics and hospitality assets.
China's MIIT enforces GB standards for aluminum alloy construction profiles while India's BIS mandates IS 733 chemical composition and mechanical property compliance for structural extrusions. Japan's METI building energy efficiency regulations drive specification upgrades toward low-emissivity glazing integration. Stakeholders must monitor divergence between national certification regimes as cross-border project execution grows.
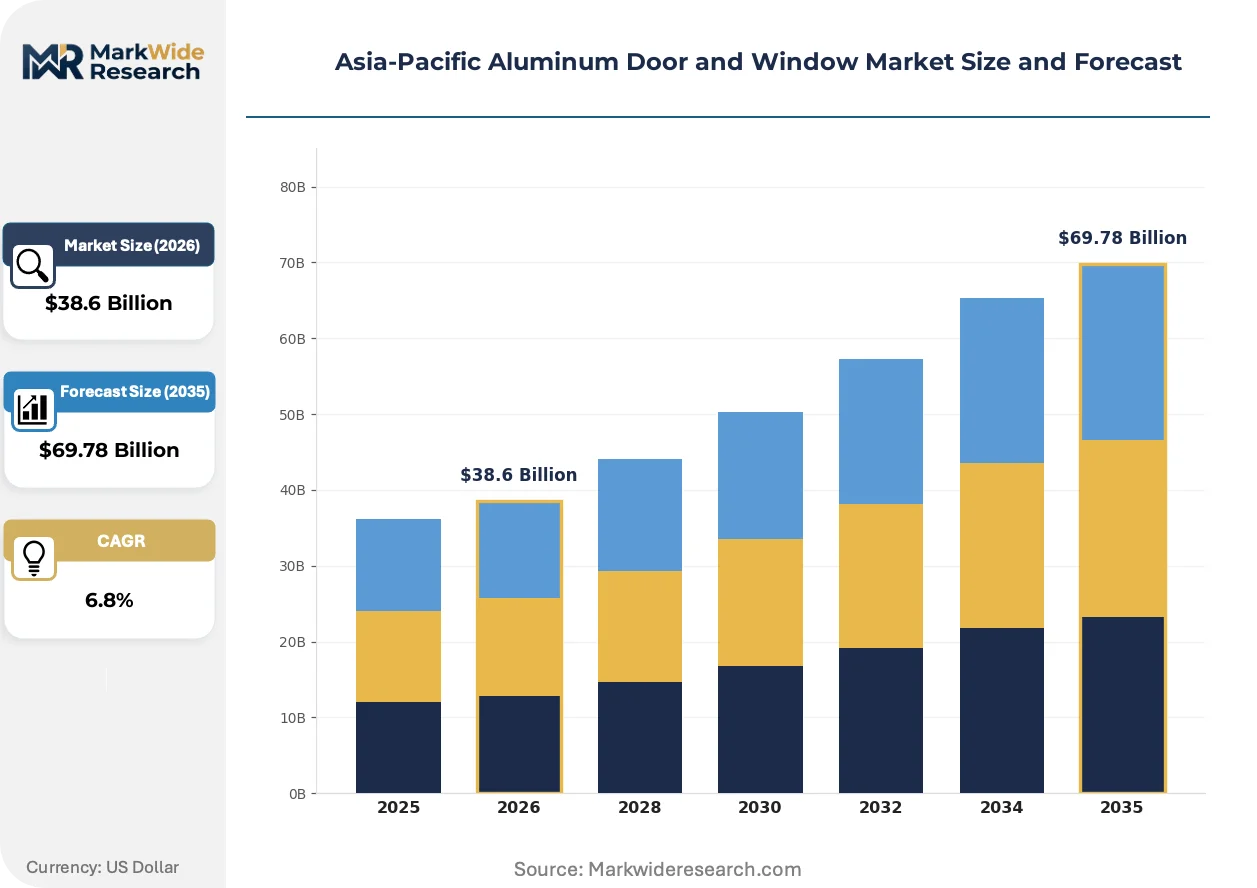
Market Dynamics
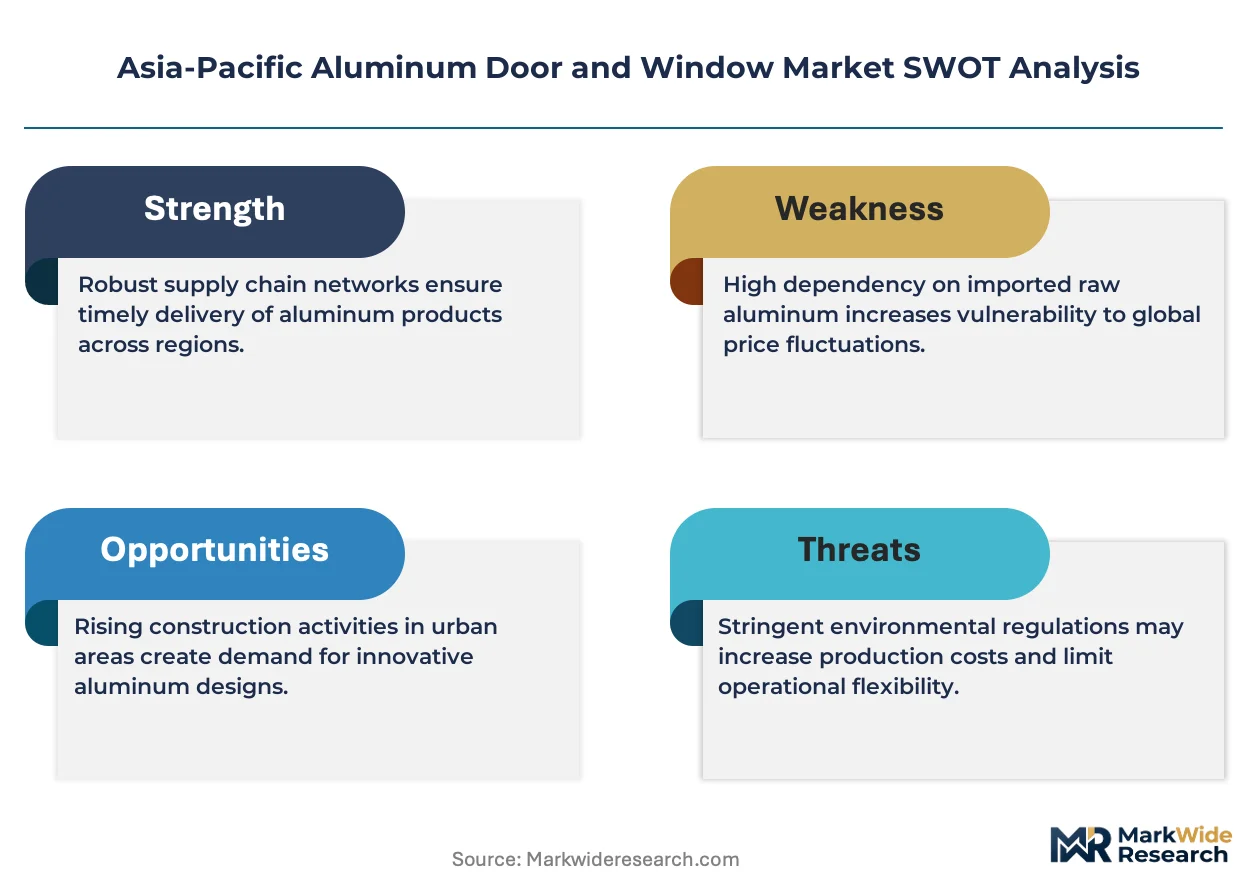
Thermal break extrusion technology is fragmenting traditional aluminum fabrication across Asia-Pacific as energy codes tighten and developers specify climate-responsive building envelopes. The shift from single-piece extrusions to polyamide-stripped assemblies reconfigures margin pools and supplier hierarchies.
Growth Catalysts
- China's GB 50189 energy codes:Commercial tower developers in Shanghai and Shenzhen now mandate U-values below 2.0 W/m²K, forcing specification upgrades across high-rise envelopes.
- India's BIS envelope standards:IS 733 compliance for structural extrusions accelerates thermal break frame adoption in institutional and hospitality construction.
- Vietnam's urban corridor concentration:Residential development clustering from Ho Chi Minh City to Binh Duong generates standardized volume demand for sliding door systems.
Market Restraints
- Primary aluminum price volatility:LME-linked input costs compress fabricator margins when construction payment cycles lag spot price movements by 90-120 days.
- Extrusion die concentration:High-precision thermal break profile tooling remains concentrated among Japanese and Korean specialty suppliers, creating bottleneck risk.
- Polyamide thermal strip substitution limits:PA66 GF25 remains the only viable thermal barrier material certified across multiple national building codes, locking designs to single-supplier chemistry.
Strategic Opportunities
- Indonesia's logistics and hospitality FDI:Foreign direct investment flows into warehouse and hotel assets outpace residential growth, creating demand for commercial-grade curtain wall systems.
- Low-emissivity glazing convergence:Integration of thermal break frames with double-silver and triple-silver low-E coatings enables single-source envelope procurement for net-zero buildings.
- Japan's METI efficiency regulations:Building energy codes now reward whole-envelope performance rather than component compliance, favoring integrated frame-glazing suppliers.
Industry Challenges
- Thermal break assembly skill scarcity:Polyamide strip insertion and crimping precision requires technician training programs that lag behind installation volume growth in Vietnam and Indonesia.
- Cross-border certification friction:Divergence between China's GB standards, India's BIS mandates, and Japan's JIS requirements complicates pan-Asia-Pacific project execution for multinational developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aluminum Door and Window Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Bi-Fold Doors, Casement Windows, Fixed Windows Application: Residential Buildings, Commercial Buildings, Industrial Facilities, Government Projects Frame Type: Thermal Break Frames, Non-Thermal Frames, Impact Resistant Frames, Standard Frames End User: Contractors, Architects, Homeowners, Developers |
| Companies Covered | VEKA, Oppein Home Group Inc., LIXIL Corporation, Shanghai Finzone Windows & Doors Co. Ltd., Huahe Group Co. Ltd., YKK AP, Shanghai SunFlower Group Co. Ltd., Foshan Huge Aluminum Co. Ltd., Profine Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aluminum Door and Window Market Evolving Landscape
Digital fabrication and material science convergence are compressing product development cycles and enabling mass customization of climate-specific frame profiles. Three distinct vectors currently reshape competitive positioning.
Polyamide thermal break technology is migrating from European-origin systems toward localized extrusion networks in Southeast Asia. Japanese fabricators now license crimping and rolling equipment to Thai and Vietnamese partners. This technology transfer compresses lead times for high-performance frames while eroding the premium position of fully imported systems.
China's MIIT enforcement of updated GB standards for aluminum alloy construction profiles tightens chemical composition tolerances and mechanical property verification. Fabricators must maintain batch-level traceability from billet to finished frame. The compliance burden falls most heavily on mid-scale residential suppliers lacking in-house metallurgical testing capacity.
Developer procurement of envelope systems now bundles glazing, framing, and installation through single-source contracts rather than discrete component sourcing. General contractors in India's tier-one cities consolidate vendor panels to reduce interface risk. This concentration is most visible in Bengaluru and Hyderabad's commercial tower pipelines, where facade performance guarantees now span 10-year warranties.
Asia-Pacific Aluminum Door and Window Market Segmentation
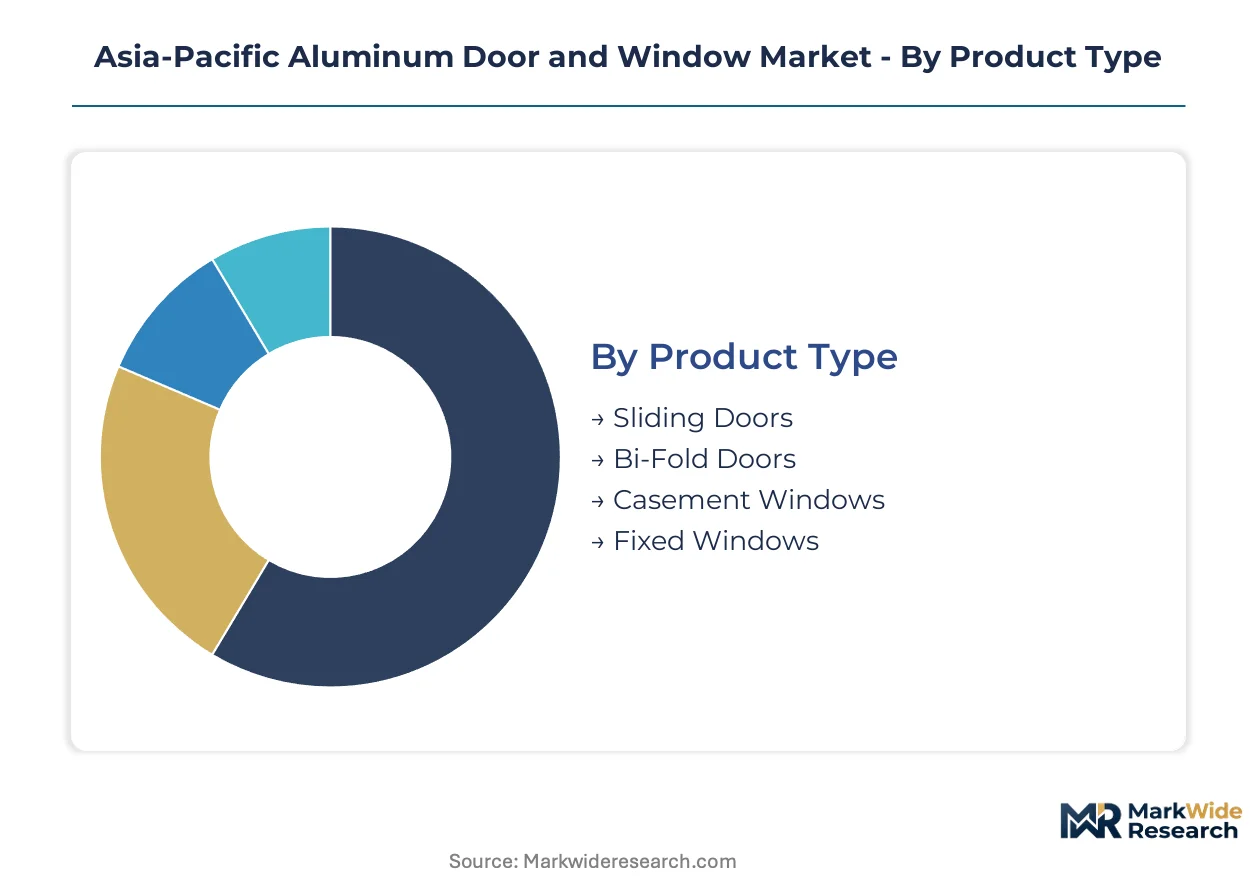
Segmentation in the Asia-Pacific aluminum door and window market reveals distinct procurement cycles and specification hierarchies. Residential developers in Vietnam and Indonesia rotate inventory faster than institutional contractors executing government projects. Thermal break technology penetration varies sharply across these boundaries.
Product Type:
Sliding doors turn inventory fastest in dense urban corridors where space constraints dominate design briefs. Fixed windows move slowest through specification channels due to longer lead times for custom glazing integration.
- Sliding Doors:Horizontal track systems fabricated from 6063-T5 extrusions dominate residential volume in Ho Chi Minh City-to-Binh Duong corridor developments. Space efficiency requirements in Vietnamese and Indonesian high-rise towers drive specification dominance.
- Casement Windows:Side-hinged configurations with multi-point locking hardware achieve superior air tightness for India's BIS energy compliance. Thermal break integration is mandatory in Bengaluru and Hyderabad commercial towers pursuing green certification.
- Bi-Fold Doors:Multi-panel folding systems command premium positioning in Australian and Japanese luxury residential retrofits.
- Fixed Windows:Non-operable glazing frames serve curtain wall applications in China's Shanghai and Shenzhen commercial towers.
Sliding doors anchors the volume base while casement windows gains share at the steepest rate.
Application:
Cost tier stratification separates specification-driven commercial procurement from price-sensitive residential volume. Government projects occupy the highest compliance tier with extended payment cycles.
- Residential Buildings:High-rise apartment towers across Vietnam's urban corridor and Indonesia's Jakarta-Bandung axis generate standardized demand for sliding door systems. Payment terms compress fabricator margins when primary aluminum prices fluctuate.
- Commercial Buildings:Green-certified towers in Shanghai and Shenzhen mandate U-values below 2.0 W/m²K, forcing thermal break frame upgrades. Facade performance guarantees now span 10-year warranties in India's tier-one cities.
- Industrial Facilities:Warehouse and logistics assets in Indonesia receive foreign direct investment flows outpacing residential growth.
- Government Projects:Institutional construction in India accelerates thermal break adoption through BIS envelope standards compliance.
Commercial buildings command the premium tier while residential buildings delivers the volume foundation.
Frame Type:
Supply concentration around polyamide thermal strip technology creates margin differentiation. Non-thermal frames retreat to cost-driven segments as energy codes tighten.
- Thermal Break Frames:Polyamide PA66 GF25 strips crimped into 6063-T5 extrusions achieve U-values below 2.0 W/m²K. China's GB 50189 and India's BIS standards accelerate specification in high-rise commercial envelopes.
- Non-Thermal Frames:Single-piece extrusions without thermal barriers serve budget residential segments in secondary Vietnamese and Indonesian cities where energy codes remain unenforced.
- Impact Resistant Frames:Reinforced profiles with laminated glazing integration target typhoon-exposed coastal developments in Philippines and southern China.
- Standard Frames:Basic anodized or powder-coated extrusions without thermal performance certification serve renovation and replacement demand.
Thermal break frames anchors the technology trajectory while impact resistant frames climbs fastest in climate-vulnerable geographies.
End User:
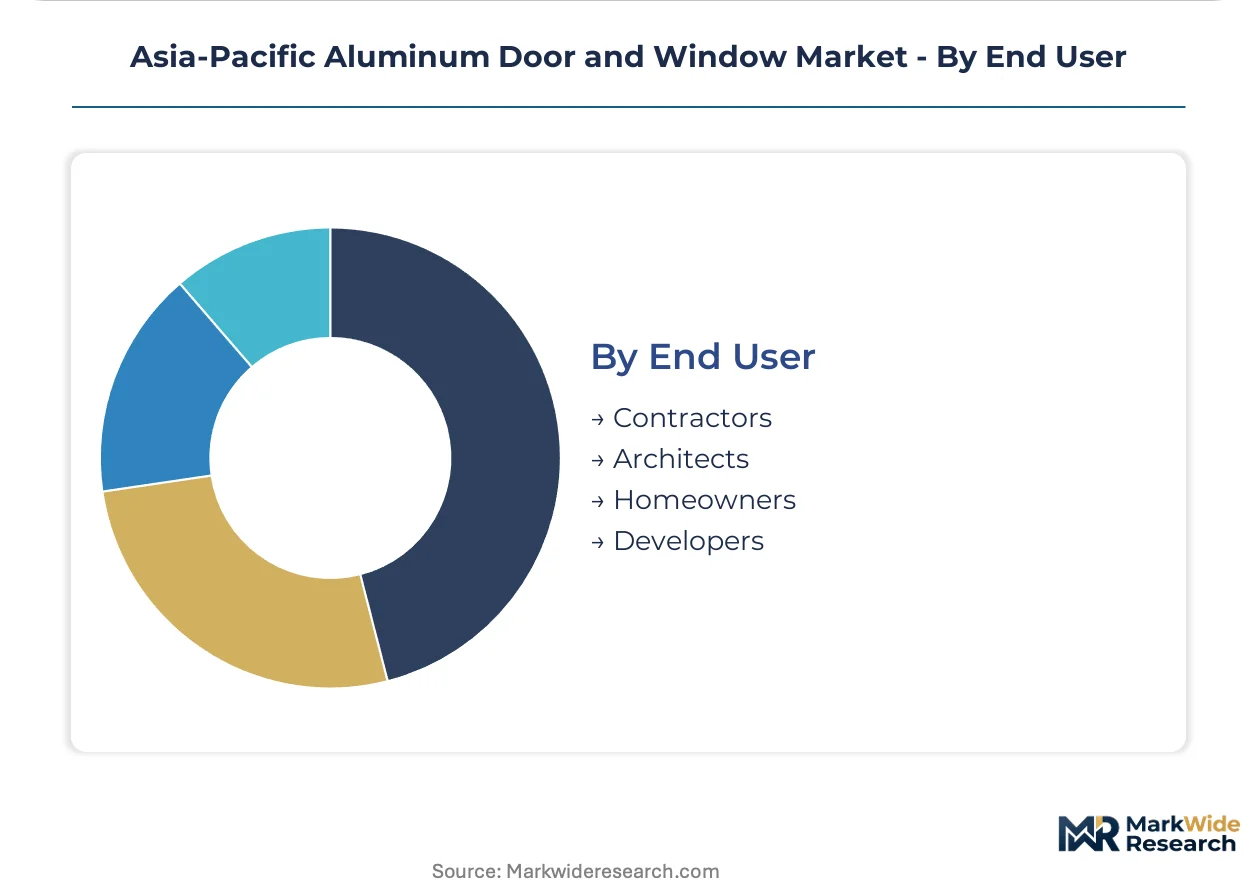
Customer type determines specification authority and procurement consolidation patterns. Developers and architects control upstream design decisions while contractors execute downstream.
- Developers:Pan-Asia-Pacific commercial tower developers in Bengaluru, Hyderabad, and Jakarta now bundle envelope systems through single-source contracts. Vendor panel consolidation reduces interface risk on large-scale projects.
- Architects:Design professionals in Japan and Australia specify whole-envelope performance rather than component compliance under METI efficiency regulations.
- Contractors:Installation specialists in Vietnam and Indonesia face thermal break assembly skill scarcity as polyamide strip insertion training lags volume growth.
- Homeowners:Individual purchasers in Australian and Japanese markets drive replacement demand for high-performance retrofits.
Developers controls the specification gateway while contractors faces the execution bottleneck.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports thermal break frame components to Vietnam and Indonesia, feeding construction booms along Southeast Asian urban corridors. Japanese fabricators supply high-performance systems to Australian commercial tower projects. Indian extruders serve domestic green building certification pipelines.
China
Commercial tower construction in Shanghai and Shenzhen drives thermal break frame demand as MIIT enforces updated GB standards for aluminum alloy construction profiles. GB 50189 energy codes now mandate U-values below 2.0 W/m²K for high-rise envelopes. The Yangtze River Delta and Pearl River Delta clusters concentrate precision extrusion capacity serving both domestic and export markets.
India
Institutional and hospitality construction in Bengaluru and Hyderabad accelerates thermal break adoption through BIS envelope standards compliance. IS 733 mandates chemical composition and mechanical property verification for structural extrusions. The Maharashtra-Gujarat industrial corridor hosts expanding fabrication capacity targeting green-certified commercial towers.
Vietnam
High-rise residential development clustering from Ho Chi Minh City to Binh Duong generates standardized volume demand for sliding door systems. National building codes remain unevenly enforced, creating tiered specification markets. The southern urban corridor concentrates foreign-invested fabrication joint ventures serving both domestic and Cambodian construction demand.
Indonesia
Foreign direct investment flows into warehouse and hotel assets outpace residential growth, creating demand for commercial-grade curtain wall systems. Logistics facility construction in the Jakarta-Bandung axis specifies thermal break frames for climate-controlled interiors. The Greater Jakarta metro anchors imported system assembly and local extrusion partnerships.
Japan
Building energy efficiency regulations under METI reward whole-envelope performance rather than component compliance, favoring integrated frame-glazing suppliers. Luxury residential retrofits in Tokyo and Osaka drive premium bi-fold door demand. The Kanto and Kansai regions concentrate R&D-intensive fabricators licensing crimping technology to Southeast Asian partners.
Asia-Pacific Aluminum Door and Window Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered specification markets. Japanese and Korean fabricators anchor premium thermal break engineering through licensed equipment networks. Chinese extruders dominate volume production of standardized residential frames. Three archetypes define positioning: integrated system suppliers bundling glazing and installation, component specialists selling extrusions and thermal strips to third-party assemblers, and regional fabricators serving single-city construction markets. Competitive moves center on technology licensing agreements and backward integration into polyamide thermal strip production.
Among Asia-Pacific-based fabricators, LIXIL Corporation, YKK AP, and Shanghai Finzone Windows & Doors Co. Ltd. occupy distinct tier positions. LIXIL exemplifies the integrated system supplier archetype through its Japanese R&D base and regional finishing networks. YKK AP represents channel control through captive extrusion and distribution infrastructure spanning Southeast Asian urban corridors. Shanghai Finzone sits within the scale-driven domestic specialist tier, serving China's concentrated commercial tower pipelines. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning without overlapping segment claims.
| Leading Market Players |
|---|
| VEKA |
| Oppein Home Group Inc. |
| LIXIL Corporation |
| Shanghai Finzone Windows & Doors Co. Ltd. |
| Huahe Group Co. Ltd. |
| YKK AP |
| Shanghai SunFlower Group Co. Ltd. |
| Foshan Huge Aluminum Co. Ltd. |
| Profine Group |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta's precision extrusion capacity concentration grants Chinese fabricators asymmetric pricing power over Vietnamese and Indonesian developers. Downward pressure on thermal break frame margins intensifies when LME-linked aluminum billets spike ahead of fixed-price construction contracts.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange primary aluminum pricing dominate commercial tower procurement in Shanghai and Shenzhen. Price differentiation rests on thermal performance certification tier and glazing integration complexity. Pricing pressure intensifies in Vietnam's residential segment as Chinese exporters absorb freight costs to defend volume share. Government project contractors exhibit lowest price sensitivity due to extended payment cycles and specification rigidity.
Supply Chain Analysis
Export controls on high-precision extrusion die technology from Japan and Korea constrain thermal break profile manufacturing expansion in Southeast Asia. Raw material flows draw from Chinese aluminum smelters, German polyamide resin suppliers, and domestic Southeast Asian powder-coat providers. Single-source vulnerability concentrates around PA66 GF25 thermal strip chemistry locked to certified formulations. Distribution runs through fabricator-direct contracts with pan-Asia-Pacific developers consolidating vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. BIS and GB standard compliance creates switching costs that anchor incumbent positions across institutional procurement channels.
For Market Incumbents: Pre-empt margin compression by backward integration into polyamide thermal strip production and captive extrusion capacity in Thailand. Defend against Chinese volume exporters by embedding ten-year facade performance guarantees into commercial tower contracts. Certification investment in India's IS 733 compliance anchors institutional hospitality pipelines.
For New Entrants and Emerging Players: Pursue white-space opportunities in Indonesia's logistics facility segment where foreign direct investment outpaces established supplier relationships. Target warehouse construction in the Jakarta-Bandung axis with standardized curtain wall systems priced below imported Japanese equivalents. Go-to-market leverage rests on licensing crimping technology from Korean equipment specialists rather than proprietary R&D investment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated frame-glazing-installation suppliers with ten-year performance warranties. Long-term viability favors fabricators with captive Southeast Asian extrusion networks serving cross-border urban corridor development. Acquisition screening should prioritize Thai and Vietnamese joint ventures with licensed Japanese thermal break technology. The signal to watch is consolidation of vendor panels by Indian tier-one city general contractors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Strip Production | Captive supply of PA66 GF25 thermal barriers insulates margins from German resin supplier pricing power. |
| Thermal Break Crimping Technology Licensing | Japanese equipment transfer to Thai and Vietnamese partners compresses lead times for high-performance frame assembly. |
| Integrated Frame-Glazing-Installation Contracts | Single-source envelope procurement reduces interface risk for Bengaluru and Hyderabad commercial tower developers. |
| IS 733 and GB 50189 Certification Investment | Compliance with India's BIS and China's MIIT standards unlocks institutional and green-certified commercial pipelines. |
| Southeast Asian Extrusion Capacity Expansion | Localized 6063-T5 profile production serving Vietnam's Ho Chi Minh City-to-Binh Duong corridor defends against Chinese import competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, MIIT and BIS regulatory filings, and aluminum industry association reports across the analysis window. Primary interviews engaged facade engineering directors at commercial tower developers, thermal break fabrication plant managers, and procurement leads at Indian and Vietnamese general contractors. Secondary validation drew from LME price series, SEC filings of listed building materials suppliers, and national building code enforcement notices. Bottom-up project pipeline enumeration triangulates against top-down construction spending forecasts.
Forecast inputs span product type segmentation across sliding doors, casement windows, and fixed glazing systems; application tiers separating residential, commercial, and industrial construction; frame technology differentiation between thermal break and non-thermal configurations; and end-user procurement patterns among developers, architects, and contractors. CAGRs derive from regression analysis of historical installation volumes against energy code enforcement timelines and foreign direct investment flows. Industry-specific modeling incorporates polyamide thermal strip adoption curves and cross-border technology licensing velocity.
Sensitivities concentrate around LME aluminum price volatility, divergence in national certification regime enforcement, and thermal break assembly skill scarcity in Vietnam and Indonesia. Forecasts reflect documented assumptions on energy code tightening schedules and logistics facility investment momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Qatar Facade Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Asia-Pacific Cement Market
Building Materials
West Africa Cement Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Global Metal Cladding Market
Building Materials
HDG Steel Pipe Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Global Pozzolan Market
Building Materials
Global Building Panels Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Global Corrugated Steel Sheets Market