
 Concrete Floor Grinding Machine Market | 2026-2036
Concrete Floor Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Floor Grinding Machine Market Analytics
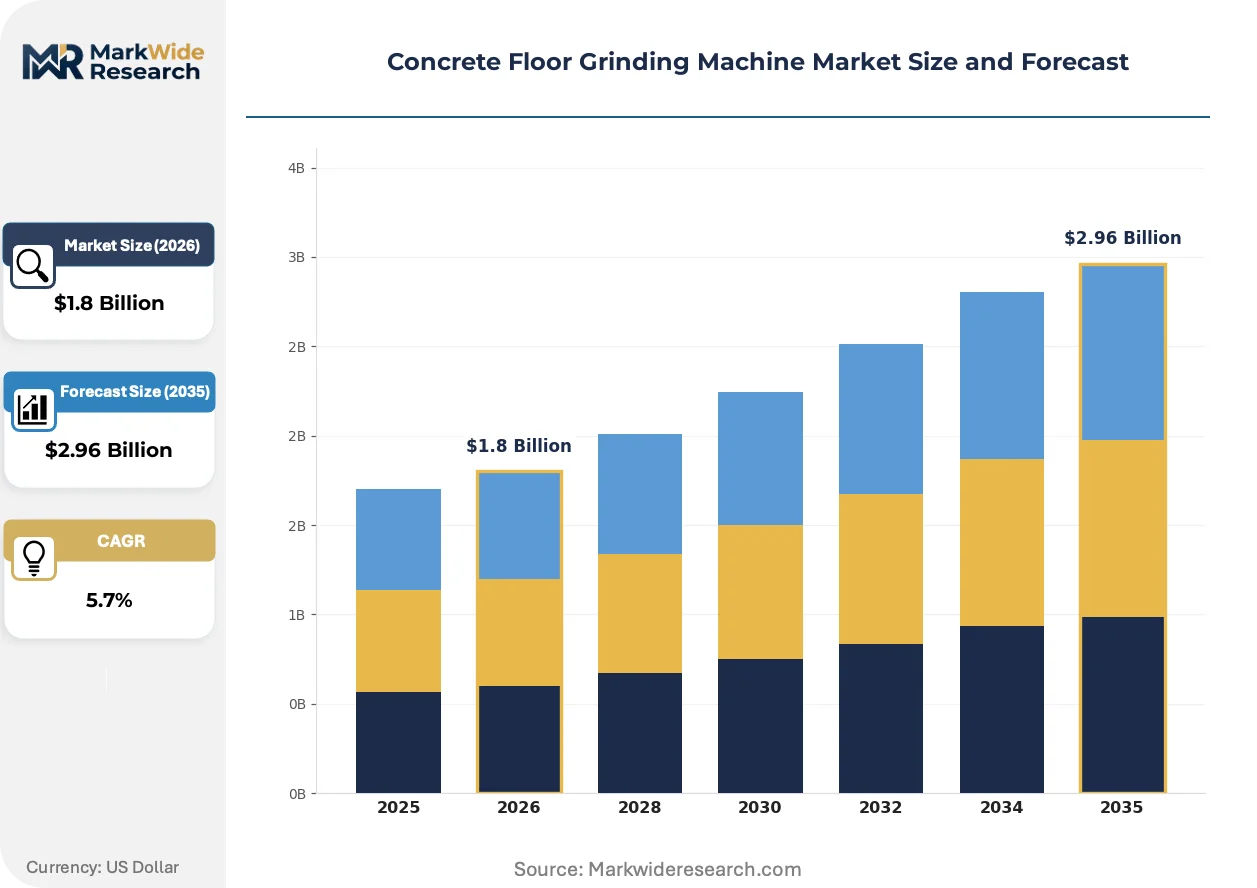
Modular attachment systems for diamond tooling and dust extraction is recalibrating how flooring contractors configure capital purchases. Husqvarna Group leverages its integrated dust-control technology to anchor premium positioning in commercial applications. SASE Company LLC competes through specialized propane-powered grinders for industrial warehouse deployments. Fujian Xingyi Polishing Machine Co., Ltd. dominates cost-sensitive segments with electric walk-behind units manufactured at scale.
Concrete floor grinding machines are rotary surface preparation equipment utilizing diamond-segmented abrasives mounted on planetary or single-disc heads to remove coatings, level substrates, or polish concrete to specified grit finishes. Walk-behind electric units serve the broadest contractor base for residential and light commercial work, while ride-on configurations command higher margins in industrial facilities where productivity per hour determines project economics. Gas-powered technology leads in outdoor or unpowered job sites, though hydraulic systems are gaining share in heavy-removal applications where torque consistency matters.
OSHA's Respirable Crystalline Silica standard compels equipment manufacturers to engineer certified dust-collection integration, while EPA emissions regulations constrain gas-powered model specifications in enclosed environments. The EU Green Deal's machinery efficiency directives are reshaping electric motor requirements for units sold in European markets. Stakeholders must weigh total cost of ownership against regional compliance thresholds when selecting powertrain and dust-control configurations.
Market Dynamics
OSHA's Respirable Crystalline Silica standard is forcing equipment manufacturers to engineer certified dust-collection integration as a non-negotiable baseline feature, compressing margins for undifferentiated suppliers while rewarding engineered systems with regulatory pre-approval.
Growth Catalysts
- Commercial Renovation Surge:North American retail and logistics facility retrofits are expanding equipment rental demand for surface preparation contractors. Property managers prioritize fast-turnaround polishing systems to minimize tenant downtime.
- EU Green Deal Machinery Directives:Efficiency mandates for electric motors are accelerating replacement cycles in European markets. Manufacturers redesigning motor architectures capture preferential procurement from sustainability-certified contractors.
- Silica Dust Compliance:OSHA enforcement is compelling contractors toward dust-controlled grinding systems. Equipment lacking certified extraction faces de facto exclusion from commercial and industrial bidding pools.
Market Restraints
- Diamond Abrasive Cost Volatility:Synthetic diamond supply concentrates in Chinese manufacturing clusters. Price swings in raw carbide substrates compress grinding contractor margins on fixed-bid projects.
- Gas-Powered EPA Constraints:Emissions regulations limit gas-powered model specifications in enclosed environments. Contractors operating mixed fleets face equipment redundancy and higher compliance documentation burdens.
- Walk-Behind Productivity Ceiling:Manual push units hit throughput limits on large-format warehouse floors. Ride-on alternatives require capital outlays that exclude smaller regional contractors from industrial tier bidding.
Strategic Opportunities
- Indian Infrastructure Buildout:Commercial real estate expansion in Mumbai and Bangalore creates first-mover positioning for rental fleet operators. Local contractors lack capital for owned equipment, favoring monthly rental structures.
- Battery-Electric Convergence:Lithium-ion powertrains paired with onboard dust extraction enable cord-free indoor operation. Early adopters in healthcare and food-processing verticals pay premiums for zero-emission certification.
- Telematics-Enabled Servitization:Hourly-usage billing models with predictive maintenance alerts are displacing traditional ownership. Equipment financiers in Germany pilot subscription offerings tied to guaranteed uptime thresholds.
Industry Challenges
- Diamond Tooling Skill Shortage:Proper grit progression and segment selection require hands-on training that vocational programs undersupply. Contractors misconfigure attachments, accelerating wear and generating rework costs.
- Multi-Vendor Integration Complexity:Dust extractors from third-party suppliers often interface poorly with grinder electronics. Field technicians waste hours troubleshooting compatibility failures across mixed-brand job sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Floor Grinding Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind, Ride-On, Edge Grinder, Concrete Polisher Application: Commercial, Residential, Industrial, Retail End User: Construction Companies, Flooring Contractors, Property Managers, DIY Enthusiasts Technology: Electric, Gas, Hydraulic, Pneumatic |
| Companies Covered | Husqvarna Group, SASE Company LLC, Achilli S.r.l., Klindex Srl, Fujian Xingyi Polishing Machine Co., Ltd., Bartell Global Inc., Blastrac, HTC Group, Scanmaskin Sverige AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Floor Grinding Machine Market Evolving Landscape
Planetary head configurations with variable pressure control are displacing fixed-head designs across premium contractor segments. Three interconnected developments are compressing traditional equipment specifications and rewiring procurement priorities.
Remote torque-monitoring sensors embedded in planetary drive systems are rewriting maintenance economics for fleet operators. Large-scale flooring contractors in Texas and Florida deploy these units to predict bearing failures before catastrophic downtime. The data stream enables outcome-based service contracts where manufacturers retain ownership risk.
REACH chemical restrictions on cobalt-containing diamond bond matrices are forcing European suppliers to reformulate segment compositions. Abrasive manufacturers in Italy and Poland accelerate ceramic-metal hybrid bonds to maintain cutting rates. The transition adds six to nine months to new product qualification timelines for CE-marked equipment.
Equipment-as-a-service contracting is displacing capital purchase models among mid-tier commercial flooring specialists. Rental platforms in California and Ontario bundle grinders, extractors, and consumables into single monthly rates. The shift concentrates fleet purchasing power with national rental chains, compressing distributor margins on unit sales.
Concrete Floor Grinding Machine Market Segmentation
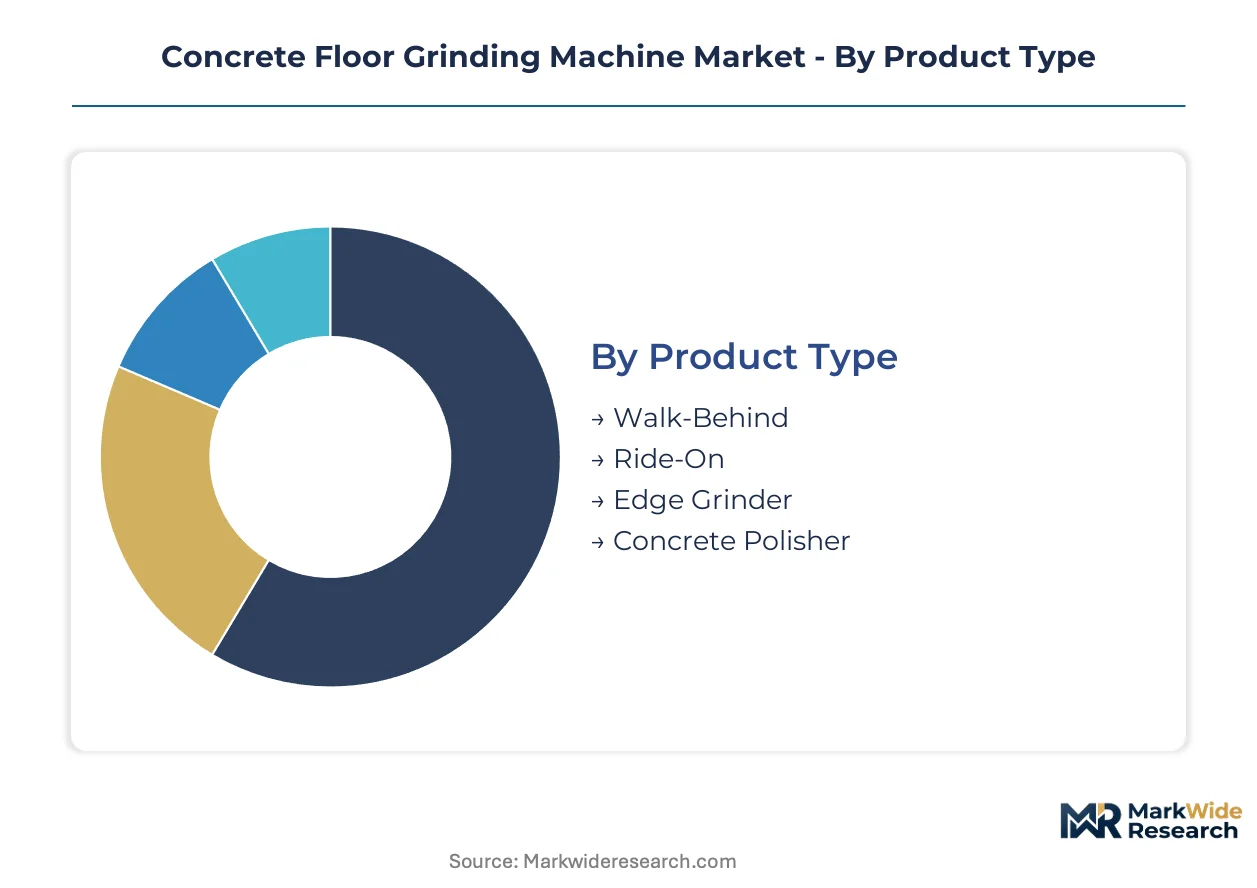
Powertrain certification requirements and dust-control integration standards fragment procurement decisions across contractor tiers. Equipment specification choices cascade through rental fleet composition, maintenance protocols, and operator training investments.
Product Type:
OSHA silica compliance and CE marking requirements apply unevenly across configurations, with ride-on units facing stricter electromagnetic compatibility testing and walk-behind models prioritizing extraction port standardization.
- Walk-Behind:Electric and propane variants dominate residential and light commercial surface preparation. Flooring contractors in Texas and Florida favor these units for tenant improvement projects where maneuverability outweighs raw throughput.
- Ride-On:Planetary head configurations with integrated dust collection serve industrial warehouse deployments across Germany and China. These units command premium positioning where OSHA silica enforcement drives certified extraction mandates.
- Edge Grinder:Compact single-disc designs address perimeter work and confined spaces.
- Concrete Polisher:Variable-speed planetary systems achieve specified grit finishes for retail and healthcare flooring.
Walk-Behind sits at the top of the volume ranking, with Ride-On climbing the fastest.
Application:
Project scale and substrate condition determine whether contractors deploy owned equipment or rental fleet solutions.
- Commercial:Office retrofits and hospitality renovations in Ontario and California drive monthly rental structures. Fast-turnaround polishing requirements compress project timelines and favor equipment-as-a-service contracting.
- Industrial:Manufacturing facilities and distribution centers in Germany specify ride-on configurations with telematics-enabled predictive maintenance. Torque consistency and uptime guarantees determine procurement decisions.
- Residential:Single-family and multi-unit surface preparation favors walk-behind electric units.
- Retail:Tenant improvement cycles prioritize dust-controlled operation during business hours.
Commercial leads absolute unit deployment, while Industrial shows the steepest expansion trajectory.
End User:
Capital availability and project recurrence shape ownership versus rental preferences across contractor categories.
- Construction Companies:General contractors with diversified project portfolios maintain mixed fleets across powertrain types. Mixed-brand job sites generate integration complexity with third-party dust extractors.
- Flooring Contractors:Specialized surface preparation firms in Poland and Italy face REACH chemical restrictions on cobalt-containing diamond bonds. Ceramic-metal hybrid segment qualification timelines extend equipment replacement cycles.
- Property Managers:Facility maintenance departments favor rental platforms for periodic restoration work.
- DIY Enthusiasts:Residential owner-operators drive entry-level electric walk-behind demand.
Construction Companies represent the largest addressable base, with Flooring Contractors gaining share fastest.
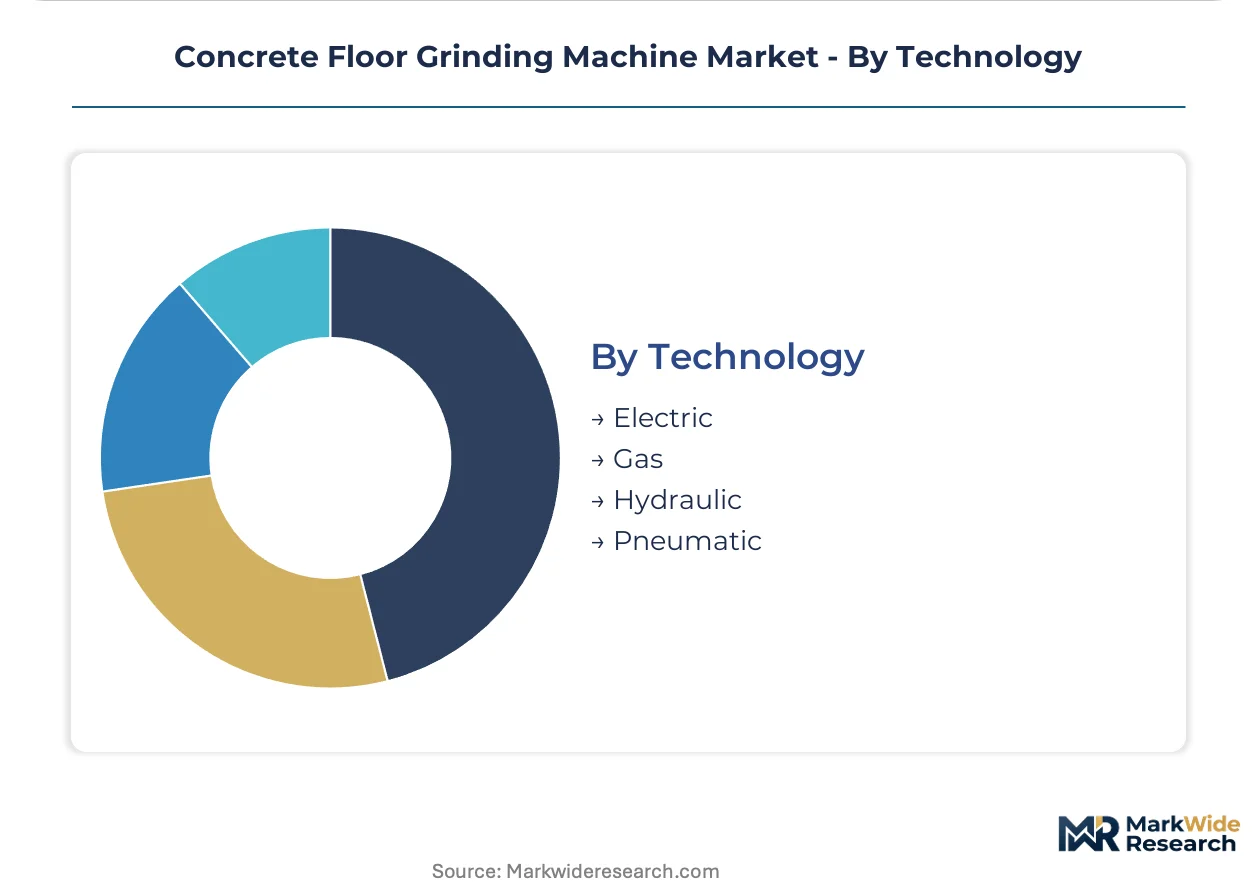
Technology:
Emissions regulations and indoor air quality standards constrain powertrain selection in enclosed environments.
- Electric:Corded and battery-electric configurations satisfy EPA indoor air requirements and EU Green Deal motor efficiency directives. Healthcare and food-processing verticals in California pay premiums for zero-emission certification.
- Gas:Propane and gasoline units lead outdoor and unpowered job sites. EPA emissions documentation burdens constrain deployment in enclosed commercial spaces.
- Hydraulic:Heavy-removal applications favor torque consistency over speed.
- Pneumatic:Compressed-air systems serve specialized explosive atmosphere requirements.
Electric dominates installed base volume, with battery-electric variants expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concrete floor grinding technology originated in post-war Germany and Italy, where terrazzo restoration traditions created early demand for planetary head systems. Equipment manufacturing subsequently dispersed across industrialized markets as surface preparation standards professionalized.
United States
Commercial renovation across Texas and Florida drives rental fleet expansion among surface preparation contractors. OSHA silica enforcement compels dust-controlled system procurement for commercial bidding eligibility. Dallas-Fort Worth logistics facility retrofits concentrate demand for fast-turnaround polishing configurations.
Germany
Industrial warehouse deployments in Bavaria and North Rhine-Westphalia specify ride-on units with telematics-enabled maintenance. EU Green Deal motor efficiency directives accelerate replacement cycles for electric grinding equipment. Stuttgart-area manufacturing clusters anchor premium equipment assembly for European distribution.
China
Infrastructure buildout in Yangtze River Delta and Pearl River Delta regions expands cost-sensitive contractor equipment demand. MIIT machinery efficiency standards reshape domestic motor specifications for export-bound units. Fujian province manufacturing bases dominate electric walk-behind volume production for global supply.
India
Commercial real estate expansion in Mumbai and Bangalore creates rental market opportunities for fleet operators. BIS equipment safety certification requirements constrain import specifications for surface preparation machinery. Maharashtra contractor bases lack capital for owned equipment, favoring monthly rental structures over purchase.
Canada
Ontario retail and hospitality renovation cycles drive equipment-as-a-service contracting among mid-tier flooring specialists. Health Canada indoor air quality guidelines influence dust extraction system specifications for enclosed commercial work. Toronto-Greater Golden Horseshoe corridor concentrates contractor demand for tenant improvement grinding services.
Concrete Floor Grinding Machine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across dust-control integration and telematics capability. The vendor base organizes into three functional tiers: integrated system architects, specialized powertrain fabricators, and scale-driven volume producers. Strategic differentiation concentrates on certified regulatory pre-approval, outcome-based service contracting, and motor efficiency architecture. Competitive moves prioritize M&A for dust-extraction technology integration and geographic expansion through rental platform partnerships.
Within the integrated system tier, Husqvarna Group anchors premium positioning through dust-control technology bundling. SASE Company LLC and Fujian Xingyi Polishing Machine Co., Ltd. occupy opposing ends of the powertrain specialization spectrum, with the former representing propane-powered industrial configurations and the latter exemplifying scale-driven electric walk-behind manufacturing. These three entities collectively illustrate how regulatory compliance depth, powertrain diversity, and production scale define competitive positioning in fragmented procurement environments.
| Leading Market Players |
|---|
| Husqvarna Group |
| SASE Company LLC |
| Achilli S.r.l. |
| Klindex Srl |
| Fujian Xingyi Polishing Machine Co., Ltd. |
| Bartell Global Inc. |
| Blastrac |
| HTC Group |
| Scanmaskin Sverige AB |
| Others |
Value Network & Pricing Analysis
Synthetic diamond price indices on Chinese carbide substrate markets cascade directly through grinding machine manufacturing costs, compressing margins for fixed-bid contractors while amplifying pricing power for integrated suppliers with captive abrasive production. Equipment tiers stratify across dust-control certification levels, with OSHA-compliant ride-on configurations commanding substantial premiums over basic walk-behind units lacking certified extraction integration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, separating telematics-enabled ride-on systems from basic electric walk-behind units and entry-level residential grinders. Price differentiation rests on motor efficiency certification under EU Green Deal directives and OSHA silica compliance pre-approval status. Cost compression in the standard tier is intensifying because synthetic diamond supply volatility feeds through consumable attachment economics. Small regional contractors exhibit highest price sensitivity, while national rental chains absorb premiums for guaranteed uptime service bundling.
Supply Chain Analysis
Container freight rate volatility from Fujian province manufacturing bases to North American distribution hubs directly impacts landed equipment costs for walk-behind electric units. Supply concentrates in China for electric motor assemblies and diamond segment fabrication, with Germany anchoring precision planetary head production and Italy hosting specialized abrasive formulation. Raw material dependencies draw from synthetic diamond synthesis, rare-earth motor magnets, and cobalt bond matrix substrates. Single-source vulnerability concentrates in Chinese carbide substrate supply. Distribution runs through national rental platforms and specialized flooring equipment distributors serving contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal motor efficiency mandates accelerate replacement cycles in Europe while OSHA silica enforcement creates parallel compliance-driven demand in North America, with cost differentials favoring integrated manufacturers with dual-certification capabilities.
For Market Incumbents: Deepen backward integration into diamond segment manufacturing to offset synthetic diamond price volatility threatening fixed-bid contractor margins. Expand captive dust-extraction technology development to defend premium positioning against emerging battery-electric entrants with integrated cordless systems. Prioritize telematics platform investment to capture outcome-based service contract growth displacing traditional unit sales. For New Entrants and Emerging Players: Launch via equipment-as-a-service rental platforms targeting Indian commercial real estate expansion in Mumbai and Bangalore where contractor capital constraints favor monthly structures over purchase. Target battery-electric walk-behind configurations for healthcare and food-processing verticals paying zero-emission premiums. Exploit multi-vendor integration complexity pain points by offering proprietary grinder-extractor bundled systems with guaranteed compatibility. For Investors and Strategic Acquirers: Consolidation pressure builds where regional distributors lack capital for telematics platform investment required by industrial fleet procurement. Long-term viability favors integrated system architects with regulatory pre-approval depth over pure-play powertrain fabricators facing margin compression. Target acquisition archetypes include specialized dust-extraction technology firms and regional rental platforms with established contractor relationships. Monitor battery-electric penetration rates in California and Ontario healthcare verticals as inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Segment Manufacturing | Captive abrasive production insulates margins from Chinese carbide substrate price swings. |
| Battery-Electric Powertrain Development | Cord-free operation with onboard extraction captures healthcare and food-processing premiums. |
| Telematics-Enabled Predictive Maintenance Platform | Outcome-based service contracts displace traditional ownership among national rental chains. |
| Regulatory Pre-Approval Investment | OSHA silica certification and CE marking accelerate procurement eligibility in commercial bidding pools. |
| Rental Platform Partnership Expansion | Equipment-as-a-service bundling concentrates fleet purchasing power with national operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flooring contractors, rental fleet managers, OEM procurement teams, and aftermarket service heads with secondary validation against customs trade data, SEC equipment manufacturer filings, and OSHA enforcement documentation. Bottom-up equipment shipment modeling triangulated against top-down construction spending forecasts across commercial, industrial, and residential application segments.
Historical reference periods anchored the projection horizon through verified installation base data and replacement cycle analysis across electric, gas, and hydraulic powertrain categories. The analytical framework modeled demand by product type, application, end-user capital availability, and technology certification tier, with CAGRs derived from regression analysis against construction output indices and regulatory compliance timelines. Forecast inputs incorporated synthetic diamond supply elasticity and rental penetration rate assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH chemical restriction expansion or lithium-ion battery supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market