
 East Africa Alcoholic Beverages Market | 2026-2036
East Africa Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Alcoholic Beverages Market Intelligence
Traditional off-premise wholesale networks is reconfiguring around modern trade and e-commerce platforms across Nairobi, Kampala, and Dar es Salaam. East African Breweries Limited anchors East Africa's beer volume through its Tusker brand dominance and regional brewing infrastructure. Castel Group leverages its Castle Lager portfolio and vineyard assets to sustain competitive positioning in spirits and wine. Diageo controls premium imported spirits distribution through established duty-free and on-premise partnerships.
East Africa alcoholic beverages encompass fermented and distilled products with ethanol content ranging from approximately 4% ABV in mainstream beers to over 40% ABV in distilled spirits, produced through malting, mashing, fermentation, and either brewing or distillation processes. These products serve social consumption, hospitality, and ceremonial end-uses across Kenya, Tanzania, Uganda, Rwanda, and Ethiopia. Beer occupies the largest volume share given its affordability and established local production, while spirits generates disproportionate margin concentration due to premium pricing and import dependency. Craft positioning within brand positioning segments attracts urban consumer experimentation but remains structurally constrained by raw material access and excise tiering.
Kenya's Alcoholic Drinks Control Act and Tanzania's excise tax framework shape labeling, advertising restrictions, and retail licensing requirements that directly affect market access and product formulation. Uganda's Uganda National Bureau of Standards enforces quality specifications that differentiate compliant formal production from informal alcohol channels. Ethiopia's Food and Drug Administration and Rwanda Standards Board add further compliance layers for cross-border portfolio expansion. Stakeholders must monitor excise harmonization discussions within the East African Community and evolving advertising restrictions that could reshape route-to-market economics.
Market Dynamics
East Africa's alcoholic beverages sector is restructuring around excise tier compression and formalization pressures that favor capitalized brewers over informal distillers. Kenya's Alcoholic Drinks Control Act and Tanzania's 2023 excise adjustments are accelerating compliance costs that reshape competitive economics across the region.
Growth Catalysts
- Urban on-premise consumption:Millennials in Nairobi, Kampala, and Dar es Salaam are driving experiential drinking venues that expand premium beer and spirits attachment rates.
- East African Community harmonization:Excise standardization discussions are creating cross-border portfolio optimization opportunities for regional manufacturers.
- Malt-based portfolio expansion:Local brewing infrastructure investments are reducing import dependency and shortening supply lead times for mainstream beer.
Market Restraints
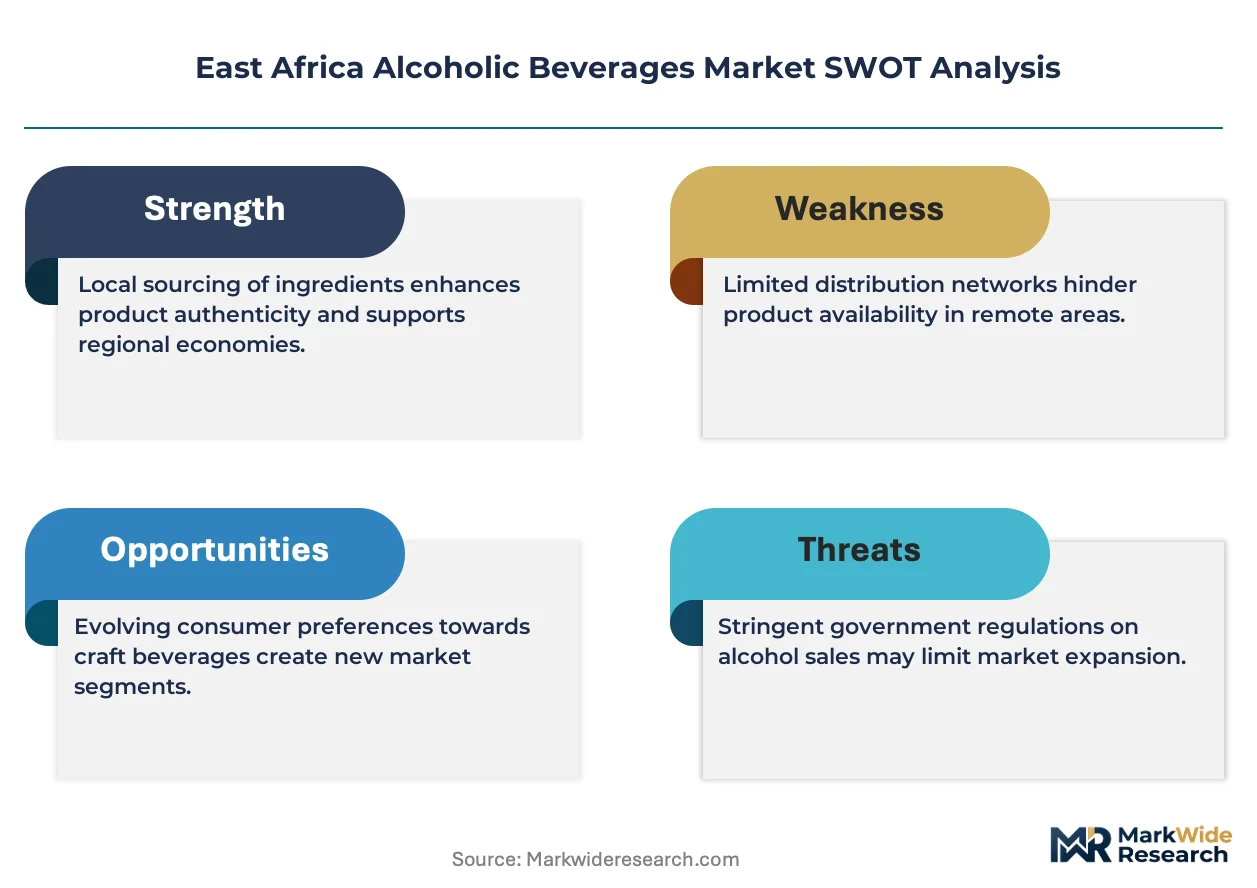
- Sorghum and barley input volatility:Climate-induced harvest variability in Ethiopia and Kenya is compressing margin predictability for malt-dependent producers.
- Informal alcohol channel persistence:Unregulated distillation in rural Uganda and Tanzania captures price-sensitive volume outside tax-compliant frameworks.
- Advertising restriction friction:Kenya's Alcoholic Drinks Control Act imposes broadcast and outdoor limitations that constrain brand-building reach versus spirits categories.
Strategic Opportunities
- Rwanda and Ethiopia penetration:Underdeveloped formal distribution in Kigali and Addis Ababa offers first-mover positioning before competitive saturation.
- E-commerce and modern trade:Digital platforms and supermarket chains in Nairobi and Dar es Salaam are opening direct-to-consumer channels previously blocked by wholesale intermediaries.
- Craft positioning experimentation:Small-batch brewing and localized flavor innovation are attracting urban consumer trial despite raw material access constraints.
Industry Challenges
- Quality certification timelines:Uganda National Bureau of Standards enforcement creates extended approval cycles for new product launches.
- Route-to-market reconfiguration:Shifting from fragmented wholesale networks to controlled retail licensing demands capital-intensive distributor restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Alcoholic Beverages Market |
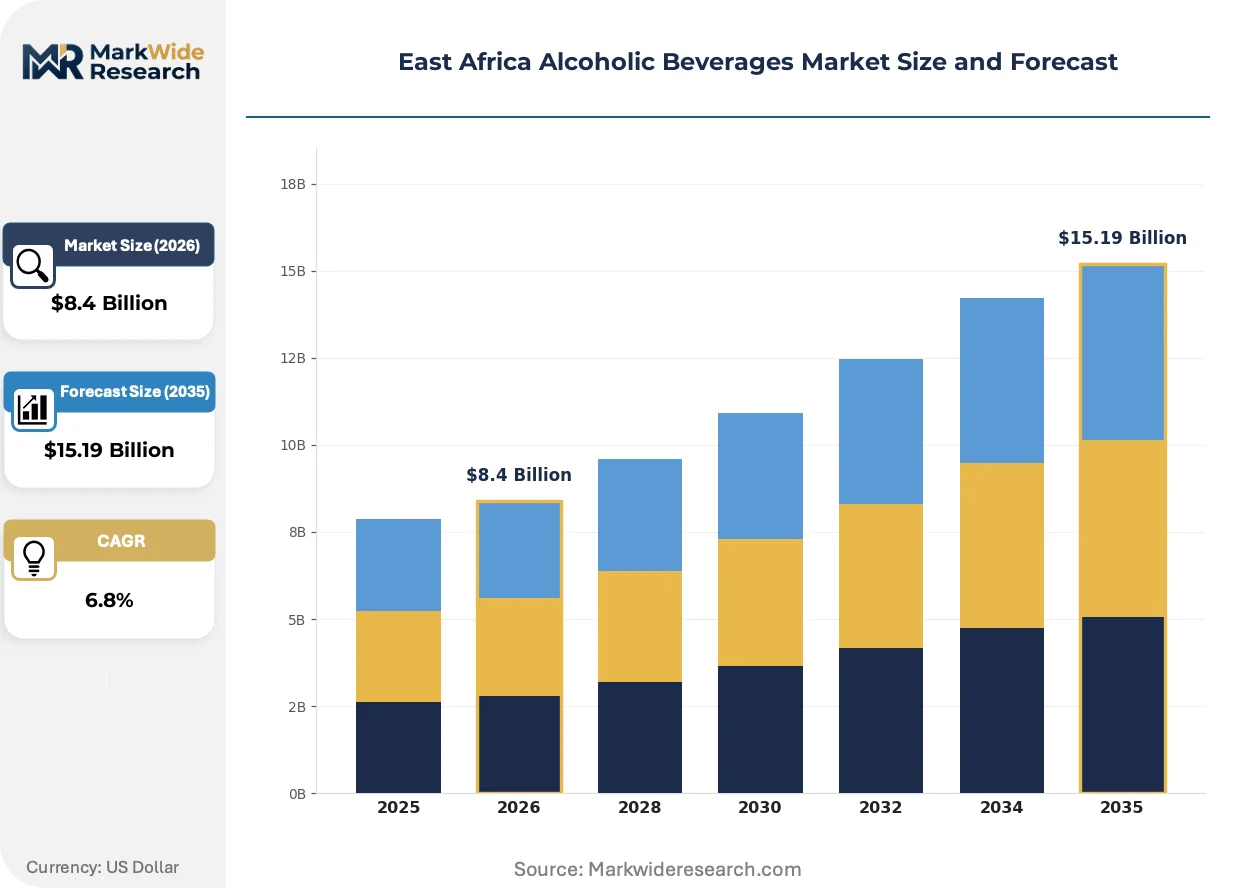
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Spirits, Wine, Cider Sales Channel: On-Premise, Off-Premise, E-commerce, Wholesale Customer Type: Retail Consumers, Restaurants, Pubs, Distributors Brand Positioning: Premium, Mid-Range, Budget, Craft |
| Companies Covered | Castel Group, Kenya Cane Distillers, East African Breweries Limited (EABL), Chrome Spirits, Serengeti Breweries, Asahi Group Holdings, Tolaram Group, Orijin Breweries, Diageo, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Alcoholic Beverages Market Strategic Shifts & Innovations
Digital traceability and localized sourcing protocols are redefining how East African brewers demonstrate compliance and provenance to regulators and urban consumers. These shifts intersect with evolving consumption rituals and channel preferences.
Paper-based excise stamps and manual batch tracking is migrating from legacy verification systems to serialized digital tax stamps with QR-code authentication. Kenya Revenue Authority and Tanzania Revenue Authority are mandating these upgrades for spirits and premium beer categories. The technology is compressing illicit trade volume while raising packaging cost structures for formal manufacturers.
Kenya's Alcoholic Drinks Control Act labeling requirements and Tanzania's 2023 excise tax framework are forcing reformulation and packaging redesign across mainstream portfolios. Manufacturers must reconcile alcohol content disclosures, health warnings, and origin markings with shelf aesthetics. Spirits importers face the steepest adaptation costs given multi-origin supply chains and premium positioning dependencies.
Experiential consumption rituals among Nairobi and Kampala professionals are displacing volume-centric occasions with occasion-specific portfolio choices. On-premise venues are unbundling food and beverage procurement to feature local craft alternatives alongside established brands. This behavioral pivot concentrates margin capture in urban clusters while rural wholesale channels stagnate.
East Africa Alcoholic Beverages Market Segmentation
East Africa's alcoholic beverages market fragments across consumption occasions, procurement channels, and price tiers that demand distinct route-to-market architectures. Manufacturers must calibrate portfolio depth, distributor incentives, and regulatory compliance to each segment's margin profile and volume velocity.
Product Type:
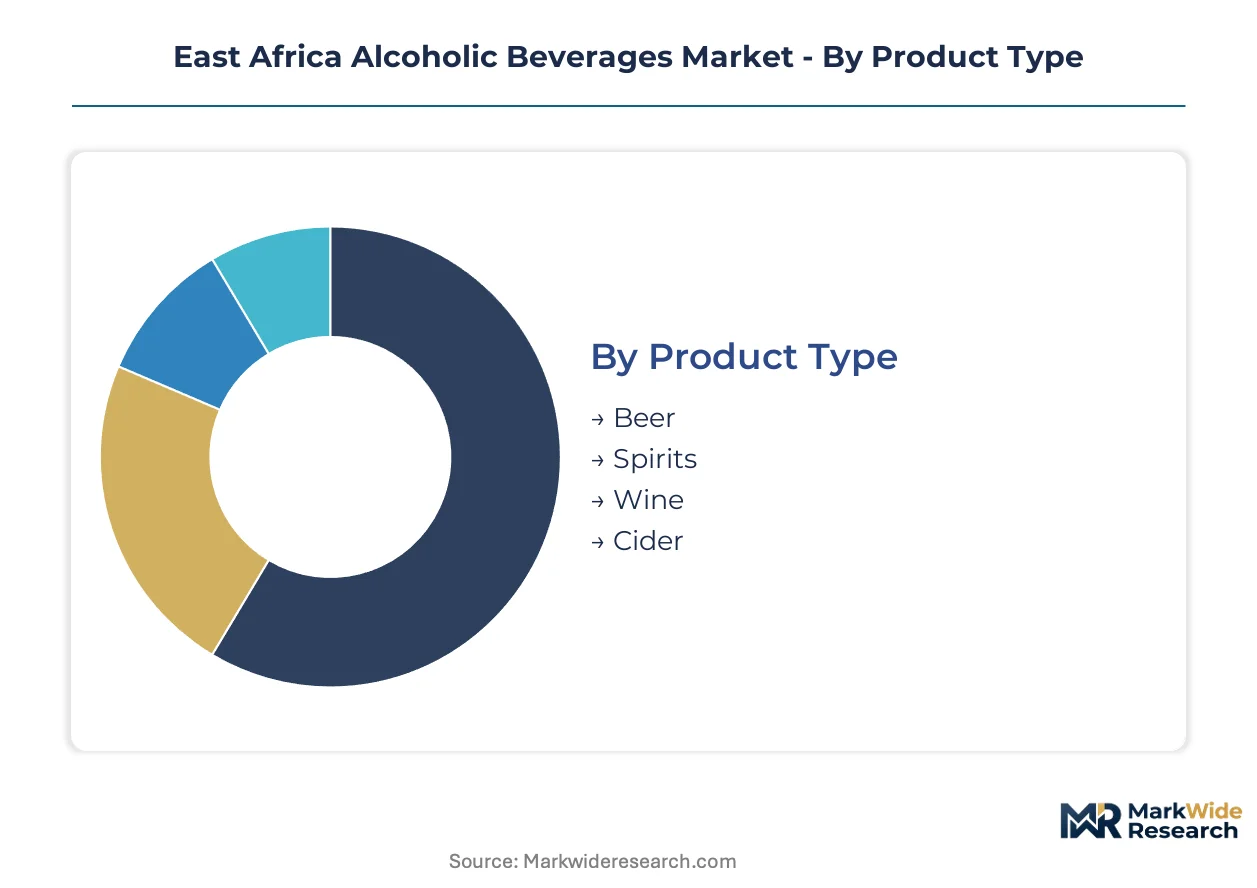
Consumption rituals span from daily refreshment to ceremonial celebration, with each product category commanding different raw material sourcing, production scale, and excise exposure.
- Beer:Fermented malt beverages at 4-6% ABV anchor regional volume through localized brewing infrastructure and barley-sorghum substitution protocols. Nairobi and Dar es Salaam's urban millennials concentrate demand in premium lager variants as EABL and Castel Group expand malt-based capacity.
- Spirits:Distilled products exceeding 40% ABV generate disproportionate margin concentration despite import dependency and steeper excise tiers. Kenya Revenue Authority's digital tax stamp mandates hit this category hardest, compressing grey-market volume while raising packaging compliance costs.
- Wine:Grape-based and fruit-fermented offerings serve ceremonial and hospitality end-uses with limited local production.
- Cider:Apple and pear-based alternatives attract experimental urban consumers but face raw material access constraints.
The dominant share belongs to Beer, while Spirits is closing the gap fastest through premium positioning and duty-free channel expansion.
Sales Channel:
Route-to-market economics diverge sharply between controlled retail licensing and informal wholesale networks, with capital requirements determining competitive access.
- On-Premise:Licensed bars, restaurants, and hotels in Kampala and Nairobi capture experiential consumption occasions with higher per-liter margins. Kenya's Alcoholic Drinks Control Act licensing requirements restrict venue density, concentrating volume in established hospitality clusters.
- Off-Premise:Supermarkets, convenience stores, and licensed liquor shops serve planned purchase occasions with standardized pricing. Modern trade expansion in Kigali and Addis Ababa is displacing fragmented traditional retail.
- E-commerce:Digital platforms and delivery apps are opening direct-to-consumer channels previously blocked by wholesale intermediaries.
- Wholesale:Distributor networks linking breweries to rural retail remain volume-heavy but margin-thin.
On-Premise commands the premium margin tier, though E-commerce is expanding most quickly as urban logistics infrastructure matures.
Customer Type:
Procurement scale and price sensitivity separate mass-market volume from value-capture opportunities across the consumption chain.
- Retail Consumers:Individual purchasers drive volume through off-premise and e-commerce channels with strong price elasticity in budget segments.
- Restaurants:Full-service dining venues in Nairobi and Dar es Salaam unbundle beverage procurement to feature premium and craft alternatives alongside established brands.
- Pubs:Licensed drinking establishments concentrate spirits attachment rates and occasion-specific portfolio choices among urban professionals.
- Distributors:Licensed wholesalers manage excise compliance and route-to-market economics for manufacturers entering underdeveloped territories.
Retail Consumers absorb the largest volume base, while Restaurants are gaining share fastest through experiential positioning.
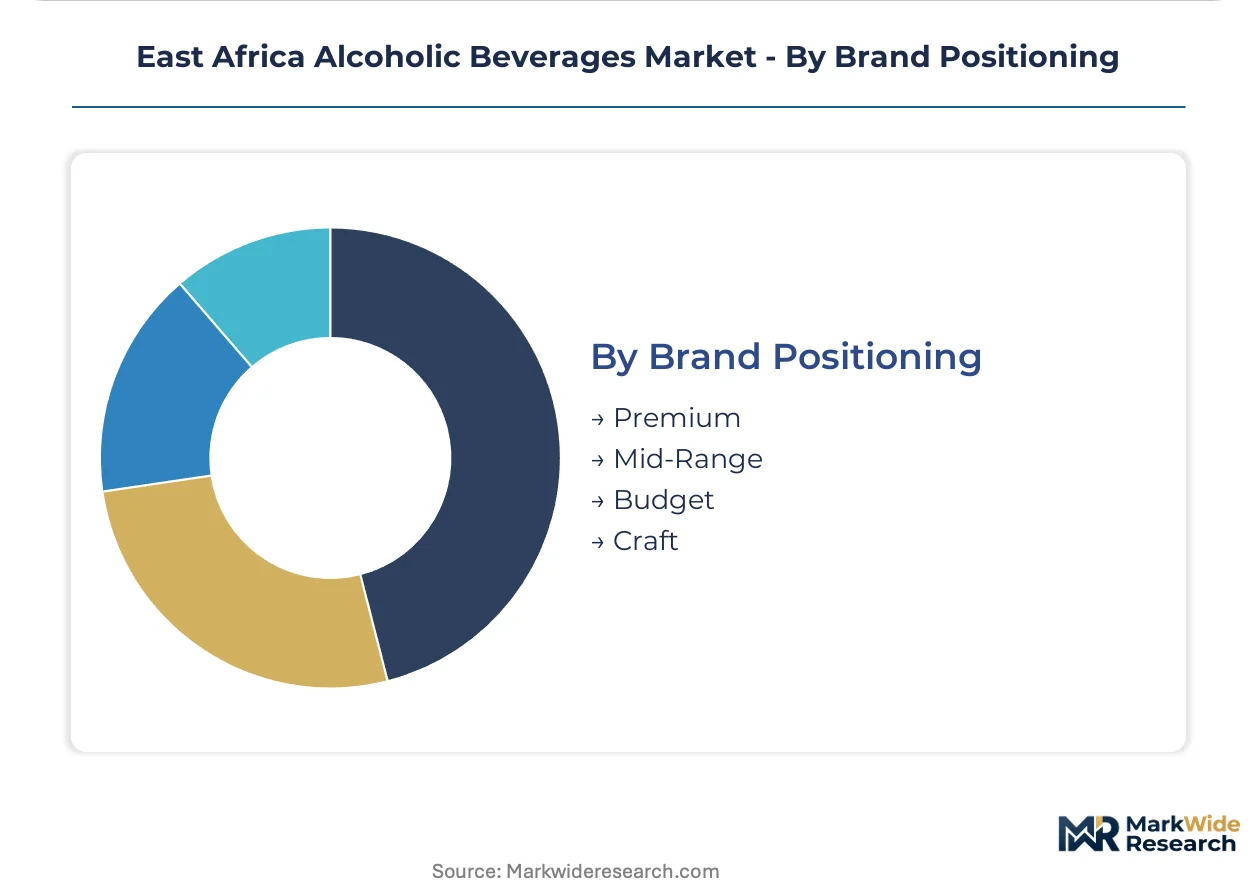
Brand Positioning:
Price tier stratification aligns with raw material quality, packaging investment, and distribution control intensity.
- Premium:Higher ABV variants, imported inputs, and sophisticated packaging target urban professionals in Nairobi's Westlands and Kampala's Kololo districts. Tanzania's 2023 excise adjustments compress margin predictability at this tier.
- Mid-Range:Locally brewed mainstream offerings balance affordability with consistent quality for daily consumption occasions.
- Budget:Economy-priced alternatives compete directly with informal alcohol channels in rural Uganda and Tanzania.
- Craft:Small-batch brewing and localized flavor innovation attract urban consumer trial despite barley access constraints and excise tiering disadvantages.
Mid-Range holds the volume center, yet Craft is climbing the fastest as Nairobi and Kampala professionals seek differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mombasa Port and Northern Corridor transport network underwrites Kenya's distribution dominance across the East African Community trade bloc.
Kenya
Nairobi's Westlands and Kilimani districts concentrate premium on-premise consumption among finance and tech professionals. Kenya Revenue Authority's digital tax stamp mandates compress illicit spirits volume while raising packaging compliance costs for formal manufacturers. Mombasa's port infrastructure enables EABL's regional export hub serving Uganda, Tanzania, and Rwanda.
Tanzania
Dar es Salaam's Kariakoo and Masaki neighborhoods anchor experiential drinking venue expansion. Tanzania Revenue Authority's 2023 excise tier adjustments reshape margin economics for imported spirits and premium beer categories. The Central Corridor rail link from Dar es Salaam to Dodoma shortens inland distribution lead times for malt-based portfolios.
Uganda
Kampala's Kololo and Nakasero districts drive spirits attachment rates among urban professionals and diplomatic communities. Uganda National Bureau of Standards quality certification timelines extend new product approval cycles for formal manufacturers. Jinja's brewery corridor hosts concentrated malting and fermentation capacity serving domestic and export markets.
Ethiopia
Addis Ababa's Bole and Kazanchis districts present underdeveloped formal distribution with first-mover positioning potential. Ethiopia's Food and Drug Administration adds compliance layers for cross-border portfolio expansion from neighboring markets. The Addis-Djibouti rail corridor offers landlocked market access to port infrastructure for imported spirits categories.
Rwanda
Kigali's Kimihurura and Nyarutarama districts attract premium positioning experiments before competitive saturation. Rwanda Standards Board enforcement differentiates compliant formal production from informal alcohol channels in rural areas. The Kigali Special Economic Zone offers tax incentives for manufacturing investment targeting regional export.
East Africa Alcoholic Beverages Market Key Industry Players
On the supply side, the industry is consolidating around capitalized brewers with regional brewing infrastructure and excise compliance capabilities. Multinational brewing groups and regional distillers compete across tiered price positioning. Three archetypes dominate: integrated brewing conglomerates with malt-based capacity, spirits specialists navigating import dependency, and emerging craft-positioned challengers. Capacity expansion and route-to-market reconfiguration from wholesale networks to controlled retail licensing represent the dominant competitive moves.
Within the integrated brewing tier, East African Breweries Limited and Castel Group exemplify capitalized regional infrastructure. Diageo occupies a position among import-dependent spirits specialists. Serengeti Breweries and Chrome Spirits represent mid-scale challengers navigating Tanzania's excise framework. Kenya Cane Distillers anchors domestic spirits production. Tolaram Group's diversified beverage portfolio spans multiple East African markets. Asahi Group Holdings and Orijin Breweries illustrate Asian-backed manufacturing investment targeting regional growth corridors.
| Leading Market Players |
|---|
| Castel Group |
| Kenya Cane Distillers |
| East African Breweries Limited (EABL) |
| Chrome Spirits |
| Serengeti Breweries |
| Asahi Group Holdings |
| Tolaram Group |
| Orijin Breweries |
| Diageo |
| Others |
Cost & Logistics Intelligence
Overcapacity in Tanzania's malting infrastructure is compressing supplier margins while simultaneously enabling aggressive pricing postures in Kenya's premium beer tier. Tanzania Revenue Authority's 2023 excise adjustments have forced brewers to absorb compliance costs upstream, reshaping how Castel Group and EABL calibrate volume-discount thresholds across the East African Community trade corridor.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between malt-based brewers and modern trade retailers in Nairobi and Dar es Salaam. Price differentiation hinges on excise compliance certification and geographic delivery cost to inland distribution hubs. Pricing pressure stems from Tanzania's excise tier compression, which squeezes margin predictability for premium imports. Budget-tier buyers in rural Uganda exhibit highest price sensitivity, while diplomatic and corporate hospitality segments in Kampala's Kololo district show lowest elasticity.
Supply Chain Analysis
Extended payment terms from Kenyan barley brokers to Ethiopian sorghum suppliers are straining working capital across the regional brewing value chain. Raw material sourcing draws from Ethiopia, Kenya, and Uganda for malt and adjunct grains, with packaging materials anchored in South African and Chinese manufacturing. Single-source vulnerability concentrates in Kenya's barley belt, where climate-induced harvest variability threatens input security. Distribution runs through Mombasa Port and Northern Corridor road networks to landlocked Rwanda and Uganda markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's alcoholic beverages sector is experiencing high-growth disruption as digital tax stamp mandates and excise harmonization discussions reshape compliance economics. Kenya Revenue Authority's serialization requirements represent the decisive regulatory inflection compressing grey-market volume and raising formal manufacturer barriers to entry.
For Market Incumbents: Build regulatory compliance moats through backward integration into malting capacity and captive supply of barley-sorghum inputs. EABL and Castel Group should deepen channel control by acquiring licensed distributor networks in Rwanda and Ethiopia before competitive saturation. Kenya's Alcoholic Drinks Control Act advertising restrictions pose the primary threat to brand-building reach, making on-premise venue ownership the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Kigali's underdeveloped formal distribution corridor, where first-mover positioning in premium craft beer remains achievable. Target Addis Ababa's Kazanchis and Bole districts for spirits import partnerships before Diageo consolidates duty-free channel dominance. Go-to-market execution should prioritize e-commerce platform partnerships in Nairobi and Dar es Salaam, bypassing wholesale intermediary fragmentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital traceability infrastructure and excise compliance technology. Long-term viability over the coming decade favors integrated brewing conglomerates with regional malting assets over import-dependent spirits specialists. Acquisition targets should display backward integration into grain sourcing and controlled retail licensing networks. The signal to monitor is excise harmonization progress within East African Community negotiations, which would reshape cross-border portfolio economics.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Tax Stamp Compliance | Kenya Revenue Authority mandates compress illicit trade while raising packaging cost structures for formal manufacturers. |
| Backward Integration into Malting | Captive barley-sorghum processing reduces import dependency and shortens supply lead times for mainstream beer. |
| Modern Trade Channel Expansion | Supermarket chains in Kigali and Addis Ababa displace fragmented wholesale networks with controlled retail licensing. |
| Craft Positioning Experimentation | Small-batch brewing attracts urban consumer trial in Nairobi's Westlands despite raw material access constraints. |
| Cross-Border Portfolio Optimization | East African Community excise harmonization discussions create regional manufacturing footprint advantages. |
Research Approach
Initial hypotheses were tested against primary input from brewery operations directors, excise compliance officers, modern trade category buyers, and licensed distributor principals and refined through secondary validation. Trade data from Kenya Revenue Authority and Tanzania Revenue Authority, East African Community customs records, Uganda National Bureau of Standards filings, and brewery capacity disclosures anchored quantitative estimates. Bottom-up volume modeling and top-down macroeconomic triangulation converged on segment-level projections.
Demand-supply-balance framing anchored the analytical architecture across the projection horizon. Segmentation dimensions modeled include product type, sales channel, customer type, brand positioning tier, and country-level regulatory cluster. CAGRs were derived from trend extrapolation moderated by structural constraint analysis. Forecast inputs incorporated excise rate trajectory assumptions and urbanization-driven on-premise consumption elasticity.
Stress conditions across excise tier adjustments, barley harvest variability, and digital traceability implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and infrastructure investment continuity. Macroeconomic volatility, regulatory reversal, or technological disruption in authentication systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Woozy Bottle Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market