
 Premium Wine Cooler Market | 2026-2036
Premium Wine Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Wine Cooler Market Analytics
Buyer concentration among hospitality groups and luxury residential developers is recalibrating procurement volumes toward built-in and large-capacity configurations. Electrolux AB leverages its European manufacturing footprint to sustain premium positioning across commercial installations. Haier Group Corporation anchors its competitive stance through integrated supply chains spanning compressor production to finished goods assembly.
A premium wine cooler is a climate-controlled refrigeration appliance engineered to maintain precise temperature ranges between 45°F and 65°F, with humidity regulation between 50% and 80% RH to preserve wine integrity during storage and aging. The unit employs either compressor-based vapor compression cycles or thermoelectric Peltier systems to achieve thermal stability without vibration transfer that could disturb sediment. Built-in units command the highest margin pools due to custom cabinetry integration requirements and longer replacement cycles. Compressor cooling technology dominates commercial installations for its temperature precision, while thermoelectric systems occupy compact countertop segments where noise suppression and energy efficiency outweigh cooling speed demands.
The U.S. Department of Energy's appliance efficiency standards and California's Title 24 building codes constrain compressor energy consumption thresholds, compelling manufacturers to redesign refrigeration circuits and insulation packages. ENERGY STAR certification administered by the EPA functions as a gatekeeping mechanism for retail channel access, with uncertified units facing delisting from major distributor catalogs. Stakeholders must monitor evolving state-level electrification mandates and refrigerant phase-down schedules under the EPA's AIM Act to anticipate retooling requirements and inventory obsolescence risks.
Market Dynamics
Compressor miniaturization and variable-speed drive integration are compressing unit footprints while tightening temperature precision tolerances, forcing incumbent manufacturers to retool assembly lines around sub-100-liter built-in formats favored by luxury residential developers.
Growth Catalysts
- California Title 24 electrification mandates:Building code amendments requiring high-efficiency appliance specifications in new luxury construction are accelerating specification of dual-zone compressor units by high-end residential developers in Los Angeles and San Francisco metropolitan clusters.
- Hospitality amenity arms race:Boutique hotel operators in Napa Valley and Sonoma County are mandating in-room wine storage as a standard room feature, expanding procurement volumes for under-counter built-in configurations with custom panel-ready exteriors.
- Humidity control sensor miniaturization:Solid-state capacitive sensors are enabling real-time RH monitoring at price points viable for residential units, broadening addressable market beyond commercial installations.
Market Restraints
- Copper and aluminum price volatility:Refrigeration coil and heat exchanger input costs fluctuate with London Metal Exchange pricing, compressing gross margins on compressor-based units during commodity spikes.
- Thermoelectric performance ceiling:Peltier systems face fundamental thermodynamic limits below 50°F ambient, restricting deployment in unconditioned garage installations across Sun Belt states.
- EPA refrigerant phase-down schedules:AIM Act hydrofluorocarbon reduction timelines are forcing premature obsolescence of R-134a dependent compressor architectures before full depreciation cycles.
Strategic Opportunities
- Texas secondary market penetration:Austin and Dallas-Fort Worth luxury home construction permits are outpacing national averages, creating white space for built-in unit specification before incumbent relationships solidify.
- Direct-to-developer channel development:Bypassing traditional appliance distributor markups through project-specific procurement portals captures margin currently allocated to regional wholesaler networks.
- IoT-enabled predictive maintenance bundles:Compressor vibration signature monitoring combined with subscription service contracts generates recurring revenue streams from commercial hospitality installations.
Industry Challenges
- Refrigeration technician specialization gap:Variable-speed compressor diagnostics and sealed system repair require skills scarce in standard appliance service networks, extending warranty resolution timelines.
- ENERGY STAR certification backlog:EPA testing facility capacity constraints delay new product launches by six to nine months, compressing competitive response windows to rival feature introductions.
- Custom cabinetry integration complexity:Built-in unit dimensional tolerances and ventilation clearances conflict with millwork shop drawing standards, generating field coordination failures and installation rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Wine Cooler Market |
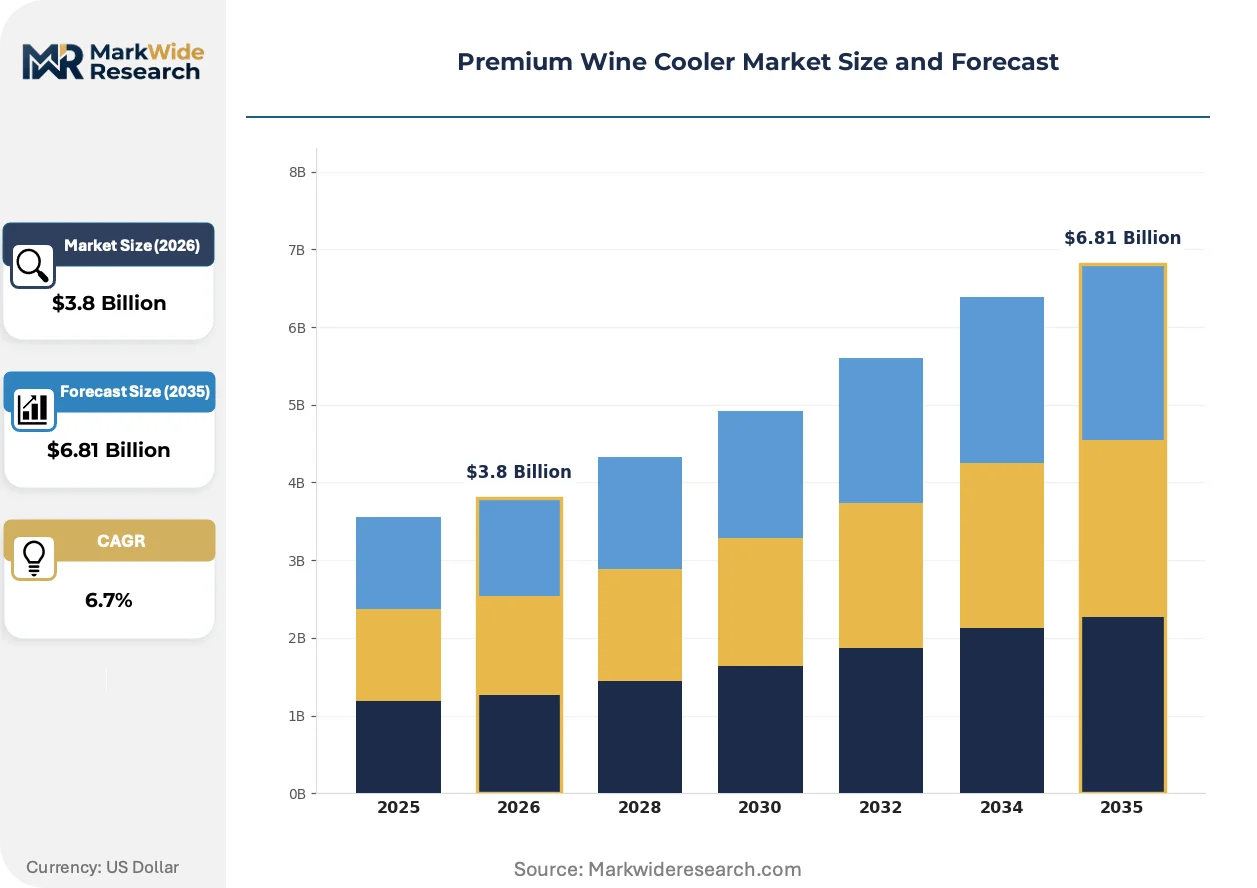
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-In, Countertop, Dual-Zone Cooling Technology: Compressor, Thermoelectric, Absorption, Hybrid End User: Residential, Commercial, Hospitality, Retail Capacity: Small (up to 20 bottles), Medium (21-50 bottles), Large (51-100 bottles), X-Large (over 100 bottles) |
| Companies Covered | Allavino Company, Avanti Products Inc, Electrolux AB, EuroCave SAS, Haier Group Corporation, LG Electronics Inc, Liebherr, Whynter LLC, Dunavox Kft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Wine Cooler Market Evolving Landscape
Refrigeration architecture is fragmenting across three vectors: compressor topology evolution, regulatory energy accounting, and procurement channel restructuring. These shifts are compressing traditional product lifecycles while opening asymmetric advantage for agile component suppliers.
Variable-speed inverter compressors are decentralizing thermal management authority from centralized mechanical systems to zone-specific modules. Luxury residential developers in Florida are specifying these units for dedicated wine walls in primary entertaining spaces, enabling independent climate zones without whole-home HVAC recalibration. This topology is decentralizing the traditional single-compressor household refrigeration paradigm into distributed appliance networks.
ENERGY STAR Most Efficient criteria revisions by the EPA are disqualifying fixed-speed compressor platforms from retail channel placement. Manufacturers must redesign refrigeration circuits around brushless DC motor architectures and vacuum-insulated panels to maintain distributor catalog presence. The built-in segment faces the steepest compliance cost escalation due to constrained exterior surface area available for insulation augmentation.
Builder-direct specification contracts are displacing retail showroom selection for new luxury construction. High-end residential developers in California and Texas are consolidating appliance procurement through national account frameworks, compressing regional distributor influence. This concentration is most visible in master-planned communities where single-source specifications lock out competing brands for multi-year development phases.
Premium Wine Cooler Market Segmentation
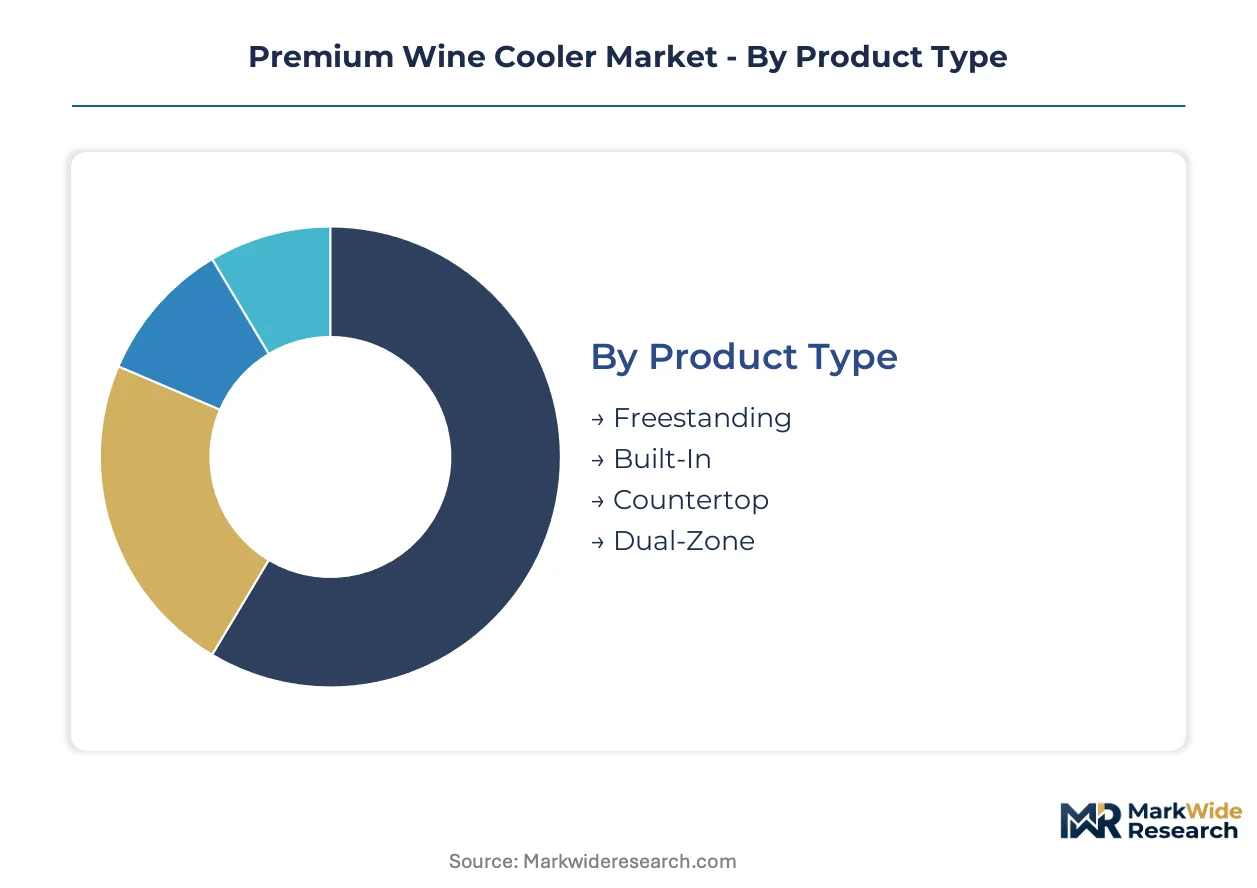
Premium wine cooler segmentation reveals distinct upgrade pathways between replacement-driven residential purchases and specification-driven commercial installations. Cooling technology and capacity choices diverge sharply across these buyer types, creating parallel product hierarchies with minimal overlap.
Product Type:
Replacement cycles vary dramatically by installation format, with built-in units commanding extended depreciation schedules and freestanding models turning over faster as design preferences shift.
- Built-In:These units integrate directly into kitchen cabinetry or wet bars with front-venting architectures that eliminate side clearance requirements. California luxury residential developers in Los Angeles and San Francisco metropolitan clusters specify these for custom wine walls, driven by Title 24 electrification mandates requiring high-efficiency appliance integration.
- Freestanding:Self-contained ventilation systems allow placement flexibility without millwork modification. Demand concentrates in Texas secondary markets where Austin and Dallas-Fort Worth luxury home construction permits outpace national averages, creating specification white space before incumbent relationships solidify.
- Countertop:Compact thermoelectric units serve space-constrained urban apartments with sub-20-bottle capacities.
- Dual-Zone:Independent climate chambers enable simultaneous red and white wine storage at distinct setpoints.
Built-In sits at the top of the volume ranking, with Dual-Zone climbing the fastest.
Cooling Technology:
Cost tiers separate precision-grade compressor systems from entry-level thermoelectric alternatives, with absorption and hybrid architectures occupying narrow specialty niches.
- Compressor:Vapor compression cycles utilizing variable-speed inverter motors deliver temperature precision within ±1°F across ambient conditions from 50°F to 95°F. EPA ENERGY STAR Most Efficient criteria revisions are disqualifying fixed-speed platforms, forcing redesigns around brushless DC architectures and vacuum-insulated panels.
- Thermoelectric:Peltier solid-state cooling eliminates compressor vibration and noise through semiconductor heat pumping. Performance ceilings below 50°F ambient restrict deployment in unconditioned garage installations across Sun Belt states, constraining addressable geography.
- Absorption:Ammonia-based silent operation suits yacht and RV applications where electrical load constraints predominate.
- Hybrid:Combined compressor-thermoelectric architectures optimize efficiency across variable load conditions.
Compressor dominates installed value, though thermoelectric maintains volume leadership in sub-$500 price bands.
End User:
Application requirements fragment procurement specifications, with hospitality installations demanding commercial-grade durability and residential buyers prioritizing aesthetic integration.
- Hospitality:Boutique hotel operators in Napa Valley and Sonoma County mandate in-room wine storage as standard room features. Under-counter built-in configurations with custom panel-ready exteriors expand procurement volumes, with IoT-enabled predictive maintenance bundles generating recurring revenue from vibration signature monitoring contracts.
- Residential:Individual collectors drive replacement demand through kitchen renovation cycles, with builder-direct specification contracts displacing retail showroom selection in new luxury construction.
- Commercial:Restaurant and bar installations emphasize rapid temperature recovery under frequent door-opening loads.
- Retail:Display cases for wine merchants require glass-door visibility with UV-filtering coatings.
Hospitality generates the steepest expansion trajectory, while Residential anchors absolute unit volumes.
Capacity:
Customer type stratification produces distinct volume bands, with serious collectors and commercial operators separating from casual enthusiasts at the 50-bottle threshold.
- Large (51-100 bottles):Dedicated climate-controlled rooms in primary entertaining spaces require distributed thermal management without whole-home HVAC recalibration. Florida luxury residential developers specify these for wine walls, enabling independent zones through zone-specific compressor modules.
- Medium (21-50 bottles):Standard under-counter dimensions align with residential kitchen renovation cycles and replacement timelines.
- Small (up to 20 bottles):Countertop and compact freestanding formats serve apartment dwellers and novice collectors.
- X-Large (over 100 bottles):Walk-in cellar alternatives for institutional collections and high-volume hospitality operations.
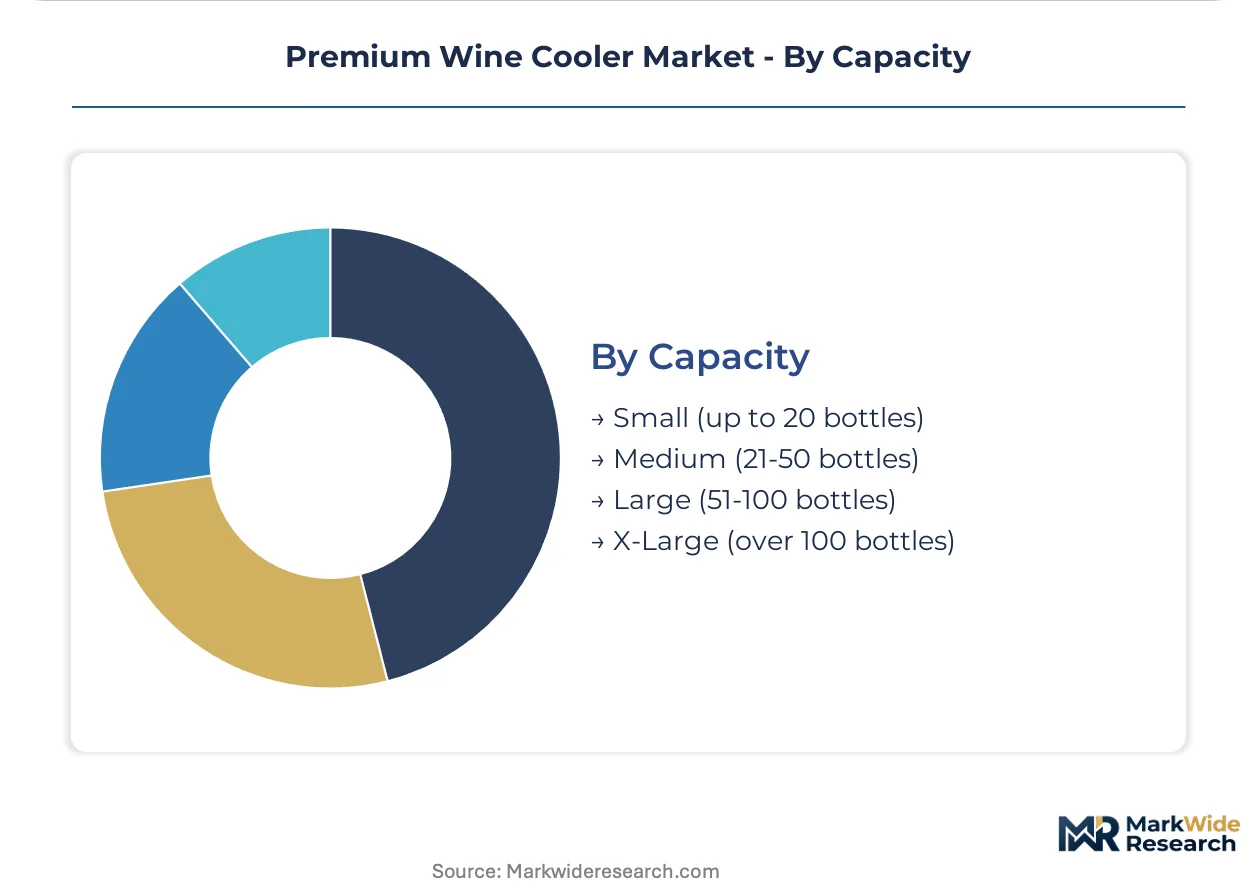
Large capacity commands the highest margin pools, with X-Large gaining share fastest among custom residential specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for built-in wine storage outpaces German procurement volumes by a factor of three, while Chinese manufacturers now supply compressor modules to both markets through distinct distribution channels.
United States
California luxury residential developers in Los Angeles and San Francisco metropolitan clusters specify dual-zone compressor units for custom wine walls. EPA ENERGY STAR Most Efficient criteria revisions disqualify fixed-speed platforms from retail channel placement. Florida developers deploy distributed thermal management systems for dedicated climate zones in primary entertaining spaces.
Germany
Precision engineering standards from VDE and TÜV certification bodies elevate quality thresholds for compressor variable-speed drive integration. EU F-Gas Regulation phase-down schedules accelerate refrigerant transition timelines beyond EPA-mandated schedules. Bavarian appliance manufacturers anchor European supply chains for brushless DC motor architectures.
China
Integrated supply chains spanning compressor production to finished goods assembly compress manufacturing cost structures for export markets. GB standards for appliance energy efficiency constrain domestic market product configurations. Zhejiang and Guangdong province manufacturing clusters supply thermoelectric modules and vacuum-insulated panel subassemblies.
France
Boutique hospitality operators in Bordeaux and Champagne regions mandate in-room wine storage as standard amenities. REACH chemical safety protocols govern insulation material specifications for EU-bound production. Auvergne-Rhône-Alpes industrial corridor hosts specialized refrigeration component fabrication.
Australia
Thermoelectric performance limitations below 50°F ambient constrain deployment in unconditioned rural installations across Queensland and Western Australia. Energy Rating Label compliance requirements from the Australian government shape product efficiency minimums. New South Wales and Victoria metropolitan construction activity drives built-in specification demand.
Premium Wine Cooler Market Competitive Landscape
European producers anchor one tier through precision manufacturing heritage; Asian specialists hold cost-optimized scale positions. The vendor base separates into three strategic archetypes: integrated appliance conglomerates with captive compressor supply, specialized climate-control equipment fabricators, and contract manufacturers serving private-label retail programs. Competitive moves concentrate on vertical integration into refrigeration component supply and direct-to-developer channel development bypassing traditional distributor markups.
Within the integrated conglomerate tier, Electrolux AB and Haier Group Corporation exemplify divergent geographic anchoring strategies. EuroCave SAS occupies a position among specialized climate-control fabricators emphasizing custom panel-ready configurations. Liebherr represents European precision-engineering positioning across commercial hospitality specifications. These archetypes illustrate how manufacturing footprint and channel access separate sustainable margin pools from commodity-exposed segments.
| Leading Market Players |
|---|
| Allavino Company |
| Avanti Products Inc |
| Electrolux AB |
| EuroCave SAS |
| Haier Group Corporation |
| LG Electronics Inc |
| Liebherr |
| Whynter LLC |
| Dunavox Kft |
| Others |
Value Network & Pricing Analysis
Copper and aluminum coil pricing volatility originating from London Metal Exchange trading floors propagates through refrigeration heat exchanger fabrication costs, compressing gross margins on compressor-based units and forcing tiered pricing stratification across premium built-in, standard freestanding, and economy countertop configurations.
Pricing Analysis
Capacity additions in China's Zhejiang and Guangdong manufacturing clusters are reshaping price floors for thermoelectric modules and vacuum-insulated panel subassemblies. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR Most Efficient certified units from fixed-speed legacy platforms facing retail delisting. Pricing pressure stems from EPA refrigerant phase-down schedules forcing premature R-134a architecture obsolescence. Residential developers in Texas and Florida exhibit lowest price sensitivity due to specification lock-in through national account frameworks, while countertop segment buyers show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese integrated manufacturing clusters controlling compressor production through finished goods assembly. Geographic supply concentration centers on China for thermoelectric modules and vacuum-insulated panels, Germany for brushless DC motor architectures, and the United States for final assembly of built-in configurations. Raw material dependencies draw from copper refrigeration coils, aluminum heat exchangers, and semiconductor-based Peltier elements. Tariff exposure on Chinese-origin components presents structural risk amid evolving trade policy. Distribution runs through national account frameworks serving luxury residential developers, bypassing traditional regional appliance distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA ENERGY STAR Most Efficient criteria revisions and AIM Act hydrofluorocarbon phase-down schedules continuously reset competitive entry barriers and demand specifications.
For Market Incumbents: Hedge refrigerant transition risk by accelerating R-600a and R-290 compressor architecture certification before EPA testing facility backlogs extend launch delays. Secure captive supply of variable-speed inverter motors through backward integration into brushless DC motor production or exclusive offtake agreements with Bavarian component suppliers. Channel control through direct-to-developer procurement portals defends margin position against distributor markup compression.
For New Entrants and Emerging Players: California Title 24 electrification mandates in Los Angeles and San Francisco metropolitan clusters open a window for specification of dual-zone compressor units in custom wine wall installations before incumbent relationships solidify. Texas secondary markets in Austin and Dallas-Fort Worth present white-space penetration opportunity given permit growth outpacing national averages. IoT-enabled predictive maintenance bundles for hospitality installations offer differentiated go-to-market positioning through recurring revenue contracts.
For Investors and Strategic Acquirers: Consolidation pressure builds where ENERGY STAR certification backlogs and retooling capital requirements strain sub-scale manufacturers lacking captive compressor supply. Long-term viability favors integrated appliance conglomerates with in-house refrigeration component production and established national account relationships with luxury residential developers. Acquisition target archetype: specialized climate-control fabricators with custom panel-ready capabilities and hospitality sector penetration. Signal to watch: EPA refrigerant phase-down enforcement acceleration triggering distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Developer Channel Development | Bypasses regional distributor markups to capture margin currently allocated to wholesaler networks in California and Texas. |
| Variable-Speed Inverter Compressor Integration | Meets ENERGY STAR Most Efficient criteria while enabling distributed thermal management for Florida wine wall specifications. |
| IoT-Enabled Predictive Maintenance Bundles | Generates recurring revenue streams from vibration signature monitoring contracts with Napa Valley boutique hotel operators. |
| Refrigerant Architecture Transition | Addresses EPA AIM Act hydrofluorocarbon reduction timelines before R-134a dependent inventory faces obsolescence. |
| Vacuum-Insulated Panel Adoption | Enables compliance with constrained surface area requirements in built-in segment insulation augmentation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with luxury residential developers, hospitality procurement officers, refrigeration component suppliers, appliance distributor network managers, and EPA regulatory affairs specialists. Secondary validation drew from ENERGY STAR certification databases, DOE appliance efficiency standard filings, U.S. Census Bureau construction permit data, London Metal Exchange pricing records, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up unit shipment modeling and top-down construction spend allocation were cross-referenced for triangulation.
Historical reference periods anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled included cooling technology topology, installation format, capacity tier, end-use application, and regional construction cluster. CAGRs were derived from regression analysis against housing permit trajectories, wine consumption indices, and regulatory compliance cost curves. Industry-specific forecast inputs incorporated ENERGY STAR criteria revision timelines and refrigerant phase-down enforcement probability.
Revisions become necessary when EPA testing facility capacity constraints extend beyond current backlog estimates, copper and aluminum commodity price spikes exceed historical volatility bands, or state-level electrification mandates accelerate beyond California Title 24 adoption patterns. Forecasts reflect documented assumptions about regulatory enforcement intensity, construction cycle duration, and hospitality capital expenditure recovery. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Grain Neutral Spirits Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Middle East and Africa Wine Market