
 Global Bourbon Market | 2026-2036
Global Bourbon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bourbon Market Analysis
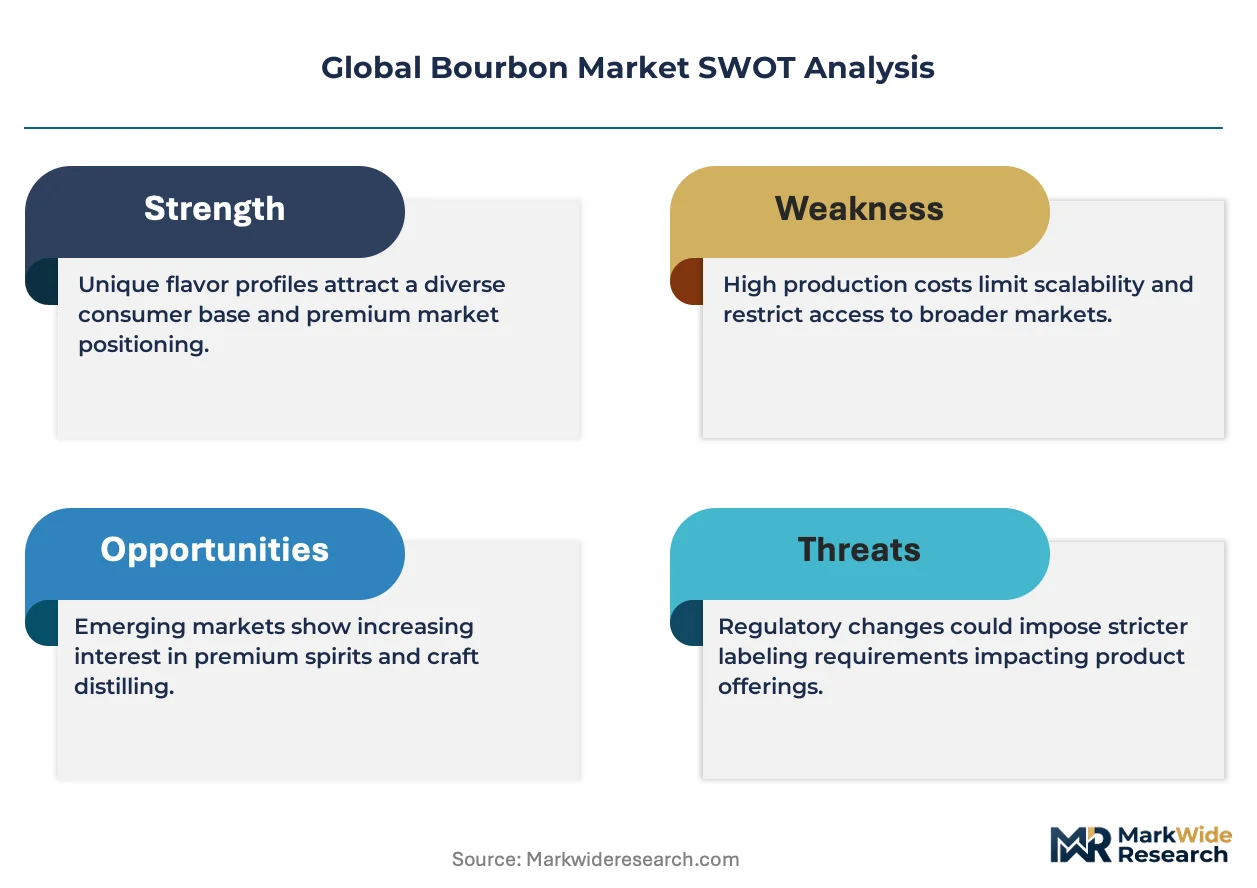
Single-barrel and cask-strength bundling is hardening as the dominant configuration pattern for premium bourbon buyers. Beam Suntory leverages its Japanese parent company's distribution muscle to anchor shelf position across Asia-Pacific duty-free channels. Brown-Forman differentiates through sustained investment in wood innovation and proprietary cooperage operations. Heaven Hill Brands competes on value-tier scale while maintaining age-stated reserves that occupy a unique price-position in the category.
Bourbon is an American whiskey distilled from a grain mixture containing at least 51 percent corn, aged in new charred oak containers, and bottled at no less than 80 proof; the TTB mandates these compositional thresholds to preserve product integrity and geographic authenticity. Straight Bourbon commands the largest volume share due to regulatory clarity and consumer recognition, while Small Batch Bourbon captures disproportionate margin as distillers emphasize craft credentials and limited releases. Specialty Stores channel growth outpaces Supermarkets for allocated expressions, though Liquor Stores retain dominance in high-frequency, standard-proof purchases.
The U.S. TTB enforces mash bill minimums and new-charred-oak mandates that shape every producer's raw material procurement and cooperage relationships. FDA labeling rules and state-level three-tier distribution laws further constrain how bourbon reaches retail shelves across American jurisdictions. Stakeholders must monitor TTB rulemaking on additive disclosures and evolving state direct-to-ship statutes that could reroute traditional wholesale pathways.
Market Dynamics
Single-barrel allocation scarcity and TTB-mandated aging floors are compressing inventory velocity, forcing producers to front-load cooperage commitments years ahead of projected bottling runs.
Growth Catalysts
- TTB Mash Bill Enforcement:The U.S. Alcohol and Tobacco Tax and Trade Bureau's strict 51% corn minimum and new-charred-oak mandates preserve authenticity barriers that insulate American producers from foreign whiskey substitution.
- Premium Cocktail Venues:Upscale hospitality establishments in London, Singapore, and Sydney are anchoring bourbon placement in high-visibility back bars, normalizing cask-strength pours among affluent international consumers.
- Kentucky-Tennessee Cluster Density:Concentrated distillery operations across these states generate shared logistics infrastructure and skilled cooperage labor pools that lower per-unit maturation costs.
Market Restraints
- New Oak Barrel Scarcity:White oak supply constraints in Appalachian forests are elevating cooperage input costs and extending procurement lead times for new-charred containers.
- Three-Tier Distribution Lock-in:State-level alcohol beverage control laws in 17 U.S. jurisdictions mandate wholesaler intermediation, preventing direct-to-retail margin capture.
- Japanese Whisky Substitution:Yamazaki and Hakushu age-stated releases are displacing bourbon in Asian duty-free allocations among collectors seeking alternative allocated spirits.
Strategic Opportunities
- Indian Duty-Free Expansion:Delhi and Mumbai international terminals lack premium bourbon penetration relative to Scotch, creating shelf-space white space for age-stated expressions.
- Direct-to-Ship Statutes:Kentucky and Tennessee legislative reforms enabling cross-state consumer shipping bypass traditional wholesaler markups in permitted jurisdictions.
- Warehouse Management Systems:RFID-enabled barrel tracking is converging with climate-controlled rickhouse design, allowing producers to monetize location-specific flavor profiles.
Industry Challenges
- Master Distiller Talent Pipeline:Retirement waves among 1980s-era distillery veterans are outpacing formal apprenticeship programs certified by the Kentucky Distillers' Association.
- Char Level Standardization:Absence of ISO-recognized char depth metrics complicates quality consistency across cooperage suppliers in Missouri and Arkansas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bourbon Market |
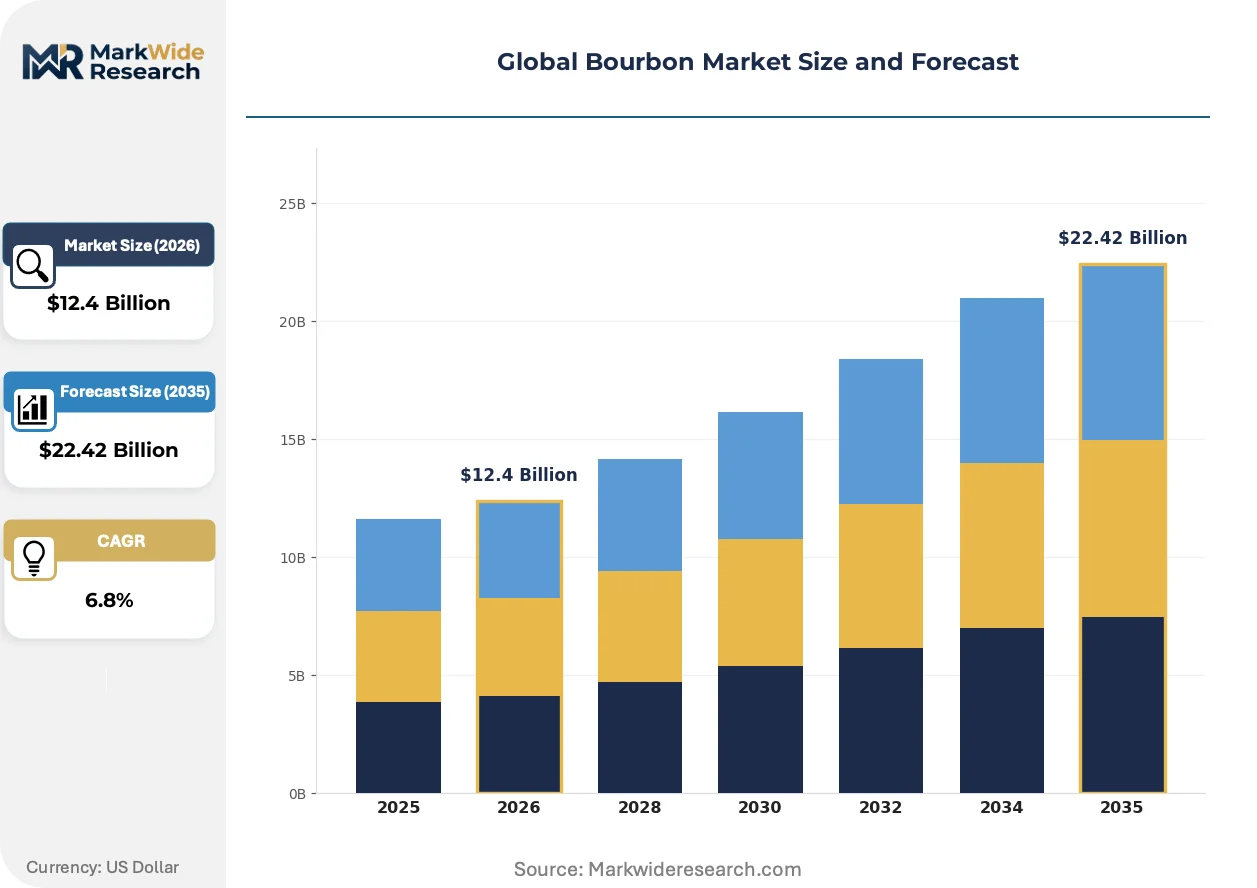
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Bourbon, Blended Bourbon, Flavored Bourbon, Small Batch Bourbon Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Liquor Stores Consumer Age Group: 21-30 Years, 31-40 Years, 41-50 Years, 51+ Years Packaging Type: Glass Bottles, Cans, Tetra Packs, Kegs |
| Companies Covered | Beam Suntory, Brown-Forman, Sazerac Company, Campari Group, Heaven Hill Brands, Diageo, Kirin Holdings Company, Barton Brands, MGP (Midwest Grain Products), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bourbon Market Emerging Trajectories
Maturation science and digital traceability are redefining how producers justify price premiums, shifting competitive advantage from heritage narrative to verifiable production parameters.
Infrared spectroscopy for real-time ethanol-vanillin mapping is converging with climate-controlled rickhouse zoning, enabling distillers to isolate high-ester barrel locations for single-barrel selection. Premium buyers in Tokyo and Seoul are demanding spectroscopic proof-of-age documentation, compressing the market for non-verified age claims. This technology is converging with blockchain lot-tracking to create immutable provenance records that command shelf price premiums.
The EU's proposed Spirits Drinks Regulation revision is tightening geographic indication enforcement for whiskey-category labeling, threatening "Tennessee-style" and "Kentucky-style" descriptor usage on European shelves. American exporters must reformulate label architectures or absorb certification costs for protected designation compliance. Small-batch producers without dedicated EU regulatory affairs staff are most exposed to entry refusal risk at Rotterdam and Hamburg ports.
Collector-driven secondary market trading through specialized auction platforms is fragmenting traditional retail allocation power, with rare bottle resale in London and Hong Kong now influencing primary release pricing. Specialty retailers in New York and San Francisco are responding with loyalty-program tiering that mimics auction access patterns. This behavioral shift is most visible among Generation X and Millennial buyers in coastal U.S. metropolitan markets, where bottle flipping has normalized as portfolio diversification behavior.
Global Bourbon Market Segmentation
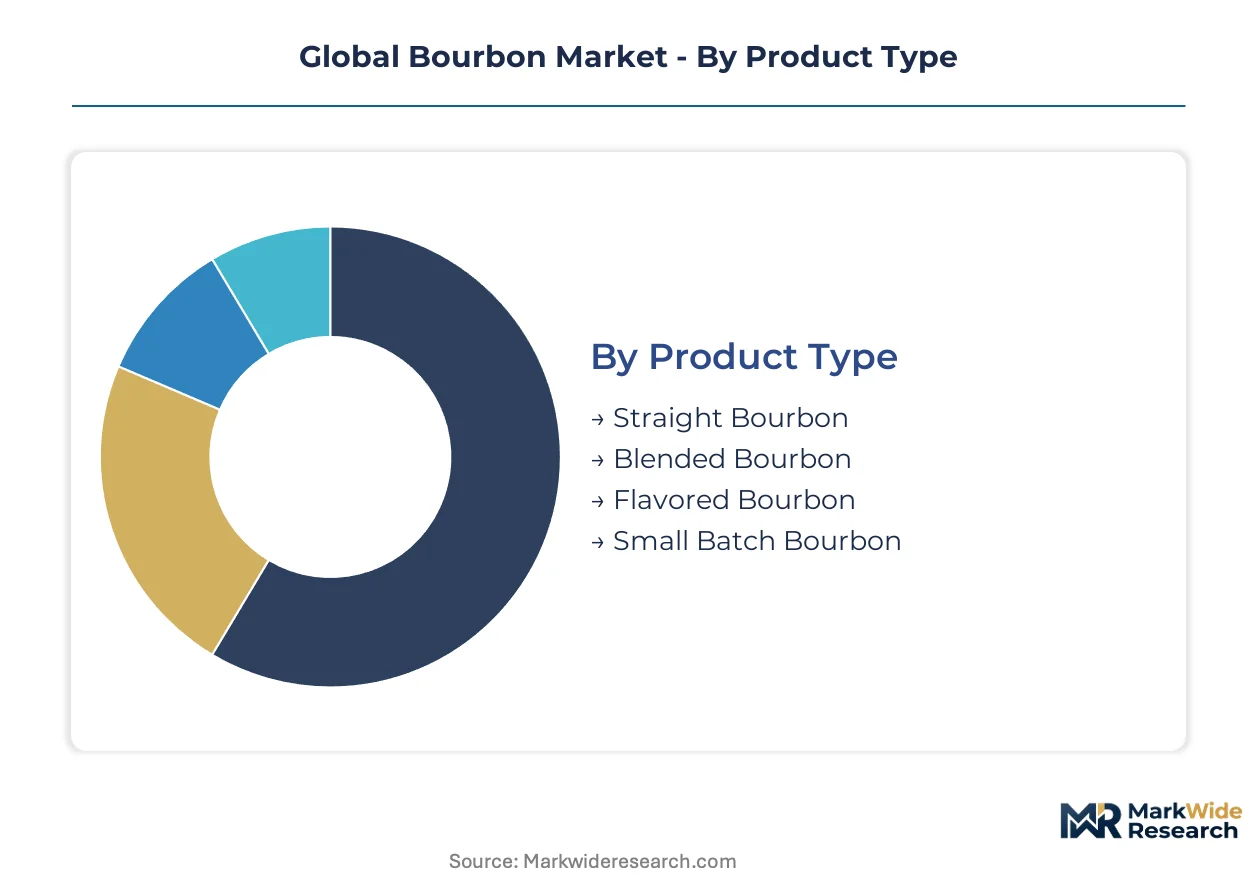
Bourbon's regulatory framework and aging economics create distinct buyer segments with divergent margin profiles. Producers must align cooperage investment and distribution strategy to the specific decision criteria governing each category.
Product Type:
Purchase decisions here turn on age verification and mash bill transparency, with TTB compliance serving as the baseline qualifier for shelf placement.
- Straight Bourbon:Aged minimum two years in new charred oak with no additives, meeting the TTB's strictest compositional standard. Volume concentrates in standard-proof retail channels across Kentucky and Tennessee distillery gift shops, constrained by extended aging cycles that tie up working capital.
- Small Batch Bourbon:Blended from select barrels (typically 150 or fewer) to achieve consistent flavor profiles, commanding price premiums through scarcity signaling. Demand clusters in Tokyo, London, and Singapore hospitality venues where bartenders use cask-strength expressions as menu differentiators.
- Blended Bourbon:Combines straight bourbon with neutral spirits or flavorings, offering accessible entry price points.
- Flavored Bourbon:Infused with honey, cinnamon, or fruit essences, targeting younger demographic trial.
Volume sits with Straight Bourbon; growth tilts toward Small Batch Bourbon.
Distribution Channel:
Channel selection determines margin capture versus reach, with three-tier laws in 17 U.S. states forcing wholesale intermediation that erodes producer economics.
- Liquor Stores:State-licensed retailers dominate high-frequency, standard-proof purchases through established relationships with local distributor networks. Revenue concentrates in Texas, Florida, and California independent operators, though shelf fees and slotting allowances compress net margins for mid-tier brands.
- Specialty Stores:Curated retailers focusing on allocated expressions and single-barrel selections, building loyalty through allocation list access. Growth accelerates in New York, San Francisco, and Chicago markets where collector communities drive secondary market price discovery.
- Supermarkets:Grocery chains with beer/wine licenses in permissive states, prioritizing volume velocity over margin.
- Online Retail:Direct-to-consumer platforms enabled by evolving state shipping statutes, bypassing traditional wholesale markups where permitted.
Transaction frequency clusters at Liquor Stores; margin expansion favors Specialty Stores.
Consumer Age Group:
Life-stage positioning dictates packaging format, proof preference, and occasion-based marketing spend allocation.
- 31-40 Years:Millennials with established careers driving premiumization, seeking age-stated expressions for home bar investment and social signaling. Concentration in coastal U.S. metropolitan markets and Seoul, where bourbon collecting has normalized as alternative asset allocation.
- 21-30 Years:Gen Z entrants exploring flavored variants and ready-to-drink formats through on-premise discovery.
- 41-50 Years:Established collectors with cellar depth, prioritizing provenance and distillery heritage narratives.
- 51+ Years:Loyalty-driven traditionalists maintaining brand relationships formed decades prior, less susceptible to innovation messaging.
Volume leadership belongs to 41-50 Years; steepest expansion trajectory emerges in 31-40 Years.
Packaging Type:
Format economics shape logistics cost structures and occasion-based consumption patterns across on-premise versus off-premise channels.
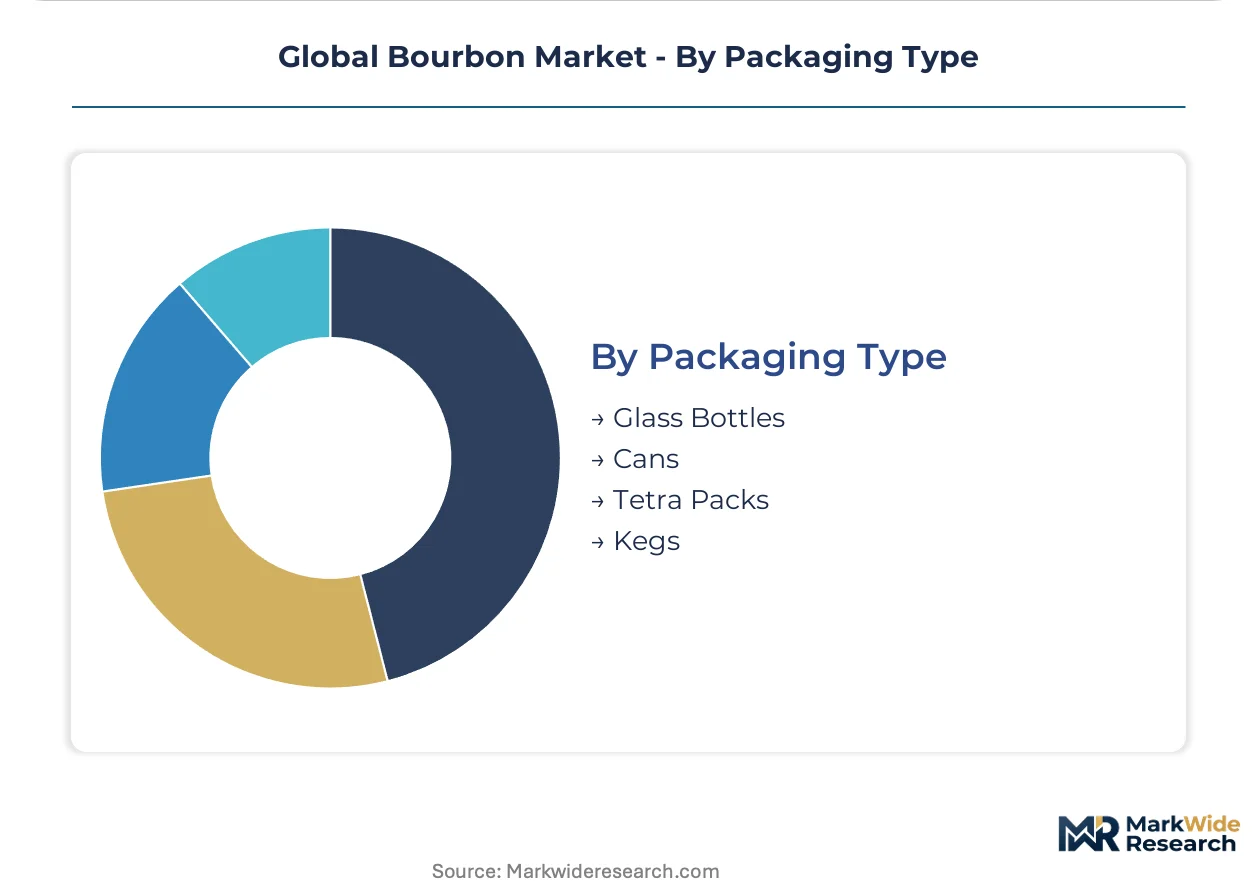
- Glass Bottles:Premium presentation standard for aged expressions, with bottle design and closure quality serving as shelf differentiation. Demand concentrates in gift-giving occasions and collector markets, though glass weight elevates freight costs for export shipments to Asian duty-free channels.
- Kegs:Stainless steel containers enabling cask-strength pours at volume for upscale hospitality venues in London, Sydney, and Singapore, reducing per-ounce serving costs while maintaining margin.
- Cans:Aluminum format for ready-to-drink bourbon cocktails, targeting outdoor and festival consumption.
- Tetra Packs:Aseptic cartons for value-tier blended expressions in price-sensitive emerging markets.
Revenue weight rests with Glass Bottles; format innovation concentrates in Kegs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States while consumption disperses across developed Asian and European markets. Kentucky and Tennessee distilleries supply over ninety percent of authentic bourbon volume. Import demand in Japan, Australia, and Germany now outpaces domestic growth trajectories.
United States
Kentucky's distillery corridor and Tennessee's Lynchburg operations anchor global supply through concentrated cooperage infrastructure and bonded warehouse networks. The TTB enforces strict mash bill minimums and new-charred-oak mandates that shape every producer's raw material procurement. Louisville and Nashville clusters generate shared logistics infrastructure that lowers per-unit maturation costs for straight bourbon output.
Japan
Tokyo and Osaka hospitality venues drive premium cask-strength consumption through visibility-driven back-bar placement. METI standards for spirits labeling create compliance thresholds for American exporters seeking shelf access. Duty-free allocations at Narita and Haneda airports concentrate collector demand for age-stated expressions.
Australia
Sydney and Melbourne bars normalize bourbon in premium cocktail programs alongside established Scotch and Japanese whisky selections. The country's national food standards regulator mandates additive disclosure requirements that parallel TTB frameworks. Independent retailers in Paddington and Fitzroy build allocation-list communities that mirror American specialty store dynamics.
Germany
Berlin and Hamburg cocktail culture absorbs bourbon into mixology-forward venues targeting affluent Millennial consumers. The EU's proposed Spirits Drinks Regulation revision threatens "Kentucky-style" descriptor usage, forcing label architecture reforms. Düsseldorf and Frankfurt duty-free terminals present shelf-space competition against Scotch and Irish whiskey incumbents.
United Kingdom
London's Mayfair and Shoreditch establishments anchor European premiumization through single-barrel allocation programs and collector event series. The Food Standards Agency enforces labeling compliance that intersects with TTB export documentation. Edinburgh and Glasgow retailers increasingly merchandise bourbon alongside native Scotch, reflecting cross-category collector behavior.
Global Bourbon Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning strata. The vendor base organizes around heritage-distillery ownership, Japanese multinational backing, and independent family-held operations. Three strategic archetypes dominate: vertically integrated cooperage-owners, contract-distillation scale players, and craft-positioned small-batch specialists. Competitive moves concentrate on wood innovation investment and Asia-Pacific duty-free channel anchoring.
Within the heritage-distillery tier, Beam Suntory and Brown-Forman occupy positions shaped by multinational resources and proprietary aging infrastructure. Heaven Hill Brands exemplifies family-held scale operations with age-stated reserve positioning. Japanese-backed Sazerac Company sits within the multinational-backed archetype leveraging distribution muscle across Pacific Rim channels.
| Leading Market Players |
|---|
| Beam Suntory |
| Brown-Forman |
| Sazerac Company |
| Campari Group |
| Heaven Hill Brands |
| Diageo |
| Kirin Holdings Company |
| Barton Brands |
| MGP (Midwest Grain Products) |
| Others |
Supply Flow & Price Mechanics
Master distiller concentration across Kentucky and Tennessee generates labor-cost differentials that widen pricing-tier spreads between allocated single-barrel releases and standard-proof volume products. Cooperage craftsmanship scarcity in these regions elevates premium-tier input costs while contract-distillation scale operations compress mid-market pricing floors.
Pricing Analysis
Margin tightening in premium tiers reflects white oak barrel scarcity and extended aging cycles that tie up working capital for six-to-eight-year maturation programs. Three-tier pricing structure across premium, standard, and economy levels separates age-stated single-barrel expressions from blended entry products, with certification-grade TTB compliance and proprietary cooperage relationships driving price differentiation. Cost-down pressure on value-tier accelerates because contract-distillation scale players flood retail channels with non-age-stated alternatives. Millennial collectors in coastal U.S. metropolitan markets exhibit lowest price sensitivity, while Gen Z entrants through flavored variants show highest elasticity.
Supply Chain Analysis
Freight cost escalation on glass bottle shipments to Asian duty-free channels compresses export margins for premium expressions. Supply concentrates in the United States, with Kentucky and Tennessee anchoring cooperage infrastructure and bonded warehouse networks. Raw material dependencies center on Appalachian white oak forests, Missouri and Arkansas stave suppliers, and corn procurement from Midwest grain elevators. Single-source vulnerability to new-charred-oak container availability creates procurement risk. Distribution runs through state-licensed wholesaler intermediation in 17 U.S. jurisdictions, with direct-to-ship statutes emerging as alternative pathways in permitted states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bourbon production is transitioning from heritage narrative to maturation science verification, with infrared spectroscopy and blockchain lot-tracking displacing traditional age-claim marketing. Producers must align capital allocation to technology-enabled provenance documentation.
For Market Incumbents: Deepen proprietary cooperage ownership to secure white oak supply against Appalachian forest depletion, while investing in RFID-enabled barrel tracking systems that monetize location-specific flavor profiles. Japanese whisky substitution in Asian duty-free channels threatens allocation power; anchor shelf position through exclusive age-stated releases at Narita, Haneda, and Singapore Changi terminals. For New Entrants and Emerging Players: Enter via Indian duty-free expansion at Delhi and Mumbai international terminals, where premium bourbon penetration lags Scotch and creates shelf-space white space. Target the 31-40 year collector demographic in Seoul and Tokyo through spectroscopic proof-of-age documentation that commands price premiums unavailable to heritage-positioned incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cooperage-owners given escalating new-oak barrel scarcity and extended procurement lead times. Long-term viability favors operations with captive stave production and climate-controlled rickhouse infrastructure. Watch TTB rulemaking on additive disclosures as inflection indicator for compliance-cost differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Cooperage Investment | Captive white oak supply insulates against Appalachian forest depletion and secures new-charred-oak container availability. |
| Spectroscopic Age Verification | Infrared ethanol-vanillin mapping satisfies Tokyo and Seoul collector demand for immutable provenance documentation. |
| Direct-to-Ship Statute Expansion | Kentucky and Tennessee legislative reforms bypass traditional wholesaler markups in permitted cross-state jurisdictions. |
| Climate-Controlled Rickhouse Zoning | Location-specific flavor profile isolation enables single-barrel selection premiums through high-ester barrel identification. |
| Asian Duty-Free Channel Anchoring | Exclusive age-stated allocations at Narita, Haneda, and Singapore Changi defend against Japanese whisky displacement. |
Methodological Framework
Multi-period observation of barrel inventory velocity, cooperage input costs, and allocation-list pricing anchored the trend analysis, supplemented by interviews with master distillers, cooperage operations managers, specialty retail buyers, and TTB regulatory affairs specialists. Secondary validation drew from U.S. Alcohol and Tobacco Tax and Trade Bureau filings, Kentucky Distillers' Association production surveys, U.S. Department of Agriculture corn price data, and customs export records. Bottom-up distillery capacity modeling triangulated against top-down category value estimates.
Input-output matrices mapped grain procurement through distillation, maturation, and bottling stages across product type, distribution channel, consumer age group, and packaging format segmentation dimensions. CAGRs were derived from rolling average growth rate convergence across the projection horizon. Forecast inputs incorporated white oak supply elasticity, three-tier distribution law evolution, and collector secondary market price discovery from London and Hong Kong auction platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under TTB additive disclosure rulemaking and EU Spirits Drinks Regulation revision enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Scotch Whisky Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Guerbet Alcohols Market