
 Honey Wine Market | 2026-2036
Honey Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Honey Wine Market Analysis
Subscription-based mead-of-the-month services is expanding how producers build recurring revenue beyond tasting-room traffic. Redstone Meadery leverages its Colorado production base to sustain direct-to-consumer relationships through seasonal releases. Schramm's Mead specializes in small-batch varietal honey sourcing, which differentiates its portfolio from commodity-grade competitors. B. Nektar Meadery controls Michigan distribution through a hybrid model combining self-distribution with selective wholesaler partnerships.
Honey wine denotes an alcoholic beverage produced through yeast fermentation of honey diluted with water, typically yielding alcohol content between eight and twenty percent by volume depending on honey concentration and fermentation duration. The primary commercial purpose centers on delivering a gluten-free, terroir-expressive alternative to grape wine and craft beer for experience-seeking consumers. Traditional honey wine occupies the mature volume position, while sparkling honey wine captures the fastest expansion as producers apply méthode champenoise techniques to attract champagne-adjacent buyers. Flavored honey wine concentrates margin pools through premium botanical infusions that justify elevated price positioning against baseline offerings.
The Alcohol and Tobacco Tax and Trade Bureau governs honey wine classification and labeling in the United States, creating compliance costs that favor established producers over informal entrants. FDA food additive regulations intersect with flavoring ingredient approvals, particularly for botanical and fruit adjuncts used in flavored honey wine production. Organic honey wine faces additional scrutiny under USDA National Organic Program standards for apiary management and honey sourcing documentation. Stakeholders must monitor evolving state-level direct shipping permissions, as interstate commerce restrictions remain the critical variable for scaling subscription and e-commerce channels.
Market Dynamics
Specialty beverage retailers are intensifying their honey wine assortments as consumer curiosity about fermented alternatives accelerates, while the Alcohol and Tobacco Tax and Trade Bureau's labeling standards reshape how producers communicate origin and composition to differentiate from grape wine.
Growth Catalysts
- Regulatory Clarity:The Alcohol and Tobacco Tax and Trade Bureau enforces distinct classification standards that separate honey wine from grape wine, reducing consumer confusion and enabling clearer shelf positioning for producers.
- Regional Production Clustering:Craft meaderies concentrate in the United States Pacific Northwest around Portland and Seattle, creating localized supply networks that reduce distribution costs and build consumer familiarity through tasting-room density.
- Ingredient Sourcing Innovation:Small-batch varietal honey sourcing allows producers to differentiate portfolios through terroir-expressive offerings that command premium positioning against commodity-grade competitors.
Market Restraints
- Input Cost Volatility:Honey prices fluctuate with colony health and climate patterns, exposing producers to margin compression when apiary yields decline in key sourcing regions.
- Regulatory Compliance Burden:FDA food additive regulations intersect with flavoring ingredient approvals for botanical and fruit adjuncts, creating documentation requirements that favor established producers with compliance infrastructure.
- Substitution Pressure:Craft beer and natural wine capture overlapping consumer segments, limiting honey wine's addressable market among experience-seeking drinkers with established category loyalties.
Strategic Opportunities
- Direct-to-Consumer Channels:Subscription-based mead-of-the-month services build recurring revenue streams that reduce dependence on tasting-room foot traffic and wholesale relationships.
- Hybrid Distribution Models:Self-distribution combined with selective wholesaler partnerships allows producers to control margin capture in core markets while scaling reach through third-party logistics.
- Organic Certification Premium:USDA National Organic Program standards for apiary management and honey sourcing documentation enable price positioning that captures health-conscious consumer segments.
Industry Challenges
- Interstate Commerce Friction:Evolving state-level direct shipping permissions create compliance complexity for subscription and e-commerce channels, requiring legal monitoring across multiple jurisdictions.
- Production Scale Economics:Small-batch fermentation methods limit volume efficiencies, constraining producers' ability to achieve cost structures competitive with mass-market alcoholic beverages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honey Wine Market |
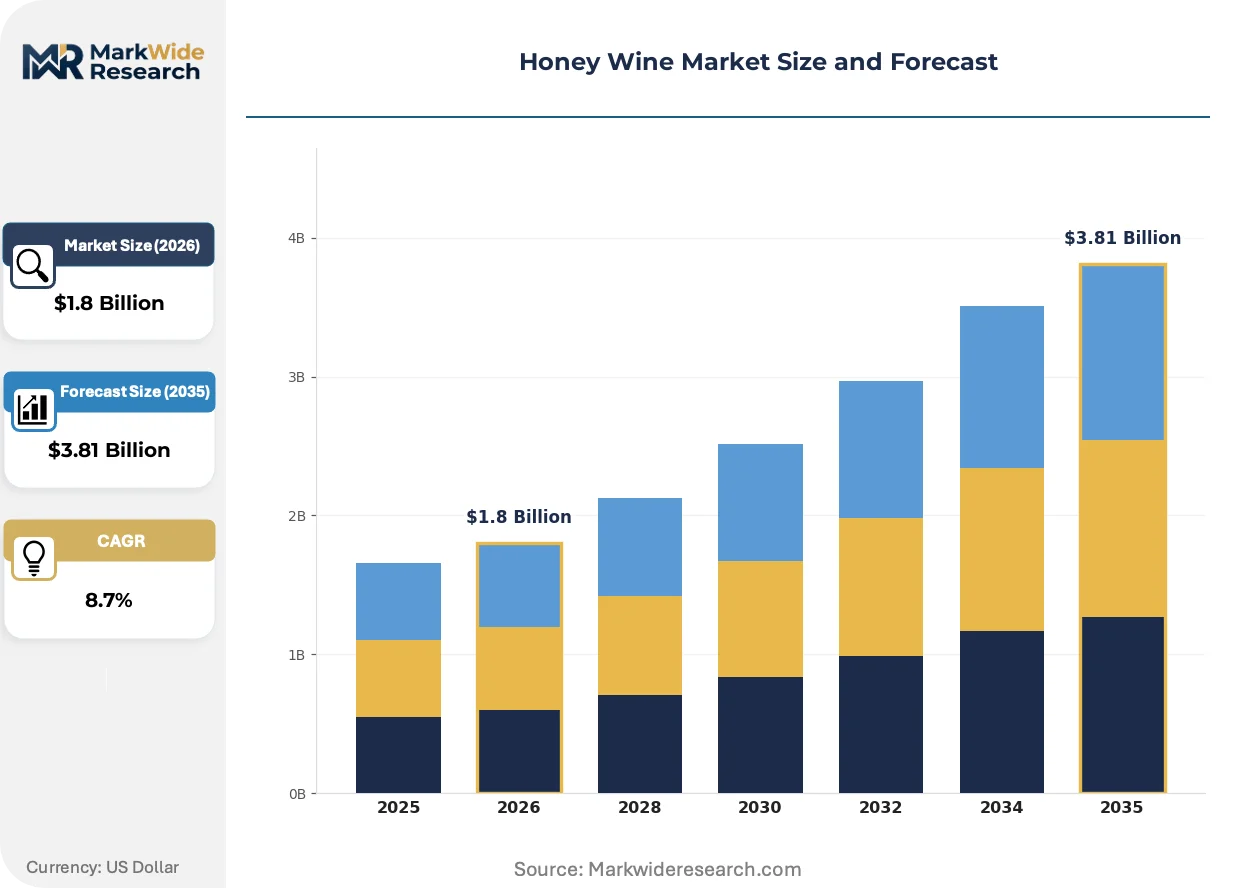
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Honey Wine, Sparkling Honey Wine, Flavored Honey Wine, Organic Honey Wine Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Packaging Type: Glass Bottles, Tetra Paks, Plastic Bottles, Kegs Customer Type: Retail Consumers, Restaurants, Bars, Event Organizers |
| Companies Covered | Redstone Meadery, Schramm's Mead, Medovina Meadery, Kuhnhenn Brewing Co. LLC, Brothers Drake Meadery, The Honey Wine Company, Martin Brothers Winery, Moonshine Meadery, B. Nektar Meadery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honey Wine Market Emerging Trajectories
Méthode champenoise techniques are migrating into honey wine production as producers seek champagne-adjacent positioning, while regulatory frameworks and consumption patterns simultaneously reshape competitive boundaries.
Controlled fermentation technology is unifying temperature, yeast strain, and honey dilution management into integrated production systems. Mid-sized meaderies adopt these platforms to reduce batch variation and accelerate product consistency. The technology is unifying quality thresholds across geographically dispersed production facilities, enabling multi-location brands to maintain sensory uniformity.
USDA National Organic Program standards are tightening apiary management documentation requirements for organic honey wine certification. Producers must now maintain chain-of-custody records from hive to bottle, increasing administrative overhead but creating defensible market segmentation. Pacific Northwest meaderies with established supplier relationships are responding fastest to capture organic price premiums.
Experience-seeking consumers are rotating toward sparkling honey wine as their entry point into the category, displacing still traditional variants as the default first purchase. Specialty beverage retailers are reconfiguring shelf space to prioritize effervescent formats with champagne-style packaging. This pattern concentrates in urban markets with established craft beverage cultures, particularly Seattle and Portland tasting rooms where staff education drives trial conversion.
Honey Wine Market Segmentation
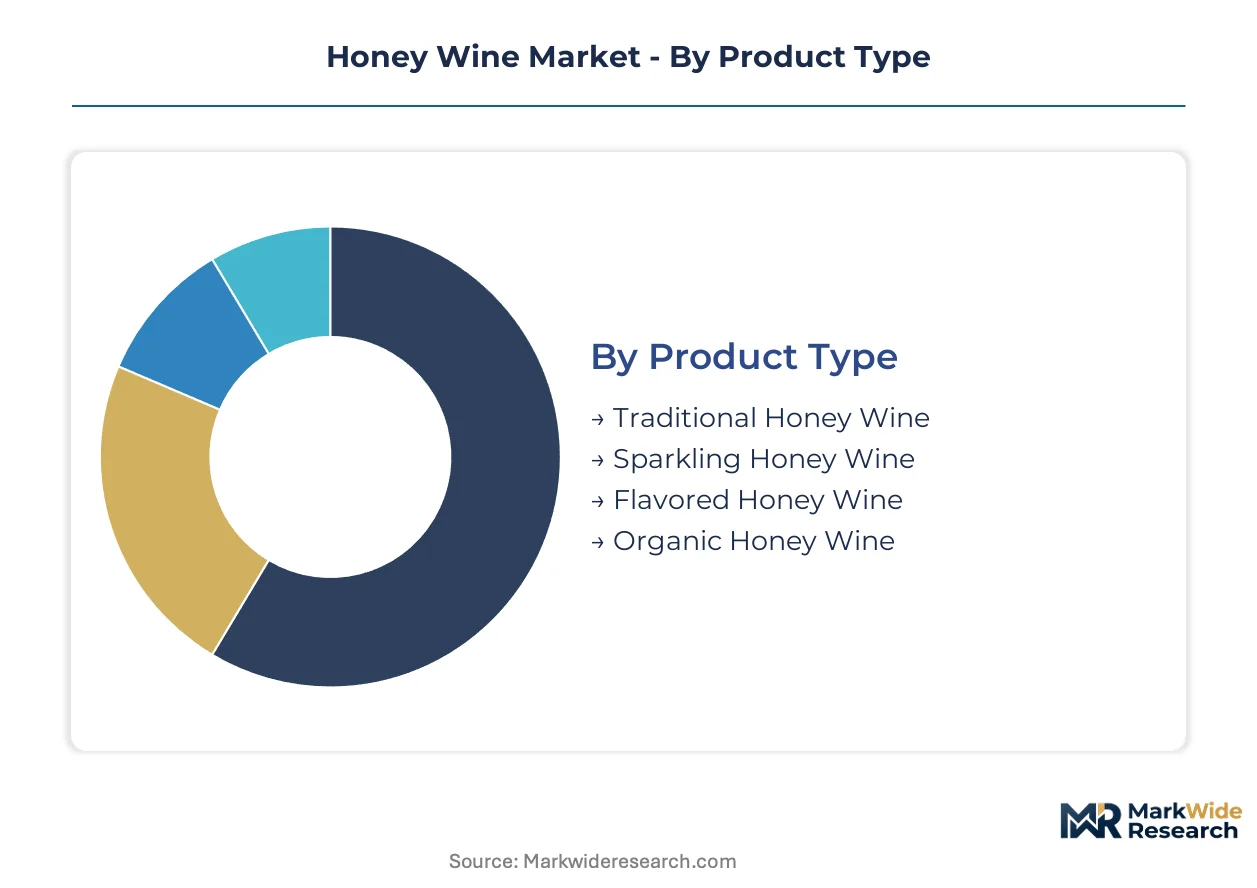
Segmentation in honey wine reveals how production methods, distribution economics, and consumption occasions fragment addressable demand. Producers must align fermentation techniques and packaging formats with distinct buyer workflows across retail and foodservice channels.
Product Type:
Fermentation specifications and ingredient handling protocols divide commercial offerings into four distinct product classes.
- Traditional Honey Wine:Still fermentation of diluted honey without carbonation or adjuncts yields alcohol content between eight and twenty percent. Volume concentrates in Pacific Northwest tasting rooms where craft meaderies build consumer education through direct sampling.
- Sparkling Honey Wine:Méthode champenoise secondary fermentation creates effervescence and champagne-adjacent positioning. Urban specialty retailers in Seattle and Portland are expanding shelf space for this format as staff-guided trial converts experience-seeking drinkers.
- Flavored Honey Wine:Botanical and fruit adjuncts infuse during or after primary fermentation. FDA food additive regulations govern ingredient approvals, creating compliance documentation that favors established producers with regulatory infrastructure.
- Organic Honey Wine:USDA National Organic Program standards mandate apiary management documentation and chain-of-custody verification from hive to bottle. Premium price positioning captures health-conscious segments willing to pay for certified sourcing transparency.
Mature deployment sits with Traditional Honey Wine. Newer deployment is concentrated in Sparkling Honey Wine.
Distribution Channel:
Margin capture and regulatory compliance requirements vary sharply across channel structures.
- Online Retail:Subscription-based mead-of-the-month services and direct-to-consumer platforms build recurring revenue streams. Interstate commerce friction from evolving state-level shipping permissions creates legal complexity requiring multi-jurisdictional monitoring.
- Specialty Stores:Curated assortments in craft beverage retailers intensify as consumer curiosity about fermented alternatives accelerates. TTB labeling standards enable clearer shelf positioning that distinguishes honey wine from grape wine.
- Supermarkets:Mass retail placement demands volume consistency and price competitiveness that small-batch producers struggle to achieve. Distribution through this channel remains limited to scaled operations with national broker relationships.
- Direct Sales:Tasting-room traffic and on-site bottle sales generate highest per-unit margins but constrain geographic reach. Regional production clustering in Portland and Seattle reduces customer acquisition costs through localized density.
Volume concentrates in Direct Sales. Margin expansion is accelerating fastest in Online Retail.
Packaging Type:
Material specifications and format economics align with consumption occasion and distribution distance.
- Glass Bottles:Standard 750ml and 375ml formats dominate premium positioning with label transparency for terroir communication. Weight and fragility increase logistics costs for direct shipping channels.
- Tetra Paks:Aseptic cartons reduce shipping weight and enable single-serve formats for outdoor and festival consumption. Adoption remains limited by consumer perception barriers in alcoholic beverage categories.
- Plastic Bottles:PET formats target price-sensitive entry-level buyers and large-format outdoor events. Oxygen permeability concerns constrain shelf life compared to glass alternatives.
- Kegs:Stainless steel and disposable bag-in-tank systems serve on-premise accounts with draft programs. Bars in craft beverage markets rotate seasonal meads alongside craft beer portfolios.
Standard deployment sits with Glass Bottles. Experimental adoption is concentrating in Kegs.
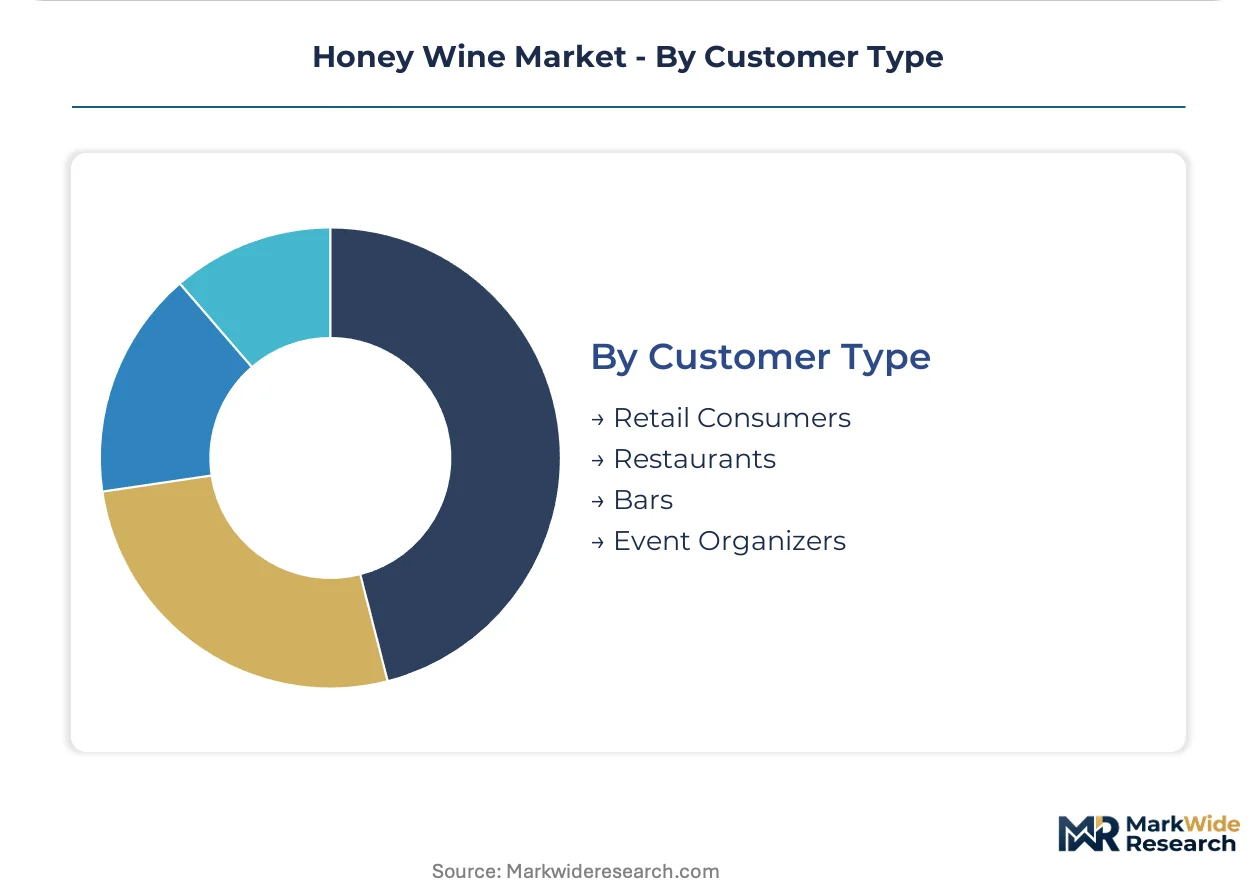
Customer Type:
Purchase frequency and volume scale separate individual buyers from institutional accounts with distinct procurement workflows.
- Retail Consumers:Individual buyers seeking gluten-free alternatives to grape wine and craft beer drive trial through tasting-room visits and specialty retailer recommendations. Repeat purchase depends on education about food pairing and serving temperature.
- Restaurants:Farm-to-table and New American cuisine establishments in Portland and Seattle feature local meaderies on beverage menus. Sommelier education programs remain underdeveloped compared to wine and beer categories.
- Bars:Craft cocktail programs incorporate honey wine as a base for signature drinks or offer draft mead as a beer alternative. Staff training requirements limit rollout speed beyond established craft beverage markets.
- Event Organizers:Weddings, corporate gatherings, and festival operators purchase in volume for experiential differentiation. Seasonal demand spikes around summer outdoor events create production scheduling challenges.
Revenue foundation sits with Retail Consumers. Account expansion is climbing fastest in Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in the United States Pacific Northwest and Michigan outpace domestic consumption, while import-dependent markets in Western Europe and East Asia absorb excess supply through specialty beverage channels.
United States
Portland and Seattle tasting rooms drive trial conversion through staff-guided education, while the Alcohol and Tobacco Tax and Trade Bureau enforces distinct labeling standards that separate honey wine from grape wine on retail shelves. Craft meaderies cluster in Colorado and Michigan, with Redstone Meadery and B. Nektar Meadery anchoring regional distribution networks.
Germany
Traditional mead consumption persists in Bavaria and Saxony, where historical brewing customs sustain baseline demand for met and honigwein variants. The country's food and beverage regulator enforces EU-wide labeling directives under the Food Information to Consumers Regulation. Small-scale producers concentrate in the Black Forest and Harz Mountain regions, supplying domestic specialty retailers and Christmas market vendors.
United Kingdom
Artisanal producers in Cornwall and Yorkshire exploit heritage positioning to capture premium segments seeking alternatives to grape wine. The Food Standards Agency coordinates with HMRC on alcohol duty classifications that affect small-batch pricing structures. London specialty retailers intensify honey wine assortments as consumer curiosity about fermented alternatives accelerates in urban craft beverage markets.
Canada
Vancouver and Toronto tasting rooms replicate Pacific Northwest consumer education models, while provincial liquor boards create distribution bottlenecks that favor established importers over direct producer relationships. Health Canada regulates additive approvals for flavored variants through the Food and Drugs Act. British Columbia apiaries supply regional meaderies with varietal honey that commands terroir-based positioning.
Australia
Victoria and New South Wales producers leverage eucalyptus and leatherwood honey varieties to differentiate export portfolios from Northern Hemisphere competitors. Food Standards Australia New Zealand mandates allergen labeling and alcohol content disclosure that shapes packaging requirements. Melbourne specialty bars rotate seasonal meads alongside natural wine programs, building staff familiarity that drives consumer trial.
Honey Wine Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base fragments across micro-meaderies with tasting-room dependency and scaled operations with national broker relationships. Three archetypes dominate: terroir-focused varietal honey sourcers, subscription-driven direct-to-consumer specialists, and hybrid distributors combining self-distribution with selective wholesaler partnerships. Competitive moves concentrate on geographic expansion through production facility replication and portfolio diversification into sparkling and flavored variants.
Within the terroir-focused tier, Schramm's Mead exemplifies small-batch varietal honey sourcing that differentiates against commodity-grade competitors. B. Nektar Meadery occupies a position combining Michigan production base with hybrid distribution control. Redstone Meadery anchors the direct-to-consumer archetype through Colorado-based seasonal release programs. These three represent distinct strategic postures without implying specific market share or operational scale claims.
| Leading Market Players |
|---|
| Redstone Meadery |
| Schramm's Mead |
| Medovina Meadery |
| Kuhnhenn Brewing Co. LLC |
| Brothers Drake Meadery |
| The Honey Wine Company |
| Martin Brothers Winery |
| Moonshine Meadery |
| B. Nektar Meadery |
| Others |
Supply Flow & Price Mechanics
Méthode champenoise adoption in sparkling honey wine production simultaneously elevates equipment capital requirements and concentrates supply networks among mid-sized meaderies with integrated temperature-control infrastructure. This technological shift tightens producer margins while rewarding Pacific Northwest operations with established fermentation platforms.
Pricing Analysis
Margin tightening in organic honey wine reflects USDA National Organic Program documentation burdens that favor established producers with compliance infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates certified organic varietals from conventional still formats and entry-level flavored variants. Cost compression in commodity-grade segments accelerates because craft beer substitution intensifies price sensitivity among trial-stage buyers. Restaurant accounts exhibit lowest price sensitivity due to menu-margin absorption, while supermarket channels demand volume discounts that strain small-batch economics.
Supply Chain Analysis
Regional distribution centers in Portland, Seattle, and Denver anchor hub-and-spoke patterns that reduce last-mile costs for direct-to-consumer channels. Raw material dependencies center on Pacific Northwest apiaries for varietal honey, California yeast suppliers, and Michigan packaging vendors. Single-source vulnerability concentrates in leatherwood and eucalyptus honey varieties sourced from Tasmania and Western Australia. Distribution runs through hybrid models combining self-distribution in core markets with selective wholesaler partnerships for geographic expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Honey wine supply constraints from apiary yield volatility prop pricing power for producers with captive hive relationships or long-term beekeeper contracts.
For Market Incumbents: Hedge against input cost volatility through backward integration into apiary operations or multi-year honey purchasing agreements with Pacific Northwest suppliers. Defend market position by accelerating sparkling format production to capture champagne-adjacent pricing premiums before craft beer and natural wine encroachment intensifies. For New Entrants and Emerging Players: Specialty beverage retailers in secondary urban markets represent the most penetrable channel partner type for building trial without tasting-room infrastructure. White-space targets include organic certification gaps in the Southeast and subscription-based direct-to-consumer models underserved by incumbent wholesaler dependence. A go-to-market angle anchored in single-origin varietal storytelling differentiates against commodity-grade competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in regional rollup strategies and craft beverage platform acquisitions. Long-term viability hinges on producers achieving scale sufficient to absorb regulatory compliance costs while maintaining terroir differentiation. Acquisition target archetypes feature mid-sized meaderies with established self-distribution networks and organic certification pipelines. The signal to watch is state-level direct shipping permission expansion enabling subscription channel scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA National Organic Program compliance captures health-conscious consumer segments willing to pay transparency premiums. |
| Sparkling Format Expansion | Méthode champenoise production attracts champagne-adjacent buyers in Seattle and Portland urban markets. |
| Subscription Channel Development | Mead-of-the-month services build recurring revenue streams reducing dependence on tasting-room foot traffic volatility. |
| Varietal Honey Sourcing Contracts | Long-term apiary agreements insulate margins from colony health-driven honey price fluctuations. |
| Hybrid Distribution Model Implementation | Self-distribution in core markets preserves margin capture while selective wholesaler partnerships enable geographic scaling. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this honey wine market analysis. Primary interviews with meadery production directors, specialty beverage retail buyers, TTB compliance officers, and apiary supply managers combined with Alcohol and Tobacco Tax and Trade Bureau labeling guidelines, FDA food additive regulations, and USDA National Organic Program standards. Bottom-up facility capacity assessments and top-down consumption pattern modeling enabled triangulation across data streams.
Data-stream reconciliation across production volume surveys, distribution channel audits, and price tracking databases informed the analytical framework. Segmentation dimensions modeled include product type, distribution channel, packaging format, and customer type across the projection horizon. CAGRs derived from historical growth pattern analysis adjusted for regulatory intervention timing and consumer adoption curve inflections. Honey price volatility indices and state-level shipping permission evolution served as industry-specific forecast inputs.
Caveats apply where apiary yield shocks from climate patterns or colony collapse disorder could materially shift the outlook. Forecasts reflect assumptions about regulatory stability and consumer substitution patterns between honey wine and competing craft beverages. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Fruit Brandy Market