
 Woozy Bottle Market | 2026-2036
Woozy Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Woozy Bottle Market Analytics
REACH compliance is repositioning the cost-of-entry calculus for European suppliers, forcing reformulation of glass coatings and plastic resin selections. Berlin Packaging L.L.C. leverages its North American distribution network to sustain volume leadership in food-grade containers. SKS Bottle & Packaging anchors its competitiveness through deep inventory of amber and clear glass woozy configurations. Xuzhou Pengxu Glass Products Co., Ltd. dominates export manufacturing through integrated furnace operations and molded finish precision.
A woozy bottle denotes a slender-necked, elongated container traditionally manufactured from amber or flint glass, though PET and HDPE variants now incorporate UV-inhibiting additives and oxygen-scavenging layers to protect light-sensitive sauces and syrups. Glass retains primacy in premium hot sauce and craft condiment segments where thermal processing compatibility and chemical inertness justify higher unit costs, while plastic variants capture volume in mass-market retail through reduced breakage rates and lighter freight economics. The 750ml capacity band leads absolute volume as barbecue sauce and marinade producers standardize around this fill size, though 250ml formats generate disproportionate margin contribution from specialty and gift-pack channels.
FDA food-contact substance regulations govern resin approvals and migration limits for plastic woozy bottles distributed in the United States, while EPA emissions standards shape glass furnace operations and secondary abatement investments. The EU Green Deal's packaging reuse targets and California's SB 54 extended producer responsibility framework are converging to mandate higher post-consumer recycled content thresholds across both glass and polymer supply chains. Stakeholders must monitor pending state-level labeling mandates and recycled-content minimums that will determine which material platforms and regional production bases retain cost-competitive access to regulated end markets.
Market Dynamics
EU Green Deal packaging reuse targets and California SB 54 extended producer responsibility mandates are forcing simultaneous reformulation of glass coatings and polymer resin selections across woozy bottle supply chains.
Growth Catalysts
- Artisanal food manufacturing clusters:Southeastern United States bottling operations are expanding capacity for premium hot sauce and craft condiment packaging, pulling demand for amber glass configurations.
- REACH compliance repositioning:European glass coaters are investing in alternative formulations that eliminate restricted substances, opening certified supply channels for food-grade containers.
- Oxygen-scavenging PET layers:Plastic variants incorporating UV-inhibiting additives are capturing volume in mass-market retail through reduced breakage rates and lighter freight economics.
Market Restraints
- Soda ash and silica input volatility:Glass furnace operations face energy cost spikes and raw material availability constraints that compress margin structures for flint and amber variants.
- Chinese furnace concentration:Export manufacturing gravity centers on integrated furnace operations in Xuzhou and surrounding industrial zones, creating single-source vulnerability for molded finish precision.
- HDPE thermal processing incompatibility:Plastic woozy bottles cannot withstand hot-fill pasteurization protocols required by barbecue sauce and marinade producers, limiting substitution in premium segments.
Strategic Opportunities
- Post-consumer recycled content mandates:California SB 54 and pending state-level labeling requirements create certified demand pull for rPET and cullet-based glass formulations.
- Gift-pack channel expansion:250ml specialty formats generate disproportionate margin contribution through curated subscription boxes and direct-to-consumer condiment assortments.
- UV-inhibiting additive convergence:Co-extrusion technology pairing oxygen scavengers with light barriers enables plastic woozy bottles to penetrate light-sensitive syrup and sauce applications previously reserved for glass.
Industry Challenges
- Migration testing bottlenecks:FDA food-contact substance approvals for novel resin formulations face extended review timelines that delay product launches.
- Furnace retooling capex intensity:Secondary abatement investments required by EPA emissions standards demand capital allocation that smaller glassworks cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woozy Bottle Market |
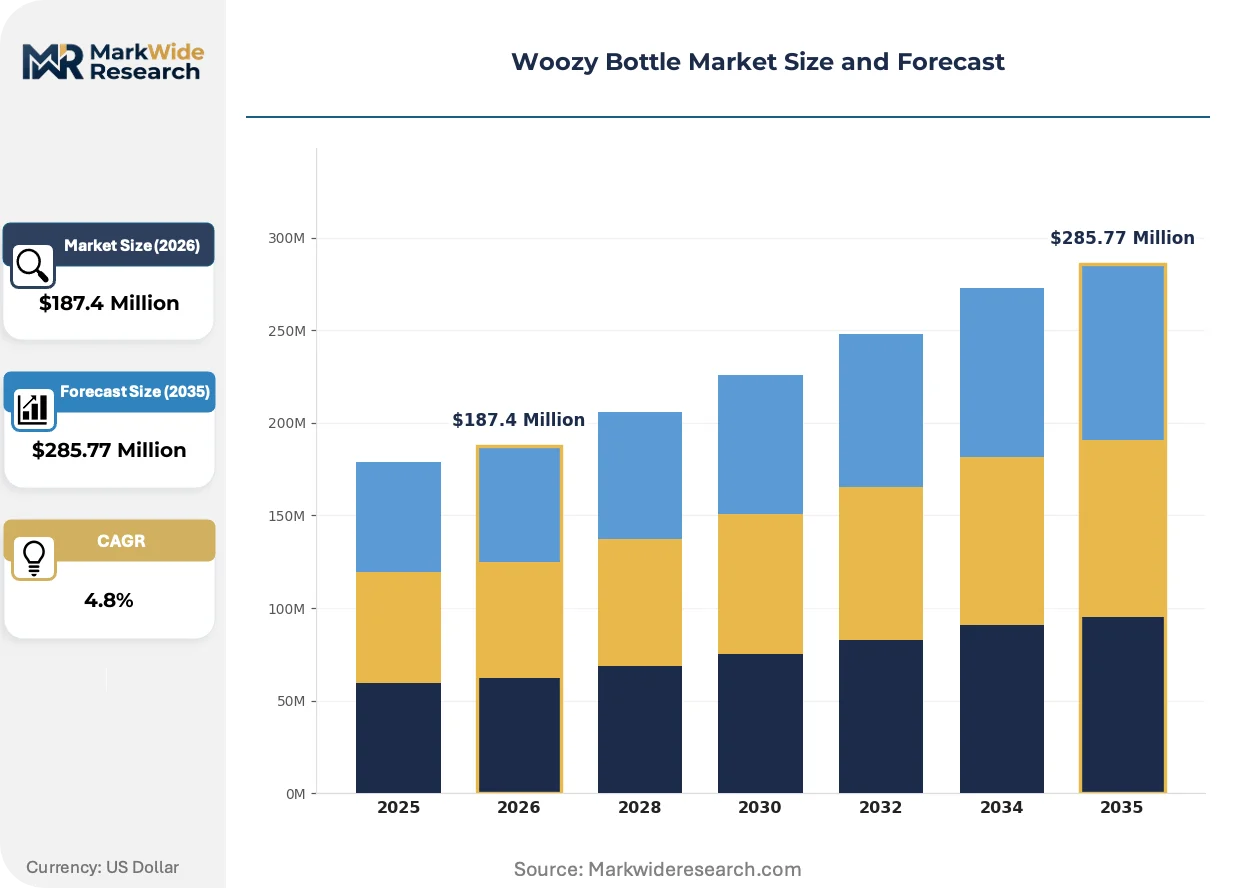
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
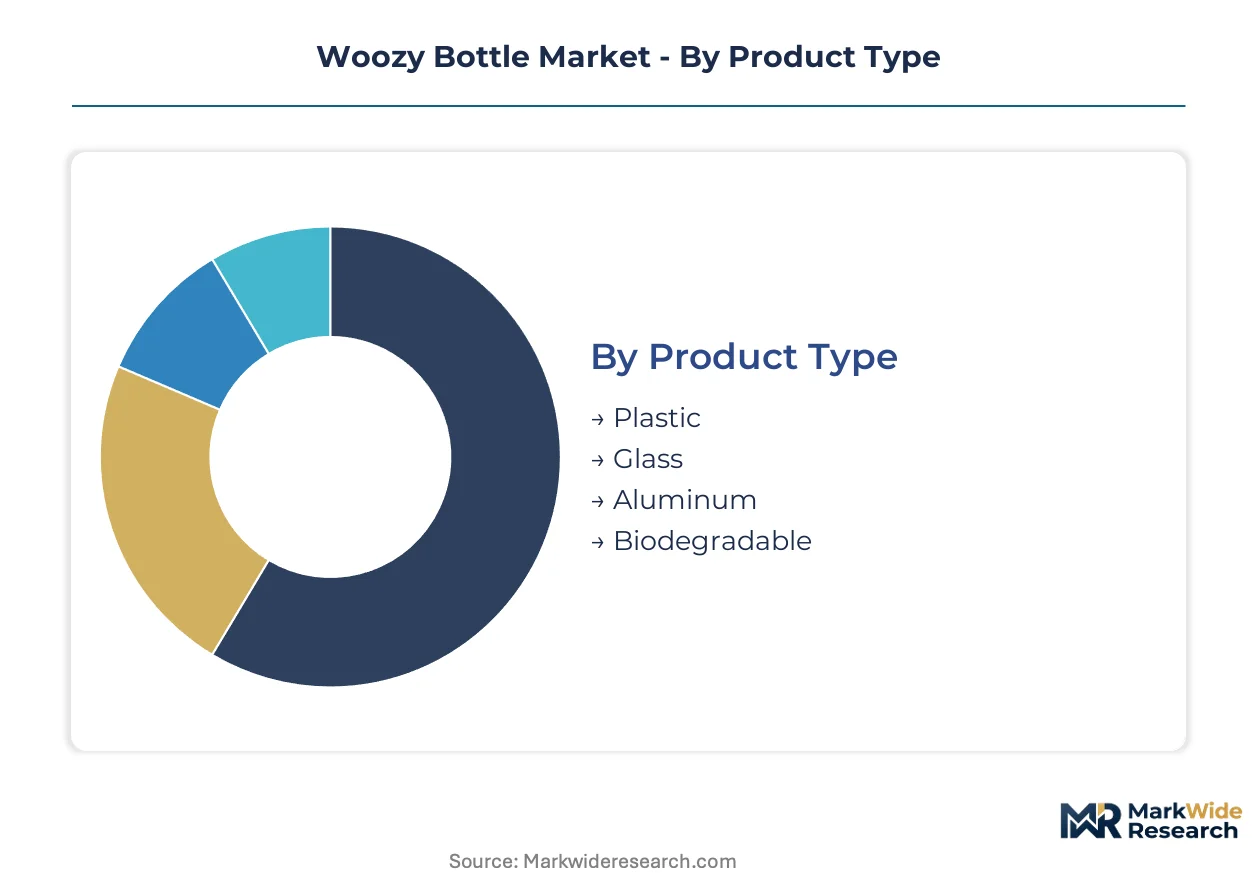
| Segmentation | Product Type: Plastic, Glass, Aluminum, Biodegradable Closure Type: Screw cap, Cork, Flip-top, Snap-on Capacity: 250ml, 500ml, 750ml, 1000ml End User: Retailers, Restaurants, Wholesalers, Consumer Direct |
| Companies Covered | Berlin Packaging L.L.C., Container and Packaging Supply, Inc., Vanjoin Hubei Industry Limited, United States Plastic Corporation, UPC Packaging, Plasdene Glass-Pak Pty Ltd., The Cary Company, SKS Bottle & Packaging, Xuzhou Pengxu Glass Products Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woozy Bottle Market Evolving Landscape
Packaging material science and regulatory compliance are converging to reshape competitive positioning in condiment containers, with automation and sustainability mandates driving capital allocation decisions.
Co-extrusion barrier technology is automating the production of multi-layer PET woozy bottles that match glass oxygen transmission rates. Hot sauce producers in Texas and Louisiana are trialing these configurations for retail shelf presence. The technology is automating quality control protocols that previously required manual inspection of amber glass for seed and stone defects.
EU Packaging and Packaging Waste Regulation material recovery requirements are tightening sorting and recycling infrastructure investments. Glass coaters must reformulate surface treatments to eliminate lead and cadmium compounds while maintaining chemical durability. European artisanal sauce brands are responding by consolidating supplier bases around REACH-certified molders with verified chain-of-custody documentation.
Direct-to-consumer condiment subscriptions are compressing traditional distributor-wholesaler channels. Specialty sauce brands now bypass foodservice intermediaries to capture margin through owned e-commerce storefronts. This pattern concentrates in the southeastern United States where regional fulfillment networks support small-batch production economics.
Woozy Bottle Market Segmentation
Woozy bottle procurement decisions cascade from material-platform selection through capacity optimization to channel-specific closure requirements. Each segmentation axis carries distinct regulatory footprints and margin implications that reshape supplier competitiveness across artisanal and mass-market tiers.
Product Type:
Amber and flint glass formulations compete against multi-layer PET and emerging biodegradable substrates on thermal tolerance, freight density, and recycled-content compliance.
- Glass:Amber and flint variants dominate premium hot sauce and craft condiment segments where FDA food-contact inertness and hot-fill pasteurization compatibility justify higher unit costs. Demand concentrates in Texas and Louisiana bottling corridors where artisanal producers require thermal processing resilience.
- Plastic:PET and HDPE configurations incorporate UV-inhibiting additives and oxygen-scavenging layers to penetrate light-sensitive sauce applications. Mass-market barbecue sauce producers in the southeastern United States favor these variants for reduced breakage rates and lighter freight economics.
- Aluminum:Lightweight metal substrates offer superior oxygen barrier properties for extended shelf-life syrups and marinades.
- Biodegradable:Emerging PLA and cellulose-based formulations target California SB 54 compliance pathways and direct-to-consumer subscription channels.
Glass leads on scale; biodegradable substrates lead on momentum.
Closure Type:
Sealing mechanisms differentiate on tamper evidence, dispensing control, and automation compatibility across retail and foodservice channels.
- Screw cap:Threaded polypropylene closures dominate 750ml barbecue sauce formats with torque-controlled sealing and pilfer-evident bands. High-speed capping lines in southeastern bottling plants standardize around 38mm neck finishes.
- Flip-top:Hinged dispensing closures capture 250ml specialty formats where controlled pour and one-handed operation drive gift-pack and subscription box adoption.
- Cork:Natural and synthetic stopper configurations serve premium artisanal segments with aesthetic differentiation requirements.
- Snap-on:Press-fit closures reduce per-unit cost for high-volume retail distribution with minimal reseal demands.
Screw cap leads on scale; flip-top leads on momentum.
Capacity:
Fill-volume selection tracks application-specific consumption patterns and retail shelf-space economics.
- 750ml:The standardized barbecue sauce and marinade format maximizes production line efficiency across co-packing networks. Retailers in the southeastern United States favor this footprint for condiment aisle planogram compliance.
- 250ml:Specialty and gift-pack configurations generate disproportionate margin contribution through curated subscription assortments and direct-to-consumer channels.
- 500ml:Mid-tier capacity serves family-size hot sauce and table syrup segments with balanced unit economics.
- 1000ml:Foodservice and institutional formats target restaurant back-of-house and wholesale redistribution.
750ml leads on scale; 250ml leads on momentum.
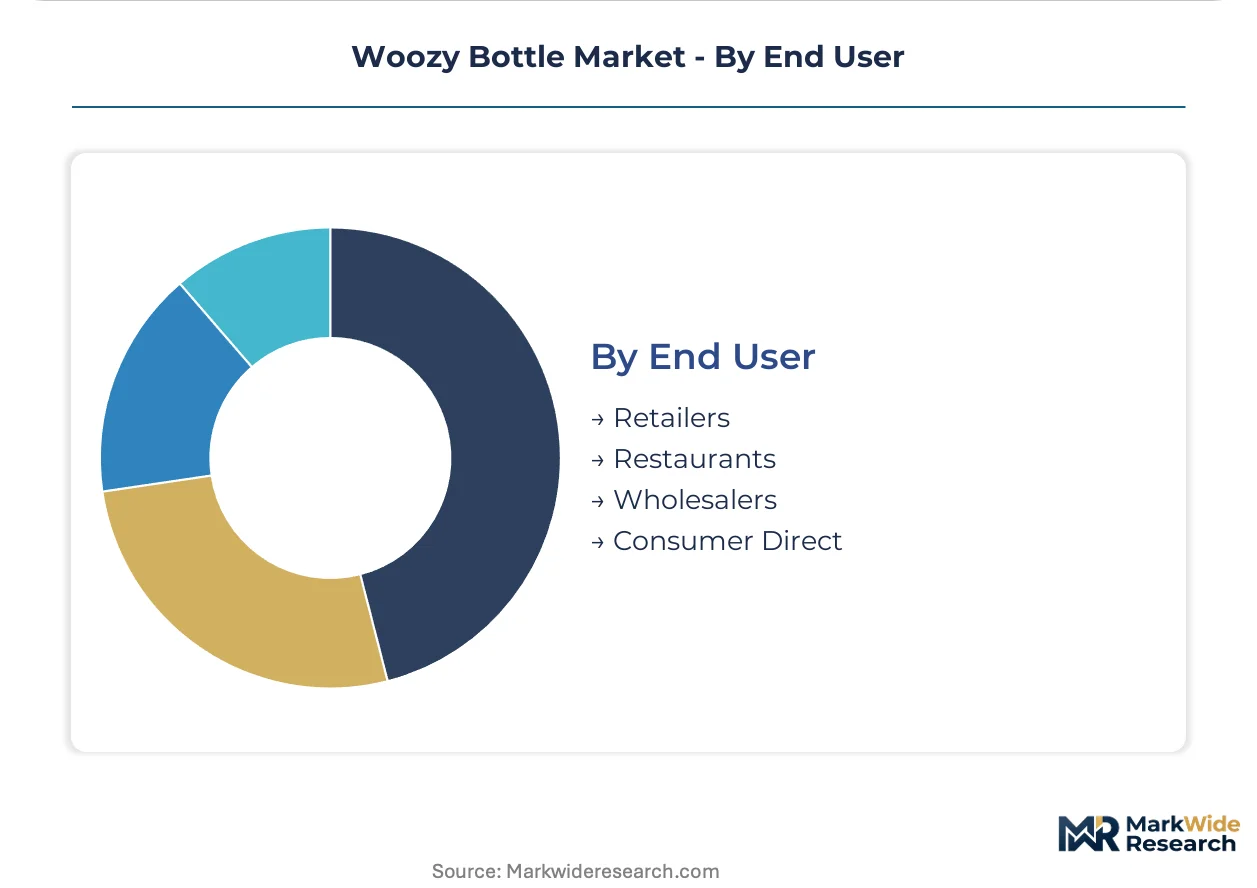
End User:
Channel configuration determines packaging specification, labeling complexity, and order-fulfillment infrastructure requirements.
- Retailers:Supermarket and specialty food chains demand palletized case packs with UPC compliance and shelf-ready secondary packaging. FDA labeling mandates and state-level recycled-content minimums shape procurement specifications.
- Consumer Direct:Subscription box operators and owned e-commerce storefronts bypass distributor-wholesaler channels to capture margin through curated assortments. This pattern concentrates in southeastern fulfillment networks supporting small-batch production economics.
- Restaurants:Foodservice accounts prioritize bulk formats with commercial dispensing compatibility and back-of-house durability.
- Wholesalers:Redistribution intermediaries aggregate fragmented artisanal production for broader geographic coverage.
Retailers lead on scale; consumer direct leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisanal sauce producers and glass furnace operators concentrate in distinct regional clusters that shape woozy bottle procurement patterns and regulatory compliance pathways across multiple continents.
United States
Texas and Louisiana hot sauce bottlers drive amber glass demand for thermal processing compatibility. FDA food-contact substance regulations govern resin approvals for plastic variants targeting mass-market barbecue sauce segments. Southeastern fulfillment networks in Georgia and Florida support direct-to-consumer subscription channels for specialty 250ml formats.
China
Xuzhou-based integrated furnace operations dominate export manufacturing through molded finish precision and scale economies. The country's national environmental regulator enforces emissions standards that shape secondary abatement investments across glassworks. Yangtze River Delta industrial zones concentrate PET co-extrusion capacity for oxygen-scavenging barrier technologies.
Germany
REACH-certified glass coaters reformulate surface treatments to eliminate restricted substances while maintaining chemical durability. ECHA compliance requirements reposition cost-of-entry calculus for European suppliers serving artisanal food brands. Bavarian industrial clusters consolidate supplier bases around verified chain-of-custody documentation for premium condiment packaging.
India
FSSAI food safety standards govern packaging material approvals for domestic hot sauce and pickle producers. Maharashtra and Gujarat manufacturing corridors expand bottling capacity for regional condiment brands targeting urban retail channels. Mumbai-Pune industrial zones develop rPET sourcing networks to address emerging extended producer responsibility frameworks.
Brazil
ANVISA pharmaceutical-grade packaging regulations influence quality standards migrating into premium food segments. São Paulo state condiment manufacturers source flint glass configurations for table sauce applications with shelf visibility requirements. Minas Gerais artisanal producers trial biodegradable substrates for export-oriented organic certification compliance.
Woozy Bottle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material platforms and geographic markets. The vendor base organizes around three strategic archetypes: integrated glass furnace operators with captive raw material sourcing, regional packaging distributors with deep inventory positioning, and specialty converters with barrier technology capabilities. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to recycled-content mandates and thermal processing requirements.
Among North American distributors, Berlin Packaging L.L.C. and SKS Bottle & Packaging exemplify inventory-heavy positioning across amber and clear glass configurations. Xuzhou Pengxu Glass Products Co., Ltd. anchors the integrated manufacturing archetype through furnace-based production scale. These three entities represent distinct strategic postures—distribution breadth, specialty format depth, and upstream manufacturing control—that collectively define competitive tension in the category.
| Leading Market Players |
|---|
| Berlin Packaging L.L.C. |
| Container and Packaging Supply, Inc. |
| Vanjoin Hubei Industry Limited |
| United States Plastic Corporation |
| UPC Packaging |
| Plasdene Glass-Pak Pty Ltd. |
| The Cary Company |
| SKS Bottle & Packaging |
| Xuzhou Pengxu Glass Products Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Soda ash price indices cascading through glass furnace operations differentiate amber and flint glass pricing tiers from multi-layer PET alternatives, with energy cost pass-through mechanisms amplifying spreads between premium craft condiment packaging and mass-market barbecue sauce segments.
Pricing Analysis
Packaging converters sell finished woozy bottles through bundled mold-lease-and-finish arrangements alongside unbundled spot purchases for established sauce brands. Price differentiation hinges on thermal processing certification grade and volume commitment scale, with hot-fill-compatible glass commanding premiums over standard flint variants. Cost compression in plastic tiers is intensifying because oxygen-scavenging co-extrusion capex amortization is spreading across thinner order books. Mass-market barbecue sauce producers exhibit highest price sensitivity; gift-pack specialty brands show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Xuzhou-based integrated furnace operations that anchor global amber glass supply for North American hot sauce bottlers. Raw material dependencies span soda ash from Wyoming and Turkey, silica sand from regional quarries in Jiangsu, and UV-inhibiting additive masterbatches from Yangtze River Delta chemical clusters. Tariff exposure on Chinese glassware imports threatens cost structures for southeastern United States co-packers. Distribution runs through regional packaging distributors with deep inventory positioning in Georgia and Texas fulfillment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The woozy bottle market operates as a regulatory compounder where California SB 54 extended producer responsibility mandates and EU Green Deal packaging reuse targets are simultaneously tightening material specifications and opening certified supply premiums.
For Market Incumbents: Deepen backward integration into cullet sourcing networks and captive soda ash contracts to defend margin position against energy cost volatility. Anchor competitiveness through REACH-certified coating formulations that lock in European artisanal sauce brand relationships before compliance deadlines eliminate uncertified rivals. For New Entrants and Emerging Players: Subscription box operators represent the most penetrable channel partner type for 250ml specialty format woozy bottles with flip-top closures and curated aesthetic differentiation. Target direct-to-consumer condiment brands in southeastern United States fulfillment zones with rapid-turn customization capabilities and California SB 54 pre-certified rPET formulations. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty converters possessing oxygen-scavenging co-extrusion patents and verified FDA food-contact substance approvals. Long-term viability favors acquisition targets with dual glass-and-plastic platform capabilities that can pivot material selection as recycled-content mandates tighten across state jurisdictions. Watch for inflection when migration testing bottlenecks at FDA clear for novel barrier resin formulations.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA-certified glass coaters capture European artisanal sauce brand consolidation. |
| Oxygen-Scavenging PET Scale-Up | Co-extrusion capacity expansion penetrates light-sensitive syrup applications. |
| Cullet-Based Glass Furnace Retrofit | Secondary abatement investments satisfy EPA emissions standards for domestic production. |
| Direct-to-Consumer Channel Bypass | Owned e-commerce storefronts capture margin from distributor-wholesaler compression. |
| 250ml Gift-Pack Format Expansion | Specialty capacity targets subscription box curation and curated assortments. |
Research Methodology
Bottom-up condiment bottler demand modeling reconciled against top-down glass furnace and PET extrusion capacity tracking forms the analytical core of this study. Primary interviews with hot sauce brand owners, co-packing operations managers, packaging procurement leads at retail chains, and regulatory compliance officers at glass coaters combined with secondary validation from FDA food-contact substance databases, EPA emissions compliance filings, ECHA REACH registration dossiers, and customs trade records on soda ash and silica sand movements.
Input-output matrices map material flows from raw material extraction through furnace operations, mold fabrication, and downstream distribution to end-use bottling facilities across the projection horizon. Segmentation dimensions modeled include material platform, capacity band, closure mechanism, and channel configuration. CAGRs derive from regression analysis of historical volume trajectories against regulatory milestone schedules and capacity expansion announcements. Forecast inputs incorporate energy cost pass-through elasticity and recycled-content mandate compliance thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to furnace fuel switching economics, migration testing clearance timelines at FDA, and state-level labeling mandate adoption cascades. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Lager Market