
 Middle East and Africa Beer Market | 2026-2036
Middle East and Africa Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Beer Market Foresight
Automation in brewhouse control systems is narrowing quality gaps between multinational standards and regional production. Heineken N.V. leverages its Star Brewer program to sustain consistency across African facilities. South African Breweries anchors its Southern African position through captive malting capacity. Castel Group competes through hyper-local brand portfolios tailored to Francophone markets.
Beer in the Middle East and Africa comprises fermented cereal beverages, typically 4-6% alcohol by volume, produced through mashing, boiling, fermentation, and conditioning of malted barley with water, hops, and yeast. The product serves social consumption occasions, refreshment demand, and premium gifting rituals across diverse religious and cultural contexts. Lager dominates volume due to its compatibility with warm climates and mass-market pricing, while ale and stout command disproportionate margin pools in urban specialty bars. The 25-34 consumer age group represents the fastest-expanding cohort, with supermarkets and convenience stores capturing the bulk of off-premise flow.
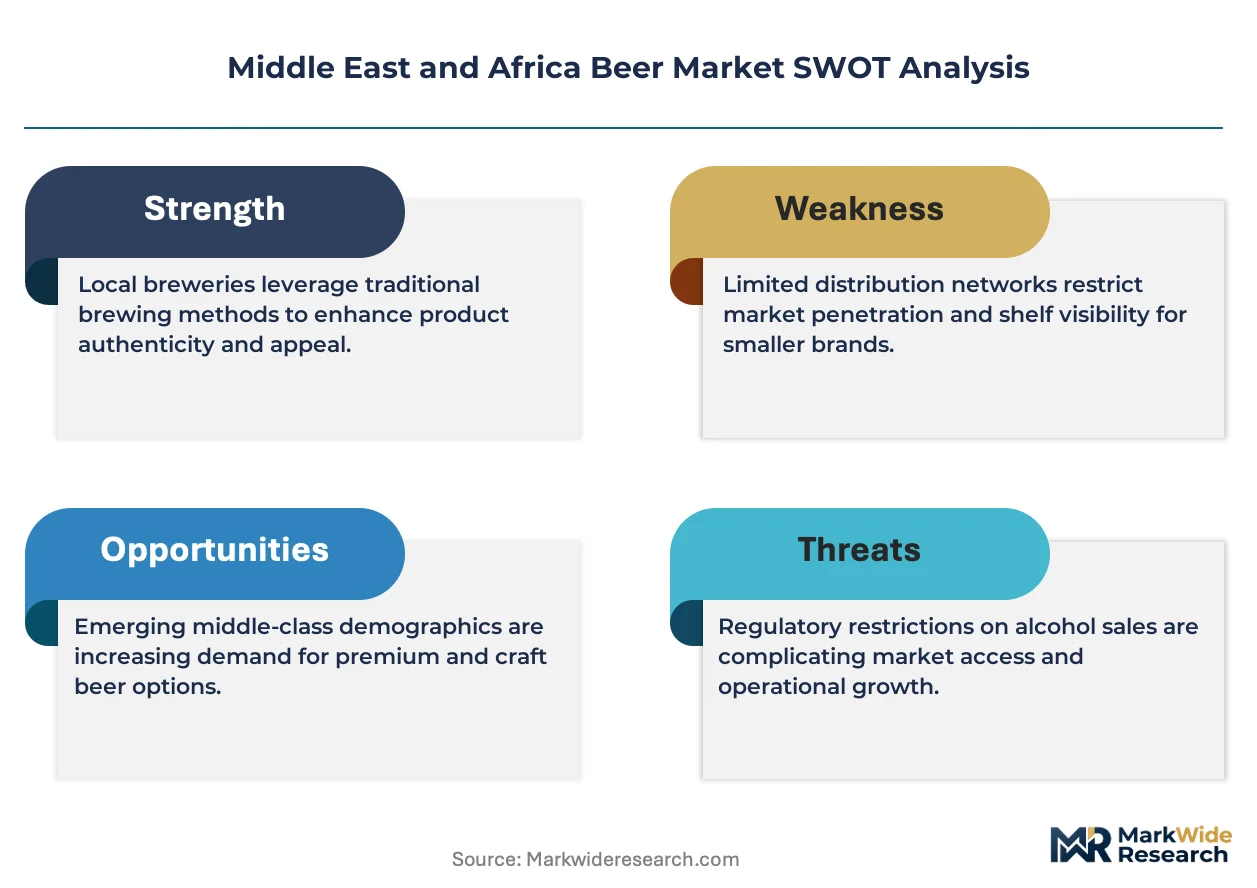
Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) enforces labeling and alcohol content standards, while South Africa's excise regime shapes price-tier architecture through ad valorem taxation. The UAE's strict federal alcohol licensing framework limits on-trade access but permits duty-free and designated-zone distribution. Stakeholders must monitor how shifting excise structures and religious consumption norms reshape channel strategy and portfolio composition.
Market Dynamics
Excise tax volatility across Southern Africa and the Gulf Cooperation Council is compressing margin structures and forcing portfolio rebalancing toward premium-price tiers with inelastic demand elasticity.
Growth Catalysts
- Urbanization density:Lagos, Nairobi, and Johannesburg are generating concentrated on-premise consumption clusters that reward localized distribution infrastructure.
- NAFDAC labeling harmonization:Nigeria's streamlined alcohol content disclosure requirements are reducing cross-border compliance friction for regional brewers.
- Heat-tolerant yeast strains:New fermentation biotechnology is extending shelf stability in ambient-temperature supply chains without cold-chain dependency.
Market Restraints
- Sorghum price volatility:Local grain input costs fluctuate with Sahel rainfall patterns, destabilizing cost-of-goods for indigenous brewing operations.
- Import dependency:Hops and specialty malts concentrate in South African and European supply nodes, exposing Francophone markets to currency-transmission shocks.
- Religious consumption norms:Sharia-compliant jurisdictions including Saudi Arabia and Iran impose absolute prohibitions that eliminate addressable population segments.
Strategic Opportunities
- Ethiopian market opening:Partial privatization of state-owned breweries and foreign investment liberalization is creating greenfield production capacity.
- Non-alcoholic beer formats:Halal-certification pathways and zero-ABV positioning unlock consumption occasions previously excluded from category participation.
- Duty-free channel expansion:Dubai International Airport and Johannesburg OR Tambo are anchoring premium gifting volume with traveler-exclusive SKUs.
Industry Challenges
- Refrigeration infrastructure gaps:Last-mile cold-chain reliability in secondary Nigerian cities and rural Kenya degrades product quality consistency.
- Excise compliance complexity:Ad valorem calculation methodologies vary across South Africa, Botswana, and Namibia, multiplying tax audit exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Beer Market |
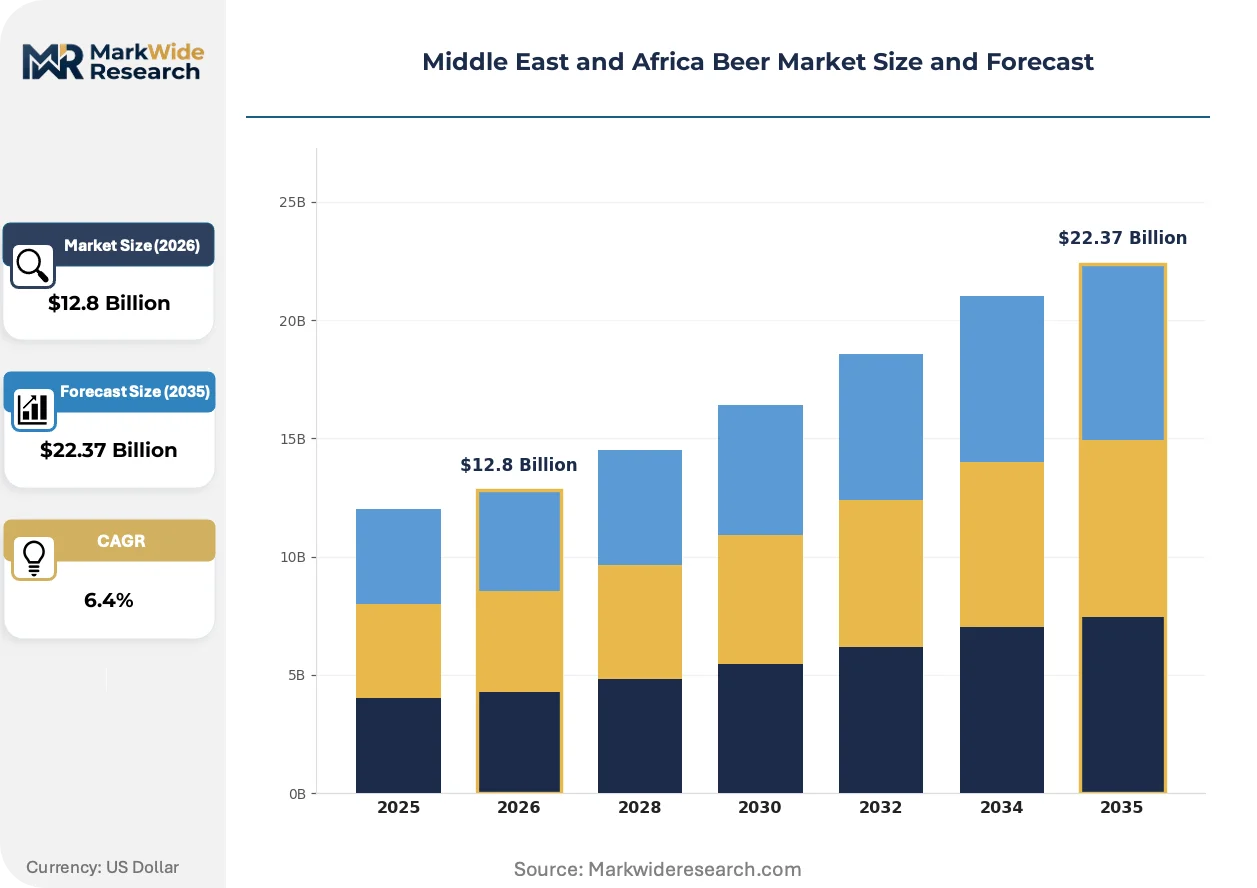
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Porter Consumer Age Group: 18-24, 25-34, 35-44, 45+ Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Bars Flavor Profile: Citrus, Hoppy, Malty, Spicy |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Diageo plc, South African Breweries, Société des Brasseries et Glacières Internationales (Castel Group), Nigerian Breweries Plc, East African Breweries PLC, Al Ahram Beverages Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Beer Market Shifts & Advancements
Digital traceability and fermentation biotechnology are converging to reshape production economics and consumer transparency expectations across the Middle East and Africa brewing landscape.
Automated brewhouse control systems are collapsing quality variance between multinational-scale facilities and smaller regional operations. Nigerian and Kenyan mid-cap brewers are adopting sensor-network fermentation monitoring at accelerating deployment rates. This compression of technical capability thresholds is enabling second-tier producers to meet retail-chain specification requirements previously reserved for integrated multinationals.
South Africa's evolving excise regime is restructuring price-tier architecture through ad valorem taxation bands that escalate with alcohol content. The policy mechanism is compressing volume-share in standard-strength lagers while expanding margin pools in premium and super-premium positioning. Gauteng and Western Cape retail channels are responding with accelerated SKU rationalization toward higher-price, lower-volume portfolios.
Young adult consumers in the 25-34 bracket are rotating consumption occasions from traditional on-trade venues toward home-based social gatherings and delivery-mediated consumption. Supermarkets and convenience stores in Lagos, Nairobi, and Accra are capturing this flow through expanded chiller space allocation and promotional bundling. This channel migration is most visible in Nigeria, where off-premise volume now exceeds on-trade flows in Abuja and select Lagos sub-markets.
Middle East and Africa Beer Market Segmentation
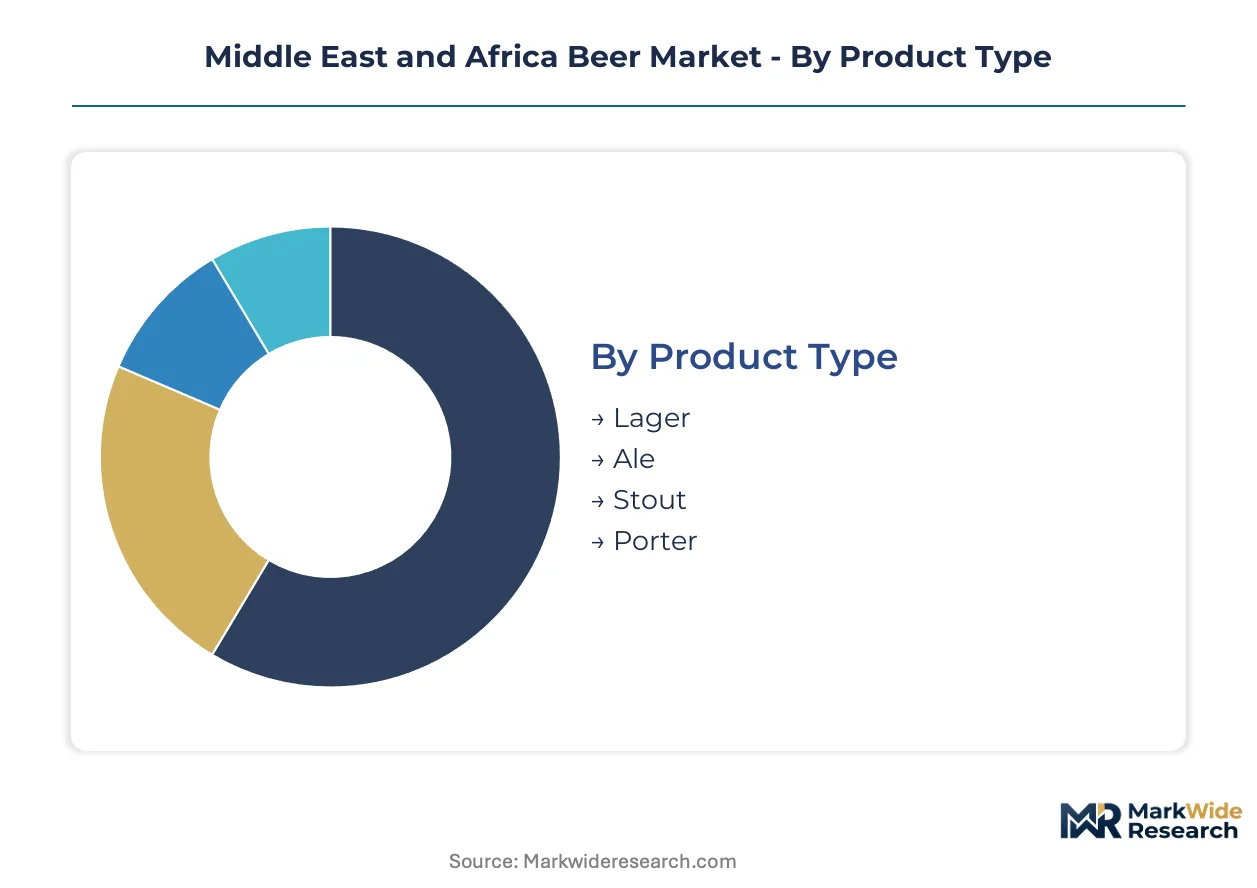
Segmentation in the Middle East and Africa beer market reveals how climate constraints, religious norms, and urban infrastructure shape product development and channel strategy across heterogeneous consumer bases. Understanding these divides enables targeted portfolio allocation between heat-stable formulations and occasion-specific positioning.
Product Type:
Mature lager formats dominate volume throughput, while emerging specialty styles capture margin expansion in urban on-trade clusters.
- Lager:Bottom-fermented at cooler temperatures yielding crisp, pale profiles with 4-5% ABV. Nigerian and South African brewing facilities prioritize lager lines for ambient distribution compatibility and mass-market price accessibility. Lagos and Johannesburg retail chains allocate disproportionate chiller space to standardized lager SKUs.
- Ale:Top-fermented varieties with fruit-forward ester profiles and broader temperature tolerance. Nairobi and Accra specialty bars drive demand for craft ale positioning as differentiation from multinational lager portfolios. Heat-tolerant yeast strains developed in South African R&D labs extend shelf stability without cold-chain dependency.
- Stout:Dark-roasted malt beverages with creamy mouthfeel, historically concentrated in West African markets.
- Porter:Lower-gravity dark beer with chocolate and coffee notes, niche positioning in urban expatriate venues.
Lager retains volume leadership; ale holds the steepest expansion curve.
Consumer Age Group:
Purchasing power concentration varies sharply across generational cohorts, with disposable income thresholds determining premium adoption rates.
- 25-34:Urban professionals with established careers driving premium lager uptake and home-entertainment occasion expansion. Abuja and Lagos sub-markets show this cohort rotating from on-trade to delivery-mediated consumption. Supermarkets capture this flow through promotional bundling and expanded chiller allocation.
- 18-24:Price-sensitive entrants prioritizing accessible standard-strength formats and shared-pack occasions. Kenyan and Nigerian universities anchor volume for economy-tier positioning. Limited disposable income constrains individual premium purchases despite aspirational brand awareness.
- 35-44:Established households with preference for consistent quality and recognized multinational labels.
- 45+:Loyalty-driven segment with lower experimentation rates, concentrated in traditional on-trade venues.
The 25-34 bracket commands premium revenue concentration; 18-24 expands most quickly through volume-base accumulation.
Distribution Channel:
Channel economics reflect infrastructure maturity gaps between primary cities and secondary markets, with cold-chain reliability determining quality-tier accessibility.
- Supermarkets:Formal retail with controlled temperature storage enabling premium and super-premium SKU placement. Lagos and Nairobi supermarket chains are rationalizing toward higher-price, lower-volume portfolios. Off-premise volume in Abuja now exceeds on-trade flows through this channel.
- Convenience Stores:High-frequency neighborhood outlets capturing impulse refreshment demand and single-serve occasions. Ambient-temperature storage favors heat-stable lager formats with extended shelf life. Last-mile distribution density rewards localized depot infrastructure.
- Online Retail:Emerging delivery platforms aggregating home-entertainment demand in connected urban centers.
- Bars:Traditional on-trade with concentrated consumption in Johannesburg, Nairobi, and Lagos entertainment districts.
Supermarkets anchor margin contribution; convenience stores scale fastest through footprint expansion.
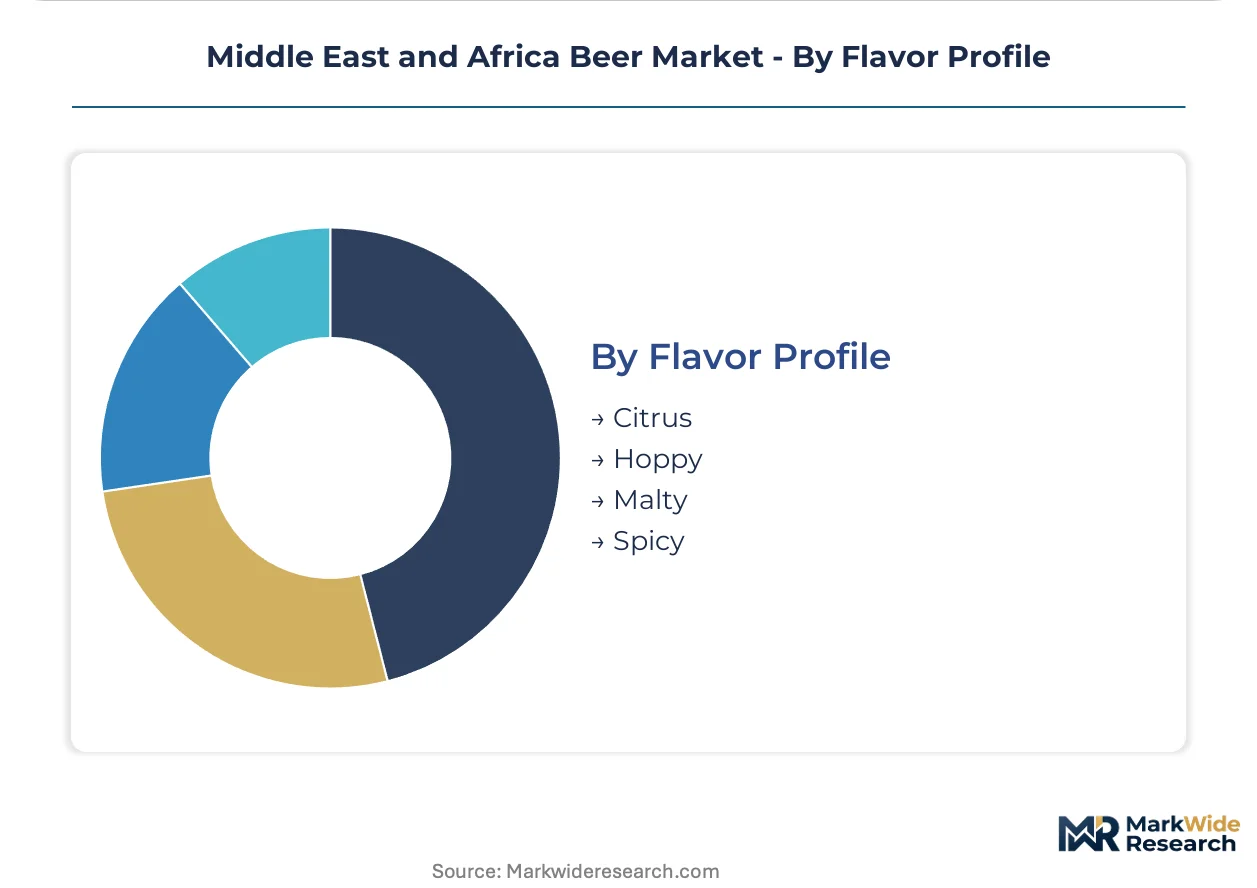
Flavor Profile:
Flavor innovation responds to indigenous ingredient availability and import substitution pressures in hop-dependent formulations.
- Citrus:Bright, acidic profiles achieved through local fruit adjuncts or imported hop varieties with grapefruit and lemon notes. Nigerian brewers leverage domestic citrus supply to reduce import dependency. Lagos consumers show preference for refreshing profiles compatible with humid climates.
- Malty:Caramel and biscuit-forward profiles from specialty malt roasting. South African captive malting capacity enables consistent supply for premium positioning. Sweetness perception appeals to transitioning consumers from sorghum-based traditional beverages.
- Hoppy:Bitterness-forward profiles requiring imported aroma hops, exposing Francophone markets to currency-transmission cost volatility.
- Spicy:Indigenous ingredient integration with ginger, clove, or pepper notes in experimental craft positioning.
Malty formulations retain production cost advantage; citrus profiles gain share fastest through local supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa exports malt and brewing inputs to Nigerian and Kenyan facilities, anchoring regional supply flows. This trade corridor shapes competitive positioning across sub-Saharan markets.
Nigeria
Lagos and Abuja drive premium lager demand through urban professional consumption. NAFDAC enforces streamlined alcohol content disclosure requirements that reduce cross-border compliance friction. The Lagos-Ibadan corridor anchors volume growth through expanded supermarket chiller allocation.
South Africa
Gauteng and Western Cape retail channels concentrate premium and super-premium SKU placement. The country's ad valorem excise regime escalates taxation with alcohol content, compressing standard-lager volume share. Captive malting capacity in the Western Cape secures cost advantages for regional supply.
Kenya
Nairobi anchors craft ale demand in specialty bar clusters as differentiation from multinational portfolios. The national standards regulator oversees labeling harmonization with regional trade protocols. Sensor-network fermentation monitoring is accelerating deployment among mid-cap brewers in the capital.
Ethiopia
Addis Ababa and surrounding industrial zones attract greenfield production investment under partial privatization. The government liberalizes foreign investment rules for state-owned brewery assets. New capacity installations target domestic demand and regional export positioning.
UAE
Dubai International Airport anchors premium gifting volume through duty-free traveler-exclusive SKUs. MOHAP and federal authorities maintain strict licensing frameworks that limit on-trade access. Designated-zone distribution permits circumvent absolute prohibitions in neighboring jurisdictions.
Middle East and Africa Beer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented national markets. The structure tiers between multinational brewers with integrated African operations and regional specialists with hyper-local brand portfolios. Two archetypes dominate: scale-driven multinationals leveraging captive supply chains, and mid-cap national champions exploiting regulatory familiarity. Competitive moves concentrate on portfolio rebalancing toward premium-price tiers and localized distribution infrastructure deployment.
Among the scale-driven multinationals, Heineken N.V. and Anheuser-Busch InBev occupy positions as archetypal integrated operators with continental facility networks. South African Breweries anchors supply-side concentration through backward integration into malting capacity. Castel Group exemplifies the regional specialist model with Francophone market focus. Nigerian Breweries Plc represents the national champion archetype with deep regulatory familiarity in West Africa's largest market.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Carlsberg Group |
| Diageo plc |
| South African Breweries |
| Société des Brasseries et Glacières Internationales (Castel Group) |
| Nigerian Breweries Plc |
| East African Breweries PLC |
| Al Ahram Beverages Company |
| Others |
Supply & Pricing Matrix
Undercapacity in Ethiopian brewing assets is compressing supplier margins while elevating pricing power for South African malt exporters. This utilization asymmetry forces Nigerian and Kenyan buyers into longer contract tenors with indexed raw material clauses.
Pricing Analysis
Cost-plus contracts with malt and hop price indexation dominate procurement between Nigerian brewers and South African suppliers. Three-tier pricing structure across premium, standard, and economy levels differentiates by alcohol content certification and cold-chain reliability. Price compression runs through standard-lager tiers as ad valorem taxation escalates in South Africa and Botswana. Economy-tier consumers in Kenyan university markets exhibit highest price sensitivity, while premium buyers in Lagos and Abuja show inelastic demand.
Supply Chain Analysis
Contract-malting concentration in South Africa's Western Cape and captive brewing capacity in Nigeria's Lagos-Ibadan corridor anchor regional supply. Malted barley draws from South African farms, while aroma hops feed from European import nodes. Single-source vulnerability in hop supply exposes Francophone markets to euro-denominated cost volatility. Distribution runs through temperature-controlled depot networks in primary cities, with ambient-last-mile fallback in secondary Nigerian and Kenyan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa beer market is recovering from excise-induced demand compression as urbanization density in Lagos, Nairobi, and Johannesburg rebuilds on-premise velocity.
For Market Incumbents: Insulate margin pools by deepening backward integration into captive malting capacity in South Africa and securing long-term sorghum supply contracts in Nigeria. Heineken N.V. and South African Breweries must defend against craft ale entrants in Nairobi specialty bars through accelerated SKU rationalization toward heat-tolerant yeast formulations.
For New Entrants and Emerging Players: Establish a beachhead in Ethiopian greenfield production zones under partial privatization rules. The most penetrable white-space sits in non-alcoholic beer formats for Halal-certified distribution in UAE designated zones. Go-to-market leverage rests on duty-free channel partnerships at Dubai International Airport and Johannesburg OR Tambo.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mid-cap Nigerian brewers with NAFDAC regulatory familiarity and supermarket distribution lock-in. Long-term viability centers on portfolio rebalancing toward premium-price tiers with inelastic demand elasticity. Acquisition targets should show sensor-network fermentation monitoring deployment. The signal to monitor is NAFDAC labeling harmonization progress as inflection indicator for cross-border compliance cost reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malting Capacity | South African Breweries secures cost advantage through Western Cape captive supply. |
| Heat-Tolerant Yeast Strain Adoption | Nigerian mid-cap brewers collapse quality variance with multinational technical standards. |
| Duty-Free Channel Expansion | Dubai International Airport anchors premium gifting volume with traveler-exclusive SKUs. |
| Non-Alcoholic Format Certification | Halal positioning unlocks consumption occasions in UAE and Saudi adjacent markets. |
| Sensor-Network Fermentation Monitoring | Kenyan brewers meet retail-chain specifications previously reserved for integrated multinationals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NAFDAC regulatory filings, South African Revenue Service excise disclosures, and trade flow databases. The research combined interviews with brewery operations directors, excise compliance officers at South African Breweries, supermarket category buyers in Lagos, and malt procurement leads in Nairobi. Secondary validation drew from customs records, Nielsen retail audit data, and brewery association production statistics. Bottom-up facility capacity assessments and top-down consumption modeling were triangulated to anchor volume estimates.
Forecast inputs span urbanization density projections, excise regime evolution scenarios, and heat-tolerant biotechnology adoption curves across the analysis window. Segmentation modeling incorporated product type, consumer age bracket, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation with cross-validation against macroeconomic drivers. Specific inputs included Lagos-Ibadan corridor population growth and Ethiopian privatization timeline assumptions.
Sensitivities concentrate around sorghum price volatility from Sahel rainfall patterns and excise recalibration in South Africa and Botswana. Forecasts embed assumptions about NAFDAC harmonization progress and cold-chain infrastructure deployment in secondary Nigerian cities. Quarterly review of malt import volumes, supermarket chiller allocation rates, and craft ale SKU counts in Nairobi is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Beer Processing Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Global Red Wine Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Flavored Whiskey Market