
 Canada Tequila Market | 2026-2036
Canada Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Tequila Market Insights
Super-premium and extra añejo expressions is reorganizing the Canada tequila landscape as consumers trade up from entry-level mixto products. Patron leverages its estate-grown agave narrative and distillery transparency to sustain pricing power in Ontario and Quebec. Don Julio anchors the ultra-premium tier through controlled allocation and aged-stock scarcity. Casamigos competes on celebrity-backed lifestyle positioning that extends distribution into private liquor stores and hospitality channels.
Tequila denotes a distilled spirit produced exclusively from Weber blue agave in designated Mexican states, with blanco bottled immediately after distillation while reposado and añejo undergo oak maturation of two months to one year and one to three years respectively. Blanco retains the largest volume footprint due to its versatility in cocktails and lower price entry point, though añejo commands the deepest margin pools as aged-stock scarcity intensifies. Super-premium price tier positioning concentrates among restaurants and specialty liquor stores where staff education and tasting events convert trial to repeat purchase.
Health Canada enforces compositional standards and allergen labeling under the Food and Drugs Act, while provincial liquor authorities such as the LCBO and SAQ administer import permits, pricing floors, and retail distribution rules that shape market access. The Canadian Food Inspection Agency verifies geographic indication compliance for spirits labeled as tequila. Stakeholders must monitor provincial markup policy shifts and agave supply volatility in Jalisco as dual determinants of portfolio profitability and inventory planning.
Market Dynamics
Agave supply volatility in Jalisco is compressing inventory planning horizons for Canadian importers while Health Canada's labeling enforcement tightens compliance costs across provincial liquor board channels.
Growth Catalysts
- Mixology Culture Maturation:Toronto and Vancouver cocktail bars are converting consumers to sipping tequilas through staff education programs and vertical tasting flights. This on-premise channel now drives premium tier velocity.
- Health Canada GI Verification:The Canadian Food Inspection Agency's geographic indication enforcement is filtering counterfeit agave spirits from retail shelves. Legitimate producers gain shelf space and pricing power.
- Weber Blue Agave Terroir Narratives:Estate-grown single-field expressions are commanding attention in Ontario specialty stores. Consumers pay premiums for harvest-date transparency and tahona-crush provenance.
Market Restraints
- Jalisco Harvest Cyclicality:Seven-year agave maturation creates supply gluts and shortages that destabilize Canadian wholesale pricing. Inventory carrying costs spike during shortage phases.
- Provincial Markup Floors:LCBO and SAQ minimum pricing rules prevent discount entry strategies. New entrants face margin compression before achieving scale.
- RTD Substitution Threat:Canned agave-based cocktails at grocery retail are capturing casual consumption occasions. Tequila's core spirits category loses volume to convenience formats.
Strategic Opportunities
- Alberta Private Retail Expansion:Calgary and Edmonton independent liquor stores lack tequila category depth. Dedicated agave spirits sections with educated staff unlock underserved demand.
- Extra Añejo Collector Segment:Limited-release aged stocks above three years attract connoisseur buyers. Auction-style allocation builds scarcity premiums and direct consumer relationships.
- Sustainable Certification Alignment:Mexico's Consejo Regulador del Tequila environmental standards overlap with Canadian consumer values. Certified sustainable production gains preferential retail placement.
Industry Challenges
- Agave Literacy Gap:Frontline staff at BC Liquor Stores and private retailers lack depth on additive-free distinctions. Training investment requirements burden distributor margins.
- Cross-Provincial Compliance Complexity:Each liquor board maintains distinct label approval timelines and French-language requirements. SKU proliferation strains regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Tequila Market |
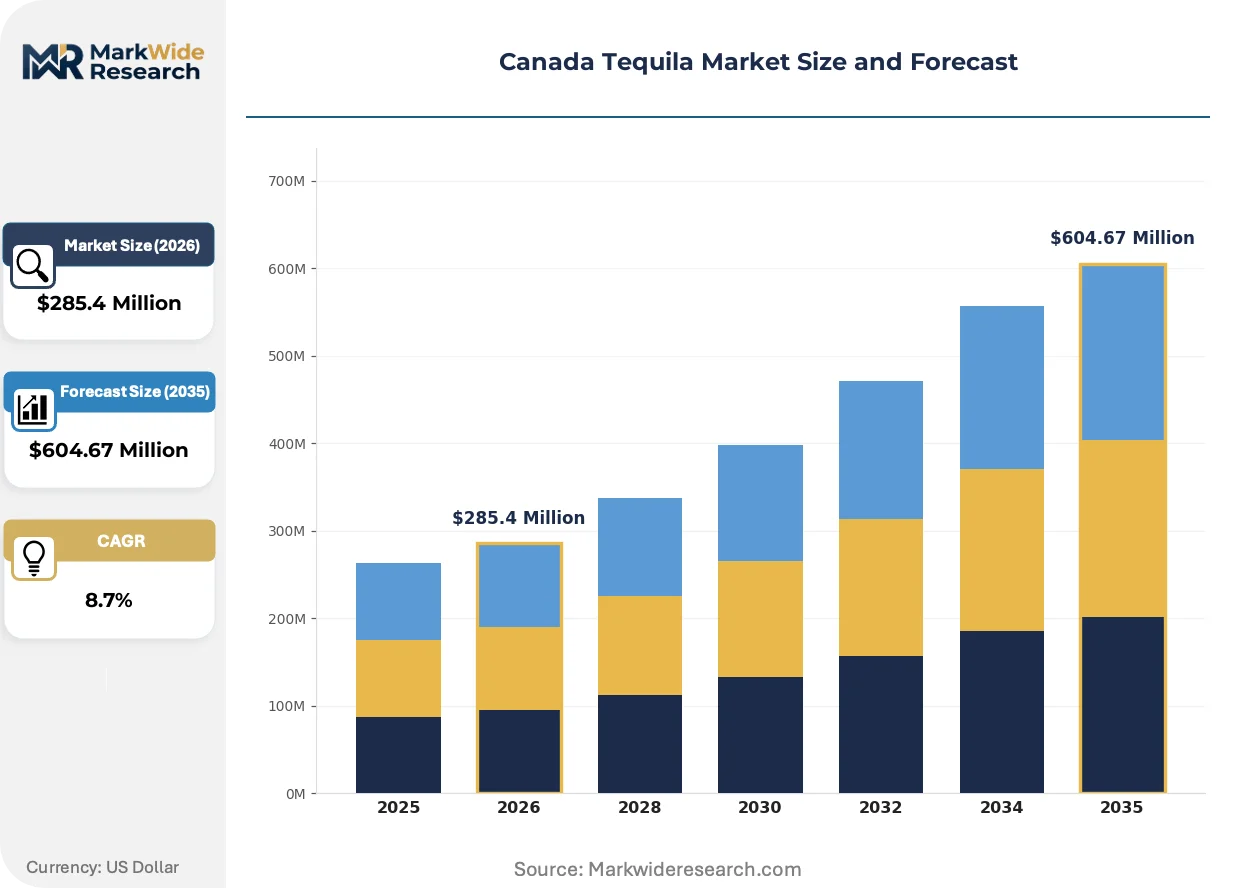
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Customer Type: Retail Consumers, Bar Owners, Restaurants, Distributors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Liquor Stores Price Tier: Premium, Super Premium, Mid Range, Economy |
| Companies Covered | Jose Cuervo, Patron, Sauza, Don Julio, Espolon, Cazadores, 1800 Tequila, El Jimador, Casamigos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Tequila Market Trends and Innovations
Tequila production transparency and consumption occasion expansion are reconfiguring how Canadian buyers evaluate quality and allocate spending across price tiers.
Blockchain-enabled provenance tracking is fragmenting supply chain opacity that previously protected commodity mixto producers. Ontario specialty retailers and Vancouver restaurant groups now demand harvest-lot verification and distillery audit trails. This technology compression forces laggard suppliers to invest in traceability infrastructure or retreat to price-driven channels.
Health Canada's Food and Drugs Act allergen disclosure amendments are tightening label precision requirements for spirits imports. The Canadian Food Inspection Agency now scrutinizes additive declarations and processing aid residues. Ultra-premium brands with clean-label positioning capture shelf space as retailers preempt compliance risk.
Home bartending sophistication is rotating demand toward versatile blanco expressions with distinct agave character. Consumers in Montreal and Toronto are building personal collections spanning multiple terroirs. This consumption-pattern shift pressures brands to deliver educational content and tasting formats beyond traditional on-premise activation.
Canada Tequila Market Segmentation
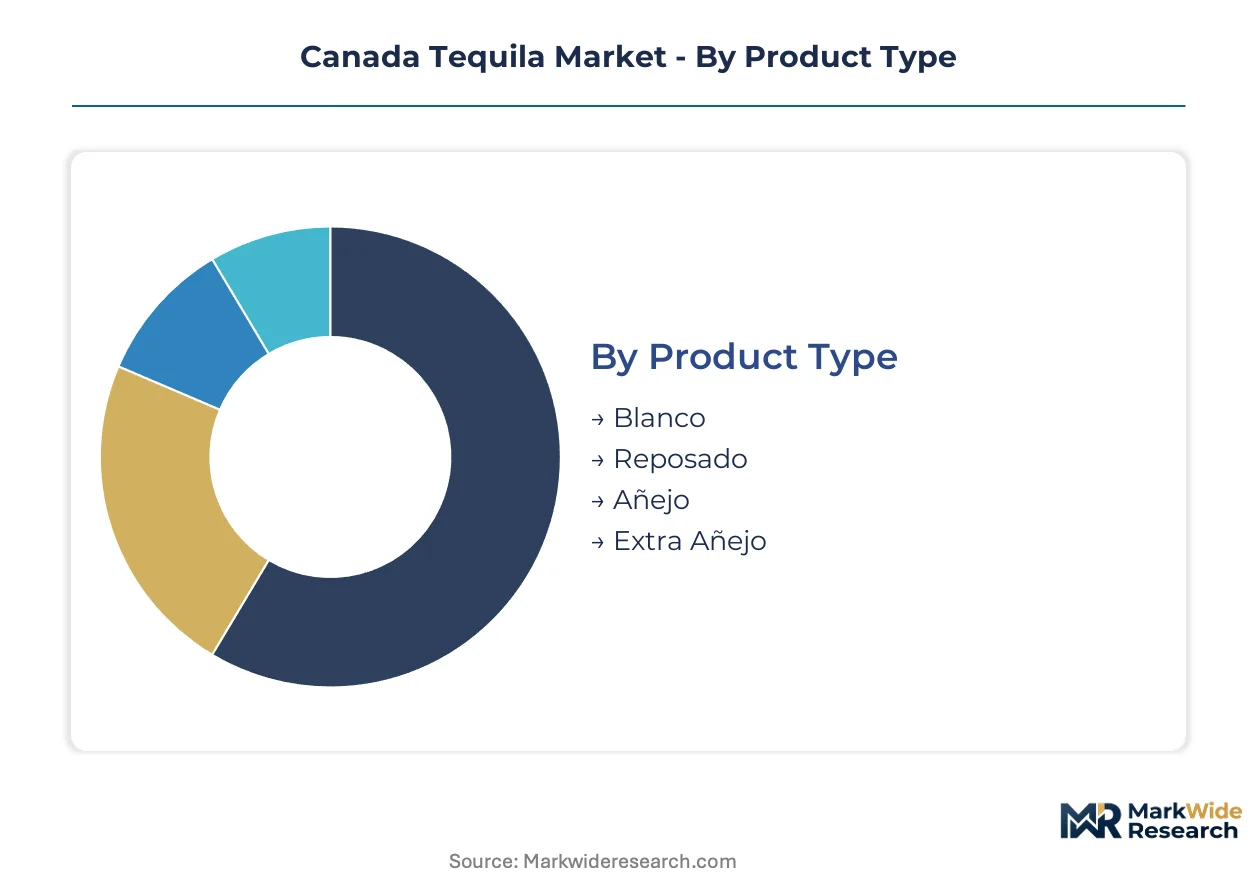
Tequila segmentation in Canada reflects divergent margin architectures across aging categories, channel control points, and provincial regulatory environments. Understanding where value concentrates enables portfolio allocation decisions amid tightening Health Canada compliance and LCBO pricing floors.
Product Type:
Margin pools deepen with oak maturation duration as aged-stock scarcity compounds with agave supply cyclicality in Jalisco.
- Blanco:Unaged spirit bottled immediately after distillation preserves raw agave character and terroir expression. Demand concentrates in Toronto and Vancouver cocktail bars where bartenders prize versatility for margaritas and palomas; volume leadership here masks thinner per-unit margins compared to aged expressions.
- Añejo:One-to-three-year oak maturation develops vanilla, caramel, and spice complexity that commands sipping occasions. Ontario specialty liquor stores and Vancouver restaurant groups drive velocity through staff-guided tasting programs; scarcity premiums expand as harvest-date transparency becomes a purchase trigger.
- Reposado:Two-to-twelve-month barrel rest bridges mixology and sipping use cases with moderate price accessibility.
- Extra Añejo:Extended aging beyond three years targets collector segments through auction-style allocation and direct consumer relationships.
The dominant share belongs to Blanco, while Añejo is closing the gap fastest.
Customer Type:
Channel control over staff education and tasting access determines conversion efficiency from trial to repeat purchase.
- Restaurants:On-premise accounts in Toronto, Vancouver, and Montreal anchor super-premium tier velocity through sommelier-driven pairing programs and vertical flight presentations. Staff depth on additive-free distinctions and tahona-crush methods separates high-performing accounts from commodity-pushing competitors.
- Retail Consumers:Home bartending sophistication in Ontario and British Columbia rotates demand toward versatile blanco expressions with distinct agave character; personal collection building across multiple terroirs pressures brands to deliver educational content beyond traditional activation.
- Bar Owners:Independent cocktail bars prioritize speed-to-serve and cost-per-ounce in high-volume margarita programs.
- Distributors:Provincial liquor board relationships and label approval bandwidth constrain SKU proliferation across LCBO, SAQ, and BC Liquor channels.
Restaurants capture the deepest margin per liter, while Retail Consumers are expanding most quickly.
Distribution Channel:
Regulatory control over shelf placement and pricing floors varies sharply across provincial retail structures.
- Liquor Stores:Government-controlled LCBO, SAQ, and BC Liquor locations dominate volume with mandatory markup rules that prevent discount entry strategies. These channels filter counterfeit agave spirits through Canadian Food Inspection Agency geographic indication verification, advantaging legitimate producers with compliant labeling.
- Specialty Stores:Alberta private retailers and Ontario agency stores offer dedicated agave spirits sections where educated staff unlock underserved demand; estate-grown single-field expressions with harvest-lot transparency command attention here.
- Online Retail:Provincial e-commerce portals extend reach but face French-language labeling requirements and cross-provincial shipping restrictions.
- Supermarkets:Grocery retail in provinces permitting spirit sales captures casual consumption occasions threatened by RTD substitution.
Liquor Stores retain volume leadership, while Specialty Stores are gaining share fastest.
Price Tier:
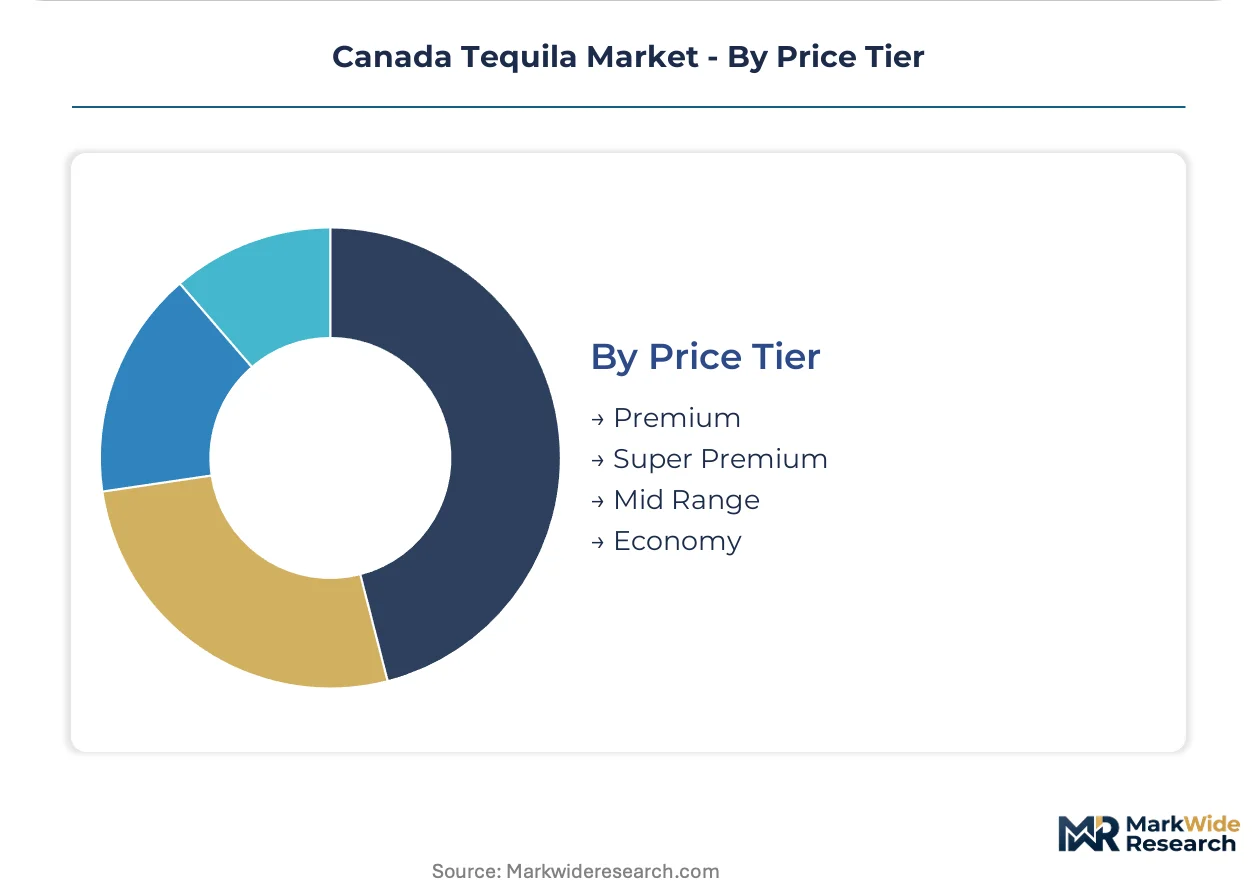
Three-tier pricing structure across premium, super-premium, and economy levels reflects production method transparency and agave sourcing rigor.
- Super Premium:Estate-grown Weber blue agave with tahona-crush or additive-free certification anchors pricing power in Ontario and Quebec. Health Canada's tightening allergen disclosure amendments reward clean-label positioning with preferential retail placement as retailers preempt compliance risk.
- Premium:Controlled allocation and aged-stock scarcity sustain margin pools in Vancouver and Toronto hospitality channels where connoisseur buyers seek limited-release expressions.
- Mid Range:Mixto products and diffuser-processed spirits compete on accessibility for casual cocktail occasions.
- Economy:Price-driven channels retreat as blockchain-enabled provenance tracking fragments supply chain opacity that previously protected commodity producers.
Super Premium holds the dominant share, while Premium is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican distilleries in Jalisco and Guanajuato ship finished tequila through Lázaro Cárdenas and Manzanillo ports for Canadian distribution via Vancouver and Montreal entry points. Provincial liquor boards in Ontario, Quebec, and British Columbia control final-mile retail access through government-monopoly channels.
Ontario
Toronto's cocktail bar density and mixology education programs drive super-premium tequila velocity through on-premise accounts. The LCBO enforces minimum pricing floors and French-language labeling requirements that filter SKU proliferation. Distillery District tasting events and sommelier-led vertical flights convert consumers to estate-grown expressions.
British Columbia
Vancouver's restaurant groups anchor añejo and extra añejo demand through staff-guided pairing programs and harvest-lot transparency requirements. BC Liquor Distribution Branch controls wholesale pricing and shelf placement through government retail monopoly. Yaletown and Gastown hospitality clusters concentrate agave spirit literacy and collector-segment cultivation.
Quebec
Montreal's home bartending sophistication rotates demand toward versatile blanco expressions with distinct terroir character. The SAQ administers import permits and mandatory markup rules that prevent discount entry strategies. Plateau-Mont-Royal specialty retailers build personal collection segments through educational content and tasting formats.
Alberta
Calgary and Edmonton independent liquor stores lack dedicated agave spirits category depth, creating expansion opportunities for educated staff investments. The province's private retail structure permits dedicated shelf sections and competitive pricing flexibility unavailable in government-controlled markets. Southern Alberta distribution networks extend reach into underserved Prairie Provinces consumption.
Canada Tequila Market Competitive Landscape
Listed spirits conglomerates compete with private specialists across estate-grown agave sourcing and additive-free certification dimensions. Market structure concentrates around three to five dominant players controlling super-premium shelf placement, while mid-tier fragmentation persists in mixto and value segments. Strategic archetypes separate estate-distilled heritage brands from celebrity-backed lifestyle entrants and diffuser-processed volume suppliers. Competitive moves center on controlled allocation strategies and direct-to-consumer relationship building through limited-release aged stocks.
Among heritage Mexican distillers, Jose Cuervo, Patron, and Don Julio exemplify contrasting positioning archetypes. Jose Cuervo represents volume-scale heritage with broad distribution through provincial liquor board channels. Patron occupies the estate-grown transparency tier, leveraging tahona-crush provenance and harvest-date verification. Don Julio anchors ultra-premium scarcity through aged-stock allocation discipline and collector-segment cultivation. These three players collectively demonstrate how production method transparency and maturation depth stratify competitive position within Health Canada's tightening labeling enforcement environment.
| Leading Market Players |
|---|
| Jose Cuervo |
| Patron |
| Sauza |
| Don Julio |
| Espolon |
| Cazadores |
| 1800 Tequila |
| El Jimador |
| Casamigos |
| Others |
Pricing and Supply Chain Analysis
Diffuser-processed mixto tequila substitution for tahona-crush artisanal production is compressing supply geography toward Jalisco's industrialized highlands while simultaneously fragmenting pricing economics between commodity volume and scarcity-premium tiers. Canadian provincial liquor boards amplify this bifurcation through LCBO and SAQ markup floors that prevent mid-market entrants from bridging the gap.
Pricing Analysis
Prior-generation diffuser-processed spirits face accelerating price erosion against current-generation tahona-crush estate expressions, while next-generation blockchain-verified single-field releases command scarcity premiums in Ontario specialty channels. Three-tier pricing structure across super-premium, premium, and economy levels stratifies by additive-free certification and harvest-date transparency. Pricing pressure stems from agave supply cyclicality compressing wholesale margins during shortage phases. Bar owners and high-volume on-premise accounts exhibit highest price sensitivity, whereas collector-segment retail consumers demonstrate lowest elasticity for extra añejo allocations.
Supply Chain Analysis
Mexico's Jalisco highlands and Los Altos regions anchor Weber blue agave cultivation, with Guanajuato emerging as secondary terroir for estate-grown expressions. Canadian importers draw from seven-year maturation cycles, oak barrel cooperage in American and French forests, and glass packaging from domestic suppliers. Supply chain risk centers on single-source vulnerability to Jalisco harvest failures and climate-driven agave disease outbreaks. Distribution runs through provincial liquor board monopolies at Vancouver and Montreal ports, with Alberta's private retail channel offering alternative downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada tequila market is recovering from agave shortage cyclicality as Jalisco harvest volumes normalize and aged-stock inventories rebuild across super-premium tiers.
For Market Incumbents: Secure additive-free certification alignment ahead of Health Canada's tightening allergen disclosure amendments. Lock in multi-year agave supply contracts with Jalisco estate growers to defend margin position against harvest volatility. Vertical integration into tahona-crush production capacity insulates pricing power from diffuser-processed commodity encroachment. For New Entrants and Emerging Players: Differentiate on Alberta private retail expansion where Calgary and Edmonton independent stores lack dedicated agave spirits category depth. Target the extra añejo collector segment through auction-style allocation models that bypass LCBO shelf-space constraints. Leverage sustainable certification from Mexico's Consejo Regulador del Tequila as go-to-market entry credential. For Investors and Strategic Acquirers: Secondary-cycle assets sit with celebrity-backed lifestyle brands seeking exit liquidity as consumer sophistication shifts toward production transparency narratives. Long-term viability over the coming decade hinges on additive-free positioning and direct-to-consumer relationship infrastructure. Watch Jalisco agave planting rates as inflection indicator for supply-driven margin compression cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Estate-Grown Agave Sourcing Agreements | Multi-year contracts with Jalisco highland growers lock in tahona-crush supply ahead of shortage cycles. |
| Additive-Free Certification Investment | Clean-label positioning captures LCBO preferential placement as Health Canada enforcement tightens. |
| Alberta Private Retail Channel Buildout | Calgary and Edmonton independent stores offer pricing flexibility unavailable in government-controlled markets. |
| Blockchain Provenance Tracking Deployment | Harvest-lot verification satisfies Vancouver restaurant group transparency demands and filters counterfeit competition. |
| Extra Añejo Direct-to-Consumer Platform | Limited-release aged stock allocation bypasses provincial markup floors and builds collector relationships. |
Research Methodology
A standing panel of tequila brand managers, provincial liquor board category buyers, Toronto and Vancouver sommeliers, and Mexican distillery operations directors provided ongoing calibration throughout the study period. Primary interviews with LCBO and SAQ procurement specialists, Alberta private retail owners, and agave supply chain coordinators were cross-referenced against secondary sources including Health Canada Food and Drugs Act filings, Canadian Food Inspection Agency geographic indication enforcement records, and Consejo Regulador del Tequila production statistics. Bottom-up volume modeling from provincial import data and top-down value triangulation from retail pricing audits converged on segment-level estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including aging category, price tier, distribution channel structure, and provincial regulatory environment. CAGRs were derived from trend-line extrapolation of historical import velocity adjusted for agave planting cycle projections and mixology culture maturation indices. Forecast inputs incorporated Health Canada labeling amendment timelines and provincial liquor board markup policy stability assumptions.
Material uncertainties — agave disease outbreaks, provincial markup policy shifts, and RTD substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about Jalisco harvest normalization and sustained super-premium consumer trading. Recalibration cycles align with material shifts in agave supply availability and Health Canada enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Beer Filter System Market