
 Europe Wine Coolers Market | 2026-2036
Europe Wine Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wine Coolers Market Insights
Connected maintenance subscriptions and software-defined temperature profiling is restructuring how value gets captured in wine cooler commercialization. Climadiff leverages its French manufacturing base to dominate premium built-in segments for hospitality clients. Dunavox anchors its competitive position through specialized dual-zone engineering that sustains precise cellar conditions across varietal categories. Hisense competes aggressively on compressor cost structures, extending its footprint into mid-tier residential channels across Southern Europe.
Europe wine coolers are thermoelectric or compressor-based refrigerated cabinets engineered to maintain stable temperatures between 5°C and 18°C with humidity control and UV-resistant glass, designed to preserve wine quality during short-to-medium-term storage before consumption. Built-in and under-counter configurations command the strongest margin pools as kitchen-integrated aesthetics drive replacement cycles in premium residential renovations, while freestanding units occupy the largest volume position due to lower installation barriers and rental-friendly mobility. Compressor cooling technology leads the commercial installed base for its reliability across restaurant and hotel duty cycles, though thermoelectric systems are gaining traction in compact residential applications where noise reduction and vibration elimination differentiate the user experience.
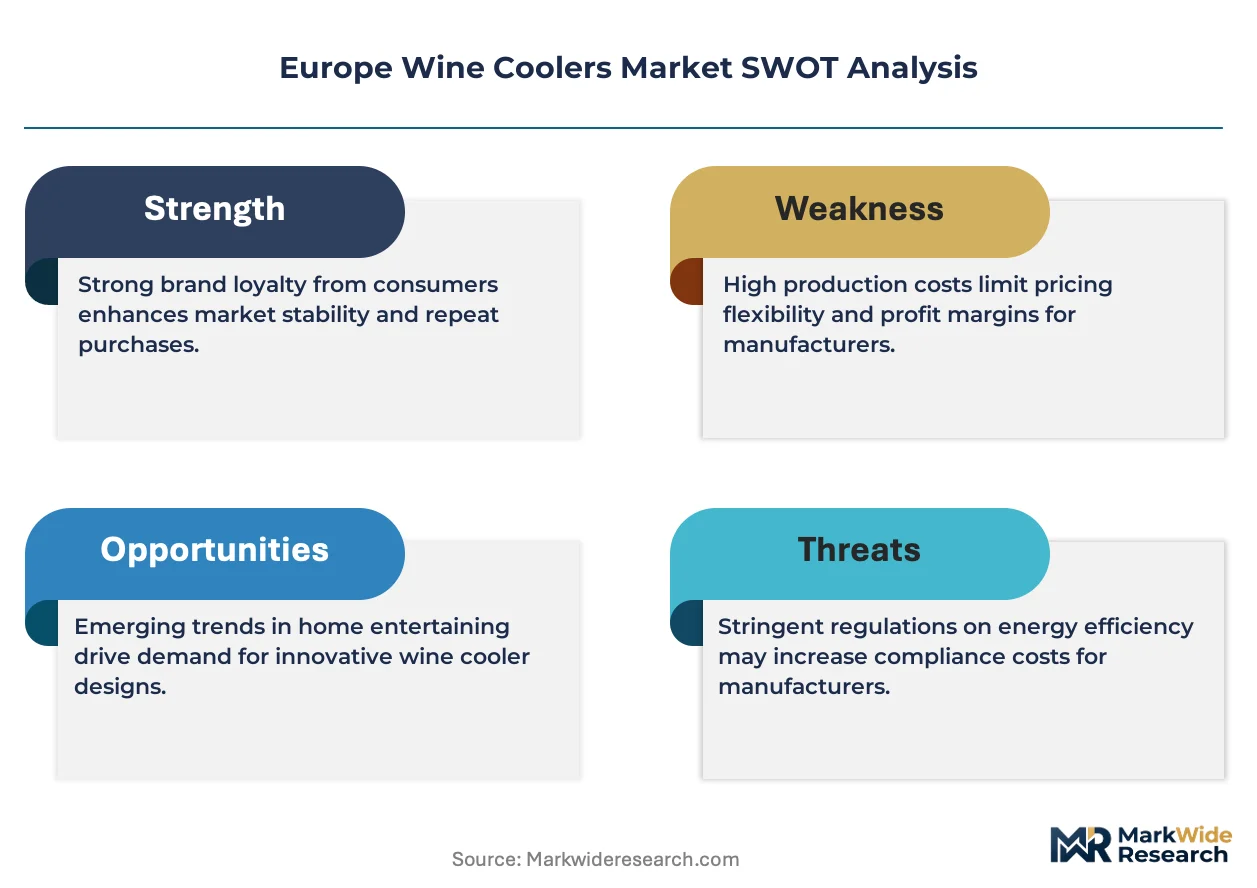
The EU Ecodesign Directive and national transpositions in Germany, France, and Italy mandate escalating energy efficiency minimums for refrigeration equipment, compelling manufacturers to redesign insulation packages and compressor selections. REACH compliance governs refrigerant chemistries and thermal insulation foams, constraining material choices while creating compliance cost tiers that favor scaled producers. Stakeholders must monitor how the EU F-Gas Regulation phase-down reshapes compressor technology roadmaps and whether national building codes in Spain and Portugal accelerate mandatory efficiency thresholds ahead of the common timeline.
Market Dynamics
The EU Ecodesign Directive is compressing margin structures across wine cooler manufacturing, forcing simultaneous redesign of insulation packages, compressor selections, and refrigerant chemistries while hospitality clients demand precision temperature control for expanded by-the-glass programs.
Growth Catalysts
- Restaurant wine-by-the-glass expansion:French, Italian, and Spanish hospitality operators are scaling temperature-controlled storage capacity to support premium pour programs and reduce waste from bottle oxidation.
- REACH-compliant refrigerant transitions:The F-Gas Regulation phase-down is accelerating adoption of lower-GWP compressor technologies that manufacturers position as efficiency differentiators in commercial bids.
- German residential renovation cycles:Premium kitchen refurbishments in Munich, Hamburg, and Berlin are incorporating built-in wine preservation systems as standard appliances in high-value property segments.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing and heat exchanger fabrication face margin pressure from base metal price swings that resist full pass-through in contract pricing.
- Thermoelectric efficiency ceiling:Peltier cooling systems hit thermal performance limits above 50-liter capacity, constraining their addressable market to compact residential applications.
- CE marking compliance layering:Conformity assessment procedures for electrical safety, electromagnetic compatibility, and energy labeling create fixed cost barriers for smaller assembly operations.
Strategic Opportunities
- Portuguese and Spanish hospitality upgrade cycles:Lisbon and Barcelona hotel renovation pipelines lack mature wine service infrastructure, creating first-mover positioning for dual-zone system suppliers.
- Software-defined temperature profiling:Connected maintenance subscriptions enable recurring revenue capture from hospitality clients seeking remote monitoring and predictive service scheduling.
- EU Green Deal renovation wave incentives:National transpositions of building efficiency subsidies in Italy and France are creating partial funding mechanisms for appliance replacement in hospitality and residential settings.
Industry Challenges
- Refrigeration technician specialization gaps:Commercial compressor servicing requires F-gas certification that remains scarce in Southern European secondary cities, elongating repair timelines.
- Dual-zone calibration complexity:Maintaining precise cellar conditions across varietal categories demands sensor integration and control logic that strains quality assurance protocols at volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wine Coolers Market |
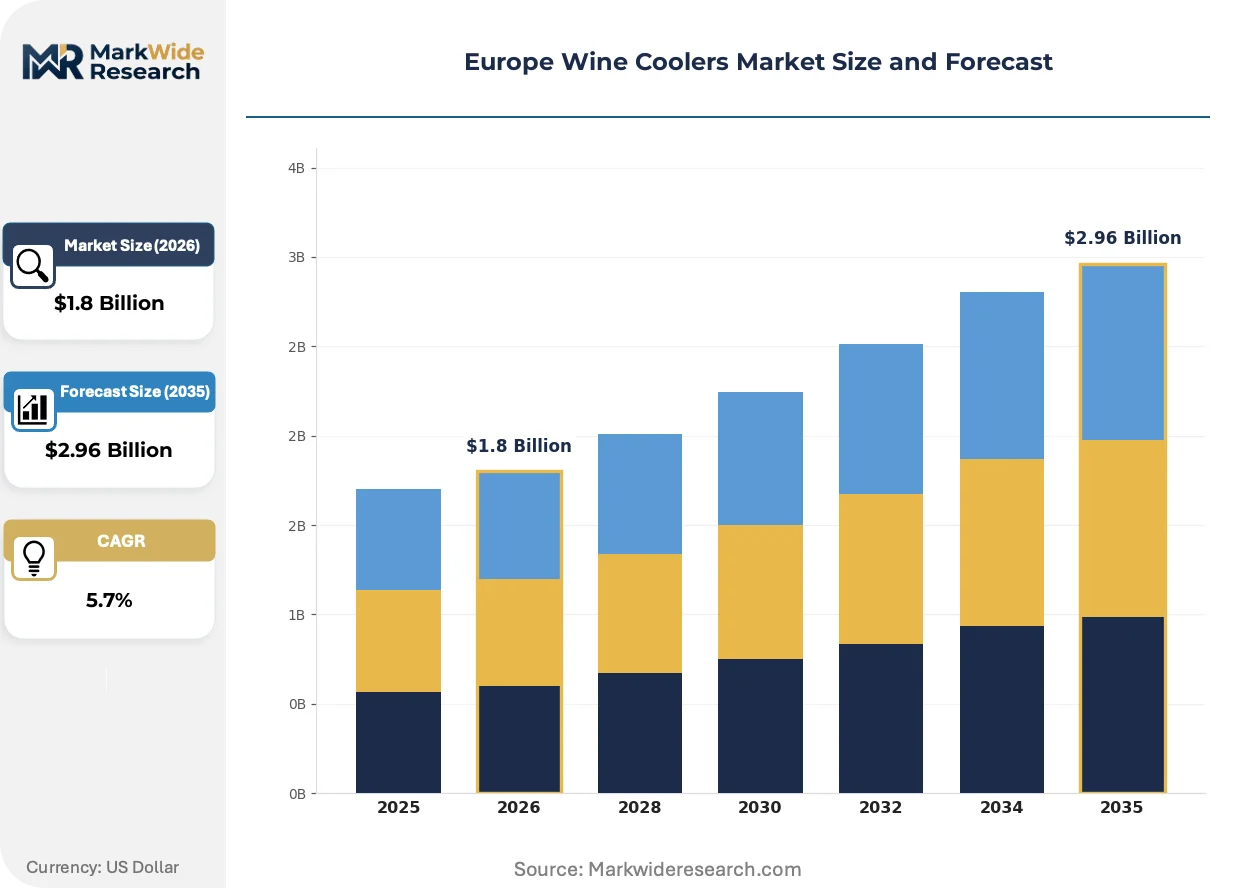
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Under-Counter, Dual-Zone End User: Residential, Restaurants, Hotels, Events Cooling Technology: Thermoelectric, Compressor, Absorption, Hybrid Distribution Channel: Online, Retail Stores, Specialty Shops, Distributors |
| Companies Covered | Climadiff, Dunavox, Smad, Haier, Hisense, AB Electrolux, Liebherr, Miele, Siemens, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wine Coolers Market Trends and Innovations
Connected diagnostics and predictive maintenance capabilities are restructuring value capture in wine cooler commercialization, shifting revenue from hardware transactions to ongoing service relationships while regulatory pressure accelerates hardware redesign cycles.
Variable-speed inverter compressors are rewriting thermal management economics in mid-capacity segments. These systems modulate cooling output to match load conditions rather than cycling on-off, reducing energy consumption and vibration transmission. Hospitality operators in France and Italy are specifying inverter technology for cellar rooms and back-bar installations where noise control affects dining atmosphere. The technology is compressing the performance gap between premium built-in units and standard commercial cabinets.
The EU F-Gas Regulation phase-down is mandating refrigerant transitions that cascade through compressor supply chains. Manufacturers must qualify new thermal working fluids and redesign seal packages while maintaining warranty terms. Germany's national implementation through the Chemicals Climate Protection Ordinance imposes earlier compliance deadlines than the EU baseline, forcing accelerated inventory transitions for products sold into that market.
Subscription-based maintenance contracts are displacing transactional service calls in commercial hospitality accounts. Operators in Spain and Portugal are bundling remote temperature monitoring, filter replacement scheduling, and priority technician dispatch into annual agreements. This shift transfers operational risk from venue managers to equipment suppliers while creating predictable revenue streams that hardware margins alone cannot sustain.
Europe Wine Coolers Market Segmentation
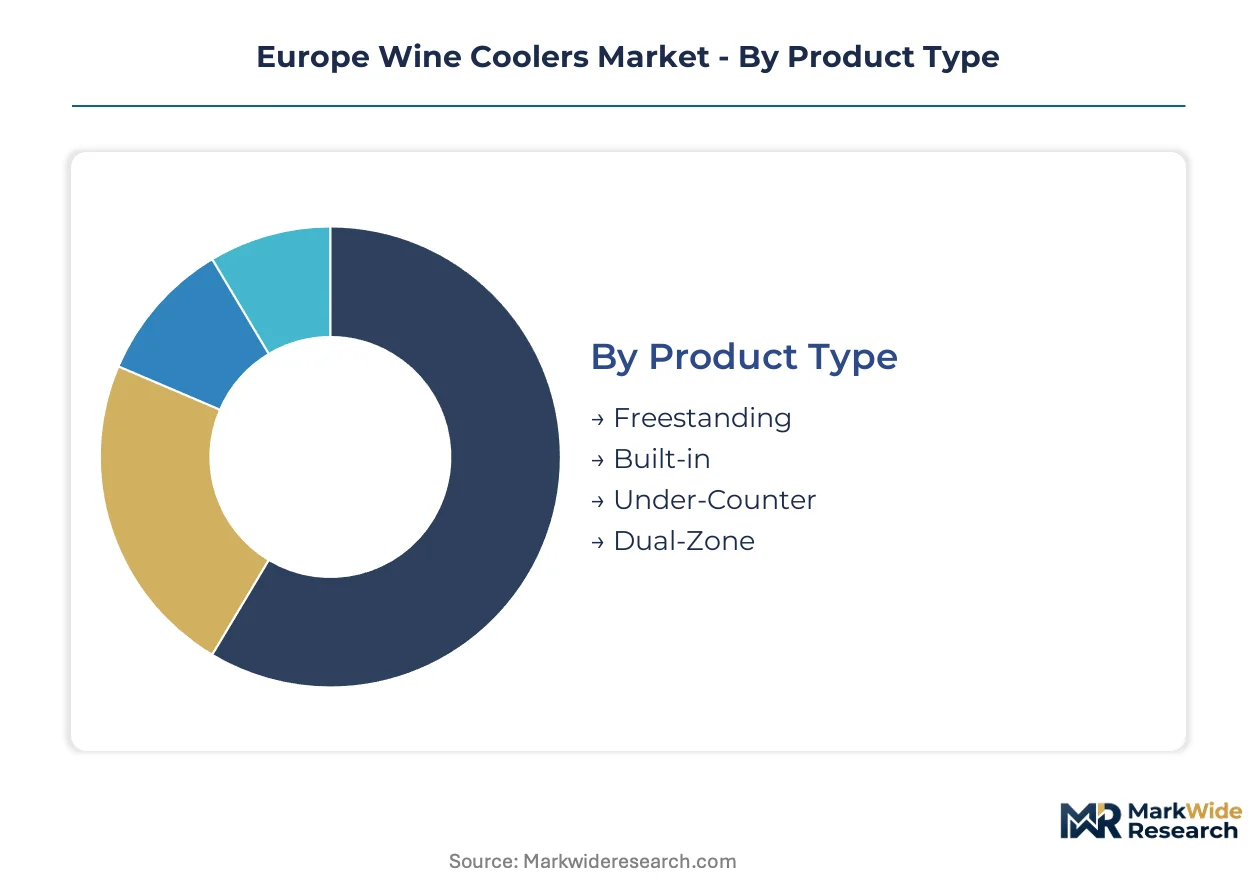
Wine cooler segmentation in Europe tracks divergent supply chain configurations across installation requirements, cooling physics, and channel economics. Manufacturers calibrate production lines to distinct margin pools where built-in systems command premium positioning against commoditized freestanding volumes.
Product Type:
Supply concentration tilts toward integrated kitchen solutions as German and French cabinetry manufacturers specify captive cooler dimensions.
- Freestanding:Self-contained units with finished exteriors deploy compressor or thermoelectric cooling across 20-300 liter capacities. Spanish and Portuguese rental markets drive volume here, where mobility outweighs installation permanence and price sensitivity limits margin extraction.
- Built-in:Front-venting cabinets engineered for seamless kitchen integration achieve the steepest expansion trajectory as Munich and Hamburg renovation cycles normalize wine preservation alongside dishwashers and ovens. REACH-compliant insulation and F-Gas-regulated compressors differentiate qualified suppliers.
- Under-Counter:Compact built-in variants sized for standard cabinetry footprints serve space-constrained urban kitchens in Paris and Milan.
- Dual-Zone:Independent temperature chambers accommodate simultaneous red and white service temperatures, penetrating hospitality accounts in Bordeaux and Tuscany where varietal breadth matters.
Today's leader: Built-in. Tomorrow's challenger: Dual-Zone.
End User:
Cost tier stratification separates premium residential renovations from price-pressured hospitality procurement.
- Residential:Individual consumers purchasing through retail or online channels prioritize noise reduction and aesthetic integration. German kitchen studios specify built-in units as standard in properties above defined value thresholds.
- Restaurants:French, Italian, and Spanish operators expanding by-the-glass programs require precise temperature control and rapid bottle recovery. F-Gas certification constraints on service technicians elongate equipment replacement cycles in Southern Europe.
- Hotels:Lisbon and Barcelona renovation pipelines lack mature wine infrastructure, creating specification opportunities for dual-zone back-bar systems.
- Events:Temporary rental demand concentrates in summer tourism corridors where mobile thermoelectric units serve outdoor service requirements.
Residential commands installed value. Restaurants capture fastest volume growth.
Cooling Technology:
Application requirements dictate thermal physics selection across noise, vibration, and capacity constraints.
- Thermoelectric:Peltier-effect cooling eliminates compressor vibration and operates silently below 50-liter capacities. Compact residential applications in noise-sensitive urban apartments favor this technology despite efficiency ceilings that bar commercial deployment.
- Compressor:Vapor-compression systems with variable-speed inverter modulation dominate commercial hospitality for reliability across continuous duty cycles. EU Ecodesign Directive efficiency minimums force simultaneous redesign of insulation packages and refrigerant selections.
- Absorption:Ammonia-based cooling operates without moving parts in off-grid or silent-critical installations, occupying niche hospitality positioning.
- Hybrid:Combined thermoelectric-compressor architectures attempt to bridge efficiency and silence trade-offs, gaining limited traction in mid-capacity residential segments.
Compressor holds commercial lock-in. Thermoelectric defends residential compact segments.
Distribution Channel:
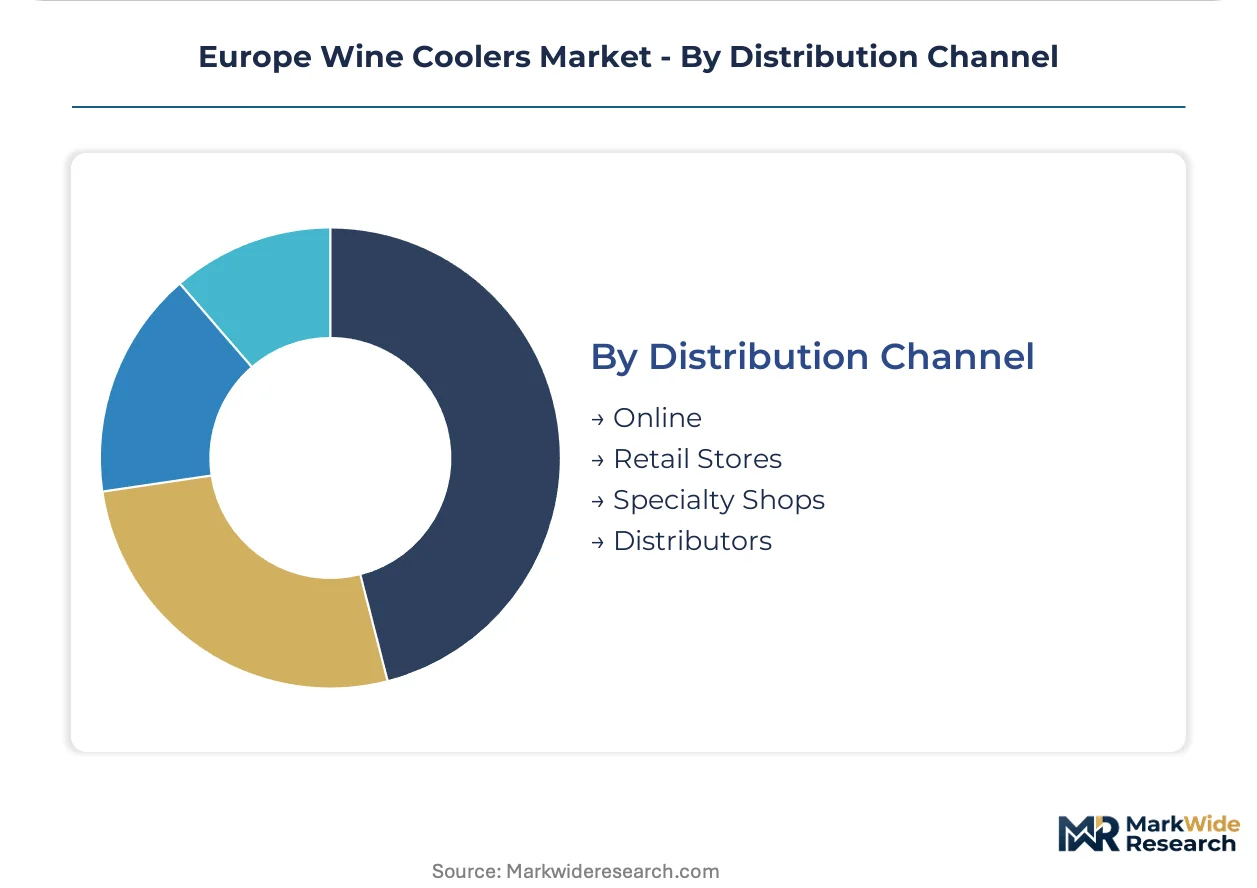
Volume flows through divergent channel economics where specialty expertise competes against digital convenience.
- Online:E-commerce platforms aggregate freestanding and compact thermoelectric demand, with Southern European consumers accepting delivery logistics for price transparency.
- Retail Stores:Big-box and electronics chains stock mid-tier compressor units, serving replacement demand with immediate fulfillment advantages.
- Specialty Shops:Wine merchants and kitchen design studios consult on built-in and dual-zone specifications, capturing margin through installation coordination and cellar planning expertise in France and Italy.
- Distributors:B2B channels project-manage hospitality procurement across multi-unit restaurant and hotel contracts, bundling maintenance subscriptions and F-Gas-compliant service networks.
Specialty shops anchor premium specification. Distributors capture hospitality recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany captures premium residential renovation value, while France concentrates hospitality specification power through its wine service infrastructure heritage.
Germany
Munich, Hamburg, and Berlin renovation cycles normalize built-in wine preservation as standard kitchen appliances in high-value properties. The Chemicals Climate Protection Ordinance accelerates F-Gas Regulation compliance timelines beyond EU baselines. Bavaria's kitchen studio networks specify REACH-compliant integrated systems for properties above defined value thresholds.
France
Bordeaux and Lyon hospitality operators expand by-the-glass programs requiring precise temperature-controlled storage capacity. CE marking conformity assessment procedures layer electrical safety and energy labeling requirements on equipment imports. Climadiff leverages its French manufacturing base to dominate premium built-in segments for restaurant and hotel clients.
Italy
Tuscany and Piedmont wine tourism corridors drive dual-zone system demand across hospitality renovation pipelines. The EU Ecodesign Directive transposition mandates escalating efficiency minimums for refrigeration equipment sold into Italian markets. Milan kitchen design studios consult on built-in specifications, capturing margin through installation coordination.
Spain
Barcelona and Madrid hotel renovation cycles lack mature wine service infrastructure, creating specification opportunities for back-bar system suppliers. National building codes in Spain may accelerate mandatory efficiency thresholds ahead of common EU timelines. Southern European secondary cities face F-gas certification scarcity that elongates commercial compressor repair timelines.
United Kingdom
London residential developments incorporate under-counter wine preservation in space-constrained urban kitchens. Post-Brexit regulatory divergence from EU Ecodesign frameworks creates parallel compliance pathways for equipment suppliers. Southeast England kitchen retailers stock mid-tier compressor units serving replacement demand with immediate fulfillment.
Europe Wine Coolers Market Competitive Landscape
Top-tier vendors anchor premium built-in and dual-zone specification channels, while mid-tier competitors compete on compressor cost structures and volume throughput. The vendor base stratifies across manufacturing scale tiers with distinct margin extraction models. Three archetypes dominate: heritage European appliance manufacturers, Asian electronics conglomerates with refrigeration divisions, and specialized climate-control engineering firms. Capacity expansion in thermoelectric compact segments and strategic partnerships for F-Gas-compliant compressor sourcing represent the dominant competitive vectors reshaping positioning.
Within the heritage European tier, Liebherr and Miele exemplify premium built-in specification power through kitchen integration partnerships. Hisense occupies a position at the scale-driven end of mid-tier residential channels, competing aggressively on compressor cost structures across Southern Europe. Climadiff anchors the specialized climate-control archetype, leveraging geographic proximity to French hospitality clients. These three represent distinct strategic postures: heritage premium integration, Asian volume manufacturing, and regional specialist engineering.
| Leading Market Players |
|---|
| Climadiff |
| Dunavox |
| Smad |
| Haier |
| Hisense |
| AB Electrolux |
| Liebherr |
| Miele |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists across France and Italy anchor premium built-in manufacturing, their patient capital allowing decade-long kitchen integration partnerships that Asian volume producers cannot replicate, while their concentrated ownership structures enforce pricing discipline through direct margin oversight rather than quarterly earnings pressure.
Pricing Analysis
Capacity additions in China are reshaping price floors for compressor-based freestanding units, compressing margins in Southern Europe's mid-tier residential channels. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant built-in systems with F-Gas-certified compressors from basic thermoelectric imports. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Hisense and Haier leverage scale manufacturing. Spanish and Portuguese rental markets exhibit highest price sensitivity; German kitchen studios show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese compressor motor and control electronics suppliers, where COVID-era consolidation eliminated alternative sources for mid-capacity inverter units. Manufacturing concentrates in China, Germany, and France, with final assembly drawing from Italian cabinetry partnerships for built-in integration. Raw material dependencies include copper windings, aluminum heat exchangers, and REACH-compliant polyurethane foam insulation. Tariff exposure on Chinese electronics imports represents the dominant structural risk. Distribution runs through B2B project distributors for hospitality and specialty kitchen studios for premium residential.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe wine coolers function as a stable compounder anchored by renovation-driven replacement cycles in German residential and hospitality upgrade pipelines across France, Italy, and Spain.
For Market Incumbents: To counter thermoelectric disruption in compact residential segments, Liebherr and Miele should deepen backward integration into REACH-compliant insulation supply and accelerate F-Gas-certified service network certification in Southern European secondary cities. Channel control through captive kitchen studio partnerships remains the priority defensive lever. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most viable entry vector for Portuguese and Spanish hospitality accounts lacking mature wine infrastructure. Lisbon and Barcelona hotel renovation pipelines represent the most penetrable white-space. White-label dual-zone specification for regional distributor brands provides the cleanest go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized climate-control engineering firms with French or Italian manufacturing footprints and established F-Gas compliance roadmaps. Long-term viability over a 5-10 year window rests on software-defined service revenue attachment rates. The signal to watch is connected maintenance subscription penetration in hospitality accounts as a leading indicator of recurring revenue quality.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Inverter Compressor Adoption | Reduces energy consumption and vibration transmission for French and Italian hospitality operators. |
| REACH-Compliant Insulation Redesign | Meets EU Ecodesign Directive minimums while differentiating premium built-in specifications. |
| Connected Maintenance Subscription Launch | Captures recurring revenue from Spanish and Portuguese hotel operators seeking operational risk transfer. |
| Dual-Zone Calibration Software Development | Enables precise cellar conditions across Bordeaux and Tuscany varietal service requirements. |
| F-Gas Certification Network Expansion | Addresses technician scarcity in Southern European secondary cities that elongates repair timelines. |
Research Methodology
Coverage spans Western Europe, with primary inputs from each national market, combining structured interviews with kitchen studio procurement leads, hospitality operations directors, refrigeration equipment distributors, and F-Gas-certified service technicians with secondary validation through EU Ecodesign Directive regulatory filings, REACH compliance databases, and national building code transpositions. Bottom-up manufacturer shipment data triangulates against top-down renovation spend estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include installation type, cooling technology, end-use sector, and distribution channel. CAGRs derive from logistic diffusion curves fitted to replacement cycle data and hospitality capex intentions. Industry-specific forecast inputs incorporate German kitchen renovation permit flows and French restaurant by-the-glass program expansion rates.
Regulatory timeline acceleration, copper price volatility, and thermoelectric efficiency breakthroughs are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about F-Gas phase-down compliance pacing and national subsidy program uptake. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Absinthe Market