
 Food and Beverages Color Fixing Agents Market | 2026-2036
Food and Beverages Color Fixing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverages Color Fixing Agents Market Analysis
Specialty ingredient distribution is fragmenting as regional distributors lose ground to direct procurement platforms and consolidated food-service networks. Chr. Hansen Holding A/S leverages its fermentation-derived portfolio to anchor premium positioning in natural color-fixing solutions. Sensient Technologies competes through integrated color systems that extend from pigment extraction to finished application support. Kerry Group sustains scale advantages in blended curing systems for processed meat manufacturers across multiple continents.
Food and beverages color fixing agents comprise chemical compounds—principally sodium nitrite, sodium nitrate, and ascorbic acid derivatives—that bind with myoglobin to stabilize cured-meat color against oxidation and light degradation, typically dosed at 120–200 ppm in finished products. Natural color fixers, including celery powder and cherry-derived nitrite sources, capture expanding share as processors reformulate around EFSA and FDA scrutiny of synthetic nitrite safety claims. Powder formulations dominate volume in cured meat applications, while liquid concentrates lead in beverage stabilization where uniform dispersion matters. Synthetic agents still occupy the largest revenue pool, though margin compression from regulatory pressure and consumer preference shifts erodes their historic premium.
FDA's color additive regulations and USDA-FSIS labeling mandates govern nitrite usage thresholds and disclosure requirements in the United States, while EFSA's ongoing re-evaluations of nitrosamine formation risks reshape permissible applications across Europe. The EU Green Deal's chemical sustainability targets and REACH compliance obligations compound reformulation pressures for exporters serving both markets. Stakeholders must monitor evolving maximum residue limits and invest in natural alternative validation to preserve market access across jurisdictions with divergent safety benchmarks.
Market Dynamics
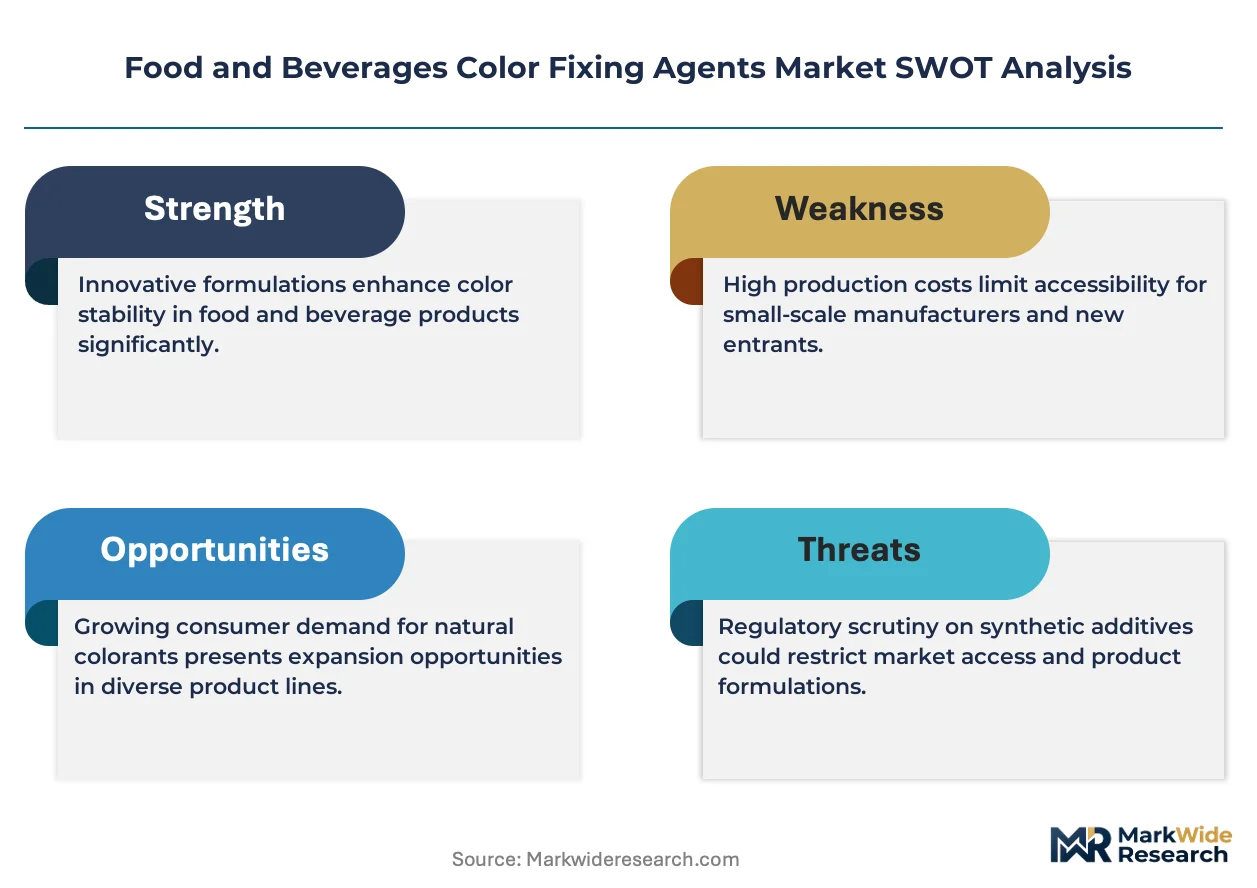
EFSA's nitrosamine risk re-evaluation is forcing processed meat formulators across Europe to abandon synthetic nitrite curing systems and validate natural alternatives before 2027 enforcement deadlines. This regulatory inflection compresses reformulation timelines and redistributes competitive advantage toward fermentation-derived ingredient suppliers.
Growth Catalysts
- EFSA Additive Re-evaluation:The 2023-2027 re-assessment of nitrite safety creates immediate replacement demand for celery powder and cherry-derived nitrite sources in German and Italian cured meat production.
- Clean-Label Meat Processing:Retailers in France and Spain now mandate nitrite-free claims on premium charcuterie, compelling processors to adopt natural color-fixing systems regardless of cost premiums.
- Fermentation Technology Maturation:Bioprocess engineering advances reduce natural nitrite production costs by half, enabling price parity with synthetic alternatives in high-volume applications.
Market Restraints
- Input Cost Volatility:Celery powder supply concentrates in California and Michigan growing regions, exposing European processors to dollar-denominated agricultural commodity swings and climate yield risk.
- Technical Performance Gaps:Natural nitrite sources deliver inconsistent residual nitrite levels compared to synthetic sodium nitrite, complicating shelf-life guarantees for export-bound products.
- Regulatory Asymmetry:USDA-FSIS labeling rules permit "uncured" claims only with specific disclosure language, blocking unified global packaging for multinational meat brands.
Strategic Opportunities
- Underpenetrated Beverage Applications:Ascorbic acid derivatives stabilize color in fruit juices and sports drinks, a segment where synthetic fixer penetration remains below fifteen percent in Brazil and Mexico.
- EU Green Deal Chemical Targets:REACH compliance incentives favor bio-based color fixers, creating subsidy-accessible market entry for fermentation-derived ingredient platforms.
- Direct Procurement Platforms:Digital ingredient marketplaces disintermediate regional distributors, allowing natural fixer suppliers to capture margin previously lost to layered distribution in Southern European markets.
Industry Challenges
- Reformulation Timeline Compression:EFSA's phased implementation demands simultaneous stability testing, sensory validation, and supply chain qualification within eighteen-month windows.
- Analytical Capability Gaps:Natural nitrite quantification requires mass spectrometry methods unfamiliar to quality control labs optimized for colorimetric synthetic nitrite assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverages Color Fixing Agents Market |
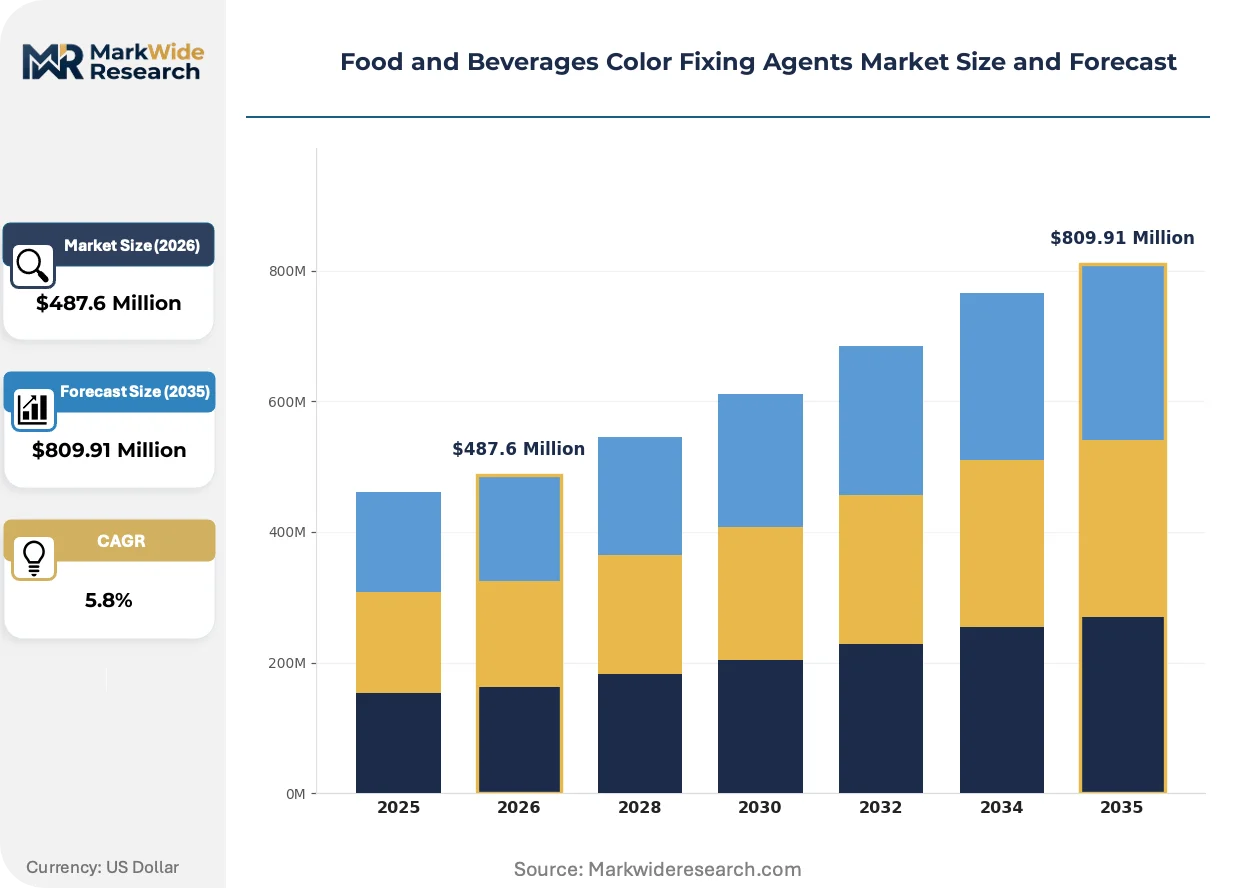
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Natural, Organic, Inorganic Application: Beverages, Dairy Products, Snacks, Confectionery End User: Food Manufacturers, Beverage Producers, Retailers, Food Service Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Chr. Hansen Holding A/S, Sensient Technologies, Kerry Group, BASF SE, Givaudan (Naturex), Archer Daniels Midland (ADM), DSM-Firmenich, Merck KGaA, Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverages Color Fixing Agents Market Emerging Trajectories
Fermentation-derived color stabilization is displacing chemical synthesis as the dominant production paradigm, with biomanufacturing scale-up determining competitive survival. Three interconnected developments are restructuring ingredient supply economics and buyer-processor relationships.
Bioprocess engineering for natural nitrite generation is migrating from pilot-scale demonstration to industrial fermentation infrastructure. German and Danish meat processors now specify fermentation-derived celery powder in tender documents, compressing synthetic sodium nitrite volumes in premium cured sausage categories. This technology migration from laboratory to tonnage production enables price convergence with conventional curing salts by 2027.
REACH authorization requirements for nitrite-based substances are tightening impurity thresholds and demanding expanded toxicological dossiers from remaining synthetic suppliers. The industrial consequence is withdrawal of several legacy nitrite formulations from the EU market, concentrating supply among dossier-compliant manufacturers. Small and mid-sized Spanish and Portuguese cured meat exporters face disproportionate compliance burdens relative to integrated multinational processors with in-house regulatory affairs capacity.
Ingredient sourcing decisions now prioritize verified supply chain documentation over historical supplier relationships. French and Italian retail chains audit nitrite provenance through blockchain-tracked certificates, displacing spot-market purchasing for color-critical applications. This verification-driven procurement pattern concentrates volume among suppliers with integrated farm-to-fermentation traceability systems, marginalizing traders without captive agricultural supply.
Food and Beverages Color Fixing Agents Market Segmentation
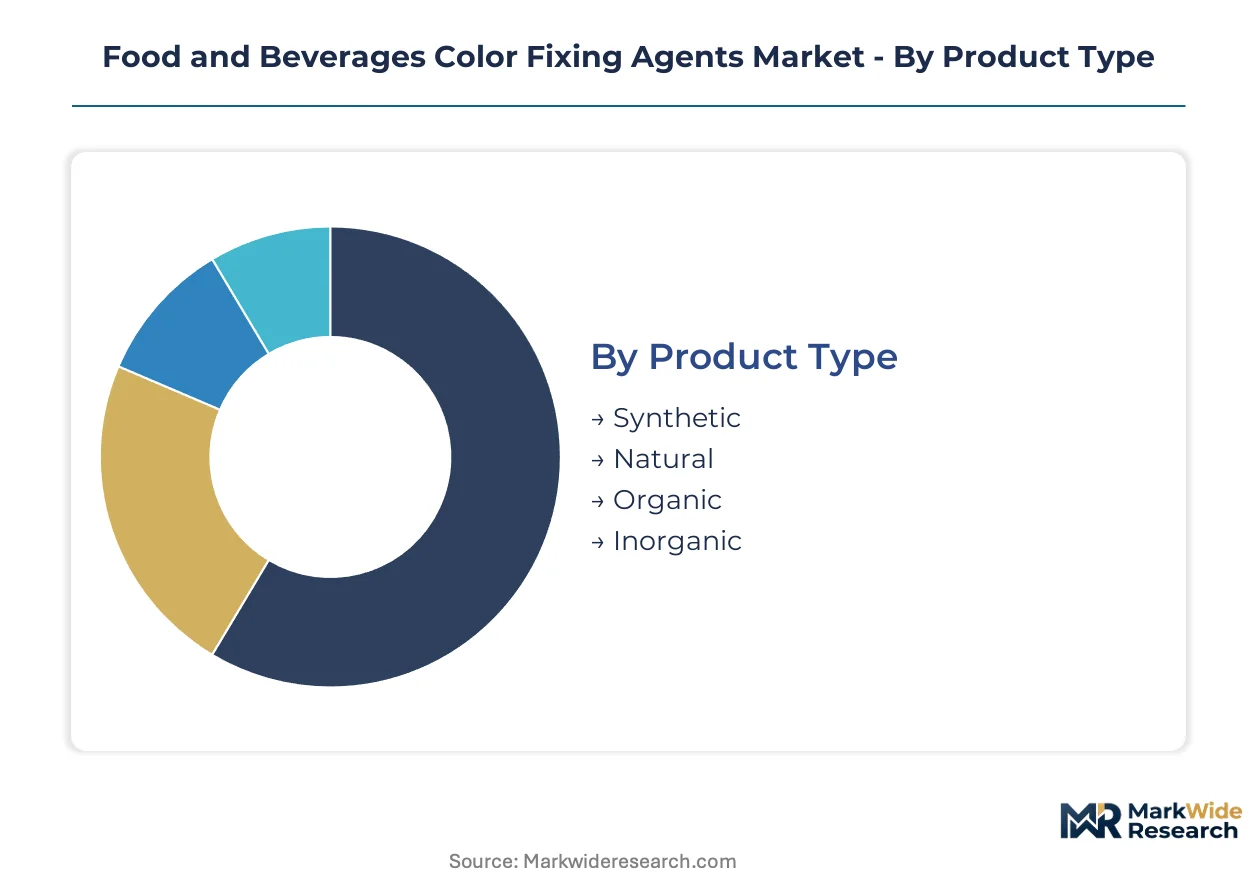
Color fixing agents serve distinct functional requirements across formulation chemistries and physical states. Segmentation reveals where synthetic sodium nitrite retains dominance versus where celery-derived and fermentation-based alternatives displace legacy curing systems.
Product Type:
Mature synthetic chemistries coexist with emerging bio-based alternatives as EFSA re-evaluation accelerates formulation turnover.
- Synthetic:Sodium nitrite and sodium nitrate formulations deliver precise residual nitrite control at 120-200 ppm dosing in German and Italian cured meat production. Processed meat manufacturers in these markets face compressed reformulation timelines as EFSA enforcement deadlines approach.
- Natural:Celery powder and cherry-derived nitrite sources capture expanding share in French and Spanish premium charcuterie where retailers mandate nitrite-free claims. Fermentation technology maturation is halving production costs and enabling price parity with synthetic alternatives.
- Organic:Certified organic celery powder and vegetable-derived nitrites command premium positioning in clean-label sausage categories across EU organic retail channels.
- Inorganic:Mineral-based stabilizers including ascorbic acid derivatives serve niche beverage color preservation applications with limited penetration in meat curing.
Synthetic formulations handle the majority of throughput; natural alternatives are gaining share fastest as regulatory pressure intensifies.
Application:
Volume concentration varies sharply by shelf-life requirements and oxidation sensitivity of the finished product matrix.
- Beverages:Ascorbic acid derivatives stabilize anthocyanin and carotenoid pigments in fruit juices and sports drinks. Brazil and Mexico represent underpenetrated markets where synthetic fixer adoption remains below fifteen percent.
- Dairy Products:Natural color fixers prevent light-induced degradation in flavored milk and yogurt applications, with clean-label demands driving reformulation in French and German dairy processing.
- Snacks:Powdered fixers maintain visual appeal in seasoned meat snacks and extruded products where Maillard browning requires controlled inhibition.
- Confectionery:Liquid concentrates enable uniform dispersion in gummy and hard candy applications with stringent color consistency requirements.
Processed meat applications dominate absolute volume; beverage stabilization climbs the fastest as ascorbic acid platforms expand.
End User:
Procurement sophistication diverges between integrated multinationals with in-house regulatory capacity and fragmented regional processors.
- Food Manufacturers:German and Italian cured meat processors drive specification changes toward fermentation-derived celery powder in tender documents, compressing synthetic sodium nitrite volumes in premium sausage categories.
- Beverage Producers:Juice and sports drink formulators in Latin American markets represent expansion targets for ascorbic acid derivative suppliers.
- Retailers:French and Italian retail chains audit nitrite provenance through blockchain-tracked certificates, displacing spot-market purchasing for color-critical applications.
- Food Service:Prepared meal and catering operators prioritize cost-stable synthetic formulations where clean-label claims carry less consumer visibility.
Food manufacturers handle the majority of procurement volume; retailers are the fastest mover on compliance-driven specification changes.
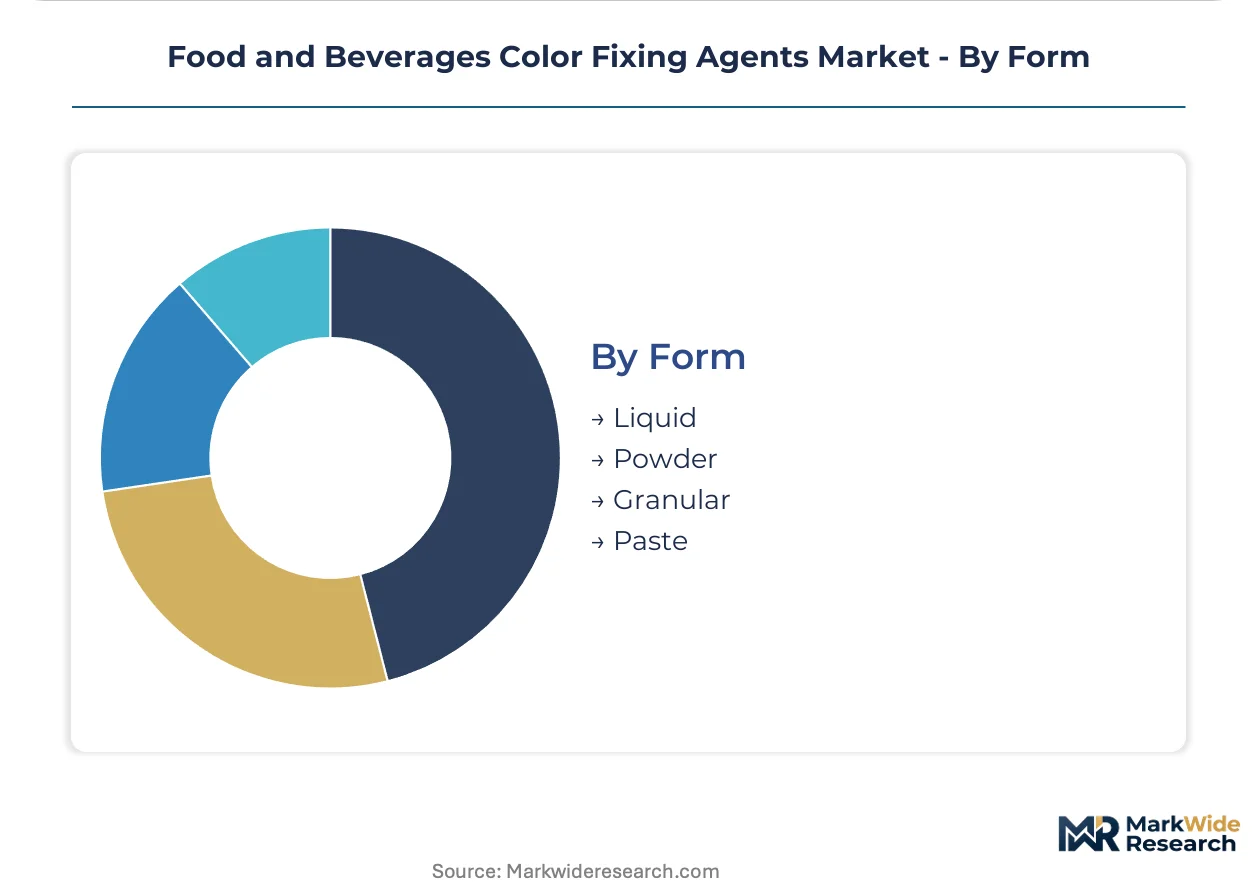
Form:
Physical state selection depends on dispersion requirements, dosing precision, and compatibility with existing production line infrastructure.
- Liquid:Concentrates enable uniform dispersion in beverage stabilization where sedimentation risks compromise visual consistency. Kerry Group and Sensient Technologies compete through integrated liquid color systems with application support.
- Powder:Dominates cured meat applications where dry blending with curing salts simplifies processing workflows in high-volume German and Italian sausage production.
- Granular:Reduced dusting and improved flow characteristics serve automated dosing systems in large-scale meat processing facilities.
- Paste:High-concentration formats minimize water activity introduction in moisture-sensitive confectionery and snack applications.
Powder formulations handle the majority of throughput; liquid concentrates expand most quickly in beverage stabilization segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for fermentation-derived celery powder, while the Rhine-Alpine rail corridor moves color-fixing agents into German sausage manufacturing clusters. Rotterdam's port infrastructure similarly underwrites Benelux chemical import volumes for synthetic nitrite formulations.
Germany
Currywurst and bratwurst production in Lower Saxony and Bavaria sustains substantial sodium nitrite consumption. EFSA's 2023-2027 re-evaluation is forcing processors in Frankfurt-Rhine-Main to validate celery powder alternatives before enforcement deadlines. The Frankfurt meat processing corridor is converting tender specifications toward fermentation-derived natural nitrite sources.
Italy
Parma ham and salami traditions in Emilia-Romagna drive premium charcuterie demand for color-stable curing systems. Italian retailers now mandate blockchain-tracked nitrite provenance certificates under EFSA-aligned national guidelines. The Parma food valley cluster is piloting cherry-derived nitrite validation for export-bound prosciutto.
France
Lyonnaise sausage and dried meat production in Auvergne-Rhône-Alpes requires precise color fixation for Protected Designation of Origin compliance. ANSM enforces strict residual nitrite thresholds alongside EFSA-mandated reformulation timelines. The Lyon meat processing basin is adopting ascorbic acid derivatives to stabilize natural nitrite performance variability.
United States
Chicago and Milwaukee meatpacking corridors process substantial cured pork and beef volumes for domestic retail. FDA color additive regulations and USDA-FSIS labeling mandates govern nitrite thresholds and "uncured" claim disclosure language. Wisconsin's sausage manufacturing belt is qualifying California-sourced celery powder to meet clean-label retailer specifications.
Brazil
São Paulo-state meat processors supply Latin America's largest cured meat market with cost-sensitive formulations. ANVISA maintains distinct additive approval pathways separate from EFSA and FDA benchmarks, complicating multinational formulation standardization. The São Paulo meatpacking cluster is testing ascorbic acid derivatives for beverage color stabilization in adjacent juice processing facilities.
Food and Beverages Color Fixing Agents Market Vendor Landscape
On the supply side, the industry is consolidating around fermentation technology platforms and integrated color system providers. Tiered competitive positioning separates multinational ingredient conglomerates with dossier-compliant REACH portfolios from regional distributors losing ground to direct procurement channels. Three archetypes dominate: fermentation-derived natural nitrite specialists, synthetic sodium nitrite manufacturers with regulatory affairs scale, and integrated color system houses extending from pigment extraction to application support. Dominant competitive moves include backward integration into captive agricultural supply for celery powder sourcing and technology licensing partnerships for bioprocess engineering scale-up.
Among Denmark-based fermentation specialists, Chr. Hansen Holding A/S exemplifies the natural nitrite technology archetype. Sensient Technologies and Kerry Group represent integrated color system providers with application support capabilities spanning multiple continents. These three companies occupy positions that reflect the market's bifurcation between synthetic legacy formulations and bio-based replacement platforms.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Sensient Technologies |
| Kerry Group |
| BASF SE |
| Givaudan (Naturex) |
| Archer Daniels Midland (ADM) |
| DSM-Firmenich |
| Merck KGaA |
| Cargill Inc. |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity underutilization in Danish and German bioprocessing facilities is compressing contract pricing for natural nitrite alternatives while forcing synthetic sodium nitrite suppliers into defensive margin retention. This utilization asymmetry between bio-based and chemical platforms reshapes procurement negotiations across European cured meat processing clusters.
Pricing Analysis
Volume-discount tiering separates multinational processors committing to annual fermentation-derived celery powder offtake from spot-market purchasers of synthetic sodium nitrite. Price differentiation hinges on REACH dossier compliance status and captive agricultural supply integration, with certified organic celery powder commanding substantial premiums over conventional grades. Pricing pressure stems from EFSA-mandated reformulation deadlines compressing buyer decision timelines. Small and mid-sized Spanish and Portuguese exporters exhibit acute price sensitivity, while integrated German sausage manufacturers absorb cost premiums to secure supply continuity.
Supply Chain Analysis
Tariff exposure between California agricultural suppliers and European processors dominates supply chain risk planning for celery powder sourcing. Geographic supply concentration centers on California and Michigan growing regions for natural nitrite feedstock, with German and Danish fermentation facilities processing active ingredients. Raw material dependencies include vegetable nitrate sources, fermentation nutrients, and specialized drying equipment. Single-source vulnerability concentrates in California celery cultivation exposed to climate yield volatility. Distribution runs through Rotterdam and Hamburg port infrastructure into Rhine-Alpine rail corridors serving German meat processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with REACH dossier compliance and EFSA validation timelines creating structural barriers to rapid competitive entry. Incumbents leveraging pre-approved natural nitrite platforms capture reformulation-driven demand before challengers complete qualification protocols.
For Market Incumbents: Build regulatory dossier depth by accelerating toxicological submissions for fermentation-derived nitrite variants ahead of EFSA enforcement windows. Deepen backward integration into captive celery cultivation in California's Central Valley to insulate supply from climate volatility. Consolidate position by acquiring mid-sized Spanish and Portuguese processors lacking in-house regulatory affairs capacity, neutralizing emerging entrant threats from fragmented southern European suppliers.
For New Entrants and Emerging Players: Pursue beverage stabilization applications in Brazil and Mexico where ascorbic acid derivative penetration remains below fifteen percent and regulatory pathways diverge from saturated European meat curing markets. Target Latin American juice processors seeking color stability solutions without EFSA-equivalent reformulation pressure. Establish go-to-market partnerships with regional distribution platforms bypassing traditional layered intermediaries in Southern European markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation technology licensors with multi-year supply agreements tied to EFSA-mandated reformulation deadlines. Long-term viability favors platforms with integrated farm-to-fermentation traceability systems validated by French and Italian retail blockchain auditing requirements. Prioritize acquisition targets possessing mass spectrometry analytical capabilities for natural nitrite quantification. Monitor EFSA maximum residue limit announcements as the critical inflection signal for valuation repricing across natural versus synthetic exposure profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Celery Cultivation | Captive supply from California growing regions mitigates dollar-denominated commodity volatility for European processors. |
| EFSA Dossier Submission Acceleration | Early validation of fermentation-derived nitrite platforms secures premium positioning ahead of enforcement deadlines. |
| Blockchain Traceability Implementation | Farm-to-fermentation documentation satisfies French and Italian retail audit requirements displacing spot-market purchasing. |
| Mass Spectrometry Capability Investment | Analytical infrastructure for natural nitrite quantification addresses quality control gaps in legacy colorimetric laboratories. |
| Latin American Beverage Partnership | Ascorbic acid derivative supply agreements with Brazilian juice processors exploit underpenetrated stabilization markets. |
Methodological Framework
Desk research of EFSA additive re-evaluation documentation, REACH authorization databases, and USDA-FSIS labeling guidance preceded structured interviews with fermentation technology directors, processed meat procurement leads, and retail category managers. Primary fieldwork encompassed German sausage manufacturing clusters, Italian Parma ham production facilities, and California celery powder processing operations. Secondary validation drew from customs trade data, SEC filings of listed ingredient suppliers, and industry association technical publications. Bottom-up volume estimates from individual facility throughput were triangulated against top-down market sizing derived from downstream consumption patterns.
Assumptions held fixed across the projection horizon include EFSA enforcement timeline adherence, existing REACH authorization thresholds, and current FDA color additive regulations. The analytical framework modeled segmentation across product type, application, end user, and physical form dimensions. CAGRs were computed from annualized growth trajectories fitted to validated base-year estimates. Industry-specific forecast inputs incorporated fermentation technology cost reduction curves and natural nitrite price convergence assumptions against synthetic sodium nitrite benchmarks.
Sensitivities concentrate around EFSA maximum residue limit revisions, California agricultural yield volatility, and REACH authorization withdrawal decisions for legacy nitrite formulations. Forecasts reflect assumptions subject to revision from regulatory enforcement delays, biotechnology scale-up failures, or trade policy disruptions affecting transatlantic celery powder flows. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
United Kingdom Food Additives Market