
 High Ratio Shortening Market | 2026-2036
High Ratio Shortening Market Size, Share, and Industry Trends Forecast 2026-2036
High Ratio Shortening Market Foresight
Bakery end-use demand is decoupling from traditional lard-based formulations as plant-based alternatives gain formulation share. Cargill Incorporated leverages its oilseed processing infrastructure to secure supply continuity across North American bakery channels. Bunge Limited anchors its position through backward integration into tropical oil sourcing. Wilmar International competes on cost efficiency in Asian palm-derived shortening production.
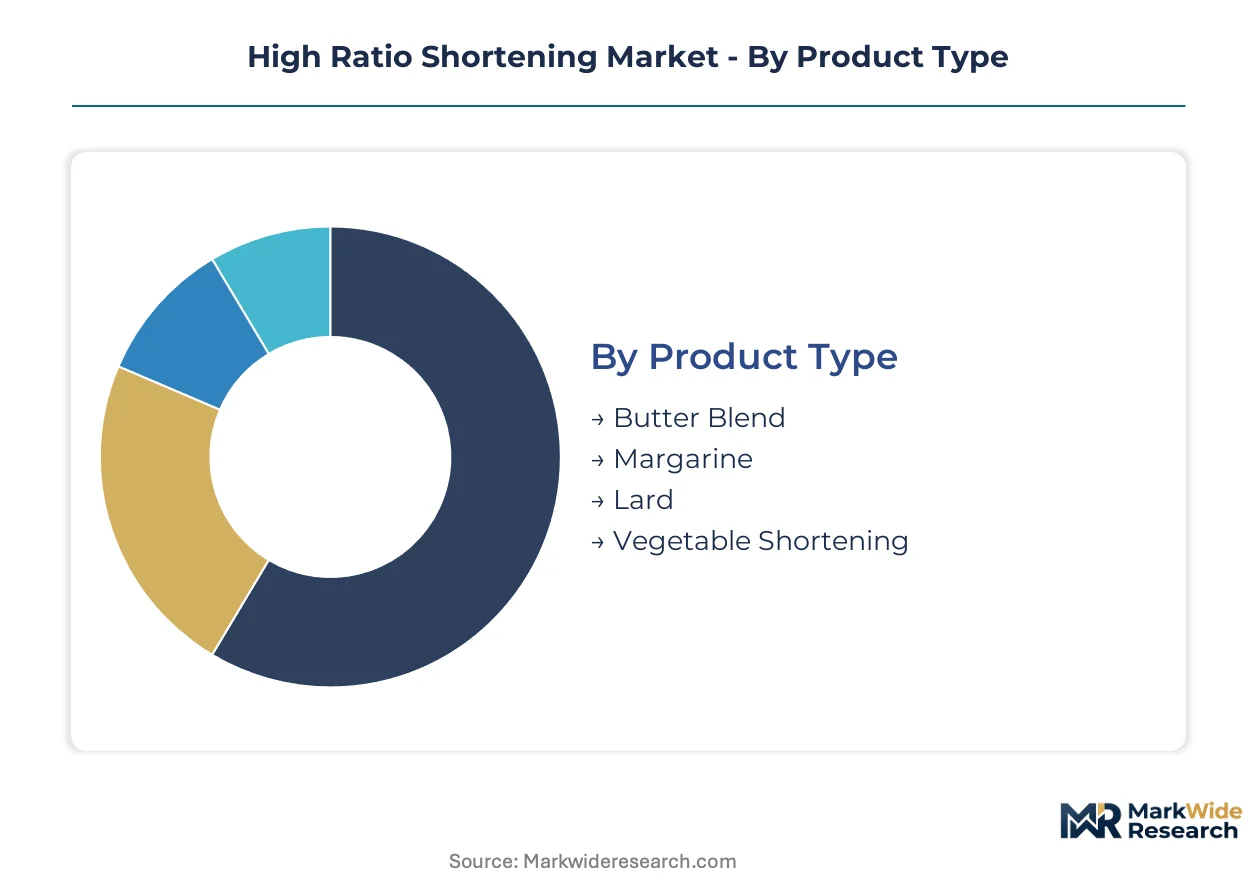
High ratio shortening is a hydrogenated or interesterified fat blend containing emulsifiers, typically maintaining a ratio of sugar to fat exceeding one-to-one by weight, designed to incorporate high air volumes and retain moisture in baked goods. The product type segment shows vegetable shortening leading volume while butter blends command premium positioning in clean-label niches. By end use, baking remains the dominant application though confectionery represents the fastest-growing margin pool as chocolate and coating formulations demand specialized fat crystallization profiles. Emulsified forms capture value through functional performance in industrial scale production despite higher unit costs versus solid blocks.
The FDA governs trans fat disclosure and GRAS status for partially hydrogenated oils, while the USDA oversees shortening used in federally inspected meat and poultry processing facilities. EFSA and national EU regulators enforce acrylamide and contaminant limits that influence frying fat specifications across export-oriented production. Stakeholders must monitor evolving emulsifier approval pathways and regional palm oil sustainability certification requirements as procurement criteria harden.
Market Dynamics
The FDA's trans fat labeling requirements and EFSA contaminant limits are compressing formulation flexibility while Southeast Asian bakery chains scale procurement of clean-label emulsified shortenings.
Growth Catalysts
- Clean-label emulsification:Bakery chains in Indonesia and Vietnam are reformulating to eliminate synthetic emulsifiers, pulling interesterified fat blends into high-volume cake production.
- Confectionery fat crystallization specialization:Chocolate coating manufacturers require precise polymorphism control, expanding demand for high-ratio shortenings with tailored solid fat content profiles.
- Palm oil sustainability certification:RSPO and ISPO standards are hardening procurement criteria, redirecting volume toward certified supply chains in Malaysian and Indonesian processing hubs.
Market Restraints
- Tropical oil price volatility:Crude palm oil futures fluctuate with El Niño cycles and Indonesian export policy shifts, compressing margin predictability for shortening blenders.
- Partial hydrogenation regulatory sunset:The FDA's revocation of GRAS status for PHOs forces reformulation investment, stranding legacy production assets in North American facilities.
- Butter and margarine substitution:Clean-label bakery segments in Western Europe are pivoting toward butter blends and liquid margarine systems, constraining high-ratio shortening penetration in premium positioning.
Strategic Opportunities
- Vietnam confectionery production scaling:Domestic chocolate and biscuit manufacturing is expanding factory capacity, creating unmet demand for specialized coating fats with high aeration tolerance.
- Interesterification technology convergence:Enzymatic interesterification combined with fractionation is enabling trans-free formulations that match hydrogenated fat functionality at industrial scale.
- Direct-to-bakery distribution:Regional shortening producers are bypassing traditional ingredient distributors, building captive supply relationships with Southeast Asian bakery chain procurement teams.
Industry Challenges
- Emulsifier approval pathway delays:Novel clean-label emulsifiers face extended EFSA and FDA safety evaluations, stretching new product development timelines to 18-24 months.
- Fractionation capacity reconfiguration:Shifting from partial hydrogenation to enzymatic interesterification requires capital-intensive crystallizer and separator upgrades at tropical oil processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Ratio Shortening Market |
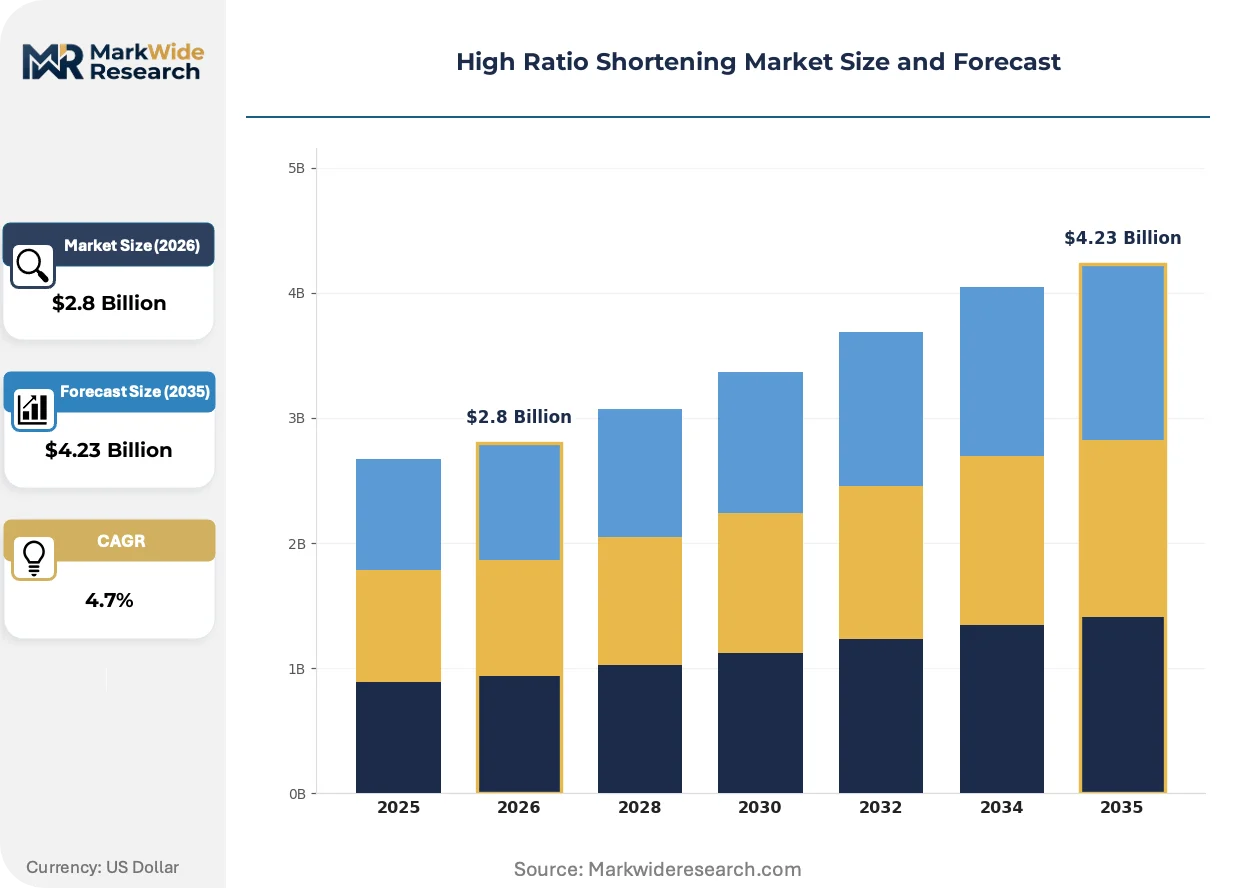
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter Blend, Margarine, Lard, Vegetable Shortening End Use: Baking, Confectionery, Cooking, Snacks Distribution Channel: Online Retail, Supermarkets, Wholesalers, Convenience Stores Form: Liquid, Solid, Powdered, Emulsified |
| Companies Covered | Cargill Incorporated, Du Pont Nutrition and Health, Bunge Limited, Wilmar International, Stepan Specialty Products LLC, AAK AB, Stratas Foods LLC, Fine Organics, Ventura Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Ratio Shortening Market Shifts & Advancements
Formulation chemistry and procurement models are diverging as regulatory pressure and end-use specialization accelerate product segmentation across bakery and confectionery channels.
Enzymatic interesterification systems are automating the production of trans-free high-ratio shortenings with precise solid fat content curves. Industrial bakery operations in Indonesia and Malaysia are adopting these systems at replacement cycle pace. The technology is automating quality consistency while compressing batch-to-batch variability that previously required manual adjustment.
EFSA acrylamide limits and FDA trans fat disclosure rules are tightening contaminant thresholds for frying and baking fats. European export-oriented producers must reformulate to meet dual jurisdiction compliance. Confectionery applications face the steepest reformulation burden as chocolate coatings require both low trans content and precise crystallization behavior.
Bakery chain procurement teams are consolidating supplier relationships around certified sustainable palm sources with full traceability documentation. Traditional ingredient distributors are losing volume to direct mill relationships in Vietnam and the Philippines. This consolidation is most visible in industrial-scale cake and pastry production where procurement teams prioritize supply security over unit cost minimization.
High Ratio Shortening Market Segmentation
High ratio shortening formulation diverges sharply across end-use applications, with emulsification chemistry and fat crystallization profiles determining procurement decisions. Supply chain configuration for each segment reflects distinct processing investments and regulatory compliance burdens.
Product Type:
Supply concentration in palm oil fractionation infrastructure favors processors with backward integration into Southeast Asian sourcing.
- Vegetable Shortening:Hydrogenated or interesterified palm and soybean oil blends dominate industrial bakery procurement in Indonesia and Vietnam. RSPO certification requirements are hardening procurement criteria among Southeast Asian bakery chains.
- Butter Blend:Cream-derived fat systems with vegetable oil admixtures command premium positioning in Western European clean-label niches. Reformulation costs from butter price volatility constrain volume expansion in cost-sensitive channels.
- Margarine:Water-in-fat emulsions with lower solids content serve spreading and cooking applications where aeration tolerance is secondary.
- Lard:Rendered pork fat retains formulation share in traditional Mexican and Eastern European bakery applications despite plant-based displacement elsewhere.
Today's leader: Vegetable Shortening. Tomorrow's challenger: Butter Blend.
End Use:
Application-specific fat functionality requirements create divergent margin structures across industrial and artisanal channels.
- Baking:Cake, pastry, and bread production consumes the largest volume, with high-ratio formulations incorporating sugar-to-fat ratios exceeding one-to-one by weight. Indonesian bakery chains are scaling procurement of clean-label emulsified shortenings for sponge cake production.
- Confectionery:Chocolate coatings and biscuit fillings demand precise polymorphism control and steep solid fat content curves for snap and gloss retention. Vietnamese domestic chocolate manufacturing expansion is pulling specialized coating fat demand.
- Cooking:Frying applications prioritize oxidative stability and acrylamide minimization under EFSA contaminant limits.
- Snacks:Extruded and baked savory products require low-moisture fat systems with extended shelf-life stability.
Baking commands current volume leadership. Confectionery offers the steepest expansion trajectory as Southeast Asian production scales.
Distribution Channel:
Direct mill relationships are compressing traditional distributor margins in high-volume industrial procurement.
- Wholesalers:Bulk ingredient distributors retain relevance in fragmented artisanal bakery supply across secondary Indonesian and Philippine cities.
- Supermarkets:Retail-packaged shortening for home bakers concentrates in urban Vietnamese and Malaysian markets.
- Online Retail:E-commerce penetration remains limited by temperature-controlled logistics requirements for fat-based products.
- Convenience Stores:Small-format retail captures impulse purchases in dense urban clusters with limited cold-chain infrastructure.
Wholesalers anchor present industrial volume. Direct-to-bakery procurement models represent the structural challenger.
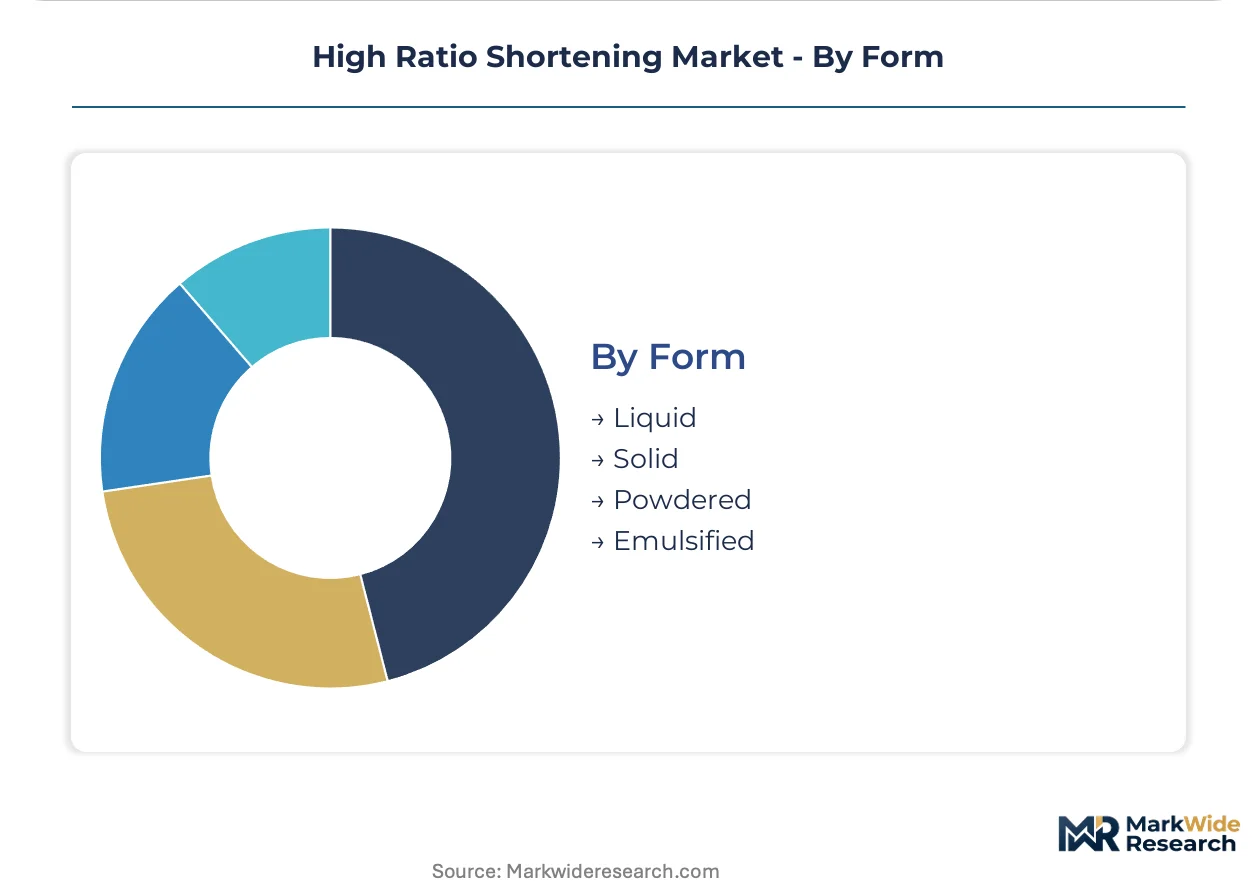
Form:
Processing technology investments determine form-specific supply availability and unit economics.
- Emulsified:Pre-blended shortening with mono- and diglycerides enables industrial-scale cake production with consistent aeration. Enzymatic interesterification systems are automating trans-free emulsified shortening output in Malaysian processing hubs.
- Solid:Block and flake formats serve traditional bakery operations with manual creaming methods. Partial hydrogenation asset stranding under FDA PHO revocation is forcing solid shortening reformulation investment.
- Liquid:Pourable shortening systems reduce handling costs in large-scale frying operations.
- Powdered:Encapsulated fat powders address extended shelf-life requirements in dry mix and instant bakery applications.
Emulsified forms lead functional value capture. Solid blocks face regulatory-driven displacement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting high ratio shortening production toward jurisdictions with lower compliance costs for trans fat reformulation. FDA PHO revocation in the United States and EFSA contaminant thresholds in Europe are accelerating capacity migration to Southeast Asian processing hubs with enzymatic interesterification infrastructure.
United States
Domestic bakery chains are absorbing reformulation costs from FDA PHO revocation. The USDA maintains oversight of shortening in federally inspected meat and poultry facilities. Chicago and Minneapolis-St. Paul processing clusters are retrofitting hydrogenation assets for enzymatic interesterification systems.
Indonesia
Bakery chain expansion in Jakarta and Surabaya is scaling procurement of RSPO-certified emulsified shortenings. The national food and drug regulator enforces halal certification requirements on fat-based ingredients. Malaysian-owned processing facilities in Medan are automating trans-free shortening output for domestic sponge cake production.
Vietnam
Domestic chocolate and biscuit manufacturing expansion in Ho Chi Minh City and Binh Duong province is pulling specialized coating fat demand. The Ministry of Health implements trans fat limits aligned with WHO guidelines. Direct mill relationships are displacing traditional distributors in industrial bakery procurement.
Malaysia
RSPO and ISPO certification concentration supports premium positioning in export-oriented shortening blends. The Malaysian Palm Oil Board enforces sustainability traceability standards. Port Klang processing hubs are consolidating fractionation capacity for confectionery fat crystallization specialization.
Germany
Clean-label bakery segments in Bavaria and North Rhine-Westphalia are pivoting toward butter blends and liquid margarine systems. EFSA acrylamide limits constrain frying fat specifications for export production. Hamburg port infrastructure handles refined palm oil imports for Central European shortening blenders.
High Ratio Shortening Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit hydrogenation assets for enzymatic interesterification systems. The vendor base concentrates around integrated oilseed processors with backward integration into tropical oil sourcing and regional specialists with direct bakery relationships. Three archetypes define competitive positioning: multinational agribusiness conglomerates with fractionation infrastructure, Southeast Asian palm oil processors with cost-efficient emulsified shortening output, and regional blenders with direct-to-bakery distribution models. Strategic moves cluster around sustainability certification alignment and geographic proximity to scaling confectionery production.
Among integrated agribusiness operators, Cargill Incorporated exemplifies the multinational archetype with oilseed processing infrastructure securing supply continuity across North American bakery channels. Bunge Limited occupies a position within the tropical oil sourcing tier, anchoring competitive positioning through upstream control over palm and palm kernel supply chains. Wilmar International represents the Southeast Asian processing specialist, sitting within the cost-efficiency segment of palm-derived shortening production for regional bakery and confectionery demand.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Du Pont Nutrition and Health |
| Bunge Limited |
| Wilmar International |
| Stepan Specialty Products LLC |
| AAK AB |
| Stratas Foods LLC |
| Fine Organics |
| Ventura Foods |
| Others |
Supply & Pricing Matrix
RSPO certification tiers bifurcate procurement economics across Southeast Asian bakery chains, with premium-grade emulsified shortenings commanding supply security premiums while uncertified palm fractions compete on spot-market volatility. This tier divergence concentrates pricing power among Malaysian and Indonesian processors with backward integration into certified plantation networks, while forcing reformulation cost absorption among North American blenders facing FDA PHO revocation.
Pricing Analysis
Distributor margin compression runs through traditional ingredient channels as direct mill relationships displace wholesale intermediaries in Vietnam and Indonesia. Three-tier pricing structure across premium RSPO-certified, standard industrial-grade, and economy spot-market tiers reflects sustainability documentation depth and crystallization precision. Pricing pressure stems from El Niño-driven crude palm oil futures volatility, with Indonesian export policy shifts amplifying margin unpredictability. Artisanal bakery segments in secondary Philippine cities exhibit highest price sensitivity, while industrial-scale confectionery manufacturers in Ho Chi Minh City prioritize supply security over unit cost minimization.
Supply Chain Analysis
Crude palm oil supply rests on Indonesian and Malaysian plantation networks, with Philippine and Thai secondary sourcing for specialized kernel fractions. Malaysian Port Klang and Indonesian Medan processing hubs concentrate enzymatic interesterification capacity, drawing from tropical oil feedstocks and imported soybean oil blends. Single-source vulnerability concentrates around Indonesian export licensing regimes and Malaysian ISPO certification bottlenecks. Distribution runs through direct-to-bakery procurement teams consolidating around certified sustainable palm sources with full traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic interesterification cost curves are flattening as Malaysian processing hubs automate trans-free output, enabling margin expansion through reformulation service premiums rather than commodity fat arbitrage.
For Market Incumbents: Anticipate stranded asset risk from legacy partial hydrogenation infrastructure by accelerating crystallizer and separator upgrades at tropical oil processing facilities. Defensive consolidation around RSPO certification concentration protects procurement relationships with scaling Southeast Asian bakery chains. Channel control through direct mill relationships in Vietnam and the Philippines anchors volume retention against regional specialist competition. For New Entrants and Emerging Players: Launch via direct-to-bakery distribution models targeting unmet confectionery fat demand in Binh Duong province and Ho Chi Minh City chocolate manufacturing expansion. White-space concentration sits with specialized coating fats for biscuit filling applications requiring steep solid fat content curves. Geographic entry through Vietnamese domestic production scaling offers lowest incumbent saturation among high-growth margin pools. For Investors and Strategic Acquirers: Consolidation pressure builds where fractionation capacity shortages intersect with enzymatic interesterification technology gaps among mid-scale Southeast Asian processors. Long-term viability favors acquisition targets with backward integration into certified palm sourcing and established direct procurement relationships with Indonesian bakery chain expansion. The signal to watch is FDA novel emulsifier approval velocity, which would compress 18-24 month product development timelines for clean-label entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Interesterification Capacity Expansion | Malaysian processing hubs automate trans-free shortening output for Indonesian bakery chain procurement. |
| RSPO Certification Investment | Sustainability traceability documentation hardens procurement criteria among Southeast Asian confectionery manufacturers. |
| Direct-to-Bakery Distribution Buildout | Regional shortening producers bypass traditional distributors to capture Vietnamese industrial bakery volume. |
| Backward Integration into Plantation Networks | Upstream palm oil sourcing control secures margin predictability against El Niño-driven price volatility. |
| Clean-Label Emulsifier Development Partnership | Novel mono- and diglyceride alternatives compress EFSA and FDA safety evaluation timelines for reformulation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at Malaysian and Indonesian processing facilities, procurement leads at Southeast Asian bakery chains, distribution channel partners in Vietnam and the Philippines, and technical R&D directors specializing in fat crystallization systems. Secondary validation drew from customs and trade data, Malaysian Palm Oil Board sustainability reports, FDA GRAS determination filings, and EFSA contaminant limit documentation. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions.
Segment-weighting across product type, end use, distribution channel, and form dimensions anchored the analytical framework across the analysis window. CAGRs derived from trend extrapolation of enzymatic interesterification adoption curves, RSPO certification penetration rates, and regional bakery chain expansion trajectories. Forecast inputs incorporated crude palm oil futures volatility patterns and regulatory compliance cost burdens for trans fat reformulation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Indonesian export policy shocks or accelerated FDA novel emulsifier approvals. Projections reflect assumptions around enzymatic technology cost curves and sustainability certification adoption timelines. Material deviation in El Niño cycle intensity or EFSA emulsifier pathway delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Lignans Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
South America Feed Palatability Enhancers Market