
 Brewers Spent Grain Market | 2026-2036
Brewers Spent Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Brewers Spent Grain Market Analytics
Mechanical dehydration and pelletization is fragmenting traditional wet-grain logistics by enabling longer shelf life and intercontinental shipment of brewers spent grain. Anheuser-Busch InBev anchors North American supply through captive brewery networks that feed integrated drying operations. Kerry Group plc differentiates via food-grade extraction technologies that isolate protein and fiber fractions for human nutrition applications. Upcycled Foods Inc. specializes in branded ingredient positioning that commands premium placement against commodity animal feed outlets.
Brewers spent grain consists of the solid residue remaining after mashing and lautering during wort production, typically containing 20-30% protein, 50-60% fiber, and 10% moisture when dried, with primary commercial purpose as a nutritionally dense, low-cost input for animal ration formulation and emerging food applications. Animal feed dominates volume throughput due to established procurement channels from livestock operations, while food ingredient captures expanding margin pools as fractionation technology improves protein isolate purity. Dried form leads logistics economics for export-oriented suppliers, though wet form sustains cost advantage for hyperlocal delivery radiuses under fifty kilometers.
The EPA regulates brewers spent grain under the Food Safety Modernization Act when destined for animal consumption, while the EU Green Deal and REACH framework impose traceability and chemical residue thresholds on cross-border material flows. Germany's KBA-aligned waste hierarchy enforcement and France's ANSM food contact material standards collectively tighten compliance burdens for processors seeking multi-market access. Stakeholders must monitor evolving mycotoxin testing protocols and carbon accounting methodologies that will determine which drying and transport configurations retain license to operate across jurisdictions.
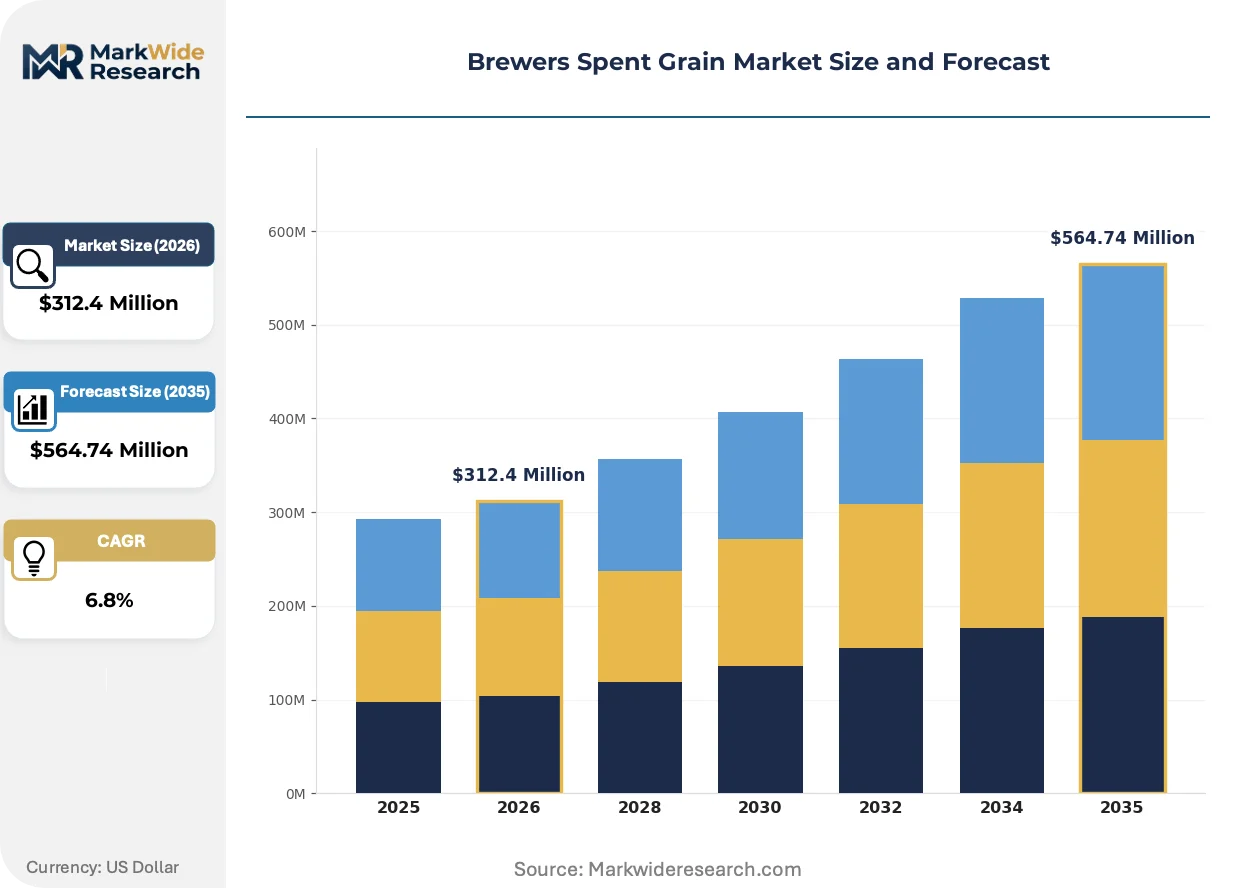
Market Dynamics
Mechanical dehydration and pelletization technologies are compressing logistics costs and extending shelf life, enabling brewers spent grain to compete with soybean meal and corn gluten across intercontinental supply chains.
Growth Catalysts
- EU Green Deal circular economy mandates:European brewers face binding landfill elimination targets that valorize side-stream processing. Germany's KBA-aligned waste hierarchy enforcement accelerates commercial adoption.
- Protein isolate fractionation:Food-grade extraction technologies unlock human nutrition applications with margin premiums above commodity feed outlets. Kerry Group plc advances this capability.
- Bavaria-North Rhine-Westphalia brewing cluster density:Concentrated feedstock supply enables adjacent agricultural offtake agreements within economical transport radiuses.
Market Restraints
- Input cost volatility in natural gas:Drying operations remain energy-intensive. European gas price spikes compress processor margins and deter capacity expansion.
- Regulatory friction from REACH chemical residue thresholds:Cross-border material flows face traceability burdens that fragment EU internal market efficiency.
- Substitution threat from distillers dried grains:Corn ethanol byproducts offer established procurement channels and comparable protein profiles for livestock ration formulation.
Strategic Opportunities
- Underpenetrated food ingredient channels:Protein isolate purity improvements enable bakery and snack applications with premium positioning against commodity outlets.
- Carbon accounting methodology alignment:EU Green Deal emission disclosure requirements reward low-carbon feedstock sourcing. Processors capturing biogas from anaerobic digestion gain competitive differentiation.
- Direct-to-farm digital platforms:Wet grain logistics within fifty-kilometer radiuses bypass traditional distributor markups. Hyperlocal matching algorithms reduce spoilage losses.
Industry Challenges
- Food-grade certification timeline:ANSM food contact material standards in France impose extended validation periods for novel ingredient applications.
- Mycotoxin testing protocol fragmentation:Divergent national standards for aflatoxin and ochratoxin A thresholds complicate multi-market product registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewers Spent Grain Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Feed, Biofuel, Food Ingredient, Organic Fertilizer End Use Industry: Agriculture, Food Processing, Brewing, Renewable Energy Packaging Type: Bags, Bulk, Pallets, Containers Form: Dried, Wet, Pelletized, Powdered |
| Companies Covered | Carlsberg Group, Kerry Group plc, Anheuser-Busch InBev, Tetra Pak International S.A., Bühler AG, Heineken N.V., Diageo plc, Upcycled Foods Inc., Molson Coors Beverage Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewers Spent Grain Market Evolving Landscape
Technology convergence between mechanical processing and biological fractionation is expanding addressable applications beyond traditional animal feed channels into human nutrition and functional ingredients.
Mechanical dehydration systems with integrated pelletization are migrating from batch-operated brewery adjuncts to continuous-flow industrial configurations. Large-scale feed compounders in Germany and the Netherlands adopt these systems to secure year-round supply independent of harvest cycles. This technology migration from seasonal wet-grain logistics to storable dry product formats compresses price volatility and enables export-oriented supply contracts.
REACH framework chemical residue thresholds and EU Green Deal circular economy reporting requirements impose traceability mandates on cross-border spent grain flows. Processors must document input material provenance and processing parameters for customs clearance. Small-scale operators in Eastern Europe face compliance cost barriers that favor consolidation toward integrated drying facilities with in-house laboratory testing capacity.
Livestock operations are consolidating procurement decisions through centralized nutritionist teams rather than decentralized farm-level purchasing. This buyer concentration compresses spot market liquidity and rewards long-term offtake agreements with volume guarantees. The shift is most visible in Germany's dairy sector, where cooperative feed buying groups negotiate multi-year supply contracts directly with brewery networks.
Brewers Spent Grain Market Segmentation
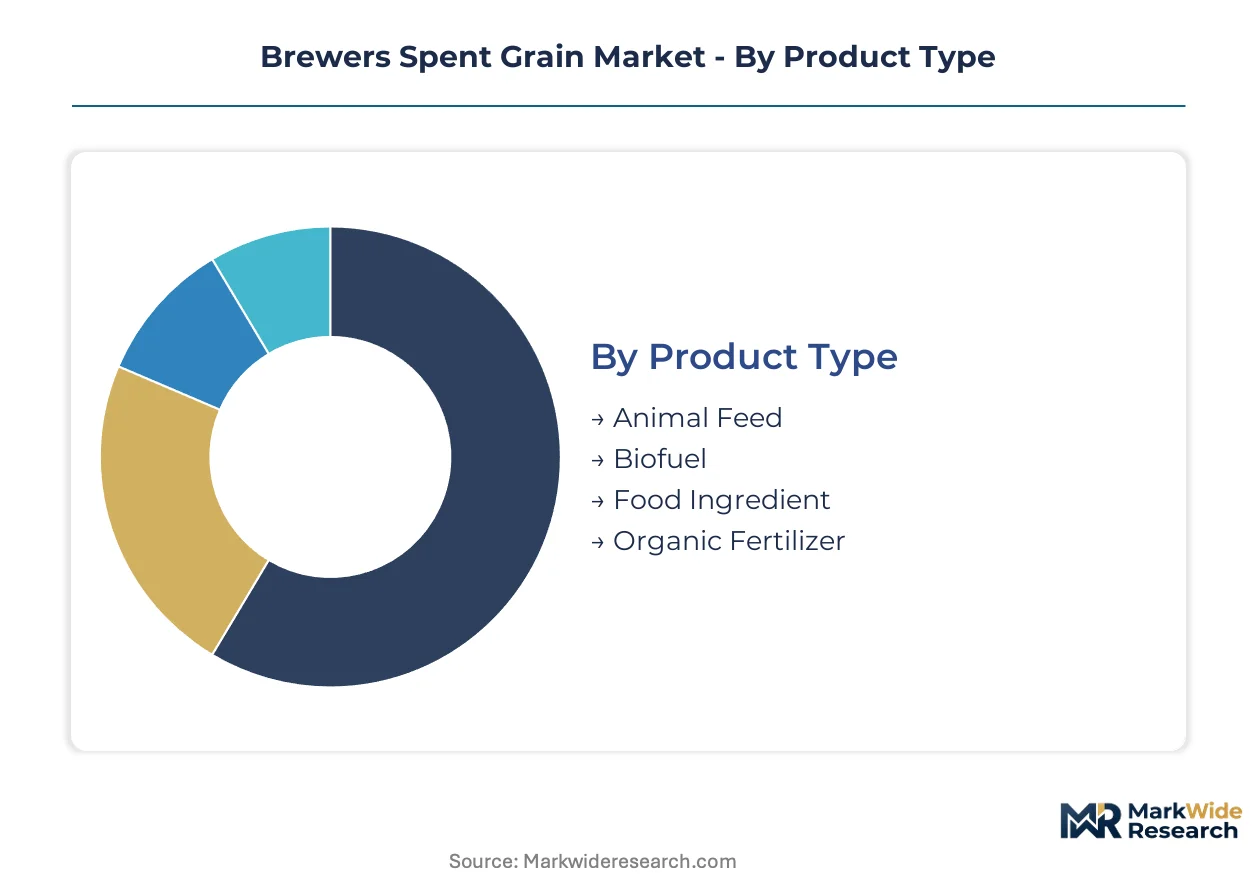
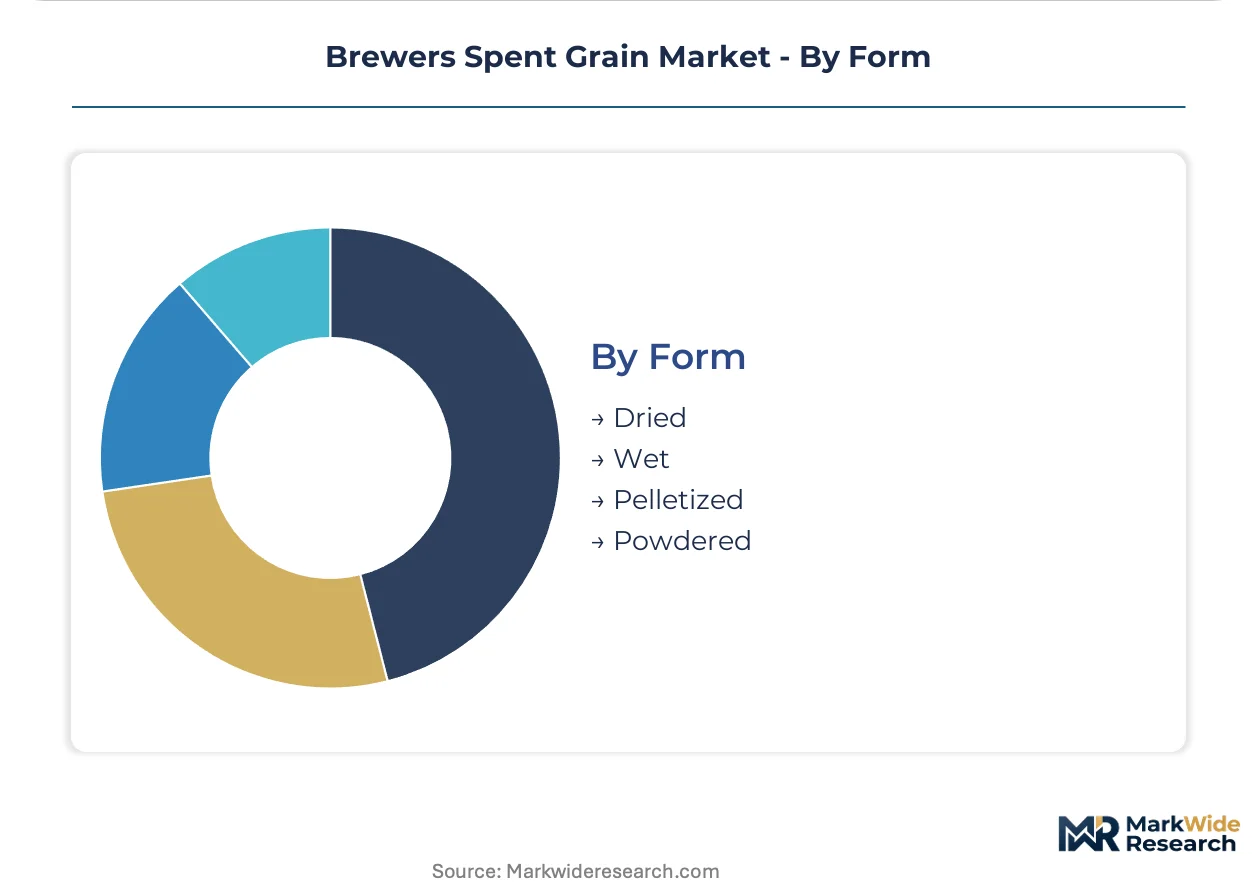
Brewers spent grain flows through distinct commercial channels shaped by moisture content, regulatory classification, and end-use nutritional requirements. Each segment carries unique logistics economics and margin profiles that determine processor investment priorities.
Product Type:
Mature applications dominate volume while emerging categories capture technology-driven premiums.
- Animal Feed:Dried and pelletized spent grain delivers 20-30% protein content with standardized fiber profiles for dairy and cattle rations. Livestock operations in Bavaria and North Rhine-Westphalia absorb concentrated supply from adjacent brewing clusters under KBA-aligned waste hierarchy enforcement.
- Food Ingredient:Protein isolate fractionation yields human-grade fiber and protein concentrates for bakery and snack applications. Kerry Group plc advances extraction purity that commands premium positioning against commodity feed outlets.
- Biofuel:Anaerobic digestion systems convert spent grain to biogas for captive brewery energy or grid injection.
- Organic Fertilizer:Composted applications serve regional agriculture with lower processing overhead than dried alternatives.
Animal Feed handles the majority of throughput; Food Ingredient is expanding most quickly on margin capture.
End Use Industry:
Customer concentration varies by procurement sophistication and volume scale.
- Agriculture:Dairy cooperatives and feed compounders in Germany negotiate multi-year offtake agreements with brewery networks. Centralized nutritionist teams displace decentralized farm purchasing, compressing spot market liquidity.
- Food Processing:Ingredient manufacturers seek protein isolates with ANSM-compliant food contact certification for EU market access.
- Brewing:Captive anaerobic digestion and drying operations close material loops within production facilities.
- Renewable Energy:Biogas upgrading equipment enables biomethane injection into national grids under EU Green Deal carbon accounting frameworks.
Agriculture absorbs the dominant share of volume; Food Processing shows the steepest expansion trajectory as fractionation technology matures.
Packaging Type:
Logistics configuration dictates shelf life and intercontinental shipment feasibility.
- Bulk:Unpackaged dried grain moves via pneumatic conveyor and bulk trailer for compounder intake within 500-kilometer radii. REACH traceability mandates require documented provenance for cross-border flows.
- Containers:Intermodal shipping enables export contracts to Asian feed markets independent of harvest cycle timing.
- Bags:25-50kg woven polypropylene serves smallholder dairy operations with limited storage infrastructure.
- Pallets:Unitized loads facilitate warehouse handling for food-grade ingredient distribution.
Bulk dominates domestic throughput; Containers are gaining share fastest on export route development.
Form:
Moisture content determines transport economics and application suitability.
- Dried:Mechanical dehydration reduces moisture to 10% for year-round storage and intercontinental shipment. Natural gas price volatility in Europe compresses processor margins and deters capacity expansion.
- Pelletized:Densified format improves flowability and reduces dust generation for automated feeding systems.
- Wet:70-80% moisture content sustains cost advantage for hyperlocal delivery within fifty-kilometer radii where spoilage risk remains manageable.
- Powdered:Milled dried grain enables precise ration formulation and food ingredient blending.
Dried handles the majority of commercial volume; Pelletized is climbing the fastest on logistics efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy cooperatives and feed compounders dominate procurement decisions across major brewing regions. Centralized nutritionist teams displace farm-level purchasing. This buyer concentration compresses spot market liquidity and rewards long-term offtake agreements with volume guarantees.
Germany
Bavaria and North Rhine-Westphalia generate concentrated feedstock supply for adjacent agricultural operations. KBA-aligned waste hierarchy enforcement accelerates commercial adoption of side-stream valorization. Munich and Dortmund brewery clusters feed integrated drying facilities serving regional dairy cooperatives.
United States
Captive brewery networks anchor North American supply through integrated drying operations. EPA Food Safety Modernization Act regulations govern animal feed applications with documented processing parameters. Wisconsin and Colorado brewing corridors sustain hyperlocal wet grain logistics within fifty-kilometer farm delivery radii.
France
ANSM food contact material standards impose extended validation periods for novel ingredient applications. EU Green Deal circular economy mandates pressure brewers to eliminate landfill disposal. Paris Basin and Hauts-de-France agricultural regions absorb pelletized supply for compounder ration formulation.
Netherlands
Large-scale feed compounders adopt continuous-flow industrial drying configurations independent of harvest cycles. REACH framework chemical residue thresholds require documented provenance for cross-border material flows. Rotterdam and Eindhoven logistics hubs enable intermodal container shipment to Asian feed markets.
United Kingdom
Scotland and England brewing clusters face post-Brexit customs documentation burdens on EU material flows. EFSA-aligned mycotoxin testing protocols complicate multi-market product registration. London and Midlands feed distributors negotiate multi-year supply contracts directly with brewery networks.
Brewers Spent Grain Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. The market exhibits moderate consolidation where multinational brewers leverage captive supply networks against independent processors serving spot markets. Three archetypes dominate: vertically integrated brewery operators, food-grade extraction technology providers, and branded ingredient positioning specialists. Competitive moves center on backward integration into drying infrastructure and strategic partnerships with feed compounders for volume offtake security.
Within the vertically integrated tier, Anheuser-Busch InBev anchors North American supply through captive brewery networks. Kerry Group plc occupies a position exemplifying food-grade extraction technology advancement. Ucycled Foods Inc. represents the branded ingredient positioning archetype commanding premium placement against commodity outlets.
| Leading Market Players |
|---|
| Carlsberg Group |
| Kerry Group plc |
| Anheuser-Busch InBev |
| Tetra Pak International S.A. |
| Bühler AG |
| Heineken N.V. |
| Diageo plc |
| Upcycled Foods Inc. |
| Molson Coors Beverage Company |
| Others |
Value Network & Pricing Analysis
Bavaria and North Rhine-Westphalia brewing clusters concentrate wet grain supply within fifty-kilometer farm delivery radii, anchoring margin pools in mechanical dehydration and pelletization infrastructure rather than raw feedstock procurement. Natural gas price volatility in Europe compresses processor margins and determines which drying configurations retain competitive license to operate.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate processor-brewery agreements, transferring energy volatility risk to compounders through quarterly adjustment clauses. Price differentiation rests on moisture content certification and REACH-compliant traceability documentation, with food-grade protein isolates commanding premiums against commodity feed outlets. Pricing pressure stems from distillers dried grains substitution in livestock rations, eroding spot market liquidity. Dairy cooperatives exhibit highest price sensitivity through centralized nutritionist procurement, while food ingredient manufacturers accept premiums for ANSM-validated fiber concentrates.
Supply Chain Analysis
Contract manufacturing concentration sits with Bühler AG and Tetra Pak International S.A. for continuous-flow industrial drying systems, while regional compounders operate captive batch configurations. Geographic supply concentration clusters in Germany, the Netherlands, and the United States, with Bavaria and Wisconsin sustaining hyperlocal wet grain logistics. Raw material dependencies center on malted barley supply from brewing operations, natural gas for thermal processing, and polymer feedstock for pellet binding agents. Single-source vulnerability runs through European gas import corridors. Distribution feeds from brewery-integrated drying facilities to compounder intake silos via pneumatic bulk trailer within 500-kilometer radii, with Rotterdam and Eindhoven hubs enabling intermodal container export to Asian feed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as livestock procurement centralization displaces decentralized farm purchasing, creating niche openings for hyperlocal digital matching platforms and food-grade extraction specialists.
For Market Incumbents: Insulate volume offtake through multi-year supply contracts with dairy cooperatives in Germany and captive integration into drying infrastructure. Kerry Group plc's protein fractionation capability and Anheuser-Busch InBev's brewery network control illustrate defensive positioning against distillers dried grains substitution and natural gas margin compression. Prioritize biogas capture from anaerobic digestion to align with EU Green Deal carbon accounting rewards. For New Entrants and Emerging Players: Food ingredient channels in France and the Netherlands represent the most penetrable entry point, where ANSM validation timelines deter incumbent expansion and protein isolate purity improvements command premium positioning. Direct-to-farm digital platforms for wet grain logistics within fifty-kilometer radii bypass traditional distributor markups in Bavaria and Wisconsin corridors. Target cooperative feed buying groups with algorithmic spoilage reduction guarantees. For Investors and Strategic Acquirers: Capital is best deployed toward integrated drying facilities with in-house laboratory testing capacity, as REACH traceability mandates and mycotoxin protocol fragmentation consolidate small-scale Eastern European operators. The five-to-ten year viability window favors processors capturing biogas value streams and food-grade certification capabilities. Monitor EU Green Deal landfill elimination enforcement intensity and natural gas price normalization as inflection indicators for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drying Infrastructure | Captive brewery networks secure year-round supply independent of harvest cycles. |
| Food-Grade Protein Fractionation Investment | Kerry Group plc extraction purity commands premium placement against commodity feed outlets. |
| Biogas Capture and Grid Injection | EU Green Deal carbon accounting rewards low-carbon feedstock sourcing for processors. |
| Direct-to-Farm Digital Platform Launch | Hyperlocal matching algorithms reduce spoilage losses within fifty-kilometer wet grain radii. |
| Multi-Year Offtake Agreement with Dairy Cooperatives | Germany's centralized nutritionist procurement compresses spot market liquidity. |
Research Methodology
The analysis maps animal feed, food ingredient, biofuel, and organic fertilizer sub-sectors, each validated through brewery operations managers, feed compounder procurement leads, dairy cooperative nutritionists, and regulatory affairs specialists at extraction technology providers. Primary interviews triangulate against customs trade data, KBA waste hierarchy enforcement records, EU Green Deal circular economy reporting frameworks, and SEC filings from publicly traded brewers. Bottom-up volume estimates from individual facility capacities reconcile with top-down addressable market sizing across the analysis window.
Assumptions held fixed include EU Green Deal landfill elimination mandates and REACH chemical residue thresholds, while natural gas price trajectories and mycotoxin testing protocol harmonization were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end-use industry, packaging configuration, and moisture content form, with regional regulatory cluster and brewing density as cross-cutting variables. CAGRs derive from installed drying capacity expansion schedules and livestock ration formulation adoption curves, incorporating protein isolate purity improvement timelines and anaerobic digestion penetration rates as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in European natural gas pricing, barley harvest yields, or dairy sector profitability would shift the trajectory. Forecasts reflect assumptions documented above without claiming predictive certainty. Quarterly review of EU Green Deal enforcement intensity, EFSA mycotoxin threshold revisions, and compounder capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Non-Fuel Grade Alcohol Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Dark Beer Market