
 Fintech Lending Market | 2026-2036
Fintech Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Fintech Lending Market Insights
Cloud-native infrastructure is realigning cost structures across the lending value chain, displacing legacy core banking systems that previously dominated origination and servicing economics. Upstart leverages machine learning models trained on non-traditional data signals to sustain approval rates for thin-file borrowers. SoFi anchors its position through in-house securitization capabilities and vertical control over deposit funding. Affirm differentiates at the point of sale through merchant-integrated installment APIs that bypass traditional card networks entirely.
Fintech lending encompasses algorithmic origination, automated underwriting, and digital disbursement of credit products through non-bank platforms operating on API-first architectures with sub-second decision latency. These systems employ alternative data ingestion, real-time cash-flow analytics, and dynamic pricing engines to serve borrowers outside conventional credit bureau coverage, primarily reducing friction in consumer and small business credit access. Personal loans and business loans currently occupy the deepest margin pools as unit economics favor high-velocity, short-duration products with automated servicing, while supply chain finance and invoice financing represent the fastest-expanding application categories as embedded finance APIs penetrate B2B trade workflows. Artificial intelligence and machine learning dominate technology investment as lenders compete on predictive accuracy and fraud detection throughput.
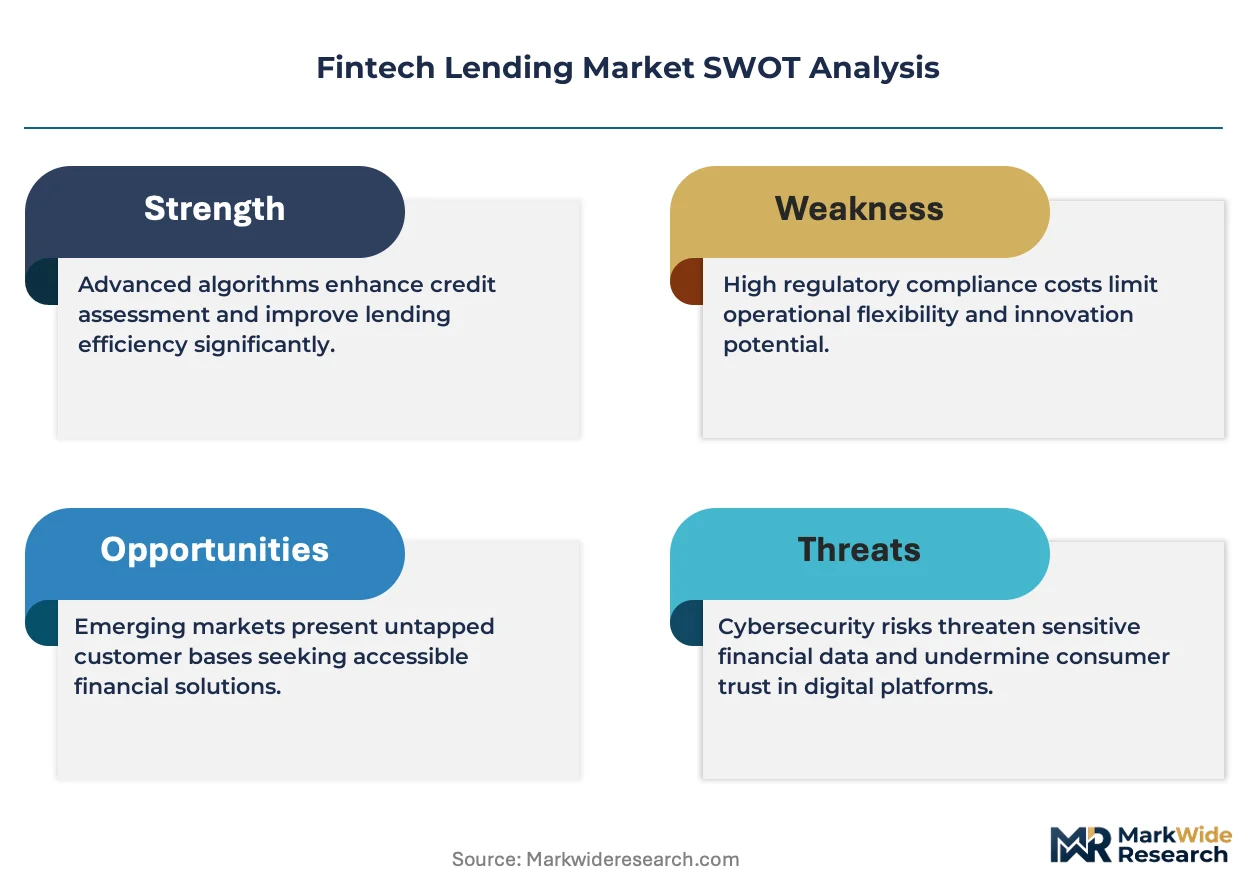
The Consumer Financial Protection Bureau shapes product structures through fair lending enforcement and open banking rulemaking in the United States, while the Financial Conduct Authority and Prudential Regulation Authority calibrate capital requirements and borrower protection standards in the United Kingdom. India's Reserve Bank issues priority sector lending mandates and digital lending guidelines that directly determine which fintech models qualify for bank partnership structures. Stakeholders must monitor how divergent data localization requirements and AI governance frameworks across these jurisdictions constrain cross-border model deployment and capital sourcing strategies.
Market Dynamics
Cloud-native infrastructure is compressing origination costs while open banking mandates force incumbent banks to share customer data, eroding traditional credit moats and accelerating platform competition.
Growth Catalysts
- Open Banking APIs:Regulatory frameworks in the United Kingdom and European Union compel incumbent banks to expose customer transaction data, enabling fintech platforms to underwrite thin-file borrowers with real-time cash-flow analytics.
- AI-Driven Credit Scoring:Machine learning models trained on alternative data signals—utility payments, rental history, gig economy earnings—expand addressable populations beyond FICO-dependent systems.
- SME Working Capital Gap:Small and medium enterprises in India face persistent credit access constraints, driving adoption of digital lending platforms that bypass branch-based documentation requirements.
Market Restraints
- Capital Concentration Risk:Wholesale funding markets in the United States remain dominated by money-center banks and institutional investors, creating refinancing vulnerability for non-depository lenders during rate volatility.
- Model Risk Governance:The Consumer Financial Protection Bureau's fair lending enforcement creates compliance friction for algorithmic underwriting systems that lack explainability documentation.
- Data Localization Mandates:India's Reserve Bank requires domestic storage of borrower data, fragmenting cloud infrastructure strategies and raising operational complexity for cross-border platforms.
Strategic Opportunities
- Embedded B2B Finance:Supply chain finance APIs are penetrating procurement workflows, enabling lenders to originate at the point of invoice generation rather than through direct customer acquisition.
- Regulatory Sandboxes:The United Kingdom's Financial Conduct Authority permits controlled testing of novel products, reducing time-to-market for income-share agreements and dynamic repayment structures.
- Deposit Funding Integration:Charter acquisition or bank partnership structures allow fintech lenders to access low-cost stable funding, compressing net interest margin pressure from volatile wholesale markets.
Industry Challenges
- Explainable AI Talent Scarcity:Model risk management and regulatory interpretation of black-box algorithms require specialized quantitative compliance professionals in short supply across financial services.
- Legacy Core Integration:Partnership-dependent lenders face API latency and data format mismatches when connecting to incumbent banks' decades-old loan origination systems.
- Fraud Vector Proliferation:Synthetic identity generation and document manipulation attack vectors evolve faster than defensive model retraining cycles, elevating loss rates in automated approval workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fintech Lending Market |
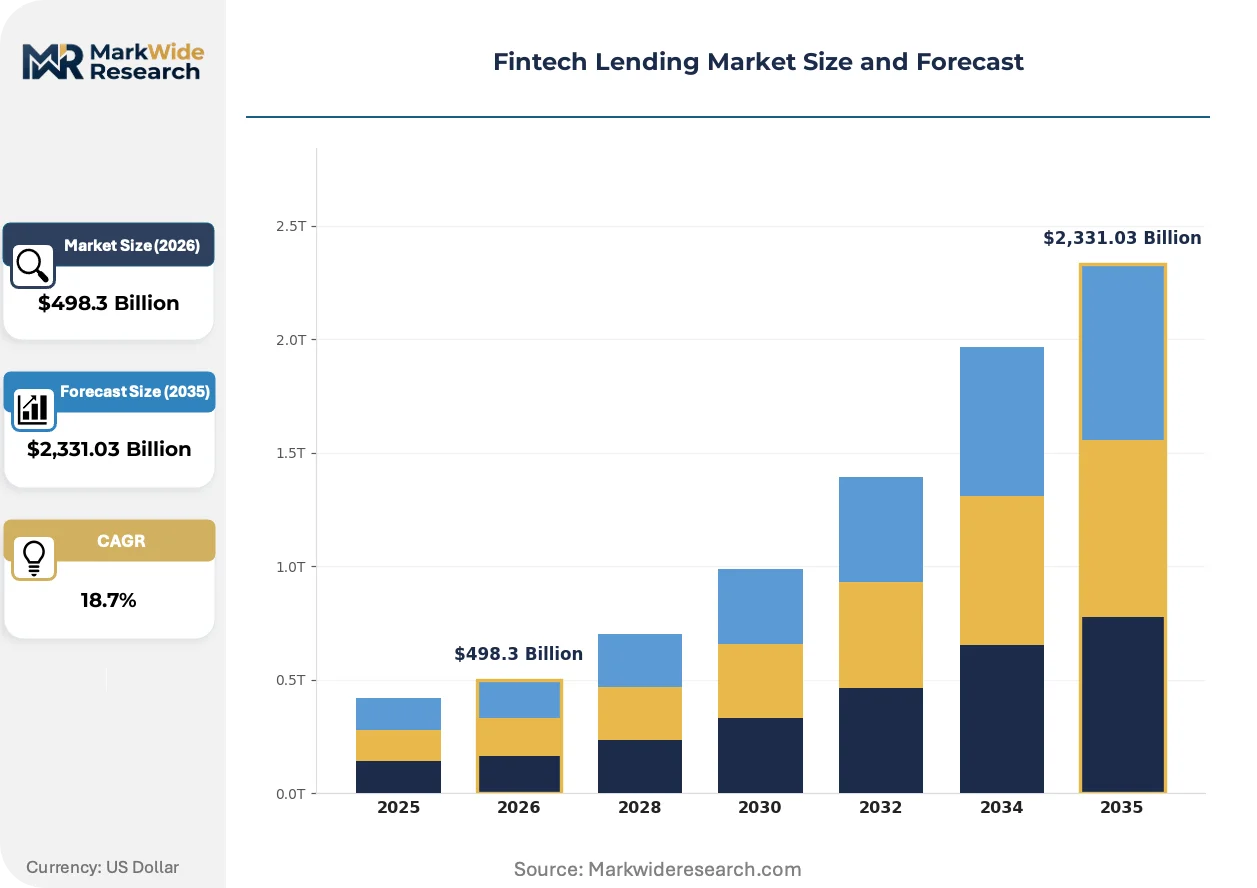
| Market Size in 2026 | $498.3 Billion |
| Market Size in 2035 | $2,331.03 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Personal Loans, Business Loans, Mortgage Loans, Student Loans, Equipment Financing Technology: Blockchain, Artificial Intelligence, Machine Learning, Robotic Process Automation, Cloud Computing Application: Consumer Credit, Small Business Financing, Peer-to-Peer Lending, Invoice Financing, Supply Chain Finance End User: Individual Borrowers, Small and Medium Enterprises, Startups, Nonprofit Organizations, Freelancers |
| Companies Covered | SoFi, Creditas, GoodLeap, Avant, OakNorth, Upstart, Kiavi, Chime, Affirm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fintech Lending Market Trends and Innovations
Real-time data infrastructure is collapsing decision timelines from days to milliseconds, while regulatory fragmentation forces architectural choices that prioritize jurisdictional adaptability over standardization.
Embedded lending infrastructure is integrating merchant point-of-sale systems with credit decision engines, enabling instant installment origination at transaction completion. Retailers and e-commerce platforms are adopting these APIs to reduce cart abandonment and capture interchange revenue. This architecture is integrating commerce and credit into single-session experiences that bypass traditional card network economics entirely.
The Consumer Financial Protection Bureau's open banking rulemaking in the United States mandates standardized data sharing interfaces, compelling banks to dismantle screen-scraping workarounds. Fintech platforms gain direct API access to transaction histories, reducing data acquisition costs and improving model accuracy. Consumer credit segments are responding fastest, with personal loan originators rebuilding underwriting stacks around cash-flow-based rather than credit-score-centric evaluation.
Revenue model experimentation is displacing fixed-rate amortization as the dominant product structure. Borrowers in gig economy verticals demand income-adjusted repayment schedules that flex with irregular cash flows. The United Kingdom and Australia exhibit the deepest adoption of dynamic repayment products, where regulatory flexibility permits structures that would trigger usury or fair lending concerns under United States precedent.
Fintech Lending Market Segmentation
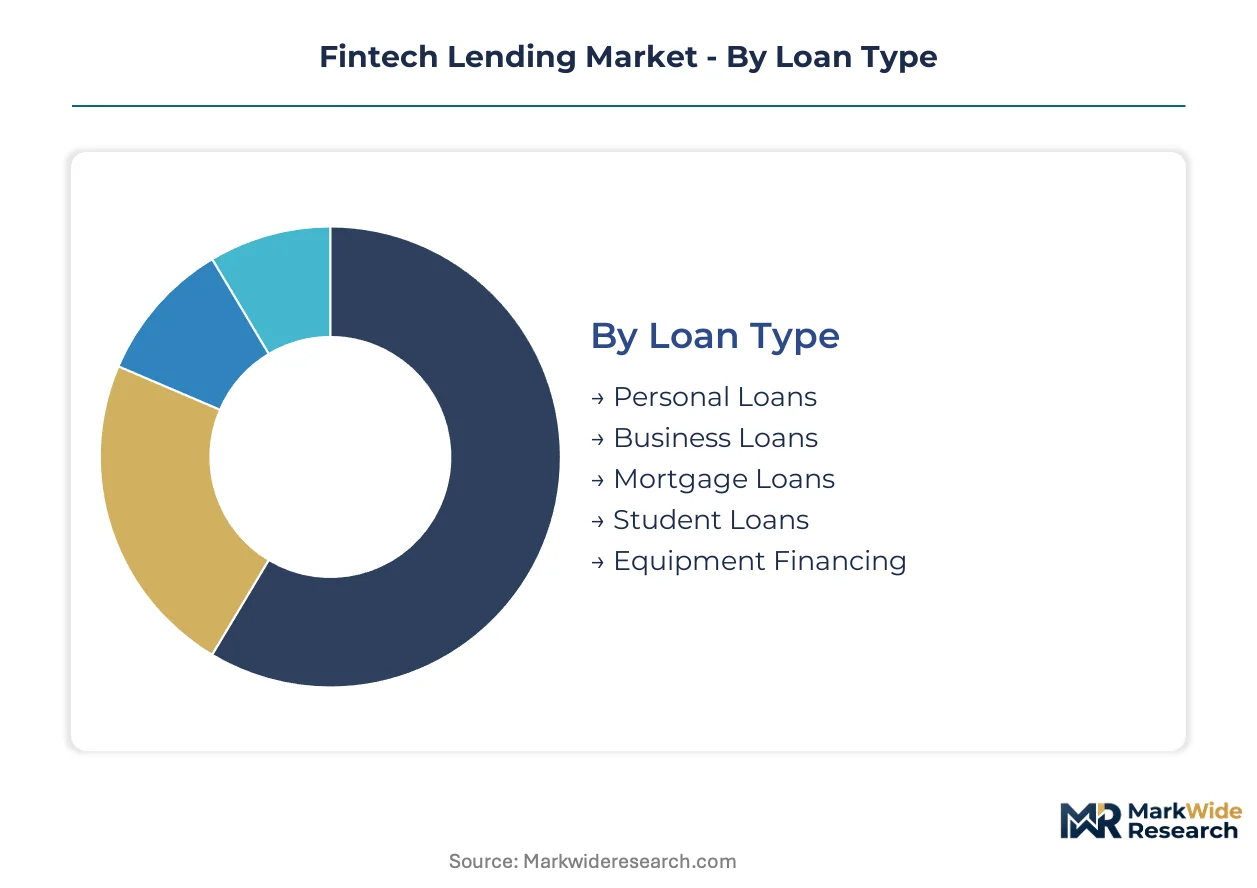
Fintech lending platforms architect product portfolios around distinct risk-return profiles and origination economics. Segmentation reveals how technology choice and borrower type determine unit economics, regulatory treatment, and capital sourcing strategies across the value chain.
Loan Type:
Standardized term structures dominate high-volume segments while bespoke arrangements concentrate in collateralized categories.
- Personal Loans:Unsecured installment products with fixed amortization schedules and sub-second digital origination. Demand clusters in the United States and United Kingdom where cash-flow-based underwriting displaces FICO-centric models.
- Business Loans:Working capital facilities and term debt for established enterprises with automated document verification. Small and medium enterprises in India drive origination velocity as branch-based documentation requirements erode.
- Mortgage Loans:Long-duration secured products requiring property appraisal integration and regulatory disclosure protocols.
- Student Loans:Income-contingent repayment structures with deferred payment triggers tied to enrollment status.
- Equipment Financing:Asset-backed facilities with residual value estimation and vendor program integrations.
Most installed capacity flows through Personal Loans. Expansion is steepest in Business Loans.
Technology:
Technology selection tracks the maturity curve of algorithmic decisioning, with frontier capabilities commanding premium implementation costs.
- Artificial Intelligence:Neural network architectures for fraud detection and dynamic pricing with real-time model retraining. United States lenders invest most heavily as the Consumer Financial Protection Bureau clarifies explainability requirements.
- Machine Learning:Gradient-boosted frameworks for credit scoring on alternative data signals including utility payments and rental history. Deployment concentrates in thin-file borrower segments across India and the United Kingdom.
- Blockchain:Distributed ledger infrastructure for loan syndication and secondary market settlement.
- Robotic Process Automation:Workflow automation for document ingestion and compliance checking in legacy system environments.
- Cloud Computing:Elastic infrastructure for origination spikes and disaster recovery with jurisdictional data residency controls.
Machine Learning absorbs the largest share of technology budgets. Blockchain pilots are gaining share fastest in cross-border syndication use cases.
Application:
Application architecture determines whether platforms acquire borrowers directly or embed within existing commercial workflows.
- Consumer Credit:Point-of-sale installment origination and revolving credit lines with merchant-integrated APIs. United States adoption accelerates as open banking mandates dismantle screen-scraping dependencies.
- Small Business Financing:Revenue-based financing and term loans with automated bank account analysis. India's priority sector lending requirements channel bank partnership capital toward this segment.
- Peer-to-Peer Lending:Marketplace structures matching retail investors with screened borrowers under platform facilitation models.
- Invoice Financing:Receivable-backed liquidity with dynamic advance rates tied to debtor credit quality.
- Supply Chain Finance:Reverse factoring programs anchored by buyer credit ratings and procurement system integration.
Consumer Credit carries the deepest origination volume. Supply Chain Finance is climbing the fastest as embedded finance APIs penetrate B2B procurement platforms.
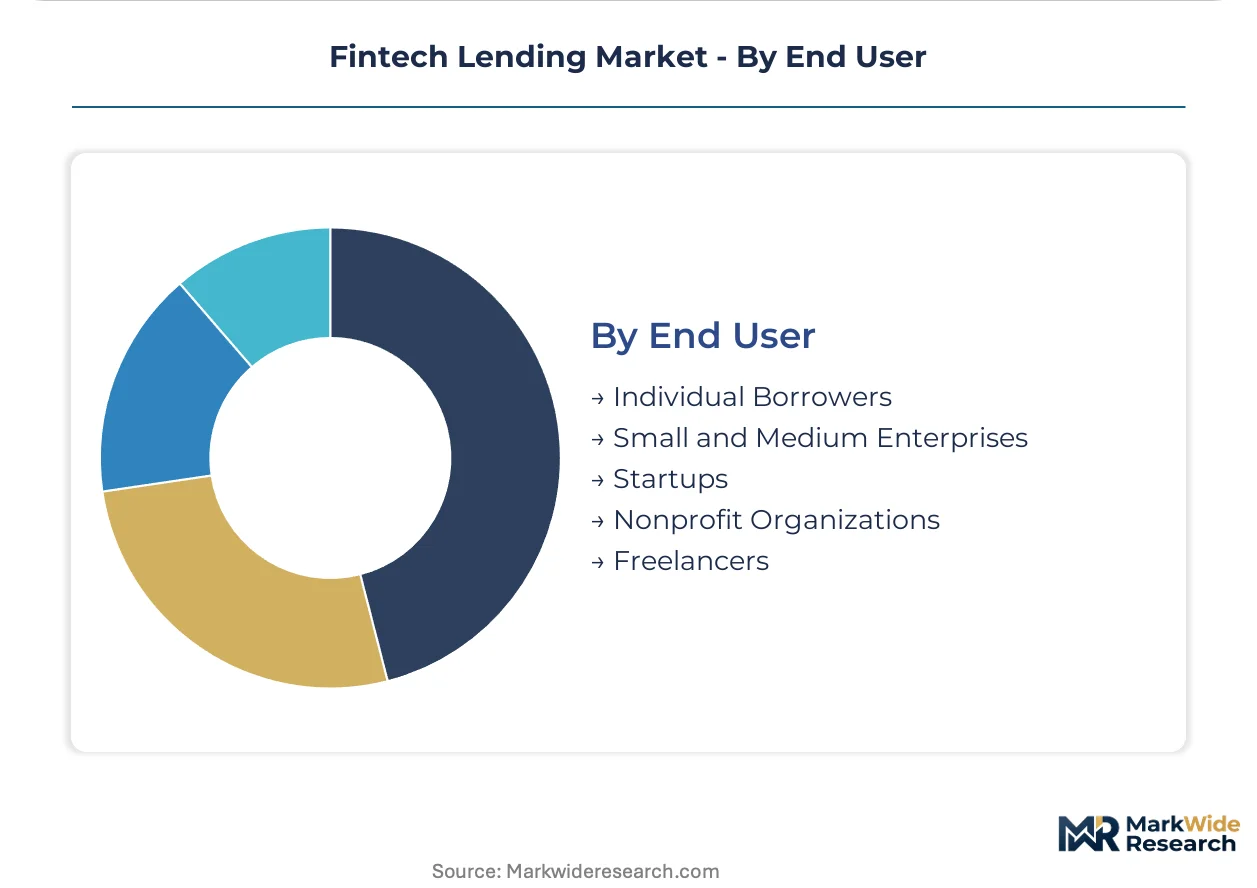
End User:
Borrower taxonomy shapes documentation requirements, pricing elasticity, and regulatory safeguards across origination funnels.
- Individual Borrowers:Mass-market consumers with variable credit histories seeking debt consolidation and purchase financing. United Kingdom regulatory sandboxes permit novel repayment structures unavailable under United States precedent.
- Small and Medium Enterprises:Established businesses with bank account data sufficient for cash-flow underwriting but insufficient collateral for traditional term loans. India's digital lending guidelines determine platform eligibility for bank partnerships.
- Startups:Venture-backed companies with negative cash flows and equity cushion dependencies.
- Nonprofit Organizations:Mission-driven entities with restricted revenue streams and board-governed borrowing authority.
- Freelancers:Gig economy workers with irregular income patterns requiring income-adjusted repayment schedules.
Individual Borrowers represent the largest addressable population. Freelancers are gaining share fastest as platform capabilities adapt to variable income verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors fintech lending innovation through venture capital concentration and regulatory sandbox proximity. Digital lending platforms cluster where open banking mandates and deep technology talent pools converge.
United States
The Consumer Financial Protection Bureau's open banking rulemaking mandates standardized data sharing interfaces, dismantling screen-scraping dependencies. SoFi and Upstart exemplify machine learning underwriting deployment from San Francisco and San Mateo. New York City houses alternative credit scoring specialists serving thin-file borrowers.
United Kingdom
The Financial Conduct Authority's regulatory sandbox permits controlled testing of income-share agreements and dynamic repayment structures. London's fintech corridor concentrates embedded lending API developers integrating with merchant point-of-sale systems. The Prudential Regulation Authority calibrates capital requirements for non-depository lenders.
India
The Reserve Bank of India's priority sector lending mandates channel bank partnership capital toward small and medium enterprises. Mumbai and Bangalore host digital lending platforms bypassing branch-based documentation requirements. Data localization requirements fragment cloud infrastructure strategies for cross-border platforms.
Germany
BaFin's implementation of EU open banking frameworks exposes incumbent bank transaction data to fintech underwriters. Berlin's startup ecosystem concentrates revenue-based financing specialists serving gig economy workers. Frankfurt's banking infrastructure supports wholesale funding relationships for platform lenders.
Australia
The Australian Securities and Investments Commission's regulatory flexibility permits dynamic repayment products unavailable under United States precedent. Sydney fintechs deploy cash-flow analytics for variable income verification. Melbourne houses supply chain finance platforms penetrating B2B procurement workflows.
Fintech Lending Market Competitive Landscape
Global majors compete with regional champions across underwriting technology and funding model differentiation. The vendor base stratifies between deposit-funded integrated banks, marketplace lenders dependent on institutional capital, and embedded finance API providers. Three archetypes dominate: vertically integrated charter holders, algorithmic origination specialists, and merchant-integrated point-of-sale lenders. Competitive moves concentrate on charter acquisition for stable funding access and AI talent acquisition for model accuracy.
Among algorithmic underwriting specialists, Upstart represents machine learning deployment on alternative data signals, while SoFi occupies a position as a charter-integrated lender with securitization capabilities. Affirm exemplifies merchant-embedded installment origination at point-of-sale, bypassing traditional card network economics entirely.
| Leading Market Players |
|---|
| SoFi |
| Creditas |
| GoodLeap |
| Avant |
| OakNorth |
| Upstart |
| Kiavi |
| Chime |
| Affirm |
| Others |
Pricing and Supply Chain Analysis
Machine learning engineering talent concentration in the San Francisco Bay Area and Bangalore widens pricing spreads between premium algorithmic underwriting platforms and legacy-dependent competitors, as labor-cost differentials directly determine model-development velocity and risk-pricing accuracy.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and specialized AI talent expenses shapes tiered pricing structures across the lending value chain. Premium-mid-economy pricing differentiation separates charter-integrated lenders with captive deposit funding from wholesale-dependent platforms and API-only middleware providers. Price compression in the mid-market intensifies as open banking mandates commoditize transaction-data access and erode proprietary data moats. Small and medium enterprises exhibit highest price sensitivity due to thin margins and working capital urgency, while embedded finance merchants prioritize integration speed over rate competition.
Supply Chain Analysis
Workforce availability for quantitative risk modeling and regulatory compliance expertise concentrates in the United States, the United Kingdom, and India, anchoring platform development and model governance functions. Cloud computing infrastructure draws from hyperscaler regions in the United States, Ireland, and Singapore, while alternative data providers source from open banking APIs, payroll aggregators, and accounting software integrations. Single-source vulnerability in wholesale funding markets—particularly institutional securitization buyers in the United States—creates refinancing risk during rate volatility cycles. Distribution runs through direct-to-consumer digital channels, bank partnership origination funnels, and merchant-embedded point-of-sale APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fintech lending represents a margin-expansion trajectory as cloud-native infrastructure compresses origination costs and premium-tier borrowers migrate toward algorithmic platforms with superior approval rates.
For Market Incumbents: Cement defensible positioning through charter acquisition or bank partnership structures that secure low-cost deposit funding and reduce wholesale market dependency. Invest in explainable AI documentation capabilities ahead of Consumer Financial Protection Bureau fair lending enforcement to preempt model risk governance friction. Incumbent banks must accelerate legacy core system modernization to reduce API latency disadvantages against cloud-native competitors. For New Entrants and Emerging Players: Enter via supply chain finance APIs penetrating B2B procurement workflows in India and Southeast Asia, where priority sector lending mandates channel bank partnership capital toward thin-file small and medium enterprises. Target invoice financing and revenue-based financing segments with automated bank account analysis as the most penetrable white space. Pursue merchant-embedded origination partnerships rather than direct customer acquisition to bypass saturated consumer credit markets. For Investors and Strategic Acquirers: Charter-integrated fintech lenders with in-house securitization capabilities are the most active acquirer targets in this space, as vertical control over funding and distribution commands premium valuations. Long-term viability favors platforms with regulatory sandbox track records and jurisdictional adaptability across United States, United Kingdom, and India frameworks. Watch open banking implementation velocity and AI explainability rulemaking as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Charter Acquisition | Deposit funding access reduces net interest margin pressure from volatile wholesale securitization markets. |
| AI Talent Acquisition | Machine learning engineering capacity determines predictive accuracy and thin-file borrower approval rates. |
| Open Banking API Integration | Real-time transaction data ingestion displaces FICO-centric underwriting and reduces data acquisition costs. |
| Embedded Finance Partnership | Merchant point-of-sale integration captures origination at transaction completion and reduces customer acquisition expense. |
| Regulatory Sandbox Participation | Controlled testing environments in the United Kingdom and India accelerate novel product validation and compliance pathway clarity. |
Research Methodology
Direct dialogue with chief technology officers at digital lending platforms, risk management executives at bank partnership programs, regulatory affairs leads at fintech charter applicants, and procurement officers at embedded finance merchants grounded qualitative findings. Secondary validation drew from Consumer Financial Protection Bureau rulemaking dockets, Reserve Bank of India digital lending guidelines, Financial Conduct Authority sandbox outcome reports, and SEC securitization disclosures. Bottom-up origination volume estimates and top-down addressable market sizing were triangulated against cloud infrastructure spend patterns and AI talent hiring data.
Segmented projections across loan type, technology deployment, application architecture, and end-user taxonomy were generated through the analytical framework. Machine learning model accuracy improvements, open banking API adoption curves, and regulatory sandbox expansion trajectories served as key forecast inputs. CAGRs were derived from elasticity-adjusted origination velocity assumptions and funding cost compression scenarios across the projection horizon.
The model holds under stable regulatory interpretation of algorithmic underwriting and sustained wholesale funding market access; deviation in fair lending enforcement intensity or securitization market liquidity contraction would shift competitive positioning and origination capacity estimates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Europe Embedded Finance Market
FinTech
UAE Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
Africa AI in Fintech Market
FinTech
Financial Services Cloud Market
FinTech
Australia Fintech Market
FinTech
Autonomous Finance Market
FinTech
Hand Account Software Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Germany Fintech Market
FinTech
Latin America Fintech Market
FinTech
Vietnam Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
Financial Cloud Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Wealthtech Solutions Market