
 Reverse Factoring Market | 2026-2036
Reverse Factoring Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Factoring Market Analytics
Asset-light supply chain finance models is fragmenting competitive barriers in reverse factoring, allowing non-bank platforms to challenge traditional lenders. Taulia leverages cloud-native architecture to anchor enterprise buyer relationships across Fortune 500 accounts. FundThrough competes by specializing in SME invoice acceleration with automated underwriting pipelines. Triumph Business Capital dominates transportation sector factoring through captive broker networks and fuel card integrations.
Reverse factoring is a tripartite financing arrangement where a corporate buyer facilitates early payment to suppliers through a financial intermediary, typically structured as receivables purchase programs with credit risk anchored to the buyer's rating rather than the supplier's. The mechanism operates through invoice verification, buyer confirmation of payable obligations, and subsequent funding disbursement at a discount rate reflecting the buyer's creditworthiness. Supply chain financing programs command the largest transaction volume pool due to embedded working capital optimization within enterprise procurement systems. Digital platforms represent the fastest-expanding service type as API-driven onboarding and real-time invoice matching displace manual documentation workflows. Buyer-led programs concentrate margin capture with originating corporates, while third-party financing models distribute risk across institutional funders seeking short-duration, trade-linked yield.
Basel III liquidity coverage ratios constrain European bank-sponsored models, redirecting origination toward balance-sheet-light intermediaries. The EU Late Payment Directive mandates maximum 60-day terms for public sector contracts, mechanically expanding eligible receivables volumes for structured programs. China's NMPA and SAMR oversight of fintech lending platforms introduces capital reserve requirements that favor bank-affiliated digital originators over standalone operators. Stakeholders must monitor how open banking APIs and real-time payment infrastructures alter invoice verification economics and intermediary value capture.
Market Dynamics
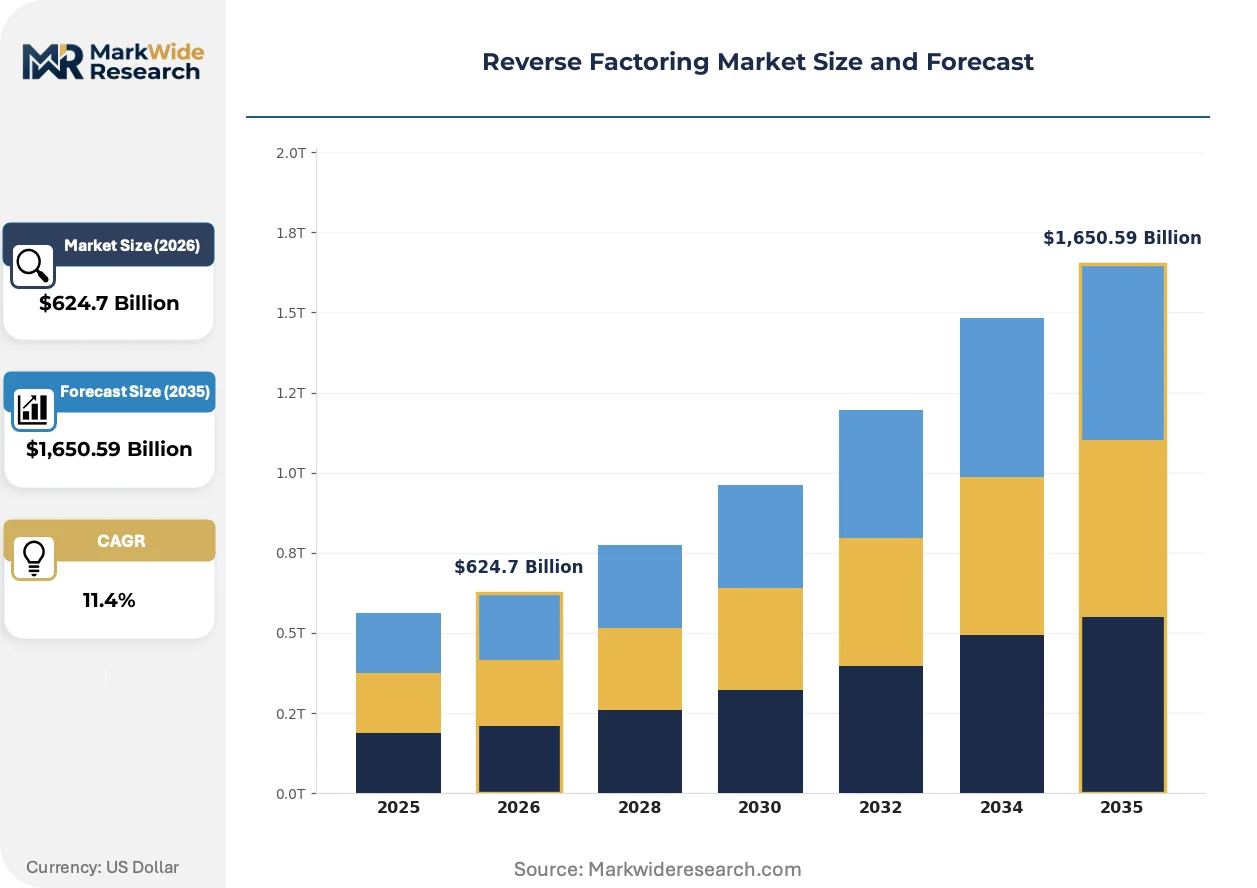
Buyer credit rating arbitrage is reconfiguring reverse factoring economics as working capital optimization migrates from bank balance sheets to distributed fintech infrastructure. The EU Late Payment Directive and Basel III liquidity coverage ratios are compressing traditional lender margins while accelerating platform intermediation.
Growth Catalysts
- EU Late Payment Directive:The 60-day maximum payment term mandate for public sector contracts mechanically expands eligible receivables volumes for structured supplier finance programs across European procurement systems.
- Automotive supply chain stress:German and Mexican automotive OEMs are deploying buyer-led programs to stabilize tiered supplier ecosystems amid raw material cost volatility and just-in-sequence production pressures.
- API-driven invoice matching:Real-time data exchange between enterprise ERP systems and financing platforms is collapsing verification timelines from days to minutes, unlocking transaction velocity previously constrained by documentation friction.
Market Restraints
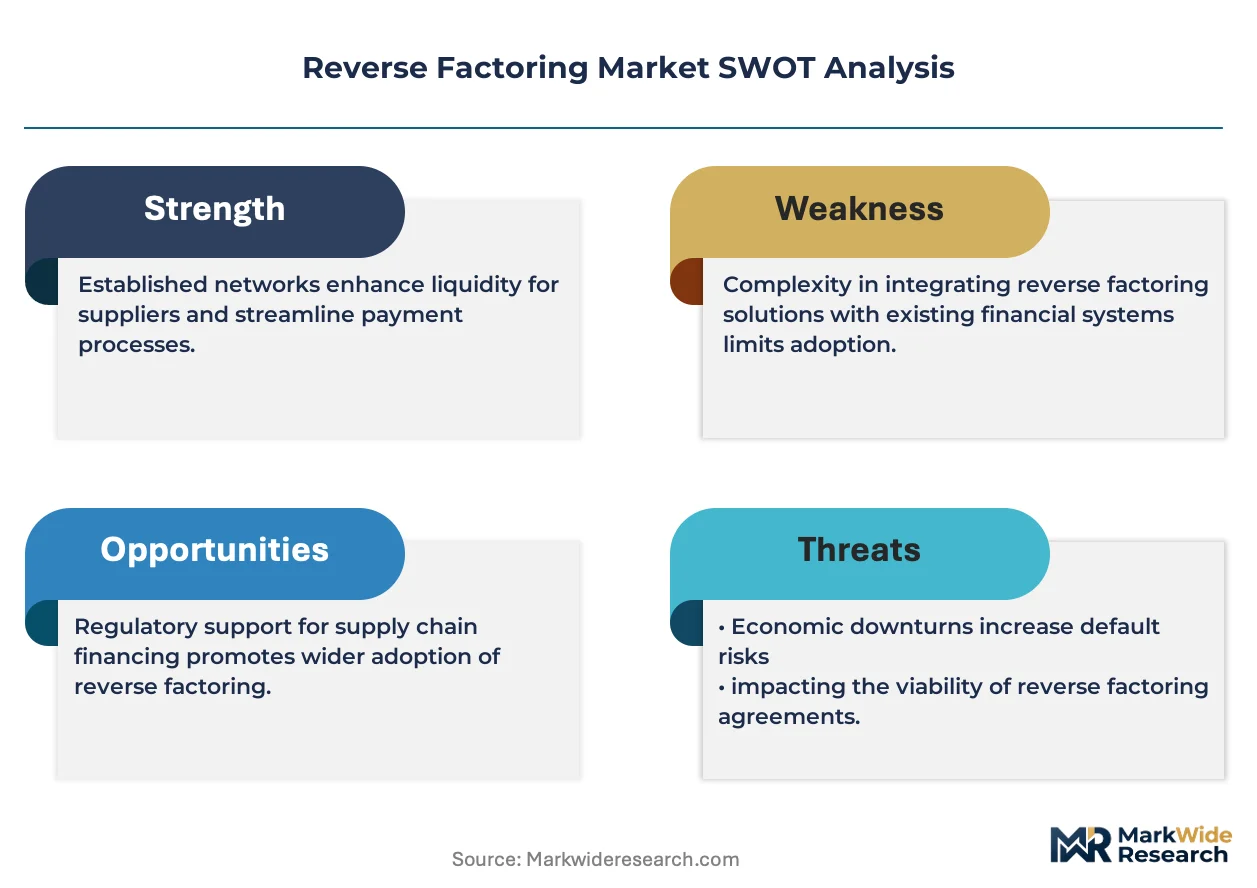
- Basel III liquidity coverage ratios:European bank-sponsored reverse factoring models face capital charge disadvantages that redirect origination toward non-bank intermediaries with lighter balance sheet requirements.
- Concentrated buyer credit dependency:Program economics collapse when anchor buyers experience rating downgrades, creating systemic exposure in sectors with consolidated procurement power like automotive and retail.
- Blockchain verification limitations:Distributed ledger solutions for invoice authentication remain constrained by interoperability gaps with legacy enterprise systems and inconsistent regulatory recognition across jurisdictions.
Strategic Opportunities
- China SME ecosystem stabilization:State-owned enterprises are expanding reverse factoring deployment to counter credit tightening effects on small supplier liquidity, creating volume concentration in the world's largest manufacturing base.
- Real-time payment infrastructure convergence:The intersection of open banking APIs and instant settlement rails enables dynamic discounting models that capture value previously lost to payment timing inefficiencies.
- Transportation sector captive finance:Fuel card integrations and freight brokerage networks create embedded origination channels for invoice acceleration products tailored to carrier cash flow cycles.
Industry Challenges
- Legacy system integration complexity:Enterprise procurement platforms require expensive middleware development to connect with multi-bank financing portals, delaying program launch timelines and inflating implementation costs.
- Supplier onboarding attrition:KYC documentation requirements and multi-step enrollment workflows cause abandonment rates exceeding 40% among small suppliers, constraining program network effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Factoring Market |
| Market Size in 2026 | $624.7 Billion |
| Market Size in 2035 | $1,650.59 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Early Payment Programs, Supply Chain Financing, Digital Platforms, Invoice Financing Industry Vertical: Manufacturing, Retail, Construction, Telecommunications Client Type: Small Enterprises, Medium Enterprises, Large Corporations, Public Sector Financing Model: Buyer-led Programs, Supplier-led Programs, Third-party Financing, Bank-sponsored Models |
| Companies Covered | RTS Financial, Apex Capital Corp, Taulia, altLINE, FundThrough, Riviera Finance, eCapital, Scale Funding, Triumph Business Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Factoring Market Evolving Landscape
Digital infrastructure is collapsing the traditional trade finance value chain as automated underwriting and real-time risk pricing displace manual credit assessment. Three interconnected developments are accelerating this structural shift.
Artificial intelligence-powered credit decisioning is migrating from rules-based scoring engines to machine learning models trained on transactional behavioral data. Large corporate buyers in manufacturing and retail are adopting these systems to extend programmatic early payment offers to thousands of suppliers simultaneously. The technology is compressing origination costs to sub-basis-point levels previously unattainable through manual underwriting.
China's NMPA and SAMR oversight frameworks are imposing capital reserve requirements on fintech lending platforms that favor bank-affiliated digital originators over standalone operators. The regulatory architecture is redirecting platform development toward joint venture structures with licensed financial institutions. Domestic technology providers are responding by deepening API partnerships with state-owned banks to maintain market access.
Enterprise procurement organizations are consolidating supplier finance decisions under centralized treasury functions rather than decentralized purchasing units. This behavioral shift is displacing fragmented, relationship-driven bank selection with competitive platform auctions that compress financing spreads. The concentration is most visible in German automotive supply chains, where OEMs now mandate participation in unified reverse factoring programs as a supplier qualification requirement.
Reverse Factoring Market Segmentation
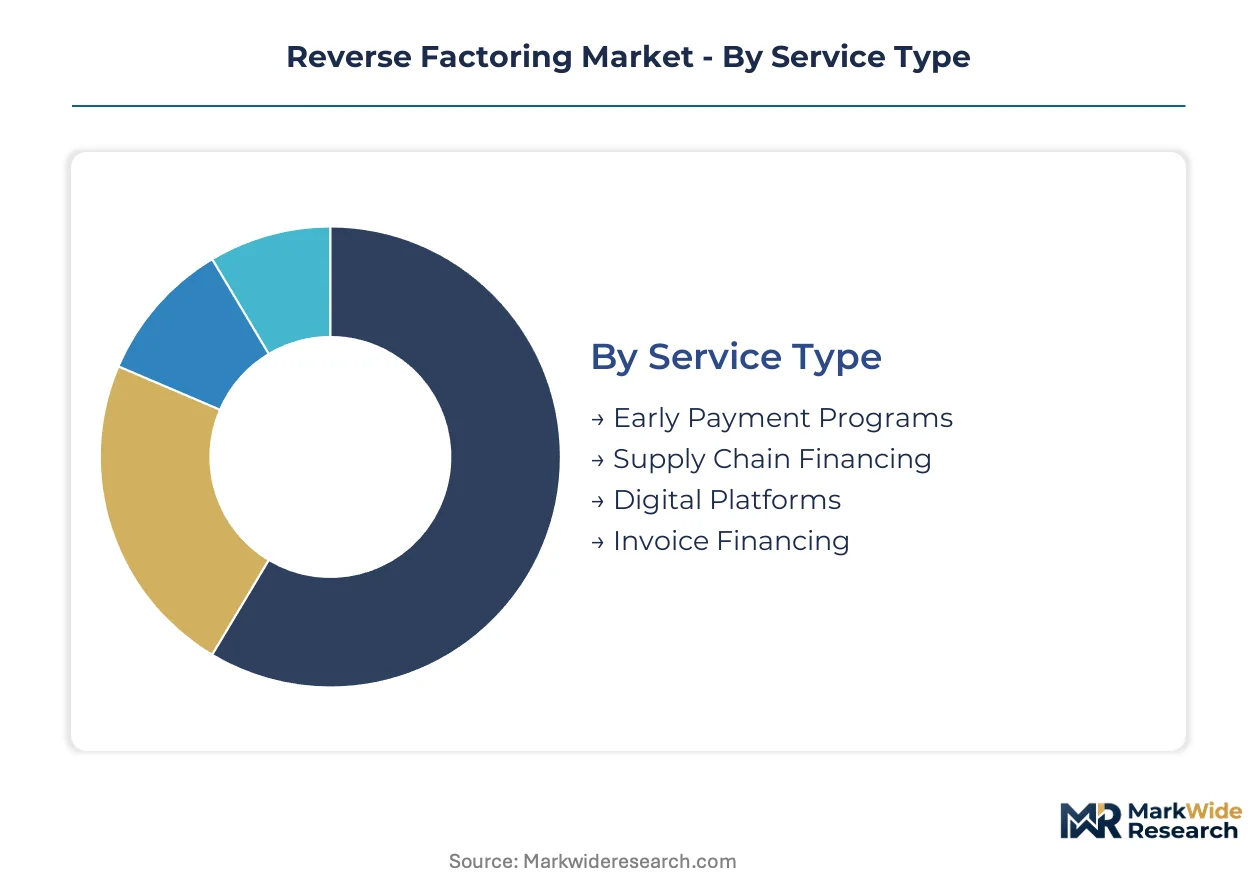
Reverse factoring segmentation reveals how transaction velocity, counterparty risk profiles, and technology adoption create distinct commercial pockets. Understanding these divisions exposes where capital efficiency gains concentrate and which program structures resist margin compression.
Service Type:
Cycle times vary dramatically across service types, with real-time platforms compressing settlement windows from weeks to hours while traditional invoice products retain multi-day documentation burdens.
- Supply Chain Financing:Embedded working capital programs integrated directly into enterprise procurement systems command the largest transaction volumes. Manufacturing buyers in Germany and Mexico anchor demand as just-in-sequence production pressures intensify liquidity needs across tiered supplier bases.
- Digital Platforms:API-driven onboarding and automated invoice matching displace manual workflows, collapsing verification timelines from days to minutes. These platforms expand most quickly as open banking infrastructure matures and real-time payment rails proliferate across European and Asian markets.
- Early Payment Programs:Dynamic discounting models capture value from payment timing inefficiencies, prevalent in retail and automotive supply chains with high invoice frequency.
- Invoice Financing:Standalone receivables purchase retains relevance for suppliers outside approved buyer programs, particularly smaller enterprises lacking procurement system integration.
Supply Chain Financing anchors the volume base while Digital Platforms gain share at the steepest rate.
Industry Vertical:
Margin structures diverge sharply by vertical, with automotive and retail procurement power enabling aggressive supplier finance terms while construction's project-based billing resists standardization.
- Manufacturing:Automotive OEMs deploy buyer-led programs as supplier qualification requirements, concentrating margin capture with originating corporates. German and Mexican production clusters drive program adoption amid raw material cost volatility.
- Retail:High invoice frequency and concentrated buyer power create ideal conditions for programmatic early payment offers. Large merchants leverage machine learning credit decisioning to extend financing to thousands of suppliers simultaneously.
- Telecommunications:Equipment procurement and maintenance contracts generate recurring receivables suitable for structured programs, though network infrastructure cycles extend duration versus consumer-facing verticals.
- Construction:Project-based milestone billing and lien complexity fragment demand, limiting reverse factoring penetration compared to continuous procurement environments.
Manufacturing dominates transaction value while Retail shows the most rapid platform adoption trajectory.
Client Type:
Customer scale determines onboarding economics and risk pricing granularity, with large corporates capturing program control while smaller enterprises face higher attrition in enrollment workflows.
- Large Corporations:Centralized treasury functions consolidate supplier finance decisions, displacing fragmented bank selection with competitive platform auctions. These buyers mandate program participation as contractual requirements.
- Public Sector:EU Late Payment Directive mandates maximum 60-day terms, mechanically expanding eligible receivables volumes across European government procurement systems.
- Medium Enterprises:Growing adoption as cloud-native platforms reduce implementation thresholds, though middleware costs still delay program launches.
- Small Enterprises:KYC documentation requirements and multi-step enrollment cause abandonment rates exceeding 40%, constraining network effects despite acute working capital needs.
Large Corporations control program origination while Public Sector contracts expand fastest under regulatory mandate.
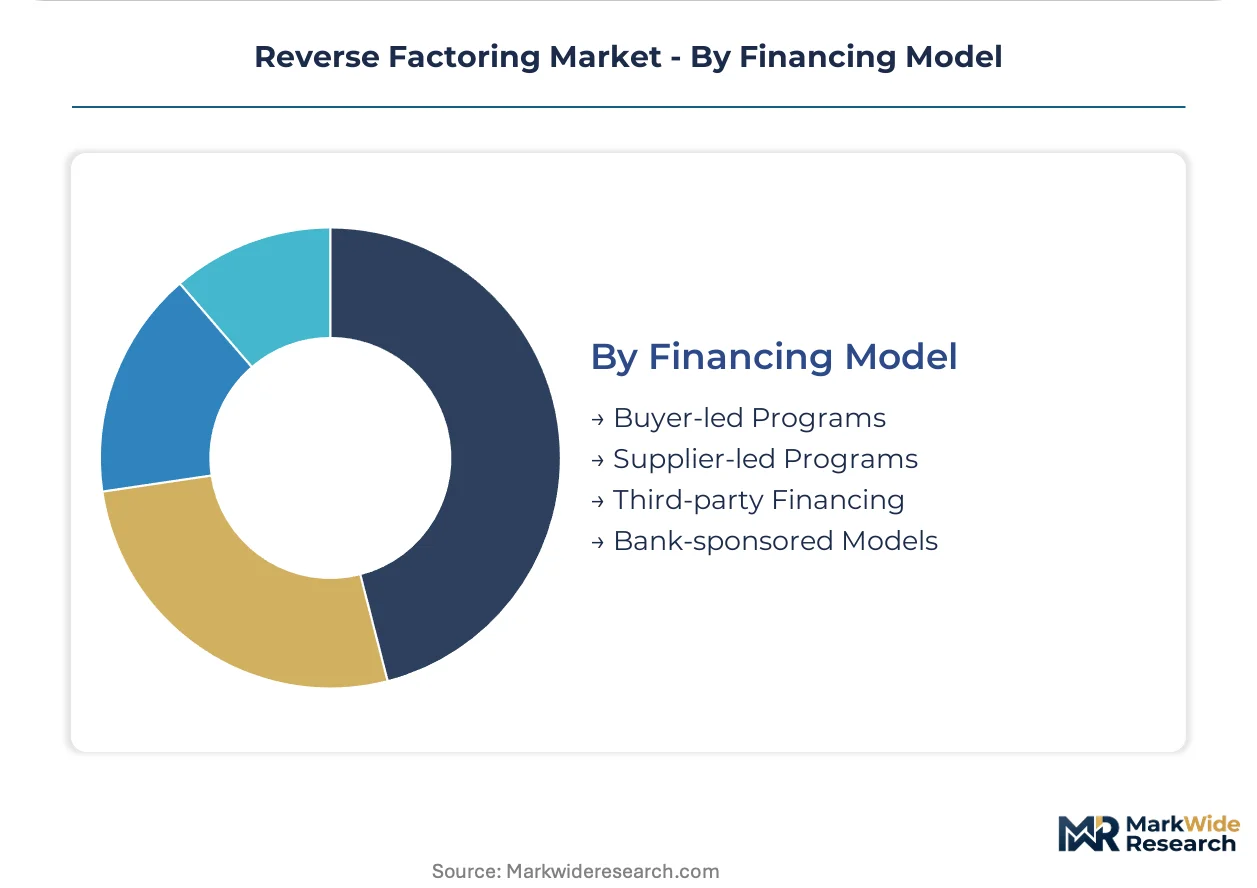
Financing Model:
Balance sheet intensity separates models, with bank-sponsored structures facing capital charge disadvantages under Basel III while distributed fintech infrastructure captures migrating origination.
- Buyer-led Programs:Credit risk anchors to the buyer's rating rather than the supplier's, enabling favorable discount rates. These programs concentrate margin capture with originating corporates and dominate automotive supply chains.
- Third-party Financing:Institutional funders seeking short-duration, trade-linked yield distribute risk across diversified pools. The model expands as bank balance sheet constraints redirect origination.
- Bank-sponsored Models:European lenders face liquidity coverage ratio disadvantages, compressing margins and ceding share to lighter intermediaries.
- Supplier-led Programs:Less prevalent as suppliers lack procurement leverage to structure favorable terms; remains niche for strategic vendors with irreplaceable components.
Buyer-led Programs anchor current volume while Third-party Financing climbs the fastest as capital migrates off bank balance sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Late Payment Directive and Basel III liquidity coverage ratios are redirecting reverse factoring origination toward balance-sheet-light intermediaries across key manufacturing economies. State-owned enterprises in China deploy supplier finance to stabilize SME liquidity amid credit tightening.
Germany
Automotive OEMs mandate reverse factoring participation as supplier qualification requirements across tiered production networks. The EU Late Payment Directive's 60-day maximum term for public contracts mechanically expands eligible receivables volumes in federal procurement systems. Stuttgart and Wolfsburg production clusters anchor buyer-led program adoption as raw material cost volatility intensifies working capital pressures.
China
State-owned enterprises expand reverse factoring deployment to counter credit tightening effects on small supplier ecosystems. NMPA and SAMR oversight frameworks impose capital reserve requirements favoring bank-affiliated digital originators over standalone operators. Yangtze River Delta manufacturing bases concentrate program volume as SOEs stabilize SME liquidity through structured payable programs.
Mexico
Automotive supply chains accelerate buyer-led program adoption as just-in-sequence production pressures intensify liquidity needs across tiered supplier bases. Nearshoring manufacturing investments expand eligible receivables pools for structured supplier finance. Nuevo León and Bajío Region production clusters drive working capital optimization through embedded procurement system financing.
United States
Fortune 500 procurement organizations consolidate supplier finance decisions under centralized treasury functions, displacing fragmented bank selection with competitive platform auctions. Open banking APIs and real-time payment rails enable dynamic discounting models capturing value from payment timing inefficiencies. Detroit automotive and Dallas-Fort Worth logistics clusters anchor transportation sector factoring through fuel card integrations and freight brokerage networks.
United Kingdom
Post-Brexit trade finance restructuring redirects reverse factoring origination toward non-bank platforms with lighter regulatory capital requirements. FCA oversight of supply chain finance disclosure standards shapes program transparency requirements for listed corporates. London's financial services concentration supports third-party financing model expansion as institutional funders seek short-duration, trade-linked yield.
Reverse Factoring Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented competitive landscape where cloud-native platforms challenge traditional bank-sponsored models. Balance-sheet-light intermediaries capture origination migrating from European lenders constrained by Basel III liquidity coverage ratios. Two strategic archetypes dominate: enterprise buyer relationship platforms anchoring Fortune 500 accounts, and sector-specialist operators embedding finance through captive distribution networks. Competitive moves concentrate on API-driven middleware development and strategic partnerships with ERP system providers.
Among platform-based intermediaries, Taulia occupies a position exemplifying cloud-native architecture deployment across enterprise buyer relationships. FundThrough represents the SME invoice acceleration archetype through automated underwriting pipelines. Triumph Business Capital anchors transportation sector specialization through embedded origination channels. These three players illustrate how technology infrastructure and sector focus separate competitive positions in a market where transaction velocity and onboarding economics determine scale.
| Leading Market Players |
|---|
| RTS Financial |
| Apex Capital Corp |
| Taulia |
| altLINE |
| FundThrough |
| Riviera Finance |
| eCapital |
| Scale Funding |
| Triumph Business Capital |
| Others |
Value Network & Pricing Analysis
Undercapacity in European bank-sponsored reverse factoring channels is redirecting origination toward non-bank platforms, compressing financing spreads as distributed fintech infrastructure captures migrating volume. This utilization shift simultaneously intensifies supplier onboarding competition and erodes the pricing power traditionally held by balance-sheet-heavy intermediaries.
Pricing Analysis
Buyer credit rating tiering creates the primary spread differentiation in reverse factoring programs, with investment-grade anchors commanding discount rates significantly below sub-investment-grade counterparts. Program economics stratify across three tiers: large corporate-led structures with centralized treasury functions, mid-market buyer arrangements through multi-bank portals, and standalone supplier financing outside approved programs. Cost compression in bank-sponsored models is intensifying because Basel III liquidity coverage ratios impose capital charge disadvantages, forcing European lenders to cede margin to lighter intermediaries. Small enterprises exhibit the highest price sensitivity, with KYC documentation burdens and multi-step enrollment workflows driving abandonment rates that constrain their access to favorable terms.
Supply Chain Analysis
Cloud-native platform providers including Taulia and FundThrough hold the dominant contract-origination capacity in distributed reverse factoring infrastructure, displacing traditional bank balance sheet deployment. Supply concentration centers on Germany, China, and Mexico for automotive sector programs, with the United States anchoring transportation and logistics-focused factoring. Technology inputs draw from API development talent pools and real-time payment rail integrations, while risk assessment capabilities hinge on machine learning model training data and ERP system partnerships. Single-source vulnerability runs through buyer credit rating dependency, where anchor buyer downgrades trigger systemic program collapses. Distribution runs through embedded procurement system integrations, with enterprise treasury departments consolidating supplier finance decisions under centralized functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse factoring is experiencing high-growth disruption as API-driven invoice matching collapses verification timelines from days to minutes, with the EU Late Payment Directive mechanically expanding eligible receivables volumes across European public procurement systems.
For Market Incumbents: Build switching-cost moats through deep ERP system integrations and captive fuel card networks in transportation verticals. Incumbents should defend against cloud-native platform encroachment by accelerating middleware development for multi-bank portal connectivity, while investing in machine learning credit decisioning to compress origination costs below fintech challenger levels. Channel control through freight brokerage networks represents the critical lever for transportation specialists. For New Entrants and Emerging Players: Pursue white-space opportunity in China SME ecosystem stabilization, where state-owned enterprise supplier finance programs remain underpenetrated by foreign platforms. New entrants should target medium enterprises in Mexico's nearshoring manufacturing corridors, leveraging open banking API infrastructure to bypass legacy middleware requirements that delay program launches. A direct go-to-market angle through strategic partnerships with domestic technology providers offers the fastest path to state-owned bank integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise buyer relationship platforms with Fortune 500 account concentration, as these structures embed working capital programs into procurement system workflows that resist displacement. Long-term viability favors balance-sheet-light intermediaries with diversified funding sources over bank-sponsored models facing regulatory capital constraints. Acquisition targets should display deep API integration capabilities and sector-specific captive distribution channels. The signal to watch is real-time payment infrastructure convergence with open banking rails, which enables dynamic discounting models that capture previously lost payment timing value.| Strategic Initiative | Industry Significance |
|---|---|
| API-Driven Platform Integration | Real-time invoice matching with SAP and Oracle ERP systems collapses verification timelines from days to minutes. |
| Transportation Sector Captive Finance | Fuel card integrations and freight brokerage networks embed origination into carrier cash flow cycles. |
| Strategic Partnership with State-Owned Banks | Joint venture structures satisfy NMPA and SAMR capital reserve requirements in China fintech lending. |
| Machine Learning Credit Decisioning | Behavioral data-trained models compress origination costs to sub-basis-point levels for programmatic supplier offers. |
| Dynamic Discounting Model Deployment | Open banking APIs and instant settlement rails capture value from payment timing inefficiencies in retail supply chains. |
Research Methodology
The analysis maps supply chain financing programs, digital platform intermediaries, early payment arrangements, and invoice financing products, each validated through structured dialogue with corporate treasury executives, procurement platform engineers, fintech product managers, and institutional credit officers. Primary intelligence combines with secondary validation from Basel Committee regulatory filings, EU Commission late payment directive implementation reports, SEC 10-K supply chain finance disclosures, and China NMPA fintech lending oversight documents. Bottom-up transaction volume estimates triangulate against top-down working capital optimization spending patterns across automotive, retail, and manufacturing verticals.
Assumptions hold fixed the EU Late Payment Directive's 60-day maximum term mandate and Basel III liquidity coverage ratio implementation timelines, while varying open banking API adoption rates and real-time payment infrastructure deployment speeds. The modeling framework segments by service type, industry vertical, client type, and financing model, with additional dimensioning by buyer credit rating tier and geographic regulatory cluster. CAGRs derive from regression analysis against historical working capital intensity ratios and procurement system digitization curves, with automotive production volatility and SME credit tightening severity serving as key forecast sensitivity inputs.
Sensitivities concentrate around regulatory enforcement intensity of EU late payment rules, anchor buyer credit rating migration, and open banking API standardization timelines across European and Asian markets. Forecasts reflect assumptions regarding continued migration of origination from bank balance sheets to distributed fintech infrastructure. Quarterly review of automotive OEM program participation mandates, China SOE supplier finance expansion rates, and platform onboarding completion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Online Investment Platform Market
Financial Services
India Legal Services Market
Financial Services
ATM Software Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Canada Credit Cards Market
Financial Services
Capital Restructuring Services Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
China Factoring Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Germany Factoring Services Market
Financial Services
Financial Advisory Services Market
Financial Services
Debt Settlement Solution Market
Financial Services
Factoring Services Market
Financial Services
North America Financial Advisory Services Market
Financial Services
ATM Management Service Market