
 China Trade Finance Market | 2026-2036
China Trade Finance Market Size, Share, and Industry Trends Forecast 2026-2036
China Trade Finance Market Analysis
Asset-light supply chain finance is fragmenting traditional bank dominance in documentary credit origination. Industrial and Commercial Bank of China leverages its state-backed balance sheet to anchor large-ticket letter of credit volumes. China Merchants Bank competes through technology leadership in digital trade platforms. Ping An Bank differentiates via integrated fintech stacks that streamline receivables financing for mid-market manufacturers.
Trade finance encompasses the specialized banking instruments, credit facilities, and risk mitigation tools that facilitate international and domestic goods exchange, including documentary credits with standardized SWIFT messaging protocols, bank guarantees backed by tier-one capital reserves, and factoring arrangements secured against verified accounts receivable. Its primary commercial purpose is to bridge payment timing gaps between exporters and importers while allocating counterparty default risk to financial intermediaries. Supply chain finance and export financing currently lead service-type revenue pools, driven by working capital pressures across China's manufacturing base. Letter of credit products retain structural importance in high-value transactions, though receivables financing is accelerating fastest among small and medium transaction-size segments where speed of execution outweighs cost sensitivity.
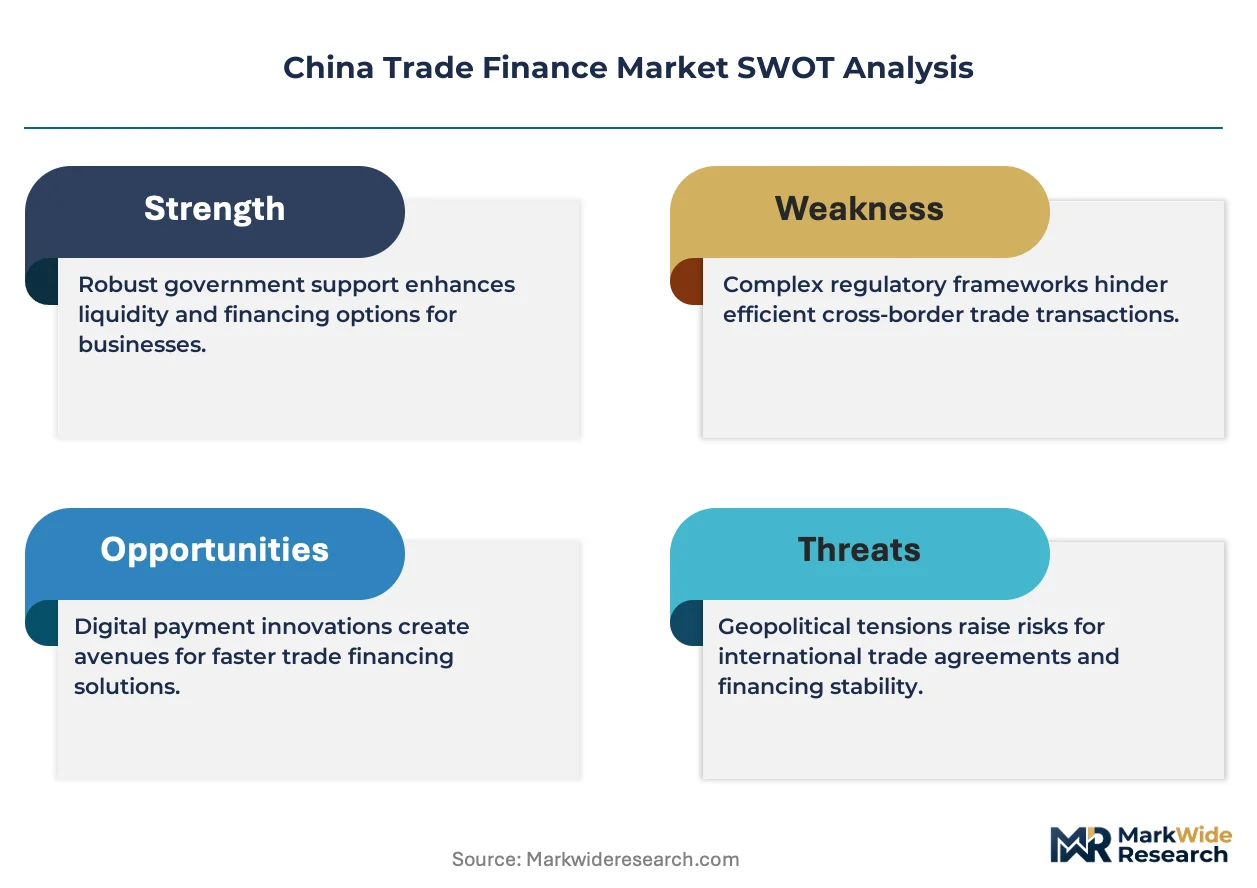
The People's Bank of China shapes market structure through digital currency settlement pilots and cross-border payment system directives, while the China Banking and Insurance Regulatory Commission enforces capital adequacy requirements that constrain bank guarantee issuance volumes. SAMR's fintech licensing frameworks determine which non-bank platforms can intermediate trade credit flows. Stakeholders must monitor how regulatory convergence between traditional banking supervision and digital payment oversight redefines competitive entry barriers.
Market Dynamics
The People's Bank of China's digital yuan settlement pilots are compressing documentary credit processing timelines from weeks to hours, forcing commercial banks to restructure trade finance product architectures around real-time clearing rails rather than traditional correspondent banking networks.
Growth Catalysts
- Cross-border e-commerce expansion:Platforms in the Yangtze River Delta manufacturing corridor are embedding supply chain finance instruments directly into checkout flows, pulling mid-market exporters into formal trade credit systems.
- Dual carbon policy frameworks:China's emissions intensity targets are greening letter of credit eligibility criteria, channeling capital toward low-carbon export manufacturers through preferential guarantee terms.
- Blockchain-based document verification:Distributed ledger protocols are reducing fraud rates in bills of lading and commercial invoices, cutting due diligence costs for receivables financing originators.
Market Restraints
- Capital adequacy compression:The China Banking and Insurance Regulatory Commission's tier-one reserve requirements constrain guarantee issuance volumes at joint-stock banks during credit-tightening cycles.
- Concentrated manufacturing exposure:Export finance portfolios cluster heavily in electronics and textiles clusters around Shenzhen and Dongguan, amplifying sector-specific demand shocks.
- Documentary credit substitution:Open account trading terms are displacing traditional letters of credit among established trading partners with long payment histories.
Strategic Opportunities
- Central and western provinces:Underpenetrated manufacturing bases in Sichuan and Chongqing lack correspondent banking density, creating white space for fintech-anchored trade credit platforms.
- Carbon-linked trade finance:Emissions-verified supply chain instruments align with EU Carbon Border Adjustment Mechanism compliance requirements for Chinese exporters.
- API-embedded financing:Logistics platforms and customs data systems are opening distribution channels that pre-qualify exporters for automated receivables advances.
Industry Challenges
- Legacy core banking integration:State-owned institutions struggle to interface digital yuan settlement modules with decades-old transaction processing architectures.
- Trade documentation standardization:Inconsistent electronic bill of lading formats across ports and carriers delay automated verification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Trade Finance Market |
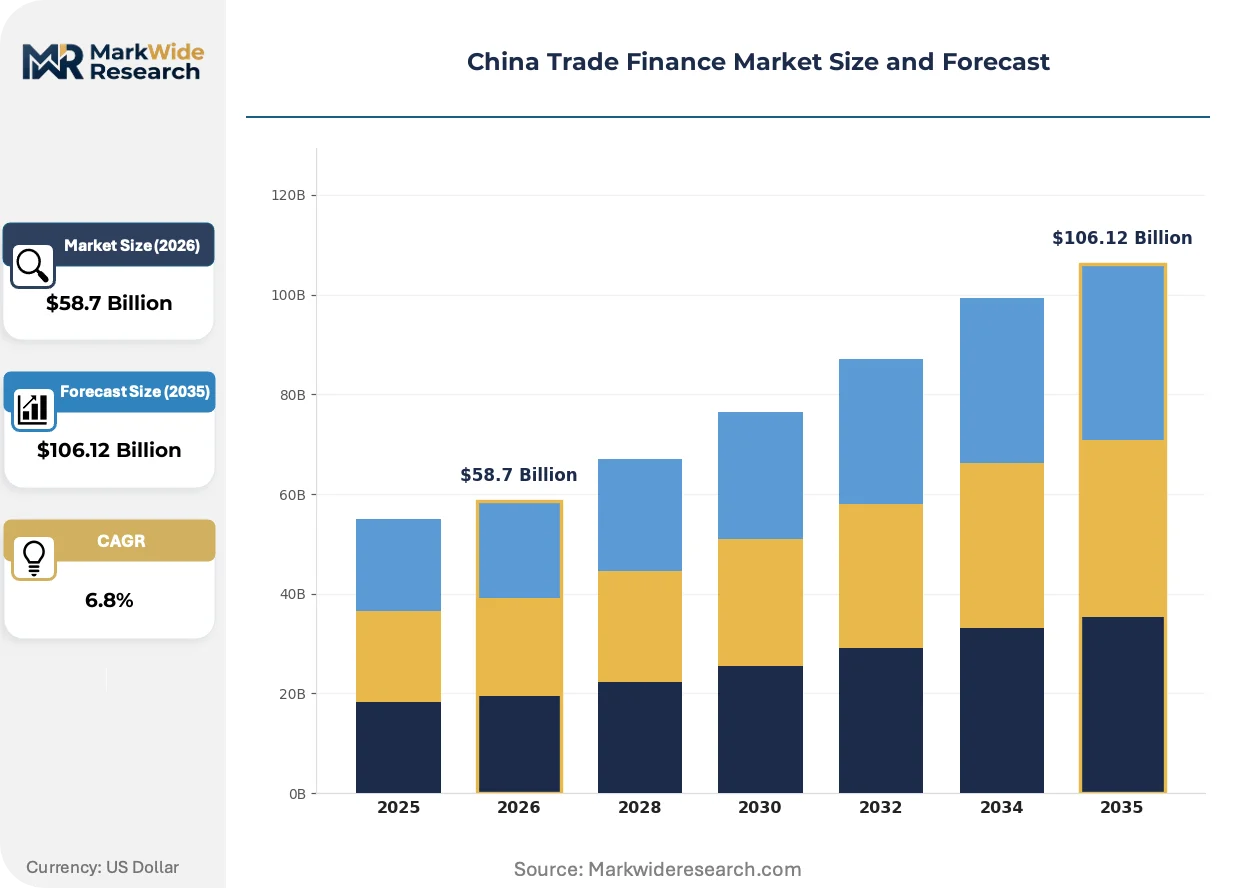
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Documentary Credit, Trade Credit, Export Financing, Supply Chain Finance End User: Manufacturers, Wholesalers, Exporters, Importers Product Type: Letter of Credit, Bank Guarantees, Receivables Financing, Factoring Transaction Size: Small, Medium, Large, High-Value |
| Companies Covered | China Merchants Bank, Huaxia Bank, China CITIC Bank, China Zheshang Bank, China Guangfa Bank, China Minsheng Bank, Ping An Bank, Industrial and Commercial Bank of China, China Everbright Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Trade Finance Market Emerging Trajectories
Trade finance infrastructure is converging around programmable money and real-time data feeds, collapsing the information asymmetries that historically justified multi-day document examination periods and correspondent banking fees.
Artificial intelligence-powered credit scoring is hybridizing traditional balance-sheet analysis with alternative data streams from logistics platforms, customs declarations, and tax records. Mid-market manufacturers in Zhejiang and Jiangsu provinces are adopting these tools fastest, drawn by sub-24-hour approval windows. The compression of origination timelines is forcing incumbent banks to unbundle relationship-managed credit from automated working capital lines.
SAMR's fintech licensing frameworks are tightening capital and data governance requirements for non-bank trade finance platforms, elevating compliance costs for technology-first originators. The regulatory friction most acutely affects receivables marketplaces without banking licenses, pushing several toward strategic partnerships with licensed joint-stock banks. Guangdong-based platforms are responding by pursuing trust company licenses to retain direct lending capabilities.
Export manufacturers are consolidating banking relationships around institutions offering integrated foreign exchange hedging and supply chain finance, displacing fragmented multi-bank arrangements. Single-relationship banking is displacing the traditional model of separate trade finance, cash management, and FX providers among transaction-size exporters in the Pearl River Delta. This concentration is most visible among electronics assemblers facing volatile renminbi-dollar movements.
China Trade Finance Market Segmentation
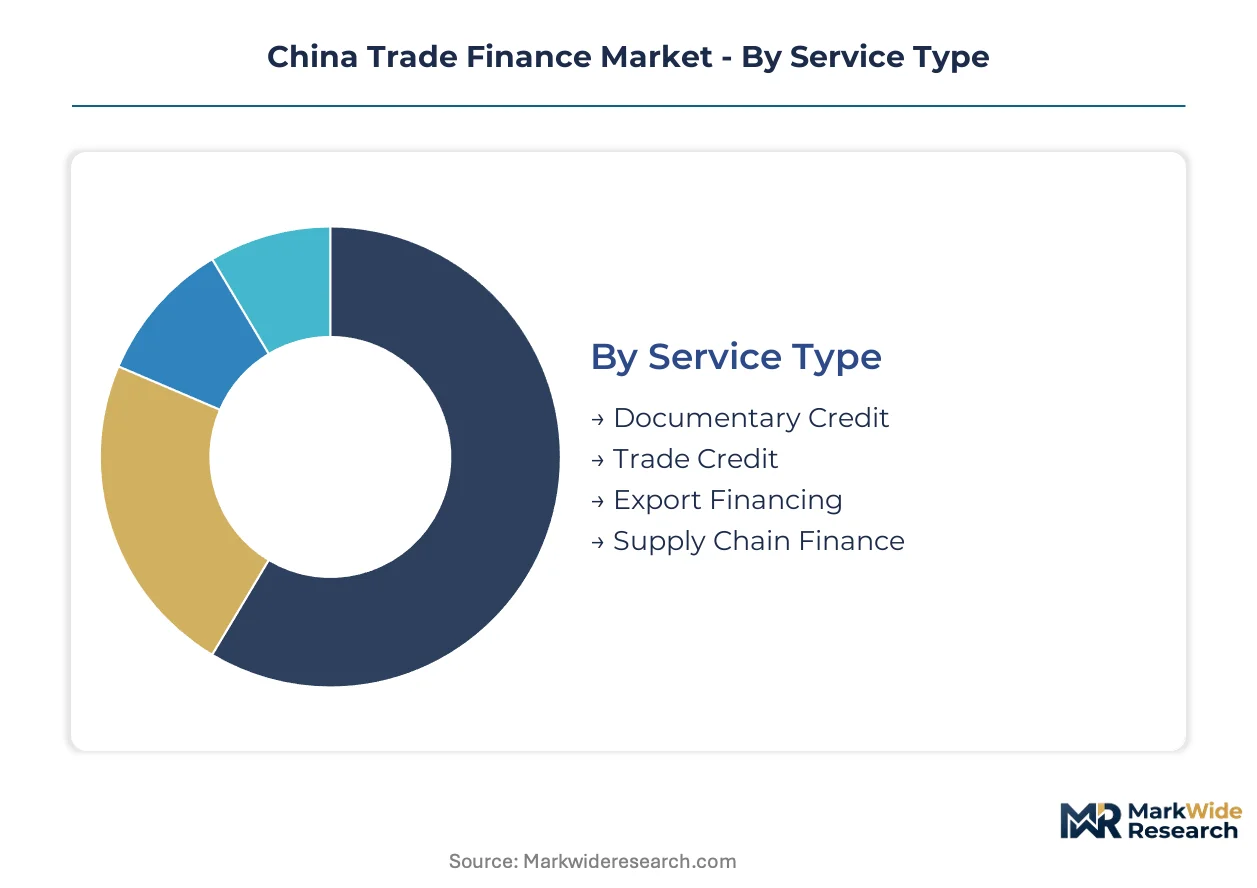
China's trade finance market segments along four functional dimensions that reflect divergent risk profiles, operational complexity, and servicing intensity. Each category captures distinct commercial logic governing how financial institutions structure working capital solutions across the country's manufacturing and export base.
Service Type:
After-sales servicing intensity varies dramatically across service types, with documentary credit requiring intensive documentation review and dispute resolution versus automated supply chain finance platforms.
- Supply Chain Finance:Programmatic financing solutions anchored to verified purchase orders and inventory positions within buyer-supplier networks. Demand concentrates among electronics assemblers in the Pearl River Delta where buyer creditworthiness substitutes for supplier collateral, compressing origination timelines through ERP integration.
- Export Financing:Pre-shipment working capital facilities secured against confirmed export contracts and documentary evidence of production milestones. Yangtze River Delta textile exporters draw heavily on these instruments to bridge raw material procurement and ocean freight dispatch.
- Documentary Credit:Traditional letter-of-credit issuance with SWIFT messaging protocols and multi-party document examination.
- Trade Credit:Open-account supplier financing arrangements without bank intermediation.
By volume, export financing leads among service types. By growth pace, supply chain finance is expanding most quickly through platform-embedded distribution channels.
End User:
Cost tier stratification shapes end-user segmentation, with manufacturers accessing preferential pricing through collateralized facilities versus wholesalers paying risk-adjusted spreads.
- Manufacturers:Production-stage enterprises with tangible asset bases and verifiable output records qualifying for secured revolving credit structures. Zhejiang and Jiangsu province machinery producers represent the densest concentration, leveraging factory equipment and inventory as dual collateral pools.
- Exporters:Shipment-oriented firms requiring foreign exchange hedging bundled with pre-export working capital. Electronics exporters in Shenzhen command the largest aggregate facility sizes, though fragmentation across thousands of mid-market firms complicates relationship management economics.
- Wholesalers:Inventory-heavy intermediaries with limited production assets and higher counterparty risk profiles.
- Importers:Domestic distribution enterprises financing inbound shipments against warehouse receipt structures.
By volume, manufacturers dominate end-user flows. By growth pace, exporters are gaining share fastest through cross-border e-commerce platform integration.
Product Type:
Application maturity differentiates product types, with letter of credit representing decades-old infrastructure versus receivables financing built on emerging data verification architectures.
- Receivables Financing:Advance facilities against verified accounts receivable with automated eligibility scoring through tax and logistics data integration. Mid-market manufacturers in Dongguan adopt these instruments fastest, drawn by sub-24-hour funding windows that displace traditional documentary credit timelines.
- Letter of Credit:Bank-issued payment undertakings governed by UCP 600 protocols with standardized document examination procedures. High-value machinery transactions between established trading partners retain structural dependence on this instrument despite accelerating open-account migration.
- Bank Guarantees:Standby credit support instruments backing contractual performance obligations.
- Factoring:True-sale receivables purchase arrangements with credit risk transfer to specialized factors.
By volume, letter of credit retains leadership among product types. By growth pace, receivables financing shows the steepest expansion trajectory through fintech-anchored origination platforms.
Transaction Size:
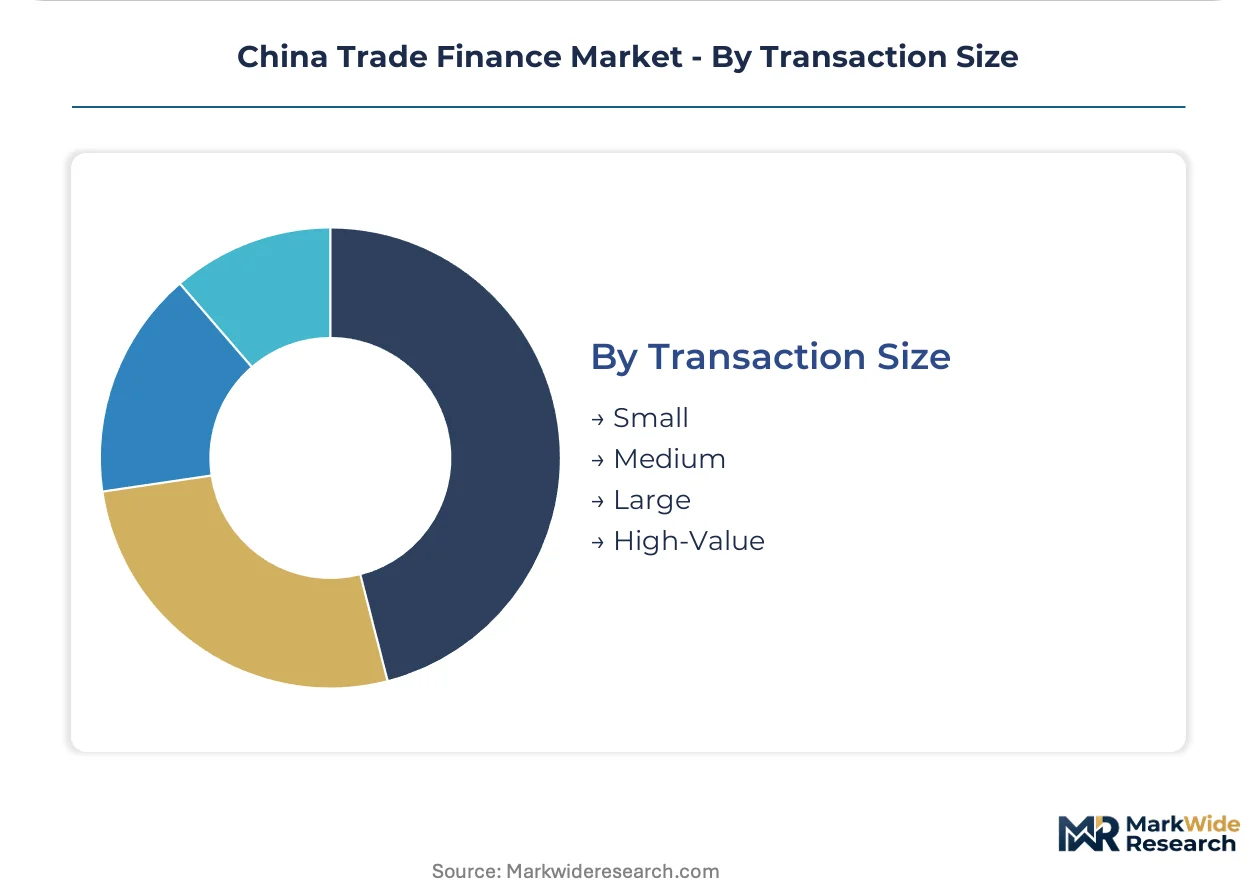
Customer type concentration defines transaction size segmentation, with relationship-managed large-ticket business contrasting against automated small-ticket processing.
- Medium:Transaction ranges where hybrid servicing models blend relationship oversight with partial automation. Jiangsu province automotive parts exporters cluster in this segment, requiring customized foreign exchange hedging alongside standardized working capital lines.
- Small:Automated origination through platform-embedded credit decisioning with minimal manual intervention. Cross-border e-commerce sellers in the Yangtze River Delta manufacturing corridor drive volume concentration, accepting standardized pricing in exchange for execution speed.
- Large:Bilaterally negotiated facilities with bespoke structuring and dedicated relationship management.
- High-Value:Syndicated or participated structures distributing exposure across multiple banking institutions.
By volume, medium transaction sizes lead. By growth pace, small transactions are climbing the fastest through API-embedded financing distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The People's Bank of China's digital yuan settlement pilots and cross-border payment directives are redistributing trade finance activity across domestic manufacturing corridors. Provincial governments in Jiangsu, Zhejiang, and Guangdong have launched supply chain finance subsidy programs to accelerate SME onboarding.
Yangtze River Delta
Shanghai and Suzhou electronics exporters drive demand for receivables financing instruments. The Jiangsu provincial government offers interest rate subsidies for supply chain finance platforms serving cross-border e-commerce sellers. Ningbo port operators are integrating blockchain-based bill of lading verification into documentary credit workflows.
Pearl River Delta
Shenzhen machinery manufacturers consolidate banking relationships around integrated FX hedging and working capital lines. Guangdong SAMR enforces fintech licensing requirements that push receivables marketplaces toward trust company partnerships. Dongguan automotive parts suppliers adopt AI-powered credit scoring for sub-24-hour facility approvals.
Beijing-Tianjin-Hebei
State-owned enterprise procurement platforms anchor large-ticket letter of credit volumes. The Beijing municipal government directs state-backed banks to prioritize carbon-linked trade instruments under national dual carbon policy frameworks. Tianjin port authorities pilot digital yuan settlement for import financing documentation.
Sichuan-Chongqing
Underpenetrated manufacturing bases in Chengdu and Chongqing lack correspondent banking density. The Chongqing municipal government subsidizes fintech platform establishment to fill trade credit gaps for electronics assemblers. Local joint-stock banks compete through technology partnerships rather than branch network scale.
Shandong Peninsula
Qingdao textile exporters draw on pre-shipment working capital facilities secured against confirmed export contracts. Shandong provincial regulators enforce capital adequacy requirements that constrain guarantee issuance at regional banks during credit-tightening cycles. Weihai fishing equipment manufacturers cluster in medium transaction-size segments requiring hybrid relationship-automation servicing.
China Trade Finance Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure. State-backed institutions anchor large-ticket documentary credit origination through balance sheet scale, while joint-stock banks differentiate through technology leadership and platform integration. Three archetypes dominate: state-owned commercial banks with correspondent network density, technology-forward joint-stock banks with digital trade platforms, and fintech-anchored specialists with automated receivables capabilities. Competitive moves center on API-embedded financing distribution partnerships and strategic licensing arrangements with logistics data providers.
Among state-backed institutions, Industrial and Commercial Bank of China occupies a position exemplifying balance sheet-driven market anchoring. China Merchants Bank and Ping An Bank represent the technology-forward tier, with the former sitting within digital trade platform leadership and the latter exemplifying integrated fintech stack differentiation for mid-market segments. These three institutions collectively illustrate the competitive spectrum from scale-driven documentary credit dominance to automation-first receivables origination.
| Leading Market Players |
|---|
| China Merchants Bank |
| Huaxia Bank |
| China CITIC Bank |
| China Zheshang Bank |
| China Guangfa Bank |
| China Minsheng Bank |
| Ping An Bank |
| Industrial and Commercial Bank of China |
| China Everbright Bank |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics manufacturing corridor concentrates working capital demand from thousands of mid-market exporters, compressing pricing power among regional joint-stock banks competing for relationship consolidation. The Pearl River Delta's platform-embedded finance penetration creates tiered pricing dynamics where speed of execution commands premium spreads over traditional documentary credit products.
Pricing Analysis
Transaction size creates the primary spread differentiation across China's trade finance landscape. Three-tier pricing structure across premium, standard, and economy levels governs facility origination: large-ticket bilateral negotiations command relationship-managed spreads, medium-ticket hybrid servicing blends automation with customized FX hedging, and small-ticket API-embedded flows accept standardized pricing for sub-24-hour execution. Cost compression in small-ticket segments is intensifying because cross-border e-commerce platforms aggregate exporter demand into concentrated procurement pools. Cross-border e-commerce sellers in the Yangtze River Delta manufacturing corridor exhibit highest price sensitivity, while state-owned enterprise procurement platforms anchored in Beijing-Tianjin-Hebei demonstrate lowest sensitivity due to bundled service requirements.
Supply Chain Analysis
Industrial and Commercial Bank of China, China Merchants Bank, and Ping An Bank hold dominant origination capacity across correspondent banking networks and digital trade platforms. Geographic supply concentration spans three distinct hubs: the Yangtze River Delta anchors receivables financing innovation through ERP-integrated supply chain programs, the Pearl River Delta concentrates export financing demand from electronics assemblers, and Sichuan-Chongqing represents underpenetrated white space where fintech platforms compete through technology partnerships. Raw material dependencies draw from semiconductor components, textile feedstocks, and automotive parts inventories that collateralize working capital facilities. Single-source vulnerability runs through the People's Bank of China's digital yuan settlement infrastructure, where pilot program expansion determines real-time clearing adoption timelines. Distribution runs through logistics platform APIs, customs data systems, and cross-border e-commerce checkout flows that pre-qualify exporters for automated advances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated banking relationships among Pearl River Delta electronics exporters, fragmenting the traditional multi-bank arrangement model and compressing servicing margins for institutions without integrated FX hedging capabilities.
For Market Incumbents: Entrench market position by deepening correspondent banking density in underpenetrated western provinces and accelerating digital yuan settlement module integration with legacy core systems. The threat of fintech-anchored platforms automating receivables origination demands defensive certification investment in SAMR licensing frameworks to retain direct lending capabilities. Capacity addition in Sichuan and Chongqing serves as the priority lever to preempt technology-first entrants from capturing electronics assembler relationships. For New Entrants and Emerging Players: Central and western provinces present the most penetrable geographic white space, where manufacturing bases lack correspondent banking density and municipal governments subsidize fintech platform establishment. Carbon-linked trade instruments aligned with EU Carbon Border Adjustment Mechanism compliance requirements offer the fastest-growing application entry point. API-embedded financing partnerships with logistics platforms and customs data systems provide the essential go-to-market angle for automated receivables advance distribution. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-convergence play because SAMR's tightening fintech licensing frameworks are elevating compliance costs for technology-first originators and pushing receivables marketplaces toward strategic partnerships with licensed joint-stock banks. Acquisition targets should emphasize trust company licenses or banking charters that retain direct lending capabilities without partnership dependency. The signal to watch is municipal subsidy program expansion in underpenetrated provinces, indicating local government commitment to filling trade credit gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Yuan Settlement Integration | Restructures product architectures around real-time clearing rails rather than correspondent banking networks. |
| Trust Company License Acquisition | Retains direct lending capabilities for fintech platforms facing SAMR capital and data governance tightening. |
| API-Embedded Financing Partnership | Opens distribution channels through logistics platforms and customs data systems that pre-qualify exporters. |
| Carbon-Linked Trade Instrument Development | Aligns with EU Carbon Border Adjustment Mechanism compliance requirements for Chinese exporters. |
| Western Province Platform Establishment | Captures underpenetrated manufacturing bases in Sichuan and Chongqing lacking correspondent banking density. |
Methodological Framework
Initial hypotheses were tested against primary input from trade finance product heads at joint-stock banks, supply chain finance platform executives, export manufacturer CFOs, and SAMR regulatory affairs leads, and refined through secondary validation against PBOC digital yuan pilot disclosures, CBIRC capital adequacy circulars, provincial government subsidy program announcements, and customs export data releases. Bottom-up facility origination volumes triangulated against top-down banking sector trade finance asset disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, end user archetype, product instrument, and transaction size tier alongside regional regulatory cluster differentiation reflecting PBOC pilot geography. CAGRs were derived through trend extrapolation adjusted for policy intervention timing. Industry-specific forecast inputs incorporated digital yuan settlement adoption curves and cross-border e-commerce platform penetration rates.
Practitioners should monitor PBOC digital yuan pilot expansion announcements, CBIRC capital adequacy requirement adjustments, and EU Carbon Border Adjustment Mechanism implementation timelines for early signals of forecast revision. Quarterly review of municipal subsidy program activations and fintech licensing grant volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Legal Management Consulting Service Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Global Temporary Labor Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Currency Exchange Software Market
Financial Services
Solar Powered ATM Market
Financial Services
Global Management Consulting Services Market
Financial Services
Trade Finance Market
Financial Services
India Legal Services Market
Financial Services
BFSI A2P SMS Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Online Lottery Market
Financial Services
Source to Pay Market
Financial Services
United States Payroll Services Market
Financial Services
Power Bank Sharing Services Market