
 Contract for Difference Broker Market | 2026-2036
Contract for Difference Broker Market Size, Share, and Industry Trends Forecast 2026-2036
Contract for Difference Broker Market Insights
Retail trader participation is collapsing toward mobile-first demographics while institutional flow stagnates. IG dominates UK and European retail CFD onboarding through proprietary platform technology. eToro leverages social trading network effects to capture younger retail cohorts entering leveraged derivatives. Saxo Bank anchors institutional and high-net-worth segments with multi-asset custody integration.
A contract for difference broker facilitates leveraged derivative trading where the counterparty settles the price differential between contract opening and closing without underlying asset ownership, typically offering margin ratios from 5:1 to 30:1 depending on asset class and jurisdiction. The primary commercial purpose centers on enabling directional speculation and hedging across equities, forex, commodities, indices, and cryptocurrencies through synthetic exposure. Spread-based revenue models capture the majority of retail flow profitability, while API trading platforms command premium pricing from algorithmic and institutional clients requiring direct market access. Commission-based structures concentrate among equities CFD offerings where transparent execution costs attract sophisticated traders.
The UK's Financial Conduct Authority imposes permanent leverage restrictions at 30:1 for major forex pairs and 2:1 for cryptocurrencies, directly constraining broker product architecture. Australia's ASIC and the EU's ESMA maintain parallel leverage caps and negative balance protection mandates that standardize retail risk management across major markets. Cyprus CySEC licensing remains a critical market access gateway for brokers serving European Economic Area clients under MiFID II passporting provisions. Stakeholders must monitor divergent regulatory postures between jurisdictions tightening retail protections and those maintaining lighter-touch frameworks that attract broker migration.
Market Dynamics
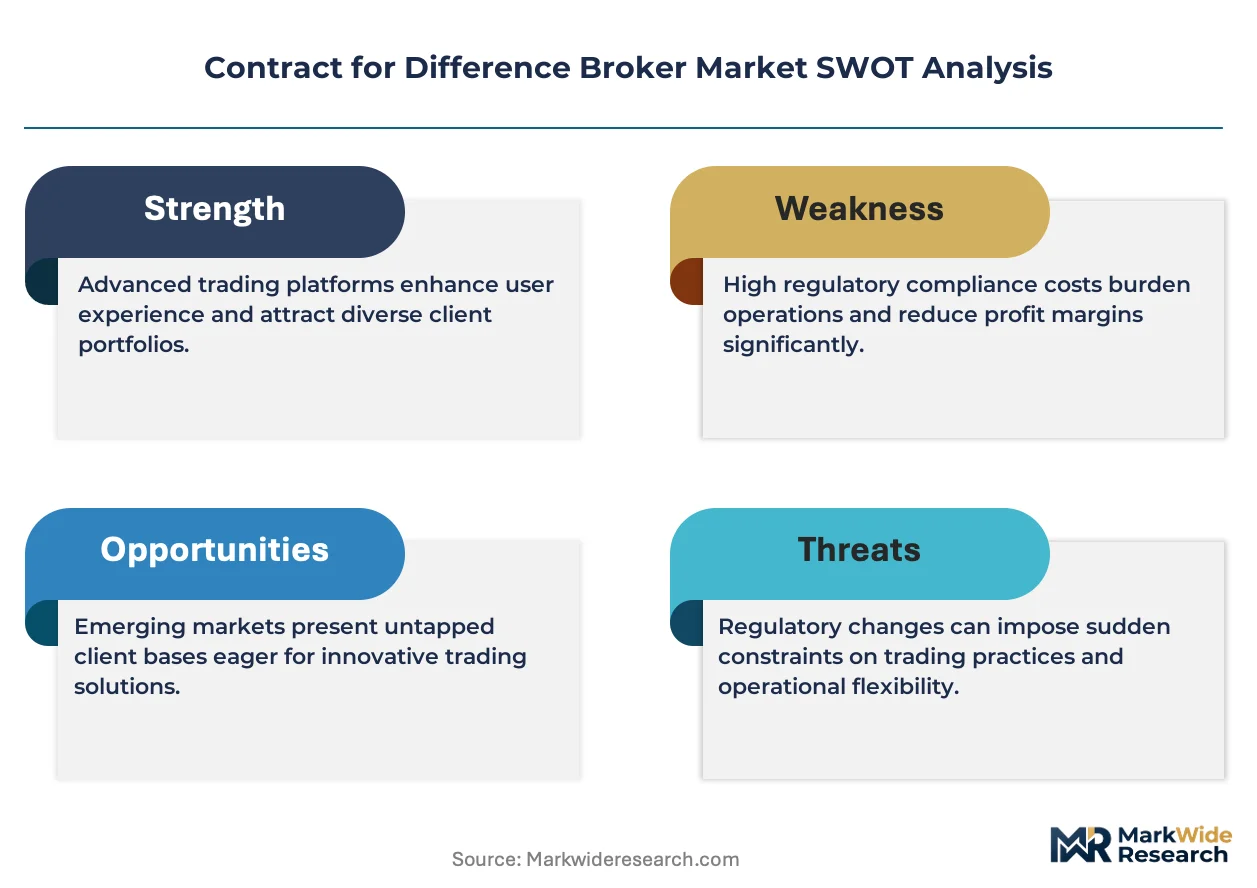
Leverage compression mandates from the UK's Financial Conduct Authority and parallel EU restrictions are forcing CFD brokers to reconstruct revenue models around lower-margin, higher-volume retail flows.
Growth Catalysts
- Mobile Trading Infrastructure:Smartphone-native execution platforms are capturing younger retail demographics across Australia and Germany. Execution latency below 50 milliseconds now determines platform switching costs.
- Cryptocurrency Derivatives Expansion:Synthetic crypto exposure without wallet custody appeals to risk-managed retail segments. Singapore's Payment Services Act provides regulatory clarity that attracts broker licensing.
- ASIC Retail Reforms:Australia's negative balance protection mandate and leverage caps standardized client safeguards. These rules reduced broker litigation exposure while legitimizing the product category.
Market Restraints
- Regulatory Arbitrage Constraints:MiFID II passporting restrictions limit Cyprus-based brokers from seamless EU market access. Compliance fragmentation raises operational overhead.
- Prime Brokerage Concentration:Tier-one liquidity providers cluster in London and New York. Smaller brokers face counterparty credit compression during volatility spikes.
- Client Acquisition Cost Inflation:Digital marketing saturation across established jurisdictions pushes cost-per-qualified-lead upward. Meta and Google advertising restrictions on leveraged products compound this pressure.
Strategic Opportunities
- Southeast Asian Retail Penetration:Thailand and Vietnam exhibit low CFD awareness but rising equity market participation. Local language platforms and domestic payment rails unlock access.
- API Institutional Connectivity:Direct market access protocols attract algorithmic traders and commodity hedgers. White-label infrastructure reduces time-to-market for regional entrants.
- ESG-Themed Index Products:Synthetic exposure to sustainability benchmarks aligns with EU CSRD disclosure trends. Green taxonomy compliance creates product differentiation.
Industry Challenges
- Quantitative Risk Modeling Talent:Stress-testing engines for 30:1 leverage products require specialized quantitative developers. Competition from fintech and crypto exchanges tightens hiring pipelines.
- Cross-Border Compliance Orchestration:Divergent margin rules between the UK, EU, and Australia force parallel platform architectures. Real-time regulatory monitoring systems demand sustained capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract for Difference Broker Market |
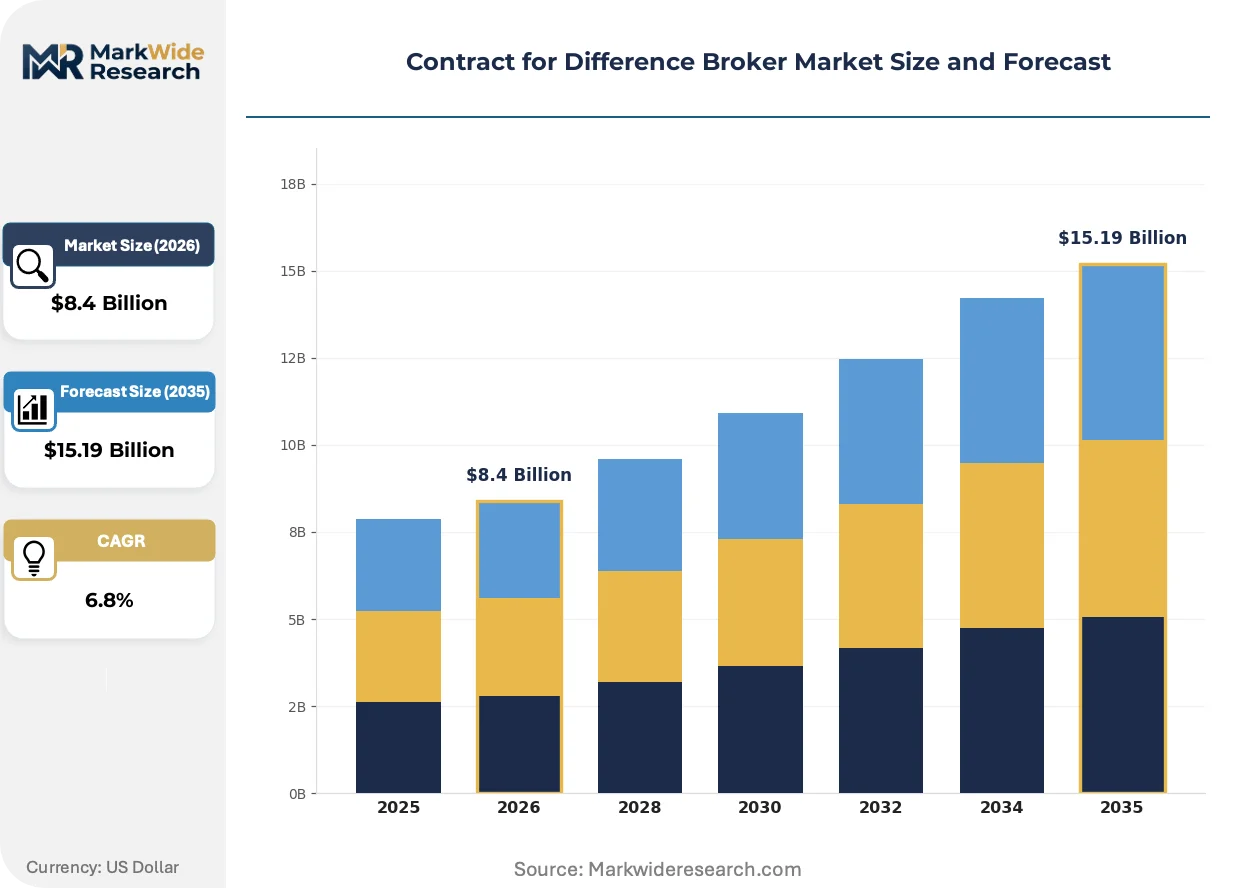
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Desktop Trading, Mobile Trading, Web-Based Interface, API Trading Customer Type: Retail Traders, High-Net-Worth Individuals, Institutional Investors, Day Traders Asset Class: Equities, Forex, Commodities, Indices, Cryptocurrencies Revenue Model: Commission-Based, Spread-Based, Subscription, Performance Fee |
| Companies Covered | XM, FP Markets, IG, eToro, Pepperstone, Interactive Brokers, IC Markets, Oanda, Saxo Bank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract for Difference Broker Market Trends and Innovations
Execution infrastructure and client interface layers are undergoing simultaneous transformation as latency-sensitive automation converges with social engagement mechanics.
Cloud-native matching engines with sub-millisecond co-location are displacing legacy on-premise server stacks. Proprietary trading firms and high-frequency API clients now demand microsecond-level determinism. This infrastructure shift compresses operational expenditure for scale players while raising barriers for broker-dealers dependent on third-party software.
The EU's Digital Operational Resilience Act imposes mandatory ICT risk management frameworks across financial entities. Incident reporting thresholds and third-party vendor oversight requirements reshape broker technology procurement. MiFID II-aligned firms in Germany and France are front-loading compliance investments ahead of enforcement deadlines.
Social trading functionality is capturing execution flow from traditional signal services. Copy-trading interfaces allow novice retail clients to replicate positions from verified strategy providers. This behavioral shift concentrates most visibly among Australian and UK demographics under 35, where platform selection prioritizes community validation over raw spread competitiveness.
Contract for Difference Broker Market Segmentation
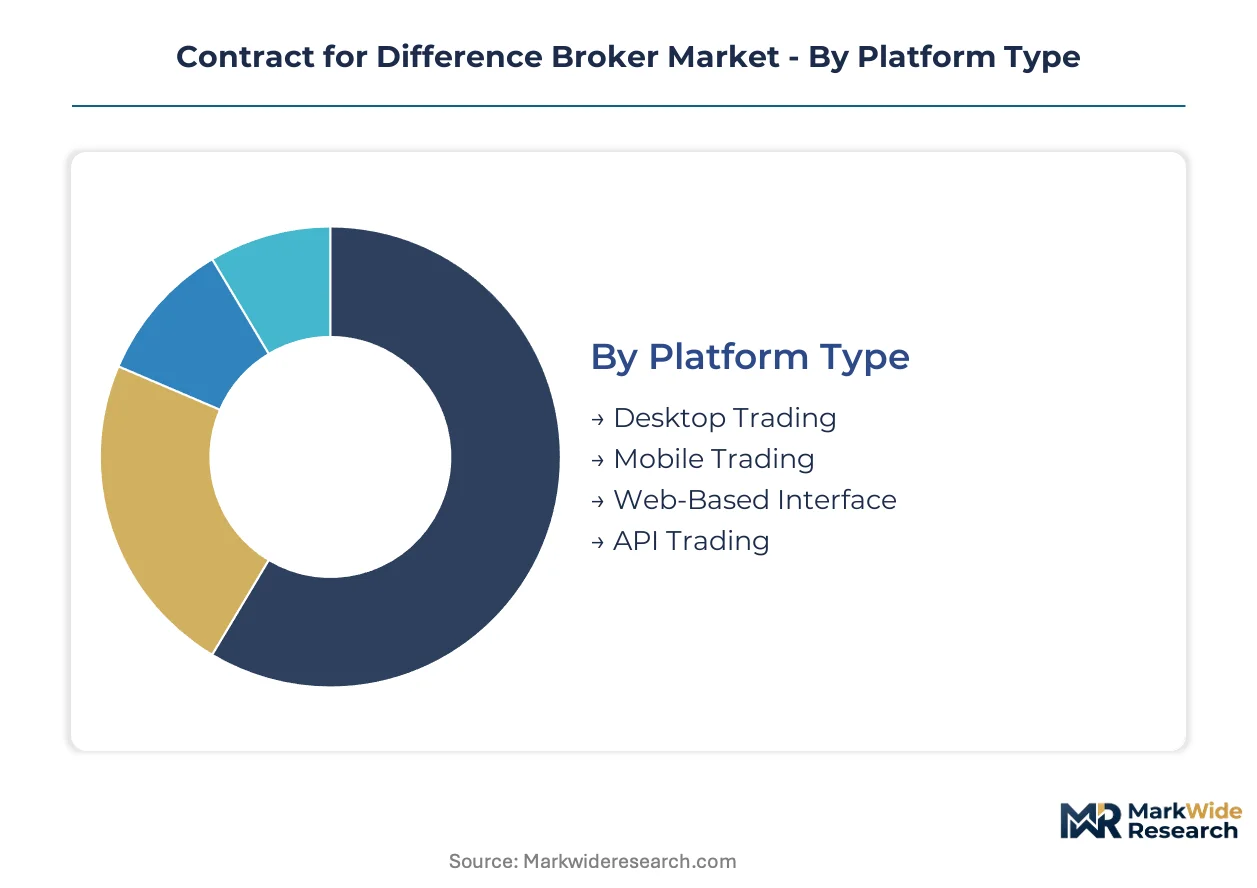
CFD broker architecture fragments across four interdependent dimensions that determine capital efficiency, regulatory exposure, and client lifetime value. Platform infrastructure and revenue model choices lock in operational cost structures, while customer type and asset class selections define compliance jurisdiction and leverage availability.
Platform Type:
Channel mix varies sharply by client sophistication, with retail flow concentrating in smartphone-native interfaces while institutional demand routes through direct API connectivity.
- Desktop Trading:Feature-rich terminals with advanced charting and multi-monitor support serve active traders requiring complex order types. Demand concentrates among German and UK day traders executing high-frequency strategies where screen real estate reduces execution latency perception.
- Mobile Trading:Native iOS and Android applications with biometric authentication and push-alert functionality dominate Australian retail onboarding. Younger demographics in Southeast Asia prioritize platform selection based on app store ratings and social trading integration over spread competitiveness.
- Web-Based Interface:Browser-agnostic HTML5 platforms eliminate download friction for casual traders. These interfaces capture sporadic users across Cyprus-licensed brokers serving EU passport clients.
- API Trading:FIX and REST protocols enable algorithmic execution and white-label integration. Quantitative funds and commodity hedgers in London and Singapore demand microsecond-level determinism.
By volume, Mobile Trading leads. By growth pace, API Trading is expanding most quickly.
Customer Type:
Margin contribution per client scales inversely with sophistication, as retail traders generate spread capture while institutions negotiate commission compression.
- Retail Traders:Individual accounts with deposits below professional client thresholds drive platform economics through spread markups. UK and Australian regulators impose leverage caps and negative balance protections that standardize risk management.
- High-Net-Worth Individuals:Sophisticated investors with portfolio values exceeding retail thresholds access enhanced margin terms and dedicated relationship management. Singapore's Payment Services Act licensing attracts this segment through regulatory clarity.
- Institutional Investors:Asset managers and corporate treasuries require multi-asset custody integration and prime brokerage relationships. Counterparty credit lines concentrate among London-based tier-one liquidity providers.
- Day Traders:High-velocity participants executing multiple intraday positions demand sub-50 millisecond execution and direct market access. German and UK markets exhibit dense concentrations of this cohort.
Retail Traders dominate account volume. High-Net-Worth Individuals deliver steepest expansion trajectory.
Asset Class:
Product architecture determines regulatory jurisdiction, with cryptocurrency derivatives facing divergent treatment across ASIC, FCA, and CySEC frameworks.
- Forex:Currency pair CFDs with 30:1 leverage caps under UK and EU rules generate the majority of retail trading volume. Major pairs concentrate liquidity in London and New York trading sessions.
- Cryptocurrencies:Synthetic exposure to Bitcoin and Ethereum without wallet custody appeals to risk-managed segments. Singapore and Australia provide clearer licensing pathways than EU jurisdictions with 2:1 leverage restrictions.
- Equities:Single-stock and basket CFDs attract commission-sensitive traders seeking transparent execution costs. German DAX constituents and US tech names concentrate demand.
- Commodities:Precious metals and energy derivatives serve inflation-hedge demand. Gold CFDs maintain consistent volume across volatility regimes.
- Indices:Synthetic exposure to benchmarks like FTSE 100 and S&P 500 reduces single-stock research burden. Passive directional strategies favor this category.
Forex leads by transaction volume. Cryptocurrencies gain share fastest.
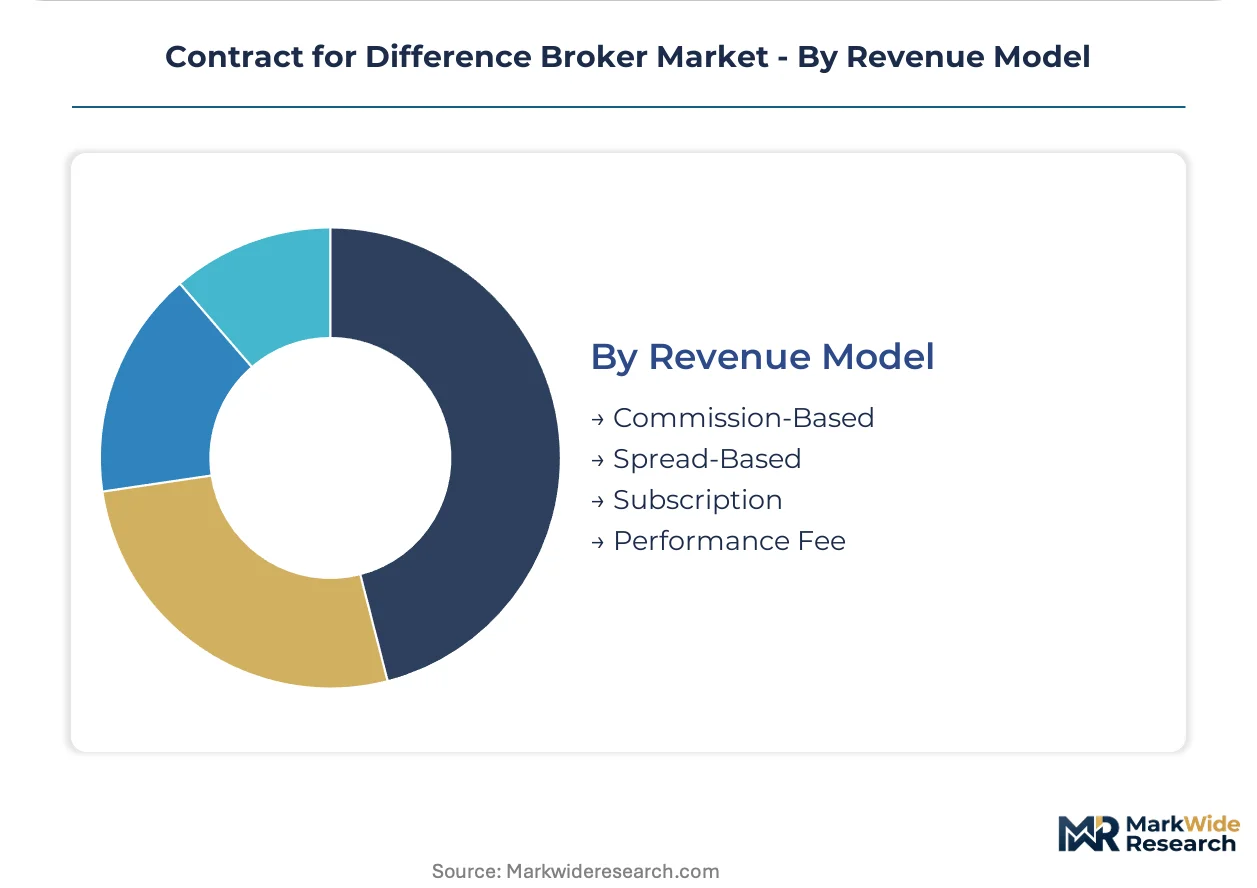
Revenue Model:
Economic capture mechanisms align with client sophistication, with spread-based models dominating retail and commission structures penetrating institutional segments.
- Spread-Based:Bid-ask markups embedded in quoted prices capture profitability from retail flow with minimal transparency friction. This model dominates UK and Australian retail platforms.
- Commission-Based:Explicit per-trade fees plus raw spreads attract sophisticated traders valuing execution cost clarity. Equities CFD offerings concentrate this structure.
- Subscription:Fixed monthly fees for premium platform features and reduced spreads target high-activity retail segments. Australian brokers pilot this model for advanced charting packages.
- Performance Fee:Revenue share from profitable copy-trading strategies aligns broker interests with strategy providers. Social trading platforms in the UK deploy this mechanism.
Spread-Based models dominate revenue volume. Subscription structures climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London-New York fiber corridor underwrites transatlantic liquidity flows that sustain the United Kingdom's position as the primary CFD trading hub. Frankfurt's DE-CIX internet exchange anchors continental European execution infrastructure. Singapore's subsea cable landing points connect Asia-Pacific retail demand to global price discovery mechanisms.
United Kingdom
Retail trader density in Greater London generates concentrated order flow for forex and equity index derivatives. The Financial Conduct Authority's 30:1 leverage cap and negative balance protection mandate reshape broker product architecture. The Square Mile hosts prime brokerage relationships with tier-one liquidity providers including LMAX Exchange and CMC Markets.
Australia
ASIC's 2021 retail trading reforms standardized client safeguards while legitimizing leveraged derivatives for domestic investors. Sydney's fintech corridor concentrates mobile-first platform development targeting Southeast Asian expansion. Melbourne-based brokers leverage domestic payment rails to capture Vietnamese and Thai retail cohorts.
Germany
BaFin enforcement of MiFID II transparency requirements elevates compliance costs for Cyprus-licensed brokers serving German-speaking clients. Frankfurt's trading infrastructure supports high-velocity day trader communities executing DAX and EURO STOXX strategies. Bavarian technology clusters develop risk management software for 30:1 leverage products.
Singapore
The Monetary Authority of Singapore's Payment Services Act licensing framework attracts broker regional headquarters seeking regulatory clarity for cryptocurrency derivatives. Marina Bay financial district concentrates prime brokerage and custody services for institutional hedgers. Local payment integration enables seamless SGD funding for retail traders across ASEAN markets.
United States
Commodity Futures Trading Commission restrictions on retail forex leverage limit domestic CFD market development. Chicago's derivatives infrastructure supports institutional synthetic exposure through futures and options rather than OTC contracts. New York-based prime brokers extend credit lines to UK and Australian regulated entities serving international clients.
Contract for Difference Broker Market Competitive Landscape
Concentration sits with vertically integrated multi-asset platforms that combine proprietary execution technology with prime brokerage relationships. The vendor base stratifies across three tiers: retail-focused spread-capture specialists, institutional API connectivity providers, and social trading network operators. Two dominant competitive moves define current positioning: geographic licensing expansion into Southeast Asian jurisdictions and technology acquisitions targeting sub-millisecond execution infrastructure.
Within the retail-focused tier, IG and eToro occupy positions exemplifying divergent client acquisition strategies—IG through established platform technology and eToro through social network effects. Saxo Bank anchors the institutional connectivity segment with multi-asset custody integration. These three entities represent distinct archetypes: legacy retail infrastructure, community-driven onboarding, and high-net-worth service architecture.
| Leading Market Players |
|---|
| XM |
| FP Markets |
| IG |
| eToro |
| Pepperstone |
| Interactive Brokers |
| IC Markets |
| Oanda |
| Saxo Bank |
| Others |
Pricing and Supply Chain Analysis
MiFID II passporting provisions and CySEC licensing requirements gate both prime brokerage qualification and spread-based revenue differentiation simultaneously. Brokers serving European Economic Area clients must maintain parallel compliance architectures that inflate operational overhead while compressing margin capture from retail forex flows.
Pricing Analysis
Volume-discount tiering structures separate high-frequency API clients from retail spread-capture segments across UK and Australian platforms. Spread-based models dominate retail onboarding with embedded bid-ask markups, while commission-based structures penetrate institutional equities CFD offerings where execution transparency commands premium positioning. Pricing pressure stems from digital marketing saturation pushing cost-per-qualified-lead upward across established jurisdictions. Retail traders exhibit highest price sensitivity to spread differentials, whereas algorithmic funds prioritize latency determinism over explicit cost structures.
Supply Chain Analysis
Inbound logistics costs through the London-New York fiber corridor and Singapore's subsea cable landing points anchor prime brokerage connectivity pricing for tier-one liquidity providers. Liquidity concentration rests on London, New York, and Singapore as execution infrastructure hubs. Raw material dependencies span co-location server capacity, FIX protocol software licenses, and real-time market data feeds. Single-source vulnerability concentrates among tier-one prime brokers during volatility spikes. Distribution runs through proprietary platform technology, white-label API integrations, and mobile-native execution interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile-first execution infrastructure and cryptocurrency derivatives licensing are disrupting traditional spread-capture economics. Regulatory arbitrage constraints between UK FCA leverage caps and lighter-touch Asian jurisdictions create geographic repositioning incentives.
For Market Incumbents: Consolidate prime brokerage relationships through exclusive credit line arrangements with LMAX Exchange and CMC Markets to defend against counterparty compression during volatility events. Deepen in-house production of sub-millisecond matching engines rather than licensing third-party software stacks vulnerable to EU Digital Operational Resilience Act vendor oversight mandates.
For New Entrants and Emerging Players: Lead with social trading network effects and copy-trading functionality to capture Australian and UK demographics under 35 where community validation outweighs raw spread competitiveness. Target Thailand and Vietnam through local language platforms and domestic payment rails where CFD awareness remains nascent but equity market participation is climbing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across API trading infrastructure as cloud-native matching engines displace legacy on-premise server stacks. Acquisition candidates should demonstrate established CySEC licensing with MiFID II passporting pathways, proven negative balance protection systems, and quantifiable mobile app store ratings above 4.5 stars. Watch for Singapore Payment Services Act licensing approvals as signal of cryptocurrency derivatives regulatory clarity.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Licensing Expansion | CySEC and Singapore MAS approvals unlock European Economic Area and ASEAN retail access respectively. |
| Sub-Millisecond Infrastructure Acquisition | Cloud-native matching engines with co-location at DE-CIX reduce execution latency below 50 milliseconds for German day traders. |
| Social Trading Platform Integration | Copy-trading interfaces capture UK and Australian demographics under 35 through community validation mechanics. |
| Cryptocurrency Derivatives Licensing | Synthetic crypto exposure without wallet custody appeals to risk-managed segments under ASIC and Singapore frameworks. |
| API Institutional Connectivity Development | FIX and REST protocol deployment attracts algorithmic funds and commodity hedgers in London and Singapore. |
Research Methodology
Desk research of regulatory filings from the UK's Financial Conduct Authority, Australia's ASIC, and Cyprus CySEC preceded structured interviews with CFD platform CTOs, prime brokerage relationship managers, retail trader acquisition heads, and quantitative risk modeling directors. Secondary validation drew from MiFID II transparency databases, ASIC market integrity reports, and broker annual disclosures. Bottom-up transaction volume estimates across platform types triangulated with top-down addressable market calculations.
Variance decomposition across platform infrastructure investments, regulatory compliance costs, and client acquisition expenditures informed the analytical framework over the projection horizon. Segmentation dimensions modeled include platform type, customer sophistication tier, asset class exposure, and revenue capture mechanism. CAGRs were derived from historical flow velocity patterns and jurisdictional regulatory posture trajectories. Forecast inputs incorporated mobile penetration rates in Southeast Asian markets and cloud infrastructure cost curves.
Forecasts assume regulatory continuity in UK FCA leverage restrictions, EU ESMA negative balance protections, and Singapore Payment Services Act licensing frameworks; material policy shifts would require re-modeling. Specific risk factors include divergent margin rule adoption across ASEAN jurisdictions and Meta advertising policy changes restricting leveraged product promotion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Digital Account Opening Market
Financial Services
Online Lottery Market
Financial Services
Europe E-Brokerages Market
Financial Services
Multivendor ATM Software Market
Financial Services
Financial Advisory Services Market
Financial Services
ATM Managed Services Market
Financial Services
South Korea Factoring Services Market
Financial Services
India Legal Services Market
Financial Services
China Supply Chain Financing Market
Financial Services
Factoring Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Benefits Consulting Service Market
Financial Services
Global Management Consulting Services Market
Financial Services
Australia Online Gambling Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Africa Lottery Market