
 Europe BFSI Biometrics Market | 2026-2036
Europe BFSI Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe BFSI Biometrics Market Insights
ISO 30107-3 Presentation Attack Detection (PAD) certification is collapsing the gap between enterprise-grade and consumer-grade facial recognition systems in European banking. IDEMIA leverages its deep integration with national ID card programs across France and the Netherlands to sustain channel control in high-assurance identity verification. Thales Group anchors its position through cryptographic hardware security modules that bind biometric templates to EU-qualified trust service standards.
BFSI biometrics encompasses multimodal physiological and behavioral measurement systems—fingerprint minutiae extraction, iris code generation, voiceprint frequency analysis, and liveness detection algorithms—deployed to authenticate individuals and authorize transactions within banking, financial services, and insurance workflows. These systems operate on FAR/FRR performance thresholds typically below 0.1% for regulated financial applications, with PAD resistance mandatory under EBA guidelines for strong customer authentication. Fingerprint recognition dominates transaction volumes at physical POS and ATM endpoints, while facial recognition captures the fastest growth trajectory as remote onboarding platforms displace branch-based identity proofing across Nordic and Benelux markets. Cloud-based deployment models are concentrating margin pools among hyperscale-aligned vendors, though hybrid architectures retain preference among German Landesbanken and Swiss private banks with data residency constraints.
GDPR Article 9 restrictions on processing special category biometric data, supplemented by the EU AI Act's prohibition of real-time remote biometric identification in publicly accessible spaces for law enforcement, are forcing BFSI deployers toward explicit consent architectures and on-device template storage. EBA guidelines on strong customer authentication under PSD2, alongside national implementations by BaFin in Germany and ACPR in France, mandate step-up authentication flows that favor multimodal systems combining inherence with possession factors. Stakeholders must monitor the European Commission's ongoing delegated act refinements for biometric AI systems, as reclassification of banking authentication tools into higher-risk categories would trigger conformity assessment obligations that reshape vendor competitive dynamics and procurement timelines.
Market Dynamics
The EU AI Act's risk-based classification system is forcing BFSI deployers to rearchitect biometric systems around explicit consent and on-device template storage, collapsing legacy centralized processing models.
Growth Catalysts
- PSD2 Strong Customer Authentication:EBA guidelines mandate step-up authentication flows that favor multimodal systems combining inherence with possession factors across European retail banking.
- Remote Onboarding Platforms:Nordic and Benelux financial institutions are displacing branch-based identity proofing with facial recognition systems for digital account origination.
- Voice Recognition:Frankfurt's financial hub density accelerates enterprise-scale deployment of voiceprint authentication for telephone banking and trading floor access.
Market Restraints
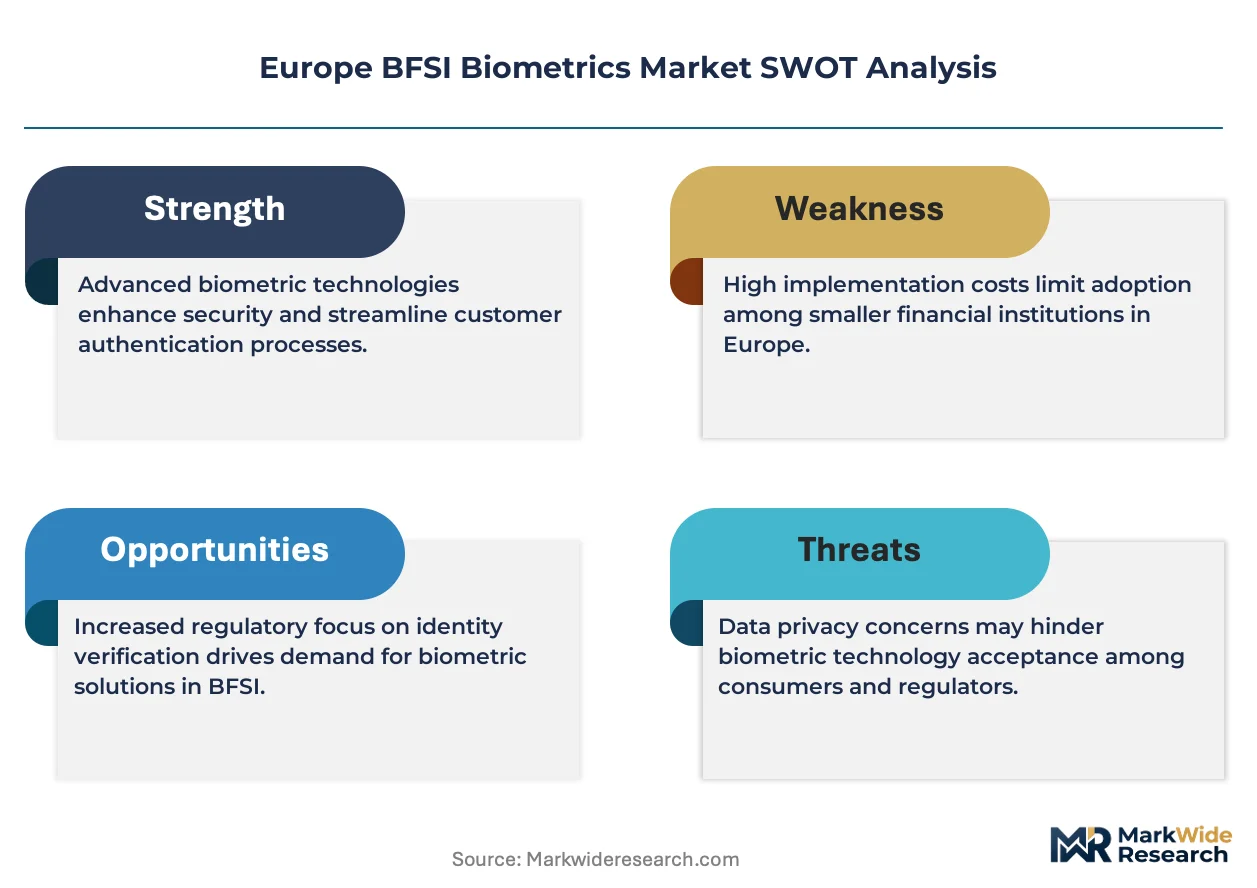
- GDPR Article 9 Restrictions:Special category biometric data processing requires explicit consent architectures that increase implementation complexity and user friction.
- ISO 30107-3 Certification Costs:Presentation Attack Detection compliance creates capital barriers for mid-tier vendors seeking banking-grade facial recognition contracts.
- Hardware Security Module Dependency:Cryptographic binding of biometric templates to EU-qualified trust standards concentrates supply leverage among established HSM manufacturers.
Strategic Opportunities
- Swiss Private Banking:Data residency constraints among Geneva and Zurich wealth managers favor hybrid cloud-on-premise biometric architectures over pure SaaS models.
- EU AI Act Delegated Acts:Pending reclassification of banking authentication tools could trigger conformity assessment obligations that reshape vendor procurement timelines.
- Behavioral Biometrics Convergence:Integration of keystroke dynamics with physiological modalities opens new authentication layers for continuous session monitoring in mobile banking.
Industry Challenges
- Template Interoperability:Fragmented proprietary formats between national ID card programs and banking systems force costly middleware development for cross-border authentication.
- Liveness Detection Arms Race:Deepfake presentation attacks outpace PAD algorithm updates, compressing certification validity windows and requiring continuous revalidation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe BFSI Biometrics Market |
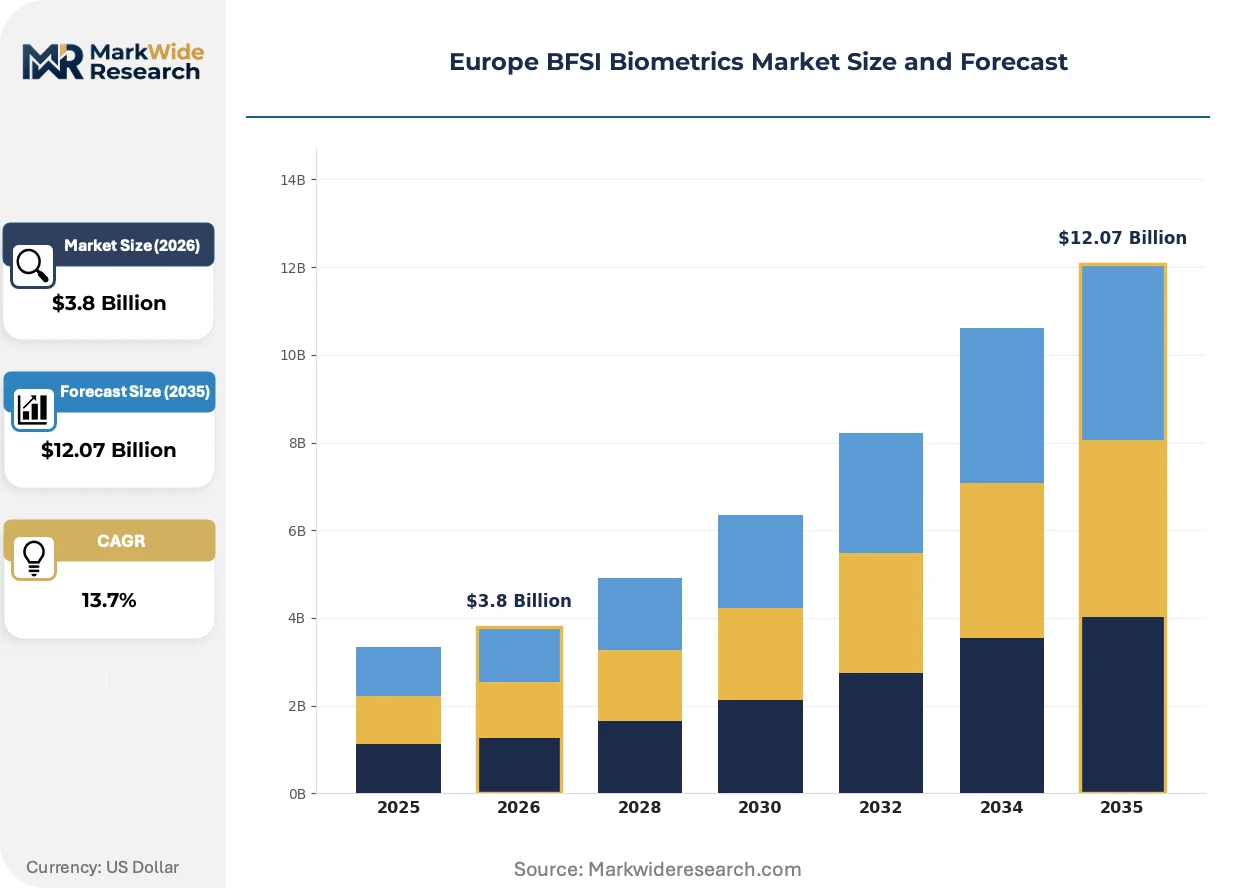
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Customer Authentication, Fraud Prevention, Identity Verification, Access Control End User: Banking Institutions, Investment Firms, Insurance Companies, Credit Unions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Veridium, Aware Inc, IDEMIA, Fulcrum Biometrics Inc, Precise Biometrics AB, Thales Group, HID Global Corporation, M2SYS Technologies, Fujitsu, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe BFSI Biometrics Market Trends and Innovations
Biometric authentication in European BFSI is pivoting from single-factor physiological capture toward continuous behavioral monitoring and multimodal fusion architectures.
Facial recognition with embedded liveness detection is bifurcating the vendor landscape between ISO 30107-3 certified enterprise platforms and consumer-grade alternatives excluded from regulated financial workflows. German Landesbanken and Dutch retail banks are consolidating procurement around PAD-validated systems, compressing margins for uncertified suppliers while expanding contract values for compliant vendors.
GDPR's data minimization principles are reshaping system architecture toward edge-based template processing. The regulation forces biometric data localization within EU jurisdiction, compelling cloud providers to establish regional sovereign infrastructure and triggering procurement preference shifts among French and Italian institutions.
Buyer concentration among Frankfurt, London, and Paris financial hubs is consolidating vendor relationships around framework agreements with hyperscale-aligned platforms. Tier-two regional banks are responding through purchasing consortiums that aggregate demand for multimodal authentication suites, redistributing negotiation leverage toward mid-market deployers in Spain and Portugal.
Europe BFSI Biometrics Market Segmentation
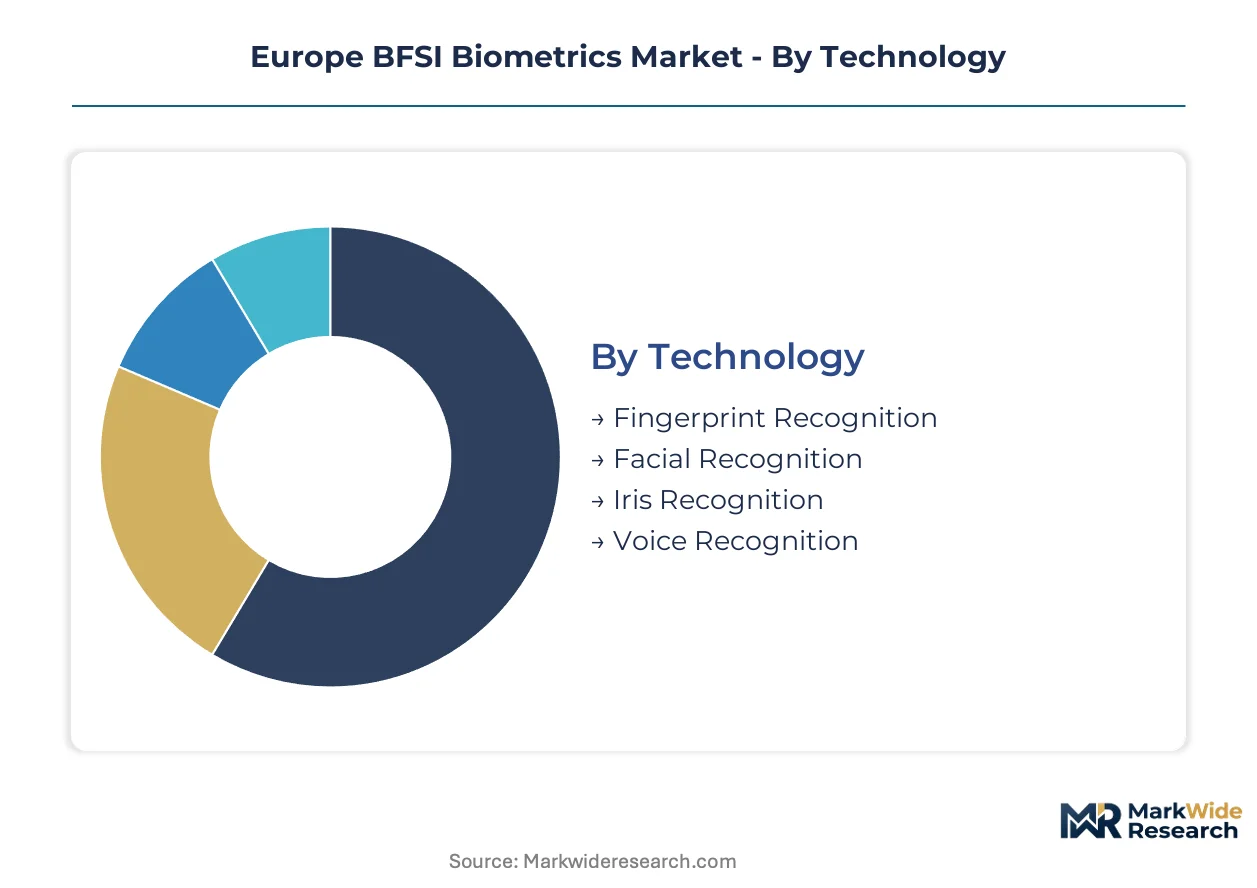
Biometric system procurement across European BFSI follows distinct technology-application matrices, with margin concentration shifting toward multimodal platforms that satisfy EBA strong customer authentication mandates. Deployment architecture choices increasingly determine vendor selection criteria as GDPR data residency requirements harden.
Technology:
Margin pools concentrate in facial recognition platforms with embedded liveness detection, where ISO 30107-3 certification creates pricing power for compliant vendors.
- Facial Recognition:Three-dimensional depth sensing and infrared spectrum analysis enable remote onboarding without specialized hardware. Nordic retail banks in Stockholm and Copenhagen are consolidating procurement around PAD-validated systems for digital account origination, displacing branch-based identity proofing.
- Fingerprint Recognition:Minutiae extraction algorithms operating at sub-0.1% FAR thresholds dominate physical transaction volumes at German ATM networks and Dutch POS terminals. Frankfurt's Sparkassen and Volksbanken maintain extensive deployed bases, though growth is decelerating as contactless modalities gain preference.
- Iris Recognition:Pattern-matching systems with cryptographic template binding serve high-assurance vault access and trading floor entry at Swiss private banks in Zurich.
- Voice Recognition:Frequency analysis engines authenticate telephone banking users across London investment houses and Parisian asset managers.
Fingerprint recognition holds installed capacity. Facial recognition is rotating up the share rankings.
Application:
Authentication workflows demanding continuous session monitoring command premium pricing over one-time verification events.
- Customer Authentication:Step-up authentication flows combining inherence with possession factors satisfy PSD2 regulatory mandates across Italian and Spanish retail banking. Multimodal fusion architectures integrating behavioral biometrics with physiological capture are expanding contract values for compliant vendors.
- Identity Verification:Document-centric proofing with biometric binding anchors remote onboarding platforms displacing physical branch presence in Benelux markets. Dutch ING and Belgian KBC are consolidating procurement around framework agreements with hyperscale-aligned platforms.
- Fraud Prevention:Real-time transaction scoring with biometric session validation protects payment rails at French mutual banks.
- Access Control:Physical entry systems with template-on-card architectures secure data centers serving Luxembourg fund administrators.
Identity verification is climbing the fastest as branch networks contract. Customer authentication retains the largest absolute spend base.
End User:
Buyer concentration among universal banks with pan-European footprints redistributes negotiation leverage toward framework agreements.
- Banking Institutions:Universal banks with retail and commercial divisions drive enterprise-scale multimodal deployments. Deutsche Bank and BNP Paribas are consolidating vendor relationships around single-source biometric platforms spanning authentication, fraud prevention, and access control.
- Investment Firms:Trading floor access control with voiceprint authentication dominates procurement at Frankfurt and London asset managers. Compliance with MiFID II recording requirements shapes biometric data retention architectures.
- Insurance Companies:Claims verification with facial recognition prevents synthetic identity fraud at Munich reinsurance groups.
- Credit Unions:Cooperative banking federations in Ireland and Portugal aggregate demand through purchasing consortiums.
Banking institutions anchor procurement volumes. Investment firms are gaining share in authentication technology spending.
Deployment:
Data residency constraints among Swiss and German institutions sustain hybrid architecture preference against pure SaaS migration.
- Hybrid:Split processing with edge-based template extraction and cloud-orchestrated decisioning satisfies GDPR localization mandates. Geneva and Zurich wealth managers favor this architecture for client biometric data subject to Swiss banking secrecy laws.
- On-Premises:Hardware security module integration with EU-qualified trust standards anchors high-assurance deployments at Bundesbank-supervised institutions. BaFin operational risk guidelines reinforce preference for cryptographic key custody within national jurisdiction.
- Cloud-Based:Hyperscale infrastructure with regional sovereign zones serves mid-tier Spanish and Italian banks without dedicated security operations.
- Mobile Solutions:On-device template storage with secure enclave processing enables smartphone-centric authentication for neobank customers.
On-premises retains share in high-assurance segments. Hybrid deployment is expanding most quickly as regulatory clarity emerges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biometric system vendors supply authentication infrastructure to French and Dutch banking networks, establishing a north-south trade corridor across continental European financial hubs.
Germany
BaFin operational risk guidelines drive demand for hardware security module integration in Frankfurt's Sparkassen and Volksbanken networks. The Federal Financial Supervisory Authority mandates cryptographic key custody within national jurisdiction for Bundesbank-supervised institutions. Bavarian and Hesse banking clusters deploy multimodal authentication platforms combining fingerprint minutiae extraction with voiceprint frequency analysis.
France
ACPR implementation of PSD2 strong customer authentication accelerates procurement of step-up authentication flows at BNP Paribas and Société Générale. GDPR Article 9 restrictions on special category biometric data processing require explicit consent architectures that increase implementation complexity. Parisian asset managers and Île-de-France retail banking headquarters consolidate vendor relationships around framework agreements with hyperscale-aligned platforms.
United Kingdom
MiFID II recording requirements shape biometric data retention architectures at London investment houses and trading floors. The Financial Conduct Authority's operational resilience framework drives demand for continuous session monitoring capabilities. City of London and Canary Wharf financial clusters deploy voiceprint authentication for telephone banking and trading floor access compliance.
Netherlands
Dutch ING and ABN AMRO displace branch-based identity proofing with facial recognition systems for digital account origination. The Dutch Data Protection Authority enforces GDPR data minimization principles that reshape system architecture toward edge-based template processing. Amsterdam and Rotterdam banking clusters consolidate procurement around PAD-validated systems with ISO 30107-3 certification.
Switzerland
Swiss banking secrecy laws sustain hybrid cloud-on-premise biometric architectures among Geneva and Zurich wealth managers. FINMA operational risk guidelines reinforce preference for data residency constraints over pure SaaS migration. Zurich private banks and Geneva fund administrators deploy iris recognition with cryptographic template binding for high-assurance vault access.
Europe BFSI Biometrics Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and national ID program integration. The vendor landscape concentrates around three tiers: hyperscale-aligned platforms capturing framework agreements, national champions leveraging sovereign infrastructure relationships, and mid-tier specialists aggregating demand through purchasing consortiums. Dominant competitive moves include M&A to acquire PAD certification capabilities and strategic partnerships with hardware security module manufacturers.
Within the national champion tier, IDEMIA and Thales Group exemplify archetypes built on deep integration with European sovereign identity programs. IDEMIA leverages its position across French and Dutch national ID card ecosystems to sustain channel control in high-assurance verification workflows. Thales Group anchors its competitive position through cryptographic hardware security modules that bind biometric templates to EU-qualified trust service standards. Aware Inc represents the specialist archetype, occupying a position among mid-tier vendors seeking banking-grade facial recognition contracts through ISO 30107-3 compliance investment.
| Leading Market Players |
|---|
| Veridium |
| Aware Inc |
| IDEMIA |
| Fulcrum Biometrics Inc |
| Precise Biometrics AB |
| Thales Group |
| HID Global Corporation |
| M2SYS Technologies |
| Fujitsu |
| Others |
Pricing and Supply Chain Analysis
Hardware security module manufacturing at scale in Germany and France compresses unit economics for compliant biometric platforms while elevating price floors for uncertified alternatives. Cloud infrastructure amortization across hyperscale regional zones further stratifies procurement tiers, concentrating margin capture among PAD-certified vendors serving Frankfurt and Paris financial clusters.
Pricing Analysis
Next-generation liveness detection algorithms command substantial premiums over legacy two-dimensional facial recognition systems, while prior-generation fingerprint minutiae extraction faces commoditization. Three-tier pricing structure across PAD-certified enterprise, compliant mid-market, and uncertified economy levels reflects ISO 30107-3 validation status and hardware security module integration depth. Cost compression in economy-tier voice recognition stems from open-source frequency analysis libraries eroding proprietary algorithm value. Mid-tier Spanish and Italian cooperative banks exhibit highest price sensitivity, while Swiss private wealth managers prioritize cryptographic assurance over unit cost.
Supply Chain Analysis
Extended lead times for specialized infrared depth sensors and cryptographic co-processors constrain deployment velocity for multimodal authentication platforms. Component sourcing concentrates on German precision optics manufacturers, Taiwanese semiconductor foundries, and Dutch MEMS sensor specialists. Single-source vulnerability in EU-qualified trust service hardware creates procurement risk for Bundesbank-supervised institutions requiring BaFin-compliant key custody. Distribution runs through systems integrators with national ID program relationships, bypassing direct vendor engagement for high-assurance deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric platform vendors increasingly monetize continuous authentication monitoring and fraud-scoring subscriptions, where recurring revenue expansion outpaces hardware license growth. Service-attach rates for behavioral biometrics integration and PAD revalidation cycles now determine lifetime customer value.
For Market Incumbents: Secure PAD certification moats through accelerated ISO 30107-3 revalidation investments as deepfake presentation attacks compress certification validity windows. Consolidate channel control by acquiring middleware specialists addressing template interoperability gaps between French and Dutch national ID ecosystems. Vertical integration into hardware security module distribution insulates against supply concentration among established cryptographic manufacturers. For New Entrants and Emerging Players: Anchor in Portuguese and Irish credit union purchasing consortiums, where aggregated demand creates viable contract scale without direct competition from hyperscale-aligned incumbents. Behavioral biometrics convergence with keystroke dynamics for mobile banking session monitoring represents the most penetrable white-space segment. Go-to-market positioning should emphasize rapid deployment timelines against legacy multimodal integration cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with ISO 30107-3 compliance assets and national ID program integration relationships over pure-play algorithm developers. Long-term viability hinges on regulatory technology adaptation capabilities as EU AI Act delegated acts reshape conformity assessment obligations. Watch European Commission reclassification signals for banking authentication tools as the primary inflection indicator for vendor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 30107-3 Certification Investment | EBA guidelines mandate PAD validation for PSD2 strong customer authentication compliance. |
| Hardware Security Module Partnership | BaFin operational risk guidelines require cryptographic key custody within German jurisdiction. |
| Behavioral Biometrics Integration | Keystroke dynamics fusion opens continuous session monitoring revenue layers for mobile banking. |
| National ID Program Alignment | Deep integration with French and Dutch card ecosystems sustains channel control in verification workflows. |
| Hybrid Cloud Architecture Development | Swiss banking secrecy laws and GDPR localization mandates favor split-processing deployments. |
Research Methodology
A standing panel of biometric platform product managers, bank IT security officers, regulatory compliance leads, and hardware security module procurement specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EBA guideline publications, BaFin operational risk circulars, EU AI Act delegated act drafts, and ISO 30107-3 certification registries. Bottom-up deployment estimates across German Sparkassen networks and top-down vendor revenue analysis were triangulated against hyperscale infrastructure capex disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology generation transitions, deployment architecture preferences, application workflow types, and end-user institution tiers throughout the forecast period. CAGRs were derived from biometric authentication transaction volume trajectories and platform licensing revenue patterns, incorporating PSD2 mandate compliance deadlines and GDPR enforcement intensity as demand-side inputs.
Decision-makers should treat outputs as directional under stable regulatory classification assumptions for biometric AI systems; material reclassification would warrant model refresh. Specific risk factors include EU AI Act delegated act timing, deepfake presentation attack evolution, and hardware security module supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market