
 Europe Financial Advisory Services Market | 2026-2036
Europe Financial Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Financial Advisory Services Market Analysis
Subscription-based financial planning is pivoting from episodic project delivery into recurring revenue architectures across European advisory practices. Deloitte leverages its multi-jurisdiction tax infrastructure to anchor complex cross-border mandates for mid-cap corporates. Rothschild & Co sustains its dominance in independent M&A counsel, navigating conflicts that constrain integrated banking competitors. UBS specializes in ultra-high-net-worth family office structures, occupying a tier where relationship tenure exceeds product turnover.
Financial advisory services encompass strategic counsel on capital allocation, investment structuring, risk quantification, and regulatory compliance delivered through certified professionals operating under fiduciary or suitability standards. Corporate finance advisory dominates current fee pools, while transaction advisory represents the fastest-expanding segment as European private equity dry capital seeks deployment targets. Retainer-based engagement models capture the most stable revenue streams, though project-based structures command premium pricing for complex restructuring and distressed asset mandates.
ESMA's MiFID II conduct rules shape product governance and disclosure obligations, while the EU Green Deal's taxonomy criteria redirect capital-raising advisory toward verifiable sustainability-linked instruments. The Digital Operational Resilience Act imposes new cyber and third-party risk frameworks on advisory firms serving systemically important clients. Stakeholders must monitor how the EU AI Act's deployment rules for algorithmic decision-support tools redefine permissible automation in client-facing investment recommendations.
Market Dynamics
The EU's Sustainable Finance Disclosure Regulation is compressing advisory product development cycles toward ESG-aligned portfolio construction, while MiFID II conduct rules reshape how firms monetize client relationships across the continent.
Growth Catalysts
- ESG Mandate Expansion:The EU Green Deal's taxonomy criteria redirect capital-raising advisory toward verifiable sustainability-linked instruments, creating new fee pools for green bond structuring.
- Cross-Border Transaction Flows:Private equity dry capital concentrated in London, Frankfurt, and Zurich financial centers sustains demand for complex mandate execution spanning multiple jurisdictions.
- Subscription Model Migration:Wealth management platforms are absorbing recurring revenue architectures that replace episodic project delivery with ongoing client engagement.
Market Restraints
- Regulatory Compliance Burden:ESMA's MiFID II disclosure obligations impose fixed cost structures that disproportionately constrain smaller advisory practices lacking multi-jurisdiction tax infrastructure.
- Talent Concentration Risk:Certified professionals with cross-border structuring expertise cluster in London, Frankfurt, and Zurich, limiting service scalability to peripheral markets.
- Technology Substitution Pressure:Algorithmic decision-support tools threaten traditional fee structures for standardized portfolio allocation services.
Strategic Opportunities
- Family Office Penetration:Ultra-high-net-worth segments in Germany and France remain underpenetrated by dedicated multi-generational wealth structuring services.
- Digital Operational Resilience Act:DORA's cyber and third-party risk frameworks create advisory demand for compliance architecture among firms serving systemically important clients.
- AI-Enabled Personalization:Convergence of natural language processing with regulatory parsing tools enables scalable bespoke advice at mid-market price points.
Industry Challenges
- Fiduciary Standard Talent Gap:Shortage of certified professionals capable of operating under evolving suitability standards across multiple EU member states.
- Legacy System Integration:Established practices face friction embedding ESG data streams into existing client reporting infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Financial Advisory Services Market |
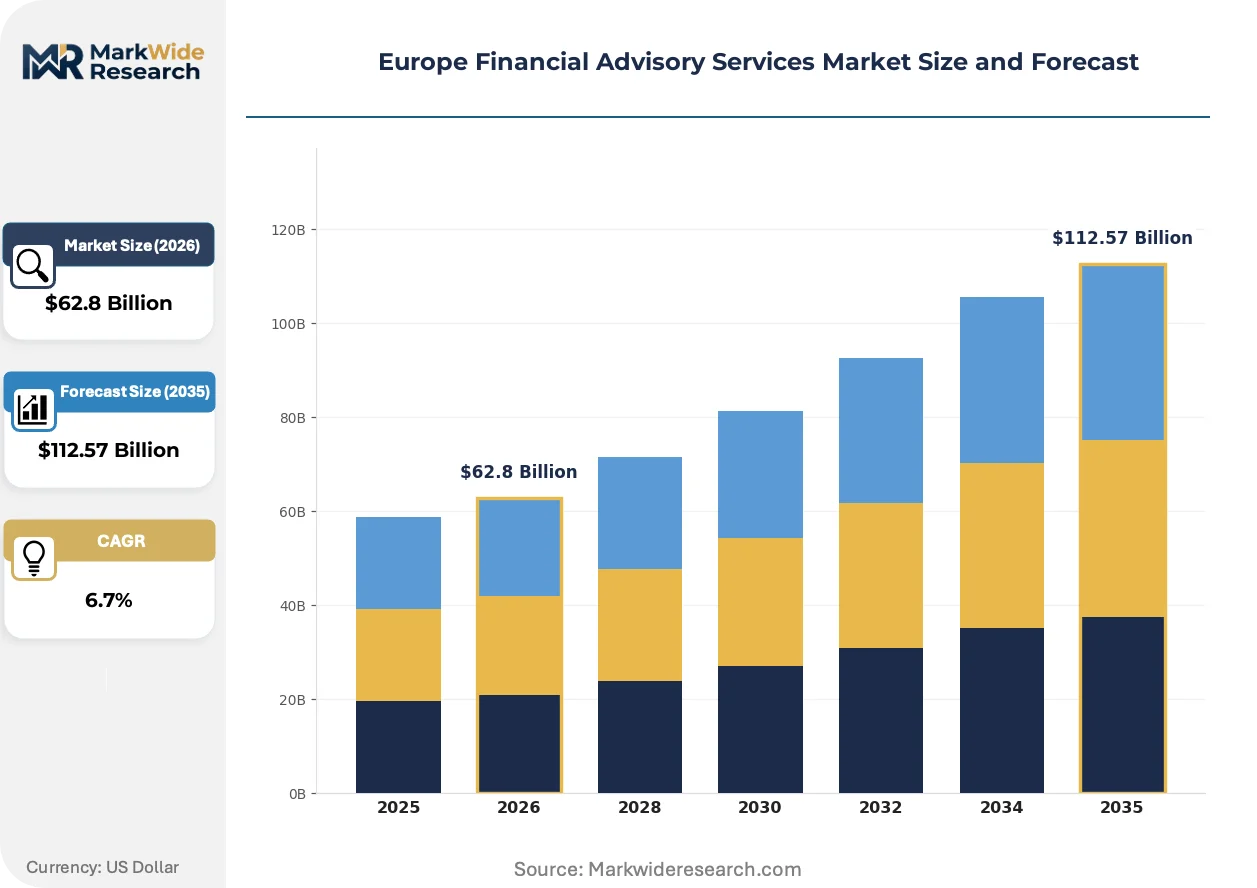
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $112.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transaction Advisory, Risk Management, Corporate Finance, Tax Advisory Client Type: Corporates, High-Net-Worth Individuals, Institutional Investors, Startups Engagement Model: Retainer-Based, Project-Based, Contingency Fee, Hourly Rate Asset Class: Equity, Debt, Real Estate, Alternatives |
| Companies Covered | Mediobanca, Deloitte, Rothschild & Co, KPMG, PwC, Morgan Stanley, UBS, EY, JP Morgan, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Financial Advisory Services Market Emerging Trajectories
Advisory delivery models are fragmenting across human-augmented and algorithmic channels, with regulatory technology investments determining which firms capture margin in standardized versus bespoke service tiers.
Natural language processing engines are absorbing document-intensive due diligence workflows previously executed by junior analysts. Mid-cap corporate advisory desks in Frankfurt and Paris are deploying these tools for cross-border transaction preparation. The technology is absorbing routine compliance verification tasks while compressing headcount ratios in traditional analyst pyramids.
The EU AI Act's deployment rules for algorithmic decision-support tools impose new governance layers on client-facing investment recommendations. Firms must maintain human oversight protocols for automated advice pathways. Independent M&A counsel and integrated banking competitors face divergent compliance cost structures depending on their existing technology infrastructure depth.
Retainer-based engagement models are displacing pure project structures among mid-market wealth segments seeking predictable advisory costs. Family offices and multi-generational households in France and Germany favor ongoing relationship architectures over episodic mandate pricing. This behavioral shift is most visible in cross-border structuring services where relationship tenure exceeds product turnover.
Europe Financial Advisory Services Market Segmentation
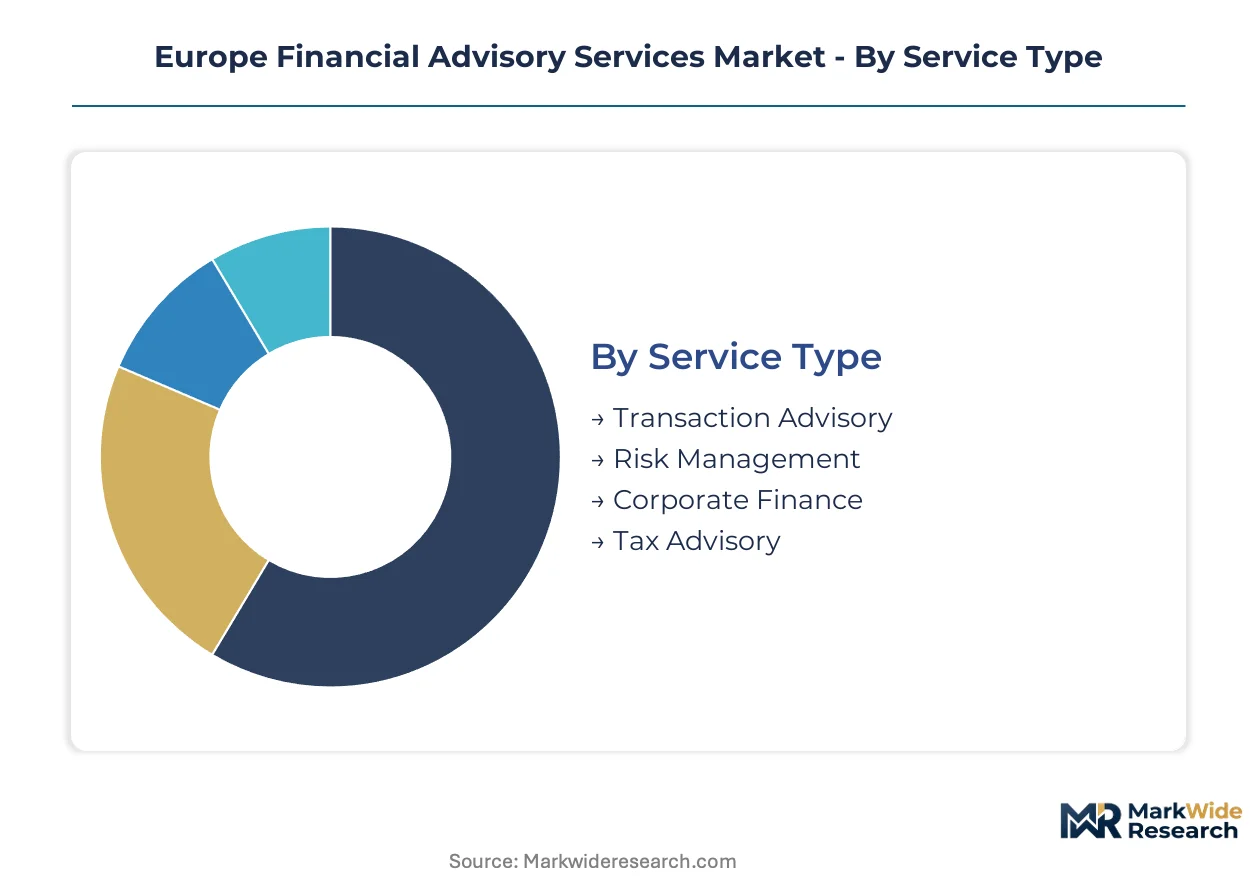
Service differentiation across Europe's advisory landscape reflects divergent regulatory burdens, client sophistication levels, and margin structures. Segmentation reveals where fee pools concentrate and which delivery models capture sustainable economics under MiFID II and DORA compliance frameworks.
Service Type:
Client risk tolerance and transaction complexity separate buyers across this dimension, with regulatory intensity varying sharply by mandate nature.
- Transaction Advisory:M&A execution, due diligence coordination, and deal structuring for cross-border mandates spanning London, Frankfurt, and Zurich. Demand concentrates among private equity funds deploying dry capital across German mid-cap industrials and French technology targets, with EU merger control timelines extending fee recognition periods.
- Corporate Finance:Capital raising, restructuring counsel, and balance sheet optimization delivered through certified professionals operating under fiduciary standards. French and German corporates drive retainer-based engagements for ongoing strategic counsel, particularly around sustainability-linked instrument issuance under EU Green Deal taxonomy criteria.
- Risk Management:Quantification frameworks for market, credit, and operational exposures.
- Tax Advisory:Cross-border structuring and compliance architecture leveraging multi-jurisdiction expertise.
Corporate Finance leads volumes today; Transaction Advisory is gaining share fastest.
Client Type:
Wealth concentration and governance sophistication determine service tier access, with family office penetration varying by country maturity.
- High-Net-Worth Individuals:Multi-generational wealth structuring, succession planning, and concentrated position management for households with relationship tenure exceeding product turnover. German and French private banking clients favor subscription-based planning over episodic project delivery, absorbing platforms that embed ESG alignment into reporting infrastructure.
- Corporates:Strategic capital allocation, M&A counsel, and regulatory compliance for mid-cap and large-cap entities. Cross-border transaction advisory linking London, Frankfurt, and Zurich financial centers sustains premium pricing for complex mandate execution.
- Institutional Investors:Portfolio construction, liability-driven investment strategies, and alternative asset due diligence.
- Startups:Early-stage fundraising preparation, cap table management, and exit pathway planning.
Corporates anchor current fee pools; High-Net-Worth Individuals show steepest expansion trajectory.
Engagement Model:
Revenue predictability and pricing power trade off across structures, with regulatory disclosure obligations reshaping contract terms.
- Retainer-Based:Ongoing advisory relationships with fixed periodic fees for continuous strategic counsel. Family offices and multi-generational households in France and Germany favor this architecture for cross-border structuring services where ESMA's MiFID II conduct rules require sustained documentation trails.
- Project-Based:Discrete mandates with defined deliverables and premium pricing for complexity. Distressed asset restructuring and contested M&A situations command elevated fees, though revenue recognition concentrates in volatile quarters.
- Contingency Fee:Success-based compensation tied to transaction closure or specified outcomes.
- Hourly Rate:Time-and-materials billing for standardized compliance and documentation tasks.
Retainer-Based structures dominate recurring revenue; Project-Based captures peak margin per engagement.
Asset Class:
Regulatory treatment and data availability differentiate advisory intensity, with sustainability-linked instruments creating new specialization requirements.
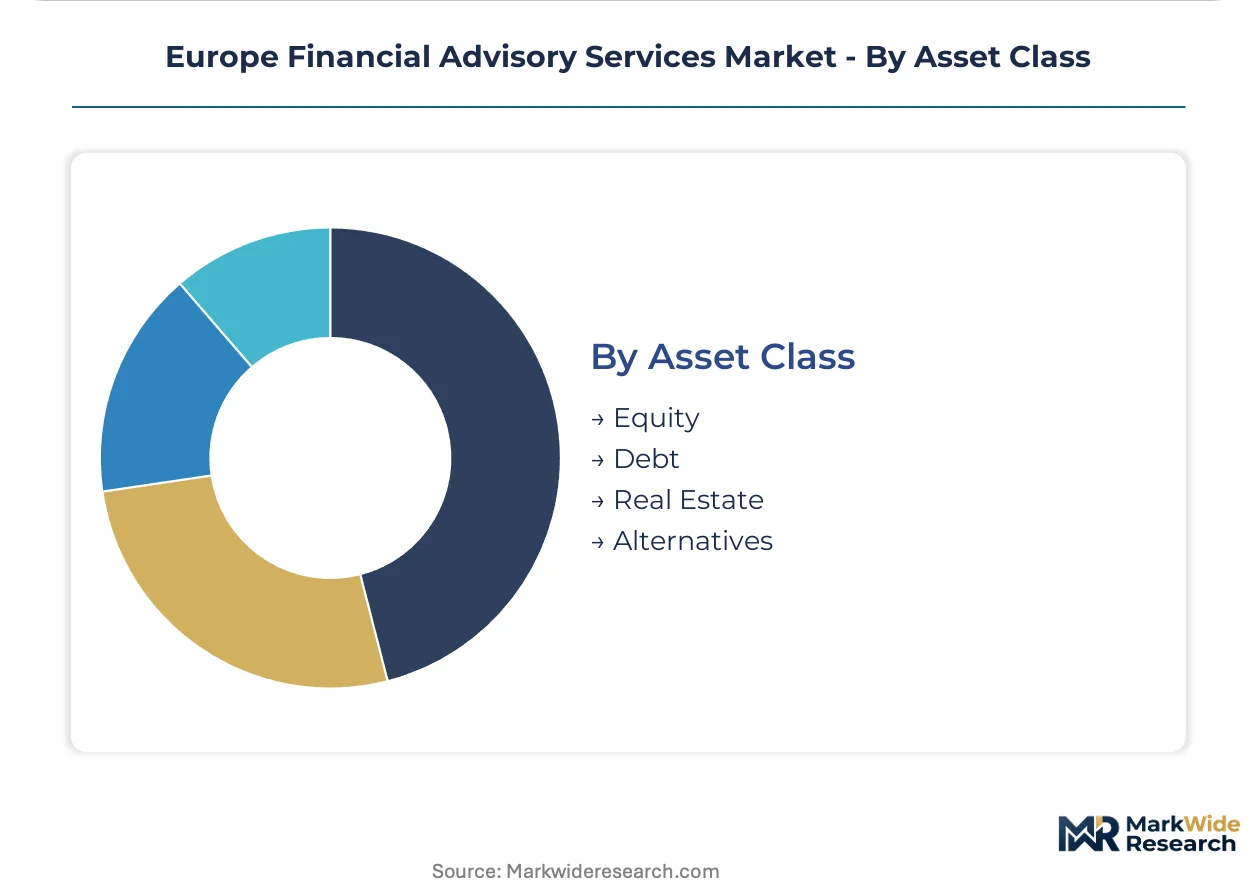
- Alternatives:Private equity, venture capital, infrastructure, and hedge fund structuring for illiquid exposure management. EU Sustainable Finance Disclosure Regulation redirects advisory product development toward ESG-aligned portfolio construction in this segment, with verifiable taxonomy compliance adding fee layers.
- Equity:Public and private equity allocation, shareholder activism defense, and index replication strategies.
- Debt:Fixed income portfolio construction, credit analysis, and interest rate risk management.
- Real Estate:Direct property investment, REIT structuring, and development finance advisory.
Equity advisory leads by mandate count; Alternatives shows fastest climb in fee per client.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United Kingdom diverge sharply in advisory service composition, with Frankfurt-driven corporate finance contrasting London's transaction advisory dominance. France occupies a middle position where family office penetration lags both markets. Switzerland and the Netherlands complete the core cluster where regulatory frameworks and wealth concentration shape distinct competitive environments.
Germany
Mid-cap industrials and private equity dry capital sustain demand for cross-border M&A execution and sustainability-linked instrument structuring. BaFin's implementation of EU Green Deal taxonomy criteria redirects capital-raising advisory toward verifiable ESG compliance documentation. The Frankfurt financial center anchors complex mandate coordination linking domestic corporates to Zurich and London counterparties.
United Kingdom
Transaction advisory volumes concentrate around private equity deployment timelines and contested M&A situations commanding premium fees. The Financial Conduct Authority's MiFID II conduct rule enforcement shapes how firms monetize client relationships through disclosure obligation frameworks. London's clustering of certified professionals with cross-border structuring expertise limits service scalability to peripheral UK markets.
France
Multi-generational households and family offices in Paris and Lyon drive retainer-based engagement models for ongoing wealth structuring counsel. Autorité des Marchés Financiers supervision of algorithmic decision-support tools imposes human oversight protocol requirements on automated advice pathways. The Île-de-France region remains underpenetrated by dedicated ultra-high-net-worth family office services relative to German benchmarks.
Switzerland
Ultra-high-net-worth individual segments favor relationship architectures where tenure exceeds product turnover in cross-border structuring mandates. FINMA's prudential frameworks for systemically important advisory firms align with DORA cyber resilience requirements for third-party risk management. Zurich's financial center specializes in multi-jurisdiction tax infrastructure serving German and French private banking clients.
Netherlands
Pension fund advisory and institutional liability-driven investment strategies sustain demand for risk quantification and alternative asset due diligence. De Nederlandsche Bank's supervision of MiFID II product governance obligations shapes disclosure requirements for ESG-aligned portfolio construction. The Amsterdam financial cluster serves as a distribution node for sustainability-linked instruments targeting Benelux institutional capital pools.
Europe Financial Advisory Services Market Vendor Landscape
Top-tier vendors anchor integrated multi-service platforms, while independent boutiques capture premium pricing in conflict-sensitive mandates. The market structures around three concentration nodes: accounting-network advisory practices, investment banking divisions, and independent M&A specialists. Strategic archetypes include fiduciary-standard wealth managers, cross-border tax infrastructure operators, and algorithmic-augmented portfolio constructors. Competitive moves center on talent acquisition in certified professional pools and technology licensing for regulatory parsing automation.
Within the independent advisory tier, Rothschild & Co and Mediobanca exemplify conflict-navigation positioning that integrated banking competitors cannot replicate. Deloitte and KPMG occupy the accounting-network archetype where multi-jurisdiction tax infrastructure anchors complex cross-border mandates for mid-cap corporates. UBS represents the ultra-high-net-worth concentration where relationship tenure metrics exceed product turnover benchmarks.
| Leading Market Players |
|---|
| Mediobanca |
| Deloitte |
| Rothschild & Co |
| KPMG |
| PwC |
| Morgan Stanley |
| UBS |
| EY |
| JP Morgan |
| Others |
Supply Flow & Price Mechanics
Certification-tier divergence between MiFID II fiduciaries and suitability-standard practitioners manifests in both fee structures and talent sourcing configurations across European advisory markets. Premium retainer rates for cross-border tax infrastructure operators in Frankfurt and Zurich reflect concentrated supply of certified professionals, while standardized portfolio services face algorithmic substitution compressing price floors.
Pricing Analysis
Capacity additions in London and Frankfurt are reshaping price floors for transaction advisory as private equity dry capital sustains demand for complex mandate execution. Project-based structures command premium pricing for distressed restructuring and contested M&A situations, while subscription models for wealth management absorb recurring revenue architectures at mid-market price points. Cost compression in standardized portfolio allocation stems from NLP-enabled document processing tools. Family offices and ultra-high-net-worth segments in Germany and France show least price sensitivity; mid-market corporates exhibit highest sensitivity to advisory fees.
Supply Chain Analysis
Certified professional supply rests on concentrated talent pools in London, Frankfurt, and Zurich financial centers, with cross-border structuring expertise clustering in these nodes. Regulatory technology inputs and ESG data infrastructure feed from specialized vendors in these same markets. Single-source vulnerability concentrates in human capital pipelines for fiduciary-standard practitioners. Distribution runs through partner-track hierarchies at accounting-network practices and independent M&A boutiques, with algorithmic channels emerging for standardized compliance tasks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's financial advisory services market compounds steadily as regulatory complexity deepens client reliance on certified professional counsel. ESG mandate expansion and cross-border transaction flows provide durable fee pool growth.
For Market Incumbents: To counter algorithmic substitution in standardized portfolio services, anchor differentiation in multi-jurisdiction tax infrastructure and embed ESG compliance architecture into retainer-based relationships. Deepen vertical integration into regulatory technology tooling for MiFID II and DORA parsing automation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in family office services for French and German multi-generational households opens white-space penetration opportunities. Target underpenetrated ultra-high-net-worth segments in Île-de-France and Lyon with dedicated multi-generational wealth structuring. Lead with AI-enabled personalization at mid-market price points to bypass established talent concentration barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance burdens disproportionately constrain smaller advisory practices lacking multi-jurisdiction infrastructure. Long-term viability favors acquiring boutiques with specialized cross-border structuring expertise and established ESMA conduct rule documentation systems. Watch MiFID II enforcement intensity and EU AI Act deployment rule finalization as inflection indicators for automation-driven margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Licensing | MiFID II and DORA parsing automation reduces compliance headcount ratios for mid-cap advisory desks. |
| Family Office Platform Launch | Dedicated multi-generational wealth structures capture underpenetrated ultra-high-net-worth segments in France and Germany. |
| ESG Data Infrastructure Partnership | EU Green Deal taxonomy compliance layers add fee pools to sustainability-linked instrument advisory. |
| Cross-Border Tax Infrastructure Expansion | Multi-jurisdiction expertise anchors complex mandates linking London, Frankfurt, and Zurich financial centers. |
| AI-Enabled Personalization Investment | NLP and regulatory parsing convergence enables scalable bespoke advice at mid-market price points. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wealth management platform executives, regulatory affairs directors at advisory firms, family office principals, and MiFID II compliance officers with secondary validation. Bottom-up and top-down triangulation drew from ESMA conduct rule filings, EU Green Deal taxonomy implementation reports, BaFin and FCA enforcement disclosures, and private equity deployment databases.
Segment-weighting approaches modeled service type, client type, engagement model, and asset class dimensions across the projection horizon. CAGRs derived from historical fee pool trajectories and regulatory mandate expansion curves, with cross-border transaction flow velocity and ESG-aligned portfolio construction adoption serving as industry-specific forecast inputs.
Caveats apply where MiFID II enforcement intensity, EU AI Act deployment rule finalization, or private equity dry capital deployment timing could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Contract for Difference Broker Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Financial Services Software Market
Financial Services
North America B2B Legal Services Market
Financial Services
Intellectual Property Valuation Market
Financial Services
ATM Managed Services Market
Financial Services
China Trade Finance Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Solar Powered ATM Market
Financial Services
Hyperinflation System Market
Financial Services
Global Product Cost Management Market
Financial Services
Direct Selling Market
Financial Services
Financial Services Application Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Mobile Notary Public Market
Financial Services
Europe E-Invoicing Market