
 Europe Insurance Brokerage Market | 2026-2036
Europe Insurance Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insurance Brokerage Market Foresight
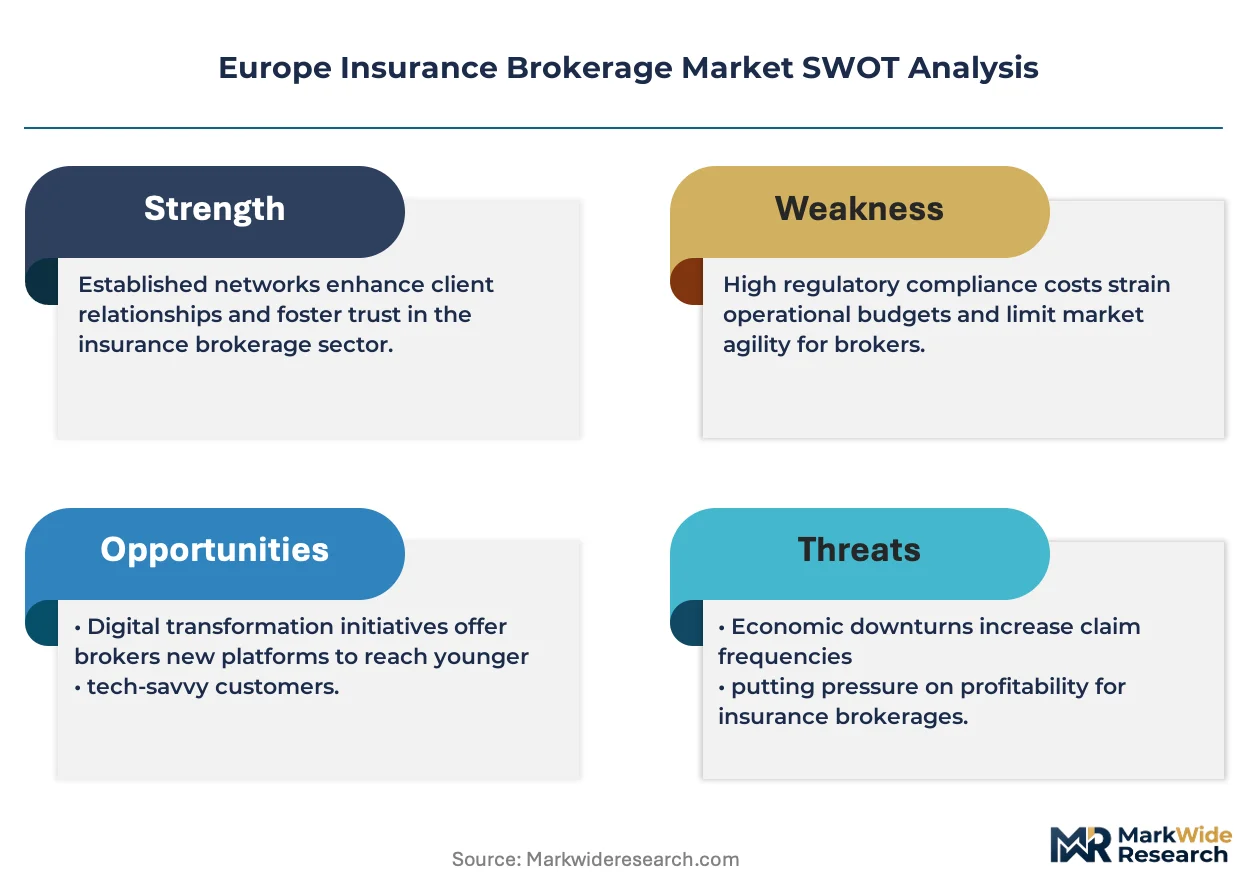
Digital infrastructure is shifting the cost base of policy distribution across European broker networks. Marsh McLennan Companies leverages proprietary risk analytics platforms to sustain pricing power in commercial lines. Aon plc anchors its continental footprint through specialized reinsurance advisory capacity in London and Zurich. Howden Group competes on mid-market commercial accounts with localized broker teams across Scandinavia and Southern Europe.
Europe insurance brokerage denotes intermediaries licensed under national financial conduct regimes to arrange, advise on, and administer insurance contracts between policyholders and underwriters, typically earning commission income of ten to twenty-five percent of premium value depending on line complexity. The primary commercial purpose centers on risk transfer optimization for buyers and market access aggregation for insurers across fragmented national regulatory landscapes. Commercial insurance commands the largest revenue pool among service types, reflecting sustained corporate demand for property, casualty, and directors-and-officers coverage across EU member states. Retail insurance through online platforms represents the fastest-expanding distribution channel, though broker-mediated placement still dominates premium value in specialty and reinsurance segments where contractual negotiation demands technical expertise.
EIOPA coordinates national conduct standards for insurance intermediaries under the Insurance Distribution Directive, while GDPR imposes data governance obligations on client information handling across cross-border broker operations. The EU Green Deal and CSRD disclosure requirements are reshaping demand for environmental liability and transition risk coverage, directly expanding broker advisory mandates. Stakeholders must monitor whether the EU AI Act's risk classification framework extends to algorithmic underwriting tools deployed by broker-affiliated managing general agents.
Market Dynamics
EIOPA's Insurance Distribution Directive and the EU's Digital Operational Resilience Act are compressing compliance timelines for intermediaries while simultaneously elevating the technical threshold for market entry across European broker networks.
Growth Catalysts
- CSRD disclosure mandates:The Corporate Sustainability Reporting Directive obliges mid-cap enterprises to quantify transition risk exposure, expanding advisory mandates for environmental liability placement across France and Germany.
- SME risk complexity:German and French small and medium enterprises are deepening broker engagement as cyber, supply chain, and ESG liabilities outstrip in-house risk management capacity.
- Cloud-native policy administration:API-first core systems are enabling real-time premium adjustments and embedded coverage integration within digital banking and payroll platforms.
Market Restraints
- Commission compression:Standardized personal lines placement through price comparison websites is squeezing traditional percentage-based remuneration toward single-digit levels.
- Talent scarcity:Actuarial and cyber risk advisory expertise concentrates in London and Zurich, creating recruitment bottlenecks for continental mid-market specialists.
- Regulatory fragmentation:National conduct regimes under EIOPA coordination still require separate licensing, capital, and complaint-handling procedures in each member state.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania exhibit broker density ratios below Western European benchmarks, presenting first-mover advantages for digital-first distribution models.
- Climate risk analytics:Flood and wildfire parametric products are converging with satellite imagery and IoT sensor networks to create subscription-based advisory services.
- MGA technology stack:Algorithmic underwriting tools deployed by broker-affiliated managing general agents are capturing specialty lines previously reserved for Lloyd's syndicates.
Industry Challenges
- Legacy system integration:Decades-old policy administration databases at incumbent carriers resist real-time data exchange with modern broker management systems.
- GDPR compliance architecture:Cross-border client data handling requires jurisdictional consent frameworks that delay multi-country account onboarding by weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insurance Brokerage Market |
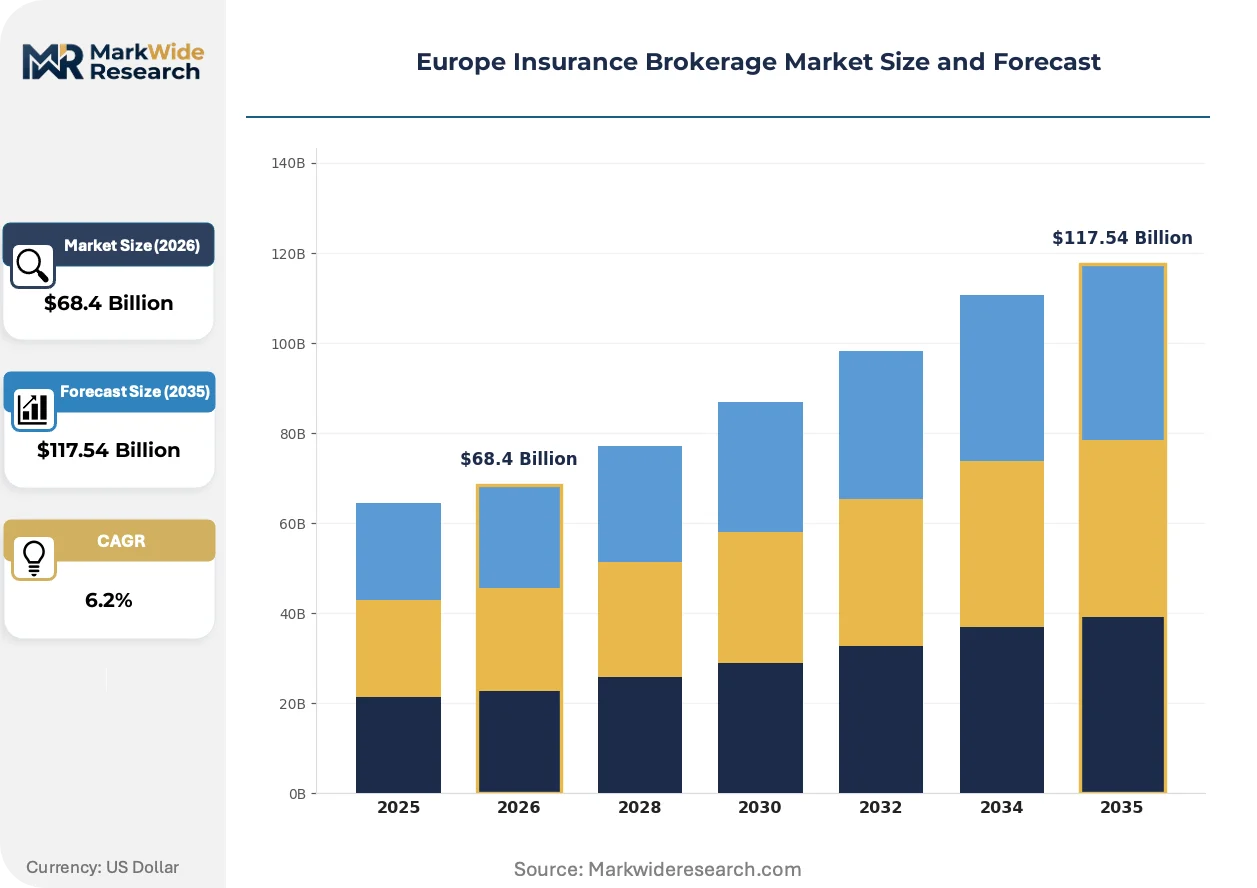
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail Insurance, Commercial Insurance, Reinsurance, Specialty Insurance Distribution Channel: Direct Channel, Broker Channel, Online Platform, Telemarketing Policy Type: Life Insurance, Health Insurance, Property Insurance, Casualty Insurance Customer Type: Individuals, Small Enterprises, Corporates, Institutions |
| Companies Covered | Arthur J. Gallagher & Co., Brown & Brown, Marsh McLennan Companies, Quintes Holding, Hyperion Insurance Group, Aon plc, Howden Group, GGW Group, Willis Towers Watson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insurance Brokerage Market Shifts & Advancements
Algorithmic placement tools and sustainability-linked coverage structures are redrawing the boundary between transactional broking and strategic risk advisory across European commercial lines.
Application programming interfaces connecting broker management systems to carrier underwriting engines are modularizing the policy lifecycle into discrete, automatable components. Mid-market commercial buyers in the Netherlands and Belgium are adopting these interfaces to compress quote-to-bind cycles from days to hours. The structural consequence is unbundling: placement, claims advocacy, and risk consulting are separating into distinct fee arrangements rather than bundled commission.
The EU AI Act's risk classification framework is imposing algorithmic accountability obligations on automated underwriting tools deployed by intermediaries. Broker-affiliated managing general agents must now document training data provenance and model drift monitoring for high-risk applications. Specialty and reinsurance segments in London and Zurich are responding by establishing dedicated model governance functions that pre-empt regulatory examination.
Corporate risk managers are consolidating broker relationships from multi-panel arrangements toward single-advisor structures with integrated analytics capabilities. The mid-market segment across Scandinavia is displacing traditional tender-based selection with continuous performance scorecards tied to claims outcomes. This concentration is most visible in Denmark and Sweden, where manufacturing and logistics verticals prioritize loss prevention advisory over pure placement efficiency.
Europe Insurance Brokerage Market Segmentation
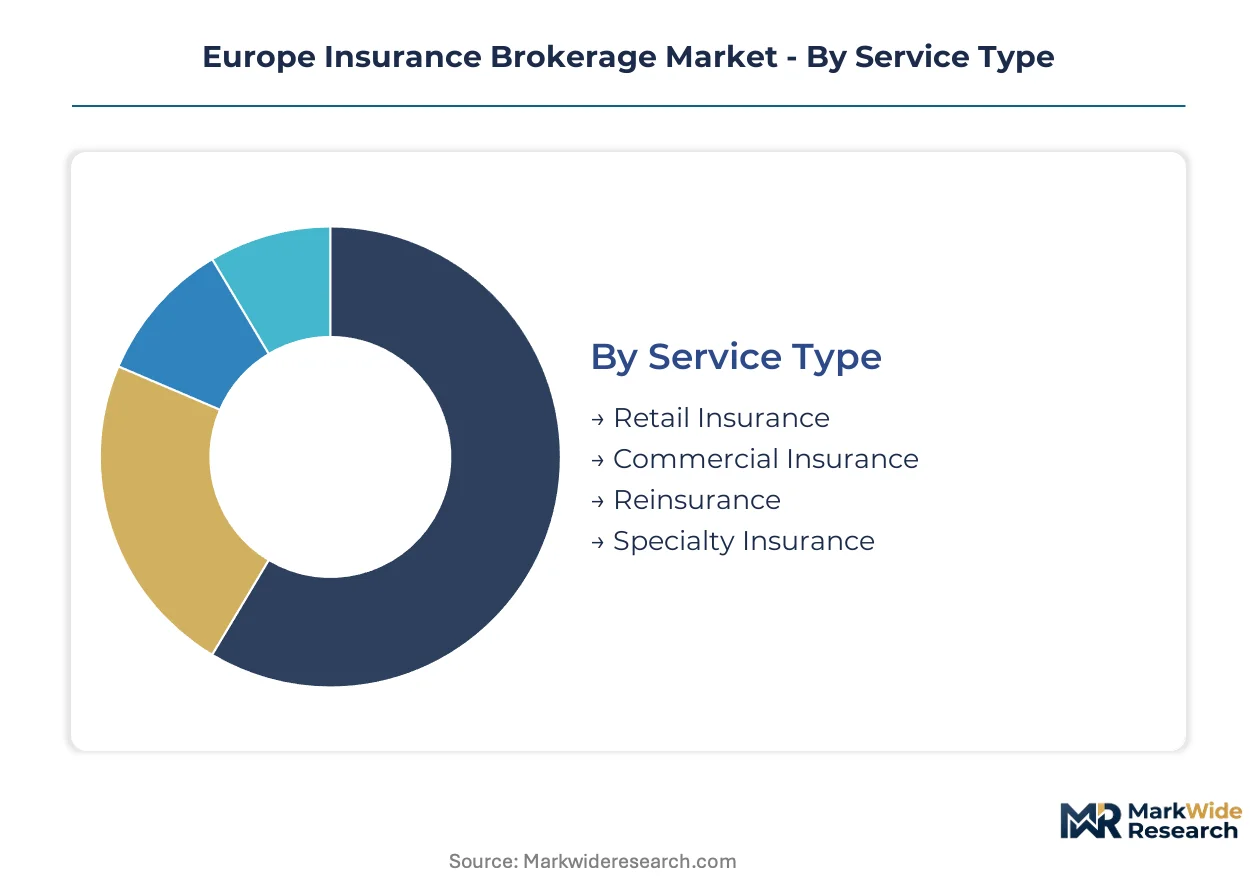
Segmentation in European insurance brokerage reveals how risk complexity, regulatory specialization, and digital maturity fragment revenue pools across service lines and customer tiers. Distinct commercial logics govern each axis, from commission structures in retail placement to fee-based advisory in reinsurance and specialty lines.
Service Type:
Risk sophistication and contract negotiation intensity separate service tiers, with premium retention rates varying by technical complexity and placement duration.
- Commercial Insurance:Property, casualty, and directors-and-officers coverage for corporate buyers generates the largest revenue concentration. German and French mid-market enterprises drive sustained demand as cyber and supply chain liabilities exceed in-house risk management capacity.
- Retail Insurance:Standardized personal lines placement through price comparison websites compresses traditional percentage-based remuneration toward single-digit levels. United Kingdom consumers dominate digital adoption, though broker-mediated advice persists for complex household and motor portfolios.
- Reinsurance:Treaty and facultative placement for ceding insurers concentrates advisory expertise in London and Zurich. Technical pricing and capital modeling requirements sustain fee structures independent of premium volume.
- Specialty Insurance:Niche coverage for marine, aviation, and political risk demands underwriter relationship depth. Lloyd's syndicate access remains the critical differentiator for continental brokers serving multinational manufacturing clients.
Mature deployment sits with Commercial Insurance. Newer deployment is concentrated in Specialty Insurance parametric products tied to climate analytics.
Distribution Channel:
Customer acquisition cost and policy lifecycle automation potential determine channel economics, with API connectivity now a baseline competitive requirement.
- Broker Channel:Traditional intermediary relationships retain dominance in specialty and reinsurance segments where contractual negotiation demands technical expertise. Netherlands and Belgium mid-market buyers are compressing quote-to-bind cycles through direct system integration.
- Online Platform:Price comparison websites and embedded coverage within digital banking interfaces are expanding fastest. Scandinavian consumers lead adoption of real-time premium adjustments through payroll platform integration.
- Direct Channel:Carrier-controlled placement captures standardized personal lines with minimal advisory component. Regulatory scrutiny under EIOPA's Insurance Distribution Directive elevates disclosure obligations for direct-to-consumer marketing.
- Telemarketing:Outbound sales operations persist for renewal retention and simple product cross-selling. GDPR consent frameworks constrain cold outreach effectiveness across cross-border operations.
Established infrastructure concentrates in Broker Channel. Channel investment is accelerating fastest in Online Platform API integrations.
Policy Type:
Capital intensity and claims settlement duration shape profitability profiles, with liability duration mismatches creating structural risk for long-tail lines.
- Property Insurance:Physical asset coverage for commercial and residential buildings. Flood and wildfire parametric products in France and Germany are converging with satellite imagery to create subscription-based advisory services.
- Casualty Insurance:Third-party liability protection spanning professional indemnity to product liability. CSRD disclosure mandates are expanding environmental liability placement advisory across mid-cap enterprises.
- Life Insurance:Mortality and savings-linked contracts with extended duration. Distribution runs through bancassurance partnerships in Southern Europe and independent advisors in Northern markets.
- Health Insurance:Supplementary medical coverage complementing national systems. German and Dutch group schemes dominate corporate benefit arrangements.
Stable premium bases anchor Property Insurance. Policy innovation is concentrating in Casualty Insurance sustainability-linked coverage structures.
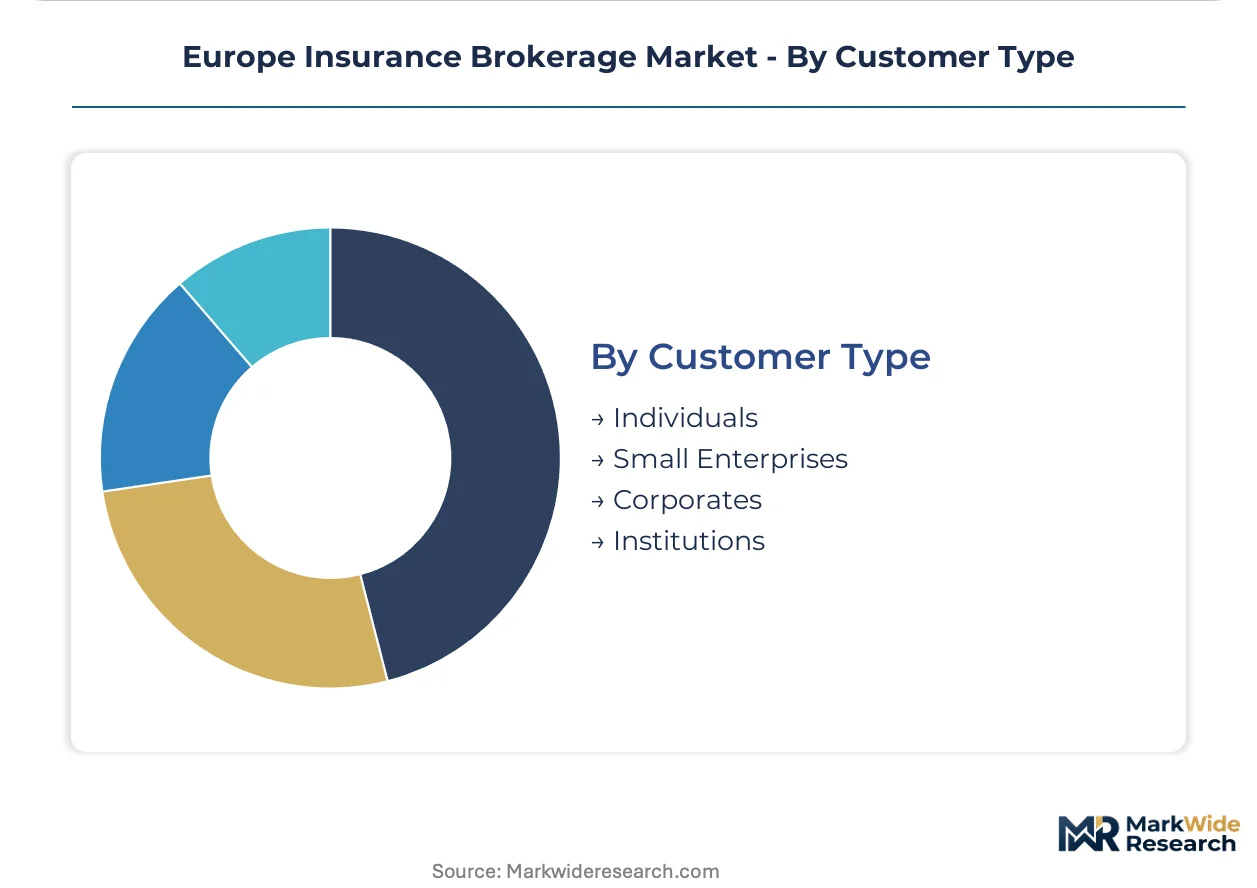
Customer Type:
Risk management maturity and procurement sophistication determine service bundling preferences, with consolidation trends favoring integrated advisory relationships.
- Corporates:Large enterprises with dedicated risk managers consolidating toward single-advisor structures. Denmark and Sweden manufacturing verticals prioritize loss prevention advisory over pure placement efficiency.
- Small Enterprises:German and French SMEs are deepening broker engagement as ESG and cyber liabilities outstrip internal capabilities. Cloud-native policy administration enables real-time premium adjustments for this segment.
- Individuals:Personal lines buyers with price-sensitive procurement patterns. Digital onboarding reduces acquisition costs but compresses advisory interaction depth.
- Institutions:Public sector and nonprofit entities with specialized procurement regimes. EU Green Deal compliance requirements are expanding transition risk coverage mandates for municipal infrastructure.
Relationship depth concentrates with Corporates. Customer acquisition investment is expanding fastest among Small Enterprises seeking outsourced risk management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Luxembourg Special Purpose Reinsurance Zone and Dublin's International Financial Services Centre concentrate captive management and reinsurance advisory operations, drawing broker back-office functions from London and Zurich.
United Kingdom
London's Lloyd's syndicate ecosystem sustains demand for specialty and reinsurance placement expertise. EIOPA's Insurance Distribution Directive imposes conduct standards on wholesale brokers operating from the Square Mile. Manchester and Birmingham mid-market teams are expanding cyber liability advisory for regional manufacturing clients.
Germany
Industrial Mittelstand enterprises in Baden-Württemberg and Bavaria deepen broker engagement for supply chain and ESG risk transfer. BaFin enforces national licensing requirements that exceed minimum EU harmonization thresholds. Frankfurt's reinsurance hub anchors continental treaty placement alongside Zurich.
France
CSRD disclosure mandates drive mid-cap enterprises in Île-de-France toward transition risk quantification services. Autorité de Contrôle Prudentiel et de Résolution supervises intermediary capital adequacy. Lyon and Marseille broker teams specialize in parametric flood coverage for agricultural cooperatives.
Netherlands
Rotterdam port operators and Amsterdam fintech clusters compress quote-to-bind cycles through API-integrated broker platforms. Dutch Authority for the Financial Markets mandates enhanced product governance for direct distribution channels. Eindhoven's high-tech manufacturing verticals prioritize embedded coverage within equipment leasing contracts.
Switzerland
Zurich's reinsurance treaty market sustains fee-based advisory independent of premium volume fluctuations. FINMA coordinates with EIOPA on cross-border intermediary passporting for EU-facing operations. Geneva private banking channels distribute life and health products through tied-agent structures.
Europe Insurance Brokerage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with scale-driven global networks dominating reinsurance advisory while regional boutiques capture mid-market commercial accounts. The vendor base exhibits tiered concentration: three multinational holding companies anchor premium-tier placement capacity, mid-cap national brokers defend geographic density, and digital-native platforms attack standardized personal lines. Strategic moves center on M&A-driven specialty line expansion and proprietary analytics platform development to sustain pricing power.
Within the premium-tier network segment, Marsh McLennan Companies and Aon plc exemplify global scale archetypes with London and Zurich hub concentration, while Howden Group occupies a position as the mid-market challenger expanding through Scandinavia and Southern Europe localized teams. These three structures represent the dominant competitive templates: analytics-led global consolidation, reinsurance-centric advisory depth, and regional density with sector specialization.
| Leading Market Players |
|---|
| Arthur J. Gallagher & Co. |
| Brown & Brown |
| Marsh McLennan Companies |
| Quintes Holding |
| Hyperion Insurance Group |
| Aon plc |
| Howden Group |
| GGW Group |
| Willis Towers Watson |
| Others |
Supply & Pricing Matrix
German Mittelstand manufacturers anchor pricing power for commercial brokerage services, concentrating procurement leverage among mid-market industrial buyers who negotiate fee-based advisory structures rather than percentage commissions. This buyer concentration compresses margins for standardized placement while elevating premiums for complex risk transfer mandates.
Pricing Analysis
Expedited placement timelines command premium fee structures in London and Zurich specialty markets, where treaty negotiation urgency justifies elevated advisory rates. Three-tier pricing structure across premium, standard, and economy levels separates reinsurance advisory from mid-market commercial placement and digital retail distribution. Cost compression in personal lines runs through price comparison website aggregation, eroding traditional commission percentages. SME risk managers exhibit highest price sensitivity, while corporate risk officers prioritize technical advisory depth over placement cost minimization.
Supply Chain Analysis
EIOPA's national licensing requirements reshape sourcing patterns for broker back-office functions, mandating jurisdictional compliance infrastructure in each member state. Advisory talent concentrates in the United Kingdom, Switzerland, and Germany, drawing from actuarial training pipelines and Lloyd's market experience. Technology inputs draw from cloud-native platform providers, satellite imagery analytics vendors, and IoT sensor networks. Single-source vulnerability sits with London's Lloyd's syndicate ecosystem for specialty line capacity. Distribution runs through licensed intermediary networks regulated under national conduct regimes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first policy administration platforms are displacing legacy broker management systems, compressing quote-to-bind cycles from days to hours across Netherlands and Belgium markets. This technology transition rewards carriers and intermediaries who modularize placement workflows into automatable components.
For Market Incumbents: Extend proprietary analytics capabilities into climate risk quantification services, anchoring advisory relationships through subscription-based parametric product offerings. Acquire specialized MGA technology stacks to capture specialty lines previously reserved for Lloyd's syndicates. Defend against digital-native entrants by embedding coverage within payroll and banking platforms through API partnerships. For New Entrants and Emerging Players: Capture Eastern European broker density gaps in Poland and Romania, where digital-first distribution models face limited incumbent resistance. Target mid-market commercial accounts in Scandinavia, where manufacturing verticals prioritize loss prevention advisory over pure placement efficiency. Enter through embedded coverage partnerships with equipment leasing platforms serving Eindhoven's high-tech manufacturing cluster. For Investors and Strategic Acquirers: The window for entry favors algorithmic underwriting specialists with documented model governance frameworks compliant with EU AI Act risk classification requirements. Long-term viability hinges on advisory capabilities that resist full automation, particularly in reinsurance treaty negotiation and climate risk analytics. Monitor EIOPA enforcement patterns for Digital Operational Resilience Act compliance as inflection indicator for regulatory-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| API Platform Integration | Rotterdam port operators compress quote-to-bind cycles through direct system connectivity. |
| Climate Analytics Acquisition | Flood and wildfire parametric products in France leverage satellite imagery subscription models. |
| MGA Technology Stack Buildout | Algorithmic underwriting tools capture specialty lines from traditional Lloyd's syndicate placement. |
| Eastern European Expansion | Poland and Romania exhibit broker density ratios below Western European benchmarks. |
| Model Governance Investment | EU AI Act compliance documentation preempts regulatory examination for automated tools. |
Research Methodology
Independent corroboration across broker management system vendors, carrier underwriting executives, and EIOPA regulatory filings underwrites the qualitative findings. Primary fieldwork engaged risk managers at German Mittelstand enterprises, Dutch fintech platform operators, and London wholesale brokers. Secondary validation drew from Insurance Distribution Directive implementation reports, national conduct authority disclosures, and Lloyd's market capacity data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European insurance value chain.
Comparable historical reference periods anchored the projection framework to pre-pandemic baseline activity and post-DORA regulatory implementation phases. The analytical framework modeled service type segmentation, distribution channel evolution, and customer tier sophistication across the projection horizon. CAGRs derived from premium volume trajectories, commission rate compression patterns, and advisory fee migration trends. Forecast inputs incorporated CSRD disclosure mandate adoption curves and cloud-native platform penetration rates by geography.
The model holds under stable regulatory harmonization and gradual interest rate normalization; deviation in EIOPA enforcement intensity or Lloyd's capacity contraction would shift trajectory boundaries. Forecasts reflect documented assumptions regarding SME risk outsourcing propensity and digital platform adoption elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
North America Trade Finance Market
Financial Services
Cash Flow Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Australia Online Gambling Market
Financial Services
United States Payroll Services Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Spain E-Brokerage Market
Financial Services
ATM Software Market
Financial Services
Europe E-Brokerages Market
Financial Services
Digital Account Opening Market
Financial Services
Debt Settlement Solution Market
Financial Services
South Korea Financial Services Software Market
Financial Services
Commodity Services Market
Financial Services
Foreign Exchange Services Market