
 Remote Mobile Payment Market | 2026-2036
Remote Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Mobile Payment Market Outlook
Merchant-side digital wallet adoption is hardening as street vendors and micro-retailers shift from cash to QR-code settlement. PayPal Holdings Inc. anchors cross-border remittance corridors through its two-sided network density. Alphabet Inc. (Google Pay) leverages India's UPI rails to sustain merchant acquisition momentum. Tencent Holdings Ltd. (WeChat Pay) dominates super-app commerce integration across Chinese-speaking consumer bases.
Remote mobile payment denotes funds transferred between parties where the payer and payee are not physically co-located, typically executed through encrypted tokenized messages routed across cellular or Wi-Fi networks with sub-second authorization latency. The system replaces physical card presentment with credential vaulting and dynamic cryptogram generation for commercial settlement. Digital wallets command the deepest user engagement loops among payment methods, while biometric authentication is displacing password-based verification as the fastest-growing technology layer. QR code infrastructure retains margin efficiency in emerging markets where NFC terminal penetration remains uneven.
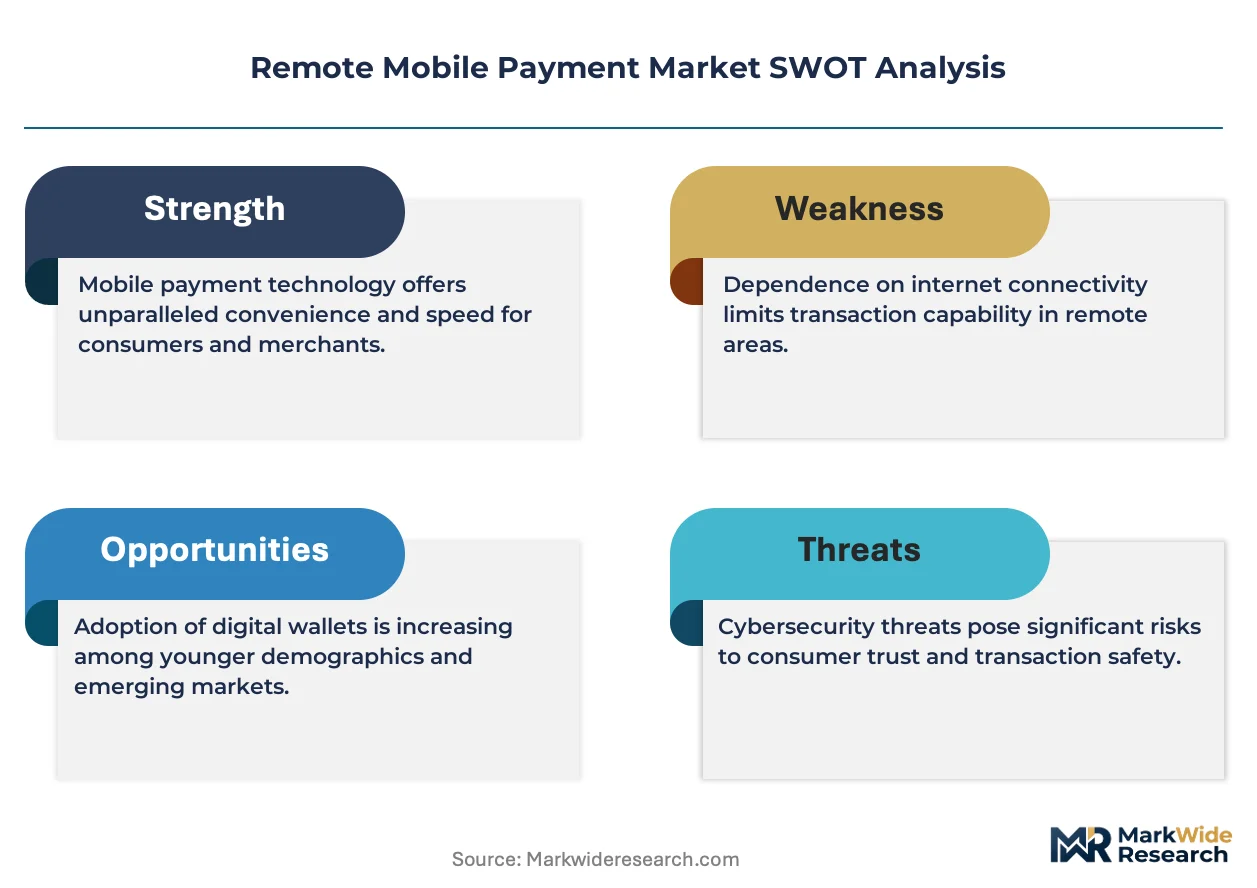
The PCI Security Standards Council governs tokenization protocols, while the EU AI Act and GDPR constrain biometric authentication deployment scope across European user bases. India's RBI mandates two-factor authentication and transaction limits that shape product architecture for domestic providers. Stakeholders must monitor whether India's proposed data localization amendments fragment cloud-based payment processing architectures.
Market Dynamics
India's UPI infrastructure expansion and the PCI Security Standards Council's tokenization mandates are compressing settlement latency while fragmenting cloud-based processing architectures across emerging market corridors.
Growth Catalysts
- UPI Rail Expansion:India's central bank mandates are hardening real-time settlement infrastructure, pulling street vendors and micro-retailers from cash into QR-code ecosystems across tier-two cities.
- Biometric Authentication Layer:Fingerprint and facial recognition protocols are displacing password-based verification, deepening user engagement loops and reducing transaction abandonment at checkout.
- Cross-Border Remittance Corridors:Two-sided network density in Southeast Asian labor migration routes is anchoring wallet-to-wallet settlement volume between sending and receiving economies.
Market Restraints
- Data Localization Proposals:India's proposed amendments to cloud processing rules threaten to fragment server architectures and inflate compliance overhead for foreign payment processors.
- NFC Terminal Gaps:Uneven contactless point-of-sale penetration across Indonesian urban corridors forces continued reliance on QR-code infrastructure with thinner margin profiles.
- Biometric Deployment Constraints:The EU AI Act and GDPR limit facial recognition authentication scope across European user bases, constraining product architecture standardization.
Strategic Opportunities
- Super-App Commerce Integration:Wallet convergence with messaging, transport, and food delivery platforms in Chinese-speaking consumer bases creates sticky ecosystem lock-in.
- Small Merchant Onboarding:Indonesia's urban corridors present white space for simplified KYC workflows targeting unbanked micro-retailers currently operating in cash.
- Tokenization Standardization:PCI Security Standards Council protocols offer regulatory tailwind for credential vaulting services that replace physical card presentment with dynamic cryptogram generation.
Industry Challenges
- Two-Factor Authentication Friction:RBI-mandated transaction limits and step-up authentication requirements complicate low-value payment flows and increase checkout abandonment.
- Legacy Core Banking Integration:Regional banks in Southeast Asia maintain siloed ledger systems that resist API-native wallet connectivity, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Mobile Payment Market |
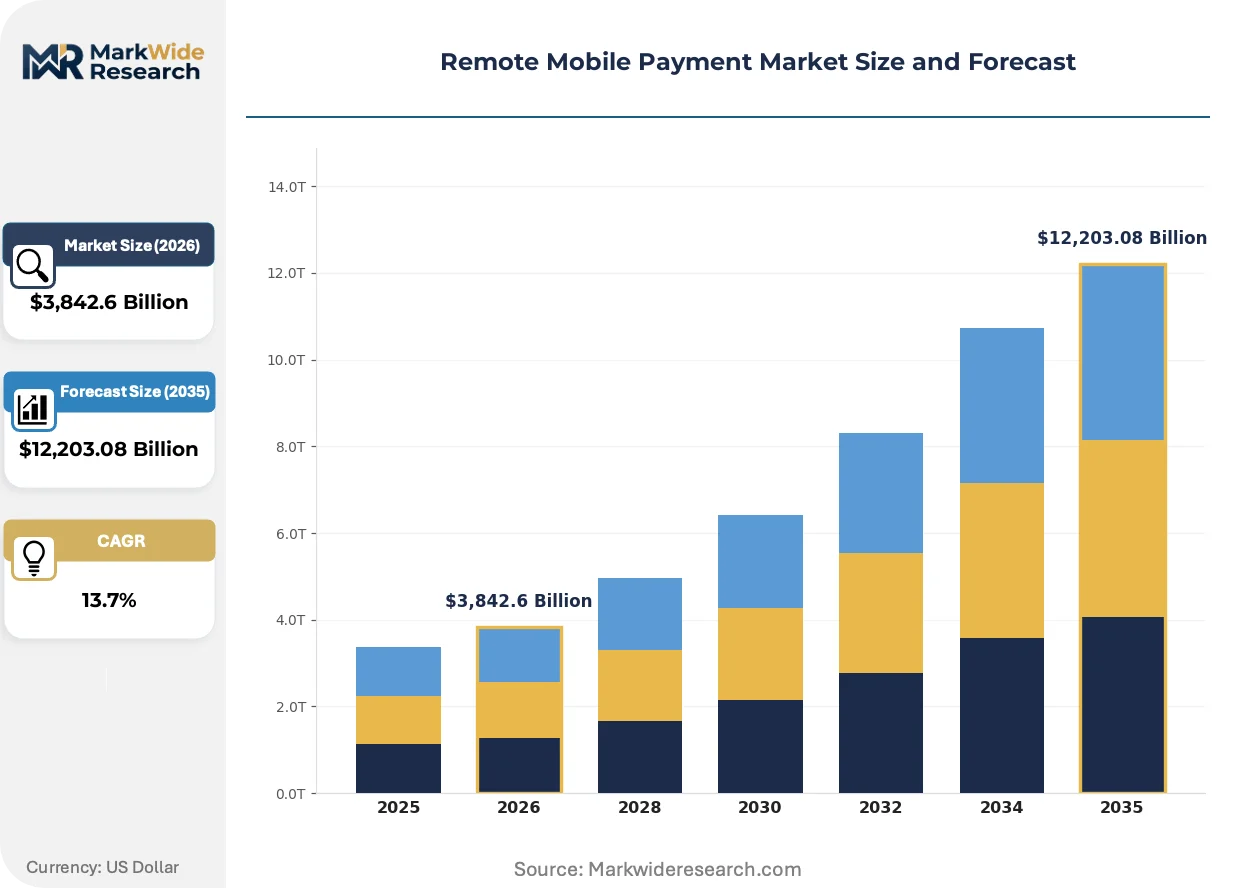
| Market Size in 2026 | $3,842.6 Billion |
| Market Size in 2035 | $12,203.08 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer User Type: Consumer, Merchant, Service Provider, Corporate Entity Technology: Near Field Communication, QR Code, Biometric Authentication, Tokenization Transaction Size: Micro Payments, Low Value, Medium Value, High Value |
| Companies Covered | Alipay (Ant Group), PayPal Holdings Inc., Apple Inc., Alphabet Inc. (Google Pay), Samsung Electronics Co. Ltd. (Samsung Pay), Tencent Holdings Ltd. (WeChat Pay), Amazon.com Inc., Visa Inc., Mastercard Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Mobile Payment Market Strategic Shifts
Payment infrastructure is modularizing around tokenized credential vaults and biometric identity layers, compressing the boundary between authentication and settlement while fragmenting legacy acquiring bank relationships.
Software-defined tokenization is modularizing transaction security architectures. The technology replaces static card numbers with dynamic cryptograms regenerated per transaction. Small merchants across India's tier-two cities are adopting vault-as-a-service models at accelerating pace. This modularization is compressing PCI compliance scope and shifting liability from merchants to token service providers.
GDPR and the EU AI Act are constraining biometric authentication deployment across European payment apps. The regulations mandate explicit consent loops and algorithmic audit trails for facial recognition systems. Premium wallet providers in Germany and France are responding by hybridizing fingerprint with PIN fallback to maintain conversion rates while preserving compliance posture.
Merchant acquisition is shifting from hardware-led terminal distribution to software-only onboarding via QR-code generation. Aggregators in Indonesia are disintermediating traditional acquiring banks by offering instant merchant IDs through mobile apps. This behavioral pivot is most visible among street food vendors in Jakarta and Surabaya who bypass POS hardware entirely.
Remote Mobile Payment Market Segmentation
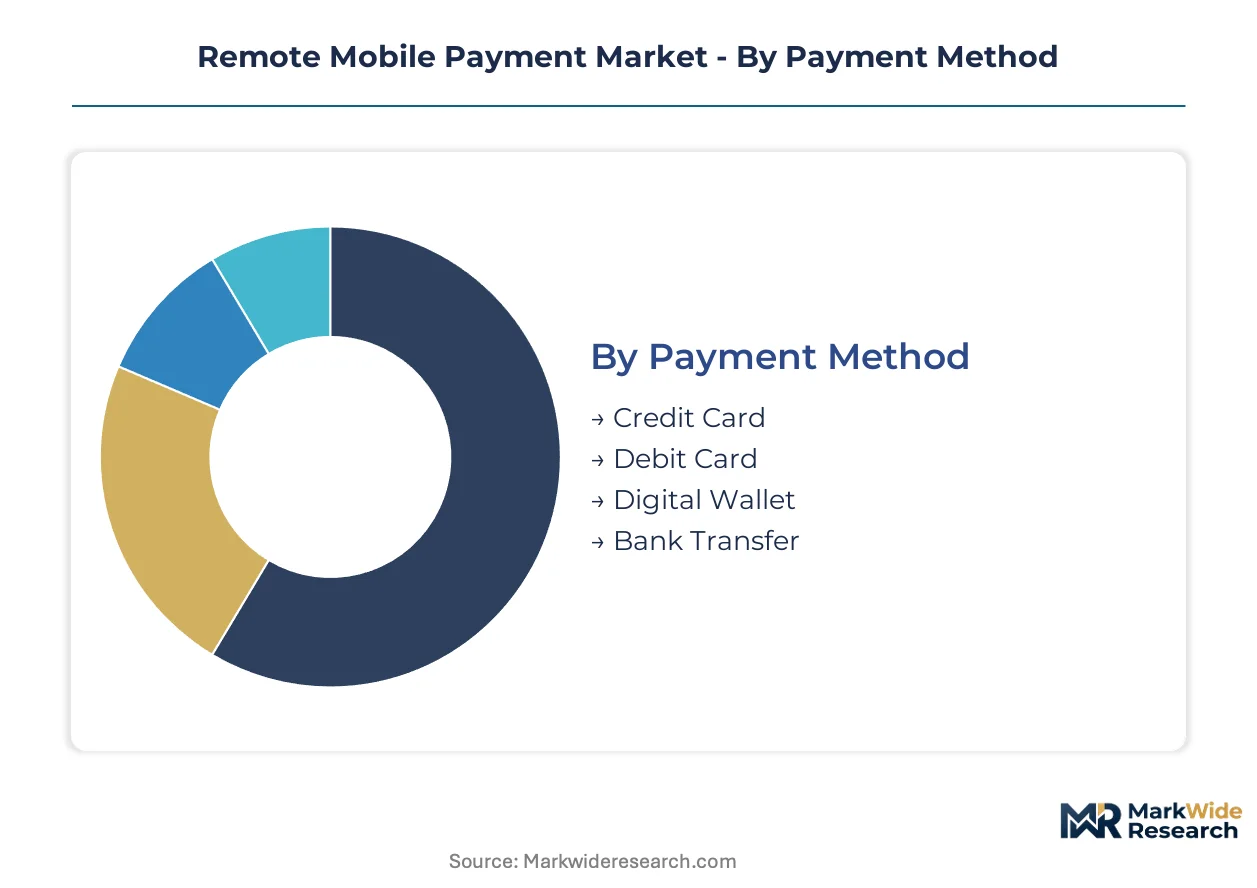
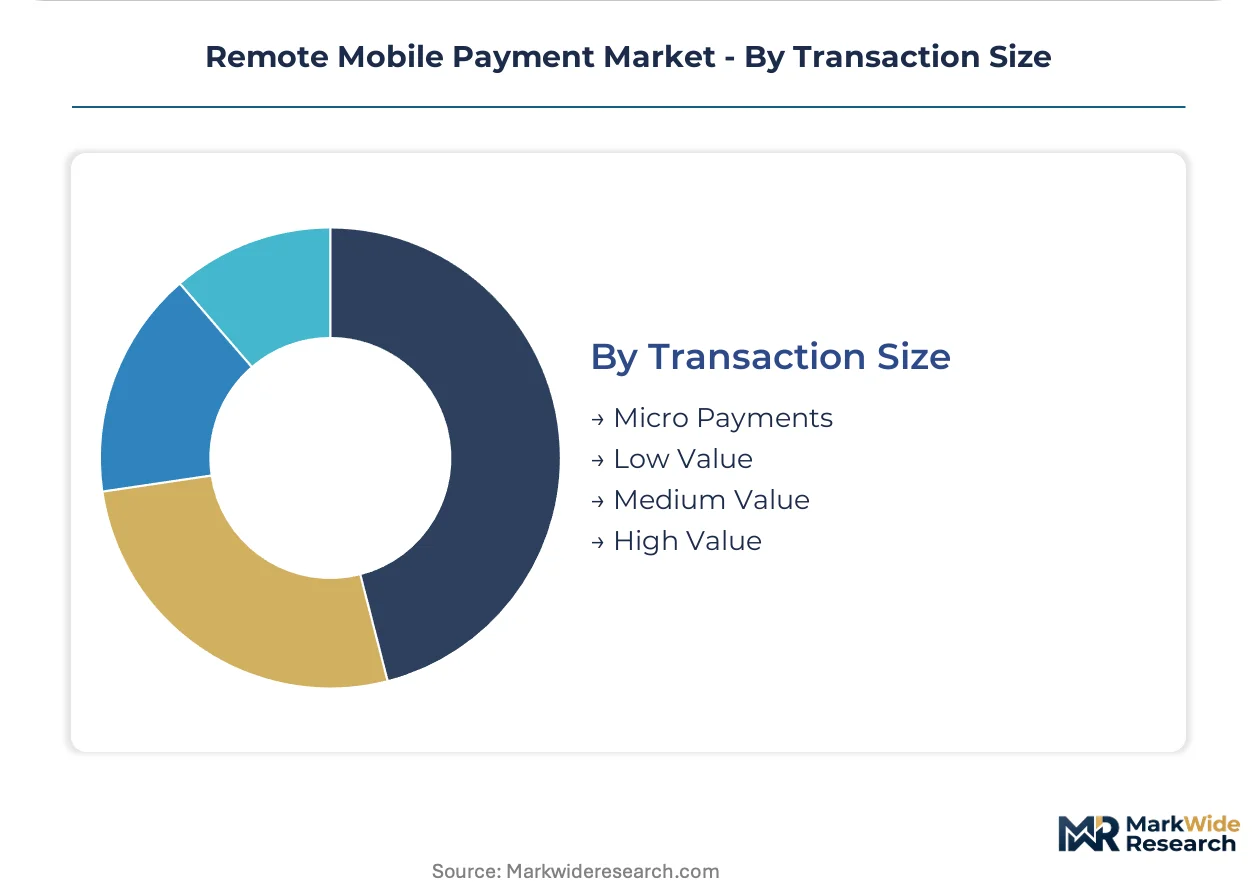
Remote mobile payment architectures fragment across four intersecting dimensions that determine infrastructure requirements, authentication protocols, and margin structures. Payment method and technology choices dictate capital intensity for merchants, while user type and transaction size shape regulatory compliance scope and fraud prevention layering.
Payment Method:
Merchant cost tolerance and settlement speed requirements differentiate buyers across this category, with micro-retailers prioritizing zero hardware deployment against corporate treasuries demanding instant reconciliation.
- Credit Card:Credential vaulting replaces physical card presentment through dynamic cryptogram generation per transaction. Demand concentrates among cross-border e-commerce merchants in India and Indonesia seeking chargeback protection and consumer trust markers.
- Debit Card:Direct bank account linkage with real-time balance verification reduces interchange costs versus credit rails. India's UPI infrastructure expansion is pulling tier-two city merchants toward debit-linked QR settlement over cash handling.
- Digital Wallet:Closed-loop stored value systems with super-app integration. Street vendors across Jakarta and Surabaya adopt instant merchant ID generation via mobile apps, bypassing POS hardware entirely.
- Bank Transfer:Account-to-account push payments with batch or real-time settlement options. Corporate entities in Southeast Asian trade corridors leverage this for supplier payments where card acceptance costs prove prohibitive.
Volume sits with Digital Wallet; growth tilts toward Bank Transfer.
User Type:
Compliance burden and transaction frequency separate participants, with consumers driving volume density while service providers require API-native infrastructure.
- Consumer:Individual payers executing peer-to-peer transfers, e-commerce checkout, and bill settlement. India's RBI-mandated two-factor authentication shapes product architecture for domestic wallet providers.
- Merchant:Businesses accepting remote payment settlement through integrated or standalone acceptance solutions. Micro-retailers in Indonesia's urban corridors present white space for simplified KYC workflows targeting unbanked operators.
- Service Provider:Technical intermediaries including payment aggregators, gateway operators, and token service providers. PCI Security Standards Council protocols compress compliance scope and shift liability from merchants to these specialized entities.
- Corporate Entity:Enterprises managing treasury flows, payroll disbursement, and supplier settlement. Cross-border remittance corridors between Southeast Asian labor-sending and receiving economies anchor wallet-to-wallet volume here.
Volume sits with Consumer; growth tilts toward Service Provider.
Technology:
Hardware penetration and biometric deployment regulations create geographic stratification in adoption patterns.
- Near Field Communication:Contactless radio-frequency communication requiring terminal infrastructure. Uneven POS penetration across Indonesian urban corridors constrains deployment versus QR alternatives.
- QR Code:Optical machine-readable matrix enabling software-only merchant onboarding. Aggregators disintermediate traditional acquiring banks through instant merchant ID issuance, visible among Jakarta street food vendors.
- Biometric Authentication:Fingerprint and facial recognition protocols displacing password verification. GDPR and the EU AI Act constrain facial recognition scope across European user bases, mandating explicit consent loops and algorithmic audit trails.
- Tokenization:Dynamic credential substitution replacing static card numbers per transaction. Software-defined tokenization compresses PCI compliance scope as small merchants in India's tier-two cities adopt vault-as-a-service models.
Volume sits with QR Code; growth tilts toward Biometric Authentication.
Transaction Size:
Authentication friction tolerance and fraud risk exposure distinguish segments, with low-value flows requiring minimal step-up and high-value transfers demanding multi-factor verification.
- Micro Payments:Sub-dollar transactions for transit, parking, and vending. RBI-mandated transaction limits complicate low-value flows in India, increasing checkout abandonment where step-up authentication triggers.
- Low Value:Everyday retail purchases below typical contactless limits. QR-code infrastructure retains margin efficiency in emerging markets where NFC terminal gaps persist.
- Medium Value:Recurring subscriptions, utility bills, and small business procurement. Biometric authentication deepens engagement loops here by reducing transaction abandonment.
- High Value:B2B settlement, property transactions, and luxury purchases. Tokenization standardization offers regulatory tailwind for credential vaulting services replacing physical card presentment.
Volume sits with Low Value; growth tilts toward Micro Payments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore have concentrated payment infrastructure development, drawing fintech investment into dense regulatory sandboxes where real-time settlement rails scale fastest.
India
UPI rail expansion pulls street vendors and micro-retailers from cash into QR-code ecosystems across tier-two cities. RBI mandates two-factor authentication and transaction limits that shape product architecture for domestic wallet providers. Mumbai and Bangalore clusters anchor merchant acquisition momentum as aggregators disintermediate traditional acquiring banks.
Indonesia
Urban corridors in Jakarta and Surabaya present white space for simplified KYC workflows targeting unbanked micro-retailers currently operating in cash. Bank Indonesia's payment system roadmap accelerates real-time gross settlement modernization. Aggregators issue instant merchant IDs through mobile apps, bypassing POS hardware entirely among street food vendors.
China
Super-app commerce integration dominates Chinese-speaking consumer bases, creating sticky ecosystem lock-in through messaging, transport, and food delivery platform convergence. SAMR antitrust oversight constrains exclusive payment arrangement enforcement. Shenzhen and Hangzhou clusters drive biometric authentication deployment at scale.
United States
Cross-border remittance corridors anchor wallet-to-wallet settlement volume between sending and receiving economies through two-sided network density. State-level money transmission licensing fragments compliance scope for foreign payment processors. Silicon Valley and New York fintech clusters concentrate tokenization protocol development.
Germany
GDPR and the EU AI Act constrain facial recognition authentication scope across European user bases, mandating explicit consent loops and algorithmic audit trails. BaFin payment services oversight shapes open banking API standardization. Berlin and Frankfurt clusters hybridize fingerprint with PIN fallback to maintain conversion rates while preserving compliance posture.
Remote Mobile Payment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with platform-native wallet providers commanding denser user engagement loops than hardware-dependent terminal distributors. The vendor base stratifies into three tiers: super-app integrators with messaging-commerce convergence, UPI-rail specialists with regulatory sandbox advantages, and cross-border remittance anchors with two-sided network density. Dominant competitive moves include strategic partnerships with regional banks for core ledger integration and geographic expansion through simplified KYC workflows targeting unbanked micro-merchants.
Within the super-app integrator tier, Tencent Holdings Ltd. and Alipay (Ant Group) exemplify ecosystem lock-in through commerce-messaging-transport convergence. PayPal Holdings Inc. anchors the cross-border remittance archetype with two-sided network density across labor migration corridors. Alphabet Inc. (Google Pay) occupies a position within the UPI-rail specialist category, leveraging India's real-time settlement infrastructure for merchant acquisition momentum.
| Leading Market Players |
|---|
| Alipay (Ant Group) |
| PayPal Holdings Inc. |
| Apple Inc. |
| Alphabet Inc. (Google Pay) |
| Samsung Electronics Co. Ltd. (Samsung Pay) |
| Tencent Holdings Ltd. (WeChat Pay) |
| Amazon.com Inc. |
| Visa Inc. |
| Mastercard Incorporated |
| Others |
Value Chain & Pricing Dynamics
Software engineering talent clusters in Bangalore and Shenzhen compress development cost differentials across tier-one and tier-two payment service providers, widening pricing spreads between premium API-native platforms and economy-grade QR-code aggregators.
Pricing Analysis
Short lead-time deployment commands premium pricing as merchants demand instant onboarding versus standard provisioning windows. The dominant structure runs subscription-tiered with transaction-volume bands, where price differentiation rests on API sophistication and RBI compliance certification tiers. Cost compression in economy-tier acquiring is intensifying because Indonesian aggregators disintermediate traditional banks with zero-hardware onboarding. Micro-merchants in Jakarta's street vendor economy exhibit highest price sensitivity; corporate treasuries in cross-border corridors show lowest.
Supply Chain Analysis
Dual-sourcing requirements from tier-one merchants mandate multi-cloud qualification across AWS, Google Cloud, and Alibaba Cloud for resilience. Geographic supply concentration centers on India, Indonesia, and Singapore for payment processing infrastructure. Raw material dependencies include semiconductor chips for POS terminals, encryption modules for tokenization, and biometric sensors for authentication layers. Single-source vulnerability in cloud regions threatens continuity. Distribution runs through API-first platform marketplaces and direct bank channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Token service provider capacity constraints prop pricing power across the credential vaulting layer, creating supply-constrained conditions for compliant infrastructure.
For Market Incumbents: Extend UPI-rail specialization through deeper RBI sandbox engagement, locking in regulatory moats against emerging neobank challengers. Fortify merchant acquisition density in India's tier-two cities before foreign wallet providers achieve compliance localization. Vertical integration into biometric authentication modules reduces dependency on constrained sensor suppliers. For New Entrants and Emerging Players: Unbanked micro-retailers in Indonesia's Surabaya corridor represent the most penetrable buyer archetype, bypassing saturated Jakarta competition. Simplified KYC workflows targeting street food vendors unlock white-space volume. Partner with existing QR-code aggregators for instant distribution rather than building merchant networks organically. For Investors and Strategic Acquirers: Re-rating potential sits with PCI-certified token service providers given India's data localization amendments accelerating domestic infrastructure demand. Long-term viability favors archetypes with regulatory sandbox positioning across multiple emerging markets. Watch RBI cloud-processing rule finalization as inflection signal for foreign processor market access.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Expansion | RBI sandbox positioning accelerates product iteration velocity ahead of compliance mandates. |
| Biometric Authentication Investment | Fingerprint and facial recognition deployment deepens user engagement loops in India. |
| Cross-Border Remittance Partnership | Two-sided network density anchors wallet-to-wallet volume across Southeast Asian labor corridors. |
| Merchant Acquisition Platform | Software-only onboarding via QR-code generation disintermediates traditional acquiring bank relationships. |
| Tokenization Infrastructure Buildout | PCI Security Standards Council protocols shift liability from merchants to specialized service providers. |
Study Parameters
Multi-period observation of UPI transaction velocity, merchant onboarding rates, and biometric authentication adoption anchored the trend analysis, supplemented by interviews with payment platform CTOs, RBI regulatory affairs leads, merchant acquiring heads at regional banks, and token service provider engineering directors. Secondary validation drew from NPCI operational bulletins, PCI Security Standards Council documentation, Bank Indonesia payment system reports, and SEC filings of listed payment processors. Bottom-up merchant density modeling triangulated against top-down market sizing across the analysis window.
Segment-weighting applied differential growth assumptions across payment method, user type, technology layer, and transaction size dimensions, with India's UPI expansion trajectory and Indonesia's financial inclusion roadmap as primary forecast inputs. CAGRs derived from logistic adoption curves fitted to historical penetration data, moderated by regulatory implementation timelines and infrastructure deployment schedules throughout the forecast period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RBI data localization amendments and EU AI Act biometric deployment constraints. Deviation in India's cloud-processing rule finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Cross-Border Payment Platform Market
Payments
Africa Mobile Money Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
MENA Digital Payments Market
Payments
Japan Credit Cards Market
Payments
B2C Payment Market
Payments
Cryptocurrency Payment Apps Market
Payments
Global Payments Market
Payments
Transit Cards Market
Payments
Latin America Retail Cash Management Market
Payments
United Kingdom Payment Gateway Market
Payments
Europe Real Time Payments Market
Payments
Europe Payment Gateways Market
Payments
Mpos Terminals Market