
 Cryptocurrency Exchanges Market | 2026-2036
Cryptocurrency Exchanges Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptocurrency Exchanges Market Insights
Stablecoin infrastructure is pivoting from Ethereum-based ERC-20 rails to lower-cost Layer-2 networks and alternative Layer-1 protocols, compressing settlement economics for exchange operators. Binance leverages its proprietary BNB Chain ecosystem to reduce withdrawal and transfer friction for retail users. Coinbase Exchange anchors its competitive position through deep integration with US banking rails and regulatory pre-clearance across multiple state jurisdictions. OKX competes aggressively on derivatives margin products, sustaining high-frequency trader engagement through sub-second matching engine latency.
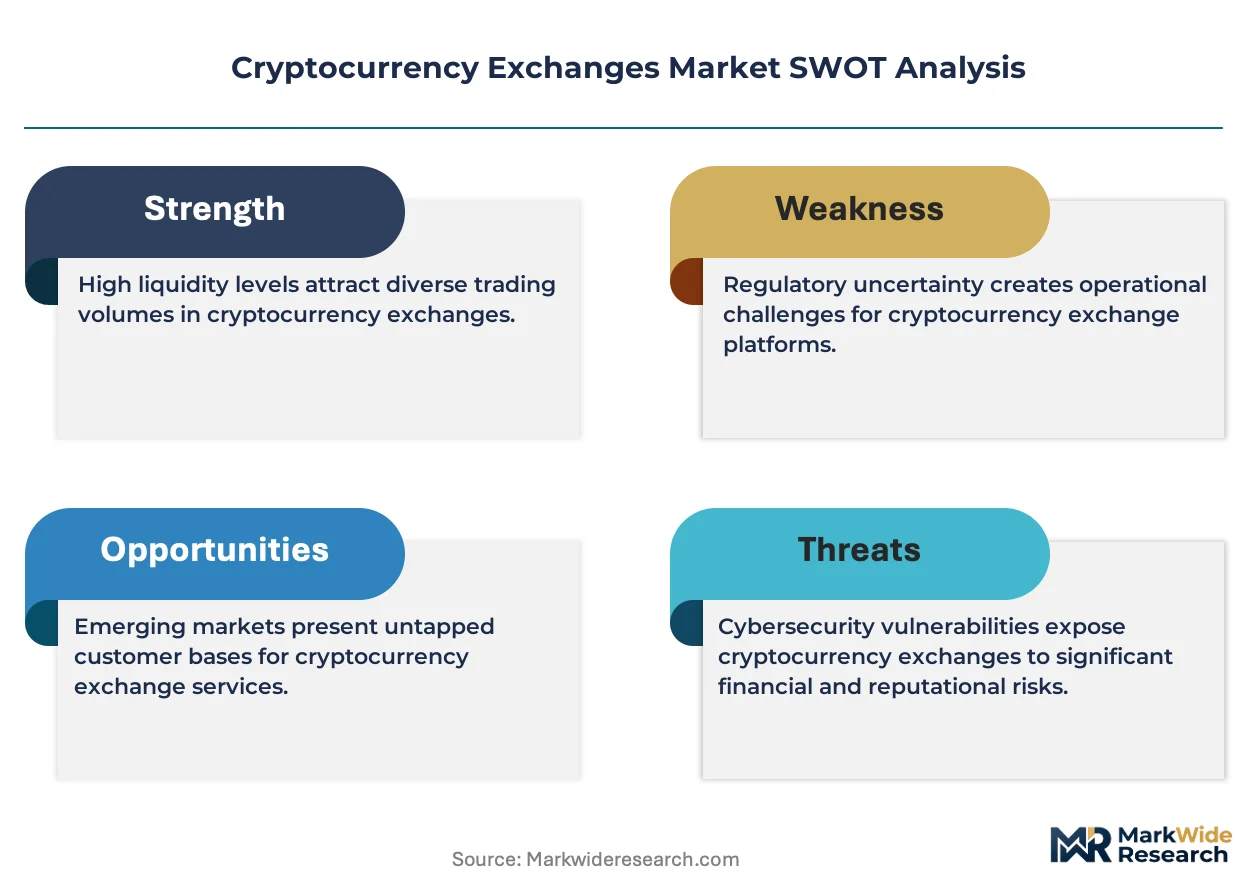
Cryptocurrency exchanges are digital platforms that match buy and sell orders for crypto assets, operating through order books or automated market maker protocols with throughput measured in thousands of transactions per second. Their primary commercial purpose is to provide price discovery, liquidity aggregation, and custody infrastructure for digital asset holders. Centralized platforms still dominate transaction volume globally, though decentralized exchange protocols capture growing share among sophisticated users seeking non-custodial execution. Revenue from trading fees remains the largest margin pool, while staking and lending services represent the fastest-growing service offering as exchanges seek recurring non-volatile income streams.
The SEC and CFTC in the United States, alongside the EU's MiCA framework and Singapore's MAS licensing regime, collectively determine which exchange business models achieve market access and which face operational restrictions. These regulators shape demand by defining permissible asset listings, reserve requirements for custodial operations, and consumer protection standards that directly influence platform architecture. Stakeholders must monitor how jurisdictional arbitrage between permissive and restrictive regimes redistributes trading volume and where licensing convergence creates sustainable competitive moats.
Market Dynamics
Stablecoin settlement infrastructure is compressing transaction economics and forcing exchanges to migrate liquidity provisioning from Ethereum mainnet to alternative Layer-1 and Layer-2 protocols.
Growth Catalysts
- MiCA Framework Implementation:The EU's Markets in Crypto-Assets regulation provides unified licensing pathways across member states, reducing compliance fragmentation for cross-border operators.
- Layer-2 Scaling Adoption:Zero-knowledge rollup architectures on Arbitrum and Optimism are slashing settlement costs by orders of magnitude compared to base-layer execution.
- Singapore Regulatory Sandbox:MAS licensing experiments accelerate institutional on-ramp development through controlled testing environments for novel custody arrangements.
Market Restraints
- State-Level Licensing Fragmentation:The US money transmitter license patchwork forces operators to maintain 50-plus separate compliance programs, inflating fixed cost structures.
- Ethereum Gas Volatility:Base-layer fee spikes during network congestion erode margin on small-denomination trades and micropayment settlements.
- Cross-Border Capital Controls:Restrictive foreign exchange regimes in emerging markets limit fiat on-ramp availability and trap liquidity in jurisdictional silos.
Strategic Opportunities
- United Arab Emirates VARA Licensing:Dubai's dedicated virtual asset regulator offers accelerated approval timelines for derivatives and staking product suites.
- Institutional Custody Integration:Convergence of multi-party computation with hardware security modules enables insurance-grade cold storage for pension and endowment allocators.
- South Korea KYC-Linked Banking:Real-name verification mandates create partnership opportunities with commercial banks for seamless won-denominated settlement rails.
Industry Challenges
- Smart Contract Audit Talent Scarcity:Formal verification expertise for complex DeFi protocol integrations commands premium compensation and extends security review timelines.
- MiCA Travel Rule Compliance:Real-time beneficiary identification requirements for transfers above EUR 1,000 demand infrastructure rebuilds for transaction monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptocurrency Exchanges Market |
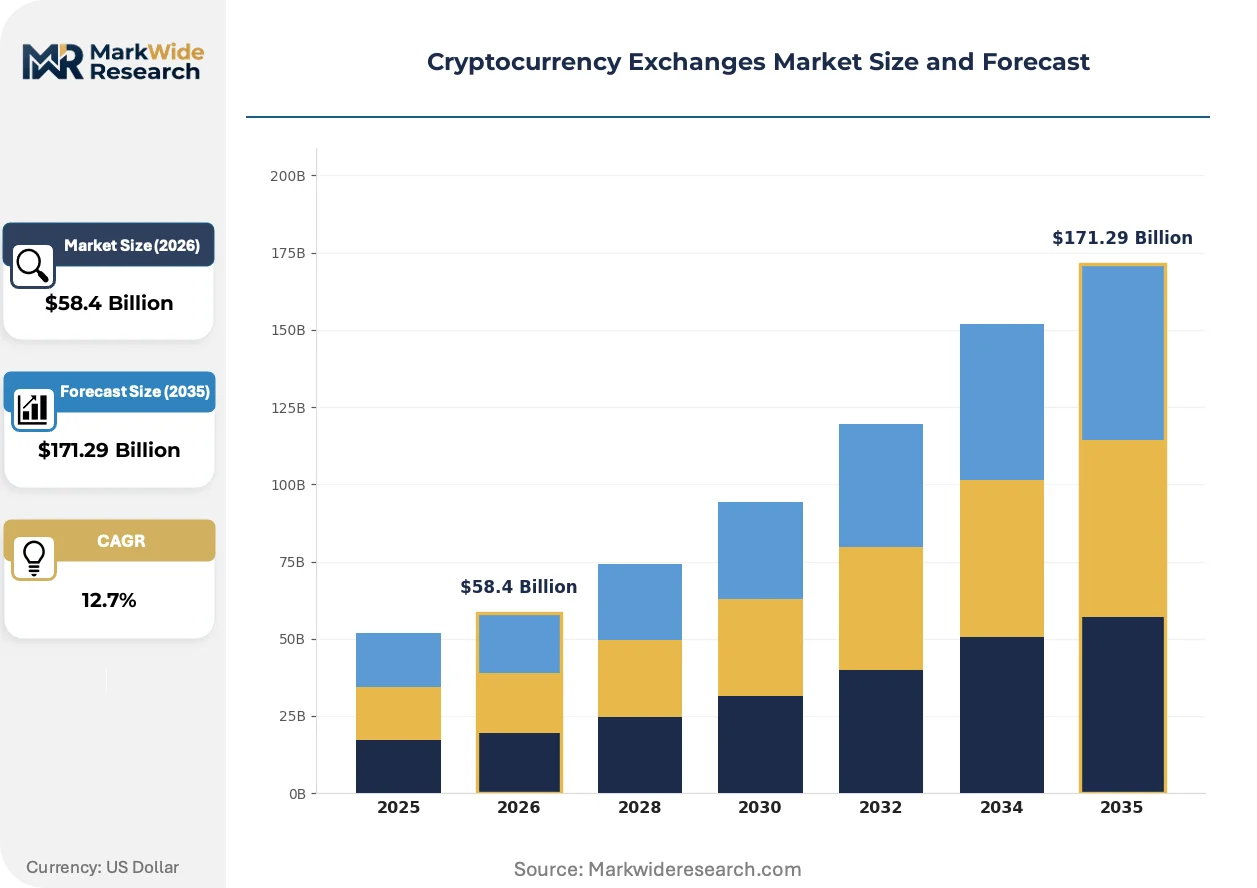
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $171.29 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Centralized, Decentralized, Hybrid, Peer-to-Peer, Broker Revenue Model: Trading Fees, Listing Fees, Withdrawal Charges, Subscription Plans, Margin Fees, Advertisement User Type: Retail Traders, Institutional Investors, High Net-Worth Individuals, Market Makers, Arbitrageurs Service Offering: Spot Trading, Futures Trading, Margin Trading, Staking, Lending, Custodial Solutions |
| Companies Covered | Binance, Bybit, Coinbase Exchange, OKX, Bitget, Gate.io, KuCoin, HTX, Kraken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptocurrency Exchanges Market Trends and Innovations
Execution infrastructure is fragmenting across specialized venues as traders demand venue-agnostic liquidity access and non-custodial alternatives erode traditional exchange dominance.
Zero-knowledge proof systems are rewriting settlement finality guarantees for retail and institutional order flow alike. High-frequency trading desks on Singapore-registered venues are migrating matching engine logic to zk-rollup sequencers for sub-100 millisecond confirmation latency. This compression is enabling atomic cross-margining between spot and perpetual futures positions without intermediate custody handoffs.
The SEC's broker-dealer custody rule proposals are forcing US-registered platforms to rearchitect cold storage operations around qualified custodian partnerships. Institutional clients now demand SOC 2 Type II attestation and insurance-backed segregation as table stakes for treasury allocation. European operators under MiCA are responding faster through passportable authorization structures that reduce state-by-state friction.
Aggregated liquidity sourcing is displacing single-venue loyalty among sophisticated retail cohorts. Traders in South Korea and the United Arab Emirates increasingly route orders through smart order routers that split execution across centralized limit books and automated market maker pools. This behavior concentrates volume on platforms offering unified API access to both custody models rather than pure-play alternatives.
Cryptocurrency Exchanges Market Segmentation
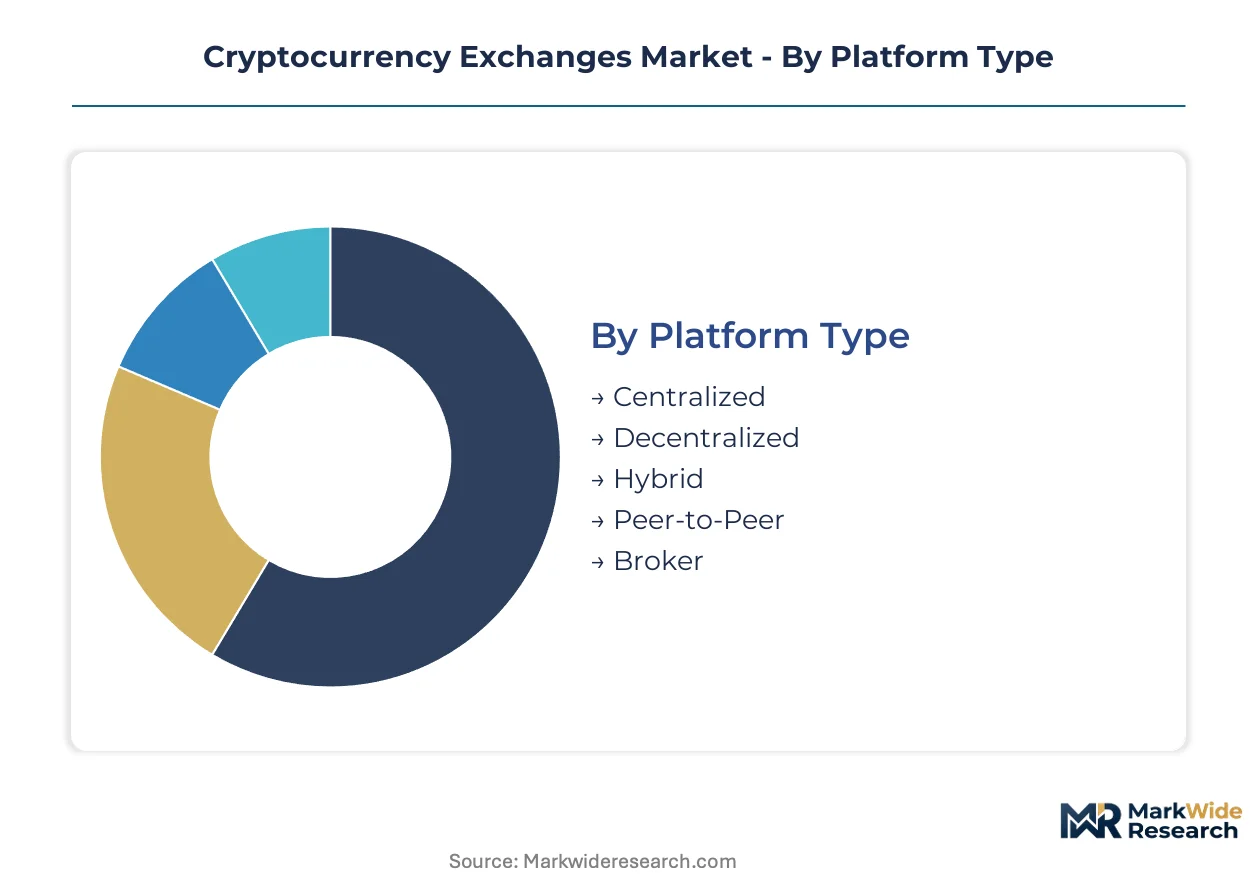
Exchange operators configure platform architecture around distinct liquidity pools, fee extraction mechanisms, and custody models. Segmentation reveals how revenue concentration shifts between retail flow capture and institutional service tiers as regulatory clarity emerges across jurisdictions.
Platform Type:
Centralized architectures dominate transaction throughput while decentralized alternatives gain traction among non-custodial seekers, spanning the standardization spectrum from fully proprietary matching engines to permissionless protocol deployments.
- Centralized:Operators maintain proprietary order books with sub-second matching latency and integrated custody infrastructure. Demand concentrates in Singapore and the United Arab Emirates where MAS and VARA licensing frameworks provide operational certainty for retail flow aggregation.
- Decentralized:Automated market maker protocols execute trades through smart contracts without intermediary custody. South Korean traders increasingly route volume through these venues to circumvent real-name banking verification friction.
- Hybrid:Combines centralized order matching with non-custodial settlement rails.
- Peer-to-Peer:Direct bilateral settlement between counterparties with escrow mediation.
- Broker:Agency execution model with mark-up pricing rather than exchange fees.
Leading the category by volume: Centralized. Growing fastest: Decentralized.
Revenue Model:
Fee structures stratify across transaction-based extraction and recurring service subscriptions, reflecting margin pressure from Layer-2 settlement cost compression.
- Trading Fees:Maker-taker schedules generate the core revenue pool, with discounts for native token staking. Institutional desks in the United States negotiate bespoke rates through prime brokerage arrangements.
- Listing Fees:Asset issuers pay for market access and liquidity bootstrapping. European projects under MiCA seek regulated venues with passportable authorization.
- Withdrawal Charges:Network fee pass-throughs with operator mark-ups.
- Subscription Plans:Tiered access to advanced analytics and API throughput.
- Margin Fees:Interest on borrowed collateral for leveraged positions.
- Advertisement:Promotional placement for token projects and DeFi protocols.
Trading fees capture the dominant share. Subscription plans are expanding most quickly as exchanges pursue recurring revenue.
User Type:
Customer segmentation tracks capital deployment scale and execution sophistication, from algorithmic arbitrage to passive custody holding.
- Retail Traders:Individual accounts with sub-$100,000 balances drive platform adoption through mobile interfaces. Southeast Asian markets exhibit the steepest expansion trajectory as stablecoin on-ramps displace traditional banking rails.
- Institutional Investors:Pension funds and endowments demand SOC 2 Type II attestation and insurance-backed segregation. US-registered platforms rearchitect custody around qualified custodian partnerships per SEC broker-dealer proposals.
- High Net-Worth Individuals:Private banking integration with dedicated relationship management.
- Market Makers:Liquidity providers earning bid-ask spreads with exchange fee rebates.
- Arbitrageurs:Cross-venue price discrepancy exploitation through automated strategies.
Retail traders dominate account count. Institutional investors command the fastest-growing service tier.
Service Offering:
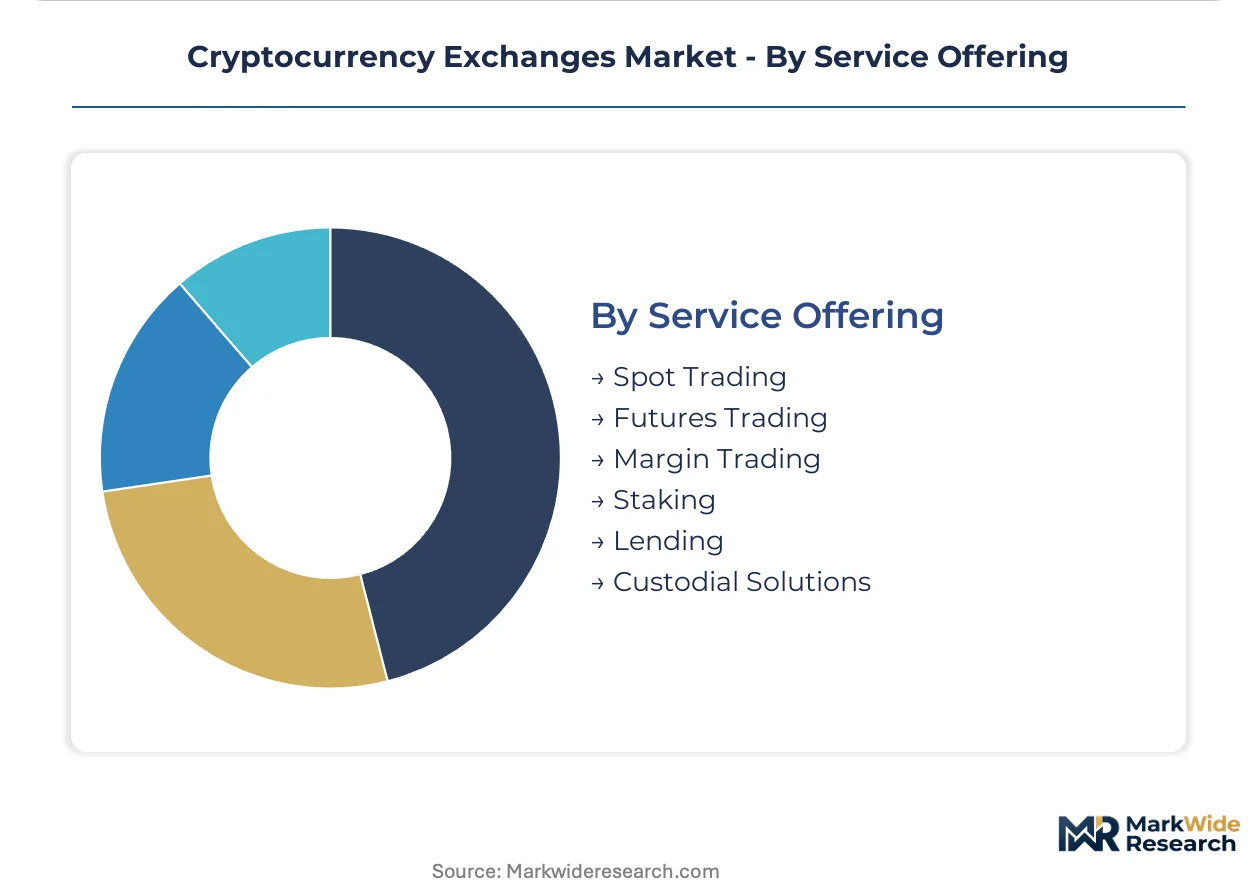
Product suites extend beyond spot execution into derivatives, yield generation, and institutional custody, creating margin differentiation through complexity.
- Spot Trading:Immediate settlement of crypto-to-crypto and fiat-to-crypto pairs. Volume concentrates on Singapore-registered venues offering zero-knowledge rollup settlement for cost efficiency.
- Futures Trading:Perpetual and dated contracts with leverage up to 125x on offshore platforms. OKX competes aggressively through sub-second matching engine latency for high-frequency engagement.
- Margin Trading:Collateralized borrowing for leveraged spot positions.
- Staking:Delegated proof-of-stake participation with operator fee sharing.
- Lending:Institutional and retail yield through pooled liquidity.
- Custodial Solutions:Cold storage with multi-party computation and hardware security module integration.
Spot trading leads by transaction count. Staking services are climbing the fastest as exchanges seek non-volatile income streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail traders in Singapore, the United Arab Emirates, and South Korea are driving platform adoption as stablecoin settlement layers replace traditional fiat on-ramps. MiCA in Europe and state-level licensing in the United States are reshaping compliance architecture. Demand concentrates in jurisdictions building tailored regulatory sandboxes.
United States
Institutional treasuries and hedge funds anchor demand through qualified custodian partnerships. The SEC's broker-dealer custody rule proposals force platforms to rearchitect cold storage operations. New York and California host the densest clusters of compliance-focused operators navigating the 50-plus state money transmitter license patchwork.
Singapore
High-frequency trading desks and family offices drive volume through zero-knowledge rollup settlement for cost efficiency. MAS licensing experiments accelerate institutional on-ramp development through controlled testing environments. The city-state's regulatory sandbox attracts derivatives specialists seeking sub-second matching engine deployment.
United Arab Emirates
Derivatives traders and staking product seekers gravitate toward Dubai's accelerated approval timelines. VARA licensing offers streamlined pathways for perpetual futures and yield-generating service suites. The emirate's financial free zones concentrate custody infrastructure providers serving Gulf-based allocators.
South Korea
Retail flow aggregates on platforms integrating real-name banking verification for won-denominated settlement. The country's financial regulator mandates KYC-linked partnerships with commercial banks. Seoul-based exchanges compete through unified API access spanning centralized limit books and automated market maker pools.
Germany
Pension funds and endowment allocators demand MiCA-compliant passportable authorization for cross-border operations. BaFin licensing requirements shape custody architecture around insurance-grade segregation standards. Frankfurt's banking cluster hosts institutional service providers leveraging multi-party computation with hardware security module integration.
Cryptocurrency Exchanges Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators seek regulatory pre-clearance across multiple jurisdictions. The vendor base concentrates around three tiers: vertically integrated conglomerates with proprietary blockchain ecosystems, bank-anchored platforms with deep fiat rail integration, and derivatives specialists competing on matching engine latency. Tier-one players pursue M&A to acquire licensing moats. Tier-two operators prioritize geographic expansion through sandbox participation.
Within the vertically integrated tier, Binance leverages its proprietary chain infrastructure to reduce withdrawal friction. Coinbase Exchange anchors the bank-anchored category through US banking rail integration. OKX occupies the derivatives specialist position, exemplifying sub-second latency competition for high-frequency engagement.
| Leading Market Players |
|---|
| Binance |
| Bybit |
| Coinbase Exchange |
| OKX |
| Bitget |
| Gate.io |
| KuCoin |
| HTX |
| Kraken |
| Others |
Pricing and Supply Chain Analysis
Smart contract audit talent concentration in Eastern Europe and Southeast Asia compresses labor-cost differentials, widening pricing-tier spreads between institutional-grade custody providers and retail-focused platforms.
Pricing Analysis
Volume capture concentrates on maker-taker schedules with native token discounts, while margin extraction shifts toward subscription plans and staking yield sharing. Price differentiation hinges on regulatory certification tier—MiCA passportable authorization commands premium positioning—and API throughput allocation for algorithmic traders. Pricing pressure intensifies in retail spot trading as Layer-2 settlement cost compression erodes per-transaction revenue. High-frequency trading desks exhibit least price sensitivity, absorbing infrastructure premiums for sub-second latency, while retail arbitrageurs drive fee compression through smart order router fragmentation.
Supply Chain Analysis
Single-source vulnerability sits with Ethereum mainnet infrastructure providers during network congestion episodes, forcing migration to Arbitrum and Optimism sequencers. Geographic supply concentration centers on Singapore for MAS-licensed custody architecture, the United Arab Emirates for VARA-authorized derivatives infrastructure, and the United States for qualified custodian banking partnerships. Raw material dependencies encompass zero-knowledge proof verification hardware, cold storage hardware security modules, and fiat settlement banking rails. Supply chain risk manifests as regulatory restriction exposure when jurisdictions revoke operating licenses. Distribution runs through unified API gateways bridging centralized order books with automated market maker liquidity pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where compliance cost inflation forces sub-scale operators toward licensing partnerships or exit.
For Market Incumbents: Anticipate margin compression from Layer-2 settlement standardization by locking in exclusive banking partnerships for fiat on-ramps. Defensive positioning demands SOC 2 Type II attestation investment and insurance-backed segregation to capture pension fund allocations. Threat vectors include MiCA travel rule compliance infrastructure costs and emerging decentralized exchange protocol fragmentation.
For New Entrants and Emerging Players: The mid-market pricing gap between premium institutional custody and economy retail execution offers white-space entry through hybrid platform architecture. Target South Korean retail flow seeking real-name banking verification workarounds via non-custodial settlement rails. Go-to-market leverage concentrates on unified API access spanning centralized and decentralized liquidity venues.
For Investors and Strategic Acquirers: The window for entry favors VARA-licensed derivatives specialists with sub-second matching engine deployment. Long-term viability rests on jurisdictional licensing moats that survive regulatory convergence. Acquisition target archetype: MiCA-authorized platforms with passportable authorization structures. Signal to monitor: state-level US money transmitter license consolidation reducing compliance fragmentation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | MAS and VARA licensing experiments accelerate institutional on-ramp development through controlled testing. |
| Layer-2 Infrastructure Migration | Arbitrum and Optimism sequencer deployment slashes settlement costs for retail flow capture. |
| Qualified Custodian Partnership | SEC broker-dealer rule compliance rearchitects cold storage around banking-anchored segregation standards. |
| Derivatives Product Expansion | Perpetual futures and margin suites sustain high-frequency trader engagement through latency competition. |
| Staking Service Integration | Delegated proof-of-stake participation generates recurring non-volatile revenue streams beyond trading fees. |
Research Methodology
Multi-period observation of trading volume migration patterns, regulatory licensing timelines, and settlement cost compression anchored the trend analysis, supplemented by interviews with exchange compliance officers, MAS licensing consultants, institutional custody architects, and derivatives trading desk heads. Secondary validation drew from SEC enforcement actions, MiCA regulatory filings, Singapore MAS licensing registers, and VARA authorization disclosures. Bottom-up platform revenue modeling and top-down market sizing triangulated across centralized and decentralized venue data.
Segment-weighting applied platform type, revenue model, and user type dimensions across the projection horizon, with additional granularity on jurisdictional regulatory cluster. CAGRs derived from volume trajectory analysis and fee structure evolution. Industry-specific forecast inputs encompassed Layer-2 adoption curves and stablecoin settlement penetration rates.
Inputs from regulatory filing databases and exchange volume aggregators were available through the study window; gaps in private derivatives desk transaction data introduce uncertainty bands around institutional flow estimates. Forecasts reflect documented assumptions regarding MiCA implementation pacing and US state licensing convergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Digital Asset Transaction Market
Digital Assets and Cryptocurrency Finance
Digital Asset Trading Platform Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Global Non-Fungible Tokens Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market