
 Middle East Islamic Finance Market | 2026-2036
Middle East Islamic Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Islamic Finance Market Foresight
Corporate treasury demand is shifting toward Shariah-compliant working capital solutions as multinationals establish regional headquarters in Dubai and Riyadh. Qatar Islamic Bank leverages its sovereign-backed balance sheet to anchor project finance mandates across energy and infrastructure. Al Rajhi Bank sustains dominant retail deposit market share through its branch density in Saudi Arabia's secondary cities. Emirates Islamic Bank differentiates via digital onboarding platforms targeting UAE-based SME segments.
Middle East Islamic Finance denotes a system of banking and capital markets operating under Shariah principles that prohibit riba (interest), gharar (excessive uncertainty), and maysir (gambling), with instruments structured through asset-backed contracts like murabaha cost-plus financing and ijara lease arrangements. Its primary commercial purpose channels risk-sharing capital into tangible economic activity rather than speculative leverage. Sukuk issuance leads product type volume as sovereign borrowers from the Gulf Cooperation Council seek benchmark-size liquidity, while takaful operators compete for corporate property and casualty contracts against conventional reinsurance panels. Infrastructure investment strategy commands the deepest margin pools given long-dated tenor and government sponsorship, though commodity trading murabaha lines generate the highest transaction velocity among retail client segments.
Saudi Arabia's central bank (SAMA) and the UAE's central bank enforce Shariah governance standards that mandate independent board certification for all retail products, tightening market access for unlicensed entrants. The Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI) issues capital adequacy guidelines adopted across Bahrain, Qatar, and Oman, creating cross-border compliance interoperability. Stakeholders must monitor whether Malaysia's Islamic Financial Services Board standards gain traction in Gulf jurisdictions, as divergence would fragment product structuring conventions and raise dual-compliance costs for regionally active institutions.
Market Dynamics
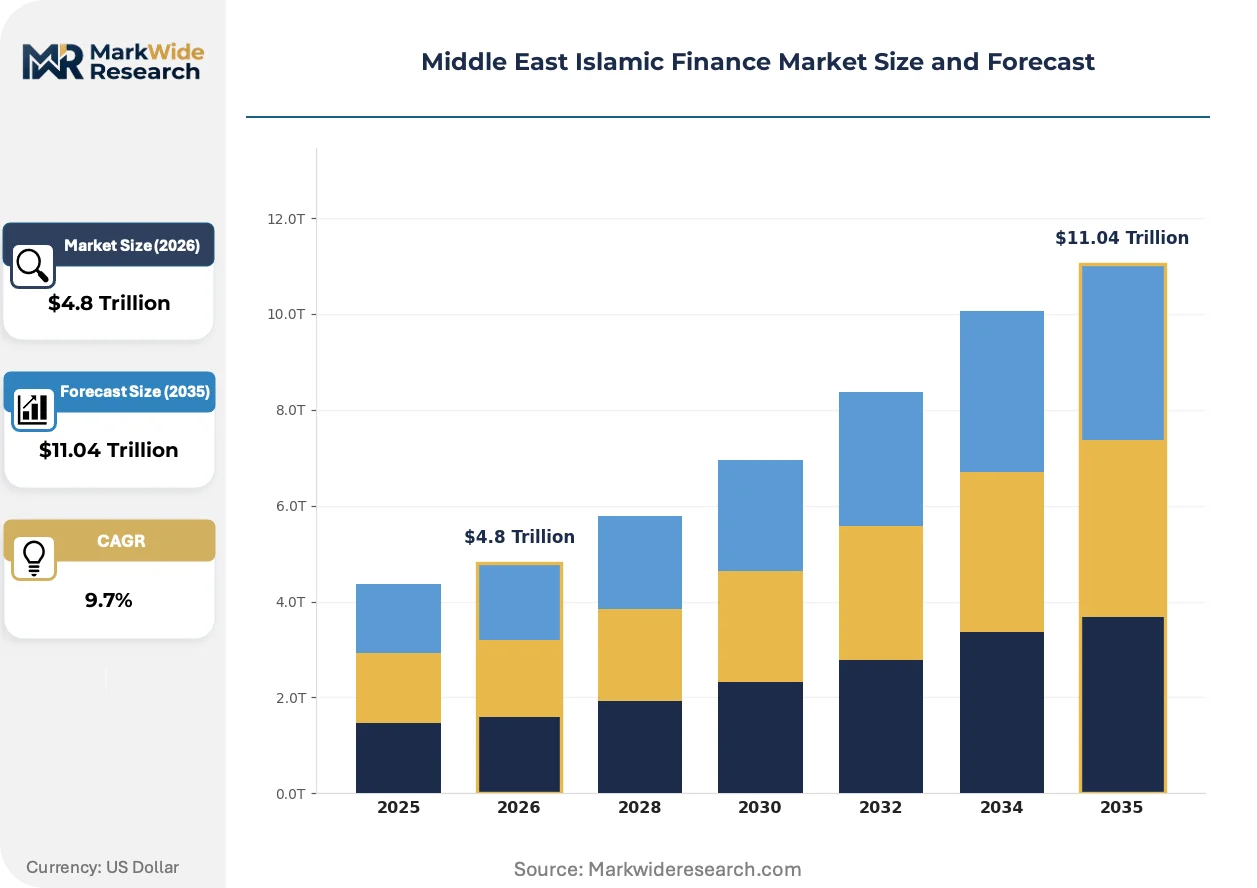
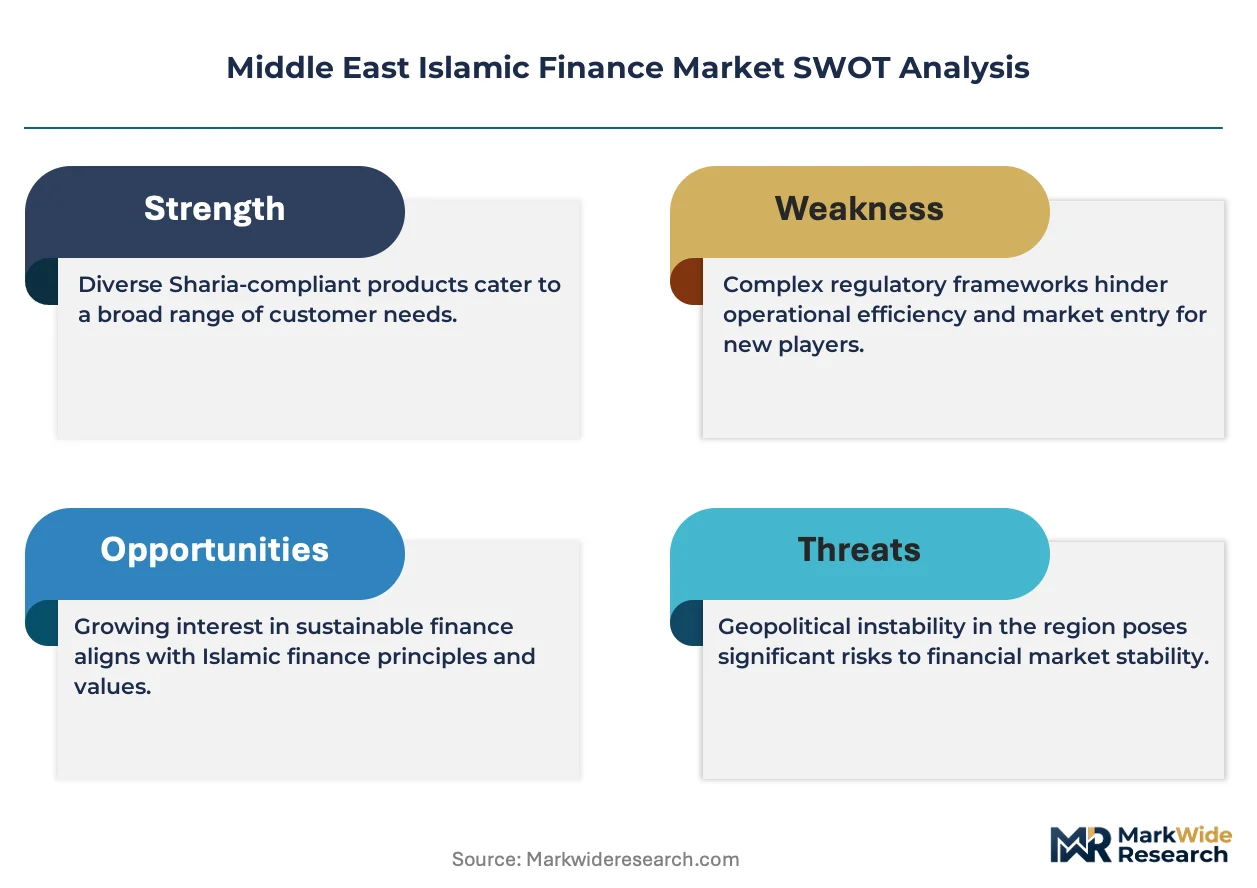
Central bank regulatory harmonization across Saudi Arabia, the United Arab Emirates, and Kuwait is compressing product approval timelines and forcing unlicensed entrants into consolidation or exit, restructuring competitive positioning around balance sheet scale and Shariah board certification quality.
Growth Catalysts
- AAOIFI Capital Standards:Cross-border compliance interoperability across Bahrain, Qatar, and Oman reduces dual-certification costs for regionally active institutions, accelerating product launches.
- Sovereign Sukuk Benchmarking:Gulf Cooperation Council government borrowers establish liquid reference curves, enabling private sector issuers to price off transparent yield levels.
- Digital Onboarding Infrastructure:API-linked identity verification platforms reduce account opening friction for UAE-based SME segments previously excluded from relationship-driven banking.
Market Restraints
- Shariah Scholar Scarcity:Limited pool of AAOIFI-certified scholars concentrates governance approval capacity at top-tier institutions, elongating product development cycles for mid-size banks.
- Commodity Murabaha Dependency:Short-dated, low-margin trade finance lines dominate retail transaction volumes, compressing net interest margins and limiting risk-adjusted return improvement.
- Conventional Reinsurance Substitution:Global takaful operators face capacity constraints on large property and casualty risks, ceding premium to conventional reinsurance panels and diluting Shariah purity.
Strategic Opportunities
- SME Working Capital White Space:Underpenetrated corporate treasury demand in Dubai and Riyadh creates openings for murabaha-based supply chain finance programs targeting multinational regional headquarters.
- Long-Dated Infrastructure Mandates:Government-sponsored energy and transport projects in Qatar and Saudi Arabia generate deep-margin pools through ijara and istisna structures with 15-25 year tenors.
- Malaysia-IFSB Convergence:Adoption of Islamic Financial Services Board standards in select Gulf jurisdictions would create first-mover advantage for institutions pre-structured for dual-framework compliance.
Industry Challenges
- Legacy Core System Integration:Batch-oriented conventional banking platforms require expensive middleware development to support real-time profit-rate calculations and Shariah-compliant accounting segregation.
- Talent Acquisition Bottlenecks:Shortage of professionals combining Islamic jurisprudence training with quantitative finance skills constrains product structuring and risk management function scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Islamic Finance Market |
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $11.04 Trillion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murabaha, Ijara, Sukuk, Takaful Investment Strategy: Equity Financing, Real Estate, Commodity Trading, Infrastructure Client Type: Retail Investors, Institutional Investors, Corporations, SMEs Transaction Size: Small, Medium, Large, Mega |
| Companies Covered | Qatar Islamic Bank, Abu Dhabi Islamic Bank, Al Rajhi Bank, Ahli United Bank, Emirates Islamic Bank, Kuwait Finance House, Alinma Bank, Bank Nizwa, Dubai Islamic Bank, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Islamic Finance Market Shifts & Advancements
Technology deployment is compressing distribution economics while regulatory convergence pressures fragment product structuring conventions, creating divergence between digital-first retail platforms and relationship-heavy institutional channels.
Blockchain-based smart contract infrastructure is overtaking manual Sukuk settlement processes. Secondary market makers in Dubai and Bahrain are adopting tokenized certificate registries to compress settlement cycles from T+2 to near-instantaneous. This compression is overtaking traditional custodian fee structures and enabling fractional retail participation in previously institutional-only issuances.
SAMA's Shariah governance standards mandate independent board certification for all retail products, tightening enforcement timelines and raising documentation requirements. UAE central bank parallel rules create compliance interoperability pressures for institutions operating across both jurisdictions. Retail product approval departments are responding by centralizing Shariah oversight functions in Riyadh and Abu Dhabi hubs.
Corporate treasury procurement of working capital solutions is rotating away from relationship-driven branch networks toward API-integrated platform access. Multinational regional headquarters in Dubai International Financial Centre now require real-time liquidity visibility across multicurrency Shariah-compliant pools. This shift concentrates vendor selection authority with group treasury technology committees rather than local relationship managers.
Middle East Islamic Finance Market Segmentation
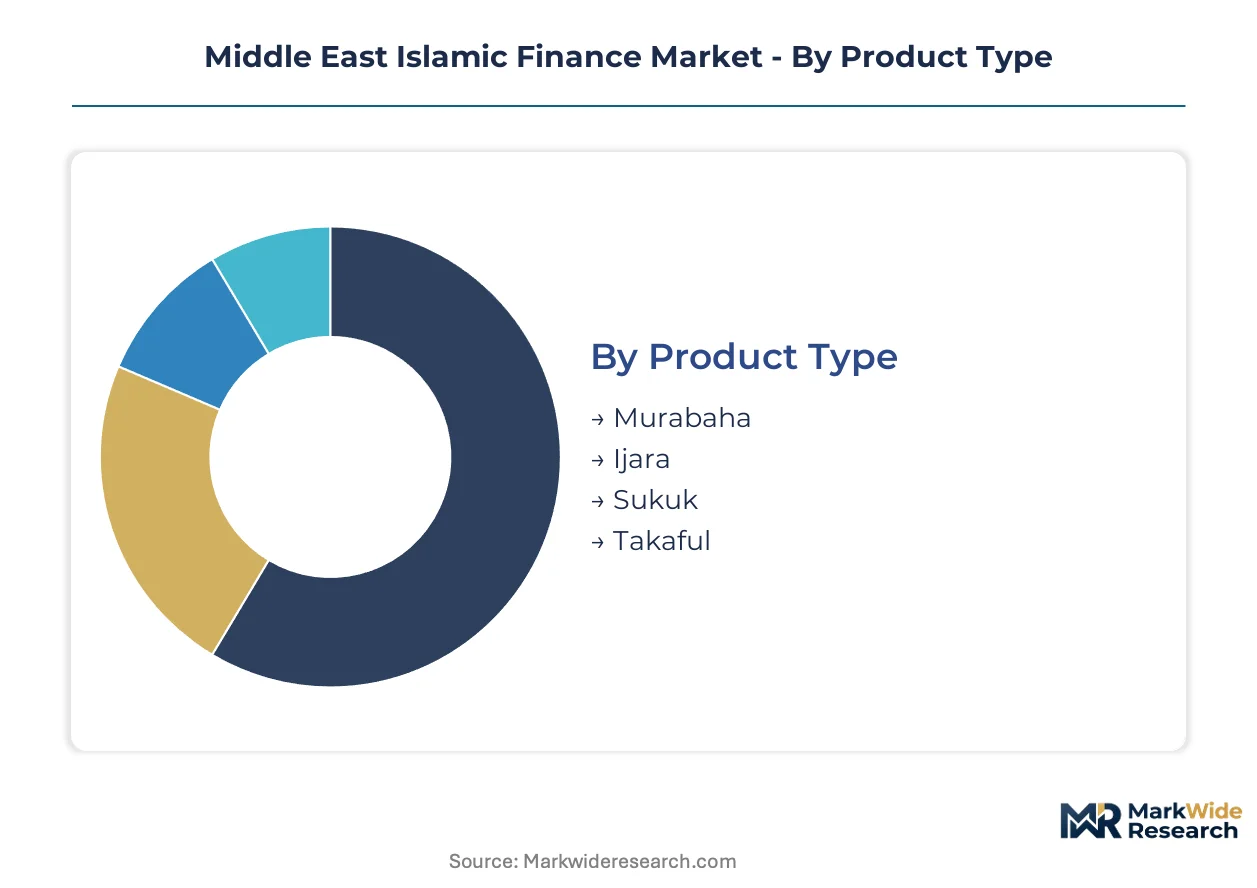
Islamic finance instruments require precise structural alignment with Shariah principles, making product taxonomy critical for regulatory compliance and investor matching. Each segment category reflects distinct risk-sharing mechanisms, tenor profiles, and governance requirements that determine institutional positioning.
Product Type:
Replacement cycles for legacy conventional instruments are accelerating Shariah-compliant product adoption across retail and wholesale channels.
- Murabaha:Cost-plus financing contracts disclose profit margins upfront, eliminating interest rate ambiguity. Demand concentrates in Saudi Arabia's secondary cities where Al Rajhi Bank's branch density captures working capital needs of trading families and small merchants.
- Sukuk:Asset-backed certificates represent beneficial ownership in tangible pools, structured through special purpose vehicles to ensure bankruptcy remoteness. GCC sovereign borrowers establish benchmark curves that enable private sector pricing transparency, with secondary market liquidity deepening in Dubai and Bahrain.
- Ijara:Lease-based arrangements transfer asset use rights without title conveyance, common in vehicle and equipment financing.
- Takaful:Mutual risk-sharing pools replace conventional insurance through participant contributions and surplus distribution.
Volume placements concentrate in Murabaha; the faster expansion belongs to Sukuk.
Investment Strategy:
Cost tier differentiation separates sovereign-backed mandates from privately sponsored transactions, with fee structures reflecting credit enhancement depth.
- Infrastructure:Long-dated project finance through istisna and ijara structures spans 15-25 year tenors, generating the deepest margin pools. Qatar and Saudi Arabia government-sponsored energy and transport projects anchor this segment, with Qatar Islamic Bank leveraging sovereign balance sheet backing to secure lead arranger roles.
- Real Estate:Diminishing musharaka and ijara muntahia bittamleek structures finance commercial and residential development. Dubai's property market concentrates demand from regional headquarters establishing physical presence, with Shariah-compliant REITs gaining traction among UAE-based institutional allocators.
- Equity Financing:Mudaraba and musharaka partnerships deploy risk capital into operating ventures, screened for Shariah compliance by independent boards.
- Commodity Trading:Short-dated murabaha lines finance metals and agricultural flows, generating high transaction velocity at compressed margins.
Fee income concentrates in Infrastructure; the steepest expansion trajectory is occurring in Real Estate.
Client Type:
Customer sophistication determines product complexity tolerance, with retail segments requiring standardized documentation and institutional clients demanding bespoke structuring.
- Retail Investors:Individual account holders access simplified murabaha deposits and takaful protection through branch and digital channels. Emirates Islamic Bank's API-linked onboarding platforms target this segment in UAE SME clusters previously excluded from relationship-driven banking.
- Corporations:Multinational regional headquarters in Dubai International Financial Centre and Riyadh drive demand for multicurrency Shariah-compliant liquidity pools and supply chain finance programs. Treasury technology committees now control vendor selection, displacing local relationship manager authority.
- Institutional Investors:Sovereign wealth funds and pension allocators deploy capital through benchmark Sukuk and managed funds.
- SMEs:Mid-size enterprises represent underpenetrated demand for working capital solutions, with murabaha-based supply chain programs creating white space opportunities.
Deposit volume concentrates in Retail Investors; corporate treasury mandates are climbing the fastest.
Transaction Size:
Deal flow distribution reflects the bifurcation between high-velocity retail transactions and lumpy institutional mandates.
- Large:Transactions between defined thresholds attract diversified bank syndicates and standard documentation templates. Saudi Arabia's Riyadh financial district concentrates this flow as sovereign wealth funds deploy capital through Shariah-compliant instruments.
- Mega:Benchmark-size issuances and project mandates require cross-border syndication and multi-jurisdictional Shariah certification. AAOIFI capital standards enable compliance interoperability across Bahrain, Qatar, and Oman, reducing dual-certification costs for arrangers.
- Small:Individual account transactions and micro-takaful policies process through automated platforms.
- Medium:Corporate working capital lines and mid-size Sukuk issuances occupy the pricing gap between retail and institutional benchmarks.
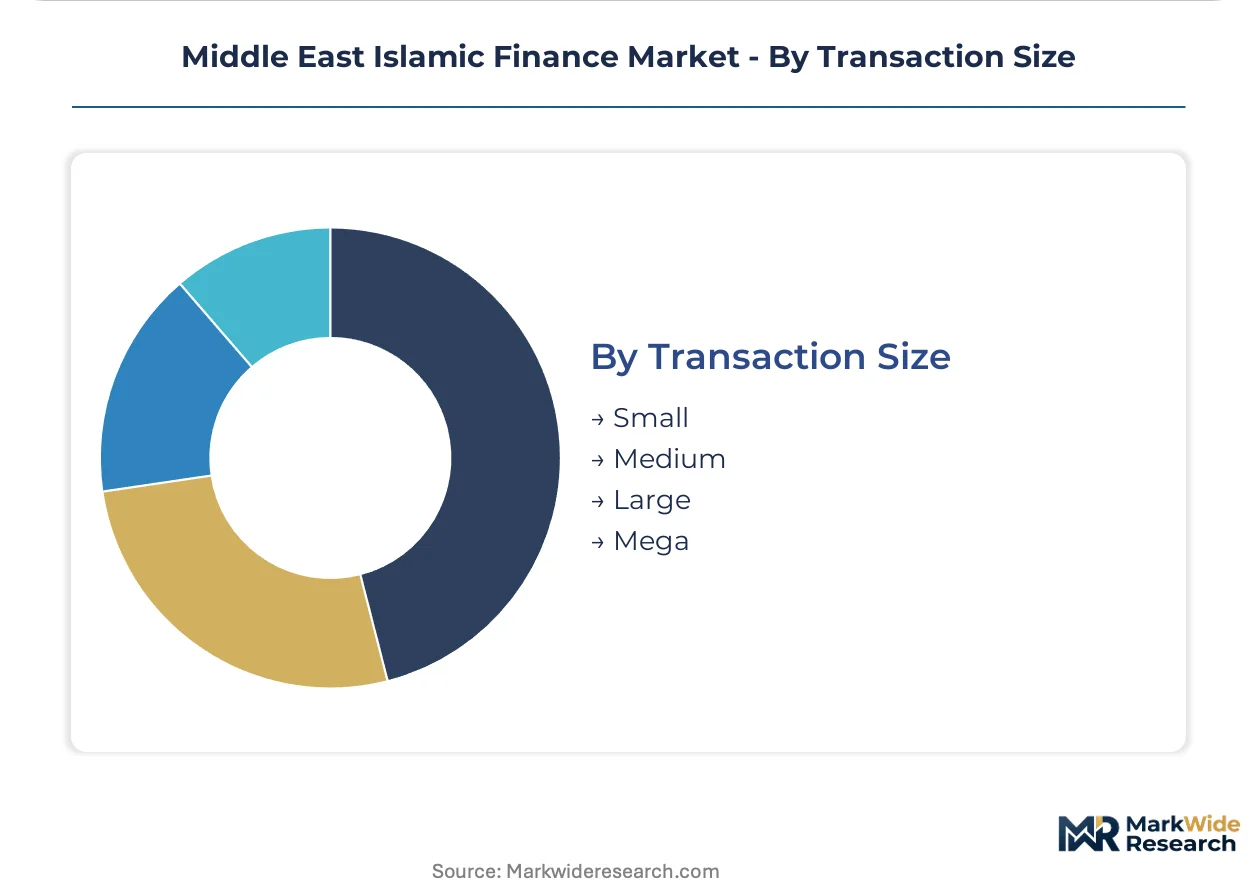
Deal count concentrates in Small; value growth is gaining share fastest in Mega transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdullah Financial District in Riyadh anchors sovereign wealth fund deployment through Shariah-compliant instruments, concentrating liquidity formation across Gulf Cooperation Council capital markets.
Saudi Arabia
SAMA's Shariah governance standards mandate independent board certification for retail products, tightening market access timelines. The Riyadh financial district hosts sovereign wealth fund treasury operations deploying capital through benchmark Sukuk issuances. Secondary cities including Jeddah and Dammam sustain Al Rajhi Bank's branch density for murabaha working capital capture.
United Arab Emirates
Dubai International Financial Centre corporate treasuries demand API-integrated multicurrency Shariah-compliant liquidity pools. The UAE central bank enforces parallel Shariah governance rules creating compliance interoperability pressures with Saudi Arabia. Emirates Islamic Bank targets SME segments through digital onboarding platforms in Dubai's technology clusters.
Qatar
Qatar Islamic Bank leverages sovereign-backed balance sheets to anchor energy and infrastructure project finance mandates. Long-dated istisna and ijara structures spanning 15-25 years generate deep-margin pools for government-sponsored transport projects. The Doha financial corridor concentrates institutional Sukuk distribution capacity.
Kuwait
Kuwait Finance House sustains retail deposit dominance through relationship-driven branch networks in Kuwait City's commercial districts. Central bank regulatory harmonization with Saudi Arabia and the UAE compresses cross-border product approval timelines. The Kuwait Stock Exchange hosts benchmark sovereign Sukuk listings establishing regional yield curves.
Bahrain
AAOIFI capital adequacy guidelines adopted across Bahrain create compliance interoperability with Qatar and Oman. Manama's financial harbor hosts secondary market makers adopting tokenized Sukuk settlement infrastructure. The Bahrain Islamic Bank cluster benefits from reduced dual-certification costs for regionally active institutions.
Middle East Islamic Finance Market Competitive Landscape
Top-tier vendors anchor sovereign-backed balance sheet scale, while mid-tier specialists compete on Shariah board certification quality and digital distribution reach. The vendor base stratifies around three archetypes: full-service universal banks with government sponsorship, retail-focused deposit aggregators with dense branch networks, and digital-first challengers targeting SME onboarding friction. Consolidation pressures favor institutions with AAOIFI-certified governance capacity and legacy core system modernization budgets. Competitive moves concentrate on strategic partnerships for technology infrastructure and selective acquisitions of unlicensed entrants facing regulatory exit pressures.
Within the sovereign-sponsored tier, Qatar Islamic Bank and Al Rajhi Bank exemplify balance sheet scale advantages. Emirates Islamic Bank occupies a position representing digital-first challenger archetypes targeting API-integrated treasury platforms. Dubai Islamic Bank and Abu Dhabi Islamic Bank sit within the full-service universal category with cross-border GCC operations. Kuwait Finance House and Alinma Bank represent geographically concentrated deposit aggregators with secondary city penetration.
| Leading Market Players |
|---|
| Qatar Islamic Bank |
| Abu Dhabi Islamic Bank |
| Al Rajhi Bank |
| Ahli United Bank |
| Emirates Islamic Bank |
| Kuwait Finance House |
| Alinma Bank |
| Bank Nizwa |
| Dubai Islamic Bank |
| Others |
Supply & Pricing Matrix
AAOIFI-certified Shariah scholars concentrate in Bahrain and Saudi Arabia, creating labor-cost differentials that widen pricing-tier spreads between premium-certified and standard-tier Islamic finance products.
Pricing Analysis
Short lead-time premiums apply to expedited Shariah board certification and fast-track Sukuk structuring, while spot inventory discounts emerge in commoditized murabaha commodity trading lines. Project-based pricing dominates infrastructure mandates through istisna and ijara structures, with price differentiation driven by certification grade (AAOIFI versus national standards) and volume scale (sovereign benchmark versus mid-size corporate). Pricing pressure stems from commodity murabaha margin compression as retail transaction volumes concentrate in low-yield trade finance. SME segments exhibit highest price sensitivity due to working capital constraints, while sovereign wealth funds demonstrate lowest sensitivity given long-dated liability matching priorities.
Supply Chain Analysis
Freight and logistics costs for physical commodity backing concentrate supply chain leverage in Saudi Arabia, the United Arab Emirates, and Bahrain as primary documentation and custody hubs. Raw material dependencies center on metals (copper, aluminum) and agricultural commodities (palm oil, wheat) underlying murabaha contracts. Single-source vulnerability characterizes Shariah scholar capacity concentrated at AAOIFI-certified institutions in Manama and Riyadh. Distribution runs through relationship-driven branch networks for retail products and API-integrated treasury platforms for corporate segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-based smart contract infrastructure is displacing manual Sukuk settlement and legacy core banking platforms, compressing distribution economics while fragmenting competitive positioning between digital-first and relationship-heavy channels.
For Market Incumbents: Cement AAOIFI governance certification quality as a defensive moat against unlicensed entrants facing regulatory exit pressures from SAMA and UAE central bank harmonization. Prioritize legacy core system modernization budgets to support real-time profit-rate calculations, while acquiring mid-tier specialists with pre-built middleware to accelerate technology deployment timelines. For New Entrants and Emerging Players: Capture SME working capital white space in Dubai International Financial Centre and Riyadh through API-integrated murabaha supply chain platforms, bypassing incumbent relationship-driven branch density. Target multinational corporate treasury mandates rotating toward real-time liquidity visibility as the most penetrable segment, leveraging digital onboarding friction reduction as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with dual-framework compliant institutions given Malaysia-IFSB convergence catalysts creating first-mover advantage in select Gulf jurisdictions. Long-term viability over a multi-year window favors acquisition targets with pre-structured AAOIFI and IFSB governance capacity, balanced by tokenized settlement infrastructure deployment. Monitor Shariah scholar scarcity resolution as the signal to watch for product development cycle normalization and margin expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Shariah Board Certification Investment | AAOIFI-certified governance capacity tightens market access timelines under SAMA enforcement standards. |
| Legacy Core System Modernization | Real-time profit-rate calculation middleware displaces batch-oriented conventional banking platforms. |
| Blockchain Settlement Infrastructure | Tokenized Sukuk registries compress settlement cycles from T+2 to near-instantaneous in Dubai and Bahrain. |
| SME Digital Platform Launch | API-linked onboarding captures corporate treasury demand rotating away from relationship-driven networks. |
| Dual-Framework Compliance Structure | Pre-built AAOIFI-IFSB interoperability reduces certification costs for Malaysia-Gulf convergence scenarios. |
Research Methodology
Central bank regulatory filings, Sukuk issuance databases, and AAOIFI capital adequacy guidelines formed the secondary backbone, cross-referenced against primary interviews with Shariah board scholars, Islamic bank treasury heads, and corporate treasury officers at multinational regional headquarters. SAMA and UAE central bank enforcement timelines provided regulatory validation points. Bottom-up transaction volume aggregation and top-down macroeconomic factor weighting enabled triangulation across data sources.
Historical trendline analysis traced murabaha margin compression and Sukuk yield curve formation across the projection horizon, with segmentation modeling across product type (murabaha, Sukuk, ijara, takaful), investment strategy (infrastructure, real estate, commodity trading), and client sophistication tier. CAGRs derived from sovereign wealth fund deployment velocity and retail deposit growth trajectories, incorporating Shariah scholar capacity constraints and digital onboarding adoption curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between AAOIFI and IFSB standards, Shariah scholar pipeline expansion rates, and blockchain settlement infrastructure adoption velocity. Forecasts reflect documented assumptions about sovereign project finance sponsorship continuity and commodity price stability underlying murabaha structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Currency Management Market
Financial Services
Debt Settlement Solution Market
Financial Services
Smart Finance Services Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
India Security Brokerage Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Banknote Counters Market
Financial Services
Financial Advisory Services Market
Financial Services
Capital Restructuring Services Market
Financial Services
South Korea Trade Finance Market
Financial Services
India Payroll Services Market
Financial Services
Online Investment Platform Market
Financial Services
Global Temporary Labor Market
Financial Services
Multivendor ATM Software Market
Financial Services
Treasury Management Market
Financial Services
China Supply Chain Financing Market