
 Source to Pay Market | 2026-2036
Source to Pay Market Size, Share, and Industry Trends Forecast 2026-2036
Source to Pay Market Analytics
API-first architectures are rebalancing integration economics across the Source to Pay landscape. SAP leverages its ERP installed base to anchor enterprise procurement workflows. Coupa Software specializes in spend optimization analytics for mid-market buyers. Jaggaer sustains its position in complex direct-material sourcing for manufacturing clients.
Source to Pay denotes an integrated procurement technology suite spanning requisitioning, supplier discovery, contract execution, purchase order management, invoice processing, and payment settlement through unified data models and automated workflow engines. The primary commercial purpose centers on reducing procurement cycle times, enforcing compliance policies, and capturing spend visibility across decentralized purchasing operations. Cloud-based deployment leads segment momentum as enterprises retire legacy on-premises installations, while supplier management solutions capture disproportionate R&D investment due to third-party risk amplification. Invoice management remains the most mature solution category with established OCR and machine-learning extraction protocols, though contract management shows accelerating attach rates as CLM modules integrate natively into broader suites.
The EU AI Act imposes algorithmic transparency obligations on automated procurement decision systems, compelling vendors to document training data provenance and audit trails. GDPR cross-border data transfer rules constrain cloud-hosted supplier databases, particularly when sub-processors operate outside European Economic Area jurisdictions. HIPAA in the United States mandates access controls and audit logging for healthcare procurement platforms handling protected health information in supplier contracts. Stakeholders must monitor evolving AI procurement guidelines from the European Commission and assess whether their current Source to Pay configurations support forthcoming explainability requirements.
Market Dynamics
API-first architectures are compressing integration economics and forcing vendors to abandon monolithic suite approaches in favor of composable procurement stacks that interoperate through standardized data exchange protocols.
Growth Catalysts
- EU AI Act Compliance Mandates:Algorithmic transparency requirements for automated procurement decisions are compelling enterprises to upgrade legacy systems, creating replacement demand across European healthcare and public sector buyers.
- Healthcare Cloud Migration:HIPAA-covered entities in the United States are accelerating SaaS procurement platform adoption to satisfy audit logging and access control mandates for supplier contracts containing protected health information.
- Spend Analytics Maturation:Machine-learning classification of indirect spend is delivering measurable working capital improvements, pulling mid-market manufacturing firms into integrated suite deployments.
Market Restraints
- GDPR Cross-Border Data Friction:Cloud-hosted supplier databases face operational constraints when sub-processors operate outside European Economic Area jurisdictions, complicating multi-country rollout timelines.
- Legacy ERP Lock-In:Decades of customized on-premises procurement workflows create switching costs that delay cloud migration decisions even where ROI cases are demonstrable.
- Supplier Data Quality Deficits:Inconsistent taxonomy standards across vendor master databases degrade spend classification accuracy, limiting the actionable output of analytics investments.
Strategic Opportunities
- Embedded Finance Convergence:Integration of supply chain finance and dynamic discounting capabilities within procurement workflows is unlocking new revenue streams for platform vendors serving cash-constrained supplier bases.
- Scope 3 Emissions Tracking:CSRD-mandated carbon disclosure requirements are creating attach-rate opportunities for supplier sustainability scoring modules within existing contract management deployments.
- Mid-Market Suite Consolidation:Fragmented point-solution stacks among sub-$500M revenue manufacturers present white space for unified Source to Pay platforms with pre-configured industry templates.
Industry Challenges
- Procurement-IT Skill Divergence:Hybrid roles combining category management expertise with API configuration and data engineering capabilities remain scarce, constraining self-service platform utilization.
- Multi-Cloud Integration Complexity:Enterprises operating across AWS, Azure, and Google Cloud environments face authentication and data synchronization hurdles when deploying unified procurement stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Source to Pay Market |
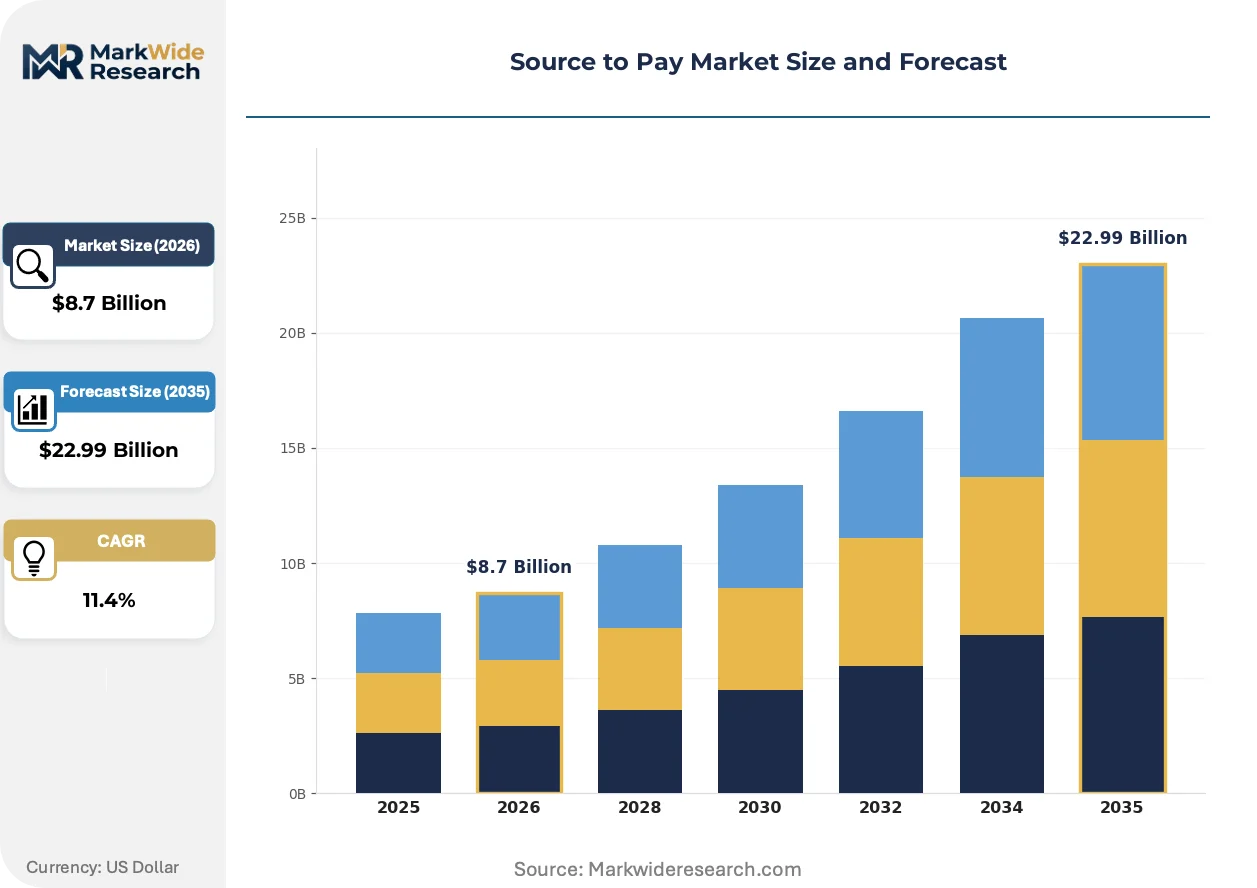
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Procurement, Invoice Management, Contract Management, Supplier Management Deployment: On-Premises, Cloud-Based, Hybrid, Software as a Service End User: Manufacturers, Retailers, Healthcare Providers, Financial Institutions Customer Type: Small Enterprises, Medium Enterprises, Large Enterprises, Public Sector |
| Companies Covered | Zip, Jaggaer, SAP, Tradeshift, Basware, Oracle, Ivalua, GEP, Coupa Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Source to Pay Market Evolving Landscape
Intelligent document processing and embedded compliance engines are redefining the boundary between procurement operations and financial controls, collapsing historically separate workflow stages into continuous automated pipelines.
Large language models applied to contract clause extraction and risk scoring are consolidating vendor evaluation and negotiation preparation into single-session workflows. Healthcare systems and financial services buyers in Germany and the United Kingdom are deploying these tools at scale, compressing sourcing cycle times from weeks to days and reducing reliance on external legal review for standard terms.
REACH chemical substance tracking requirements and the EU AI Act's algorithmic accountability mandates are forcing procurement platforms to embed audit trails directly into supplier onboarding workflows. Manufacturers sourcing raw materials from non-EU jurisdictions must now document chain-of-custody data within their Source to Pay systems, with automotive and pharmaceutical verticals investing most heavily in compliance module integration.
Centralized procurement functions are ceding control to distributed business unit buyers equipped with guided buying interfaces and pre-approved supplier marketplaces. This pattern is most pronounced in professional services and technology sectors across France and the Netherlands, where category managers now configure guardrails rather than execute transactions, shifting organizational investment from headcount to platform configuration.
Source to Pay Market Segmentation
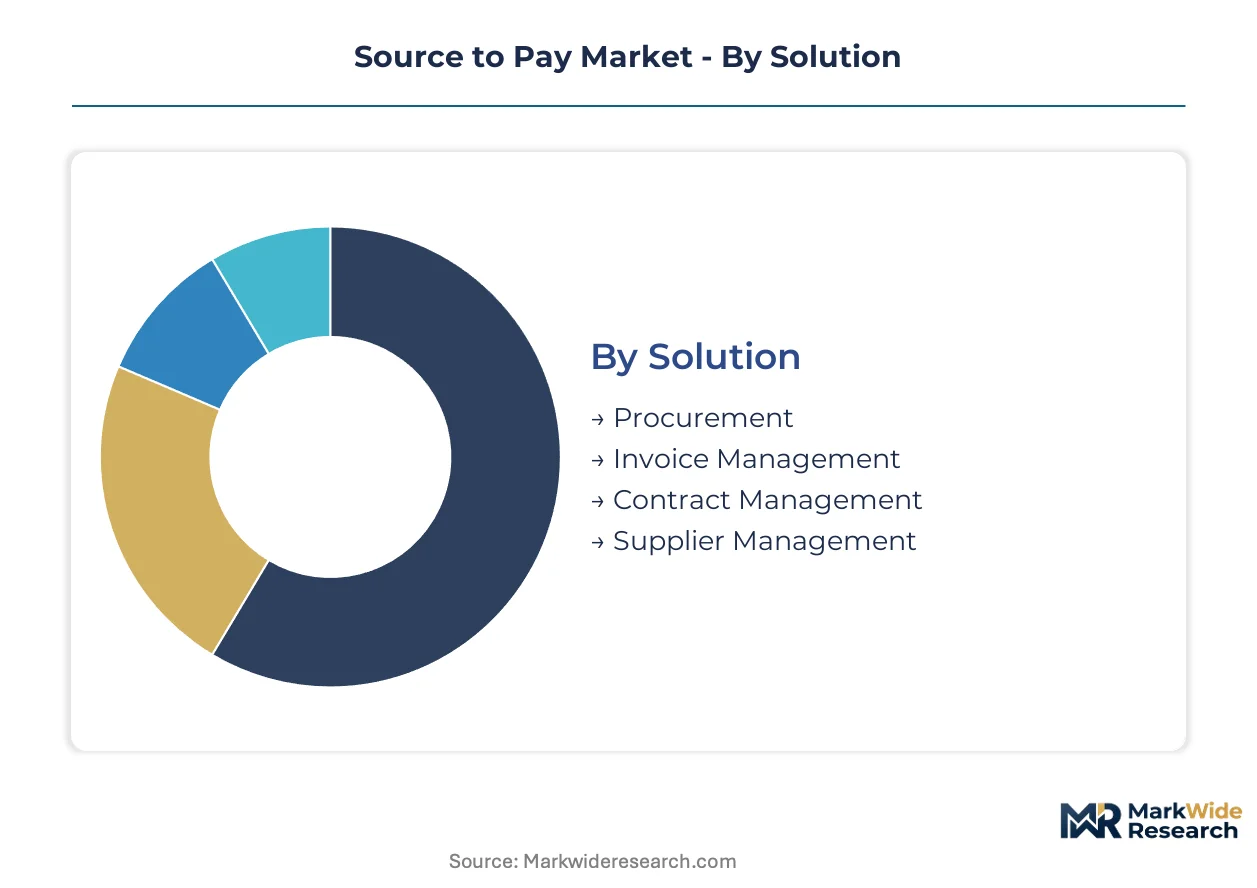
Source to Pay segmentation reveals how procurement technology value pools split between mature operational modules and emerging compliance-driven capabilities. Deployment architecture and customer scale determine pricing elasticity and implementation complexity more than any other dimension.
Solution:
Volume concentrates in transactional modules while premium capture shifts toward risk and relationship management layers.
- Procurement:Core requisition-to-purchase order workflow engine with catalog management and guided buying interfaces. Demand clusters among German automotive suppliers modernizing legacy SAP environments under EU AI Act procurement transparency mandates.
- Invoice Management:Optical character recognition and machine-learning extraction protocols for accounts payable automation. French healthcare networks deploy these systems to satisfy GDPR audit logging requirements for supplier payment data.
- Contract Management:Clause extraction and obligation tracking with native CLM suite integration.
- Supplier Management:Third-party risk scoring and sustainability assessment modules.
Today's leader: Invoice Management. Tomorrow's challenger: Supplier Management.
Deployment:
Customer risk tolerance and data sovereignty requirements fragment the technical architecture landscape.
- Cloud-Based:Multi-tenant SaaS infrastructure with API-first integration frameworks. United Kingdom financial institutions favor this model to satisfy FCA operational resilience guidelines while avoiding capital-intensive data center commitments.
- Software as a Service:Vendor-managed subscription delivery with pre-configured compliance templates. Mid-market manufacturers in France adopt these offerings to compress implementation timelines from months to weeks.
- On-Premises:Self-hosted installations retaining full data custody for classified procurement activities.
- Hybrid:Split architecture separating sensitive supplier data on-premises from transactional workflows in cloud environments.
Cloud-Based deployments currently dominate new bookings. Hybrid architectures are gaining share fastest among defense and pharmaceutical buyers.
End User:
Industry-specific regulatory exposure determines module attach rates and implementation priorities.
- Healthcare Providers:HIPAA-mandated access controls and PHI handling in supplier contracts. United States hospital systems drive demand for audit-logging capabilities that satisfy OCR enforcement priorities.
- Manufacturers:Direct material sourcing with REACH substance tracking and CSRD carbon disclosure integration. German automotive OEMs require chain-of-custody documentation for non-EU raw material suppliers.
- Retailers:High-volume indirect spend classification and supplier diversity program management.
- Financial Institutions:Counterparty risk monitoring and regulatory procurement compliance.
Healthcare Providers anchor current spending. Manufacturers represent the steepest expansion trajectory as Scope 3 emissions tracking mandates proliferate.
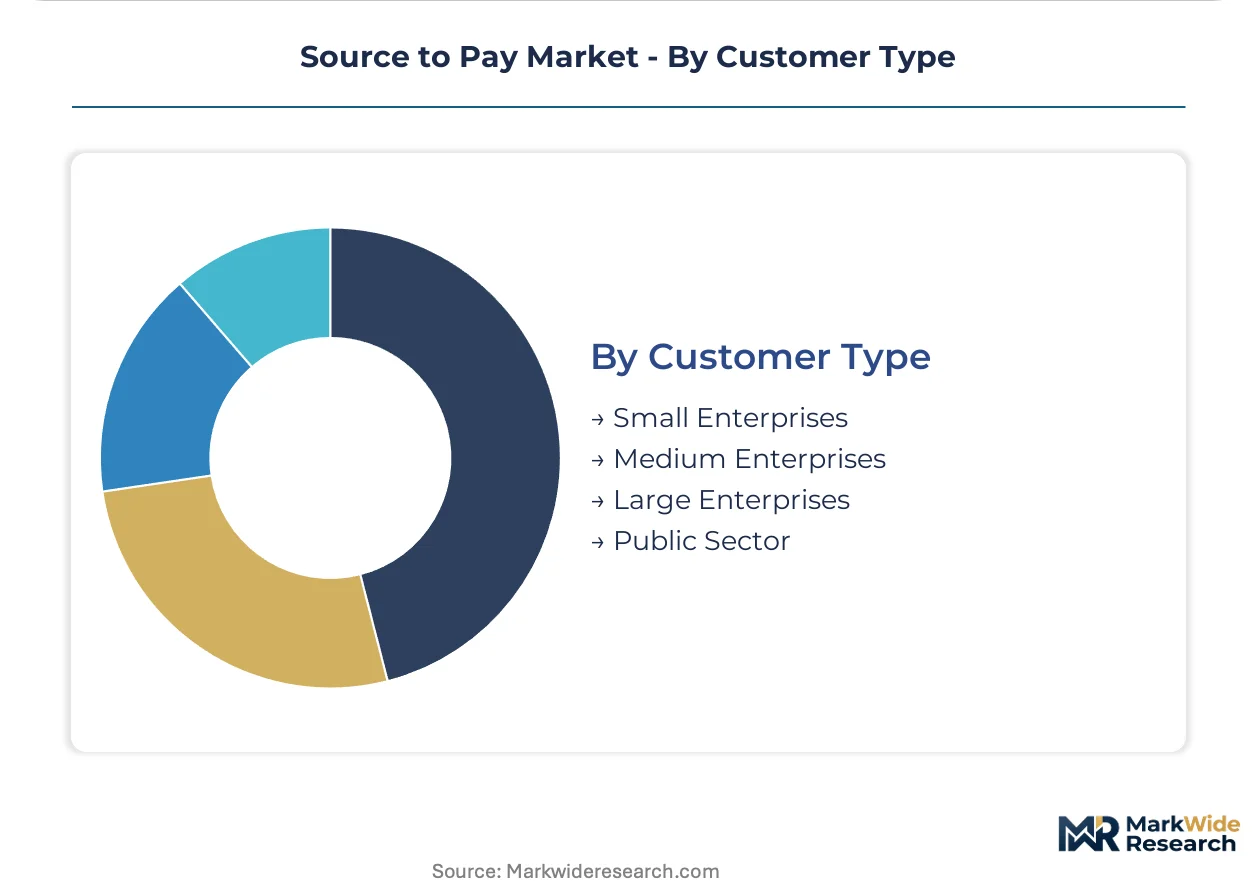
Customer Type:
Organizational scale dictates solution configurability requirements and sales channel economics.
- Large Enterprises:Global template deployment with multi-entity consolidation and advanced analytics. These buyers command dedicated customer success resources and custom integration roadmaps.
- Public Sector:Open procurement transparency and algorithmic accountability under EU AI Act and national public finance regulations. French and British government buyers mandate explainable automated sourcing decisions.
- Medium Enterprises:Pre-configured industry templates with rapid deployment methodologies.
- Small Enterprises:Lightweight requisitioning and payment automation with minimal IT overhead.
Large Enterprises consume the deepest functionality. Public Sector buyers are expanding most quickly as algorithmic procurement regulations harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters anchor procurement technology demand as EU AI Act compliance deadlines approach. Healthcare networks in France and the United Kingdom accelerate cloud migration to satisfy audit logging mandates. Manufacturing hubs across Poland and the Netherlands invest in supplier sustainability tracking modules.
Germany
Automotive OEMs in Stuttgart and Munich drive demand for chain-of-custody documentation systems. The EU AI Act imposes algorithmic transparency obligations on automated sourcing decisions for public sector buyers. Bavarian pharmaceutical manufacturers embed REACH substance tracking into supplier onboarding workflows to satisfy ECHA requirements.
France
Paris-based healthcare networks deploy invoice management systems to satisfy CNIL audit logging requirements for supplier payment data. The country's national pharmaceutical regulator enforces strict data residency rules for cloud-hosted procurement platforms. Lyon and Grenoble manufacturing clusters adopt pre-configured SaaS templates to compress implementation timelines.
United Kingdom
London financial institutions favor multi-tenant cloud infrastructure to satisfy FCA operational resilience guidelines. GDPR cross-border data transfer rules constrain supplier database architectures when sub-processors operate outside European Economic Area jurisdictions. Manchester and Birmingham healthcare systems invest in HIPAA-equivalent access controls for PHI-containing supplier contracts.
Netherlands
Amsterdam and Rotterdam professional services firms equip distributed buyers with guided buying interfaces and pre-approved supplier marketplaces. The EU Green Deal drives demand for Scope 3 emissions tracking modules among Eindhoven-based electronics manufacturers. Dutch retailers prioritize supplier diversity program management within high-volume indirect spend classification systems.
Poland
Warsaw and Krakow manufacturing hubs attract mid-market suite consolidation investments from sub-$500M revenue producers. The country's central bank guidelines shape procurement transparency requirements for financial institutions. Silesian automotive suppliers modernize legacy SAP environments under pressure from German OEM compliance mandates.
Source to Pay Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and compliance specialization. The vendor landscape splits between ERP-anchored incumbents and API-native challengers. Three archetypes dominate: suite consolidators extending procurement workflows from financial systems, spend analytics specialists targeting mid-market optimization, and compliance-focused platforms embedding regulatory engines. M&A activity concentrates on machine-learning document processing capabilities, while strategic partnerships link procurement platforms with supply chain finance providers.
Within the enterprise suite tier, SAP and Oracle occupy positions as ERP-anchored incumbents with extensive installed bases. Coupa Software sits within the spend optimization archetype, representing mid-market buyers seeking unified platforms. Jaggaer exemplifies the direct-material sourcing specialist, serving manufacturing clients with complex supplier relationship requirements.
| Leading Market Players |
|---|
| Zip |
| Jaggaer |
| SAP |
| Tradeshift |
| Basware |
| Oracle |
| Ivalua |
| GEP |
| Coupa Software |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure cost indices cascade through Source to Pay vendor pricing tiers, compressing margins for SaaS providers while amplifying differentiation premiums for compliance-embedded suites serving EU AI Act-bound buyers in Germany and France.
Pricing Analysis
Input-cost pass-through from hyperscaler compute and storage fees reshapes vendor economics, forcing subscription pricing stratification across premium, standard, and economy tiers. Price differentiation hinges on API call volume thresholds and embedded compliance module depth, with EU AI Act-ready configurations commanding substantial premiums over baseline requisitioning tools. Pricing pressure stems from mid-market buyers consolidating fragmented point solutions onto unified platforms. Small enterprises exhibit acute price sensitivity, while public sector buyers in France and the United Kingdom prioritize audit-trail capabilities over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel Source to Pay vendors to qualify multiple hyperscaler partners, reducing single-platform dependency risks. Supply concentrates in the United States, Ireland, and Germany for primary data center capacity, with secondary processing nodes emerging in Poland and the Netherlands. Raw material dependencies span semiconductor components for edge appliances, optical sensors for invoice scanning hardware, and specialized GPUs for machine-learning document processing. Tariff exposure on Chinese-manufactured scanning equipment threatens hardware-assisted capture margins. Distribution runs through direct enterprise sales forces and systems integrator partnerships, with channel partners in the United Kingdom and Germany handling mid-market deployment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Source to Pay rests on cloud infrastructure cost optimization and compliance-module premiumization as EU AI Act deadlines concentrate buyer willingness-to-pay for algorithmic transparency tooling.
For Market Incumbents: Acquire machine-learning document processing capabilities to close capability gaps against API-native challengers. Consolidate supplier risk data assets through targeted tuck-in acquisitions of sustainability scoring specialists. Deepen vertical integration into embedded finance modules, capturing supply chain finance revenue streams that point-solution vendors cannot replicate. Defend against ERP-anchored competitors by pre-building SAP and Oracle connector libraries that compress customer migration timelines. For New Entrants and Emerging Players: Begin with mid-market manufacturers in Poland and the Netherlands, where fragmented procurement stacks and CSRD disclosure mandates create immediate attach-rate opportunities for sustainability-embedded contract management. Target healthcare networks in France seeking CNIL-compliant invoice automation with faster deployment cycles than incumbent suites permit. Pursue a channel-first go-to-market through regional systems integrators already embedded in target accounts' ERP transformation programs. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-focused platforms embedding EU AI Act audit engines and REACH substance tracking modules, as regulatory enforcement hardens replacement demand across automotive and pharmaceutical verticals. Long-term viability favors vendors with durable data network effects in supplier master databases, where taxonomy standardization investments compound switching costs. Watch for inflection where German automotive OEMs mandate chain-of-custody documentation from tier-one suppliers, forcing platform standardization decisions across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Enables composable procurement stacks that interoperate through standardized protocols, reducing integration friction for German automotive buyers. |
| Embedded Compliance Engine Development | Consolidates EU AI Act audit trails and GDPR data lineage into unified supplier onboarding workflows for French healthcare networks. |
| Machine-Learning Document Processing Acquisition | Accelerates contract clause extraction and invoice capture accuracy, compressing sourcing cycle times for United Kingdom financial institutions. |
| Supply Chain Finance Module Integration | Unlocks dynamic discounting revenue streams from cash-constrained supplier bases in Netherlands manufacturing clusters. |
| Mid-Market Template Pre-Configuration | Compresses implementation timelines from months to weeks for sub-$500M revenue manufacturers in Poland and Silesia. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, the Netherlands, and Poland, with primary inputs from each market informing demand calibration. Procurement technology executives, hospital purchasing committee chairs, automotive supplier compliance officers, and cloud infrastructure procurement leads provided qualitative grounding. Secondary validation drew from EU AI Act implementation guidance, CNIL audit logging standards, FCA operational resilience frameworks, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulated against top-down software spending forecasts.
Rate-of-change decomposition isolates cloud migration velocity, regulatory compliance investment cycles, and API adoption curves as independent forecast drivers across the projection horizon. Segmentation modeling incorporates deployment architecture, solution module attach rates, customer scale tiers, and vertical regulatory exposure. CAGRs derive from fitted adoption curves benchmarked against comparable enterprise software transitions. Forecast inputs include EU AI Act enforcement timelines, REACH substance tracking mandate expansion, and healthcare HIPAA audit frequency trends.
Caveats apply where GDPR cross-border data transfer rulings or EU AI Act delegated act clarifications could materially shift the outlook. Deviation in German automotive OEM compliance mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Australia Online Trading Platform Market
Financial Services
Australia Gift Card and Incentive Card Market
Financial Services
Financial Services Software Market
Financial Services
Benefits Consulting Service Market
Financial Services
Online Investment Platform Market
Financial Services
Australia Online Gambling Market
Financial Services
Online Lottery Market
Financial Services
South Korea Financial Services Software Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Liquidation Service Market
Financial Services
Direct Selling Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
India Trade Finance Market
Financial Services
Treasury Management Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
India Security Brokerage Market