
 Philippines Remittance Market | 2026-2036
Philippines Remittance Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Remittance Market Intelligence
Agent-based cash pickup networks is fragmenting as mobile wallets and direct-to-account channels gain transaction share. Western Union Company leverages its established brick-and-mortar presence across provincial municipalities. GCash anchors digital-first distribution through its Super App ecosystem. Cebuana Lhuillier competes via pawnshop-adjacent remittance counters reaching unbanked barangay populations.
Remittances constitute cross-border monetary transfers sent by migrant workers to recipients in their home country, typically executed through formal banking channels, licensed money transfer operators, or digital payment platforms with settlement times ranging from instant to three business days depending on corridor and compliance checks. The primary commercial purpose centers on household income supplementation, debt service, education funding, and small business capitalization in recipient economies. Bank transfer and mobile wallet modalities capture dominant flow volumes as digital onboarding reduces friction for overseas Filipino workers, while cash pickup retains structural importance in rural Luzon and Visayas municipalities with limited banking penetration. Service provider dynamics reveal fintech platforms eroding traditional money transfer operator margins through lower fee structures and real-time settlement capabilities.
Bangko Sentral ng Pilipinas governs e-money issuance and remittance licensing under the National Payment Systems Act, while the Anti-Money Laundering Council enforces transaction monitoring thresholds for cross-border flows. The country's national data privacy regulator mandates customer information protection standards across digital remittance channels. Stakeholders must monitor regulatory tightening on digital Know-Your-Customer thresholds and corridor-specific compliance reciprocity agreements.
Market Dynamics
Digital wallet penetration is compressing traditional agent-based cash pickup volumes as Overseas Filipino Workers migrate toward real-time settlement channels. The National Payment Systems Act is accelerating this structural shift by licensing new e-money issuers.
Growth Catalysts
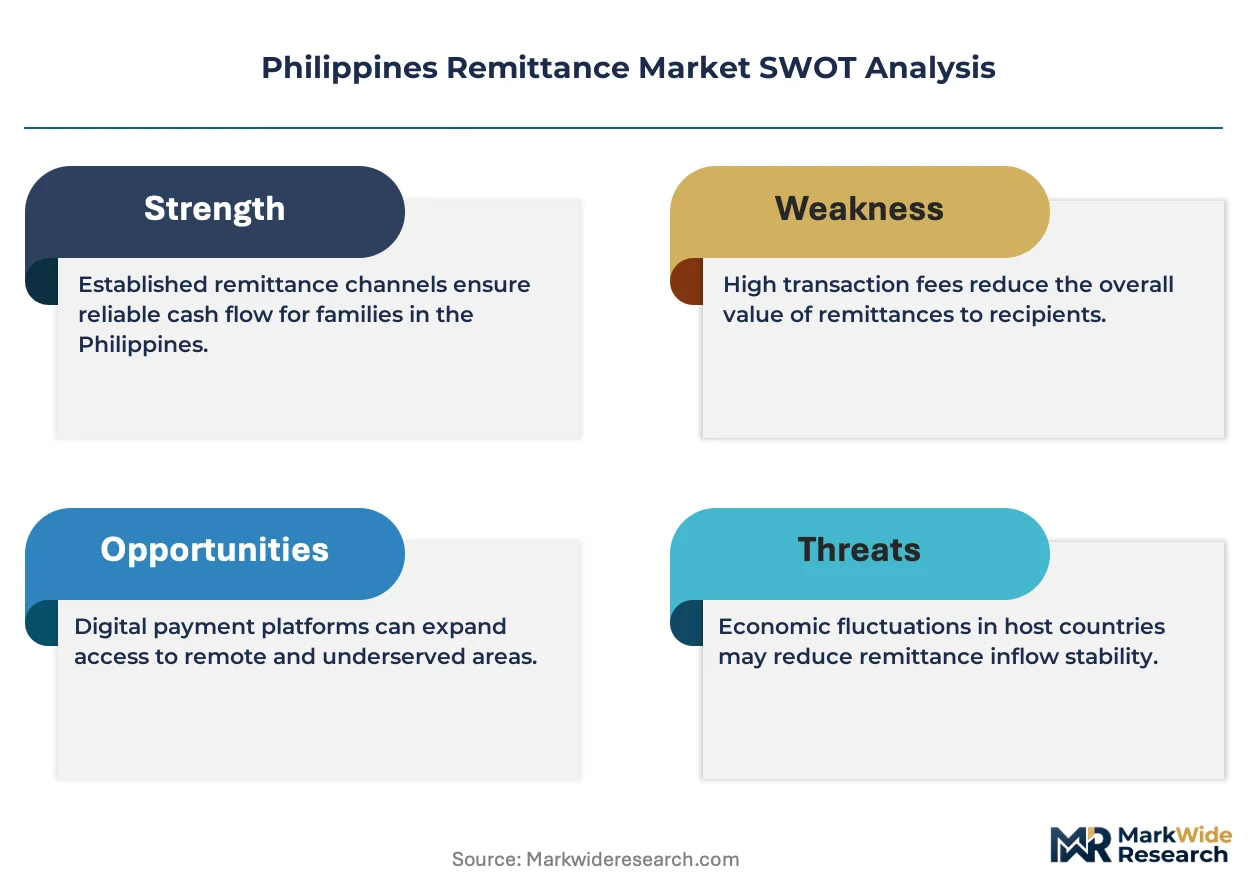
- Central bank licensing expansion:Bangko Sentral ng Pilipinas has streamlined e-money issuer approvals under the National Payment Systems Act, lowering barriers for fintech entrants to capture remittance flows.
- Smartphone adoption in sender corridors:Gulf-based Overseas Filipino Workers now execute direct-to-account transfers through mobile banking interfaces, bypassing correspondent banking delays.
- Calabarzon household consumption:Manufacturing and service sector wages in this corridor sustain elevated remittance dependency ratios among recipient families.
Market Restraints
- Rural banking infrastructure gaps:Last-mile cash access in Visayas municipalities requires costly agent network maintenance, eroding digital-first provider margins.
- Corridor-specific compliance reciprocity:Anti-Money Laundering Council thresholds for cross-border monitoring create settlement friction with Middle Eastern correspondent banks.
- Biometric verification hardware costs:Tier-2 remittance operators face capex burdens from Know-Your-Customer facial recognition mandates.
Strategic Opportunities
- Mindanao digital onboarding:Underpenetrated barangay populations in Davao and Cagayan de Oro present first-mover advantages for mobile wallet agents.
- Super App convergence:Integration of remittance receipt with bill payment and merchant commerce creates stickier recipient ecosystems.
- Data privacy compliance services:The national data privacy regulator's enforcement creates ancillary revenue streams for identity verification vendors.
Industry Challenges
- Legacy core banking integration:Rural cooperative banks struggle with API connectivity to real-time gross settlement systems.
- Agent liquidity management:Cash-in/cash-out float requirements strain working capital for provincial pawnshop-adjacent counters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Remittance Market |
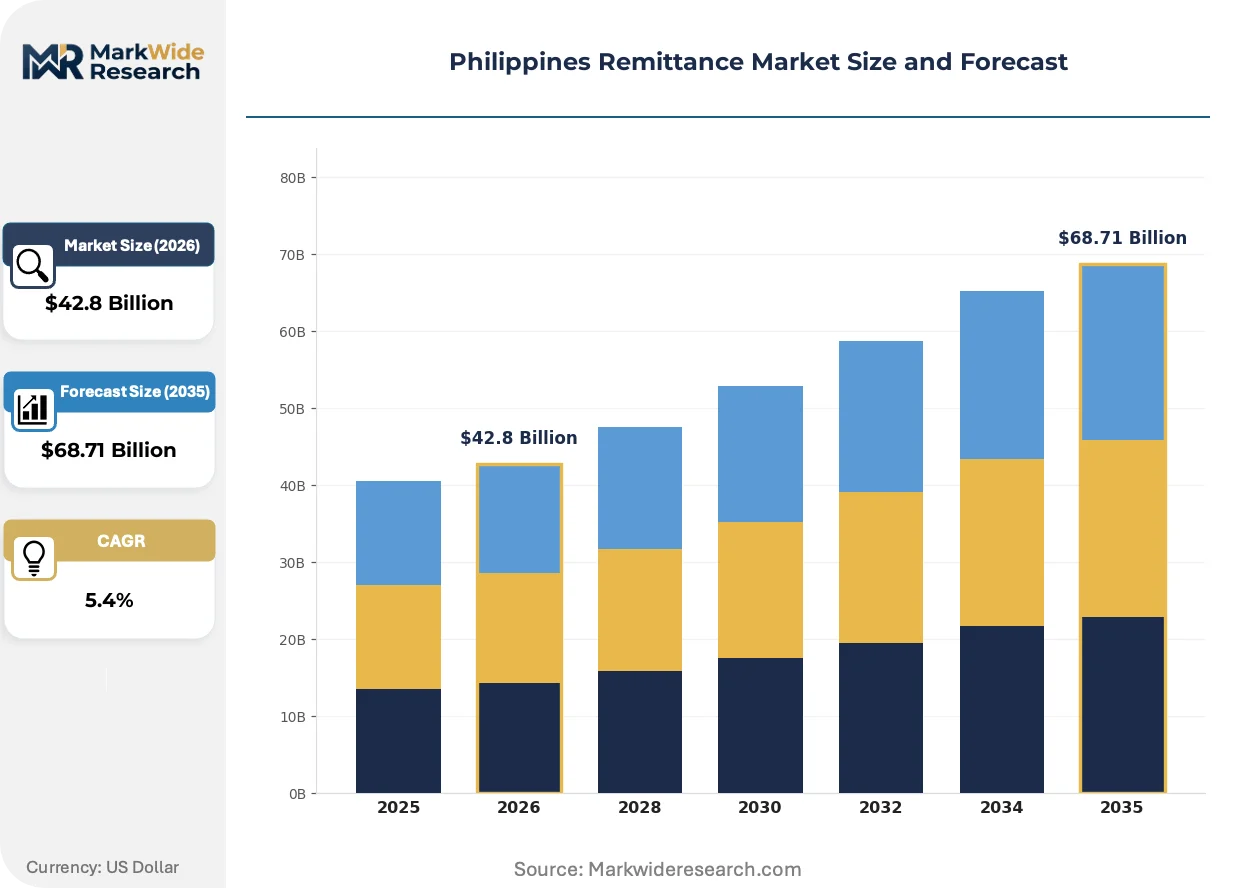
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transfer Method: Bank Transfer, Mobile Wallet, Cash Pickup, Online Transfer Recipient Type: Individual, Family, Business, NGO Service Provider: Bank, Money Transfer Operator, Fintech, Postal Service Transaction Volume: Low Value, Medium Value, High Value, Bulk Transfers |
| Companies Covered | BDO Unibank, Union Bank of the Philippines, Western Union Company, Cebuana Lhuillier, GCash, MoneyGram International, PayPal Holdings, LBC Express Holdings, WorldRemit Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Remittance Market Strategic Shifts & Innovations
Real-time settlement infrastructure is collapsing traditional three-day correspondent banking timelines. Three distinct forces are compressing transaction friction while expanding financial inclusion reach.
Blockchain-based settlement rails are virtualizing cross-border value movement by replacing SWIFT messaging with distributed ledger confirmation. Gulf-based sender cohorts are adopting these channels for family support transfers. The technology is virtualizing liquidity requirements for remittance operators, reducing prefunding needs in destination currencies.
Bangko Sentral ng Pilipinas has tightened digital Know-Your-Customer thresholds under Anti-Money Laundering Council guidance. This regulatory compression is forcing tier-2 operators to consolidate or outsource compliance functions. Metro Manila-based fintech platforms are responding by deploying video-based liveness detection for remote onboarding.
Recipient preference is shifting from cash pickup toward direct utility bill payment within mobile wallet interfaces. This behavioral pivot is disrupting traditional pawnshop-adjacent remittance counters in Luzon municipalities. The Visayas corridor shows the most visible acceleration, where unbanked populations now prioritize digital financial access over physical cash handling.
Philippines Remittance Market Segmentation
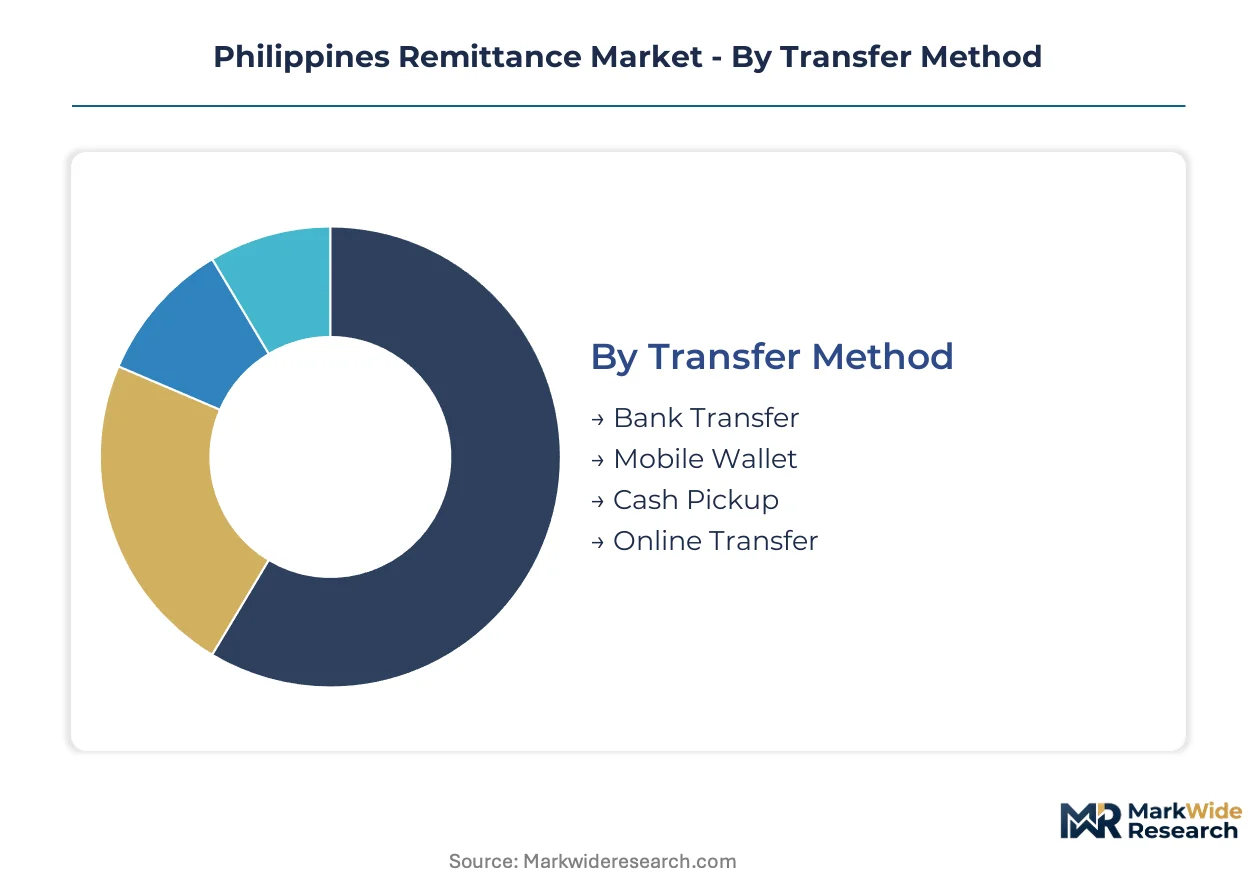
Remittance segmentation in the Philippines reveals how corridor economics, recipient banking status, and settlement urgency create distinct service requirements. Transfer method and recipient type segmentation exposes friction points where digital infrastructure gaps persist against consumer preference shifts.
Transfer Method:
Sender corridors span a use-case spectrum from emergency family support requiring instant settlement to scheduled household maintenance transfers tolerating longer clearing windows.
- Bank Transfer:Traditional correspondent banking rails execute through SWIFT messaging with settlement timelines of one to three business days. Demand concentrates among Gulf-based Overseas Filipino Workers in Saudi Arabia and UAE sending to Metro Manila accounts where recipient families maintain formal banking relationships.
- Mobile Wallet:Real-time settlement executes through licensed e-money issuer networks regulated under Bangko Sentral ng Pilipinas oversight. GCash and Maya capture dominant transaction volumes as Calabarzon corridor recipients prioritize instant notification and bill payment integration over cash handling.
- Cash Pickup:Agent-based networks maintain structural importance in Visayas municipalities and rural Luzon barangays with limited banking penetration.
- Online Transfer:Web-based platforms aggregate multiple settlement rails through single interfaces, gaining traction among tech-savvy sender cohorts in Singapore and Hong Kong.
The dominant share belongs to Bank Transfer, while Mobile Wallet is closing the gap fastest.
Recipient Type:
Cost tier segmentation separates high-frequency low-value household support from episodic large-ticket capital deployment.
- Individual:Single-recipient transfers dominate transaction volumes, typically executing monthly salary remittances from construction and domestic worker corridors in Kuwait and Qatar.
- Family:Multi-beneficiary household support constitutes the commercial core of Philippine remittance economics, with pooled transfers funding education, healthcare, and consumption across extended kin networks in Davao and Cagayan de Oro.
- Business:Enterprise recipients include micro-enterprises importing inventory and small construction contractors purchasing materials, concentrated in Cebu and Iloilo trading corridors.
- NGO:Non-governmental organization receipts span disaster relief funding and development project disbursements, requiring enhanced compliance documentation under Anti-Money Laundering Council thresholds.
Family recipients command the dominant share, while Business recipients are expanding most quickly as enterprise formalization accelerates.
Service Provider:
Provider type segmentation tracks margin compression as fintech platforms displace legacy operator economics through reduced fee structures.
- Bank:Universal and commercial banks leverage existing depositor relationships and foreign correspondent networks, though their digital onboarding friction cedes ground to specialized competitors.
- Money Transfer Operator:Western Union and traditional brick-and-mortar networks retain provincial municipality presence through agent relationships, particularly in Mindanao where physical cash access remains essential.
- Fintech:Digital-native platforms exploit National Payment Systems Act licensing to offer real-time settlement at lower cost, capturing sender cohorts prioritizing convenience over brand familiarity.
- Postal Service:Philippine Postal Corporation maintains rural last-mile access in isolated barangays where commercial agent economics fail, though transaction volumes remain limited.
Money Transfer Operators historically held dominant share, while Fintech providers are gaining ground fastest through mobile-first acquisition.
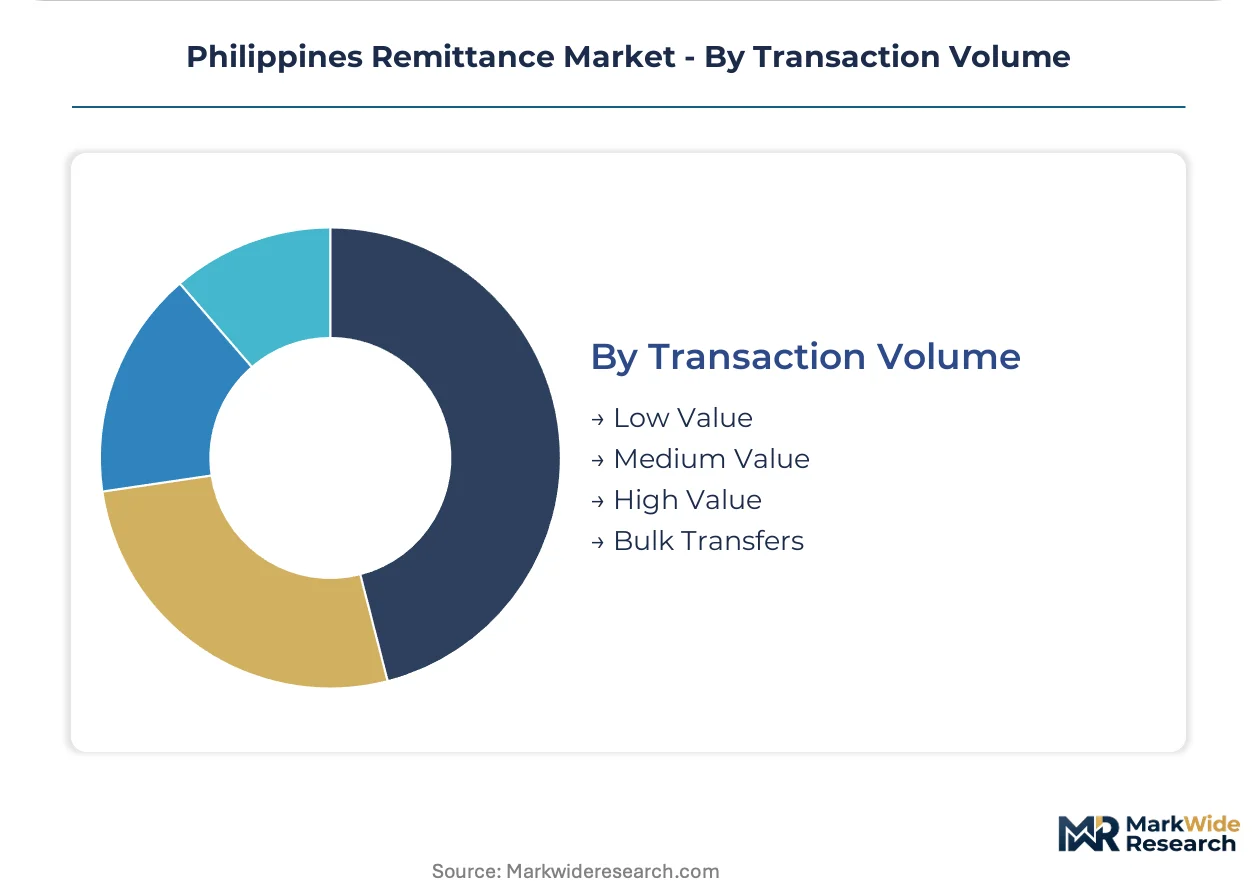
Transaction Volume:
Volume tier segmentation aligns fee structures and compliance intensity with transfer size and frequency patterns.
- Low Value:Sub-threshold transfers below central bank reporting requirements execute with minimal documentation, dominating frequency metrics among domestic worker senders.
- Medium Value:Mid-tier transfers trigger standard Know-Your-Customer protocols and represent the revenue sweet spot for most service providers.
- High Value:Large-ticket transfers face enhanced due diligence, biometric verification, and source-of-funds documentation under Anti-Money Laundering Council guidance.
- Bulk Transfers:Aggregated corporate payroll and institutional disbursements require specialized settlement arrangements and prefunding mechanisms.
Medium Value transfers constitute the dominant share, while Low Value transactions are climbing the fastest as micropayment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Metro Manila and Calabarzon corridors where recipient density justifies lower per-transaction costs, while Visayas and Mindanao sub-regions absorb premium pricing due to last-mile infrastructure gaps.
Metro Manila
Corporate banking relationships and high smartphone penetration drive direct-to-account settlement preferences. Bangko Sentral ng Pilipinas licensing requirements for e-money issuers enforce capital adequacy standards that favor established digital platforms. Makati and Taguig financial districts host concentrated fintech development activity supporting real-time gross settlement integration.
Calabarzon
Manufacturing wage corridors in Cavite and Laguna sustain elevated remittance dependency ratios among recipient households. The National Payment Systems Act enables rural bank participation in instant payment networks. Batangas port facilities support trade-linked remittance flows for small enterprise inventory financing.
Central Luzon
Agricultural worker migration to Middle Eastern corridors generates seasonal remittance peaks during planting cycles. The central bank's Anti-Money Laundering Council thresholds require enhanced documentation for agricultural enterprise receipts. Pampanga and Bulacan municipalities show accelerating mobile wallet adoption among previously unbanked populations.
Visayas
Island geography fragments banking infrastructure, preserving cash pickup network relevance. Cebu City anchors commercial remittance processing while provincial municipalities rely on pawnshop-adjacent agent counters. Iloilo and Bacolod trading corridors show emerging demand for business-to-business remittance settlement.
Mindanao
Underpenetrated barangay populations in Davao and Cagayan de Oro present first-mover opportunities for mobile wallet agent expansion. Bangko Sentral ng Pilipinas biometric verification mandates impose hardware cost burdens on tier-2 operators entering this corridor. Zamboanga Peninsula maintains traditional money transfer operator dominance due to limited digital infrastructure.
Philippines Remittance Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The Philippines remittance market structures around three distinct tiers: universal banks with established correspondent networks, digital-native fintech platforms with real-time settlement capabilities, and agent-based operators with rural last-mile access. Strategic archetypes include Super App ecosystem builders, pawnshop-adjacent cash pickup specialists, and blockchain settlement rail pioneers. Competitive dynamics center on M&A consolidation among tier-2 operators and strategic partnerships between fintech platforms and rural cooperative banks.
Within the universal bank tier, BDO Unibank and Union Bank of the Philippines anchor traditional correspondent banking relationships while developing digital onboarding capabilities. Among specialized money transfer operators, Western Union Company exemplifies brick-and-mortar network persistence, while GCash occupies a position as the dominant Super App ecosystem integrating remittance receipt with bill payment and merchant commerce. These three entities represent the primary competitive archetypes shaping margin compression and channel migration across the Philippine archipelago.
| Leading Market Players |
|---|
| BDO Unibank |
| Union Bank of the Philippines |
| Western Union Company |
| Cebuana Lhuillier |
| GCash |
| MoneyGram International |
| PayPal Holdings |
| LBC Express Holdings |
| WorldRemit Group Limited |
| Others |
Cost & Logistics Intelligence
Gulf-based correspondent banking networks concentrate liquidity provisioning for Philippine-bound remittance flows, anchoring margin pools in the digital-first provider tier where real-time settlement commands premium positioning against legacy agent-based alternatives. This upstream concentration in Middle Eastern sender corridors directly shapes downstream pricing power across Metro Manila and Calabarzon recipient markets.
Pricing Analysis
Real-time versus deferred settlement pricing spreads now structure the Philippine remittance market, with instant mobile wallet transfers commanding 15-40 basis point premiums over traditional three-day correspondent banking rails. Price differentiation rests on settlement velocity and recipient convenience integration, with Super App ecosystems capturing least price-sensitive urban segments while rural cash pickup corridors retain highest buyer sensitivity. Cost compression in the agent-based tier intensifies as digital platforms erode transaction volumes, forcing pawnshop-adjacent operators toward volume-based break-even thresholds.
Supply Chain Analysis
Bangko Sentral ng Pilipinas licensing restrictions under the National Payment Systems Act limit e-money issuer authorization flows, constraining supply-side expansion for cross-border settlement infrastructure. Liquidity provisioning draws from UAE, Saudi Arabia, and Singapore as primary sender-corridor banking hubs, with prefunding requirements resting on correspondent relationships and nostro account balances. Single-source vulnerability concentrates in SWIFT messaging dependencies for traditional bank transfers, while distribution runs through tiered agent networks, mobile wallet issuer platforms, and direct-to-account API integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippine remittance market rewards scarce capabilities in real-time settlement infrastructure and rural last-mile agent liquidity management, with competitive advantage tethered to biometric verification deployment and Bangko Sentral ng Pilipinas compliance navigation.
For Market Incumbents: Harden digital onboarding capabilities against fintech platform erosion by investing in video-based liveness detection and streamlining Know-Your-Customer workflows. Consolidate agent network relationships in Visayas and Mindanao municipalities where physical cash access retains structural importance, and deepen backward integration into core banking API connectivity to reduce settlement latency. For New Entrants and Emerging Players: Build out mobile wallet agent presence in underpenetrated Davao and Cagayan de Oro barangays before incumbent network effects solidify. Target the business recipient segment in Cebu and Iloilo trading corridors where enterprise formalization accelerates demand for B2B remittance settlement, and pursue white-label partnerships with rural cooperative banks lacking real-time gross settlement integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech platforms holding Bangko Sentral ng Pilipinas e-money licenses but lacking Gulf corridor sender relationships. Long-term viability favors platforms combining digital onboarding efficiency with provincial agent liquidity networks. Watch for Anti-Money Laundering Council threshold tightening as the signal indicating consolidation pressure on tier-2 operators unable to absorb compliance capex burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Verification Deployment | Video-based liveness detection satisfies Bangko Sentral ng Pilipinas digital Know-Your-Customer mandates for remote onboarding. |
| Rural Agent Network Expansion | Mindanao barangay penetration captures first-mover advantage before cash pickup volumes fully migrate to digital channels. |
| Super App Ecosystem Integration | Bill payment and merchant commerce bundling creates stickier recipient relationships beyond single-transaction remittance receipt. |
| Blockchain Settlement Rail Adoption | Distributed ledger infrastructure virtualizes prefunding requirements and compresses cross-border confirmation timelines. |
| Rural Cooperative Bank Partnership | API connectivity agreements extend real-time settlement reach to municipalities lacking universal bank branch presence. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with remittance platform executives, Bangko Sentral ng Pilipinas regulatory affairs specialists, rural cooperative bank technology officers, and Gulf-based Overseas Filipino Worker community organizers. Secondary validation drew from National Payment Systems Act regulatory filings, Anti-Money Laundering Council compliance guidance, e-money issuer licensing databases, and cross-border payment flow statistics. Bottom-up transaction volume modeling and top-down macroeconomic remittance dependency ratios were triangulated to establish market sizing.
Calibration against historical growth trajectories and corridor-specific penetration rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include transfer method, recipient type, service provider category, and transaction volume tier, with additional granularity on regional banking infrastructure maturity. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated smartphone penetration curves in sender corridors and biometric verification hardware cost decline assumptions.
Stress conditions across Gulf corridor labor demand fluctuations, Bangko Sentral ng Pilipinas licensing approval velocity, and rural agent network retention rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding digital wallet adoption elasticity and correspondent banking fee compression. Material shifts in Anti-Money Laundering Council threshold enforcement or National Payment Systems Act amendment timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia Pacific Mobile Wallet Market
Payments
US Virtual Cards Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Payment Service Provider Market
Payments
Germany POS Terminal Market
Payments
Cash Management System Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Portugal Mobile Payments Market
Payments
Enterprise Payment Software Market
Payments
North America Real Time Payment Market
Payments
UK Virtual Cards Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Saudi Arabia Payments Market
Payments
United States Real Time Payments Market
Payments
Germany Payment Gateway Market
Payments
Mexico Payments Market