
 Global Guillain-Barre Syndrome Market | 2026-2036
Global Guillain-Barre Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Global Guillain-Barre Syndrome Market Foresight
Plasma-derived immunoglobulin is rebalancing cost structures across the Guillain-Barre syndrome treatment landscape. CSL Behring leverages vertically integrated plasma collection networks across multiple continents. Grifols anchors European supply through its Barcelona-based fractionation campus. Octapharma AG specializes in niche immunoglobulin formulations for autoimmune neuropathies.
Guillain-Barre syndrome constitutes an acute peripheral nervous system disorder characterized by autoimmune-mediated demyelination or axonal degeneration, typically triggered by preceding infection, with diagnostic criteria requiring progressive weakness and elevated cerebrospinal fluid protein. Intravenous immunoglobulin dominates the product type landscape due to established efficacy in interrupting autoimmune antibody activity. Among therapy areas, acute inflammatory demyelinating polyneuropathy represents the most frequently diagnosed subtype, while acute motor axonal neuropathy shows faster growth in Asian patient populations. Subcutaneous delivery modes are gaining traction in rehabilitation centers seeking reduced hospitalization duration.
The FDA orphan drug program shapes development incentives for novel Guillain-Barre syndrome therapeutics, while the EMA's centralized marketing authorization governs European market access for plasma-derived products. Japan's PMDA maintains stringent viral safety standards that influence global manufacturing protocols for immunoglobulin therapies. Stakeholders must monitor evolving regulatory divergence between plasma sourcing requirements and emerging recombinant alternatives.
Market Dynamics
Plasma supply concentration among three fractionators is compressing treatment access timelines and amplifying geographic dependency in immunoglobulin procurement. CSL Behring, Grifols, and Octapharma AG collectively control upstream collection networks across North America, Europe, and select Asian markets.
Growth Catalysts
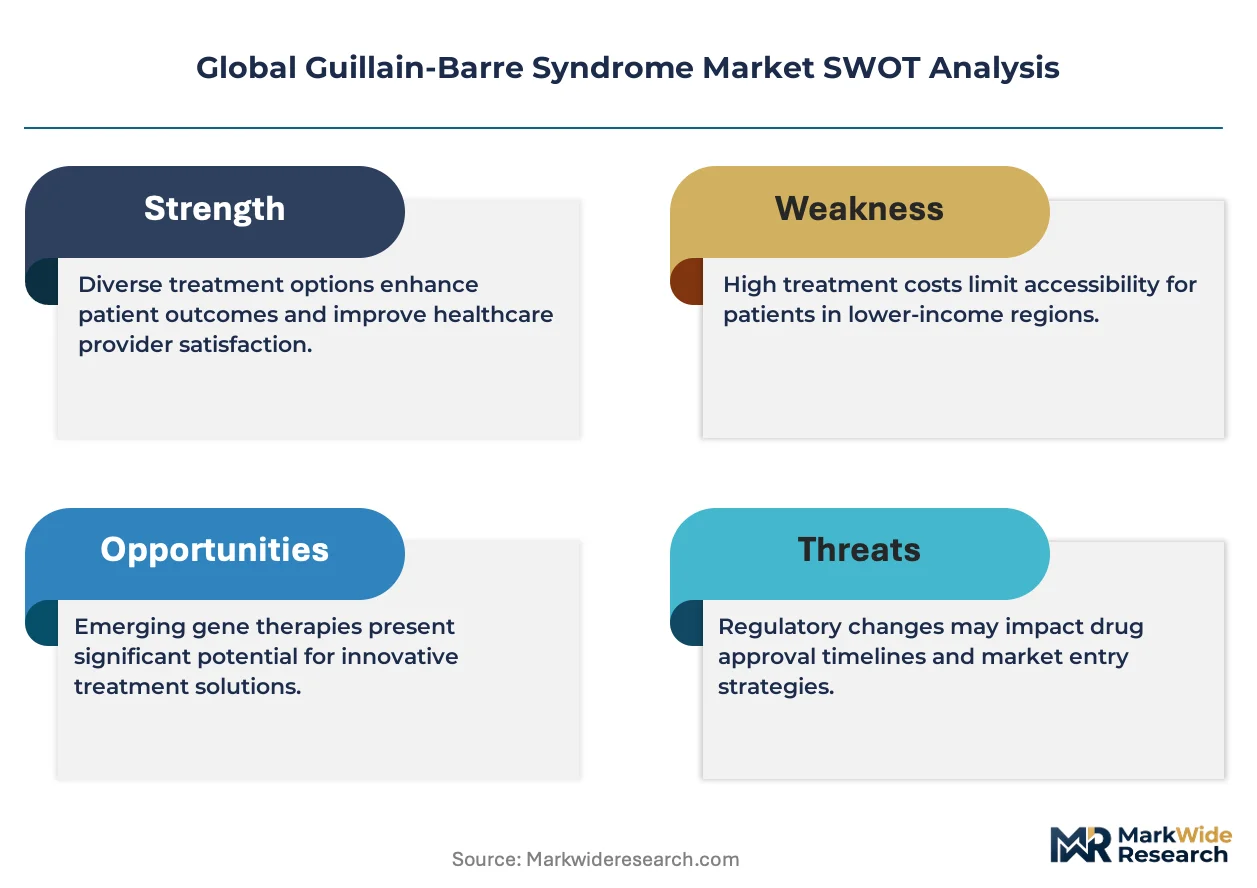
- FDA Orphan Drug Designation:The pathway accelerates novel immunotherapy development through tax credits and protocol assistance. Developers targeting refractory Guillain-Barre subtypes gain priority review advantages.
- Neurology Clinic Expansion:Specialist centers in the United States, Germany, and Japan are standardizing intravenous immunoglobulin protocols. These facilities reduce diagnostic-to-treatment intervals through dedicated autoimmune neurology units.
- Subcutaneous Delivery Innovation:Rehabilitation centers are adopting home-based administration systems. This shift reduces hospitalization duration and expands patient eligibility for early discharge protocols.
Market Restraints
- Plasma Collection Concentration:United States-based collection centers supply over sixty percent of global source material. Any disruption to American donation flows cascades through fractionation capacity worldwide.
- Viral Safety Manufacturing Costs:Japan's PMDA enforces stringent pathogen inactivation standards that extend production cycles. These requirements add validation layers without commensurate reimbursement adjustments.
- Recombinant Alternative Timeline:Fully synthetic immunoglobulin remains preclinical for autoimmune neuropathies. Plasma-derived products retain clinical monopoly despite supply vulnerability.
Strategic Opportunities
- Indian Diagnostic Expansion:Underpenetrated neurology infrastructure in tier-two Indian cities creates first-mover positioning for acute inflammatory demyelinating polyneuropathy protocols. CDSCO streamlined approval pathways for plasma-derived products reduce market entry friction.
- EMA Centralized Authorization Leverage:The Barcelona fractionation cluster can serve as a European distribution hub for Asian markets seeking CE-marked alternatives to American supply.
- Biomarker-Guided Patient Stratification:Cerebrospinal fluid protein quantification combined with anti-ganglioside antibody profiling enables subtype-specific dosing. This convergence of diagnostic and therapeutic precision supports outcome-based contracting models.
Industry Challenges
- Specialized Neurology Nursing Shortage:Intravenous immunoglobulin administration requires trained infusion specialists capable of anaphylaxis response. Competition from oncology and rheumatology clinics constrains talent pools.
- Cold Chain Integrity Complexity:Plasma-derived products require maintained temperature controls from collection through patient administration. Logistics reconfiguration for subcutaneous delivery modes demands capital deployment in distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Guillain-Barre Syndrome Market |
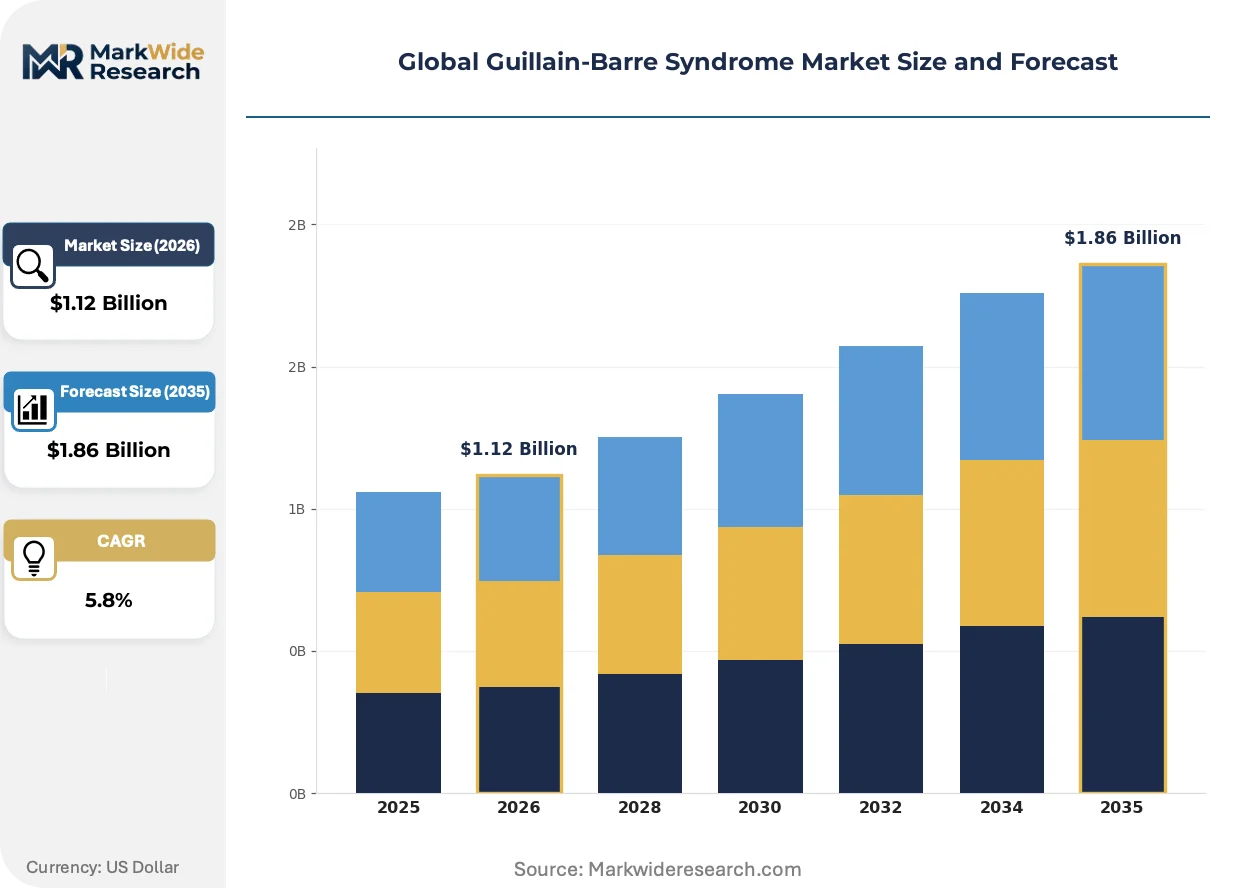
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Immunoglobulin, Plasmapheresis, Supportive Care, Immunotherapy, Respiratory Support Therapy Area: Acute Inflammatory Demyelinating Polyneuropathy, Acute Motor Axonal Neuropathy, Miller Fisher Syndrome, Acute Motor Sensory Axonal Neuropathy End User: Neurology Clinics, Rehabilitation Centers, Specialty Hospitals, Outpatient Care Centers Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Octapharma AG, Akari Therapeutics, CSL Behring, Biotest AG, China Biologic Products Holdings, Grifols, Kedrion Biopharma, F. Hoffmann-La Roche Ltd, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Guillain-Barre Syndrome Market Shifts & Advancements
Immunoglobulin manufacturing is bifurcating between plasma-dependent fractionation and recombinant protein engineering, with regulatory incentives determining competitive positioning across patient access channels.
Subcutaneous immunoglobulin formulations are electrifying post-acute care pathways. These delivery systems enable self-administration in home settings, compressing rehabilitation center occupancy rates. Neurology departments in German university hospitals are piloting nurse-supervised home infusion programs, reducing thirty-day readmission metrics.
The EMA's centralized marketing authorization for plasma-derived products is harmonizing quality standards across twenty-seven member states. This regulatory convergence eliminates redundant national inspections for fractionators. Barcelona-based manufacturing campuses now serve as single-source supply points for Nordic and Baltic markets previously requiring bilateral agreements.
Patient advocacy networks are demanding transparent pricing for intravenous immunoglobulin courses. United States Medicare Part B reimbursement adjustments are compressing margin structures for acute inpatient administration. Neurology clinics are responding by unbundling pharmacy benefit management from infusion services, creating direct manufacturer-to-payer contracting channels.
Global Guillain-Barre Syndrome Market Segmentation
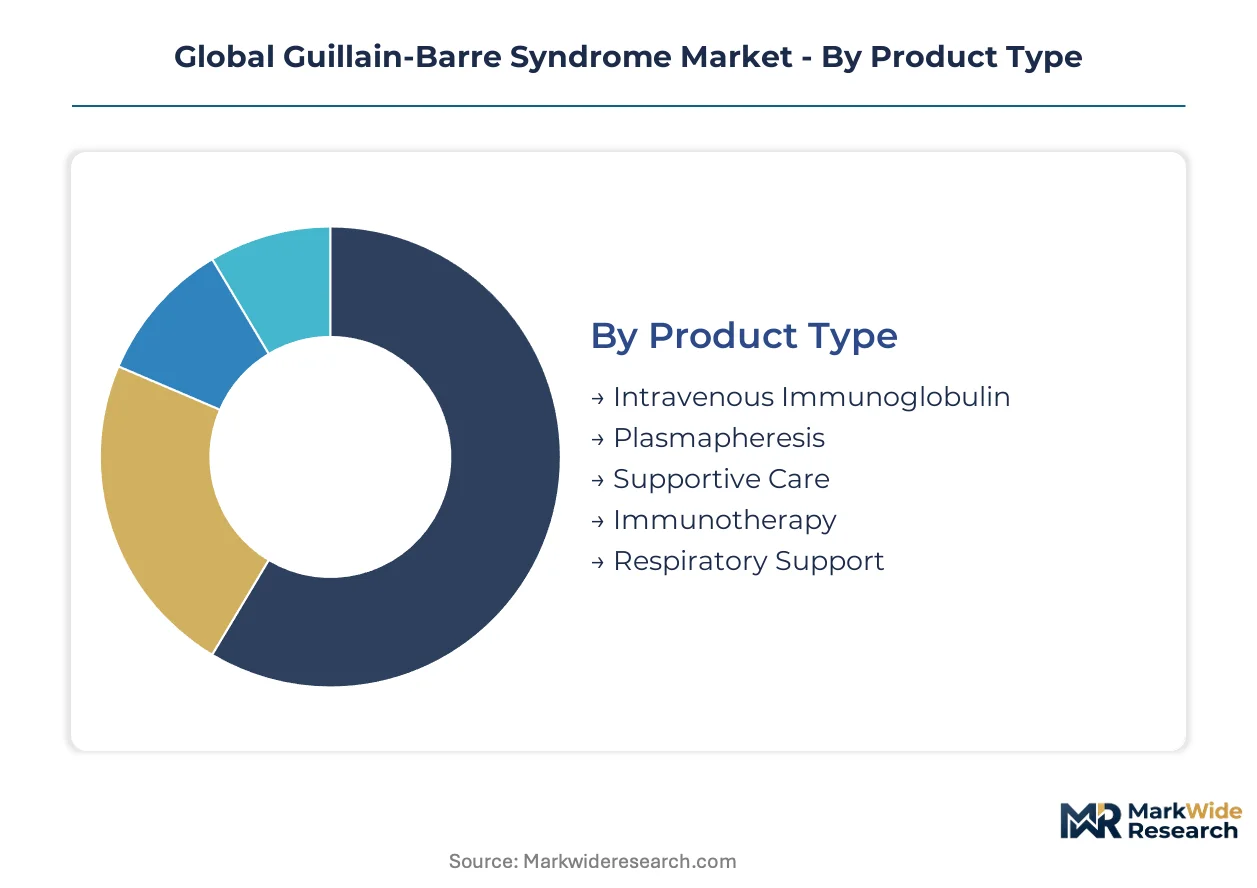
Guillain-Barre syndrome treatment pathways diverge sharply across product categories, therapy subtypes, and care settings. Procurement decisions hinge on acute versus chronic care requirements, reimbursement structures, and plasma supply availability. Understanding these segment boundaries enables targeted positioning across fractionators, device manufacturers, and service providers.
Product Type:
Hospital pharmacy committees weigh efficacy evidence against infusion logistics and viral safety profiles when selecting therapeutic modalities.
- Intravenous Immunoglobulin:Purified human immunoglobulin G antibodies interrupt pathogenic autoantibody activity through Fc receptor blockade and complement modulation. Demand concentrates in United States and German neurology clinics where Medicare and statutory health insurance reimburse multi-day infusion protocols. Supply concentration among CSL Behring, Grifols, and Octapharma AG creates procurement dependency on North American and European plasma collection networks.
- Plasmapheresis:Extracorporeal plasma exchange removes circulating autoantibodies and inflammatory mediators through membrane filtration or centrifugation. Japanese academic medical centers favor this modality for severe axonal variants, driven by PMDA reimbursement codes that cover apheresis catheter placement and intensive care monitoring. Equipment vendors compete on disposable kit pricing and nurse training programs.
- Supportive Care:Mechanical ventilation, autonomic monitoring, and thromboprophylaxis for patients with respiratory or cardiovascular compromise.
- Immunotherapy:Corticosteroids and emerging complement inhibitors for refractory or relapsing cases.
- Respiratory Support:Non-invasive ventilation and intubation equipment for phrenic nerve involvement.
Intravenous immunoglobulin leads on scale; immunotherapy leads on momentum as novel biologics enter orphan drug pipelines.
Therapy Area:
Diagnostic coding accuracy determines reimbursement rates and influences therapeutic intensity across neurological practice patterns.
- Acute Inflammatory Demyelinating Polyneuropathy:The classic demyelinating subtype presents with ascending weakness, areflexia, and albuminocytologic dissociation in cerebrospinal fluid. German university hospitals and United States academic centers generate concentrated demand for standardized IVIG dosing protocols. Diagnostic clarity enables outcome-based contracting with payers.
- Acute Motor Axonal Neuropathy:Pure motor involvement with anti-GM1 or anti-GD1a antibodies characterizes this subtype with more rapid onset and poorer prognosis. Chinese and Japanese patient populations show elevated prevalence, driving regional protocol adaptation and antibody testing infrastructure investment. Campylobacter jejuni serotyping correlates with severity stratification.
- Miller Fisher Syndrome:Ophthalmoplegia, ataxia, and areflexia triad with anti-GQ1b antibodies.
- Acute Motor Sensory Axonal Neuropathy:Combined motor and sensory axonal degeneration with limited recovery potential.
Acute inflammatory demyelinating polyneuropathy leads on scale; acute motor axonal neuropathy leads on momentum with Asian diagnostic expansion.
End User:
Site-of-care migration is reshaping capital deployment and staffing models across the post-acute continuum.
- Neurology Clinics:Specialist outpatient facilities with dedicated autoimmune neurology units and infusion suites. United States metropolitan markets concentrate demand where Medicare Part B reimbursement supports physician-administered drug margins. These clinics compete on diagnostic-to-treatment interval metrics.
- Rehabilitation Centers:Post-acute facilities managing weaning from mechanical ventilation and functional recovery protocols. German and Japanese systems integrate these centers into statutory long-term care pathways, creating predictable admission flows. Subcutaneous immunoglobulin adoption is compressing length-of-stay targets.
- Specialty Hospitals:Dedicated neurological or academic medical centers with intensive care capability.
- Outpatient Care Centers:Community-based infusion sites with lower acuity thresholds.
Neurology clinics lead on scale; rehabilitation centers lead on momentum with home-based delivery expansion.
Delivery Mode:
Administration route selection balances bioavailability requirements against patient autonomy and total cost of care.
- Intravenous:Large-volume immunoglobulin infusion requiring vascular access and infusion pump monitoring. Remains dominant for acute-phase treatment in hospital and clinic settings where anaphylaxis response capability is mandatory. Cold chain requirements extend from fractionation through patient administration.
- Subcutaneous:Smaller-volume, more frequent administration via abdominal or thigh injection sites. Rehabilitation centers and home health programs in Germany and Japan are piloting nurse-supervised patient self-administration. This mode reduces hospitalization duration and expands eligibility for early discharge protocols.
- Oral:Limited applicability for immunoglobulin due to gastrointestinal degradation; used for adjunctive agents.
- Intramuscular:Historical route largely superseded by intravenous and subcutaneous alternatives.
Intravenous delivery leads on scale; subcutaneous delivery leads on momentum with post-acute care pathway redesign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States plasma collection networks supply the dominant share of immunoglobulin feedstock for Guillain-Barre syndrome treatment worldwide. Specialist neurology infrastructure concentrates in specific metropolitan clusters across North America, Europe, and Asia-Pacific.
United States
Medicare Part B reimbursement structures sustain multi-day IVIG infusion protocols in metropolitan neurology clinics. The FDA orphan drug designation pathway accelerates novel immunotherapy development through tax credits and protocol assistance. Boston and Baltimore academic medical centers anchor demand concentration for acute inflammatory demyelinating polyneuropathy protocols.
Germany
Statutory health insurance funds reimburse standardized IVIG dosing with outcome-based contracting pilots in university hospital networks. The EMA centralized marketing authorization governs European market access for plasma-derived products. The Munich-Stuttgart corridor hosts specialized autoimmune neurology units with dedicated infusion suites.
Japan
PMDA reimbursement codes cover apheresis catheter placement and intensive care monitoring for severe axonal variants. Stringent viral safety standards enforced by the national pharmaceutical regulator extend production cycle validation layers. Tokyo and Osaka academic centers drive diagnostic expansion for acute motor axonal neuropathy with anti-ganglioside antibody profiling.
India
Tier-two city diagnostic infrastructure creates first-mover positioning for acute inflammatory demyelinating polyneuropathy protocols. CDSCO streamlined approval pathways for plasma-derived products reduce market entry friction. The Delhi-Mumbai corridor concentrates neurology specialist training programs with expanding infusion capacity.
China
Regional hospital networks in the Yangtze River Delta scale IVIG administration for Campylobacter-associated axonal variants. The national pharmaceutical regulator maintains import licensing requirements for foreign-sourced immunoglobulin. Shanghai teaching hospitals anchor clinical trial recruitment for subcutaneous delivery mode pilots.
Global Guillain-Barre Syndrome Market Competitive Landscape
Global majors compete with regional champions across plasma fractionation capacity and collection network reach. The supplier base concentrates among vertically integrated players controlling upstream source material access. Three strategic archetypes dominate: continental-scale fractionators with captive plasma supply, regional biopharma specialists with distribution partnerships, and emerging-market plasma processors with cost-advantaged production. Competitive moves center on backward integration into collection networks and geographic licensing arrangements for subcutaneous formulation technology.
Among European-headquartered fractionators, Octapharma AG, Grifols, and CSL Behring exemplify the vertically integrated archetype with multi-continent collection infrastructure. Octapharma AG occupies a position within the niche immunoglobulin formulation segment for autoimmune neuropathies. Grifols anchors European supply through its Barcelona-based manufacturing cluster. CSL Behring represents the scale-driven end with integrated networks spanning North America and select Asian markets. Akari Therapeutics and Biotest AG sit within the specialized immunotherapy development tier targeting refractory subtypes through orphan drug pathways.
| Leading Market Players |
|---|
| Octapharma AG |
| Akari Therapeutics |
| CSL Behring |
| Biotest AG |
| China Biologic Products Holdings |
| Grifols |
| Kedrion Biopharma |
| F. Hoffmann-La Roche Ltd |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
Plasma protein pricing indices cascade through fractionation economics into three-tier pricing structures across premium, standard, and economy immunoglobulin tiers. North American collection cost volatility transmits directly into hospital pharmacy procurement negotiations, with Medicare Part B reimbursement compressing margins on acute inpatient administration while subcutaneous delivery modes command outpatient premiums.
Pricing Analysis
Input-cost pass-through from plasma collection operations dominates pricing formation across immunoglobulin tiers. Three-tier pricing structure across premium, standard, and economy levels reflects viral safety validation depth and cold chain assurance grades. Pricing pressure stems from United States Medicare reimbursement compression on multi-day IVIG protocols. Academic medical centers exhibit lowest price sensitivity due to outcome-based contracting pilots, while community hospitals face acute margin constraints.
Supply Chain Analysis
Japan's PMDA domestic-content requirements for viral safety documentation are reshaping sourcing patterns toward locally validated plasma collections. Supply concentrates in the United States, Germany, and Austria where fractionation capacity feeds from captive collection networks. Raw material dependencies span source plasma, chromatography resins, and pathogen inactivation reagents. Single-source vulnerability concentrates in North American plasma flows exceeding sixty percent of global feedstock. Distribution runs through cold-chain logistics partnerships anchored in Barcelona and Los Angeles hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Guillain-Barre syndrome market functions as a stable compounder anchored by chronic plasma supply inelasticity and orphan drug regulatory protection. Immunoglobulin demand growth tracks autoimmune neurology diagnosis expansion with limited substitution risk.
For Market Incumbents: Cement collection network dominance through exclusive donor center agreements in metropolitan United States corridors and Barcelona-sourced European expansion. Grifols and CSL Behring should prioritize backward integration into Indian plasma collection infrastructure before CDSCO regulatory maturation. Threat from recombinant immunoglobulin alternatives remains distant but demands R&D optionality preservation. For New Entrants and Emerging Players: Tier-two Indian city hospital systems represent the most penetrable buyer archetype for acute inflammatory demyelinating polyneuropathy protocol establishment. Chinese regional hospital networks in the Yangtze River Delta offer secondary white-space for Campylobacter-associated axonal variant specialization. Go-to-market execution should leverage CDSCO streamlined approval pathways and direct neurology specialist education rather than distributor intermediation. For Investors and Strategic Acquirers: Asymmetric upside sits with subcutaneous formulation technology specialists possessing European CE marking and Japanese PMDA approval. Long-term viability frames around plasma supply security rather than therapeutic mechanism innovation. Acquisition target archetype: mid-scale fractionators with underutilized collection capacity in Asia-Pacific. Signal to watch: PMDA reimbursement code expansion for home-based immunoglobulin administration.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Behring's multi-continent donor center footprint secures feedstock priority amid supply concentration. |
| Subcutaneous Formulation Development | Octapharma AG's niche autoimmune neuropathy specialization enables rehabilitation center channel penetration. |
| Orphan Drug Designation Pursuit | FDA tax credit and protocol assistance accelerates novel immunotherapy timelines for refractory subtypes. |
| EMA Centralized Authorization Leverage | Barcelona fractionation cluster serves as single-source supply point for Nordic and Baltic market access. |
| Biomarker-Guided Patient Stratification | Anti-ganglioside antibody profiling enables acute motor axonal neuropathy protocol customization in Asian populations. |
Research Methodology
Direct dialogue with plasma fractionation executives, neurology clinic infusion directors, hospital pharmacy procurement managers, and PMDA regulatory consultants grounded qualitative findings. Secondary validation drew from FDA orphan drug designation filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov immunoglobulin protocol registrations, and Japanese Ministry of Health reimbursement code databases. Bottom-up patient population modeling and top-down plasma supply-demand reconciliation ensured cross-verification.
Segment-level value outputs emerged from therapy area stratification across acute inflammatory demyelinating polyneuropathy and acute motor axonal neuropathy, product type differentiation between intravenous and subcutaneous immunoglobulin, and end-user channel analysis spanning neurology clinics and rehabilitation centers. CAGRs derived from plasma collection capacity expansion trajectories, diagnostic coding trend extrapolation, and reimbursement rate elasticity assumptions across the analysis window. Forecast inputs incorporated PMDA viral safety standard evolution and Medicare Part B pricing adjustment scenarios.
Underlying measurement precision varies by segment; United States and German neurology clinic demand carries tighter precision than Indian tier-two city expansion projections. Forecasts embed assumptions regarding plasma donor recruitment sustainability and regulatory pathway timelines without guaranteed realization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Congenital Adrenal Hyperplasia Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Byler Disease Market
Rare Diseases
Turner Syndrome Market