
 Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market | 2026-2036
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market Foresight
Market Context
Antisense oligonucleotide chemistry is restructuring therapeutic economics for progeria, replacing earlier protein-based interventions with nucleic acid platforms that target the LMNA mutation at the transcript level. BioMarin Pharmaceutical sustains one of the deepest rare disease manufacturing footprints in the field, operating dedicated gene therapy production suites in California. Ionis Pharmaceuticals anchors clinical progress through its established antisense platform, while BridgeBio Pharma competes via targeted oncology and genetic disease infrastructure repurposed for HGPS development.
Technical Definition and Segment Structure
Hutchinson Gilford Progeria Syndrome therapeutics comprise pharmaceutical interventions designed to correct or compensate for the pathogenic LMNA G608G mutation, which produces the toxic progerin protein and drives premature aging through nuclear membrane dysfunction; these treatments aim to extend patient lifespan from a median of 14.5 years toward more typical human longevity. Gene therapy segments currently occupy the highest valuation tier due to curative intent and durable expression potential, while RNA therapy approaches leveraging splice-switching oligonucleotides represent the fastest-advancing modality with multiple candidates in active clinical translation. Small molecule programs targeting protein farnesylation retain established safety data but face margin compression as next-generation modalities demonstrate superior mechanistic precision.
Regulatory Framework and Outlook
The FDA Office of Orphan Products Development and EMA Committee for Orphan Medicinal Products jointly shape HGPS therapeutic development through accelerated review pathways, pediatric investigation plans, and post-market surveillance requirements that define clinical evidence standards. The NIH Rare Diseases Clinical Research Network and The Progeria Research Foundation collaborate to standardize natural history data, directly influencing regulatory acceptance of surrogate endpoints. Stakeholders must monitor how evolving gene therapy manufacturing guidelines from FDA CBER and EMA CAT reshape cost structures and approval timelines for single-patient-scale production.
Market Dynamics
Antisense oligonucleotide chemistry is restructuring therapeutic economics for progeria, replacing earlier protein-based interventions with nucleic acid platforms that target the LMNA mutation at the transcript level. This shift compresses development timelines while raising manufacturing complexity for sponsors.
Growth Catalysts
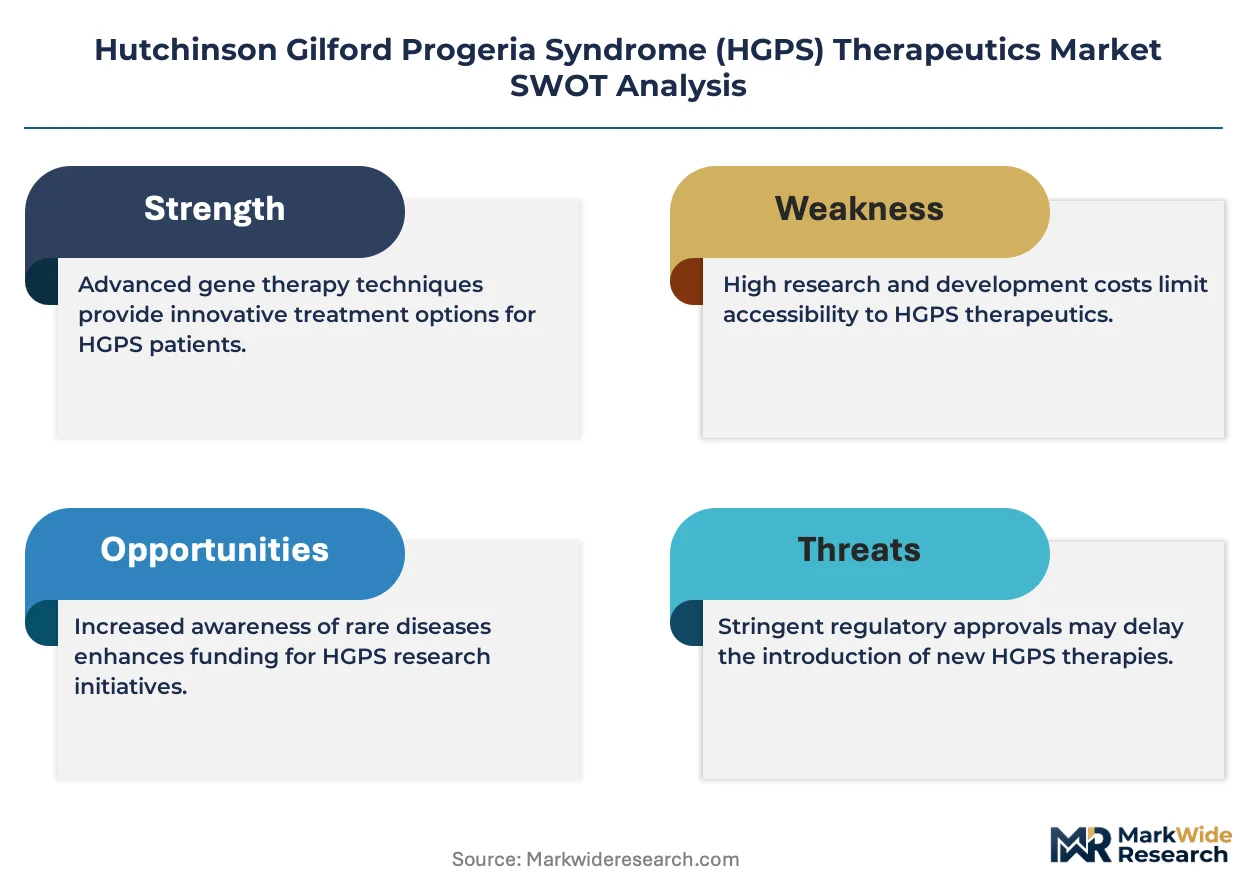
- FDA Rare Pediatric Disease Priority Review Voucher:This incentive program accelerates orphan drug commercialization timelines, directly rewarding sponsors who bring HGPS therapeutics through approval.
- Splice-switching oligonucleotides:RNA therapy platforms now enable precise transcript-level correction, offering curative potential beyond symptomatic management.
- Pediatric specialty clinic networks:Concentrated treatment centers in the United States and Germany streamline patient identification and protocol enrollment.
Market Restraints
- Patient pool limitation:Approximately 400 known cases worldwide constrain commercial scale, forcing ultra-premium pricing models that limit reimbursement negotiation leverage.
- Gene therapy manufacturing concentration:Viral vector production capacity clusters in California and Massachusetts, creating geographic supply vulnerability and capacity bottlenecks.
- Progerin farnesylation inhibitor substitution:Lonafarnib and related small molecules retain established safety profiles, creating clinical inertia against novel modality adoption.
Strategic Opportunities
- EMA Committee for Orphan Medicinal Products accelerated assessment:European regulatory pathways offer reduced fee structures and protocol assistance for HGPS sponsors.
- Natural history data monetization:The Progeria Research Foundation's standardized patient registry enables surrogate endpoint validation that compresses Phase 3 duration.
- Single-patient-scale production:Autologous gene therapy manufacturing models eliminate cold chain distribution constraints and enable direct-to-clinic delivery.
Industry Challenges
- Gene therapy talent scarcity:Viral vector process development and analytical characterization expertise concentrates at a handful of contract manufacturers, constraining sponsor hiring pipelines.
- LMNA variant heterogeneity:Non-G608G mutations require separate clinical validation, fragmenting development resources across smaller patient subpopulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market |
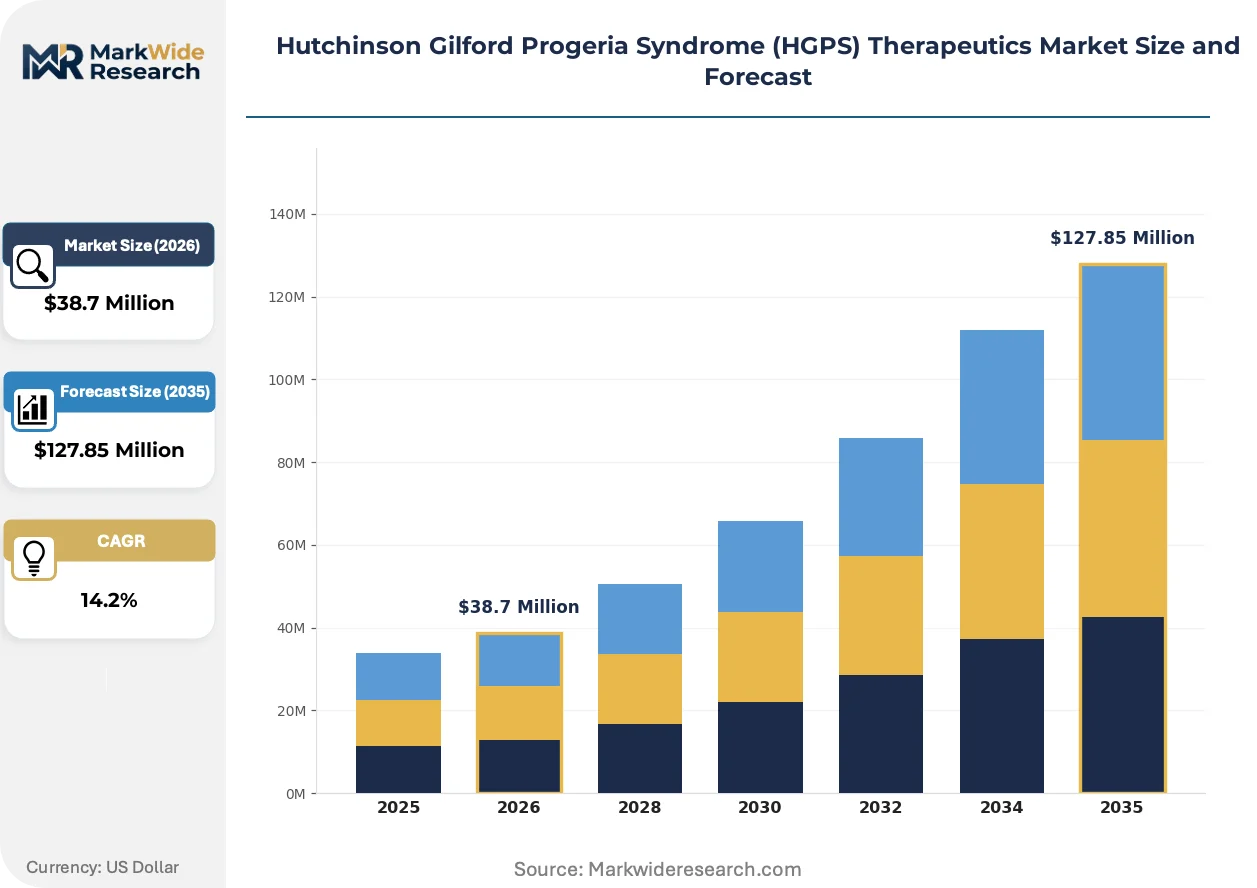
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Small Molecules, RNA Therapy, Protein Replacement Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Research Institutions, Specialty Clinics, Home Care Clinical Stage: Preclinical, Phase 1, Phase 2, Phase 3 |
| Companies Covered | Merck & Co., Inc., BioMarin Pharmaceutical Inc., Eiger BioPharmaceuticals, Inc., Sangamo Therapeutics, Inc., BridgeBio Pharma, Inc., PRG Science & Technology, Ultragenyx Pharmaceutical Inc., The Progeria Research Foundation, Ionis Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market Shifts & Advancements
Gene therapy manufacturing is consolidating around closed-system bioreactor platforms that reduce contamination risk while enabling smaller batch scales suited to ultra-orphan indications.
Antisense oligonucleotide chemistry is consolidating therapeutic development pipelines, as sponsors abandon protein farnesylation inhibitors in favor of transcript-targeting platforms that offer superior mechanistic precision. Pediatric specialty clinics are prioritizing splice-switching candidates for protocol slots, recognizing their potential to modify disease trajectory rather than merely slow progression. This modality shift is compressing investment in small molecule infrastructure while expanding nucleic acid manufacturing partnerships.
REACH and RoHS compliance requirements in the European Union are reshaping viral vector production inputs, forcing manufacturers to substitute legacy reagents with certified alternatives. The EMA's evolving gene therapy manufacturing guidelines now mandate extended characterization assays that extend release timelines. Sponsors targeting European approval are responding by front-loading CMC development to avoid regulatory delays.
Patient advocacy organizations are directly funding early-phase trials, bypassing traditional venture capital timelines and compressing protocol initiation from years to months. The Progeria Research Foundation's clinical trial consortium in the United States coordinates site activation across Boston, Houston, and San Diego, eliminating sponsor site-selection overhead. This philanthropic-industrial partnership model is displacing conventional biotech financing structures for ultra-orphan indications.
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market Segmentation
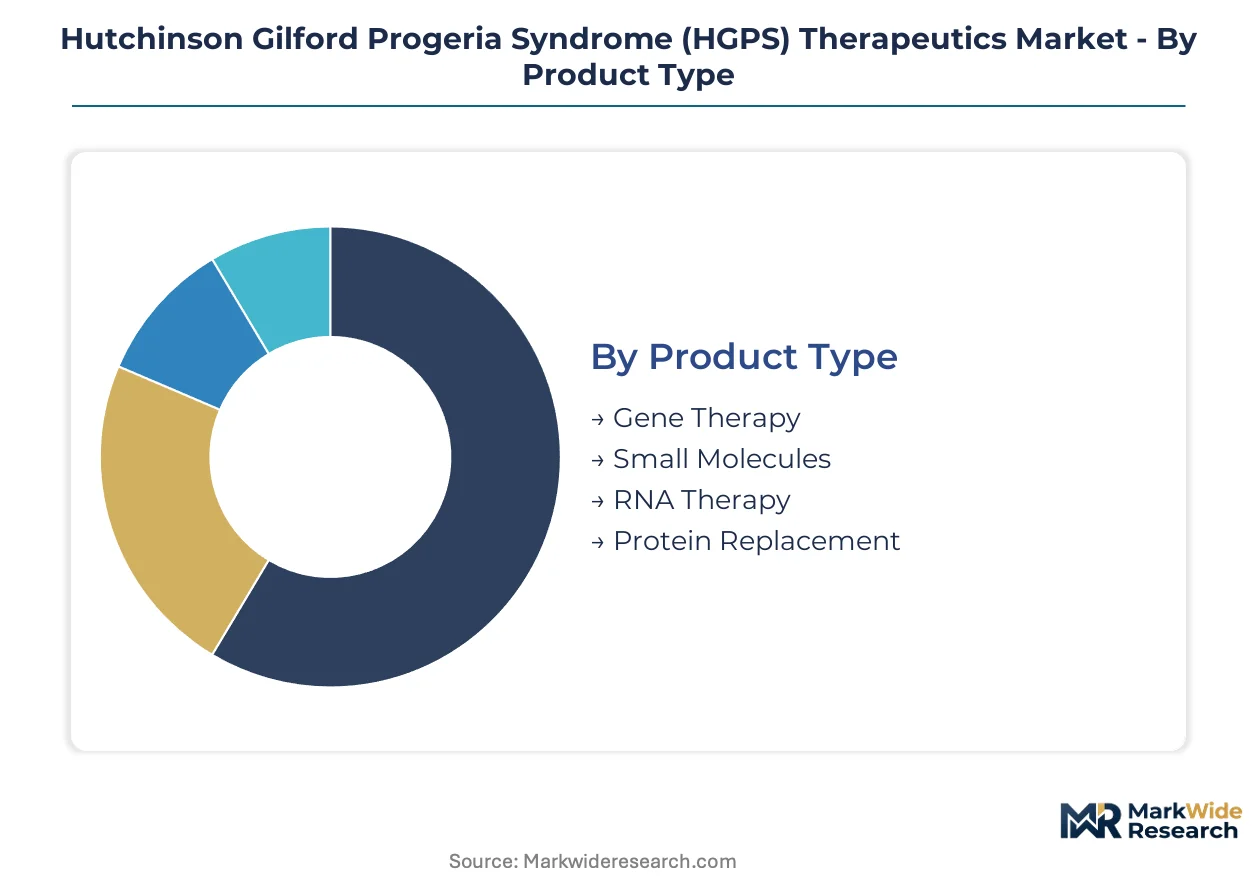
Therapeutic modality selection in HGPS determines manufacturing scale, regulatory pathway, and reimbursement negotiation leverage. Segmentation reveals how nucleic acid platforms displace protein-based interventions across clinical development pipelines.
Product Type:
Gene therapy commands premium valuation tiers due to curative intent and single-administration protocols, while RNA therapy segments accelerate through splice-switching oligonucleotide platforms that correct the LMNA G608G mutation at the transcript level.
- Gene Therapy:Adeno-associated viral vectors deliver functional LMNA constructs to vascular endothelium and skeletal muscle. Demand concentrates in pediatric specialty clinics across the United States and Germany, where regulatory familiarity with orphan gene therapy protocols compresses approval timelines.
- RNA Therapy:Antisense oligonucleotides enable exon 11 skipping to eliminate progerin production. Ionis Pharmaceuticals anchors clinical progress through established splice-switching chemistry, with manufacturing partnerships expanding capacity for ultra-orphan batch scales.
- Small Molecules:Farnesyltransferase inhibitors like lonafarnib retain established safety profiles but face margin compression as transcript-targeting modalities demonstrate superior mechanistic precision.
- Protein Replacement:Recombinant lamin A protein supplementation represents earlier-generation intervention, with limited pipeline investment as nucleic acid platforms advance.
Mature deployment sits with small molecules. Newer deployment is concentrated in RNA therapy.
Delivery Mode:
Route selection balances bioavailability requirements against patient compliance in pediatric populations, with vascular access limitations shaping protocol design for young children.
- Intravenous:Enables systemic distribution of gene therapy vectors and large-molecule biologics. Hospital-based administration dominates due to infusion monitoring requirements and vascular access challenges in pediatric patients.
- Subcutaneous:Supports sustained-release depot formulations and repeated dosing of oligonucleotides. Home care settings in the United States increasingly accommodate trained caregiver administration, reducing clinic burden.
- Oral:Small molecule farnesyltransferase inhibitors leverage familiar administration, though gastrointestinal absorption variability complicates dosing precision.
- Inhalation:Targets pulmonary vascular pathology directly, with specialized nebulizer protocols under investigation for localized progerin reduction in lung tissue.
Volume concentration favors intravenous administration. Steepest expansion trajectory is occurring in subcutaneous delivery.
End User:
Treatment site selection reflects therapy complexity, monitoring intensity, and geographic patient distribution across sparse HGPS populations.
- Specialty Clinics:Concentrated expertise in Boston, Houston, and San Diego coordinates natural history data collection and protocol enrollment. The Progeria Research Foundation's clinical trial consortium eliminates sponsor site-selection overhead through pre-activated infrastructure.
- Hospitals:Academic medical centers manage gene therapy administration with intensive care backup for vector-related adverse events. Pediatric hematology-oncology units often host HGPS protocols due to existing vascular access capabilities.
- Research Institutions:NIH Rare Diseases Clinical Research Network sites standardize biomarker collection and surrogate endpoint validation.
- Home Care:Subcutaneous oligonucleotide regimens enable direct-to-patient delivery, though nursing support requirements limit expansion to trained caregiver households.
Clinical trial volume concentrates in specialty clinics. Commercial expansion is shifting toward hospital outpatient settings.
Clinical Stage:
Development phase distribution indicates modality maturity and regulatory engagement intensity across therapeutic platforms.
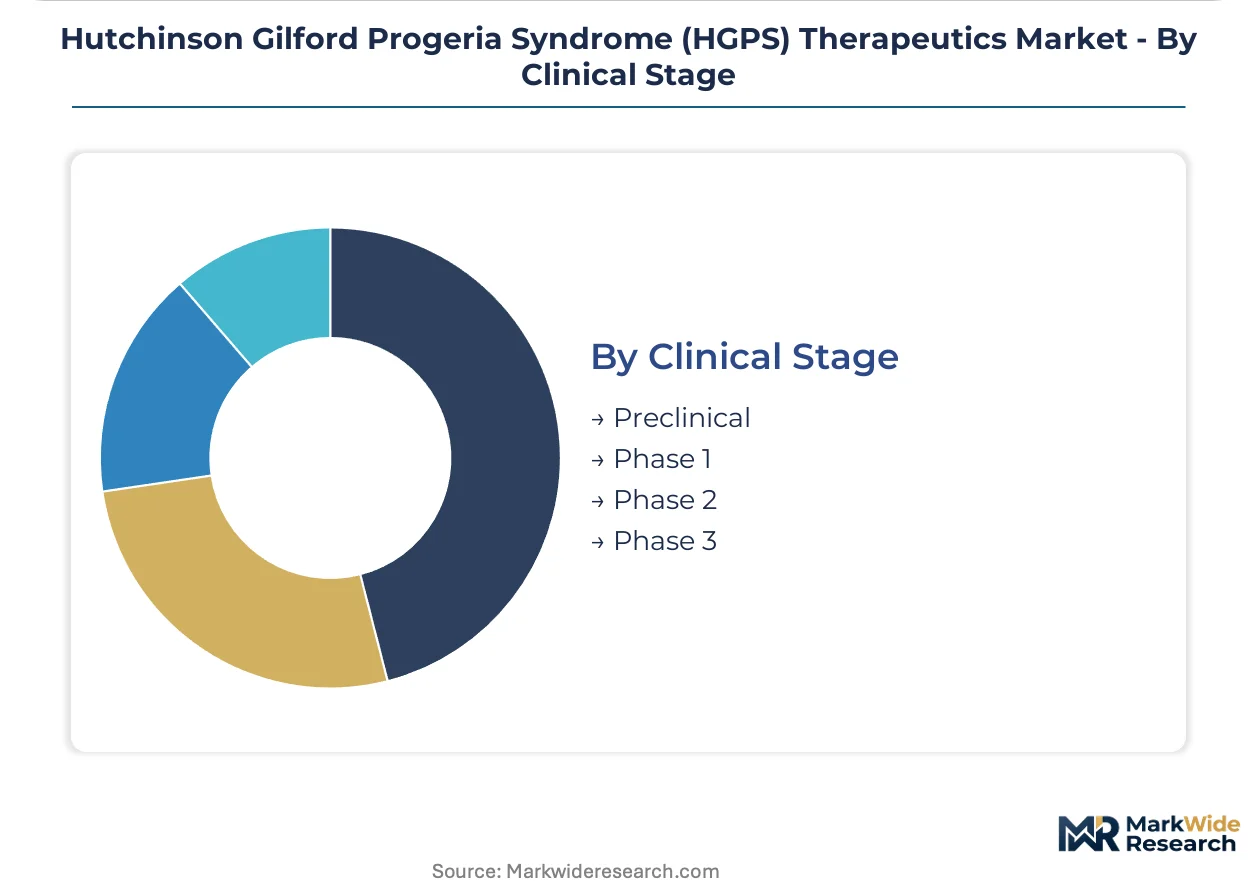
- Phase 2:Splice-switching oligonucleotides and gene therapy candidates dominate active enrollment, with surrogate endpoint validation enabling compressed duration through natural history data integration.
- Phase 1:Novel delivery technologies and next-generation vectors undergo safety evaluation in adult volunteers before pediatric transition.
- Phase 3:Lonafarnib combination studies and confirmatory gene therapy trials target mortality endpoints with extended follow-up periods.
- Preclinical:CRISPR-based editing and base correction platforms address LMNA variant heterogeneity beyond the G608G mutation.
Resource concentration sits with Phase 2 programs. Pipeline replenishment is accelerating in preclinical gene editing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric specialty clinics in the United States, Germany, and Japan concentrate the known patient population and clinical trial infrastructure for HGPS therapeutics. Regulatory incentives in these markets accelerate orphan drug development timelines while manufacturing capabilities cluster in specific biotech corridors.
United States
The FDA Rare Pediatric Disease Priority Review Voucher program drives sponsor engagement by awarding transferable vouchers worth substantial market value upon approval. Boston, Houston, and San Diego host the Progeria Research Foundation's clinical trial consortium, streamlining patient enrollment and natural history data collection. BioMarin Pharmaceutical operates dedicated gene therapy production suites in California, anchoring viral vector manufacturing capacity.
Germany
EMA Committee for Orphan Medicinal Products accelerated assessment pathways reduce regulatory fees and provide protocol assistance for HGPS sponsors. REACH and RoHS compliance requirements reshape viral vector production inputs, forcing substitution of legacy reagents with certified alternatives. Munich and Heidelberg concentrate pediatric specialty expertise, with university hospitals coordinating European protocol enrollment.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's Innovation Passport designation facilitates early engagement for gene therapy developers targeting ultra-orphan indications. London and Cambridge anchor nucleic acid manufacturing partnerships, with contract development organizations expanding capacity for splice-switching oligonucleotide production. The NHS Highly Specialised Services framework centralizes treatment access for the small national patient cohort.
Switzerland
Swissmedic's pediatric investigation plan harmonization with EMA standards reduces duplicate regulatory burden for sponsors pursuing concurrent European and Swiss approvals. Basel and Zurich host established rare disease commercial infrastructure, with pharmaceutical companies leveraging existing genetic disease portfolios for HGPS program expansion. The country's centralized healthcare system enables rapid reimbursement negotiation for ultra-orphan therapies.
Japan
PMDA's Sakigake designation system prioritizes review of innovative regenerative medicines and gene therapies, compressing approval timelines for HGPS candidates. Tokyo and Osaka concentrate the national patient registry infrastructure, with university hospitals standardizing biomarker collection protocols. The Ministry of Health, Labour and Welfare's orphan drug subsidy program covers development costs for sponsors addressing diseases with fewer than 50,000 patients nationally.
Hutchinson Gilford Progeria Syndrome (HGPS) Therapeutics Market Competitive Landscape
Strategic partnerships dominate the current landscape as sponsors access specialized manufacturing capabilities and patient registries. The vendor base clusters around three archetypes: established rare disease platforms with nucleic acid expertise, gene therapy specialists with viral vector production assets, and research foundations bridging philanthropic funding with clinical infrastructure. Competitive positioning hinges on manufacturing scale flexibility, regulatory pathway efficiency, and natural history data access rather than traditional commercial scale advantages.
Among established rare disease platforms, BioMarin Pharmaceutical, Ionis Pharmaceuticals, and BridgeBio Pharma occupy distinct positions within the competitive hierarchy. BioMarin exemplifies the integrated manufacturing archetype through its dedicated California production infrastructure. Ionis anchors the antisense chemistry specialization, leveraging established splice-switching platforms for transcript-level intervention. BridgeBio represents the targeted oncology and genetic disease repurposing model, applying existing infrastructure toward HGPS development. Each company illustrates how ultra-orphan therapeutic development rewards platform breadth and regulatory experience over therapeutic area concentration.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| BioMarin Pharmaceutical Inc. |
| Eiger BioPharmaceuticals, Inc. |
| Sangamo Therapeutics, Inc. |
| BridgeBio Pharma, Inc. |
| PRG Science & Technology |
| Ultragenyx Pharmaceutical Inc. |
| The Progeria Research Foundation |
| Ionis Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
Viral vector production costs cascade through three-tier pricing stratification across premium gene therapy, standard RNA therapy, and economy small molecule tiers, with California and Massachusetts manufacturing clusters extracting margin premiums from sponsors locked into single-source supply agreements for AAV serotypes.
Pricing Analysis
Volume concentration in small molecule farnesyltransferase inhibitors like lonafarnib compresses margins through generic substitution pressure, while gene therapy segments command ultra-premium positioning justified by curative intent and single-administration protocols. Price differentiation hinges on mechanistic precision—transcript-targeting modalities versus symptomatic management—and manufacturing scale, with autologous production justifying higher tiers than allogeneic alternatives. Pricing pressure stems from reimbursement negotiation constraints in European centralized health systems, where NICE and IQWiG assessments scrutinize cost-effectiveness thresholds. Pediatric specialty clinics demonstrate lowest price sensitivity due to philanthropic funding buffers, while hospital outpatient settings face tightening procurement budgets.
Supply Chain Analysis
REACH and RoHS compliance mandates in the European Union are forcing substitution of legacy reagents with certified alternatives, reshaping sourcing decisions for viral vector manufacturers. Supply concentrates in the United States, Germany, and Switzerland, with plasmid DNA, cell culture media, and AAV serotype-specific packaging lines drawing from concentrated biotech corridors. Single-source vulnerability pervades AAV9 and AAV8 capsid supply, where patent thickets and trade-secret manufacturing know-how create unsubstitutable dependencies. Distribution runs through direct-to-clinic cold chain logistics for gene therapy, while subcutaneous oligonucleotides enable pharmacy-benefit-manager channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into viral vector manufacturing and captive plasmid supply represents the decisive competitive lever in this market, with sponsors racing to secure production autonomy as capacity bottlenecks intensify.
For Market Incumbents: Hedge against antisense oligonucleotide substitution by securing exclusive access to The Progeria Research Foundation's natural history database, while expanding California manufacturing suites to accommodate single-patient-scale batch flexibility. Gene therapy talent scarcity at contract manufacturers like Catalent and Thermo Fisher threatens production timelines, making in-house process development capabilities essential for regulatory submission pacing. For New Entrants and Emerging Players: Home care administration of subcutaneous splice-switching therapies offers the most penetrable white space, as trained caregiver protocols reduce clinic burden and unlock reimbursement advantages through reduced site-of-care costs. Target EMA accelerated assessment pathways for European market entry, leveraging reduced fee structures and protocol assistance that compress development timelines relative to FDA routes. For Investors and Strategic Acquirers: Distressed-cycle entries favor antisense chemistry platforms with validated splice-switching mechanisms in the United States, where FDA Rare Pediatric Disease Priority Review Voucher monetization provides liquidity events independent of commercial scale. Platform breadth and regulatory experience outweigh therapeutic area concentration in ultra-orphan valuation frameworks. The signal to watch is EMA gene therapy manufacturing guideline finalization, which will reshape cost structures and approval timelines for viral vector-dependent programs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system bioreactor investments reduce contamination risk while enabling ultra-orphan batch economics. |
| Regulatory Approval Pathway | FDA Rare Pediatric Disease Priority Review Voucher capture accelerates sponsor liquidity through transferable voucher monetization. |
| Pipeline Diversification | LMNA variant heterogeneity programs address non-G608G mutations, fragmenting development across smaller subpopulations. |
| Strategic Partnership | Philanthropic-industrial consortiums with The Progeria Research Foundation compress protocol initiation timelines. |
| Clinical Trial Advancement | Surrogate endpoint validation through standardized patient registries shortens Phase 3 duration. |
Research Methodology
Multi-period observation of gene therapy manufacturing capacity utilization, antisense oligonucleotide clinical trial enrollment velocity, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with drug development executives at rare disease sponsors, regulatory affairs leads at FDA and EMA, formulary directors at major payers, and hospital procurement managers at pediatric specialty clinics. Secondary validation drew from FDA Office of Orphan Products Development filings, EMA Committee for Orphan Medicinal Products assessments, ClinicalTrials.gov protocol registrations, and The Progeria Research Foundation natural history publications. Bottom-up patient pool sizing and top-down therapeutic modality valuation triangulated market estimates.
Input-output matrices mapped gene therapy, RNA therapy, small molecule, and protein replacement segments across treatment lines, administration routes, and regional regulatory clusters, with CAGR derivation reflecting modality-specific approval probability weighting and manufacturing scale constraints. Patient identification rate assumptions, vector production yield curves, and splice-switching chemistry manufacturing cost trajectories fed scenario-based projections across the analysis window.
Revisions become necessary when FDA CBER gene therapy manufacturing guidelines finalize with extended characterization requirements, when EMA REACH compliance mandates force reagent substitution disrupting viral vector supply, or when philanthropic funding flows shift toward competing ultra-orphan indications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market