
 Dissolving Microneedle Eye Patch Market | 2026-2036
Dissolving Microneedle Eye Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolving Microneedle Eye Patch Market Insights
Med-spa and aesthetic dermatology channels is shifting toward at-home-compatible formats that bridge professional efficacy with consumer convenience. Raphas Co. Ltd. leverages its Korean manufacturing base to dominate supply for Asian aesthetic chains. CosMED Pharmaceutical Co. Ltd. specializes in polymer science for controlled dissolution kinetics. Nissha Co. Ltd. anchors precision micro-molding capabilities that competing contract manufacturers struggle to replicate.
Dissolving microneedle eye patches incorporate biocompatible matrices of hyaluronic acid, polyvinylpyrrolidone, or polylactic acid formed into conical projections measuring 200-1000 micrometers that fully degrade within 15-30 minutes of dermal application, delivering active compounds past the stratum corneum barrier for periorbital indications. Single-use formats lead current revenue due to hygiene protocols in clinical settings, while home-care demand is pulling multi-use and customizable configurations into faster development cycles. Anti-aging therapy areas command the deepest margin pools, though drug-delivery applications for ophthalmic conditions represent the most technically differentiated expansion vector.
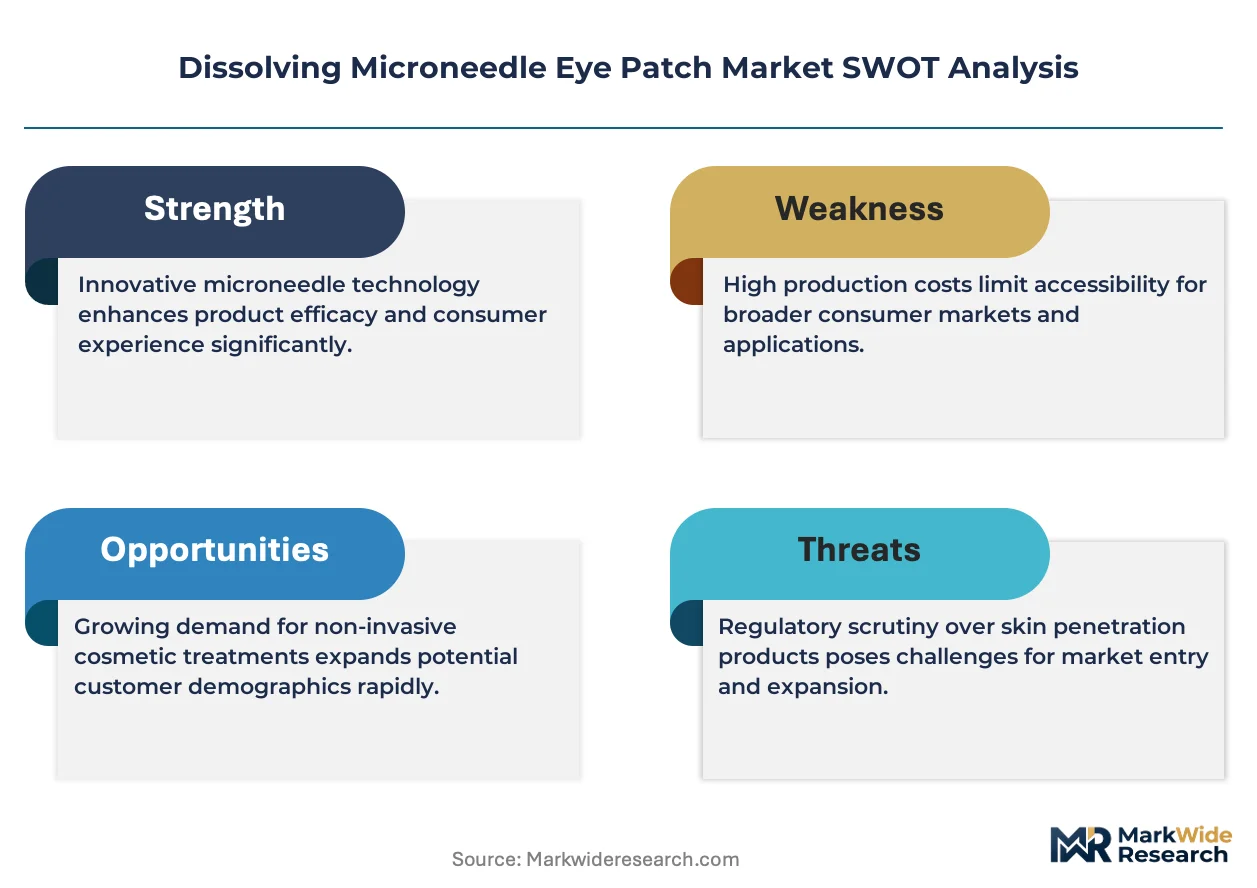
FDA combination product regulations and EMA medical device directives shape formulation stability requirements and clinical evidence thresholds for commercial approval, while ISO 10993 biocompatibility standards govern polymer selection and cytotoxicity testing protocols. Japan's PMDA maintains distinct dissolution-rate documentation requirements that filter out under-validated entrants. Stakeholders must monitor evolving pharmacovigilance expectations for consumer-grade microneedle platforms as regulatory boundaries between cosmetics and medical devices continue to tighten across major markets.
Market Dynamics
Biocompatible polymer formulation science is compressing development cycles for dissolving microneedle platforms, as Seoul and Tokyo dermatology clinics demand faster clinical validation turnaround for periorbital rejuvenation protocols.
Growth Catalysts
- FDA combination product pathway:Streamlined 510(k) and PMA routes for device-drug hybrids accelerate commercial entry timelines for hyaluronic acid matrix developers targeting US aesthetic medicine channels.
- South Korea aesthetic corridor concentration:Dense clustering of med-spa chains and dermatology clinics in Seoul generates concentrated demand pull for at-home-compatible dissolving formats.
- Controlled dissolution kinetics:Advances in polylactic acid and polyvinylpyrrolidone blend engineering enable 15-30 minute degradation profiles that match clinical hygiene protocols.
Market Restraints
- Polymer feedstock concentration:Medical-grade hyaluronic acid supply concentrates among three Japanese and Korean specialty chemical producers, creating input cost volatility for patch manufacturers.
- PMDA dissolution-rate documentation:Japan's pharmaceutical regulator mandates extensive kinetic validation studies that extend approval timelines and filter out under-capitalized entrants.
- Topical retinoid substitution:Established periorbial anti-aging creams and serums retain physician familiarity and lower patient education burdens in conservative dermatology practices.
Strategic Opportunities
- Ophthalmic drug-delivery expansion:Glaucoma and dry-eye therapeutic applications represent technically differentiated white space beyond cosmetic rejuvenation, with higher reimbursement potential.
- EMA medical device directive harmonization:Streamlined CE marking pathways across EU member states create regulatory tailwinds for biocompatible polymer platforms with ISO 10993 certification.
- Direct-to-consumer channel development:Subscription-based home delivery models bypass clinical gatekeepers and capture margin pools previously allocated to aesthetic dermatology practices.
Industry Challenges
- Micro-molding talent scarcity:Precision conical projection engineering requires rare combinations of polymer science and MEMS fabrication expertise that competing contract manufacturers struggle to source.
- ISO 10993 cytotoxicity testing backlog:Biocompatibility certification queues at accredited laboratories extend product launch timelines and compress R&D budget efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolving Microneedle Eye Patch Market |
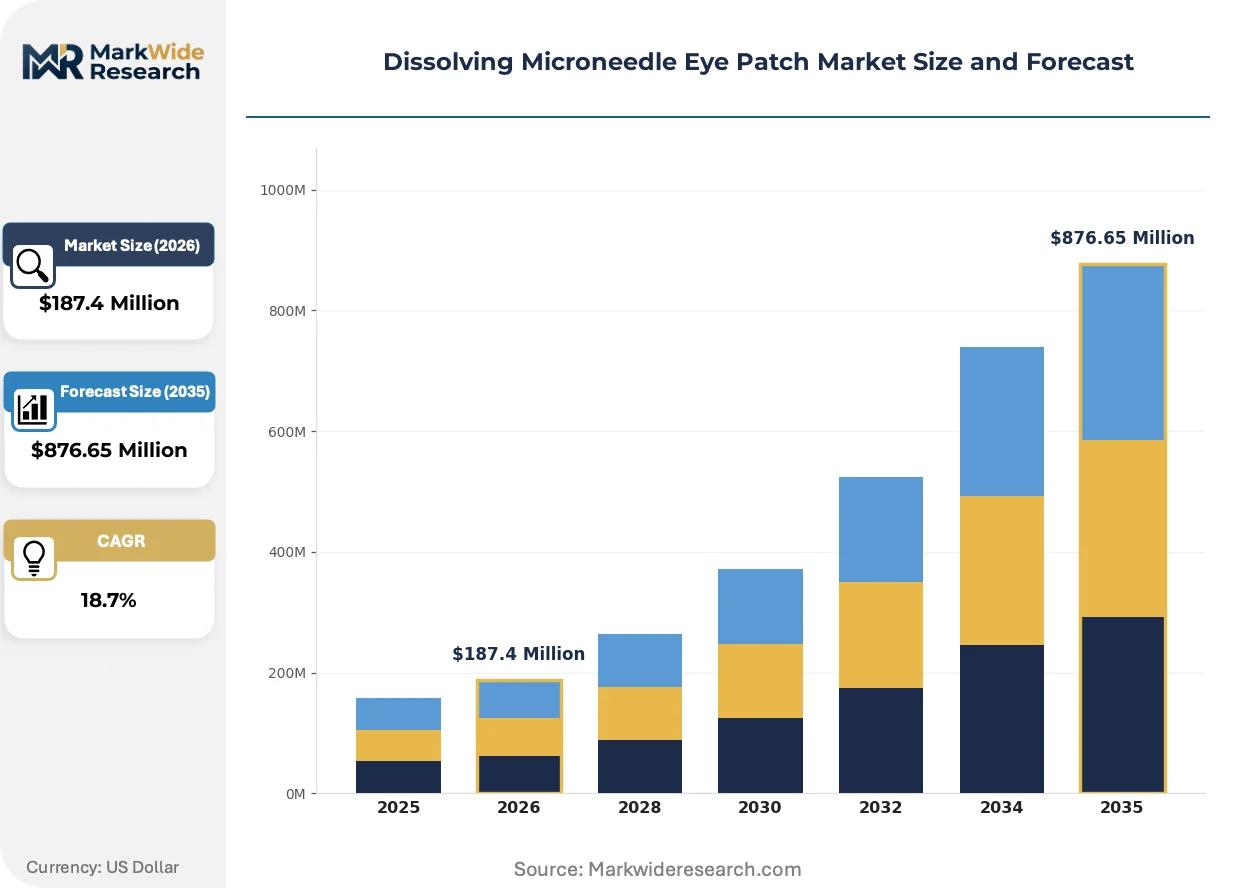
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Multi Use, Customizable, Pre-filled Therapy Area: Anti-Aging, Dry Eye, Anesthesia, Drug Delivery End User: Hospitals, Clinics, Home Care, Research Institutions Distribution Channel: Online Retail, Pharmacies, Hospital Supply, Direct Sales |
| Companies Covered | Raphas Co. Ltd., PCA SKIN, CosMED Pharmaceutical Co. Ltd., Micropoint Technologies, Vaxess Technologies, Inc., Micron Biomedical, Inc., Skyn ICELAND, QuadMedicine, Nissha Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolving Microneedle Eye Patch Market Trends and Innovations
Active pharmaceutical ingredient integration into dissolving matrices is reshaping competitive positioning, as manufacturers differentiate beyond cosmetic hyaluronic acid delivery into therapeutic ophthalmic applications with higher technical barriers.
Silicon micro-molding replication technology is converging with bioresorbable polymer casting processes to enable sub-200 micrometer tip geometries. Seoul-based aesthetic chains are piloting these formats for enhanced stratum corneum penetration. The structural consequence is compressing the efficacy gap between professional microneedling devices and consumer-grade dissolving patches.
Japan's PMDA revised guidance on combination product dissolution kinetics now requires real-time degradation monitoring data for ophthalmic indications. This elevates clinical evidence thresholds for commercial approval. European developers with EMA MDR pre-certification are responding by front-loading kinetic validation studies to maintain competitive parity in Asian regulatory submissions.
Subscription-based replenishment models are displacing single-unit retail purchases in premium at-home segments. Aesthetic dermatology practices in Tokyo and Seoul are unbundling professional treatment protocols into monthly patch deliveries. This pattern is most visible in South Korea's Gangnam district med-spa networks, where patient retention metrics now prioritize recurring revenue over per-visit procedures.
Dissolving Microneedle Eye Patch Market Segmentation
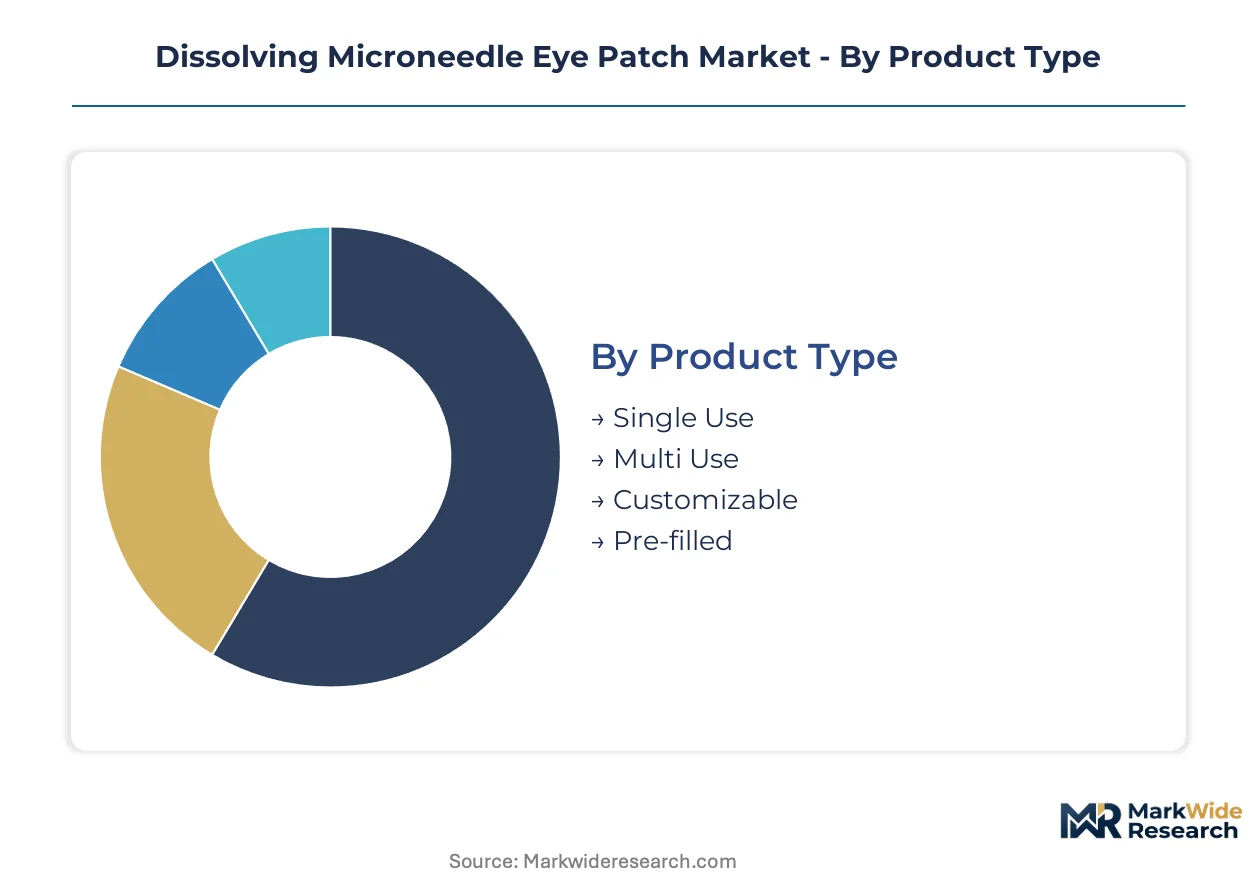
Dissolving microneedle eye patch manufacturers calibrate product architectures against distinct usage protocols, therapeutic targets, and procurement channels. Segment boundaries increasingly blur as clinical formats migrate toward at-home compatibility and subscription replenishment models.
Product Type:
Upgrade cycles accelerate as dermatology practices replace legacy formats with formats matching evolving hygiene standards and patient convenience expectations.
- Single Use:Individual sterile packaging with hyaluronic acid or polylactic acid matrices engineered for complete dissolution within 15-30 minutes. Seoul med-spa chains favor these formats for periorbital rejuvenation protocols requiring zero cross-contamination risk.
- Multi Use:Rechargeable or refillable patch systems with replaceable microneedle arrays. Home-care demand in Tokyo's aesthetic medicine corridor drives development of sanitizable bases with disposable tip cartridges.
- Customizable:Modular platforms allowing needle density, active compound loading, and dissolution-rate adjustments. Research institutions and premium dermatology clinics specify these configurations for protocol personalization.
- Pre-filled:Factory-loaded active formulations eliminating compounding steps at point of care. Pharmacies and hospital supply channels prefer these for inventory simplification and dosing standardization.
Volume placements concentrate in Single Use formats; the faster expansion belongs to Multi Use configurations bridging professional efficacy with consumer convenience.
Therapy Area:
Application breadth spans cosmetic rejuvenation through therapeutic intervention, with reimbursement potential determining margin architecture across segments.
- Anti-Aging:Hyaluronic acid and peptide delivery for periorbital wrinkle reduction and skin elasticity restoration. Dermatology clinics in Seoul and Tokyo generate concentrated procedure volume for this indication.
- Drug Delivery:Ophthalmic therapeutic applications including glaucoma medication and anti-inflammatory compounds. PMDA and FDA combination product pathways elevate technical barriers and exclusivity periods for developers.
- Dry Eye:Lubricating agent and tear-film stabilizer administration through conjunctival-adjacent microneedle application. Japanese ophthalmology research clusters pilot these protocols for chronic condition management.
- Anesthesia:Pre-procedural numbing agent delivery for ocular surface interventions. Hospital surgical suites specify these for patient comfort enhancement in cataract and refractive procedures.
Revenue depth pools in Anti-Aging applications; the steepest expansion trajectory belongs to Drug Delivery as therapeutic indications secure regulatory validation.
End User:
Customer-type stratification reflects divergent purchasing authority, with clinical gatekeepers ceding ground to direct-to-consumer channels.
- Hospitals:Surgical and ophthalmology departments procuring through centralized supply chains with ISO 10993 biocompatibility certification requirements.
- Clinics:Aesthetic dermatology and ophthalmology practices in Seoul's Gangnam district and Tokyo's Shibuya corridor driving format innovation through protocol unbundling.
- Home Care:Individual consumers accessing subscription replenishment models bypassing traditional clinical distribution.
- Research Institutions:Academic medical centers and contract research organizations validating dissolution kinetics and therapeutic efficacy for regulatory submission packages.
Procurement volume concentrates in Clinics; the fastest share gain belongs to Home Care as direct-to-consumer channels disintermediate aesthetic medicine gatekeepers.
Distribution Channel:
Channel configuration determines pricing transparency and margin capture, with digital platforms compressing traditional wholesale markups.
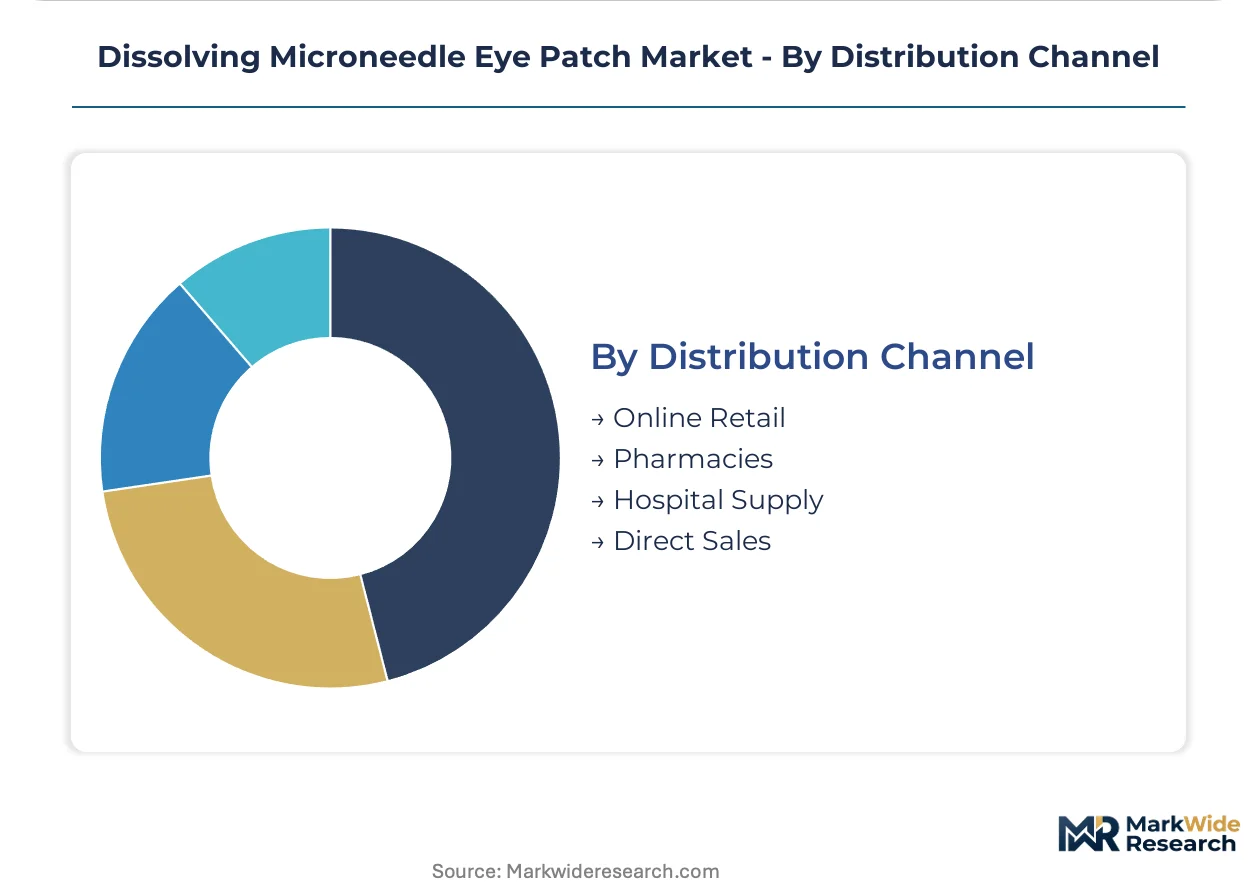
- Online Retail:E-commerce platforms and brand-direct subscription services capturing recurring revenue streams from at-home users.
- Pharmacies:Retail and hospital pharmacy networks stocking pre-filled formats with standardized dosing for consumer self-selection.
- Hospital Supply:Group purchasing organizations and centralized procurement systems serving institutional buyers with volume contracting.
- Direct Sales:Manufacturer field forces and clinical specialists calling on dermatology practices and ophthalmology departments for protocol adoption.
Transaction volume concentrates in Hospital Supply; the most rapid channel expansion belongs to Online Retail as subscription models reshape patient retention economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Free Economic Zone in Incheon accelerates concentration of biocompatible polymer manufacturing for dissolving microneedle platforms. Tax incentives for medical device exporters draw formulation scientists and precision molding specialists into clustered facilities near Seoul's aesthetic medicine corridor.
United States
FDA combination product pathways for device-drug hybrids streamline commercial entry for hyaluronic acid matrix developers. The 510(k) and PMA routes compress approval timelines for periorbital rejuvenation indications. Boston and San Francisco dermatology research clusters pilot controlled dissolution kinetics for ophthalmic therapeutic applications.
South Korea
Seoul's Gangnam district med-spa networks generate concentrated procedure volume for single-use anti-aging formats. MFDS maintains distinct documentation requirements for polymer biocompatibility certification that filter under-validated entrants. Incheon Free Economic Zone manufacturers supply Asian aesthetic chains with at-home-compatible multi-use configurations.
Japan
PMDA dissolution-rate documentation mandates extend approval timelines for therapeutic ophthalmic indications. METI funding for advanced medical device development supports precision micro-molding capabilities in Nagoya and Osaka. Tokyo's Shibuya corridor dermatology practices unbundle professional protocols into subscription-based home delivery models.
Germany
EMA Medical Device Regulation harmonization creates CE marking tailwinds for ISO 10993-certified polymer platforms. REACH compliance requirements shape hyaluronic acid feedstock sourcing from specialty chemical producers. Munich and Heidelberg aesthetic medicine clusters adopt customizable patch configurations for protocol personalization.
United Kingdom
MHRA post-Brexit regulatory autonomy enables streamlined market access for bioresorbable polymer eye patches. London's Harley Street dermatology practices drive demand for pre-filled factory-loaded formats. Oxford and Cambridge research institutions validate dissolution kinetics for regulatory submission packages targeting EMA and FDA pathways.
Dissolving Microneedle Eye Patch Market Competitive Landscape
Top-tier vendors anchor precision polymer science and micro-molding capabilities, while mid-scale specialists concentrate on regional distribution and at-home format development. The vendor base stratifies across three tiers: integrated manufacturers controlling formulation-to-fabrication workflows, regional contract producers serving aesthetic medicine chains, and emerging entrants targeting direct-to-consumer subscription channels. Two dominant competitive moves reshape positioning: backward integration into medical-grade hyaluronic acid supply chains, and strategic partnerships with Seoul and Tokyo dermatology practices for protocol co-development.
Within the integrated manufacturing tier, Raphas Co. Ltd. and CosMED Pharmaceutical Co. Ltd. exemplify Korean and Japanese archetypes respectively, occupying positions that span biocompatible polymer formulation through precision conical projection engineering. Nissha Co. Ltd. anchors the precision micro-molding specialization vector, representing capabilities that competing contract manufacturers struggle to replicate. These three entities collectively illustrate how geographic proximity to Seoul and Tokyo aesthetic medicine corridors translates into sustained supply relationships with high-volume clinical adopters.
| Leading Market Players |
|---|
| Raphas Co. Ltd. |
| PCA SKIN |
| CosMED Pharmaceutical Co. Ltd. |
| Micropoint Technologies |
| Vaxess Technologies, Inc. |
| Micron Biomedical, Inc. |
| Skyn ICELAND |
| QuadMedicine |
| Nissha Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Silicon micro-molding replication technology convergence with bioresorbable polymer casting compresses unit economics while concentrating production capability among ISO 10993-certified facilities in South Korea and Japan. This dual effect elevates pricing power for qualified manufacturers while squeezing margin pools for undifferentiated contract producers.
Pricing Analysis
Short lead-time premiums for medical-grade hyaluronic acid procurement drive pricing stratification across premium, standard, and economy tiers. ISO 10993 certification tier and volume scale differentiate contract manufacturers serving Seoul dermatology chains from spot-market suppliers. Cost compression in economy tiers intensifies due to polymer feedstock volatility among Japanese specialty chemical producers. Hospital supply channels exhibit lowest price sensitivity; direct-to-consumer subscription buyers demand volume discounts.
Supply Chain Analysis
ISO 10993 biocompatibility certification gates upstream access, filtering formulation scientists and precision molding specialists into qualified supplier pools. Medical-grade hyaluronic acid production concentrates in Japan and South Korea; polylactic acid feedstock draws from German and US specialty chemical producers. Single-source vulnerability runs through Japanese polymer suppliers subject to METI export documentation requirements. Distribution runs through hospital group purchasing organizations and aesthetic dermatology practice networks before reaching direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around backward-integrated manufacturers controlling polymer formulation through precision micro-molding, with PMDA dissolution-rate documentation requirements forcing under-capitalized entrants toward contract manufacturing roles.
For Market Incumbents: Acquire medical-grade hyaluronic acid supply contracts to secure input cost stability against Japanese feedstock volatility. Expand precision micro-molding capacity in Incheon Free Economic Zone to capture Seoul med-spa chain volume. Defend against topical retinoid substitution threat by embedding patches into unbundled subscription protocols that lock patient retention. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for bypassing clinical gatekeeper economics. Target home-care segments in Tokyo's Shibuya corridor where aesthetic medicine practices already pilot replenishment models. Pursue ophthalmic drug-delivery applications for glaucoma therapeutics, where FDA combination product pathways create exclusivity windows. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated polymer science platforms seeking precision micro-molding capabilities. Long-term viability favors developers with captive ISO 10993 certification and PMDA submission experience. Watch for MFDS biocompatibility documentation tightening as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hyaluronic Acid Supply | Captive feedstock access insulates margin pools from Japanese producer pricing volatility. |
| PMDA Dissolution-Rate Documentation Submission | Regulatory validation in Japan creates barrier against under-capitalized competitors in ophthalmic segments. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models disintermediate Seoul and Tokyo aesthetic dermatology practice gatekeepers. |
| Precision Micro-Molding Capacity Expansion | Sub-200 micrometer tip geometries compress efficacy gaps with professional microneedling devices. |
| Ophthalmic Therapeutic Indication Development | Glaucoma and dry-eye applications unlock reimbursement potential beyond cosmetic rejuvenation margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this dissolving microneedle eye patch market assessment. Primary interviews with dermatology clinic procurement managers, biomedical engineers at precision micro-molding facilities, regulatory affairs specialists navigating FDA combination product pathways, and GPO contracts managers at hospital systems combined with FDA 510(k) and PMA filings, PMDA submission databases, MFDS biocompatibility certifications, and ISO 10993 laboratory accreditation records. Bottom-up patch volume estimates from Seoul and Tokyo aesthetic medicine corridors triangulated against top-down polymer feedstock demand projections.
Reconciliation of manufacturer shipment data, import-export flows, and channel inventory positions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (single use, multi use, customizable, pre-filled), therapy area (anti-aging, drug delivery, dry eye, anesthesia), end user (hospitals, clinics, home care, research institutions), and distribution channel (online retail, pharmacies, hospital supply, direct sales). CAGRs derived from curve-fitting historical adoption patterns against regulatory approval timelines and polymer formulation innovation cycles. Industry-specific inputs incorporated PMDA dissolution-rate documentation requirements and EMA MDR harmonization progress.
The model holds under stable regulatory interpretation of combination product classifications; deviation in FDA or PMDA guidance on microneedle cosmetic-medical device boundaries would shift commercial entry timelines and revenue recognition patterns. Forecasts reflect assumptions regarding polymer biocompatibility certification queue durations and hyaluronic acid feedstock supply continuity. A model refresh is warranted upon material change in ISO 10993 cytotoxicity testing laboratory capacity or METI export documentation requirements for Japanese polymer producers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Clear Aligner Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
APAC AMH Market
Medical Devices
Plethysmograph Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Americas Wearable Medical Device Market