
 Glanzmann Thrombasthenia Market | 2026-2036
Glanzmann Thrombasthenia Market Size, Share, and Industry Trends Forecast 2026-2036
Glanzmann Thrombasthenia Market Foresight
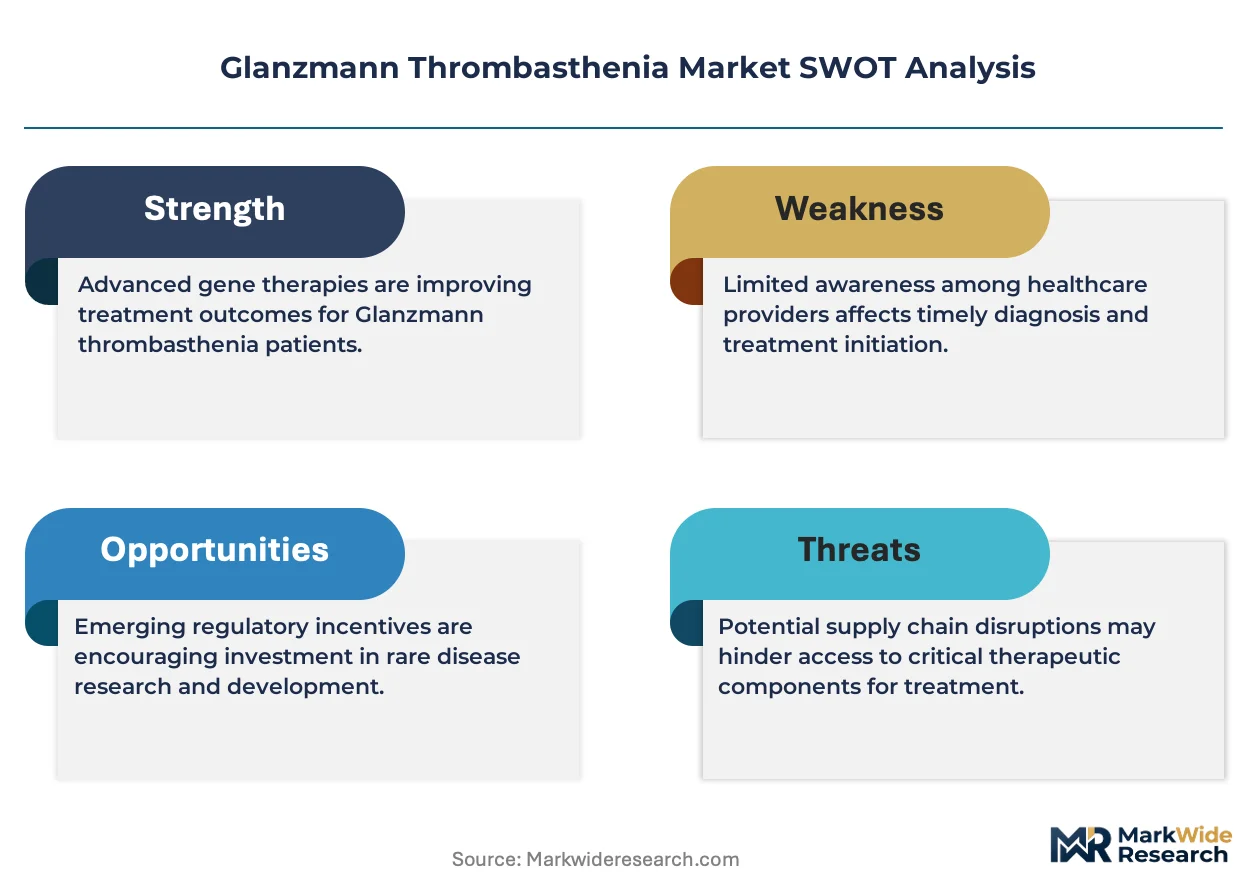
Gene therapy vector engineering is rewriting how Glanzmann thrombasthenia treatments move from plasma-derived products toward curative modalities. CSL Behring leverages its plasma fractionation infrastructure to sustain global supply of platelet transfusion products. Hemab Therapeutics specializes in recombinant approaches that differentiate its pipeline from conventional factor replacement strategies.
Glanzmann thrombasthenia is a rare autosomal recessive bleeding disorder caused by defects in the ITGA2B or ITGB3 genes encoding the αIIbβ3 integrin receptor, resulting in absent or dysfunctional platelet aggregation and severe mucocutaneous hemorrhage. Recombinant Factor VIIa dominates acute bleeding management due to its bypass mechanism and established hemostatic efficacy, while platelet transfusion retains critical utility in perioperative settings despite alloimmunization risks. Hematology centers represent the fastest-growing end user segment as centralized care models concentrate expertise and patient volume, whereas specialty clinics still occupy the largest share of routine chronic bleeding control visits.
FDA orphan drug designations and EMA's incentives for rare disease therapeutics shape clinical trial design and market access pathways for developers in this space. The European Medicines Agency's PRIority MEdicines scheme accelerates regulatory review timelines for innovative hemostatic therapies addressing unmet needs in inherited platelet disorders. Stakeholders must monitor gene therapy readouts from early-phase programs to assess whether curative approaches will displace chronic factor administration before committing manufacturing capacity.
Market Dynamics
Gene therapy vector engineering is compressing development timelines for curative Glanzmann thrombasthenia treatments, pulling investment away from chronic factor replacement manufacturing capacity as hematology centers anticipate one-time administration protocols.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate clinical trial enrollment for rare bleeding disorder therapies, reducing sponsor risk exposure in early-phase development.
- Hematology Center Consolidation:Centralized care models in Germany concentrate patient volume and expertise, creating referral networks that streamline access to recombinant factor therapies and specialized surgical support.
- Gene Therapy Manufacturing Maturation:Lentiviral and AAV vector production platforms achieve scalable yields, enabling dose supply for inherited platelet disorder programs previously constrained by batch capacity.
Market Restraints
- Plasma Supply Volatility:Fractionated plasma feedstock costs fluctuate with donor collection rates, compressing margins for platelet transfusion product manufacturers dependent on CSL Behring's global sourcing infrastructure.
- Alloimmunization Risk Ceiling:Repeated platelet transfusion exposure generates anti-HLA and anti-αIIbβ3 antibodies in 30-70% of patients, hard-limiting perioperative utility and forcing bypass agent dependence.
- EMA Regulatory Friction:Advanced therapy medicinal product classification requirements impose manufacturing consistency standards that delay gene therapy marketing authorization timelines relative to US pathways.
Strategic Opportunities
- Underpenetrated US Hematology Networks:Community-based bleeding disorder treatment centers in the American Midwest and Mountain West lack specialized coagulation expertise, creating whitespace for hub-and-spoke referral models.
- CRISPR-Based Ex Vivo Correction:Convergence of gene editing and induced pluripotent stem cell technology enables patient-derived megakaryocyte production, potentially eliminating vector-related immunogenicity concerns.
- PRIority MEdicines Scheme Access:EMA's PRIME designation provides accelerated assessment and enhanced regulatory dialogue for hemostatic therapies addressing unmet needs in inherited platelet disorders.
Industry Challenges
- Gene Therapy Talent Scarcity:Vector design, process development, and regulatory strategy functions command premium compensation, constraining sponsor hiring velocity in competitive biologics labor markets.
- Clinical Endpoint Standardization:Lack of harmonized bleeding assessment tools across FDA and EMA guidance complicates cross-regional trial design and label expansion strategies.
- Cold Chain Integrity Requirements:Recombinant Factor VIIa and platelet product stability demands strain distribution infrastructure, particularly in regions with intermittent cold storage reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glanzmann Thrombasthenia Market |
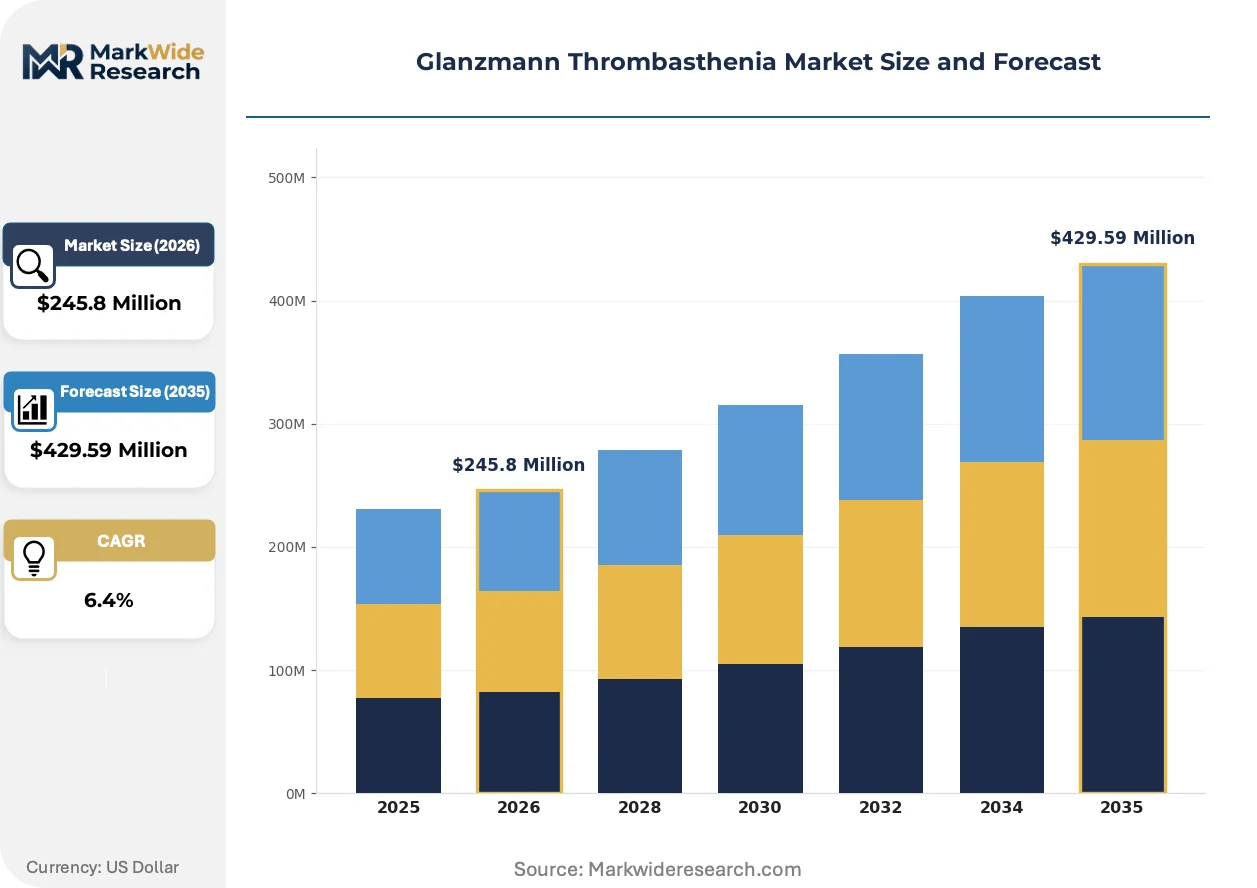
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet Aggregation Inhibitors, Recombinant Factor VIIa, Platelet Transfusion, Antifibrinolytics Therapy Area: Bleeding Disorder Management, Hemostasis Enhancement, Surgical Prophylaxis, Chronic Bleeding Control End User: Specialty Clinics, Hematology Centers, Diagnostic Laboratories, Blood Banks Delivery Mode: Intravenous, Subcutaneous, Oral, Transfusion-Based |
| Companies Covered | CSL Behring, Bayer, Novo Nordisk, Alnylam Pharmaceuticals, Bristol-Myers Squibb, Biogen, Pfizer, Hemab Therapeutics, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glanzmann Thrombasthenia Market Shifts & Advancements
Therapeutic modality selection in Glanzmann thrombasthenia is bifurcating between acute bypass agents and definitive genetic correction, with manufacturing investment decisions increasingly contingent on early-phase gene therapy readouts.
Lentiviral gene therapy is migrating from academic proof-of-concept studies toward commercial-scale production as Hemab Therapeutics and competing sponsors advance ITGA2B/ITGB3 transduction protocols. Hematology centers in Germany and the United States are pre-qualifying for gene therapy administration, building apheresis and cell processing capabilities ahead of regulatory approval. This technology transition is compressing projected revenue duration for recombinant factor VIIa franchises as curative modalities threaten to truncate chronic administration models.
EMA's PRIority MEdicines scheme and FDA's Regenerative Medicine Advanced Therapy designation create parallel accelerated pathways for hemostatic gene therapies, compressing development timelines by 12-24 months for qualified programs. These frameworks impose manufacturing consistency and long-term follow-up requirements that favor sponsors with established viral vector production infrastructure. European sponsors are responding by centralizing quality control operations in Germany and Switzerland to satisfy both agencies' inspection readiness standards.
Specialty pharmacy distribution is displacing hospital-based procurement for recombinant bypass agents as US payers consolidate bleeding disorder benefits under pharmacy benefit managers. This channel shift concentrates purchasing leverage with CVS Specialty and Accredo, compressing net pricing through rebate aggregation and preferred product tiering. The transition is most visible in Texas and Florida, where large integrated delivery networks have outsourced factor therapy management to contracted specialty pharmacies.
Glanzmann Thrombasthenia Market Segmentation
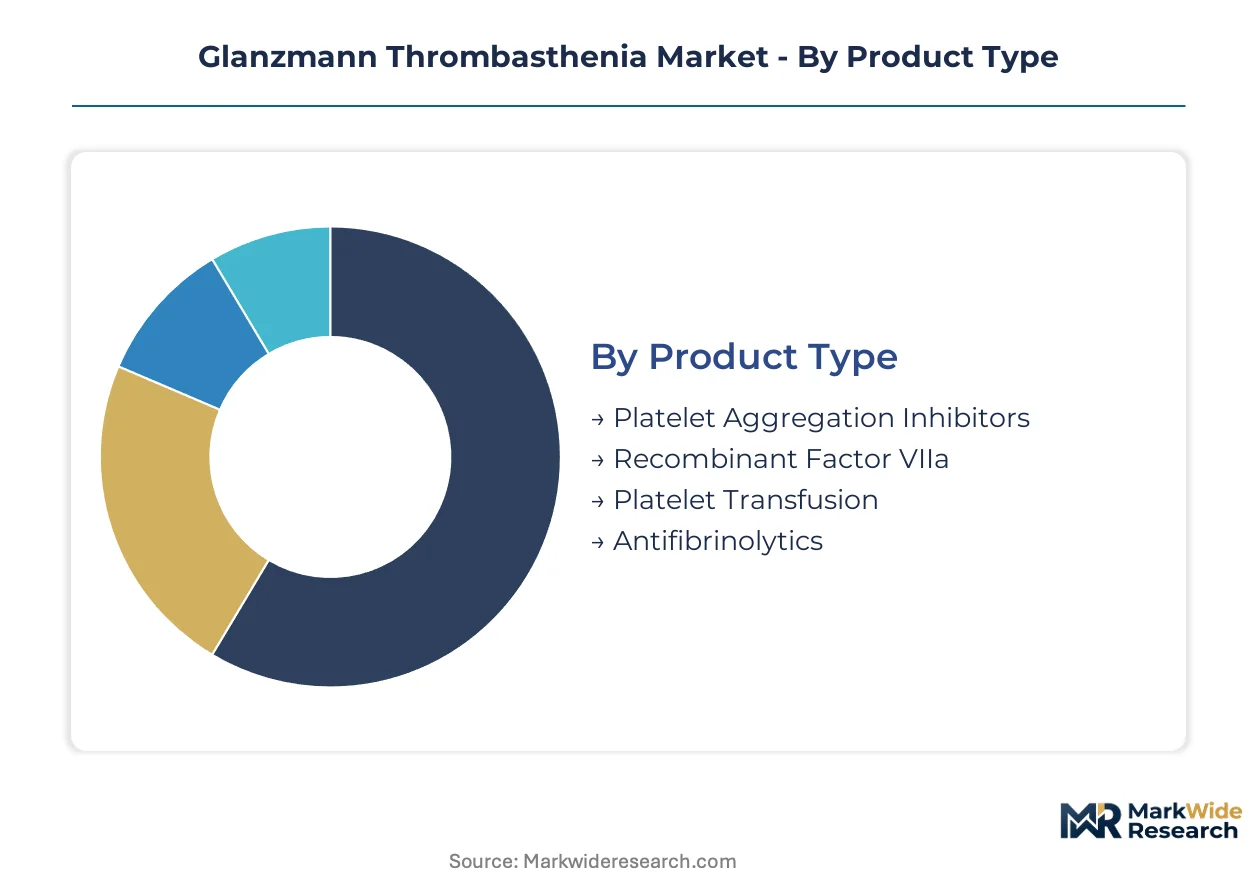
Therapeutic modality selection in Glanzmann thrombasthenia varies sharply by clinical context, with acute bleeding episodes demanding bypass agents while perioperative management requires platelet support. Segmentation reveals how treatment settings and administration routes shape procurement patterns and regulatory requirements across patient care pathways.
Product Type:
Cost tier differentiation separates chronic prophylaxis from emergency intervention products, with recombinant biologics commanding premium positioning against plasma-derived alternatives.
- Recombinant Factor VIIa:A bypass agent that activates coagulation directly at the tissue factor interface, circumventing the defective αIIbβ3 integrin pathway. Demand concentrates in US hematology centers managing acute mucocutaneous hemorrhage, driven by FDA orphan drug incentives accelerating clinical adoption. This segment holds installed capacity.
- Platelet Transfusion:Whole platelet units or apheresis concentrates providing functional αIIbβ3 receptors for perioperative hemostasis. German bleeding disorder networks utilize transfusion most intensively due to dense specialized treatment infrastructure and centralized apheresis capabilities. This segment is rotating up the share rankings.
- Platelet Aggregation Inhibitors:Agents modulating secondary hemostasis pathways in select clinical scenarios.
- Antifibrinolytics:Lysine analogs stabilizing fibrin clots in mucosal bleeding contexts.
Recombinant Factor VIIa holds installed capacity. Platelet transfusion is rotating up the share rankings.
Therapy Area:
Application urgency determines reimbursement tiering, with acute intervention commanding higher per-episode payment than chronic management protocols.
- Bleeding Disorder Management:Comprehensive care protocols addressing spontaneous hemorrhage, trauma-induced bleeding, and menstrual complications in inherited platelet disorders. US specialty clinics drive demand through consolidated bleeding disorder treatment networks. This segment holds installed capacity.
- Surgical Prophylaxis:Preoperative hemostatic optimization and intraoperative support for invasive procedures in thrombasthenia patients. German university hospitals concentrate perioperative case volume due to concentration of specialized coagulation expertise and integrated surgical services. This segment is rotating up the share rankings.
- Hemostasis Enhancement:Adjunctive therapies supporting primary hemostatic function.
- Chronic Bleeding Control:Long-term prophylaxis for recurrent mucocutaneous hemorrhage.
Bleeding disorder management anchors reimbursement frameworks. Surgical prophylaxis is climbing the fastest as gene therapy delays reshape perioperative planning.
End User:
Customer type stratification reflects care centralization trends, with high-complexity cases migrating from community settings to specialized hubs.
- Hematology Centers:Academic medical centers and dedicated coagulation institutes consolidating rare bleeding disorder expertise, patient registries, and clinical trial access. German hematology centers in Hamburg, Munich, and Frankfurt concentrate the highest patient volumes, supported by national reference laboratory networks and EMA-aligned regulatory pathways. This segment holds installed capacity.
- Specialty Clinics:Community-based bleeding disorder treatment centers providing routine factor administration and patient education. Texas and Florida specialty clinics represent significant demand concentration as US payers consolidate benefits under specialty pharmacy management. This segment is rotating up the share rankings.
- Diagnostic Laboratories:Reference facilities confirming ITGA2B/ITGB3 mutations and platelet function defects.
- Blood Banks:Regional suppliers managing platelet inventory and HLA-matched product allocation.
Hematology centers hold installed capacity. Specialty clinics are rotating up the share rankings.
Delivery Mode:
Volume throughput varies by administration complexity, with infusion-based protocols requiring infrastructure investment that oral alternatives circumvent.
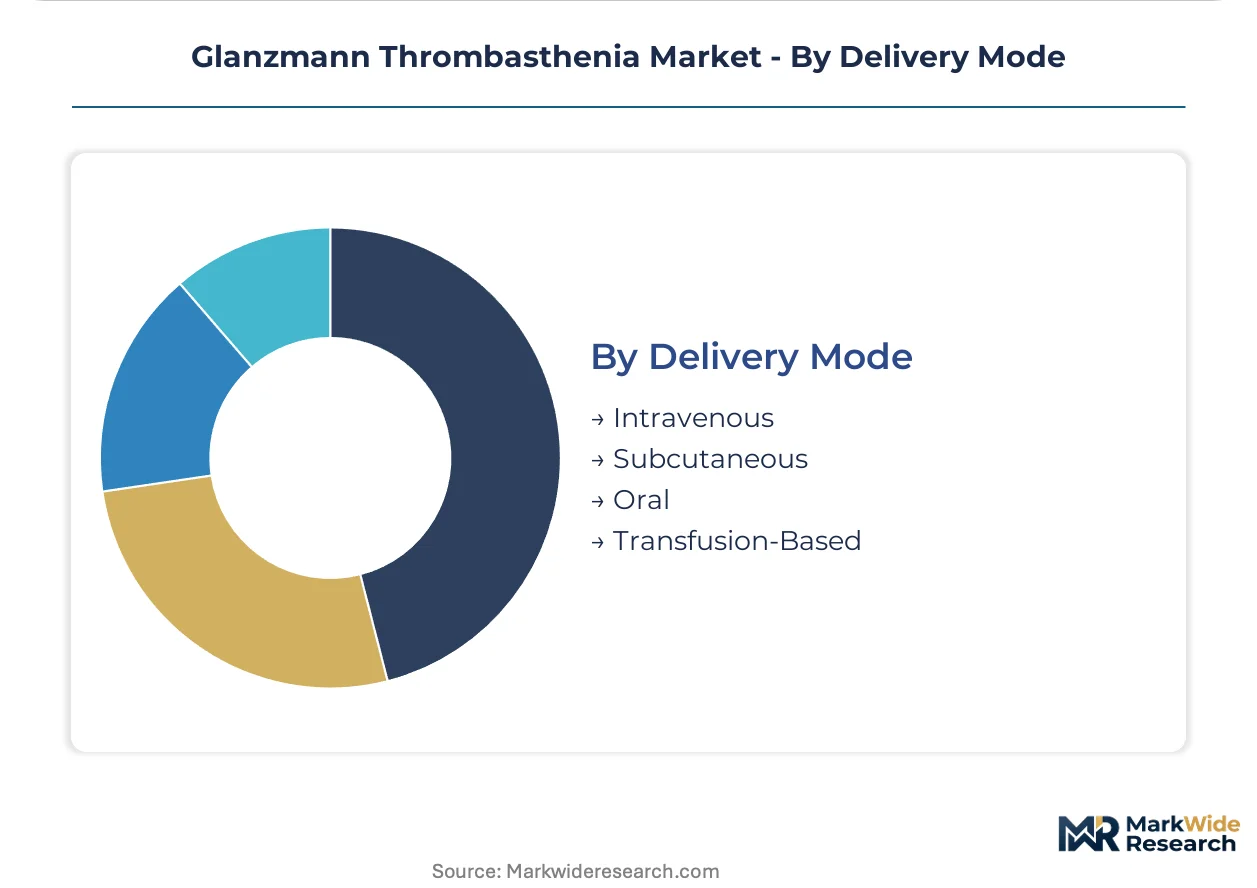
- Intravenous:Direct vascular administration of recombinant factors and bypass agents enabling rapid peak plasma concentrations for acute bleeding control. US hematology centers deploy intravenous delivery most intensively, supported by home infusion nursing networks and specialty pharmacy distribution channels. This segment holds installed capacity.
- Transfusion-Based:Apheresis platelet administration requiring blood bank coordination, HLA matching protocols, and irradiation capabilities. German transfusion services concentrate this delivery mode through centralized university hospital blood centers with integrated immunohematology laboratories. This segment is rotating up the share rankings.
- Subcutaneous:Emerging delivery route for investigational hemostatic agents.
- Oral:Antifibrinolytic tablets for mild mucosal bleeding episodes.
Intravenous delivery holds installed capacity. Transfusion-based administration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hematology centers export specialized bleeding disorder expertise to neighboring European markets through cross-border referral networks. United States treatment infrastructure concentrates recombinant factor distribution capacity. Japanese regulators maintain distinct hemostatic therapy approval pathways.
United States
FDA orphan drug incentives and specialty pharmacy consolidation drive recombinant factor VIIa procurement patterns. The agency's Regenerative Medicine Advanced Therapy designation accelerates gene therapy timelines for ITGA2B/ITGB3 programs. Texas and Florida specialty clinics anchor bleeding disorder treatment networks under consolidated payer benefit structures.
Germany
EMA-aligned regulatory pathways and dense university hospital infrastructure concentrate perioperative platelet transfusion demand. The country's PRIority MEdicines scheme attracts hemostatic gene therapy sponsors seeking accelerated assessment. Hamburg, Munich, and Frankfurt hematology centers coordinate national reference laboratory networks and patient registries.
Japan
PMDA's distinct hemostatic therapy classification shapes reimbursement tiering for bypass agents versus platelet products. METI-funded rare disease research initiatives support induced pluripotent stem cell applications in platelet disorder correction. Tokyo and Osaka academic medical centers lead Asia-Pacific bleeding disorder trial enrollment.
United Kingdom
NHS England's specialized commissioning framework concentrates Glanzmann thrombasthenia care in designated hemophilia comprehensive care centers. The MHRA's post-Brexit recognition pathways maintain EMA-aligned standards for advanced therapy medicinal products. London and Manchester treatment hubs manage national patient registries and gene therapy pre-qualification.
Switzerland
Swissmedic's precision medicine incentives attract gene therapy sponsors seeking concurrent FDA and EMA inspection readiness. The country's centralized healthcare procurement negotiates recombinant factor contracts for rare bleeding disorders. Basel and Zurich pharmaceutical clusters host viral vector manufacturing operations serving European hemostatic programs.
Glanzmann Thrombasthenia Market Competitive Landscape
Channel-controlling players compete with product-specialist players across recombinant factor and gene therapy modalities. The market structure consolidates around plasma fractionation incumbents with established cold chain distribution, while emerging biotech sponsors concentrate vector engineering capabilities. Three archetypes dominate: plasma-derived product suppliers with global sourcing infrastructure, recombinant bypass agent developers with specialty pharmacy relationships, and gene therapy sponsors with lentiviral production platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as sponsors position for curative modality transitions.
Among plasma fractionation specialists, CSL Behring and Grifols occupy positions sustained by global donor collection networks and fractionation infrastructure. Within the recombinant biologics tier, Novo Nordisk and Bayer exemplify bypass agent developers with established hemostatic franchises. At the gene therapy frontier, Hemab Therapeutics represents the emerging archetype of ITGA2B/ITGB3 transduction specialists advancing toward commercial-scale lentiviral production.
| Leading Market Players |
|---|
| CSL Behring |
| Bayer |
| Novo Nordisk |
| Alnylam Pharmaceuticals |
| Bristol-Myers Squibb |
| Biogen |
| Pfizer |
| Hemab Therapeutics |
| Grifols |
| Others |
Supply & Pricing Matrix
Basel and Zurich pharmaceutical clusters anchor lentiviral vector manufacturing capacity for European hemostatic gene therapy programs, concentrating upstream production leverage that translates into downstream pricing power for sponsors with captive viral vector supply. This geographic concentration of biologics infrastructure shapes procurement negotiations for recombinant factor therapies and platelet transfusion products across German and Swiss bleeding disorder treatment networks.
Pricing Analysis
Recombinant Factor VIIa commands premium positioning against plasma-derived alternatives due to its established bypass mechanism and FDA orphan drug exclusivity, while gene therapy candidates in early-phase development signal next-generation pricing disruption that could collapse chronic administration revenue streams. Pricing stratifies across premium recombinant biologics, standard platelet transfusion products, and economy-tier antifibrinolytic adjuncts based on clinical urgency and administration setting. Cost compression in plasma-derived segments is intensifying because fractionated feedstock costs fluctuate with donor collection rates. Community-based specialty clinics in Texas and Florida demonstrate highest price sensitivity due to consolidated payer benefit structures, whereas academic hematology centers in Germany absorb premium pricing for perioperative platelet support.
Supply Chain Analysis
Tariff exposure between United States and European Union biologics trade lanes dominates supply chain risk planning for recombinant factor manufacturers with cross-border distribution footprints. Vector production capacity concentrates in Switzerland, Germany, and United States, with lentiviral and AAV manufacturing platforms drawing from specialized cell culture media, plasmid DNA libraries, and purified viral coat protein inputs. Single-source vulnerability in cold chain logistics for platelet products strains distribution reliability, particularly for regional blood banks managing HLA-matched product allocation. Distribution runs through specialty pharmacy networks in the United States and centralized university hospital blood centers in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glanzmann thrombasthenia therapeutics represent an early-cycle expansion story as gene therapy vector engineering compresses development timelines and hematology centers pre-qualify for curative modality administration ahead of regulatory approval.
For Market Incumbents: Harden plasma fractionation infrastructure against gene therapy displacement by securing long-term donor collection contracts and expanding recombinant bypass agent formulation diversification. CSL Behring and Grifols must defend against lentiviral gene therapy truncation of chronic factor administration by deepening backward integration into viral vector production partnerships. Capacity addition in Swiss and German manufacturing clusters provides regulatory inspection readiness leverage for concurrent FDA and EMA submissions. For New Entrants and Emerging Players: Establish a beachhead in CRISPR-based ex vivo megakaryocyte correction protocols that eliminate vector-related immunogenicity concerns inherent to lentiviral approaches. Underpenetrated community-based bleeding disorder treatment centers in the American Midwest and Mountain West offer whitespace for hub-and-spoke referral models linking regional clinics to academic hematology centers. Gene editing platform licensing agreements with induced pluripotent stem cell technology providers provide differentiated go-to-market positioning against established viral vector sponsors. For Investors and Strategic Acquirers: Long-term, this sits as a modality-transition play because curative gene therapies threaten to displace chronic recombinant factor franchises within the projection horizon, compressing revenue duration for incumbent developers. Acquisition targets center on lentiviral production platform specialists with scalable yields and EMA-aligned quality control operations. The signal to watch is early-phase ITGA2B/ITGB3 transduction readouts from Hemab Therapeutics and competing sponsors that validate durable platelet function correction.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Scalable lentiviral vector production enables dose supply for inherited platelet disorder programs previously constrained by batch capacity limitations. |
| Specialty Pharmacy Distribution Partnership | CVS Specialty and Accredo consolidation concentrates purchasing leverage for recombinant bypass agents under US payer benefit management structures. |
| EMA PRIority MEdicines Designation Pursuit | Accelerated assessment pathways compress regulatory timelines for hemostatic therapies addressing unmet needs in Glanzmann thrombasthenia. |
| Hematology Center Pre-Qualification Program | Apheresis and cell processing capability investments in Hamburg, Munich, and Frankfurt prepare German centers for gene therapy administration. |
| CRISPR Ex Vivo Correction Platform Development | Patient-derived megakaryocyte production eliminates vector-related immunogenicity concerns while enabling durable platelet function restoration. |
Research Methodology
Desk research of FDA orphan drug filings, EMA advanced therapy medicinal product submissions, ClinicalTrials.gov registries, and hematology center patient volume databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork with German bleeding disorder treatment networks and US specialty clinic administrators combined with secondary validation against formulary databases and GPO contract disclosures. Bottom-up patient population estimates and top-down therapeutic modality revenue triangulation anchored market sizing across the analysis window.
Assumptions regarding gene therapy approval timelines, recombinant factor VIIa pricing persistence, and platelet transfusion alloimmunization rates were held fixed while regulatory pathway variations and vector manufacturing yield improvements were stress-tested across sensitivity bands. Segmentation modeling incorporated therapeutic modality, clinical application urgency, end-user facility type, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of modality-specific adoption curves and hematology center capacity expansion trajectories. Forecast inputs included EMA PRIority MEdicines scheme qualification rates and FDA Regenerative Medicine Advanced Therapy designation velocity.
Stress conditions across plasma supply volatility, gene therapy clinical readout timing, and specialty pharmacy rebate aggregation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding curative modality displacement rates and chronic factor administration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Fabry Disease Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Behcets Disease Market